
 Cell Therapy Technologies Market | 2026-2036
Cell Therapy Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Therapy Technologies Market Intelligence
A scarcity of specialized bioprocess engineering talent is unwinding the previously rapid scale-up timelines for new cell therapy manufacturing facilities. This constraint puts a premium on automation and integrated technology platforms. Thermo Fisher Scientific Inc. leverages its extensive portfolio of cell culture media and analytical instruments to support research and production workflows. Lonza Group specializes in contract development and manufacturing for complex allogeneic and autologous therapies. Sartorius AG provides critical bioreactor systems and filtration technologies for process optimization.
Cell therapy technologies encompass the tools, processes, and platforms used to develop, manufacture, and deliver treatments based on living cells. This includes the ex vivo manipulation of cells, such as T-cells or stem cells, through genetic modification or expansion before reinfusion into a patient. Oncology Treatment applications continue to dominate development pipelines, driven by CAR-T successes. Within the technology segment, Gene Editing and advanced Bioreactor Systems are pivotal for improving therapeutic efficacy and enabling scalable, cost-effective production.
The U.S. FDA's Regenerative Medicine Advanced Therapy (RMAT) designation provides an expedited pathway for promising therapies. Concurrently, the EMA in Europe and the NMPA in China maintain stringent but evolving guidelines for clinical trial data and manufacturing quality, influencing market access strategies. Stakeholders must navigate the complex interplay between automating manufacturing processes and meeting diverse, cross-border regulatory expectations for product characterization and comparability.
Market Dynamics
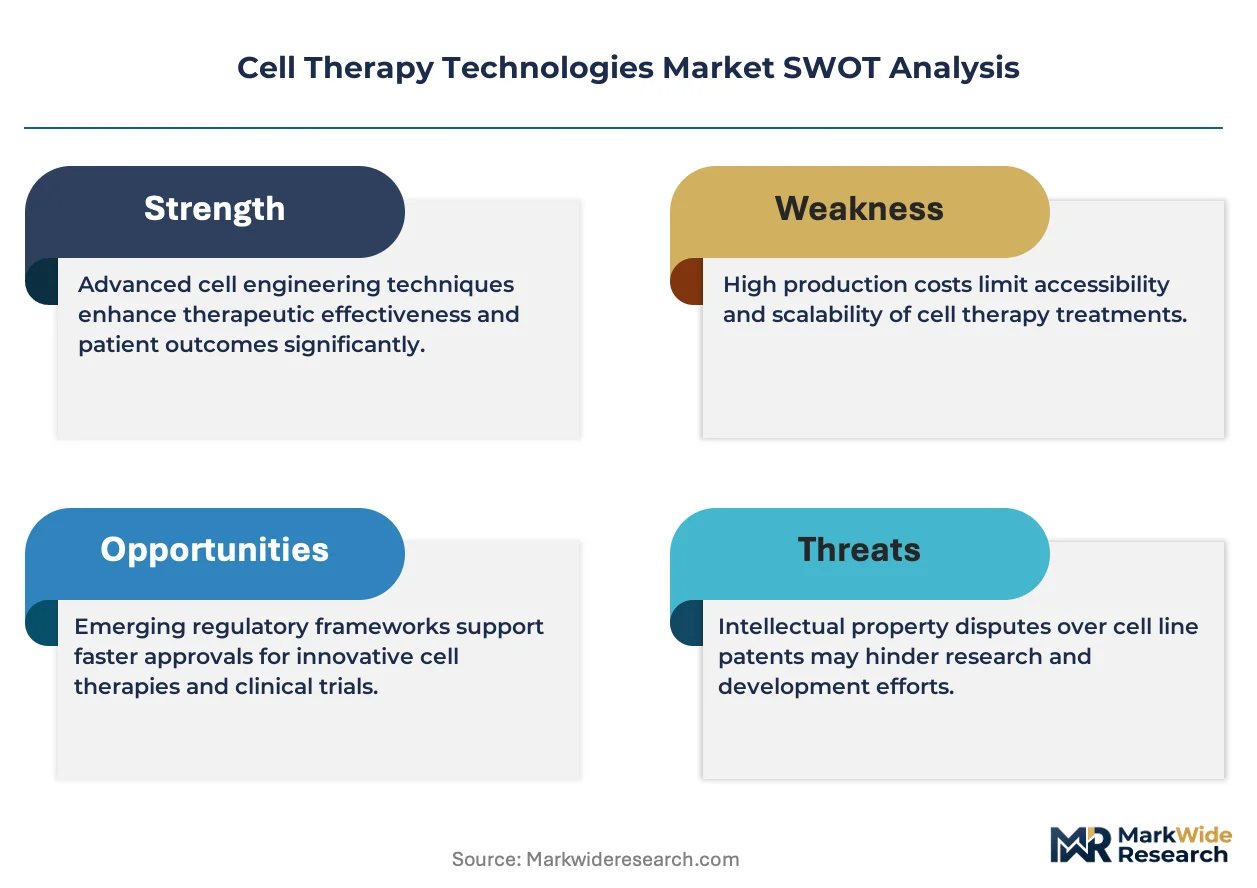
The central dynamic is the race to industrialize cell therapy manufacturing, pitting the urgent need for scalable automation against a persistent scarcity of specialized bioprocess engineering talent required to implement and operate these advanced systems.
Growth Catalysts
- Expedited Regulatory Pathways:The U.S. FDA's Regenerative Medicine Advanced Therapy (RMAT) designation offers an accelerated review process for promising therapies, incentivizing investment in novel technology platforms that support faster clinical development.
- Gene Editing Advancements:Breakthroughs in gene editing technologies, particularly CRISPR-based systems, are enhancing the precision and efficacy of cell modifications, expanding the potential scope of treatable diseases beyond oncology into rare genetic disorders.
- Concentrated Research Ecosystems:The dense concentration of research institutes and biotech startups in the United States creates sustained demand for cutting-edge bioprocessing tools, analytical instruments, and high-purity reagents, fueling technology innovation.
Market Restraints
- High Cost of Goods:The inherently personalized and manual nature of many autologous therapy manufacturing workflows results in a very high cost of goods, which creates significant reimbursement hurdles and limits patient access.
- Complex Logistics:Cell therapies are living products with short shelf lives, demanding complex and failure-intolerant cryogenic (cold chain) logistics that add significant cost and risk to the supply chain.
- Allogeneic Manufacturing Hurdles:Technical difficulties in achieving consistent, large-scale, and cost-effective cGMP manufacturing for "off-the-shelf" allogeneic therapies continue to restrain their potential to fully displace more complex autologous treatments.
Strategic Opportunities
- Non-Oncology Indications:Developing cell therapies for large, underserved patient populations in autoimmune diseases, cardiovascular conditions, and neurodegenerative disorders presents a substantial opportunity to expand beyond the current oncology focus.
- Asia-Pacific Market Entry:As regulatory frameworks mature, particularly in China under the NMPA, establishing manufacturing and clinical operations in the Asia-Pacific region offers access to a large and growing patient base.
- AI in Process Development:Integrating artificial intelligence and machine learning into process development can optimize bioreactor parameters, predict batch outcomes, and accelerate the creation of robust, scalable manufacturing processes.
Industry Challenges
- Specialized Talent Shortage:A critical shortage of bioprocess engineers, manufacturing technicians, and quality control specialists with hands-on experience in cGMP cell therapy production is a primary bottleneck for facility commissioning and operational scale-up.
- Lack of Standardization:A persistent lack of standardized analytical methods for product characterization and release testing creates comparability challenges for companies and complicates regulatory reviews by agencies like the EMA and FDA.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Therapy Technologies Market |
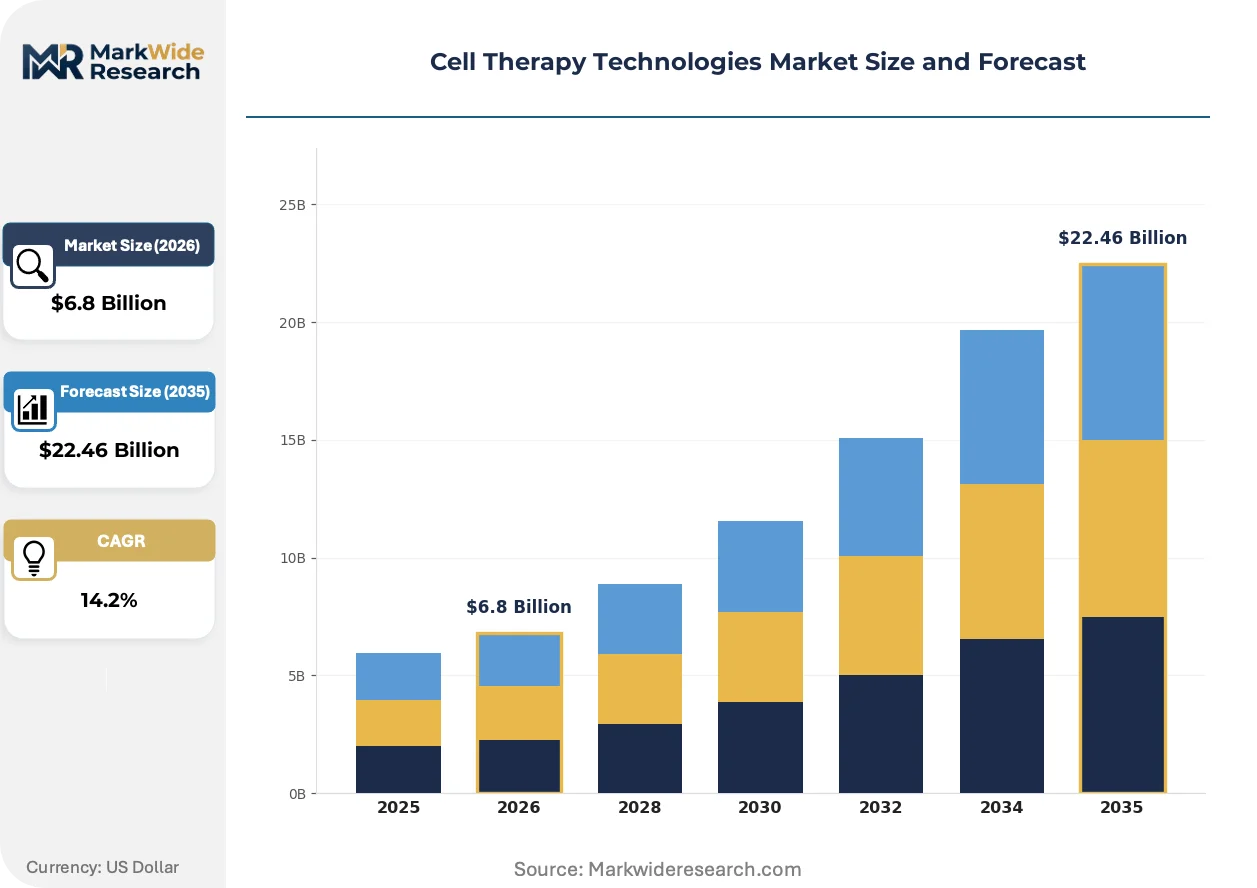
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Autologous Cells, Allogeneic Cells, Induced Pluripotent Stem Cells, Mesenchymal Stem Cells, Hematopoietic Stem Cells Technology: Gene Editing, Ex Vivo Expansion, Cryopreservation, Cell Sorting, Bioreactor Systems Application: Oncology Treatment, Immunodeficiency Disorders, Regenerative Medicine, Genetic Disorders, Cardiovascular Diseases End User: Research Institutes, Contract Manufacturing Organizations, University Laboratories, Pharmaceutical Companies, Biotech Startups |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, Lonza Group, Sartorius AG, Danaher Corporation, BD, Miltenyi Biotec, Agilent Technologies, Inc., Avantor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Therapy Technologies Market Strategic Shifts & Innovations
The push for industrialization is compelling innovation in both process automation and analytical technologies. These advancements aim to overcome manufacturing bottlenecks, reduce costs, and satisfy stringent cross-border regulatory demands for product consistency and quality.
Closed, automated cell processing systems perform multiple manufacturing steps like cell selection, activation, and expansion within a single, contained unit. Early-stage clinical trial sponsors and academic labs are adopting these platforms to ensure process consistency and reduce manual handling errors. This trend is fragmenting the traditional, open-process workflow into a series of modular, automated steps, enabling more flexible and decentralized manufacturing models.
The International Council for Harmonisation (ICH) is advancing guidelines, such as ICH Q5A(R2), to standardize viral safety evaluation for biotechnological products. This creates a more predictable global regulatory environment, reducing duplicative testing for companies seeking market access in multiple regions. Developers of viral vector-based gene therapies are most affected, now able to design a single testing strategy that is more likely to be accepted by the FDA, EMA, and PMDA.
A growing number of biotech startups are shifting from building their own manufacturing capacity to partnering with contract development and manufacturing organizations (CDMOs). This change is driven by the desire to conserve capital and access specialized expertise without the long lead times of facility construction. The trend is most prominent in North America and Europe, where a dense network of specialized CDMOs offers services from process development to commercial-scale production.
Cell Therapy Technologies Market Segmentation
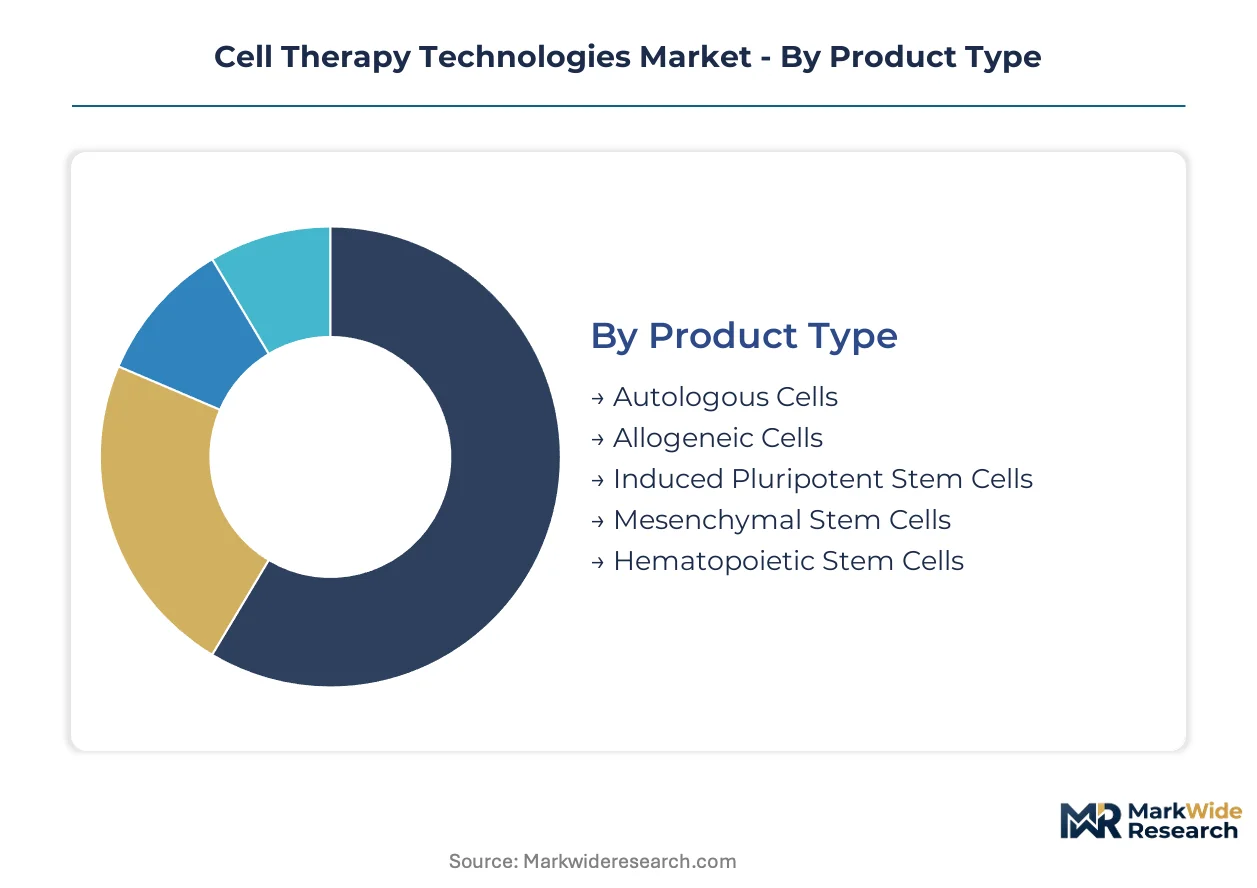
Understanding the distinct segments within the cell therapy technologies market reveals where innovation and investment converge. Each category reflects different strategic priorities for developers and manufacturers seeking to optimize therapeutic outcomes and scale production. This granular view highlights the specialized tools and processes required across the entire cell therapy value chain.
Product Type:
Margin pools within product type segmentation are significantly influenced by manufacturing complexity and patient-specific customization. Autologous therapies, while highly personalized, incur substantial per-patient costs due to individualized production. Allogeneic products aim for economies of scale, but face hurdles in consistent large-batch manufacturing.
- Autologous Cells:These therapies involve a patient's own cells, harvested, modified ex vivo, and then reinfused. CAR-T therapies exemplify this approach, demonstrating clinical success in specific oncology indications.
- Allogeneic Cells:"Off-the-shelf" therapies derived from healthy donors, these products offer scalability and reduced manufacturing lead times. Technical difficulties in achieving consistent, large-scale cGMP manufacturing persist for these treatments.
- Induced Pluripotent Stem Cells:Reprogrammed adult somatic cells that can differentiate into various cell types, offering a renewable source for regenerative medicine.
- Mesenchymal Stem Cells:Multipotent stromal cells isolated from various tissues, recognized for their immunomodulatory and regenerative properties.
- Hematopoietic Stem Cells:Found in bone marrow and umbilical cord blood, these cells are crucial for reconstituting the blood and immune system.
The dominant share belongs to Autologous Cells, while Allogeneic Cells are closing the gap fastest.
Technology:
The technological sophistication of cell therapy platforms directly correlates with their ability to enhance therapeutic efficacy and streamline manufacturing processes. Advanced technologies reduce manual intervention and improve product consistency, leading to higher quality and lower costs.
- Gene Editing:Technologies like CRISPR-Cas9 enable precise modification of cellular DNA to enhance therapeutic function or correct genetic defects. Breakthroughs in gene editing are expanding treatable diseases beyond oncology into rare genetic disorders.
- Bioreactor Systems:Controlled environments for large-scale cell culture, these systems are critical for expanding cell populations while maintaining viability and potency. Advanced bioreactor systems are pivotal for enabling scalable, cost-effective production.
- Ex Vivo Expansion:The process of growing and multiplying cells outside the body before reinfusion, crucial for obtaining sufficient therapeutic doses.
- Cryopreservation:Essential techniques for preserving living cells at ultra-low temperatures, supporting complex cold chain logistics and extending product shelf life.
- Cell Sorting:Methods used to isolate specific cell populations based on surface markers or other characteristics, ensuring purity and potency of the final product.
The most significant technological advancements are occurring in Gene Editing, with Bioreactor Systems also demonstrating rapid evolution for scalability.
Application:
Application segments highlight the primary therapeutic areas driving demand for cell therapy technologies, reflecting both established clinical successes and emerging treatment opportunities. Oncology continues to dominate, but diversification into other disease areas is a strategic imperative.
- Oncology Treatment:The largest application area, primarily driven by the clinical success of CAR-T cell therapies against hematological malignancies. Oncology treatment applications continue to dominate development pipelines.
- Genetic Disorders:Cell therapies offer the potential to correct underlying genetic defects, providing curative options for rare and inherited diseases. Breakthroughs in gene editing are expanding the potential scope of treatable diseases into rare genetic disorders.
- Regenerative Medicine:Utilizes cells to repair, replace, or regenerate damaged tissues and organs, addressing conditions from musculoskeletal injuries to organ failure.
- Immunodeficiency Disorders:Cell therapies can restore or enhance immune function in patients with compromised immune systems, such as severe combined immunodeficiency.
- Cardiovascular Diseases:Emerging applications include using stem cells to repair heart tissue damaged by infarction or to treat chronic heart failure.
Oncology Treatment maintains the largest market share, while Genetic Disorders are poised for significant expansion.
End User:
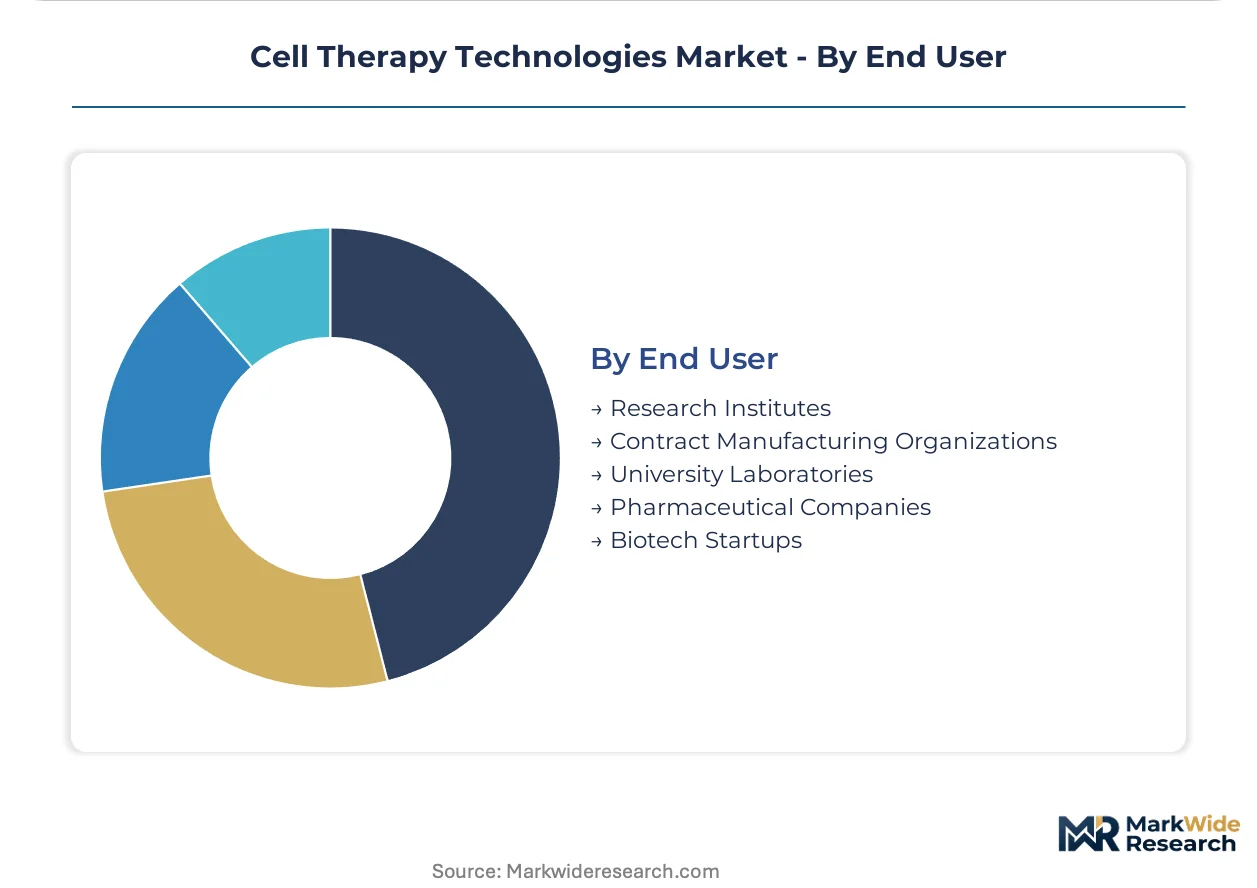
The end-user landscape dictates the specific needs for cell therapy technologies, from fundamental research tools to commercial-scale manufacturing solutions. Different organizational structures require tailored product portfolios and service offerings.
- Contract Manufacturing Organizations:Specialized firms providing development and manufacturing services for complex cell therapies, enabling biotech startups to conserve capital. A growing number of biotech startups partner with these organizations.
- Biotech Startups:Innovative companies focused on developing novel cell therapies, often relying on external expertise and specialized tools for early-stage development. The dense ecosystem of biotech startups in the United States creates sustained demand for bioprocessing tools.
- Research Institutes:Academic and non-profit organizations conducting fundamental and translational research into cell biology and therapeutic applications. The United States supports a dense ecosystem of research institutes.
- Pharmaceutical Companies:Large enterprises with established infrastructure, increasingly acquiring or partnering with smaller biotechs to enter the cell therapy space.
- University Laboratories:Key sites for early-stage discovery, proof-of-concept studies, and training the next generation of cell therapy scientists.
The most dynamic growth in demand originates from Contract Manufacturing Organizations, with Biotech Startups also driving substantial innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The U.S. FDA's expedited regulatory pathways significantly influence the global cell therapy technologies market. This regulatory environment, coupled with substantial research investment, anchors innovation and commercialization. Global expansion strategies often leverage these early successes.
United States
The United States market demonstrates robust demand for advanced bioprocessing tools driven by a dense biotech ecosystem. The FDA's Regenerative Medicine Advanced Therapy (RMAT) designation accelerates clinical development for novel treatments. Major research hubs in Boston and the San Francisco Bay Area foster continuous technological innovation.
Germany
German pharmaceutical companies prioritize high-quality manufacturing solutions for cell therapies. The EMA, through its stringent but clear guidelines, shapes market access strategies across Europe. Munich and Berlin are emerging as key centers for cell therapy research and production.
China
China's increasing patient population and government support drive significant investment in cell therapy development. The NMPA is actively evolving its regulatory framework to facilitate domestic and international clinical trials. Shanghai and Beijing host major biopharmaceutical parks focusing on advanced therapies.
Japan
Japan exhibits strong clinical research activity for regenerative medicine and cell therapies. The PMDA offers a unique conditional approval system, accelerating access for promising treatments. Tokyo and Osaka remain critical for academic research and biotech startup activity.
United Kingdom
The United Kingdom's academic excellence and clinical trial infrastructure support cell therapy innovation. The Medicines and Healthcare products Regulatory Agency (MHRA) provides guidance for advanced therapy medicinal products. London and Cambridge are prominent clusters for cell and gene therapy research and development.
Cell Therapy Technologies Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier within the cell therapy technologies market. This structure includes large diversified life science suppliers and highly specialized contract development and manufacturing organizations. Key archetypes involve end-to-end solution providers and niche technology innovators. Strategic partnerships and portfolio diversification remain dominant competitive moves.
Among the integrated solution providers, Thermo Fisher Scientific Inc. exemplifies a broad portfolio spanning cell culture media, analytical instruments, and bioprocessing equipment. Lonza Group occupies a position as a specialized contract development and manufacturing organization for complex allogeneic and autologous therapies. Sartorius AG represents a critical supplier of bioreactor systems and filtration technologies, essential for process optimization and scalability.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| Lonza Group |
| Sartorius AG |
| Danaher Corporation |
| BD |
| Miltenyi Biotec |
| Agilent Technologies, Inc. |
| Avantor, Inc. |
| Others |
Cost & Logistics Intelligence
The extended clinical trial lead times inherent in cell therapy development directly influence supply chain strategies and ultimately pricing power for novel treatments.
Pricing Analysis
Significant price disparities exist for cell therapies across the United States and Europe, primarily due to varying reimbursement policies and market access strategies. The dominant pricing structure is value-based, reflecting high development costs and clinical efficacy. Price differentiation stems from the level of customization for autologous therapies and the certification level required for cGMP manufacturing. Pricing pressure from national healthcare systems reflects increasing competition, with research institutes being the most price-sensitive buyers. Pharmaceutical companies acquiring advanced therapies often demonstrate lower price sensitivity.
Supply Chain Analysis
Strategic stockpiling of critical raw materials, particularly viral vectors and specialized cell culture media, is preferred over just-in-time approaches due to supply volatility. Geographic supply concentration for key bioprocessing components draws from the United States, Germany, and China. Raw material dependencies include high-purity reagents and single-use bioreactor bags, creating single-source vulnerability for specialized enzymes. Distribution runs through a network of specialized cold chain logistics providers to clinical sites and manufacturing hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The cell therapy market faces a profound challenge in scaling manufacturing, driven by a persistent shortage of specialized bioprocess engineering talent. This capability gap necessitates strategic adjustments across the industry.
For Market Incumbents:Compound existing strengths in bioprocessing equipment and analytical instruments through targeted R&D into AI-driven process optimization. This mitigates the threat from emerging niche technology innovators by offering more integrated solutions. Invest in advanced training programs for bioprocess engineers to address the talent bottleneck. Capacity addition in key geographies like the United States and Germany can further solidify market position against regulatory shifts.
For New Entrants and Emerging Players:Anchor in specialized technology niches, such as novel gene editing tools or next-generation bioreactor systems, to differentiate from established players. The most penetrable segment for innovation remains early-stage process development tools for academic labs. Target underserved non-oncology indications like autoimmune diseases, which offer significant white-space opportunity. A strong go-to-market angle involves offering modular, closed-system platforms that simplify manufacturing for smaller biotech startups.
For Investors and Strategic Acquirers:Carve-out targets emerge from large pharmaceutical companies divesting non-core cell therapy assets, offering established IP and clinical data. Long-term viability over a five-to-ten-year window favors companies with robust allogeneic platforms or highly automated manufacturing capabilities. Focus on acquiring specialized CDMOs with proven cGMP track records. The signal to watch is successful Phase 3 clinical trial readouts for allogeneic therapies, indicating broader market acceptance and scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Scaling production is essential for meeting patient demand and reducing the per-patient cost of goods for cell therapies. |
| Gene Editing Platform Integration | Integrating advanced gene editing technologies enhances therapeutic efficacy and broadens the scope of treatable indications. |
| CDMO Partnership Expansion | Leveraging specialized contract development and manufacturing organizations provides access to expertise and capital-efficient production capacity. |
| Automated Bioprocessing System Development | Developing automated systems addresses the specialized talent scarcity and improves product consistency and quality. |
| Non-Oncology Pipeline Diversification | Expanding therapeutic development into non-oncology indications diversifies revenue streams and expands market reach. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, patent databases, and scientific literature. This involved detailed interviews with bioprocess engineers, regulatory affairs specialists, R&D directors, and CDMO executives. Secondary validation included analysis of company investor reports, academic journals, and government health agency publications. A robust bottom-up and top-down triangulation approach ensured data consistency and market sizing accuracy.
Product type, technology, application, and end-user segments were modeled across the analysis window, alongside a specific dimension for manufacturing complexity. Our quantitative framework projects market evolution by analyzing historical growth trends and future adoption rates. Compound Annual Growth Rates were derived from proprietary algorithms considering technological advancements and regulatory changes. Forecast inputs included projected clinical trial success rates and anticipated shifts in reimbursement policies.
Decision-makers should treat outputs as directional under current regulatory stability and technological development assumptions; material deviation would warrant model refresh. Forecasts reflect a baseline scenario, acknowledging risks like unforeseen clinical trial failures or major shifts in global economic conditions. Revision becomes warranted when significant new gene editing breakthroughs or regulatory changes cross established thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Global Viral Vector Manufacturing Market
Cell & Gene Therapy
Cell Therapy Manufacturing Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
Viral Vector and Plasmid DNA Testing Service Market
Cell & Gene Therapy
Cell Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Stem Cell Manufacturing Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
North America Stem Cell Therapy Market