
 Engineered T Cells Market | 2026-2036
Engineered T Cells Market Size, Share, and Industry Trends Forecast 2026-2036
Engineered T Cells Market Foresight
A capital-intensity divergence between vector manufacturing scale and clinical trial infrastructure is reorganizing competitive hierarchies in engineered T cell development. Novartis AG leverages its in-house viral vector production network across three continents to secure supply chain continuity for commercial CAR T programs. Gilead Sciences anchors its position through Kite Pharma's concentrated manufacturing footprint in Southern California. Bristol-Myers Squibb competes via diversified TCR and CAR platforms spanning both hematologic and solid tumor indications.
Engineered T cells constitute patient-derived or allogeneic lymphocytes modified ex vivo through genetic insertion of chimeric antigen receptors, T cell receptors, or gene-editing constructs to recognize and eliminate target cells, typically requiring cryopreservation in dimethyl sulfoxide at below minus 150 degrees Celsius for viable distribution. CAR T Cells command the dominant revenue share due to established reimbursement in B-cell malignancies, while TCR T Cells represent the fastest-expanding category as developers target intracellular tumor antigens in solid cancers. Gene-Edited T Cells attract concentrated R&D investment where CRISPR-mediated knockout of PD-1 or TCR alpha chains promises reduced manufacturing complexity for off-the-shelf products.
FDA's regenerative medicine advanced therapy designation and EMA's priority medicines scheme create divergent approval timelines that shape geographic launch sequencing for engineered T cell developers. The EU AI Act introduces algorithmic transparency requirements for computational tools used in patient selection and manufacturing quality control, adding compliance layers for European trials. Stakeholders must monitor how CMS national coverage determinations for CAR T reimbursement evolve relative to site-of-care requirements and outcome-based payment pilots.
Market Dynamics
Vector manufacturing scale and clinical trial infrastructure are diverging in capital intensity, forcing developers to reorganize competitive hierarchies around in-house viral production networks versus outsourced GMP partnerships.
Growth Catalysts
- FDA regenerative medicine advanced therapy designation:This pathway compresses development timelines for cell and gene therapies, accelerating commercial launch sequences for engineered T cell programs.
- EMA priority medicines scheme:European developers leverage this framework to secure accelerated assessment timelines, creating parallel regulatory momentum alongside US pathways.
- German university hospital infrastructure:Dedicated GMP manufacturing suites for autologous cell therapies concentrate demand in centralized European clinical hubs.
Market Restraints
- Cryopreservation logistics:Dimethyl sulfoxide storage requirements below minus 150 degrees Celsius impose specialized cold chain infrastructure costs that limit distribution reach.
- Allogeneic donor network concentration:Healthy donor screening and apheresis collection centers cluster in urban academic medical centers, creating geographic supply bottlenecks.
- EU AI Act compliance layers:Algorithmic transparency requirements for computational patient selection tools add validation burdens to European trial protocols.
Strategic Opportunities
- Off-the-shelf allogeneic platforms:CRISPR-mediated PD-1 knockout and TCR alpha chain deletion promise reduced manufacturing complexity versus autologous workflows.
- Solid tumor TCR expansion:Intracellular antigen targeting opens addressable indications beyond B-cell malignancies where CAR T cells currently dominate.
- CMS outcome-based payment pilots:Site-of-care reimbursement evolution creates financial structure for value-based contracting in CAR T therapy delivery.
Industry Challenges
- Cell therapy manufacturing scientist scarcity:GMP-compliant aseptic processing and vector production expertise concentrates at a handful of academic and commercial training programs.
- Multi-site trial coordination complexity:Patient apheresis, vector transduction, and infusion logistics require synchronized scheduling across geographically dispersed clinical sites.
- Intellectual property thickets:CAR construct patents, CRISPR licensing, and manufacturing process claims create layered royalty burdens for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Engineered T Cells Market |
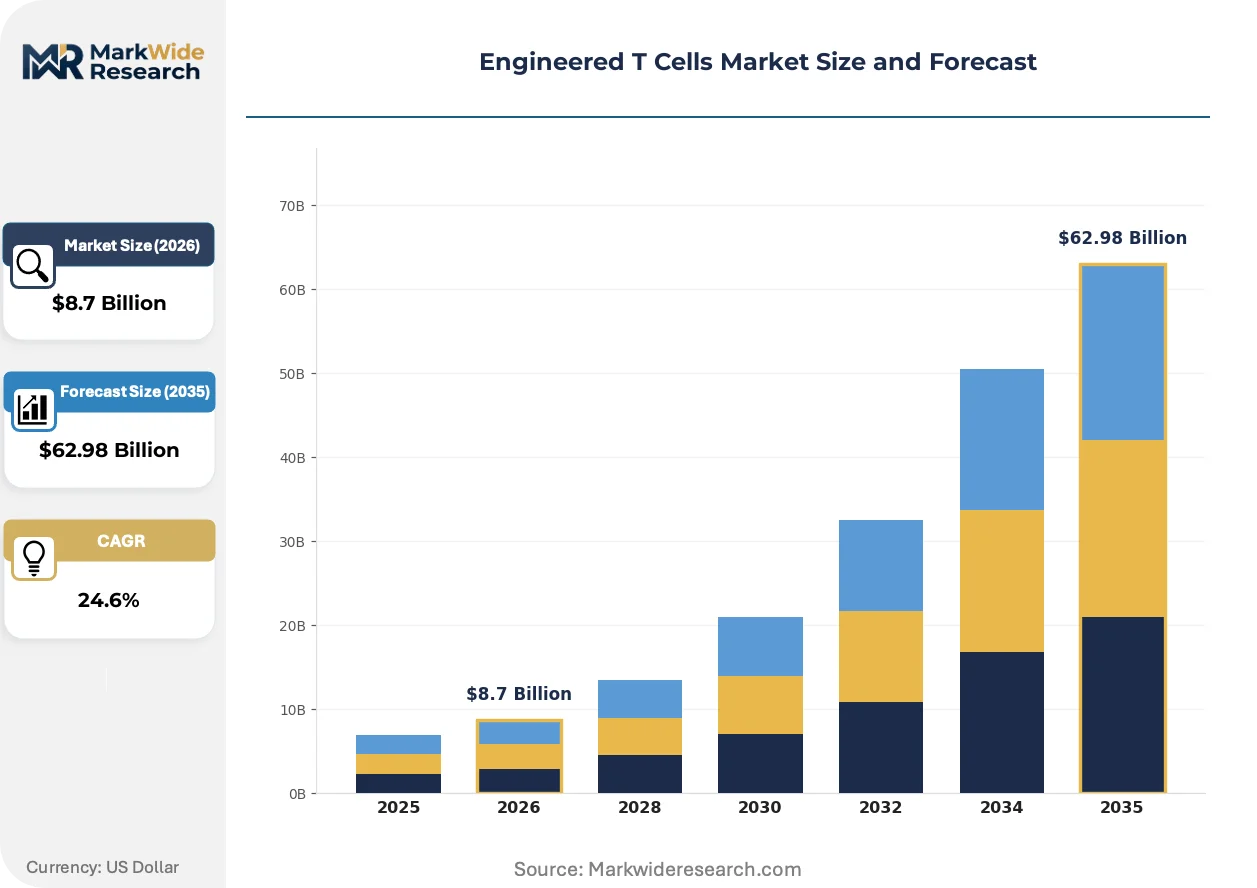
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CAR T Cells, TCR T Cells, Gene-Edited T Cells, Immune Checkpoint Inhibitors Therapy Area: Oncology, Infectious Diseases, Autoimmune Disorders, Neurological Disorders End User: Hospitals, Research Institutes, Diagnostic Laboratories, Biopharmaceutical Companies Technology: CRISPR, TALEN, Zinc Finger Nucleases, Viral Vectors |
| Companies Covered | Novartis AG, Gilead Sciences, Bristol-Myers Squibb, Amgen Inc, Pfizer Inc, Eli Lilly and Company, Bellicum Pharmaceuticals Inc, Precision BioSciences Inc, Oxford Biomedica Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Engineered T Cells Market Shifts & Advancements
Manufacturing modality and regulatory pathway choices are actively reshaping competitive positioning in engineered T cell development, with technology trajectories diverging between personalized autologous workflows and standardized allogeneic platforms.
Allogeneic T cell engineering is bifurcating development pipelines between donor-derived universal products and induced pluripotent stem cell sources. Large pharmaceutical manufacturers are prioritizing the former for near-term commercial feasibility, while biotechnology specialists pursue the latter for theoretical lot-size scalability. This technology trajectory is compressing the manufacturing cost structure differential between autologous and off-the-shelf modalities.
EMA's priority medicines scheme and FDA's regenerative medicine advanced therapy designation are creating asynchronous approval timelines that shape geographic launch sequencing. European developers face additional algorithmic transparency requirements under the EU AI Act for computational patient selection tools. Solid tumor indications with intracellular antigen targets are experiencing the most pronounced regulatory pathway fragmentation as TCR platforms navigate novel validation standards.
Hospital procurement for CAR T therapy is consolidating around academic medical centers with integrated apheresis, processing, and infusion capabilities. Community oncology practices are losing access as site-of-care requirements tighten under evolving CMS national coverage determinations. The United States exhibits the most concentrated buyer power shift, with oncology centers in Germany and university hospitals in France following similar consolidation patterns.
Engineered T Cells Market Segmentation
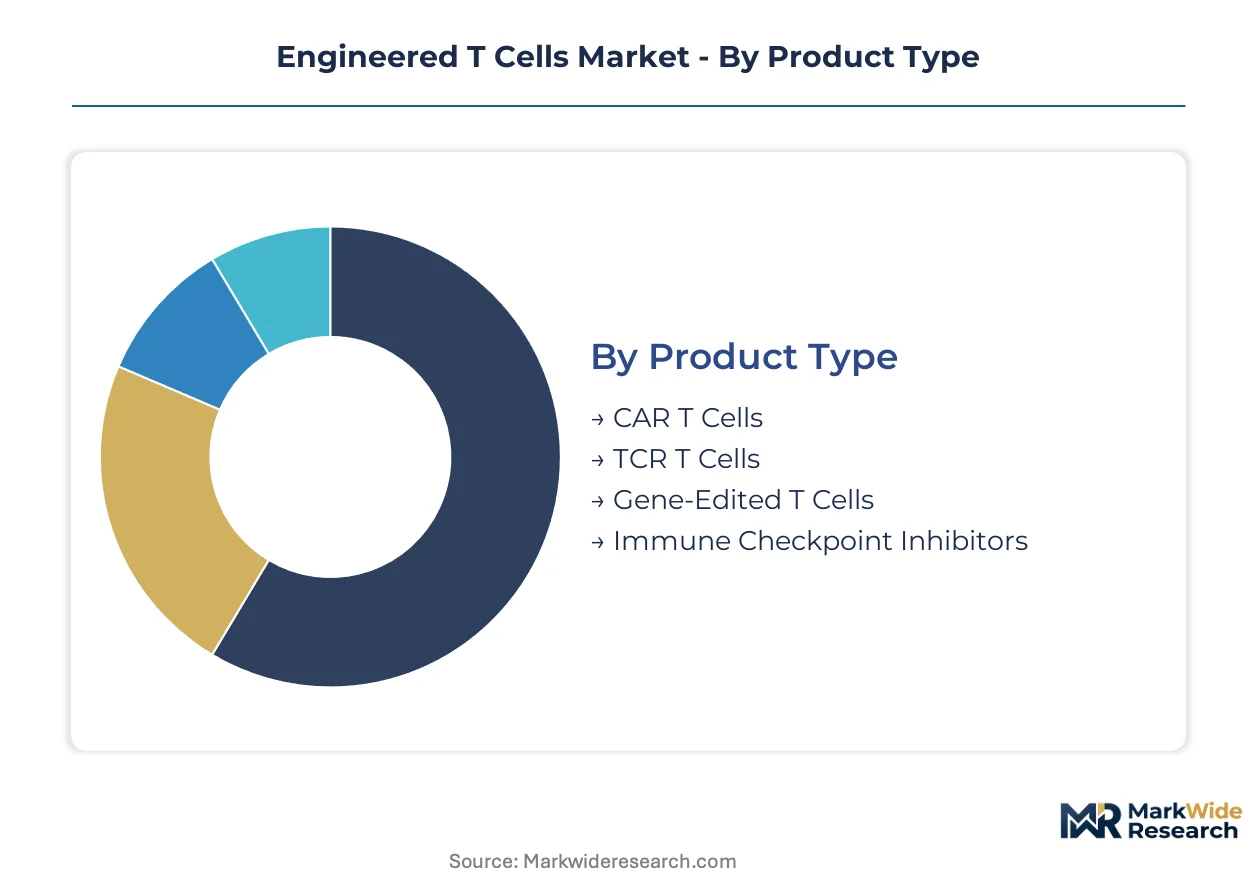
Segmentation in engineered T cells reveals how therapeutic platforms, disease targets, and technical architectures compete for capital allocation and clinical validation. Each dimension carries distinct substitution dynamics that reshape competitive hierarchies as manufacturing modalities evolve.
Product Type:
CAR T Cells face the most acute substitution pressure from allogeneic platforms promising reduced manufacturing complexity and broader patient access.
- CAR T Cells:Autologous lymphocytes engineered with chimeric antigen receptors targeting surface antigens on B-cell malignancies. Demand concentrates in United States oncology centers with integrated apheresis and cryopreservation capabilities, where FDA regenerative medicine advanced therapy designation has compressed commercial launch timelines. Reimbursement concentration in hematologic indications creates vulnerability to TCR platforms expanding into solid tumors.
- TCR T Cells:Modified lymphocytes expressing recombinant T cell receptors recognizing intracellular tumor antigens presented via MHC molecules. German university hospitals and French academic medical centers are building dedicated GMP manufacturing suites for these more complex workflows, driven by the addressable expansion beyond B-cell malignancies into lung, colorectal, and pancreatic cancers.
- Gene-Edited T Cells:CRISPR-mediated knockout of PD-1 or TCR alpha chains enables off-the-shelf allogeneic products with reduced donor matching requirements.
- Immune Checkpoint Inhibitors:Engineered T cells with modified checkpoint pathways to sustain activation in immunosuppressive tumor microenvironments.
CAR T Cells anchors the volume base while Gene-Edited T Cells gains share at the steepest rate.
Therapy Area:
Cost tier stratification separates curative oncology applications from chronic disease management where repeat dosing economics remain unresolved.
- Oncology:B-cell malignancies, solid tumors, and hematologic cancers represent the primary revenue concentration with established reimbursement frameworks. United States academic medical centers and German university hospitals command the highest procedure volumes, though solid tumor penetration remains constrained by antigen heterogeneity and tumor microenvironment suppression.
- Infectious Diseases:Engineered T cells targeting viral reservoirs in HIV and hepatitis B are advancing through early-phase trials with support from NIH and BARDA funding mechanisms.
- Autoimmune Disorders:Regulatory T cell engineering for lupus, multiple sclerosis, and type 1 diabetes addresses chronic conditions requiring durable immune tolerance mechanisms.
- Neurological Disorders:Blood-brain barrier penetration challenges limit current applicability, though CAR-T microglia platforms are emerging in preclinical development for neurodegenerative indications.
Oncology dominates current revenue while Autoimmune Disorders shows the steepest expansion trajectory in early-stage pipelines.
End User:
Customer type fragmentation reflects divergent purchasing authority between integrated health systems and specialized research organizations.
- Hospitals:Academic medical centers with apheresis capabilities, GMP-adjacent processing facilities, and infusion infrastructure command procurement concentration. United States hospital systems are consolidating CAR T programs under site-of-care requirements in evolving CMS national coverage determinations, excluding community oncology practices from reimbursement eligibility.
- Research Institutes:National Cancer Institute-designated centers and European Research Council-funded consortia drive preclinical platform development and first-in-human trial execution.
- Diagnostic Laboratories:Companion diagnostic development for patient selection biomarkers creates specialized procurement for flow cytometry and sequencing infrastructure.
- Biopharmaceutical Companies:Large manufacturers with in-house viral vector production networks and biotechnology specialists with platform licensing strategies represent divergent sourcing patterns for GMP manufacturing partnerships.
Hospitals anchor the volume base while Biopharmaceutical Companies gains share at the steepest rate through pipeline acquisition and platform consolidation.
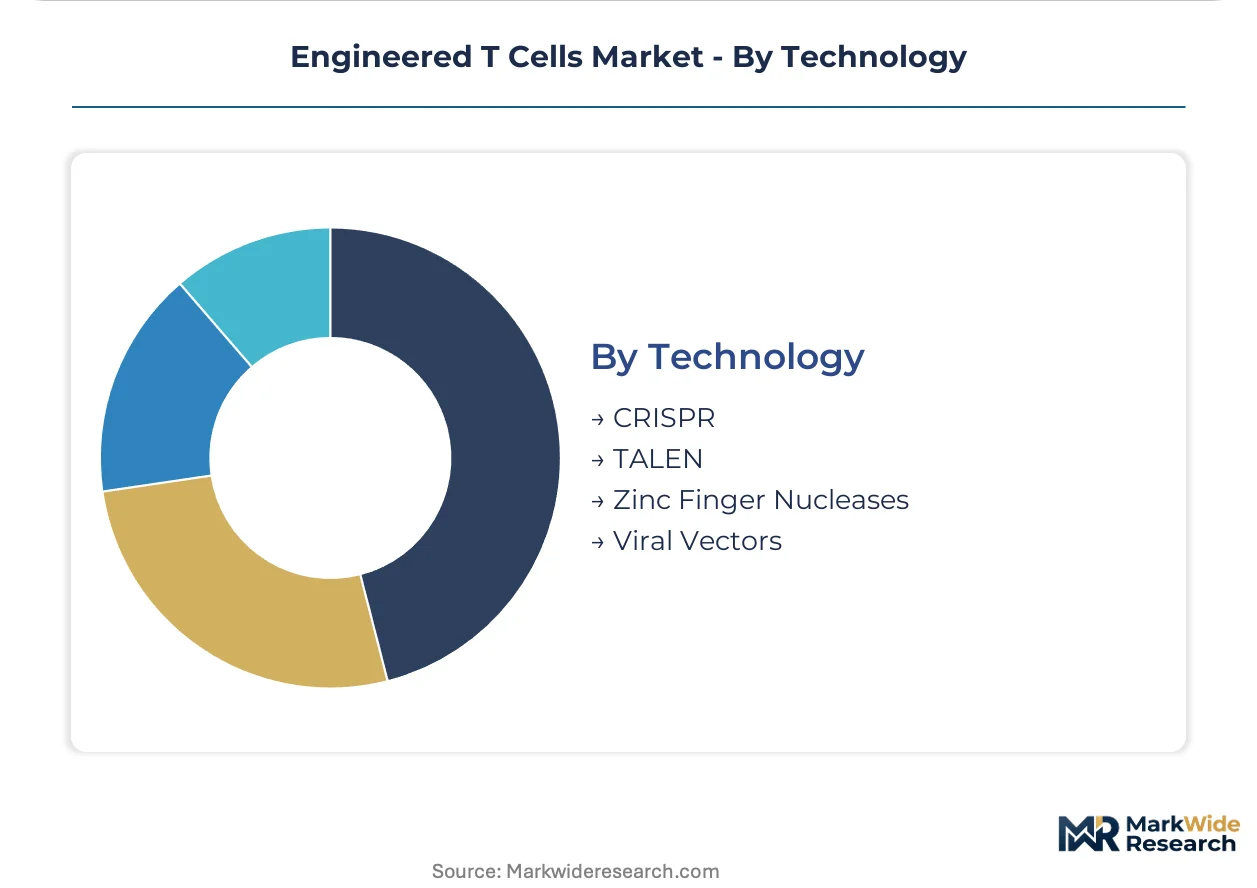
Technology:
Supply concentration in viral vector manufacturing is accelerating platform substitution toward gene-editing modalities with reduced external dependency.
- CRISPR:RNA-guided nuclease systems enabling multiplexed gene knockout and knock-in with reduced manufacturing complexity versus viral transduction. Broad Institute and University of California patent licensing structures create layered royalty burdens that concentrate development among well-capitalized developers with freedom-to-operate clearance.
- TALEN:Transcription activator-like effector nucleases offer reduced off-target activity profiles for clinical applications requiring precision editing.
- Zinc Finger Nucleases:First-generation platform with established regulatory precedent though higher development costs and longer optimization timelines.
- Viral Vectors:Lentiviral and gamma-retroviral delivery systems remain dominant in commercial CAR T manufacturing despite supply chain vulnerability to third-party GMP production constraints.
Viral Vectors anchors the volume base while CRISPR gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States show the lowest price sensitivity given established CAR T reimbursement, while emerging markets face acute cost barriers due to cryopreservation logistics and cold chain infrastructure gaps.
United States
Oncology centers at academic medical centers in Boston, Houston, and Seattle are expanding dedicated CAR T therapy programs with integrated apheresis capabilities. FDA regenerative medicine advanced therapy designation compresses development timelines for cell and gene therapies. The National Cancer Institute-designated centers in Maryland and Texas command the highest procedure volumes as site-of-care requirements tighten under evolving CMS national coverage determinations.
Germany
University hospitals in Heidelberg, Munich, and Berlin are building dedicated GMP manufacturing suites for autologous cell therapies, concentrating European demand in these centralized clinical hubs. EMA priority medicines scheme enables accelerated assessment timelines for engineered T cell developers. The Rhine-Main and Upper Bavaria regions host the densest clusters of contract manufacturing organizations supporting viral vector production.
China
Domestic biotech developers are advancing CRISPR-edited allogeneic platforms through NMPA's breakthrough therapy designation pathway. The country's national pharmaceutical regulator has streamlined IND review timelines for innovative cell therapies. Shanghai and Suzhou industrial parks house concentrated GMP manufacturing infrastructure serving both domestic trials and export-oriented contract development.
United Kingdom
London and Cambridge research institutes drive preclinical platform development with support from UK Research and Innovation funding mechanisms. The MHRA operates under retained EU legislation for advanced therapy medicinal products while developing post-Brexit divergence pathways. The Golden Triangle biotech cluster attracts engineered T cell specialists seeking proximity to translational research infrastructure.
Japan
PMDA's regenerative medicine product designation creates accelerated approval pathways for engineered T cell therapies targeting hematologic malignancies. The Kanto region around Tokyo hosts the majority of domestic clinical trial sites with apheresis and infusion capabilities. Osaka-based pharmaceutical manufacturers are pursuing strategic partnerships to secure viral vector supply chains for commercial manufacturing scale-up.
Engineered T Cells Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes in engineered T cell development, with vector manufacturing scale separating premium-tier developers from outsourced-dependent competitors. The market structure consolidates around large pharmaceutical manufacturers with captive viral production networks and biotechnology specialists with platform licensing strategies. Three archetypes dominate: integrated manufacturers controlling end-to-end supply chains, platform licensors monetizing CRISPR and CAR constructs, and regional contract developers serving geographic markets. M&A activity concentrates on pipeline acquisition for solid tumor indications, while strategic partnerships address viral vector supply constraints.
Within the integrated pharmaceutical tier, Novartis AG and Gilead Sciences exemplify divergent supply chain strategies for commercial CAR T manufacturing. Bristol-Myers Squibb occupies a position spanning both hematologic and solid tumor platform diversification. These three companies represent contrasting archetypes: the multi-continental vector producer, the concentrated regional manufacturing anchor, and the diversified modality portfolio builder respectively.
| Leading Market Players |
|---|
| Novartis AG |
| Gilead Sciences |
| Bristol-Myers Squibb |
| Amgen Inc |
| Pfizer Inc |
| Eli Lilly and Company |
| Bellicum Pharmaceuticals Inc |
| Precision BioSciences Inc |
| Oxford Biomedica Plc |
| Others |
Supply & Pricing Matrix
Vector manufacturing scale economies at Novartis AG's three-continent production network compress unit costs for lentiviral delivery systems while simultaneously erecting price floors that outsourced-dependent competitors struggle to match. Cryopreservation infrastructure requirements below minus 150 degrees Celsius concentrate bargaining power among United States academic medical centers with integrated apheresis capabilities, forcing price stratification between GMP-adjacent hospital systems and community oncology practices excluded from CMS reimbursement eligibility.
Pricing Analysis
After-sales service contracts for cryogenic logistics and patient monitoring programs capture lifetime value exceeding the initial infusion procedure. Three-tier pricing structure across premium autologous CAR T, standard allogeneic platforms, and economy research-grade vectors reflects FDA regenerative medicine advanced therapy designation tiers and GMP certification levels. Pricing pressure stems from CRISPR-mediated manufacturing simplification reducing COGS for gene-edited T cells. Academic medical centers in Boston and Houston exhibit lowest price sensitivity given established reimbursement, while emerging biotech developers face acute cost barriers from viral vector spot purchasing.
Supply Chain Analysis
Strategic stockpiling of cryopreserved apheresis collections dominates inventory strategy over just-in-time vector transduction given patient scheduling synchronization requirements across dispersed clinical sites. Viral vector manufacturing concentrates in the United States, Germany, and China, with lentiviral production drawing from third-party GMP partnerships at Oxford Biomedica and concentrated academic center capacity. Plasmid DNA, cell culture media, and dimethyl sulfoxide cryoprotectant constitute critical input dependencies. Single-source vulnerability to gamma-retroviral vector suppliers creates structural risk exposure. Distribution runs through hospital-integrated apheresis networks rather than wholesale pharmaceutical channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through FDA regenerative medicine advanced therapy designation and EMA priority medicines scheme creates formidable defensive moats for established players with validated manufacturing workflows and payer contracts.
For Market Incumbents: Compound manufacturing scale advantages through captive viral vector capacity additions in the Rhine-Main region and Southern California manufacturing corridors. Deepen backward integration into plasmid DNA supply to offset third-party GMP partnership dependencies. Defend against allogeneic platform substitution by accelerating TCR T cell solid tumor pipelines through NCI-designated center networks. For New Entrants and Emerging Players: White-space in autoimmune disorder engineered T cell applications offers penetrable entry points where reimbursement frameworks remain unresolved and incumbent clinical trial infrastructure concentrates on oncology. Target regulatory T cell engineering for lupus and multiple sclerosis through partnerships with university hospitals in Heidelberg and Berlin building dedicated GMP suites. Pursue platform licensing strategies rather than integrated manufacturing to circumvent capital intensity barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors biotechnology specialists with CRISPR-edited allogeneic platforms and freedom-to-operate clearance from Broad Institute licensing structures. Long-term viability rests on solid tumor indication expansion beyond B-cell malignancies where CAR T cells currently dominate. Acquisition target archetype includes preclinical TCR T cell developers with validated intracellular antigen targeting. Watch NMPA breakthrough therapy designations for Chinese domestic allogeneic platforms as inflection indicator for geographic manufacturing gravity shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive viral vector production at Novartis AG's three-continent network secures supply chain continuity for commercial CAR T programs. |
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation compresses development timelines and accelerates commercial launch sequences. |
| Pipeline Diversification | TCR T cell platforms targeting intracellular antigens expand addressable indications beyond B-cell malignancies into lung and pancreatic cancers. |
| Licensing Agreement | CRISPR patent structures from Broad Institute create layered royalty burdens that concentrate development among well-capitalized developers. |
| Clinical Trial Advancement | Multi-site coordination across NCI-designated centers in Maryland and Texas commands highest procedure volumes for solid tumor indications. |
Research Methodology
Cross-validation between primary interviews with cell therapy manufacturing scientists and secondary analysis of FDA filings anchors the qualitative findings in this study. Drug development executives at integrated pharmaceutical manufacturers, regulatory affairs leads navigating EMA priority medicines schemes, hospital procurement managers at academic medical centers, and payer access specialists at CMS contractor organizations provided operational perspective. Secondary validation drew from ClinicalTrials.gov protocol databases, EMA advanced therapy medicinal product submissions, CMS national coverage determination documents, and hospital GPO contract structures. Bottom-up patient volume modeling and top-down revenue triangulation across product type and therapy area segments ensured analytical consistency.
Sensitivity analysis around viral vector manufacturing capacity utilization and allogeneic platform substitution rates informs the projection framework across the analysis window. Segmentation dimensions modeled include product type, therapy area, end user, and technology platform, with regional regulatory cluster effects layered across United States, Germany, China, United Kingdom, and Japan markets. CAGRs derive from patient volume forecasts multiplied by reimbursement rate trajectories, with cryopreservation logistics cost curves and manufacturing scientist wage inflation as industry-specific forecast inputs.
Forecasts assume regulatory continuity in FDA regenerative medicine advanced therapy designation and EMA priority medicines scheme regimes; material policy shifts would require re-modeling. Specific risk factors include CMS site-of-care reimbursement restrictions tightening eligibility, EU AI Act algorithmic transparency requirements adding validation burdens, and NMPA breakthrough therapy designation accelerating Chinese domestic competition. Revision becomes warranted when allogeneic platform manufacturing cost compression crosses thresholds enabling broad reimbursement expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
RNAI Technology Market
Cell & Gene Therapy
Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Global Gene Therapy Market
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
Viral Vector and Plasmid DNA Testing Service Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market
Cell & Gene Therapy
Ipilimumab Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Cell and Gene Therapy Manufacturing Market