
 Rheumatoid Arthritis Stem Cell Therapy Market | 2026-2036
Rheumatoid Arthritis Stem Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Rheumatoid Arthritis Stem Cell Therapy Market Analytics
The EU Green Deal's pharmaceutical sustainability criteria is restructuring procurement standards for advanced cell therapies across European hospital networks. Novartis AG leverages its CAR-T manufacturing infrastructure to extend capabilities into autologous stem cell platforms for autoimmune indications. Bristol-Myers Squibb Company anchors its position through sustained R&D investment in pluripotent-derived immunomodulatory cell lines. Johnson & Johnson competes via its specialized orthobiologics distribution channels in North American academic medical centers.
Rheumatoid Arthritis Stem Cell Therapy deploys living cellular products—predominantly mesenchymal stem cells expanded ex vivo under GMP conditions—to modulate pathogenic T-cell activity and restore synovial tissue homeostasis. The intervention targets refractory patient populations where conventional DMARD and biologic sequences have failed, requiring cryopreserved or fresh formulations with defined potency assays. Mesenchymal Stem Cells dominate current clinical pipelines due to established immunosuppressive paracrine signaling and lower tumorigenic risk profiles compared to pluripotent alternatives. Allogeneic Therapy configurations attract manufacturing investment because centralized batch production reduces cost-per-dose versus patient-specific autologous processing. Intravenous Injection retains the broadest addressable patient base, though Intra-articular Delivery commands premium positioning in refractory monoarticular presentations.
FDA's regenerative medicine advanced therapy designation and EMA's priority medicines pathway create divergent market access timelines that shape corporate geographic sequencing strategies. Japan's PMDA conditional early approval system for regenerative products accelerates commercial launch for firms meeting post-market surveillance commitments. Stakeholders must monitor evolving reimbursement benchmarks for cell therapies in Germany's G-BA assessment framework and the United States' CMS national coverage determination processes.
Market Dynamics
Allogeneic manufacturing scale-up is compressing cost-per-dose differentials between centralized batch production and autologous processing, forcing therapy developers to reconfigure facility investments and partnership structures around cryopreserved inventory models.
Growth Catalysts
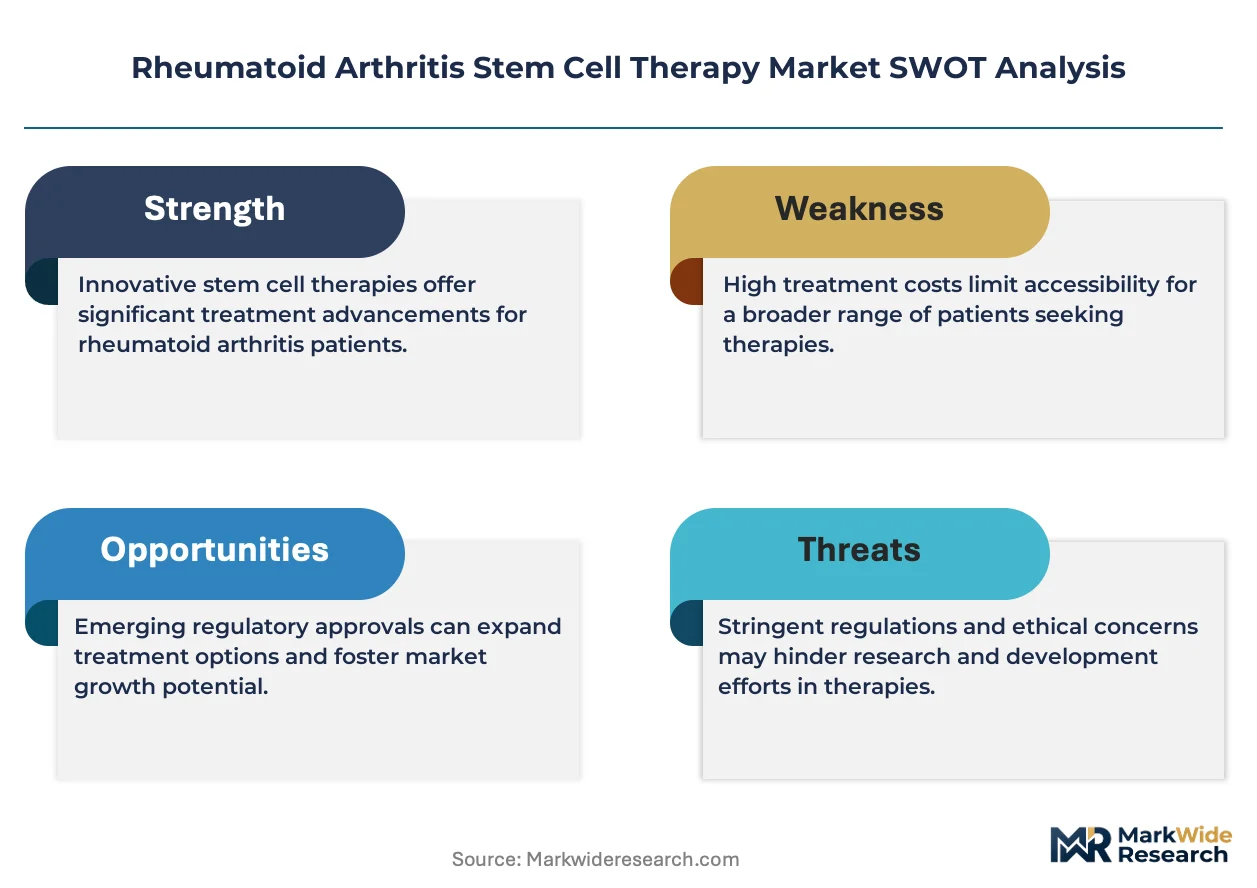
- FDA Regenerative Medicine Advanced Therapy Designation:The accelerated approval pathway compresses clinical-to-commercial timelines for mesenchymal stem cell products targeting refractory rheumatoid arthritis populations.
- Hospital-based infusion centers:These end-user channels are expanding capacity for cell therapy administration faster than standalone clinics, concentrating patient access velocity in academic medical center networks.
- Japan PMDA Conditional Early Approval:The regenerative product framework permits commercial launch with post-market surveillance commitments, attracting developers seeking earlier revenue recognition.
Market Restraints
- GMP-grade cytokine supply concentration:Recombinant growth factor production for ex vivo cell expansion concentrates among three contract manufacturers, creating input cost volatility and batch-to-batch variability risks.
- EMA adaptive licensing uncertainty:The iterative evidence-generation requirement extends reimbursement negotiation timelines, delaying hospital formulary inclusion decisions across German and French networks.
- Pluripotent stem cell tumorigenicity:Residual undifferentiated cell detection limits in immunomodulatory lineages restrict clinical pipeline progression compared to mesenchymal alternatives.
Strategic Opportunities
- Intra-articular delivery refractory monoarticular presentations:Premium positioning in single-joint failures unresponsive to systemic biologics commands higher reimbursement rates than intravenous administration.
- Germany G-BA assessment framework evolution:Early engagement with the benefit assessment process for cell therapies creates first-mover advantage in statutory health insurance coverage.
- Cryopreservation potency assay standardization:Convergence of automated cell counting with metabolomic viability markers enables inventory banking that decouples manufacturing from patient scheduling.
Industry Challenges
- Vector chemistry skill scarcity:Viral transduction expertise for engineered mesenchymal lines concentrates in gene therapy specialists, forcing autoimmune developers to compete for identical talent pools.
- ISO 14644 cleanroom capex intensity:Grade A/B suite construction for allogeneic batch production requires capital deployment that strains mid-cap balance sheets before revenue materialization.
- Release specification harmonization delays:Divergent potency assay requirements between FDA, EMA, and PMDA prevent single-batch global distribution, fragmenting manufacturing scale economies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rheumatoid Arthritis Stem Cell Therapy Market |
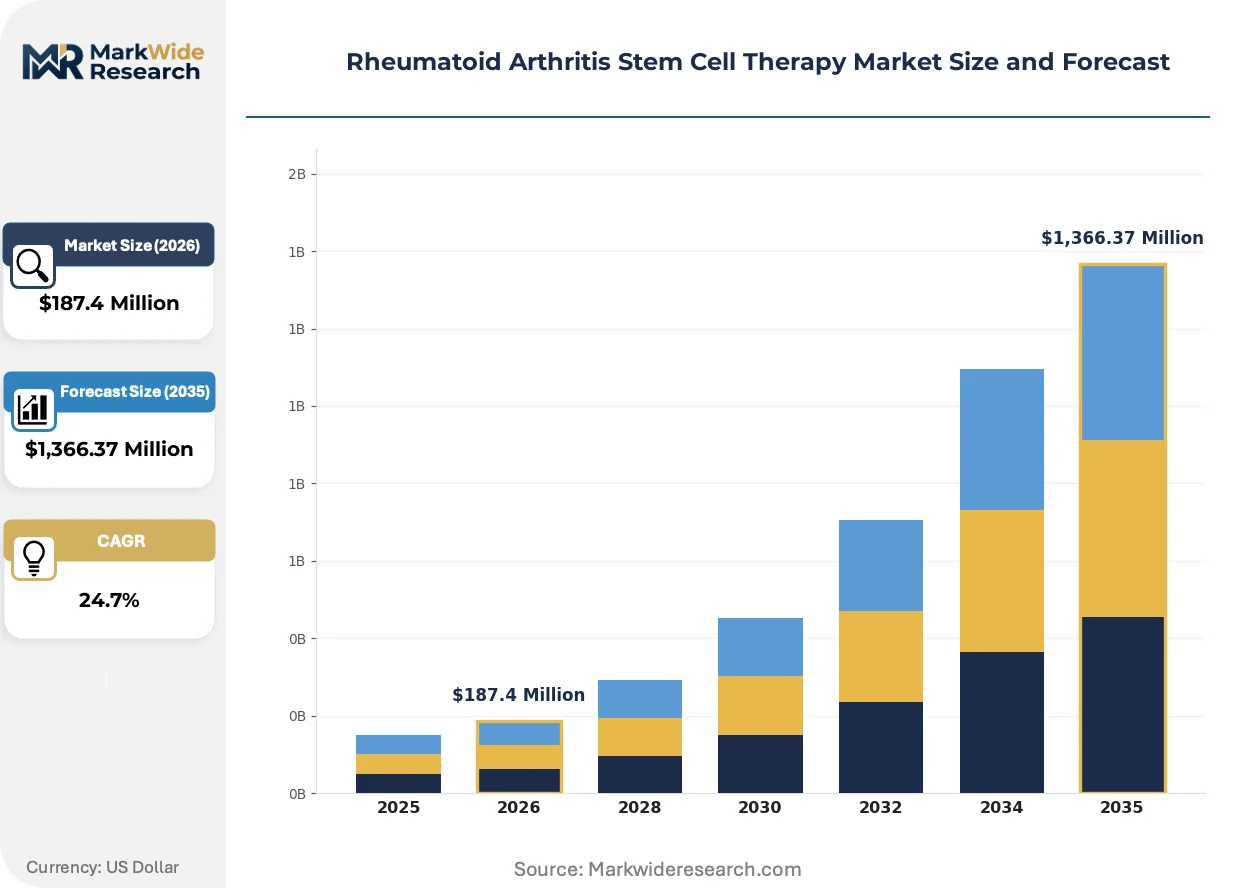
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,366.37 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mesenchymal Stem Cells, Hematopoietic Stem Cells, Adipose-derived Stem Cells, Induced Pluripotent Stem Cells Delivery Mode: Intravenous Injection, Intra-articular Injection, Subcutaneous Injection, Infusion End User: Hospitals, Research Institutions, Clinics, Rehabilitation Centers Therapeutic Approach: Autologous Therapy, Allogeneic Therapy, Combination Therapy, Regenerative Medicine |
| Companies Covered | Novartis AG, Kyverna Therapeutics, Bristol-Myers Squibb Company, Iovance Biotherapeutics, Adaptimmune Therapeutics, Johnson & Johnson, AbbVie Inc., Vericel Corporation, Gilead Sciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rheumatoid Arthritis Stem Cell Therapy Market Evolving Landscape
Automation platforms for cell expansion and cryopreservation are displacing manual GMP processing, while regulatory convergence efforts attempt to align batch release standards across major jurisdictions. These forces are compressing development timelines and reshaping competitive differentiation.
Closed-system bioreactors with integrated metabolite monitoring are rewriting manufacturing economics for mesenchymal stem cell expansion. Large academic medical centers in the United States are adopting these platforms to insource production for investigator-initiated trials. The technology is rewriting the scale threshold at which centralized allogeneic manufacturing maintains cost advantage over hospital-based production.
EMA's priority medicines pathway for regenerative therapies is compressing scientific advice and protocol assistance timelines for autoimmune indications. The framework requires parallel health technology assessment preparation, forcing developers to front-load economic modeling. German hospital networks are responding by establishing dedicated cell therapy pharmacy committees ahead of formal reimbursement decisions.
Specialist rheumatology clinics are consolidating purchasing authority through group purchasing organizations that negotiate directly with manufacturers, bypassing traditional wholesale distribution. The channel shift concentrates volume among fewer buyers, pressuring price transparency and service bundling. This pattern is most visible in United States metropolitan markets with high specialist density and integrated delivery network penetration.
Rheumatoid Arthritis Stem Cell Therapy Market Segmentation
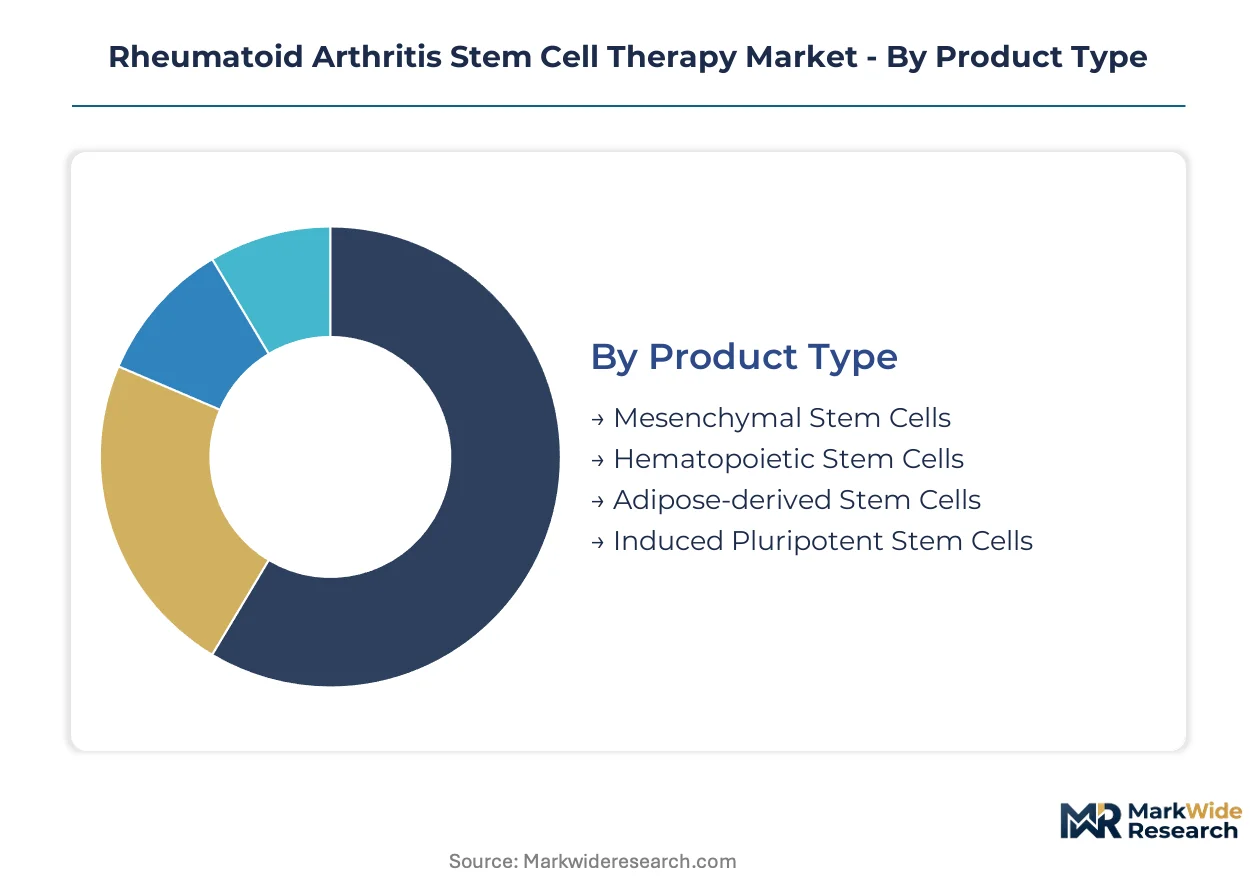
Cell therapy developers configure product portfolios around manufacturing scalability, regulatory complexity, and site-of-care economics. Segment boundaries determine partnership structures with contract manufacturers, infusion center networks, and reimbursement negotiators.
Product Type:
Immunomodulatory potency and tumorigenic risk profiles differentiate therapeutic positioning across cell lineages.
- Mesenchymal Stem Cells:Ex vivo expanded under GMP conditions with established paracrine immunosuppressive signaling. Demand concentrates in United States academic medical centers where FDA regenerative medicine advanced therapy designation accelerates commercial timelines.
- Hematopoietic Stem Cells:Bone marrow-derived populations requiring myeloablative conditioning protocols. German hospital networks favor these for severe refractory cases under EMA adaptive licensing frameworks.
- Adipose-derived Stem Cells:Lipoaspirate processing yields stromal vascular fractions with lower expansion requirements.
- Induced Pluripotent Stem Cells:Reprogrammed somatic lines face residual undifferentiated cell detection limits that restrict clinical pipeline progression.
Mesenchymal Stem Cells lead volumes today; Induced Pluripotent Stem Cells are climbing the fastest on engineered immunomodulatory platforms.
Delivery Mode:
Route selection shapes dosing frequency, pharmacy preparation complexity, and site-of-care capital requirements.
- Intravenous Injection:Systemic distribution enables multi-joint disease management without arthroscopic guidance. United States metropolitan markets with integrated delivery network penetration favor this modality for scale.
- Intra-articular Injection:Direct synovial cavity administration demands ultrasound or fluoroscopic guidance. Japanese specialist clinics command premium reimbursement under PMDA conditional early approval for monoarticular refractory presentations.
- Subcutaneous Injection:Dermal administration routes simplify outpatient logistics but limit joint-specific bioavailability.
- Infusion:Extended delivery protocols accommodate larger cell doses with nursing supervision requirements.
Intravenous Injection retains the broadest patient base; Intra-articular Injection is expanding most quickly on premium positioning.
End User:
Capital intensity and regulatory accreditation separate institutional categories for cell therapy administration.
- Hospitals:Academic medical centers with embedded GMP pharmacies and cryopreservation infrastructure dominate allogeneic therapy distribution. German university hospitals leverage EMA scientific advice pathways to accelerate formulary inclusion.
- Research Institutions:Investigator-initiated trial sites with closed-system bioreactor platforms challenge centralized manufacturing economics. United States NIH-funded centers are insourcing production for early-phase autoimmune studies.
- Clinics:Specialist rheumatology practices consolidate purchasing through group purchasing organizations.
- Rehabilitation Centers:Post-acute facilities focus on functional outcome monitoring rather than cellular product handling.
Hospitals capture the majority of commercial volume; Research Institutions are gaining share fastest on manufacturing platform adoption.
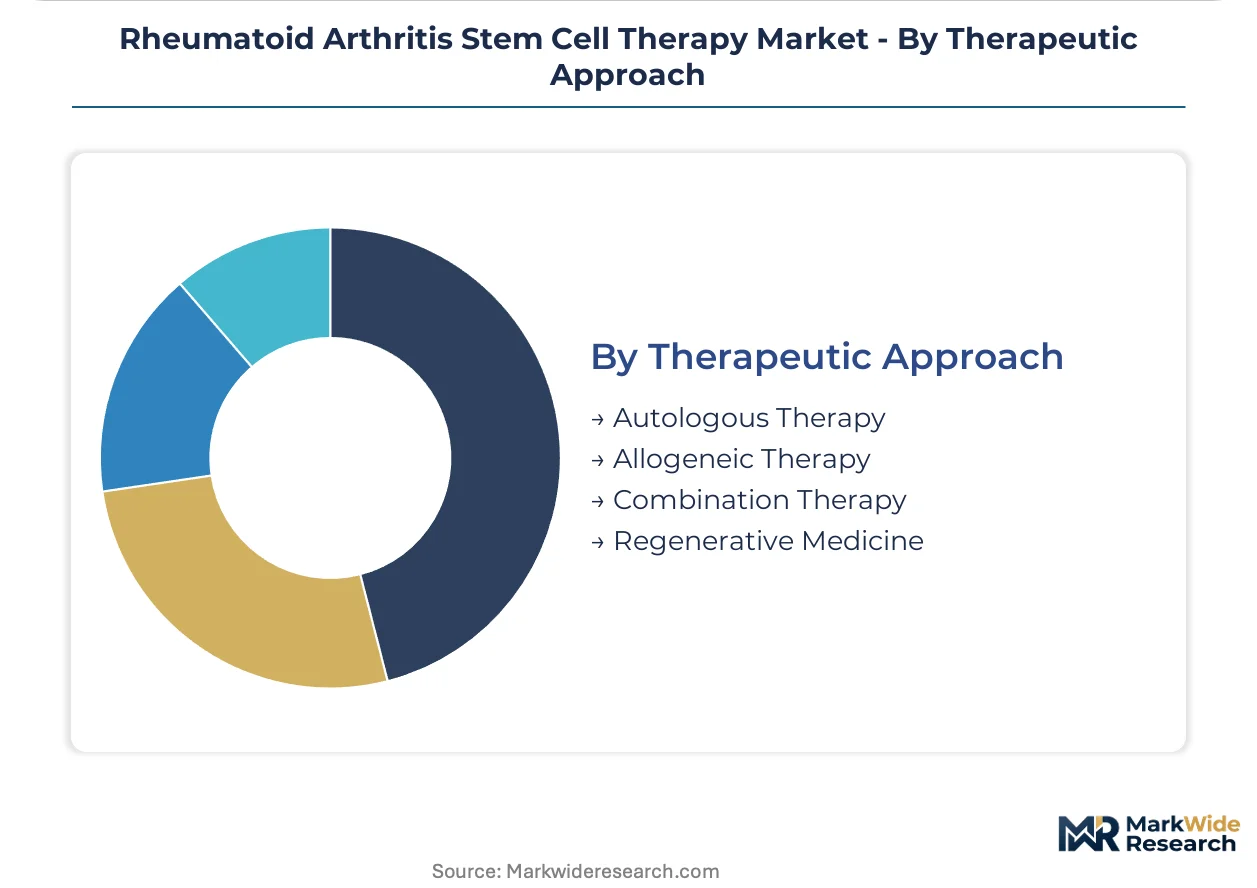
Therapeutic Approach:
Cell source configuration determines batch economics, inventory models, and patient scheduling flexibility.
- Allogeneic Therapy:Centralized batch production from qualified donors enables cryopreserved inventory banking. Manufacturing investment concentrates here as cost-per-dose compression outpaces autologous processing.
- Autologous Therapy:Patient-specific harvest and expansion requires vein-to-vein logistics coordination. Japanese commercial launches under PMDA post-market surveillance commitments favor this model for traceability.
- Combination Therapy:Sequential or concurrent biologic administration protocols complicate safety signal attribution.
- Regenerative Medicine:Tissue engineering approaches with scaffold integration remain preclinical for synovial applications.
Allogeneic Therapy dominates manufacturing investment; Autologous Therapy is expanding most quickly on personalized medicine positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rheumatoid arthritis stem cell therapy originated in academic medical centers across the United States and Germany during the early 2000s, with commercial scale-up accelerating after 2015 as GMP manufacturing standards consolidated in these markets.
United States
FDA regenerative medicine advanced therapy designation draws developers seeking compressed clinical timelines. Hospital-based infusion centers in Boston, New York, and San Francisco concentrate patient access velocity. CMS national coverage determination processes for cell therapies remain under active stakeholder negotiation.
Germany
EMA adaptive licensing frameworks extend reimbursement timelines while enabling earlier patient access. G-BA benefit assessments for mesenchymal stem cell products concentrate decision authority in Berlin and Cologne. University hospitals in Munich and Heidelberg leverage scientific advice pathways to accelerate formulary inclusion.
Japan
PMDA conditional early approval system permits commercial launch with post-market surveillance commitments. Specialist rheumatology clinics in Tokyo and Osaka command premium reimbursement for intra-articular delivery. METI industrial policy supports domestic manufacturing infrastructure for autologous processing.
Switzerland
Swissmedic alignment with EMA standards enables parallel regulatory submissions for alpine region access. Basel and Zurich anchor contract manufacturing concentration for allogeneic batch production. The country's pharmaceutical cluster hosts quality control laboratories serving EU distribution networks.
United Kingdom
MHRA post-Brexit regulatory autonomy creates divergence risk from EMA batch release standards. London and Cambridge academic centers maintain investigator-initiated trial capacity with closed-system bioreactor adoption. NHS specialized commissioning frameworks for cell therapies remain under national program development.
Rheumatoid Arthritis Stem Cell Therapy Market Competitive Landscape
Capital-heavy biopharmaceutical manufacturers compete with asset-light cell therapy developers for control of commercialization timelines. The market structure concentrates around integrated pharmaceutical conglomerates with existing CAR-T infrastructure, mid-cap autoimmune specialists, and emerging platform technology firms. Three archetypes dominate: legacy biologics players extending into cellular modalities, dedicated regenerative medicine companies, and diversified healthcare conglomerates leveraging orthobiologics channels. Competitive intensity manifests through strategic partnerships with contract manufacturers and exclusive distribution arrangements with academic medical center networks.
Among Swiss-based pharmaceutical conglomerates, Novartis AG occupies a position exemplifying CAR-T infrastructure extension into autoimmune applications. Bristol-Myers Squibb Company represents the legacy biologics archetype with sustained R&D positioning in pluripotent-derived immunomodulatory platforms. Johnson & Johnson anchors the diversified healthcare conglomerate tier through specialized orthobiologics distribution channels in North American academic medical centers.
| Leading Market Players |
|---|
| Novartis AG |
| Kyverna Therapeutics |
| Bristol-Myers Squibb Company |
| Iovance Biotherapeutics |
| Adaptimmune Therapeutics |
| Johnson & Johnson |
| AbbVie Inc. |
| Vericel Corporation |
| Gilead Sciences |
| Others |
Value Network & Pricing Analysis
Allogeneic batch production cost compression versus autologous patient-specific processing creates a bifurcated pricing architecture that reshapes both manufacturing facility investments and downstream procurement negotiations across United States, German, and Japanese hospital networks.
Pricing Analysis
Premium-mid-economy pricing differentiation separates cryopreserved allogeneic doses with standardized potency assays from fresh autologous formulations requiring vein-to-vein logistics coordination. Price differentiation hinges on GMP certification tier and volume commitment scale, with academic medical center group purchasing organizations extracting steepest discounts. Cost compression in allogeneic manufacturing is intensifying because closed-system bioreactor automation displaces manual cell expansion labor. Research institutions with insourced production capabilities exhibit lowest price sensitivity; standalone specialist clinics face highest procurement cost exposure.
Supply Chain Analysis
Cryopreserved cell product logistics costs concentrate in cold-chain integrity maintenance across United States, Switzerland, and Singapore distribution nodes. Recombinant growth factor production for ex vivo expansion draws from three contract manufacturers, creating input cost volatility. Single-source vulnerability in GMP-grade cytokine supply exposes batch economics to disruption. Distribution runs through hospital-based infusion centers with embedded GMP pharmacy infrastructure rather than wholesale pharmaceutical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Rheumatoid arthritis stem cell therapy operates as a regulatory compounder where FDA regenerative medicine advanced therapy designation and PMDA conditional early approval frameworks accelerate commercial timelines and reshape capital deployment priorities.
For Market Incumbents: Anchor manufacturing scale advantage through backward integration into cryopreservation potency assay standardization, defending against mid-cap competitors adopting closed-system bioreactor platforms. Prioritize exclusive distribution arrangements with German university hospitals navigating G-BA benefit assessment timelines. Capacity addition in Swiss contract manufacturing clusters secures EU batch release flexibility against EMA adaptive licensing uncertainty. For New Entrants and Emerging Players: Refractory monoarticular presentation specialists in Japanese metropolitan markets represent the most penetrable buyer archetype, commanding premium reimbursement under PMDA conditional approval with lower competitive density than United States systemic therapy segments. Target investigator-initiated trial sites with insourced production capabilities seeking allogeneic supply partnerships. Go-to-market angle emphasizes cryopreserved inventory banking that decouples manufacturing from patient scheduling constraints. For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 14644 cleanroom capex intensity strains mid-cap balance sheets before revenue materialization, favoring acquisition of platform technology firms with automated cell expansion capabilities over asset-heavy manufacturing developers. Long-term viability in this market hinges on regulatory convergence across FDA, EMA, and PMDA batch release standards. Signal to watch is harmonization of potency assay requirements enabling single-batch global distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA regenerative medicine advanced therapy designation compresses clinical-to-commercial timelines for mesenchymal stem cell products. |
| Manufacturing Scale-Up | Closed-system bioreactor adoption rewrites scale thresholds for centralized allogeneic versus hospital-based production economics. |
| Reimbursement Strategy | Early G-BA engagement in Germany creates first-mover advantage in statutory health insurance coverage for cell therapies. |
| Hospital System Partnership | Exclusive distribution arrangements with academic medical centers concentrate patient access velocity in high-specialist-density networks. |
| Pipeline Diversification | Pluripotent-derived immunomodulatory platforms extend addressable populations beyond mesenchymal stem cell refractory limits. |
Research Methodology
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and hospital procurement managers; secondary validation through FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases; plus bottom-up and top-down triangulation — were reconciled to construct market estimates across the analysis window.
Data-stream reconciliation applied treatment line, administration route, therapeutic approach, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from patient population epidemiology, reimbursement trajectory modeling, and manufacturing capacity expansion announcements throughout the forecast period.
Underlying measurement precision varies by segment; allogeneic therapy volumes carry tighter precision than autologous processing given centralized batch production transparency. Forecasts reflect assumptions around regulatory approval timelines and reimbursement negotiation outcomes that could shift with EMA adaptive licensing evolution or CMS national coverage determination revisions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Oncolytic Virus Therapy Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
Cell Reprogramming Market
Cell & Gene Therapy
Gene Delivery Technologies Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Asia-Pacific Viral Vector Purification Market
Cell & Gene Therapy
Cell Therapy Manufacturing Market
Cell & Gene Therapy
Hemophilia Therapeutics Market
Cell & Gene Therapy
Autologous Stem Cell and Non Stem Cell Based Therapies Market