
 Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market | 2026-2036
Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market Size, Share, and Industry Trends Forecast 2026-2036
Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market Insights
Real-time spectroscopic monitoring integrated with bioreactor control systems is reshaping how cell therapy manufacturers execute batch release decisions. Thermo Fisher Scientific leverages its chromatography portfolio to anchor downstream analytics workflows for gene therapy vectors. Sartorius sustains technology leadership through specialized electrochemical sensor platforms designed for adherent cell culture monitoring. Repligen differentiates via focused R&D intensity in single-use flow path integration for perfusion bioreactor applications.
Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms comprise integrated hardware-software systems that perform in-line measurement of critical quality attributes including dissolved oxygen, pH, glucose, lactate, and viable cell density during bioprocessing, with spectroscopic and chromatographic methods enabling real-time process control without sample withdrawal. Automated PAT Systems capture the largest installed base among platform types due to their integration with distributed control systems in commercial manufacturing suites. Flow Cytometry represents the fastest-expanding measurement technology segment as multi-parameter cell characterization becomes essential for autologous therapy release testing. Data Integration Software commands expanding budget allocations as manufacturers seek to harmonize batch records across disqualified equipment from multiple vendors.
FDA Process Analytical Technology guidance and EMA reflection papers on quality by design collectively shape validation protocols for real-time release testing in commercial cell therapy manufacturing. ISO 20391-1 cell counting standards and USP <1046> cell and gene therapy products chapters establish metrological traceability requirements that directly influence instrument procurement specifications. Stakeholders must evaluate whether their current analytics infrastructure can accommodate the shift from offline testing to continuous verification paradigms as regulatory agencies narrow acceptable variance windows for critical process parameters.
Market Dynamics
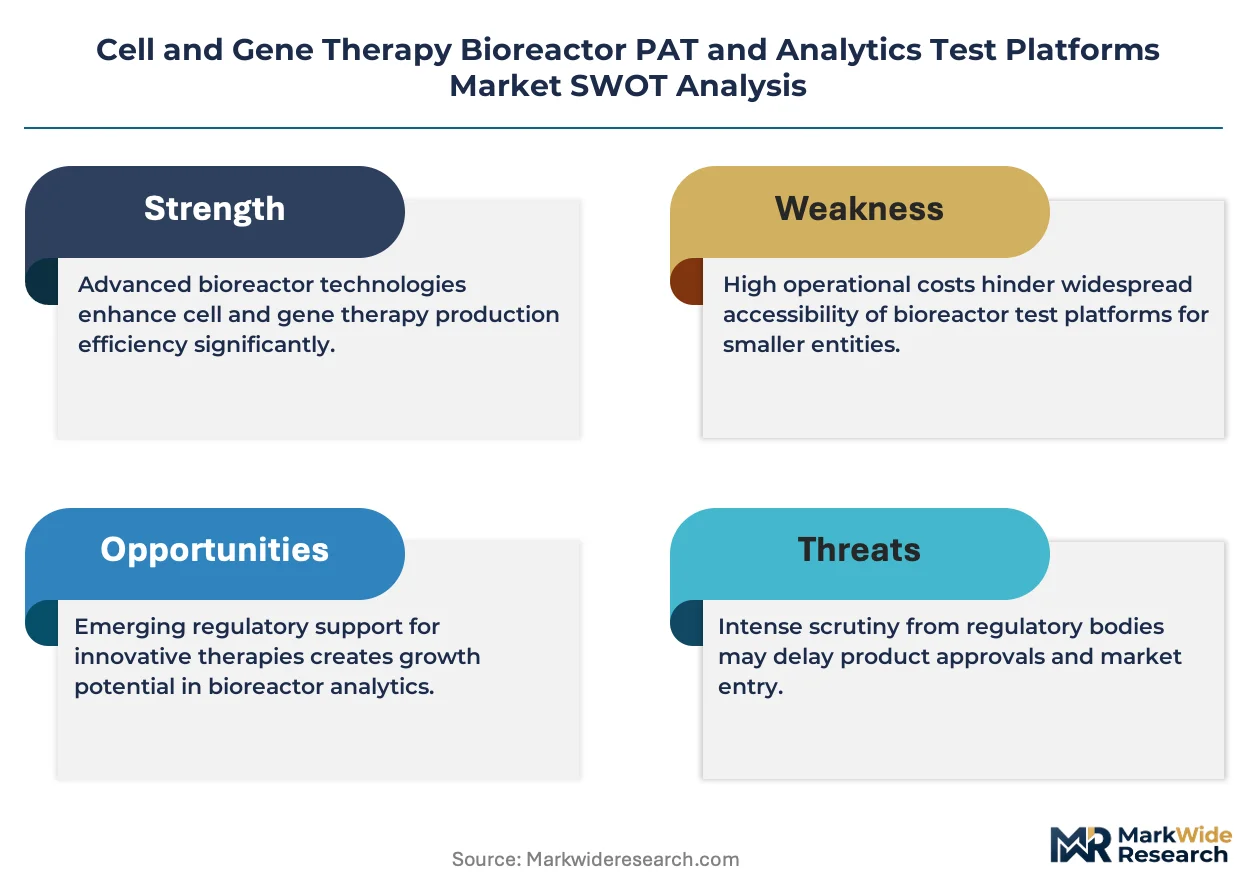
Real-time release testing mandates from FDA and EMA are compressing validation timelines for bioreactor PAT systems, forcing manufacturers to abandon offline analytics in favor of continuous verification architectures that integrate spectroscopic sensors directly into distributed control systems.
Growth Catalysts
- EMA Reflection Papers on Quality by Design:European regulatory guidance accelerates adoption of in-line metabolite monitoring for autologous cell therapy release, creating procurement pull for integrated hardware-software platforms.
- Perfusion Bioreactor Scale-Up:Gene therapy vector manufacturers deploy single-use flow path systems to maintain sterility during extended culture durations, driving sensor miniaturization R&D.
- CDMO Infrastructure Concentration:United States-based contract development organizations expand analytical service offerings to capture cell therapy manufacturing outsourcing from emerging biotech developers.
Market Restraints
- Optical Sensor Component Supply:German and Japanese specialty photonics suppliers control Raman spectroscopy probe manufacturing, creating single-source vulnerability for bioreactor integrators.
- ISO 20391-1 Metrological Compliance Costs:Cell counting standard traceability requirements force redundant instrument qualification protocols that extend deployment timelines by 6-12 months.
- Fluorescence Microscopy Substitution:Offline imaging platforms retain installed base in early-stage R&D settings where capital constraints delay PAT adoption.
Strategic Opportunities
- South Korea MFDS Fast-Track Pathway:Regulatory acceleration for cell therapy approvals creates demand for validated analytics platforms among domestic CDMOs building export capacity.
- Electrochemical-Chromatographic Convergence:Hybrid sensor architectures that combine dissolved oxygen probes with at-line metabolite analysis reduce sample withdrawal frequency.
- Data Integration Software White Space:Manufacturers seek middleware solutions to harmonize batch records across disqualified equipment from multiple vendors.
Industry Challenges
- Multivariate Data Analysis Skill Gap:Bioprocess engineers lack training in chemometric model development for spectroscopic calibration, forcing reliance on vendor-supplied algorithms.
- Legacy DCS Integration Friction:Brownfield manufacturing suites require custom protocol bridges to connect modern PAT sensors to established distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market |
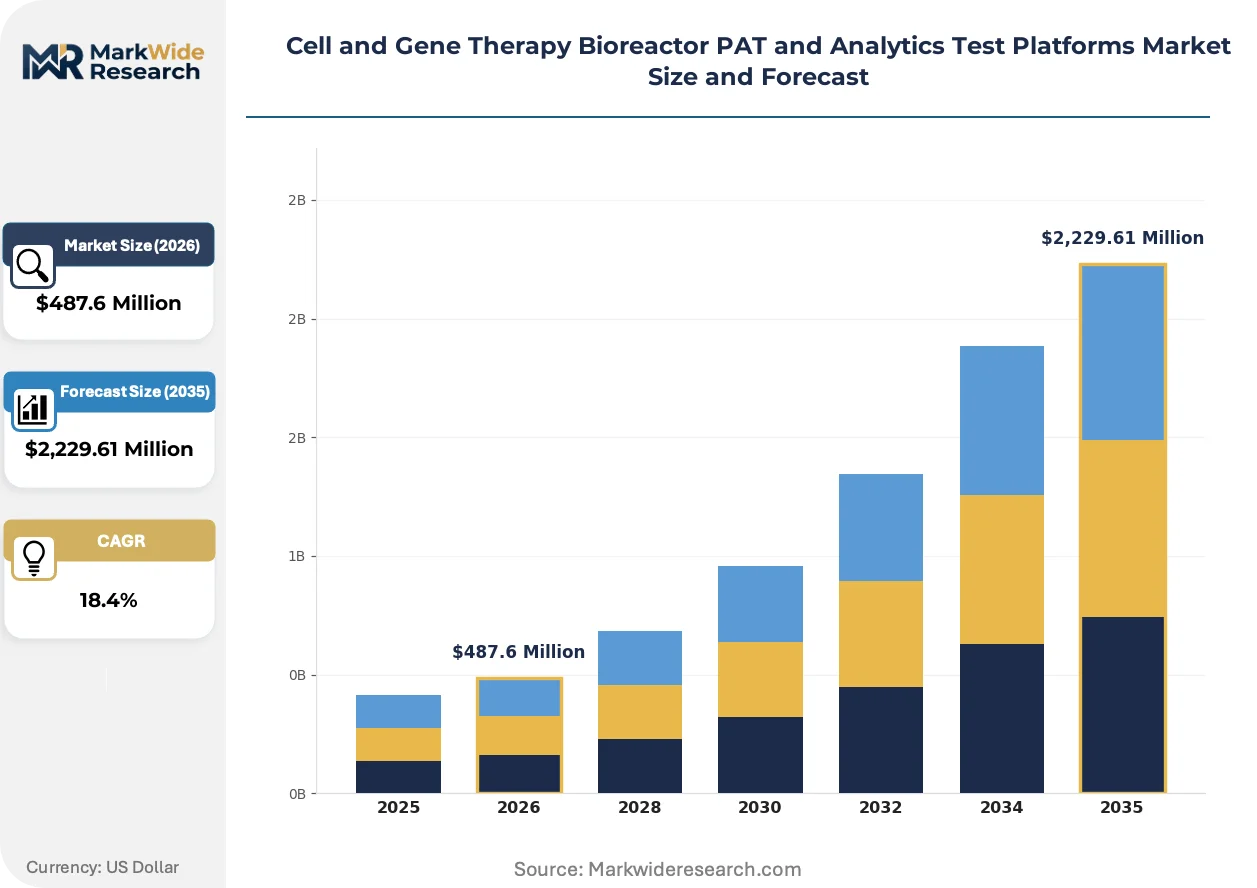
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $2,229.61 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Automated PAT Systems, Handheld Analytics Devices, Real-Time Monitoring Tools, Data Integration Software Measurement Technology: Spectroscopy, Chromatography, Flow Cytometry, Electrochemical Sensors, Mass Spectrometry Testing Application: Cell Viability Analysis, Gene Expression Profiling, Metabolite Monitoring, Protein Quantification, Impurity Detection End User Type: Biopharmaceutical Manufacturers, Research Laboratories, Contract Development Organizations, Quality Control Departments |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Sartorius, Repligen, Lonza, Miltenyi Biotec, LumaCyte, Ori Biotech, Stevanato Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market Trends and Innovations
Spectroscopic monitoring architectures are displacing extractive sampling as the dominant paradigm for bioreactor control, with software-defined analytics platforms enabling model predictive control loops that adjust process parameters without human intervention.
Raman spectroscopy is virtualizing metabolite quantification by replacing offline high-performance liquid chromatography for glucose and lactate measurement. Gene therapy vector manufacturers in commercial manufacturing suites adopt these probes at accelerating pace. This technology is virtualizing the boundary between process development and commercial operations by enabling identical analytical methods across scales.
FDA Process Analytical Technology guidance for biologics tightens validation requirements for real-time release testing in cell therapy applications. Manufacturers must demonstrate chemometric model robustness across raw material lots and operator variability. Autologous therapy developers face the steepest compliance burden as batch sizes of one preclude traditional statistical process control.
CDMOs now specify outcome-based service contracts that tie analytical performance fees to successful batch release rather than instrument uptime. This procurement model disrupts traditional capital equipment sales channels in the United States and Europe. Academic medical centers with in-house manufacturing capabilities represent the most price-sensitive buyer segment.
Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market Segmentation
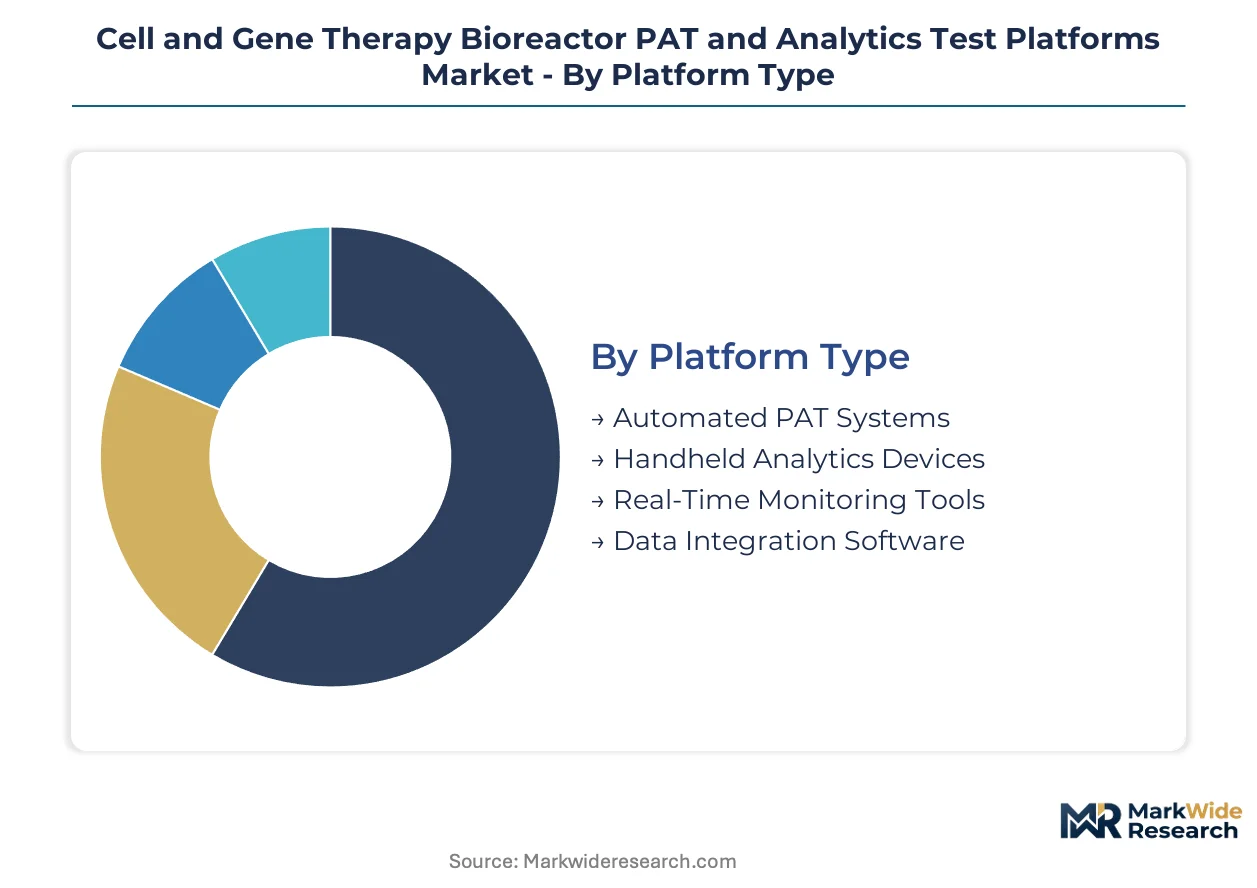
Segmentation in this market reflects the tension between validated commercial manufacturing infrastructure and emerging analytical modalities. Procurement decisions hinge on whether platforms must integrate with existing distributed control systems or operate as standalone validation tools.
Platform Type:
Use cases span from fully integrated manufacturing suites to portable field validation tools, with cost and integration complexity determining adoption patterns.
- Automated PAT Systems:These platforms combine spectroscopic sensors with distributed control system architecture for continuous verification without sample withdrawal. Demand concentrates among commercial cell therapy manufacturers in the United States facing FDA real-time release testing mandates, where integration with legacy manufacturing suites drives procurement specifications.
- Data Integration Software:Middleware solutions harmonize batch records across equipment from multiple vendors, addressing the fragmentation of brownfield manufacturing environments. Quality control departments in European biopharmaceutical operations allocate expanding budgets to these platforms as EMA reflection papers tighten data integrity requirements for autologous therapy release.
- Handheld Analytics Devices:Portable units enable at-line testing in early-stage process development settings where capital constraints delay full PAT deployment.
- Real-Time Monitoring Tools:Standalone sensor arrays provide immediate feedback on dissolved oxygen and pH without full DCS integration.
The dominant share belongs to Automated PAT Systems, while Data Integration Software is closing the gap fastest.
Measurement Technology:
Technology selection tracks the migration from extractive sampling toward non-invasive optical and electrochemical methods.
- Spectroscopy:Raman and near-infrared probes enable virtual quantification of glucose, lactate, and amino acids without chromatographic separation. Gene therapy vector manufacturers deploy these at commercial scale to eliminate offline testing bottlenecks.
- Flow Cytometry:Multi-parameter cell characterization has become essential for autologous therapy release testing where batch sizes of one preclude statistical sampling. Academic medical centers with in-house manufacturing capabilities in South Korea are expanding procurement as MFDS fast-track pathways accelerate approval timelines.
- Chromatography:High-performance liquid chromatography remains the reference standard for metabolite quantification during process validation.
- Electrochemical Sensors:Dissolved oxygen and pH probes designed for adherent cell culture monitoring anchor basic bioreactor control loops.
- Mass Spectrometry:At-line systems provide definitive identification of impurities and vector titer confirmation in gene therapy applications.
Spectroscopy holds the largest installed base, though Flow Cytometry is expanding most quickly as cell therapy complexity intensifies.
Testing Application:
Application priorities shift with therapy modality, with gene therapy developers emphasizing vector characterization and cell therapy manufacturers focusing on viability and identity.
- Cell Viability Analysis:Real-time assessment of viable cell density using impedance or optical methods enables automated feeding strategies in perfusion bioreactors. Contract development organizations specify these capabilities in service contracts that tie fees to successful batch release.
- Metabolite Monitoring:Continuous glucose and lactate measurement drives process control decisions in extended culture durations for stem cell therapies. German specialty photonics suppliers control critical Raman probe components, creating supply vulnerability for integrators serving this application.
- Gene Expression Profiling:Quantitative PCR and transcriptomic analysis verify therapeutic transgene expression during vector manufacturing.
- Protein Quantification:Titer determination for secreted therapeutic proteins relies on integrated at-line immunoassay platforms.
- Impurity Detection:Host cell protein and residual DNA analysis requires sensitive orthogonal methods for regulatory submission.
Cell Viability Analysis commands the greatest procurement volume, while Metabolite Monitoring is gaining share fastest as perfusion processes scale.
End User Type:
Buyer sophistication and integration requirements vary sharply across organizational types, from research settings with minimal validation needs to commercial suites requiring full GMP compliance.
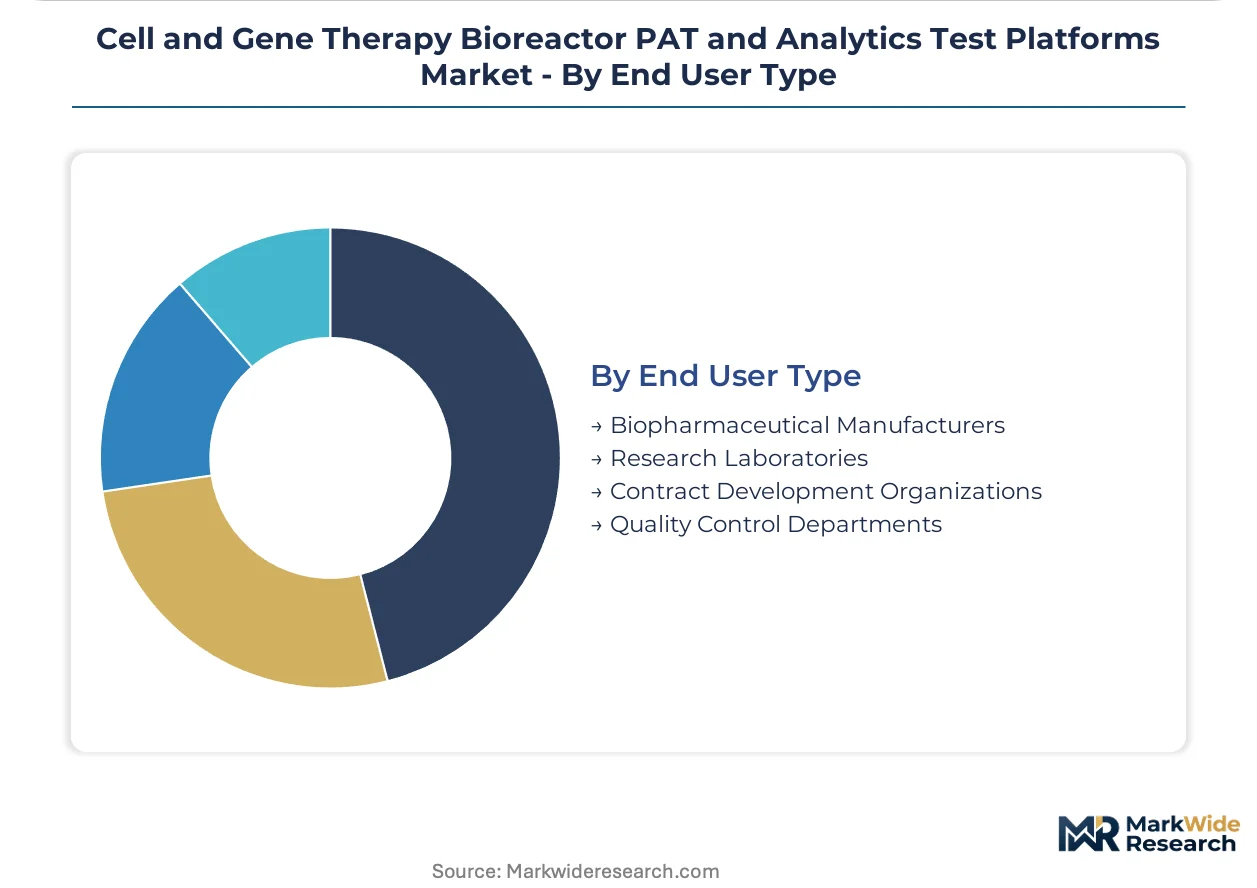
- Biopharmaceutical Manufacturers:Integrated companies with commercial cell therapy portfolios require validated platforms that satisfy FDA process analytical technology guidance for real-time release testing. These buyers specify outcome-based contracts that tie analytical performance to batch success rather than instrument uptime.
- Contract Development Organizations:CDMOs in the United States are expanding analytical service offerings to capture outsourcing from emerging biotech developers lacking in-house manufacturing infrastructure. ISO 20391-1 metrological compliance costs force redundant instrument qualification protocols that extend their deployment timelines.
- Research Laboratories:Academic and discovery settings prioritize flexibility over validation, retaining offline fluorescence microscopy for early-stage development.
- Quality Control Departments:Standalone QC operations within larger organizations focus on release testing rather than in-process monitoring.
Biopharmaceutical Manufacturers represent the largest addressable spend, though Contract Development Organizations are climbing the fastest as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German photonics suppliers export Raman spectroscopy probes to United States-based bioreactor integrators, creating a critical trade-flow dependency that shapes procurement timelines across North American cell therapy manufacturing.
United States
FDA real-time release testing mandates and concentrated CDMO infrastructure drive demand for validated PAT platforms. The FDA's Process Analytical Technology guidance for biologics tightens chemometric model requirements. Greater Boston anchors gene therapy vector manufacturing, where commercial suites deploy integrated spectroscopic monitoring for autologous therapy batch release.
Germany
Specialty photonics manufacturing and adherent cell culture sensor development concentrate analytical supply capacity. EMA reflection papers on quality by design accelerate in-line metabolite monitoring adoption. Baden-Württemberg hosts precision optics clusters supplying Raman probe components to global bioreactor integrators.
South Korea
MFDS fast-track pathways for cell therapy approvals and expanding academic medical center manufacturing capabilities create procurement pull. The Ministry of Food and Drug Safety streamlines validation requirements for domestic CDMOs building export capacity. Seoul Capital Area concentrates biotech manufacturing infrastructure targeting regional export markets.
Switzerland
Gene therapy developers and precision instrument manufacturing anchor demand for high-fidelity analytics platforms. Swissmedic guidelines align with EMA quality by design frameworks for commercial cell therapy release. Basel-area biopharmaceutical clusters integrate electrochemical sensor platforms into perfusion bioreactor workflows.
United Kingdom
Academic medical centers with in-house manufacturing and emerging CDMO capacity drive demand for flexible analytics platforms. The Medicines and Healthcare products Regulatory Agency enforces data integrity standards harmonized with EMA reflection papers. London-Southeast biotech clusters deploy handheld analytics devices for early-stage process development.
Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered market structure where instrumentation conglomerates anchor commercial manufacturing suites while focused technology developers capture emerging modalities. The vendor base organizes around three strategic archetypes: diversified life science conglomerates with chromatography and spectroscopy portfolios, specialized sensor technology developers with electrochemical expertise, and single-use systems integrators focused on perfusion applications. Competitive moves concentrate on strategic partnerships for DCS integration capabilities and portfolio diversification into data integration software.
Among diversified conglomerates, Thermo Fisher Scientific and Merck KGaA occupy positions anchoring downstream analytics workflows through chromatography portfolios and distributed control system integration. Sartorius exemplifies the specialized sensor archetype through electrochemical platforms designed for adherent cell culture monitoring. These three companies represent distinct competitive positioning vectors: scale-driven instrumentation breadth, targeted sensor technology depth, and single-use flow path integration expertise.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Sartorius |
| Repligen |
| Lonza |
| Miltenyi Biotec |
| LumaCyte |
| Ori Biotech |
| Stevanato Group |
| Others |
Pricing and Supply Chain Analysis
Baden-Württemberg's precision optics clusters anchor global Raman probe manufacturing, concentrating component supply among German and Japanese photonics specialists who command premium pricing for bioreactor integrators in the United States. This geographic chokepoint amplifies procurement costs for FDA-validated PAT systems while compressing margins for downstream platform assemblers competing on real-time release testing compliance.
Pricing Analysis
Current-generation Raman spectroscopy platforms command substantial premiums over prior-generation electrochemical sensor arrays, while next-generation software-defined analytics with integrated AI calibration remain pre-commercial and unpriced. Pricing stratifies across premium, standard, and economy tiers based on FDA validation tier and distributed control system integration depth. Cost compression in the standard tier intensifies as CDMOs consolidate procurement volumes and negotiate outcome-based service contracts. Academic medical centers with in-house manufacturing capabilities represent the most price-sensitive buyer segment, deferring full PAT deployment until regulatory submission timelines firm.
Supply Chain Analysis
Export controls on precision photonics and advanced sensor technologies limit flows of Raman spectroscopy components from Germany and Japan to United States-based bioreactor integrators. Manufacturing draws from specialty glass substrates sourced from Germany, photodetector arrays from Japan, and single-use flow path polymers from United States chemical suppliers. Single-source vulnerability concentrates in Raman probe fabrication, where two German suppliers control critical optical component production. Distribution runs through authorized integrator channels rather than direct OEM sales, with biopharmaceutical manufacturers and CDMOs as primary downstream customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Real-time release testing mandates from FDA and EMA are compressing validation timelines and forcing a technological inflection toward continuous verification architectures, creating asymmetric opportunities for positioned players.
For Market Incumbents: Build switching-cost moats through deep distributed control system integration partnerships that embed your platforms into brownfield manufacturing suites. Invest in ISO 20391-1 metrological certification infrastructure to extend deployment timeline advantages over challengers. Defend against emerging software-defined analytics entrants by anchoring chromatography reference standards that spectroscopic methods must validate against. For New Entrants and Emerging Players: Establish a beachhead in data integration software middleware, the fastest-expanding budget category where brownfield fragmentation creates white-space demand. Target South Korean CDMOs building export capacity under MFDS fast-track pathways, where regulatory acceleration outpaces incumbent sales coverage. Lead with hybrid electrochemical-chromatographic sensor architectures that reduce sample withdrawal frequency and differentiate against pure-play spectroscopy vendors. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FDA and EMA tightening of chemometric model requirements raises barriers faster than organic R&D can overcome. Prioritize acquisition targets with validated DCS integration protocols and existing FDA master file submissions. Watch for inflection when CDMO outcome-based contracts tip from pilot programs to standard procurement terms.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | MFDS fast-track validation accelerates South Korean CDMO export capacity building. |
| Strategic Partnership | DCS integration alliances embed PAT platforms into legacy manufacturing architectures. |
| Acquisition of Specialist Firm | Electrochemical sensor developers deepen adherent cell culture monitoring capabilities. |
| Product Launch | Software-defined analytics enable model predictive control without human intervention. |
| Manufacturing Scale-Up | Perfusion bioreactor sensor miniaturization supports extended gene therapy vector production. |
Research Methodology
A standing panel of bioprocess engineering directors, regulatory affairs leads at gene therapy developers, CDMO procurement managers, and academic medical center manufacturing heads provided ongoing calibration across primary fieldwork. Secondary validation drew from FDA guidance documents, EMA reflection papers, ISO 20391-1 standards, USP chapter filings, and patent landscapes covering Raman spectroscopy probe architectures. Bottom-up instrument shipment analysis triangulated against top-down biopharmaceutical capital expenditure surveys to anchor market sizing.
Scenario-bracketing framed demand projections across regulatory acceleration, supply disruption, and technology substitution pathways. Segmentation modeling spanned platform type, measurement technology, testing application, and end-user archetype across the projection horizon. CAGRs were derived from instrument replacement cycles, CDMO capacity expansion pipelines, and regulatory mandate implementation timelines. Gene therapy vector manufacturing scale-up and autologous therapy batch complexity served as primary demand drivers in the analytical framework.
Stress conditions across German-Japanese photonics supply continuity, FDA validation timeline compression, and CDMO contract model adoption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization between FDA and EMA guidance. Material shifts in export control regimes for precision photonics or sudden revisions to ISO 20391-1 traceability requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Global Gene Therapy Cell Culture Media Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Asia-Pacific Gene Therapy Market
Cell & Gene Therapy
Inherited Orphan Blood Disorders Therapeutics Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market