
 Autologous Stem Cell and Non Stem Cell Based Therapies Market | 2026-2036
Autologous Stem Cell and Non Stem Cell Based Therapies Market Size, Share, and Industry Trends Forecast 2026-2036
Autologous Stem Cell and Non Stem Cell Based Therapies Market Intelligence
The autologous therapy landscape is rebalancing between premium chimeric antigen receptor T-cell platforms and commodity-tier non-stem cell immunotherapies, with pricing power diverging sharply based on manufacturing complexity and clinical outcomes. Novartis AG dominates the premium CAR-T segment through vertically integrated vector production and dedicated treatment centers. Gilead Sciences anchors its position via Kite Pharma's distributed manufacturing network, while Bristol-Myers Squibb Company competes through dual-platform investments in both lymphoma and solid tumor autologous programs.
Autologous stem cell and non stem cell based therapies comprise patient-specific biological products manufactured from an individual's own cells or tissues, involving ex vivo manipulation, expansion, and reinfusion with critical quality parameters including cell viability above 70%, sterility assurance, and cryopreservation stability. These therapies serve primarily to treat hematologic malignancies, degenerative conditions, and autoimmune disorders where allogeneic approaches risk graft rejection. Cell therapy occupies the largest revenue pool given established CAR-T reimbursement, while gene therapy represents the fastest-expanding segment driven by lentiviral and CRISPR-edited autologous platforms. Tissue engineering applications in orthopedics concentrate margin in specialized hospital settings with captive bioprocessing capabilities.
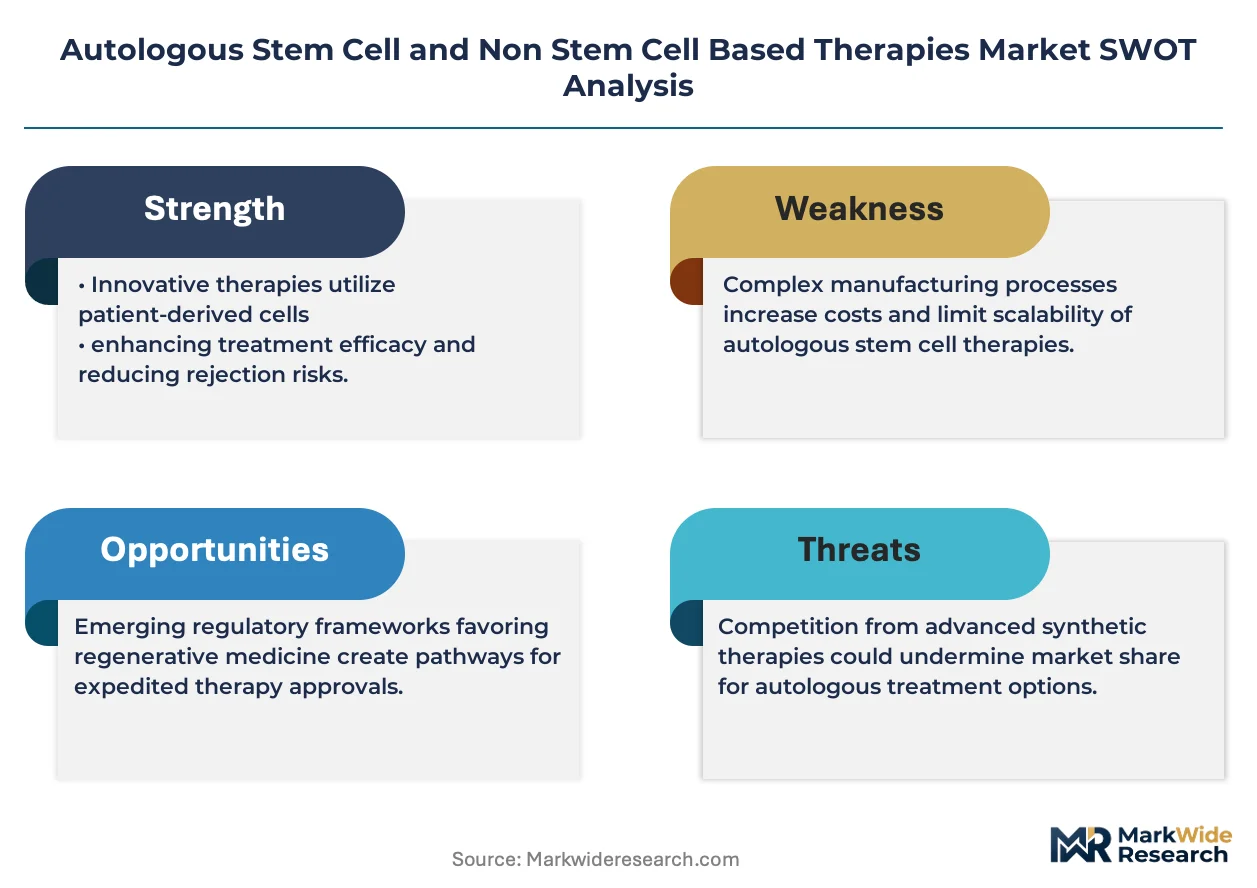
FDA's regenerative medicine advanced therapy designation and EMA's priority medicines pathway compress regulatory review timelines, directly shaping investment allocation toward autologous programs with breakthrough status. The EU's Medical Device Regulation and forthcoming Pharmaceutical Strategy impose traceability requirements that favor manufacturers with integrated chain-of-identity systems. Stakeholders must monitor evolving manufacturing standards from ISO and WHO for decentralized production models, as point-of-care cell processing threatens centralized facility economics.
Market Dynamics
FDA's regenerative medicine advanced therapy designation compresses development timelines for autologous platforms, while manufacturing scale constraints force trade-offs between centralized bioprocessing economics and point-of-care flexibility.
Growth Catalysts
- Accelerated Approval Pathways:FDA's breakthrough therapy designation and EMA's priority medicines framework compress clinical trial durations for patient-specific cellular medicines. Hematologic oncology programs leverage these mechanisms to reach commercialization faster.
- CAR-T Manufacturing Maturation:Academic medical centers in the United States, Germany, and Japan expand dedicated treatment centers with captive vector production capabilities. These facilities reduce vein-to-vein time for lymphoma and leukemia indications.
- Reimbursement Infrastructure:Germany's G-BA and Japan's MHLW establish outcome-based payment frameworks for autologous cell therapies. Payers in these markets accept higher upfront costs contingent on demonstrated durable remission rates.
Market Restraints
- Plasmid DNA Supply Concentration:Viral vector production depends on specialized plasmid suppliers concentrated in North American and European contract manufacturing organizations. Any disruption to this tier propagates through lentiviral and retroviral supply chains.
- Cryopreservation Logistics Costs:Liquid nitrogen cold chain requirements for cell viability maintenance impose infrastructure investments that exclude smaller treatment centers from autologous therapy administration.
- Allogeneic Platform Substitution:Off-the-shelf CAR-T and CAR-NK approaches from allogeneic cell banks threaten to displace autologous modalities in price-sensitive indications where immune compatibility permits.
Strategic Opportunities
- Point-of-Care Processing:Decentralized manufacturing platforms enable bedside cell expansion without centralized cleanroom infrastructure. Community oncology practices in the United States pilot these systems to capture patient volume outside academic centers.
- Solid Tumor Penetration:Autologous tumor-infiltrating lymphocyte therapies target melanoma and cervical cancer where CAR-T has demonstrated limited efficacy. Clinical programs in these indications expand addressable patient populations beyond hematologic malignancies.
- EU Medical Device Regulation Traceability:MDR Article 10 requirements for chain-of-identity systems favor manufacturers with integrated software-hardware platforms. Vendors with compliant serialization capabilities capture share in European hospital procurement.
Industry Challenges
- Cell Therapy Manufacturing Talent Scarcity:GMP-compliant aseptic processing and quality control expertise concentrates among professionals with biologics manufacturing experience. Training pipelines cannot match expansion of autologous therapy programs.
- ISO Cell Therapy Standards Harmonization:Divergent guidance between ISO 20399 for cell processing and WHO recommendations for decentralized production creates compliance ambiguity. Manufacturers face dual certification burdens.
- Legacy Electronic Health Record Integration:Hospital information systems lack native modules for chain-of-custody documentation required for patient-specific biologics. Custom middleware development extends implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autologous Stem Cell and Non Stem Cell Based Therapies Market |
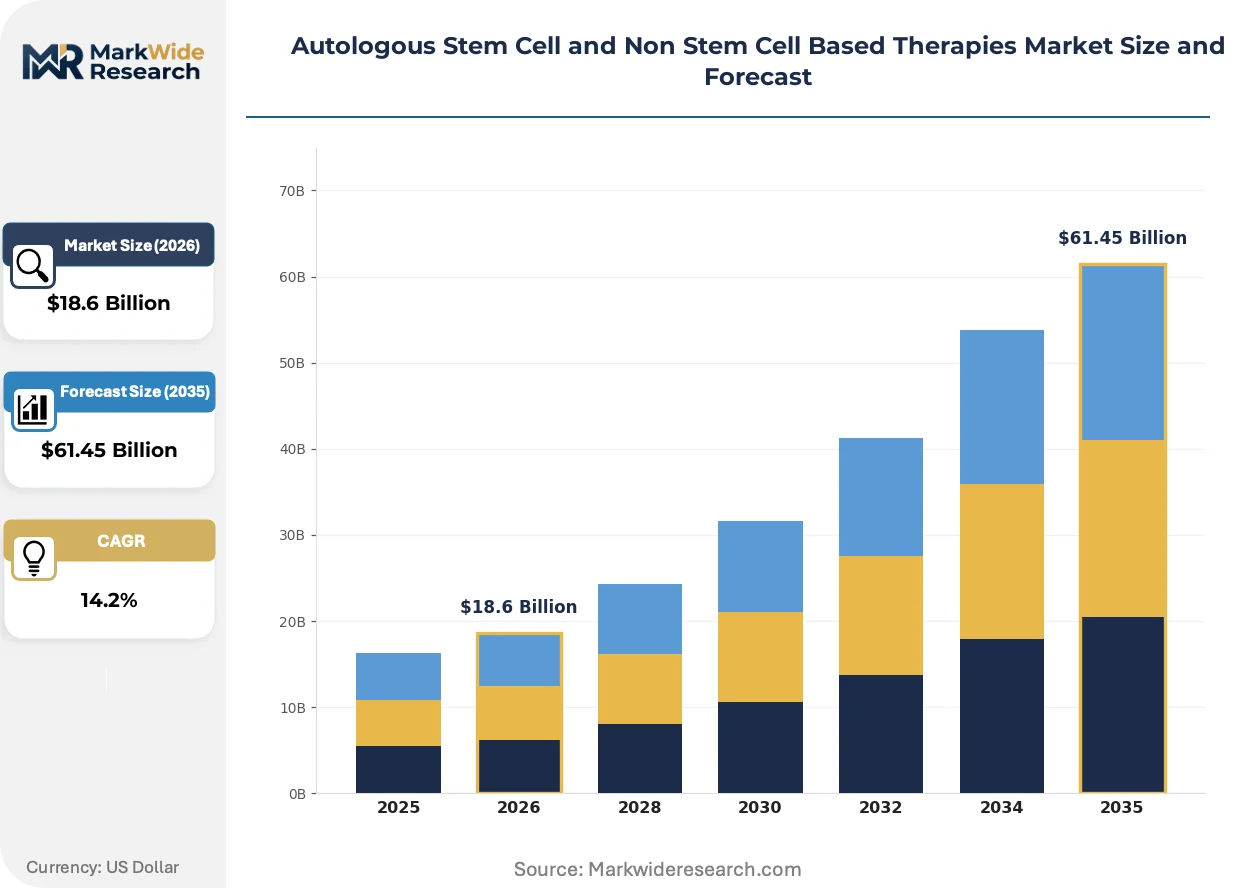
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $61.45 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Cell Therapy, Gene Therapy, Tissue Engineering, Pharmacotherapy Application: Oncology, Cardiology, Orthopedics, Neurology Delivery Mode: Intravenous, Subcutaneous, Local Implantation, Intramuscular End User: Hospitals, Research Institutes, Ambulance Services, Private Clinics |
| Companies Covered | Gilead Sciences, Novartis AG, Bristol-Myers Squibb Company, Vericel Corporation, Johnson & Johnson, BrainStorm Cell Therapeutics, Dendreon Pharmaceuticals, Bluebird bio, Takeda Pharmaceutical (TiGenix), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autologous Stem Cell and Non Stem Cell Based Therapies Market Strategic Shifts & Innovations
Autologous therapy manufacturing is bifurcating between premium centralized bioprocessing and emerging point-of-care platforms, with regulatory frameworks racing to accommodate both models.
Closed-system bioreactors for patient-specific cell expansion are absorbing quality control functions previously performed in centralized testing laboratories. Community oncology networks in the United States adopt these platforms to reduce logistics complexity and vein-to-vein time. The technology is absorbing margin from transportation and cold chain intermediaries by collapsing geographic distance between collection and reinfusion.
EMA's forthcoming Pharmaceutical Strategy imposes enhanced pharmacovigilance requirements on advanced therapy medicinal products. Manufacturers must deploy real-world evidence collection systems from first commercial doses. Cell therapy sponsors with existing patient registry infrastructure capture regulatory preference over competitors building compliance capabilities reactively.
Hospital procurement departments consolidate autologous therapy vendor relationships to secure dedicated manufacturing slots. Large academic medical centers in Germany and Japan negotiate multi-year capacity agreements with vector producers. This concentration is displacing spot-market purchasing for CAR-T and gene-modified cell therapies, locking in volume commitments that exclude smaller treatment facilities.
Autologous Stem Cell and Non Stem Cell Based Therapies Market Segmentation
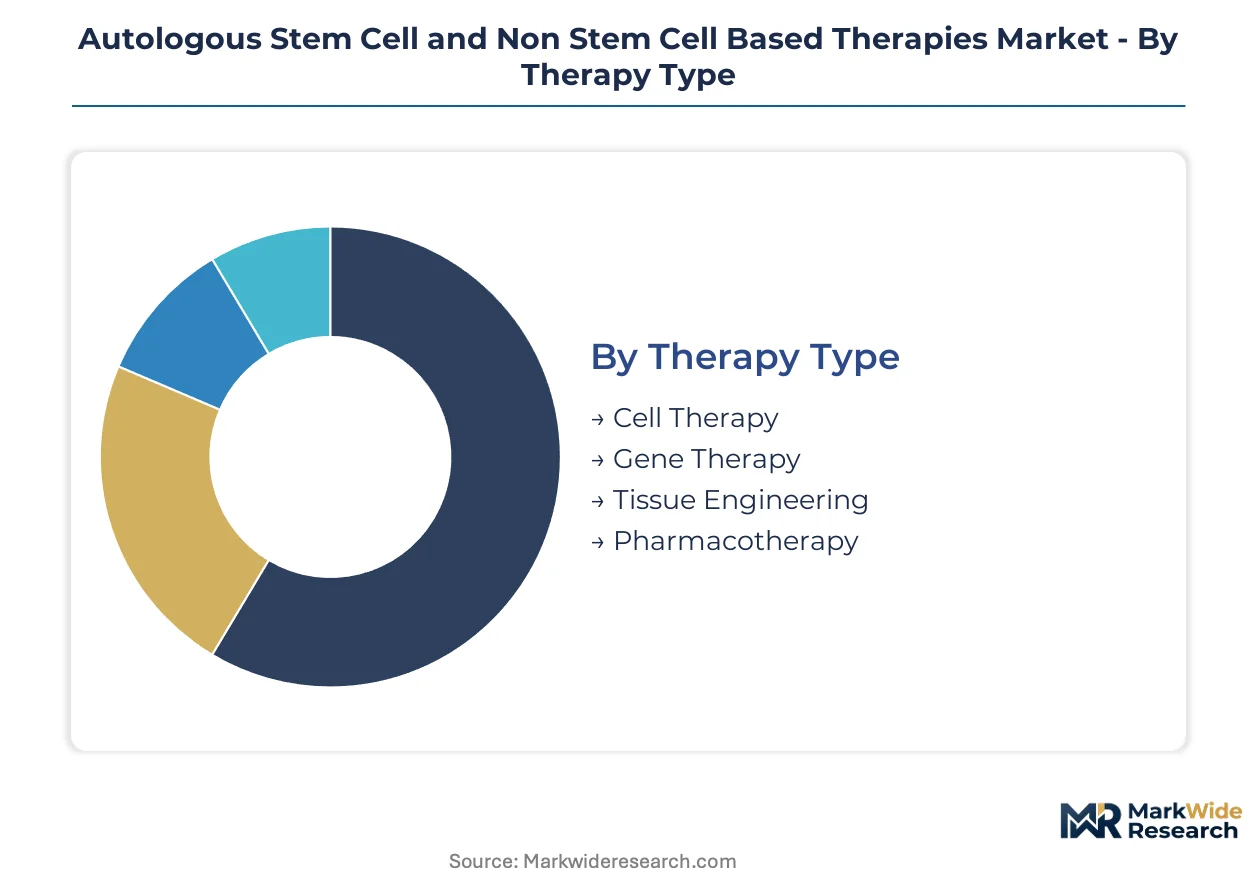
Autologous therapies demand precise segmentation because patient-specific manufacturing creates divergent cost structures, regulatory pathways, and clinical workflows across each dimension. Understanding where customization intensifies versus where standardization emerges guides capital allocation and partnership strategy.
Therapy Type:
Customization intensity varies sharply across this category, with fully individualized cell processing at one extreme and templated pharmacological protocols at the other.
- Cell Therapy:Patient-derived cellular products undergo ex vivo expansion and reinfusion, with CAR-T platforms commanding premium reimbursement through dedicated treatment centers. Demand concentrates in United States academic medical centers where FDA breakthrough therapy designation accelerates commercialization timelines for lymphoma indications.
- Gene Therapy:Lentiviral and CRISPR-edited autologous platforms modify patient cells to correct genetic defects, requiring integrated vector production capabilities. German hospital networks invest heavily in these programs under EMA priority medicines pathways that compress development cycles for rare disease applications.
- Tissue Engineering:Scaffold-based autologous constructs for orthopedic regeneration.
- Pharmacotherapy:Patient-matched biological drug protocols with standardized dosing frameworks.
Most installed capacity flows through Cell Therapy. Expansion is steepest in Gene Therapy.
Application:
Clinical maturity and reimbursement sophistication separate established hematologic indications from emerging solid tumor and degenerative targets.
- Oncology:CAR-T and tumor-infiltrating lymphocyte therapies target hematologic malignancies with established payment codes, while solid tumor programs in melanoma and cervical cancer expand addressable populations. Japanese centers under MHLW outcome-based frameworks lead adoption of next-generation autologous platforms.
- Orthopedics:Autologous chondrocyte implantation and mesenchymal stem cell therapies for joint regeneration require specialized surgical infrastructure. German G-BA reimbursement decisions shape European procurement patterns for cartilage repair procedures.
- Cardiology:Autologous cell therapies for heart failure and ischemic repair.
- Neurology:Experimental applications in neurodegenerative and autoimmune conditions.
Revenue concentration sits with Oncology. Clinical pipeline velocity is climbing fastest in Orthopedics.
Delivery Mode:
Route selection determines manufacturing specifications, cold chain requirements, and site-of-care economics for each patient-specific product.
- Intravenous:Systemic administration of cryopreserved cell products dominates CAR-T lymphoma protocols, requiring liquid nitrogen logistics and specialized infusion centers. United States community oncology networks are piloting decentralized processing to reduce vein-to-vein time.
- Local Implantation:Direct surgical placement of tissue-engineered constructs demands operating room integration and real-time viability confirmation. Japanese orthopedic centers maintain captive bioprocessing capabilities for cartilage and bone regeneration procedures.
- Subcutaneous:Depot-based autologous cell delivery for sustained therapeutic effect.
- Intramuscular:Targeted injection protocols for localized regenerative applications.
Patient volume runs predominantly through Intravenous administration. Infrastructure investment is shifting toward Local Implantation capabilities.
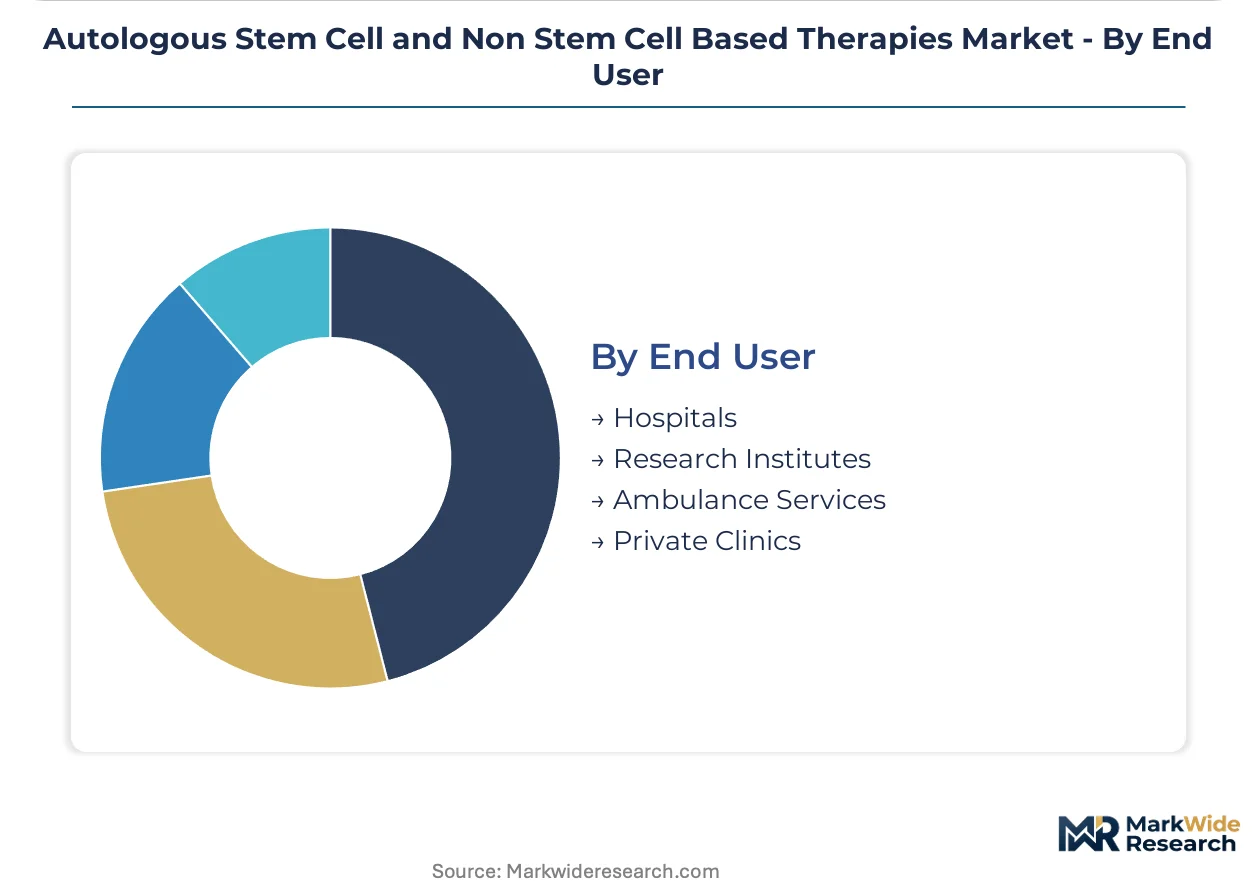
End User:
Treatment complexity and capital requirements create tiered access, with centralized academic centers separating from community and emergency settings.
- Hospitals:Academic medical centers in the United States, Germany, and Japan anchor autologous therapy delivery through integrated cleanroom facilities and dedicated CAR-T programs. FDA regenerative medicine advanced therapy designation recipients concentrate manufacturing partnerships with these institutions.
- Research Institutes:Early-phase clinical trial execution and process development for novel autologous platforms. EMA's forthcoming Pharmaceutical Strategy pharmacovigilance requirements favor sponsors with established registry infrastructure at these sites.
- Ambulance Services:Emergency cellular product transport and field stabilization protocols.
- Private Clinics:Outpatient administration of standardized autologous procedures.
Therapy authorization concentrates in Hospitals. Regulatory trial volume is expanding fastest through Research Institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cell therapy manufacturing talent concentrates in the United States, Germany, and Japan, anchoring the geographic distribution of autologous therapy development and commercialization infrastructure.
United States
FDA breakthrough therapy designations and regenerative medicine advanced therapy pathways compress development timelines for patient-specific cellular medicines. Academic medical centers in Boston, Houston, and Seattle expand dedicated CAR-T treatment facilities with captive vector production capabilities. Novartis AG and Gilead Sciences anchor manufacturing partnerships with these institutions under outcome-based reimbursement pilots.
Germany
The G-BA establishes outcome-based payment frameworks for autologous cell therapies contingent on demonstrated durable remission rates. EMA priority medicines pathways accelerate commercialization timelines for rare disease applications. Hospital networks in Munich and Heidelberg invest heavily in lentiviral and CRISPR-edited autologous platforms with integrated cleanroom facilities.
Japan
MHLW reimbursement frameworks accept higher upfront costs for autologous therapies with proven clinical outcomes. PMDA accelerated review pathways compress regulatory timelines for personalized cellular medicines. Tokyo and Osaka orthopedic centers maintain captive bioprocessing capabilities for cartilage regeneration procedures under JIS standards compliance.
United Kingdom
NHS England specialized commissioning frameworks create dedicated funding streams for CAR-T lymphoma therapies. MHRA recognition of FDA and EMA approvals streamlines parallel regulatory pathways for autologous platforms. London and Cambridge research institutes anchor early-phase clinical trial execution with established patient registry infrastructure.
Switzerland
Swissmedic alignment with EMA centralized procedures accelerates market access for advanced therapy medicinal products. Basel and Zurich hospital networks leverage proximity to vector manufacturing infrastructure for reduced vein-to-vein times. The country's pharmaceutical talent density supports specialized GMP-compliant aseptic processing expertise for patient-specific biologics.
Autologous Stem Cell and Non Stem Cell Based Therapies Market Key Industry Players
Top-tier vendors anchor premium CAR-T and gene therapy platforms, while mid-tier specialists concentrate on tissue engineering and decentralized processing technologies. The vendor base stratifies across vertically integrated pharmaceutical conglomerates, dedicated cell therapy pure-plays, and emerging point-of-care platform developers. Three archetypes dominate: vector-integrated manufacturers with captive supply chains, distributed network operators with regional cleanroom partnerships, and technology licensors with platform-agnostic processing equipment. Competitive moves center on multi-year capacity agreements with academic medical centers and backward integration into plasmid DNA supply.
Among established pharmaceutical conglomerates, Novartis AG and Gilead Sciences occupy positions exemplifying vector-integrated manufacturing archetypes with dedicated treatment center networks. Bristol-Myers Squibb Company represents the dual-platform investment approach spanning lymphoma and solid tumor autologous programs. These three anchors demonstrate how scale-driven players consolidate manufacturing partnerships with FDA breakthrough therapy designation recipients while building pharmacovigilance infrastructure for EMA's forthcoming Pharmaceutical Strategy requirements.
| Leading Market Players |
|---|
| Gilead Sciences |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Vericel Corporation |
| Johnson & Johnson |
| BrainStorm Cell Therapeutics |
| Dendreon Pharmaceuticals |
| Bluebird bio |
| Takeda Pharmaceutical (TiGenix) |
| Others |
Cost & Logistics Intelligence
Captive vector production by Novartis AG and Gilead Sciences anchors both supply security and pricing power across the premium CAR-T tier, while outsourced plasmid dependence exposes mid-tier manufacturers to cost volatility and margin compression.
Pricing Analysis
Bundled service contracts encompassing vein-to-vein logistics and cryopreservation dominate the premium CAR-T segment, whereas unbundled cell processing fees prevail in orthopedic autologous applications. Three-tier pricing structure across premium CAR-T, standard tissue engineering, and economy-tier non-stem cell immunotherapies reflects manufacturing complexity and clinical outcome guarantees. Pricing pressure stems from allogeneic platform substitution threats in price-sensitive lymphoma indications. Community oncology practices exhibit highest price sensitivity due to reimbursement lag, while academic medical centers with dedicated treatment facilities command volume discounts through multi-year capacity agreements.
Supply Chain Analysis
Direct-to-hospital channels handle CAR-T product distribution through specialized infusion centers with liquid nitrogen cold chain infrastructure. Vector manufacturing concentrates in the United States, Germany, and Switzerland where GMP-compliant aseptic processing talent pools are deepest. Plasmid DNA supply draws from North American and European contract manufacturing organizations, creating single-source vulnerability for lentiviral production. Tariff exposure on cryopreservation equipment and specialized bioreactor components threatens decentralized manufacturing economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The autologous therapy market represents a late-cycle quality story as demand shifts toward FDA breakthrough-designated platforms with demonstrated durable remission rates, displacing commodity-tier alternatives.
For Market Incumbents: Deploy backward integration into plasmid DNA supply to secure vector production continuity against contract manufacturing concentration risks. Expand dedicated treatment center partnerships in Germany and Japan under outcome-based reimbursement frameworks to lock in volume commitments. Prioritize pharmacovigilance infrastructure investment ahead of EMA's forthcoming Pharmaceutical Strategy requirements.
For New Entrants and Emerging Players: Begin with point-of-care processing platforms targeting United States community oncology networks outside academic medical center catchment areas. Capture white-space opportunity in solid tumor autologous applications including melanoma tumor-infiltrating lymphocyte therapies. Pursue hospital procurement consolidation through integrated chain-of-identity software-hardware systems compliant with EU Medical Device Regulation Article 10.
For Investors and Strategic Acquirers: Roll-up economics work for point-of-care platform developers because decentralized manufacturing threatens centralized facility economics and creates fragmented acquisition targets at attractive multiples. Long-term viability favors sponsors with established patient registry infrastructure for real-world evidence collection. Watch FDA regenerative medicine advanced therapy designation velocity as inflection indicator for premium platform valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive vector production secures supply continuity for CAR-T programs under FDA breakthrough designation. |
| Regulatory Approval Pathway | EMA priority medicines access accelerates commercialization timelines for rare disease autologous gene therapies. |
| Hospital System Partnership | Multi-year capacity agreements with German G-BA reimbursement frameworks lock in premium pricing. |
| Pipeline Diversification | Solid tumor TIL programs expand addressable populations beyond established hematologic malignancy indications. |
| Technology Licensing | Closed-system bioreactor platforms enable community oncology networks to reduce vein-to-vein time. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down vector manufacturing capacity tracking forms the analytical core of this study. Primary interviews with CAR-T program directors, GMP facility managers, payer access specialists, and regulatory affairs leads combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital formulary databases. Cross-referencing treatment center expansion announcements against reimbursement framework documentation enables supply-demand calibration.
Historical trendline analysis of CAR-T treatment volumes and gene therapy clinical trial initiations informs the projection framework across the analysis window. Segmentation dimensions include therapy type, application indication, delivery mode, and end-user facility tier. CAGRs derive from installed capacity growth rates, reimbursement expansion trajectories, and patient population epidemiology. Forecast inputs incorporate plasmid supply constraints, cold chain infrastructure investment cycles, and regulatory pathway velocity differentials.
Several conditions sit outside the modeled scope, including allogeneic platform technical breakthroughs that could accelerate substitution timelines, and macroeconomic disruptions to healthcare reimbursement. Forecasts reflect documented assumptions regarding FDA and EMA pathway continuity, G-BA and MHLW payment framework stability, and ISO harmonization progress. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Asia-Pacific Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Regenerative Therapies Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Market
Cell & Gene Therapy
GMP Cell Banking Services Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Drugs Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
Gene Electroporators Market