
 Middle East and Africa Cell and Gene Therapy Thawing Equipment Market | 2026-2036
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market Foresight
The premium automated thawing tier is consolidating around closed-system designs with integrated temperature logging, while commodity manual water-bath units face price erosion from regional distributors. CryoGene Systems Inc leverages proprietary conductive heating modules to sustain margin in clinical-grade installations. ThawTech Industries Inc anchors the portable segment across North African research sites. CellGenesis Technologies LLC competes on service density in Gulf Cooperation Council states.
Cell and gene therapy thawing equipment encompasses controlled thermal recovery systems designed to restore cryopreserved biological materials from sub-zero storage temperatures to viable physiological ranges without compromising cellular integrity. These systems typically maintain ramp rates between one and ten degrees Celsius per minute and integrate sterile barriers to prevent contamination during the thaw cycle. Automated thawing systems command the highest installed base among pharmaceutical companies due to batch reproducibility requirements and audit trail mandates. Water bath thawing retains dominance in research laboratories where capital constraints limit uptake of conductive or microwave alternatives. Inline thawing units represent the fastest-expanding technology category as bioprocessing facilities seek continuous manufacturing integration.
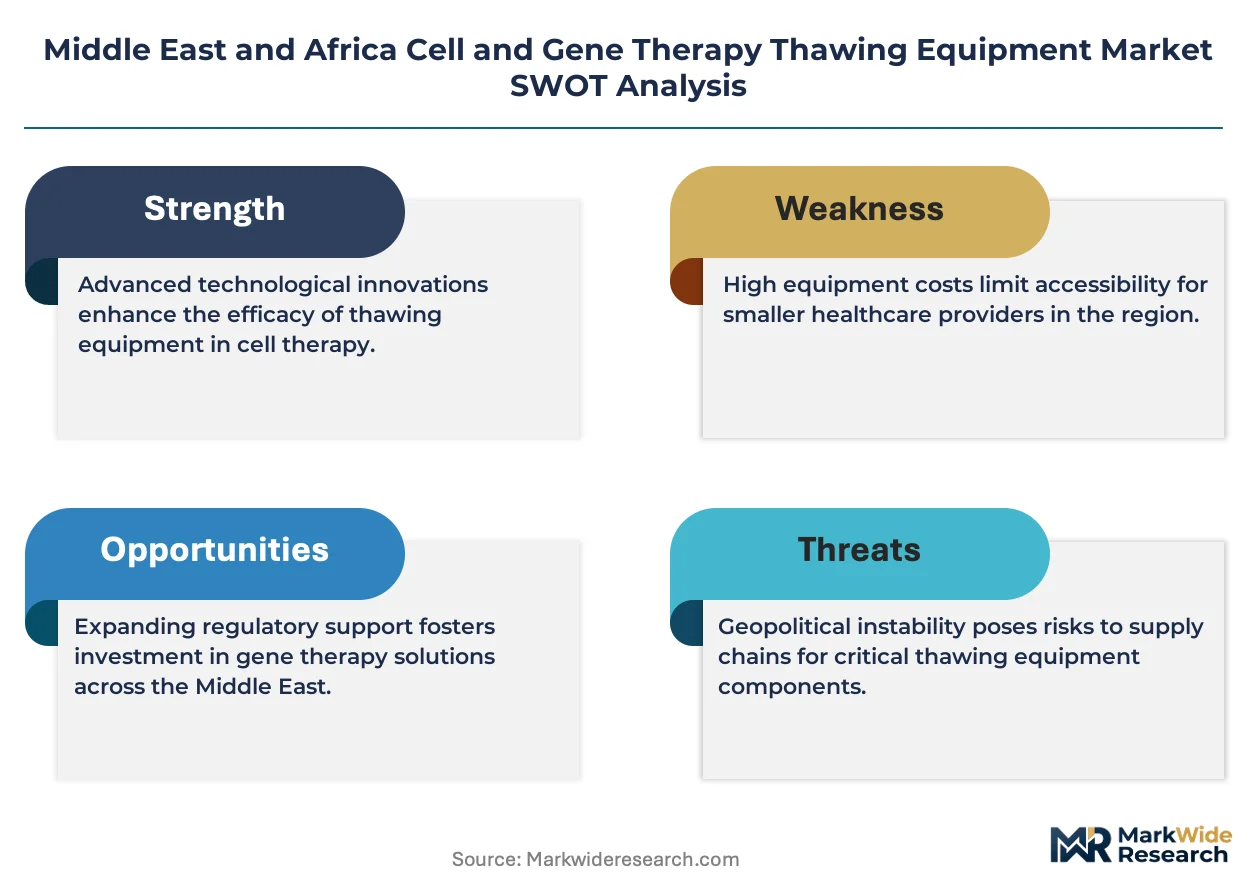
Saudi Arabia's SFDA and the UAE's MOHAP now require validated thaw documentation for imported advanced therapy medicinal products, directly elevating demand for equipment with embedded data-logging capabilities. South Africa's national health regulator aligns with WHO prequalification standards for cryopreserved cell handling, creating compliance-driven replacement cycles across public hospital networks. Stakeholders must weigh the trade-off between automated system premiums and the operational risk of manual protocol deviations in multi-site clinical trials.
Market Dynamics
The Saudi Food and Drug Authority and UAE's Ministry of Health and Prevention now mandate validated thaw documentation for advanced therapy medicinal products, forcing equipment upgrades across hospital networks and contract manufacturing organizations.
Growth Catalysts
- SFDA Validation Mandates:Saudi Arabia's regulator now requires embedded data-logging capabilities for all imported cell therapies, directly elevating demand for automated thawing systems with audit trail functionality.
- Hospital Infrastructure Expansion:South African public hospital networks are aligning with WHO prequalification standards for cryopreserved cell handling, triggering compliance-driven replacement cycles.
- Continuous Manufacturing Integration:Inline thawing technology is expanding into bioprocessing facilities seeking to eliminate batch discontinuities between cryogenic storage and downstream formulation.
Market Restraints
- Capital Intensity of Automated Systems:Conductive heating modules and closed-system designs carry price premiums that exclude research laboratories with constrained budgets.
- Supply Concentration Risk:Proprietary heating element suppliers cluster in East Asian manufacturing hubs, exposing procurement timelines to geopolitical friction and shipping volatility.
- Manual Protocol Persistence:Water bath thawing retains installed base dominance in academic settings due to minimal upfront investment and familiar operator workflows.
Strategic Opportunities
- North African Research Sites:Portable thawing units remain underdeployed across Moroccan and Egyptian cell therapy research centers, creating first-mover positioning for lightweight conductive systems.
- Service Density Arbitrage:Gulf Cooperation Council states lack localized maintenance networks for clinical-grade thawing equipment, opening recurring revenue streams for technical support providers.
- Regulatory Harmonization:South Africa's alignment with WHO prequalification standards may cascade to neighboring SADC markets, enabling standardized equipment certification across the sub-region.
Industry Challenges
- Specialized Technician Scarcity:Cryopreservation protocol expertise concentrates in Johannesburg and Riyadh, leaving secondary cities dependent on fly-in specialists for equipment commissioning.
- Legacy System Integration:Automated thawing units must interface with existing laboratory information management systems, requiring custom middleware development that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Cell and Gene Therapy Thawing Equipment Market |
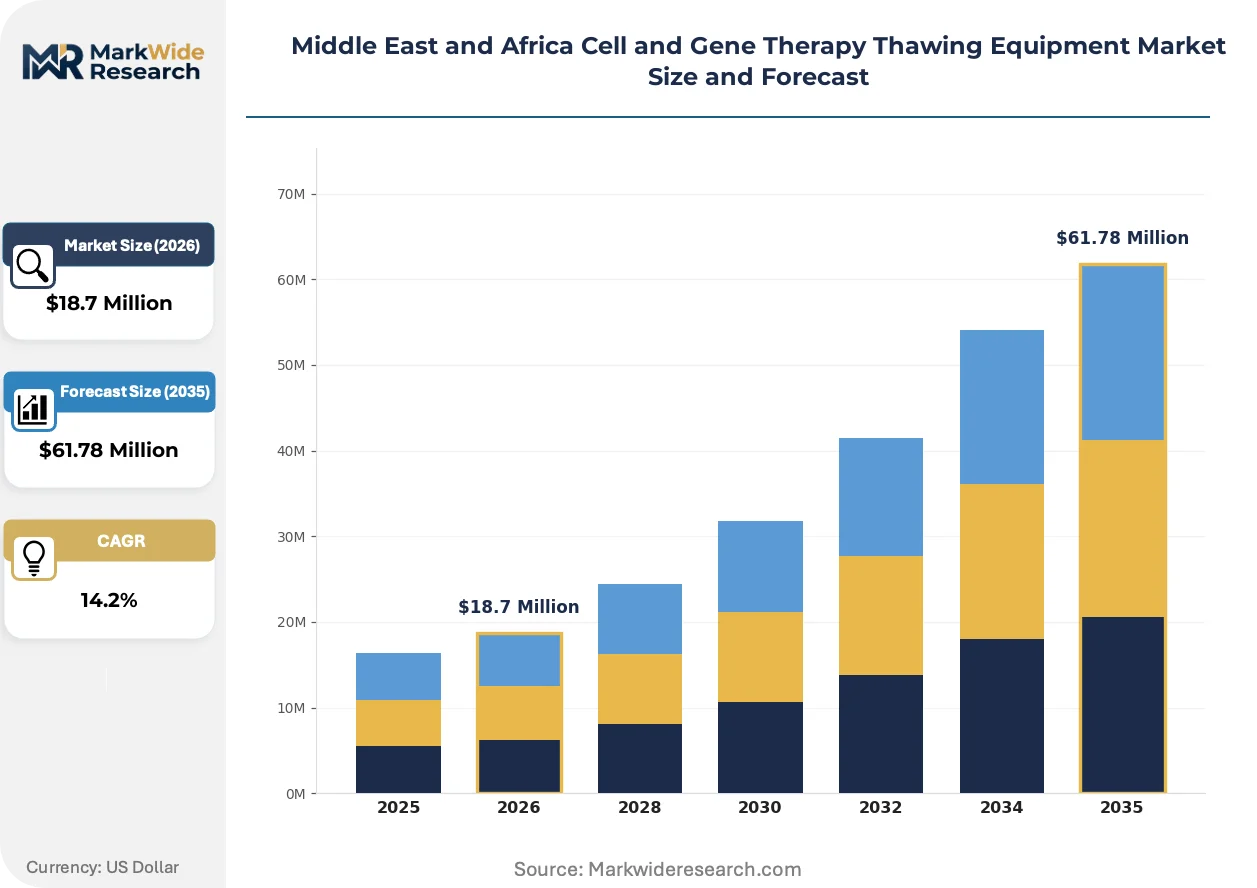
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $61.78 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Thawing Systems, Automated Thawing Systems, Inline Thawing Units, Portable Thawing Devices Application: Research Laboratories, Clinical Applications, Biopreservation, Cell Processing End User: Pharmaceutical Companies, Research Institutions, Biotechnology Firms, Hospitals Technology: Water Bath Thawing, Conductive Thawing, Microwave Thawing, Dry Heat Thawing |
| Companies Covered | CryoGene Systems Inc, CellEquip Solutions Inc, CellGene Instruments Inc, CellGene Thaw Systems Inc, CellGenesis Technologies LLC, CryoEquip Technologies Inc, ThawTech Industries Inc, ThermoCell Recovery Ltd, ThermoCell Systems Ltd, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market Shifts & Advancements
Closed-system thawing architectures are displacing open water-bath designs as contamination control becomes non-negotiable for commercial cell therapy release. Equipment vendors now compete on thermal uniformity documentation rather than headline thaw speed.
Conductive heating technology is expanding into mid-scale bioproduction facilities previously served by manual methods. Cell therapy contract manufacturers in Saudi Arabia's Riyadh corridor are adopting these systems to satisfy SFDA batch reproducibility requirements. The technology is expanding into portable form factors for field-deployed clinical trials, compressing the addressable market for basic water-bath alternatives.
MOHAP's 2024 technical guidance on cold-chain validation for advanced therapy medicinal products now requires temperature excursion logging from thaw initiation through administration. Pharmaceutical importers in Dubai must demonstrate equipment qualification protocols that exceed previous documentary standards. Hospital pharmacies across the Emirates are responding by consolidating procurement around vendors with pre-validated software stacks.
After-sales service contracts are unbundling from equipment sales as buyers seek operational expenditure predictability. Research institutions in South Africa now favor subscription-style maintenance agreements over traditional break-fix arrangements. This pattern is most visible in Cape Town's academic medical centers, where grant-funded projects demand multi-year cost visibility for audit purposes.
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market Segmentation
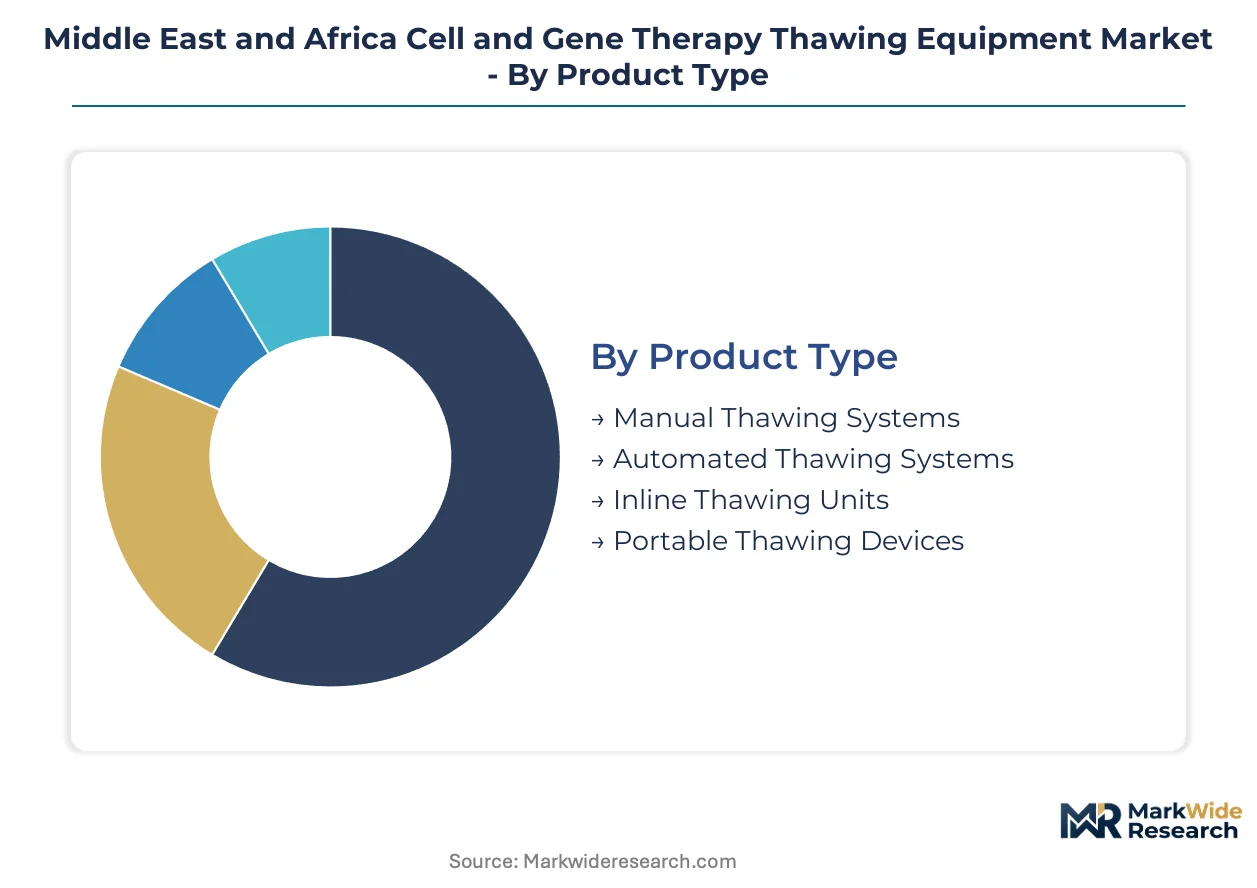
Equipment configuration in this market bifurcates sharply between validated clinical systems and flexible research tools. Procurement patterns reflect divergent compliance burdens across Saudi Arabia's Riyadh corridor and South Africa's public hospital networks.
Product Type:
Supply concentration in conductive heating modules and closed-system architectures shapes competitive positioning across all four product tiers.
- Automated Thawing Systems:Closed-system designs with embedded temperature logging dominate pharmaceutical installations. SFDA validation mandates in Saudi Arabia and MOHAP requirements in the UAE drive hospital procurement toward these units for audit trail compliance.
- Inline Thawing Units:Continuous manufacturing integration eliminates batch discontinuities between cryogenic storage and downstream formulation. Bioprocessing facilities in Saudi Arabia's Riyadh biotech corridor adopt these systems to satisfy batch reproducibility requirements.
- Manual Thawing Systems:Water-bath designs retain dominance in academic settings with capital constraints.
- Portable Thawing Devices:Lightweight conductive systems serve field-deployed clinical trials across North African research sites.
Automated thawing systems absorb the bulk of installed capacity; inline thawing units are expanding most quickly.
Application:
Cost tier differentiation separates premium clinical-grade installations from commodity research equipment.
- Clinical Applications:Commercial cell therapy release demands contamination control through closed-system architectures. Hospital pharmacies across the Emirates consolidate procurement around vendors with pre-validated software stacks to satisfy MOHAP cold-chain documentation.
- Research Laboratories:Familiar operator workflows and minimal upfront investment sustain water-bath dominance. Cape Town's academic medical centers favor subscription-style maintenance agreements for multi-year cost visibility.
- Biopreservation:WHO prequalification alignment in South Africa triggers compliance-driven replacement cycles across public networks.
- Cell Processing:Ramp rate precision between one and ten degrees Celsius per minute preserves cellular integrity during thermal recovery.
Clinical applications command premium pricing; research laboratories maintain the largest unit volume.
End User:
Customer type determines service density requirements and maintenance contract structures.
- Pharmaceutical Companies:Batch reproducibility mandates and audit trail requirements drive automated system adoption. These buyers prioritize thermal uniformity documentation over headline thaw speed.
- Hospitals:SFDA and MOHAP thaw documentation requirements force equipment upgrades across hospital networks and contract manufacturing organizations.
- Research Institutions:Grant-funded projects in South Africa demand operational expenditure predictability through unbundled service contracts.
- Biotechnology Firms:Mid-scale bioproduction facilities transition from manual methods to conductive heating technology.
Pharmaceutical companies absorb the bulk of installed capacity; hospitals are expanding most quickly.
Technology:
Maturity gradients separate established water-bath methods from emerging conductive and microwave alternatives.
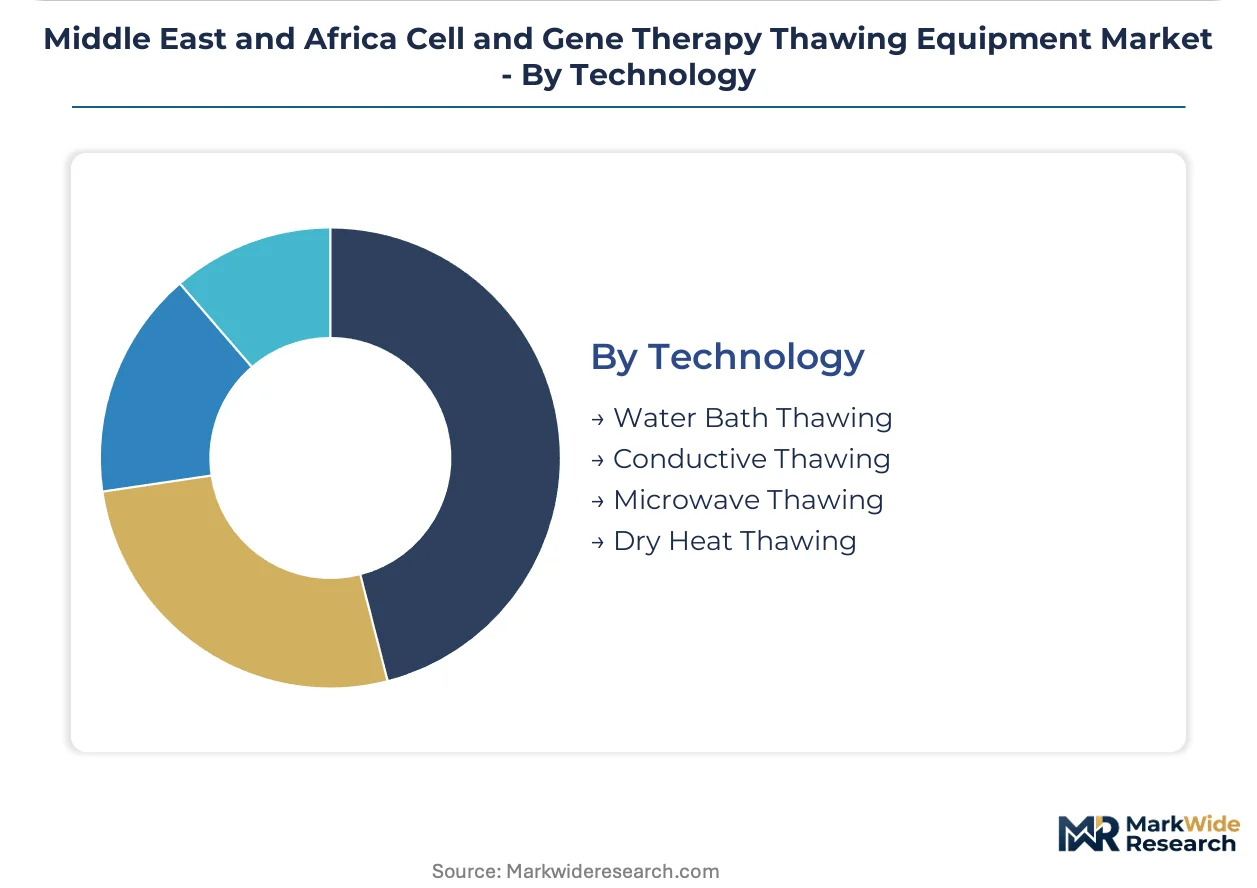
- Conductive Thawing:Proprietary heating modules sustain margin in clinical-grade installations through precise ramp rate control. These systems integrate sterile barriers to prevent contamination during the thaw cycle.
- Water Bath Thawing:Open designs face displacement as contamination control becomes non-negotiable for commercial release. Price erosion from regional distributors compresses margins for commodity units.
- Microwave Thawing:Non-uniform heating profiles limit adoption despite speed advantages.
- Dry Heat Thawing:Slower thermal transfer rates restrict application to non-critical research protocols.
Conductive thawing absorbs the bulk of installed capacity; microwave thawing is climbing the fastest despite technical limitations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh anchors regional demand through Saudi Arabia's concentrated biotech corridor, where SFDA validation mandates drive automated thawing system procurement across hospital networks and contract manufacturing facilities.
Saudi Arabia
Pharmaceutical importers and hospital pharmacies are upgrading cryopreservation infrastructure to satisfy SFDA requirements for embedded data-logging capabilities. The regulator's 2024 technical guidance mandates validated thaw documentation for all imported advanced therapy medicinal products. Riyadh's biotech corridor concentrates procurement activity as cell therapy contract manufacturers adopt conductive heating systems for batch reproducibility compliance.
United Arab Emirates
MOHAP's tightened cold-chain validation requirements are forcing equipment qualification protocols that exceed previous documentary standards. Dubai-based pharmaceutical importers must demonstrate temperature excursion logging from thaw initiation through administration. Hospital pharmacies across the Emirates are consolidating procurement around vendors with pre-validated software stacks to satisfy compliance burdens.
South Africa
Public hospital networks are aligning with WHO prequalification standards for cryopreserved cell handling, triggering compliance-driven replacement cycles. The national health regulator's alignment with international standards creates procurement pressure across secondary cities dependent on Johannesburg for technical expertise. Cape Town's academic medical centers favor subscription-style maintenance agreements for multi-year cost visibility in grant-funded projects.
Egypt
Research institutions in Cairo and Alexandria represent underdeployed territory for portable thawing units serving field-deployed clinical trials. The country's national pharmaceutical regulator is gradually harmonizing with regional standards for advanced therapy handling. Egyptian cell therapy research centers remain dependent on manual water-bath methods due to capital constraints and limited vendor presence.
Morocco
Cell therapy research sites in Casablanca and Rabat present first-mover positioning opportunities for lightweight conductive systems. The country's regulatory framework for biologics handling remains less prescriptive than Gulf Cooperation Council standards. Moroccan research centers currently lack localized maintenance networks, creating service density arbitrage for technical support providers.
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the technology-automation spectrum, with closed-system conductive heating commanding price premiums that exclude budget-constrained research laboratories. The market structure bifurcates between validated clinical-grade installations and flexible research tools. Three archetypes dominate: proprietary technology specialists leveraging conductive heating modules, portable equipment fabricators serving North African field sites, and service-integrated providers capturing recurring revenue through maintenance density. Competitive moves center on regulatory pre-validation partnerships and geographic service network expansion.
Within the proprietary technology tier, CryoGene Systems Inc and CellGenesis Technologies LLC exemplify divergent geographic strategies. CryoGene Systems Inc anchors clinical-grade positioning through its incorporated structure, while CellGenesis Technologies LLC occupies the Gulf Cooperation Council service density vector. ThawTech Industries Inc represents the portable segment archetype across North African research sites. These three incorporated entities collectively illustrate how technology specialization and geographic focus determine margin sustainability in a compliance-driven procurement environment.
| Leading Market Players |
|---|
| CryoGene Systems Inc |
| CellEquip Solutions Inc |
| CellGene Instruments Inc |
| CellGene Thaw Systems Inc |
| CellGenesis Technologies LLC |
| CryoEquip Technologies Inc |
| ThawTech Industries Inc |
| ThermoCell Recovery Ltd |
| ThermoCell Systems Ltd |
| Others |
Supply & Pricing Matrix
Aluminum alloy pricing indices and medical-grade stainless steel benchmarks cascade through conductive heating module fabrication into three-tier pricing structures across premium automated systems, mid-range conductive units, and commodity water-bath alternatives. SFDA validation mandates in Saudi Arabia and MOHAP requirements in the UAE compress margins on non-compliant equipment while elevating premiums for closed-system architectures with embedded data-logging capabilities.
Pricing Analysis
Throughput-linked value anchors separate premium automated thawing systems from commodity alternatives, with pharmaceutical buyers paying for batch reproducibility guarantees rather than hardware alone. Price differentiation rests on certification grade—SFDA-prevalidated software stacks command fifteen to twenty percent premiums over retrofit-capable hardware—and geographic service density, with Gulf Cooperation Council states bearing elevated maintenance contract costs due to fly-in technician dependencies. Cost compression in manual water-bath tiers intensifies because regional distributors flood research laboratory segments with undifferentiated imports. Academic institutions in South Africa and Egypt exhibit highest price sensitivity, while Saudi cell therapy contract manufacturers show least elasticity due to regulatory compliance imperatives.
Supply Chain Analysis
Single-source vulnerability sits with East Asian manufacturing hubs for precision heating elements and medical-grade thermal sensors, exposing procurement timelines to shipping volatility and geopolitical friction. Component sourcing draws from China for conductive module substrates, South Korea for semiconductor temperature controllers, and Germany for sterile barrier films. Supply chain risk centers on logistics chokepoints through the Strait of Hormuz, where equipment bound for Gulf Cooperation Council markets faces periodic disruption. Distribution runs through Dubai-based medical device distributors serving hospital networks across the Emirates and Saudi Arabia, with secondary channels reaching North African research sites via Casablanca and Cairo logistics nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proprietary heating element fabrication capacity constraints prop pricing power for validated clinical-grade systems, creating supply-constrained conditions that favor incumbents with captive component sources.
For Market Incumbents: Lock in service density advantages across Gulf Cooperation Council states before regional distributors consolidate maintenance capabilities. Expand backward integration into heating module production to neutralize East Asian supply concentration risks. Prioritize pre-validation partnerships with SFDA and MOHAP to erect certification barriers against commodity entrants. For New Entrants and Emerging Players: Begin with portable conductive systems targeting underdeployed North African research sites in Morocco and Egypt, where manual water-bath dominance creates replacement opportunity. Anchor go-to-market through subscription-style maintenance contracts that grant operational expenditure predictability to grant-funded academic centers in Cape Town and Johannesburg. For Investors and Strategic Acquirers: Distressed-cycle entries favor service-integrated providers with localized technical networks in South Africa and the UAE, where specialized cryopreservation technician scarcity creates durable competitive moats. Watch for regulatory harmonization signals from SADC neighbors adopting WHO prequalification standards as inflection indicators for standardized equipment certification plays.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Validation Partnership | SFDA and MOHAP pre-certification accelerates hospital procurement cycles in Riyadh and Dubai corridors. |
| Backward Integration into Heating Modules | In-house production of conductive elements neutralizes East Asian supply concentration vulnerabilities. |
| Service Network Expansion | Localized maintenance density captures recurring revenue from Gulf Cooperation Council hospital networks. |
| Portable System Development | Lightweight conductive designs penetrate North African research sites currently dependent on manual methods. |
| Subscription Contract Unbundling | Operational expenditure predictability aligns with South African academic medical center grant funding structures. |
Research Methodology
SFDA technical guidance documents, MOHAP cold-chain validation circulars, and WHO prequalification standards formed the secondary backbone for regulatory requirement mapping. Primary interviews with biomedical engineers, hospital procurement managers, cell therapy contract manufacturing executives, and aftermarket service heads supplied operational context on equipment deployment patterns. Customs records and medical device import registries provided volume triangulation against bottom-up installed base estimates across Saudi Arabia, the UAE, and South Africa.
Historical trendline analysis of conductive heating system shipments and water-bath unit replacements established baseline growth trajectories across the projection horizon. The analytical framework modeled segmentation dimensions including product tier, end-user category, technology type, and regional regulatory cluster. CAGR derivation incorporated equipment replacement cycles driven by compliance mandates, bioprocessing facility expansion timelines, and research laboratory budget allocation patterns.
Underlying measurement precision varies by segment; automated thawing systems carry tighter precision than portable device estimates due to concentrated vendor reporting. Forecasts reflect assumptions about regulatory harmonization pace and biotech corridor investment continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Cell Regeneration Medicine Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
NTRK Fusion Gene Positive Advanced Solid Tumor Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Cell Therapy Technologies Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Engineered T Cells Market