
 Cryopreservation Cell Lines Market | 2026-2036
Cryopreservation Cell Lines Market Size, Share, and Industry Trends Forecast 2026-2036
Cryopreservation Cell Lines Market Outlook
Multi-source cell line procurement is shifting from centralized in-house biobanks toward specialized third-party repositories. Thermo Fisher Scientific Inc. leverages its end-to-end cold-chain infrastructure to dominate commercial distribution. Merck KGaA sustains leadership in cryoprotectant chemistry and validated media formulations. Lonza Group Ltd. anchors high-margin custom cell-line engineering services for gene therapy developers.
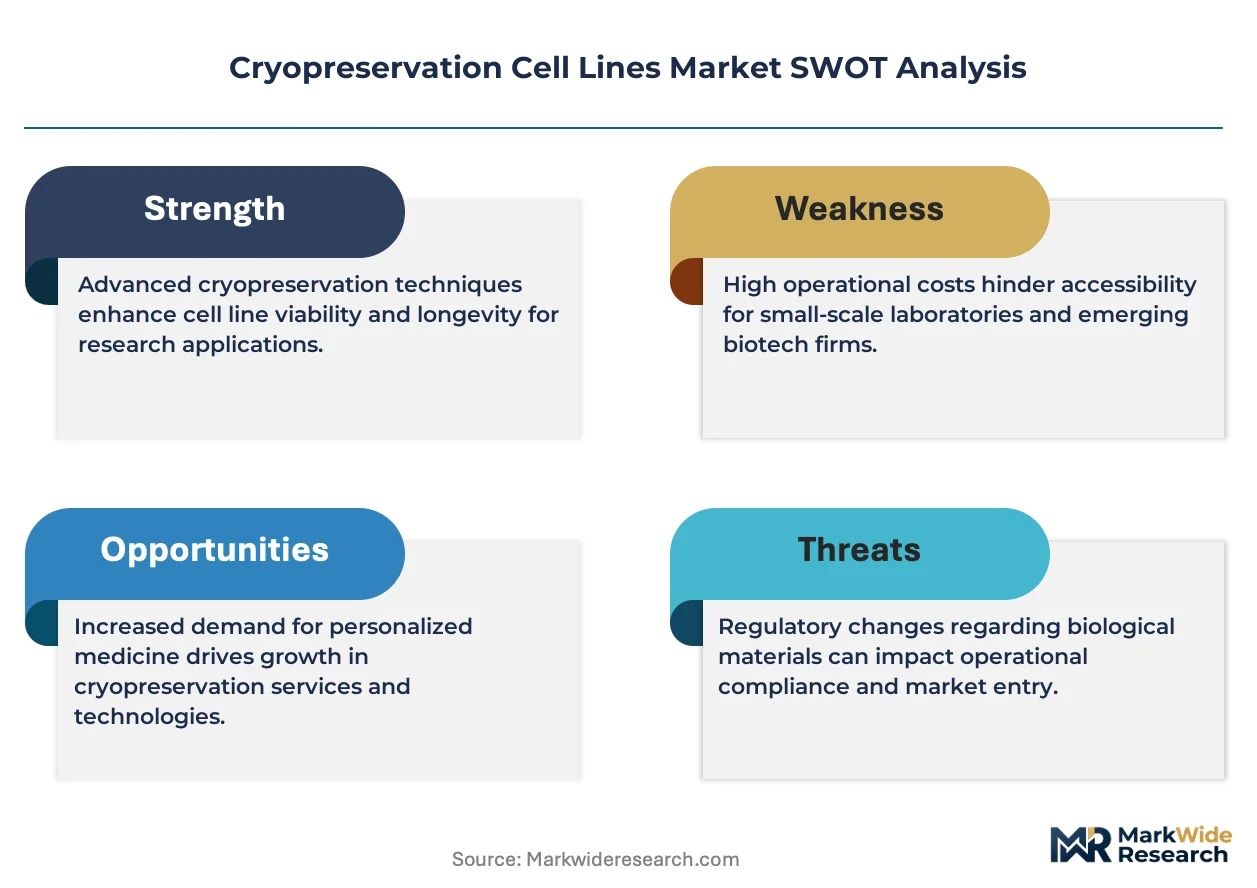
Cryopreservation cell lines are living biological materials stabilized through controlled-rate freezing, typically with dimethyl sulfoxide or glycerol-based cryoprotectants, then maintained in liquid nitrogen vapor-phase storage for subsequent revival and propagation in research or therapeutic manufacturing. Animal cell lines and stem cell lines command the largest volume positions, with stem cell lines capturing the fastest expansion as allogeneic cell therapy programs multiply. Drug development applications consume the greatest share of characterized lines, while regenerative medicine represents the emerging margin pool as clinical-grade master cell banks become mandatory.
FDA cGMP standards, EMA cell-based medicinal product guidelines, and ISO 20387 biobanking requirements collectively elevate compliance costs and favor vendors with documented quality management systems. Regulators now mandate full traceability from donor consent through cryogenic storage, pushing smaller academic repositories toward accredited commercial partners. Stakeholders must monitor evolving distinctions between research-use-only and clinical-grade designations, as this boundary determines pricing power and market access eligibility.
Market Dynamics
Biopharmaceutical pipelines are converging on allogeneic cell therapies, forcing developers to outsource master cell bank construction to specialized repositories with ISO 20387 accreditation and documented cold-chain integrity.
Growth Catalysts
- EMA cell-based medicinal product guidelines:Mandatory clinical-grade characterization standards are pulling gene therapy developers toward certified third-party biobanks with validated quality management systems.
- Dimethyl sulfoxide-free cryoprotectants:Advanced formulations reduce post-thaw apoptosis rates, enabling therapeutic developers to meet FDA cGMP potency thresholds for commercial-scale manufacturing.
- United States academic medical centers:Federally funded stem cell repositories are expanding characterization services to support investigator-initiated trials, creating demand pull for high-throughput viability testing.
Market Restraints
- Liquid nitrogen supply concentration:Industrial gas production clusters in the Gulf Coast region of the United States, exposing coastal biobanks to hurricane-related vapor-phase storage disruptions.
- FDA donor eligibility documentation:Extended traceability requirements from collection through cryogenic storage add 12-18 months to master cell bank qualification timelines.
- Electrical grid fragility:Backup generator dependency for vapor-phase storage systems creates operational vulnerability during regional power infrastructure failures.
Strategic Opportunities
- India's CDSCO accelerated approval pathway:Domestic contract research organizations are building GMP-compliant cell banking capacity to serve emerging CAR-T developers targeting the South Asian market.
- Machine learning-driven thaw optimization:Algorithmic control of warming rates is converging with robotic liquid handling to reduce post-thaw viability variance in high-value stem cell lines.
- Research-use-only to clinical-grade conversion services:Specialized vendors are capturing margin by requalifying existing academic cell lines under ISO 20387 for therapeutic manufacturing eligibility.
Industry Challenges
- Cryobiology specialist scarcity:Qualified personnel for controlled-rate freezing protocol development are concentrated at fewer than two dozen academic programs worldwide.
- Multi-site storage synchronization:Distributed master cell bank architecture requires real-time inventory visibility across vapor-phase dewars at geographically separated facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryopreservation Cell Lines Market |
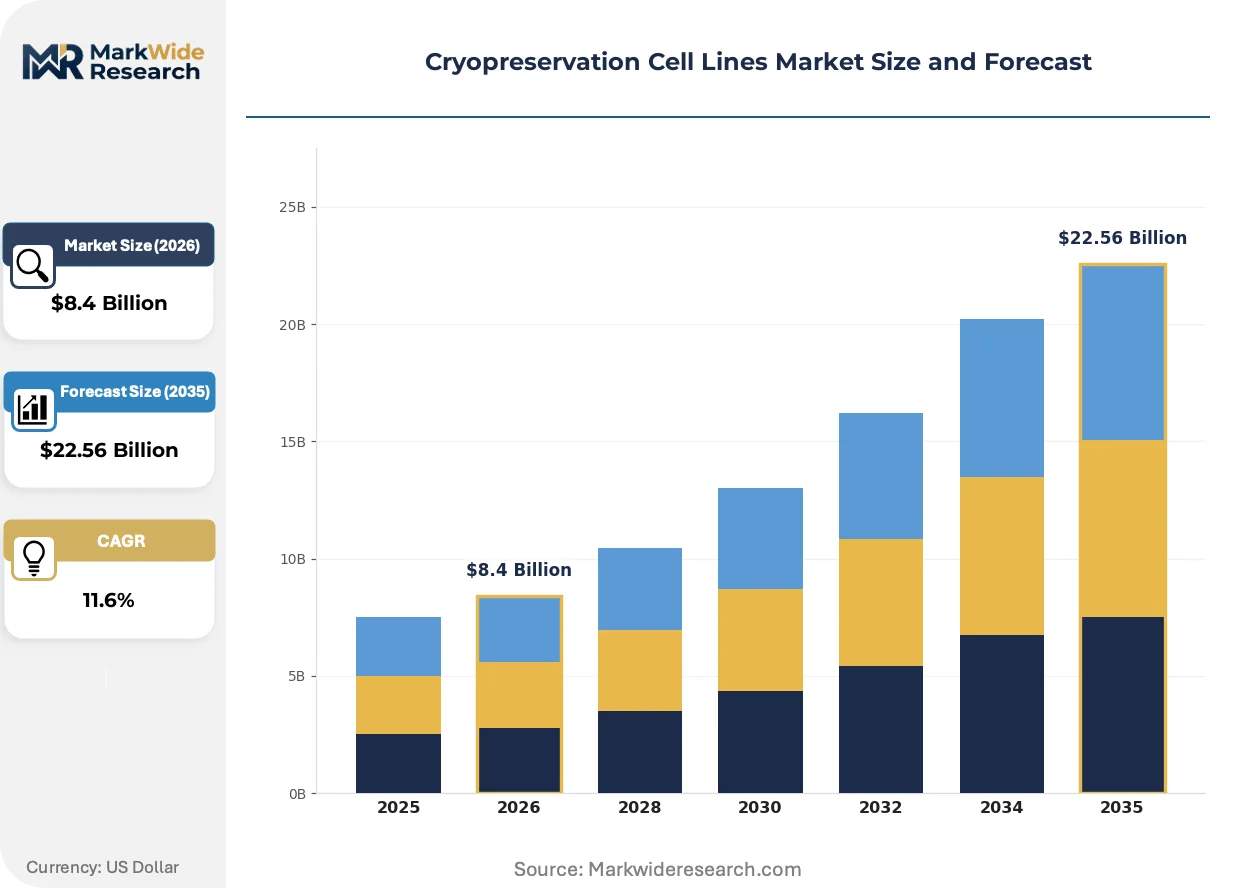
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.56 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Animal Cell Lines, Human Cell Lines, Hybridoma Cell Lines, Stem Cell Lines Application: Cell Therapy, Tissue Engineering, Drug Development, Regenerative Medicine Technology: Freezing Protocols, Cryoprotectants, Storage Equipment, Thawing Methods End User: Biopharmaceutical Companies, Research Institutes, Hospitals, Academic Laboratories |
| Companies Covered | Thermo Fisher Scientific Inc., Merck KGaA, BioLife Solutions, Inc., Corning Incorporated, Lonza Group Ltd., Sartorius AG, PromoCell GmbH, HiMedia Laboratories Pvt. Ltd., STEMCELL Technologies Canada Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryopreservation Cell Lines Market Strategic Shifts
Automation is penetrating cryopreservation workflows at the point of highest technical risk, compressing viability variance while enabling scale-out of clinical-grade cell banking services.
Controlled-rate freezing systems with integrated robotic sample handling are automating the transition from manual benchtop protocols to high-throughput production environments. Gene therapy CDMOs in Massachusetts and California are deploying these platforms to support IND-enabling studies for allogeneic programs. The technology is automating the elimination of operator-dependent temperature excursion events that previously compromised master cell bank qualification.
FDA's updated guidance on co-culture and feeder-free conditions for human pluripotent stem cells is mandating additional characterization panels for cryopreserved lines entering clinical trials. The regulation forces developers to rescreen existing banks for adventitious agents and karyotypic stability. Allogeneic cell therapy sponsors in the United States are responding by consolidating procurement with vendors holding dual ISO 20387 and cGMP certifications.
Academic medical centers are unbundling long-term storage from characterization services, contracting vapor-phase dewar capacity from specialized logistics providers while retaining scientific oversight. This disintermediation of the traditional integrated biobank model is visible most acutely at National Cancer Institute-designated centers, where principal investigators now specify storage location independently from analytical testing protocols. The shift is compressing pricing power for repositories lacking either premier scientific reputation or lowest-cost cold-chain infrastructure.
Cryopreservation Cell Lines Market Segmentation
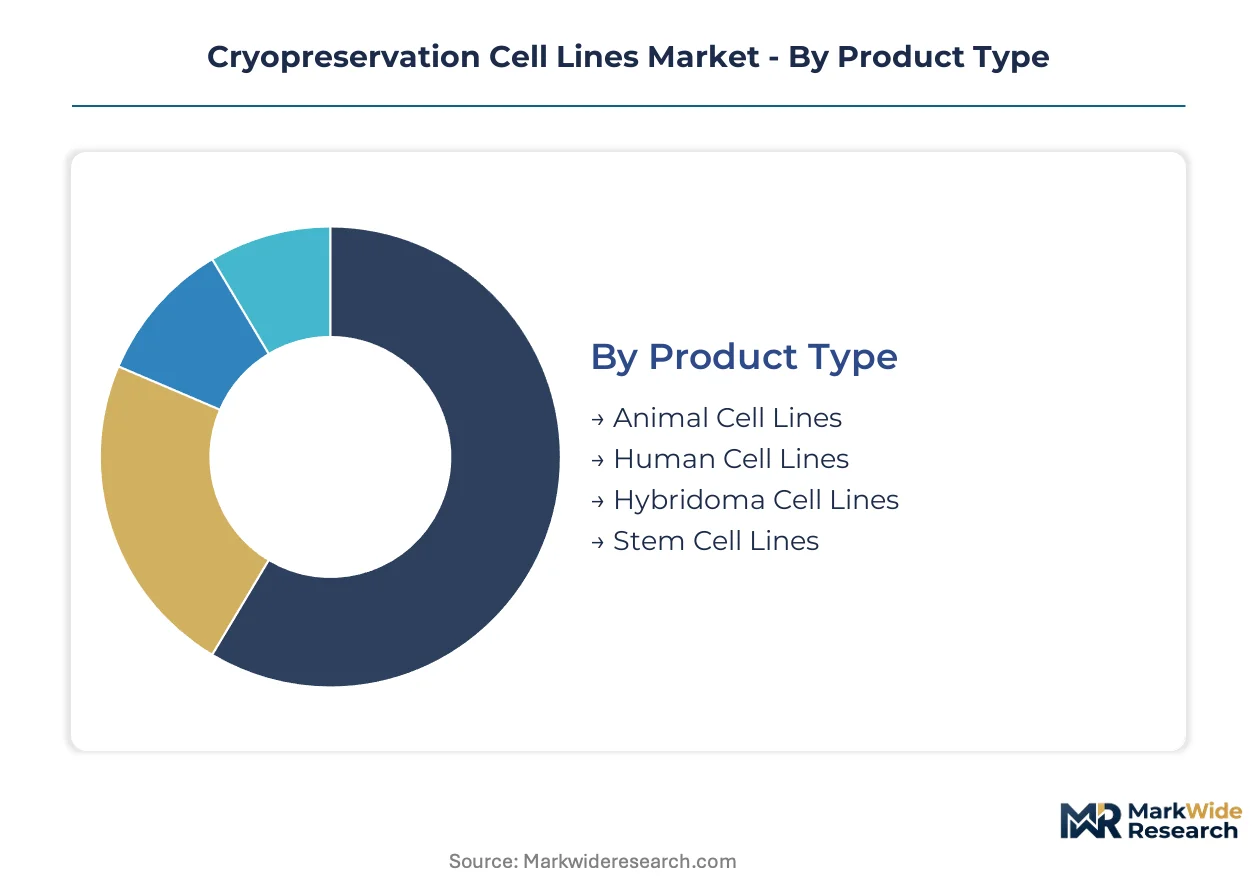
Segmentation in cryopreservation cell lines reveals how supply-side capabilities align with divergent end-use requirements. Each dimension exposes distinct margin structures, regulatory thresholds, and vendor specialization patterns that determine competitive positioning.
Product Type:
Supply concentration varies sharply across biological source materials, with stem cell repositories commanding premium positioning due to characterization complexity and clinical-grade qualification barriers.
- Stem Cell Lines:Pluripotent and multipotent populations require feeder-free culture adaptation before cryopreservation. Demand concentrates at allogeneic cell therapy developers in Massachusetts and California seeking IND-ready master cell banks with documented karyotypic stability.
- Animal Cell Lines:CHO and HEK293 derivatives dominate bioproduction workflows with established cryoprotectant protocols. Contract manufacturing organizations in Switzerland and Singapore maintain the largest characterized repositories for recombinant protein production.
- Human Cell Lines:Immortalized populations from diverse tissue origins support oncology and infectious disease research. Academic medical centers in the United States federate procurement through shared services organizations to reduce duplication.
- Hybridoma Cell Lines:Monoclonal antibody-producing fusions retain niche demand for diagnostic reagent manufacturing. Biobanks in Germany and Japan preserve legacy collections amid recombinant antibody displacement.
Today's leader: Animal Cell Lines. Tomorrow's challenger: Stem Cell Lines.
Application:
End-use economics separate research-grade consumption from clinical-grade manufacturing, with regenerative medicine applications extracting the steepest price premiums for traceability documentation.
- Drug Development:High-throughput screening and toxicity testing consume standardized cell panels in volume. Pharmaceutical sponsors in the United Kingdom and the Netherlands outsource procurement to vendors with ISO 20387 accreditation.
- Cell Therapy:Allogeneic programs require donor-eligible lines with full provenance documentation. CDMOs in North Carolina and Texas are expanding vapor-phase capacity to support commercial-scale master cell bank construction.
- Tissue Engineering:Scaffold-seeded constructs demand specialized thaw protocols to preserve extracellular matrix interactions. Research institutes in Sweden and South Korea pioneer organoid banking standards.
- Regenerative Medicine:Clinical-grade designation mandates cGMP-compliant characterization panels. The segment climbs fastest as FDA and EMA tighten potency assay requirements for cryopreserved starting materials.
Drug Development commands present volume. Regenerative Medicine captures future margin expansion.
Technology:
Technology selection determines post-thaw viability variance, with automated controlled-rate systems displacing manual protocols in high-value therapeutic manufacturing.
- Cryoprotectants:Dimethyl sulfoxide-based formulations retain dominance despite cytotoxicity concerns. Dimethyl sulfoxide-free alternatives gain traction at gene therapy developers facing FDA cGMP scrutiny.
- Freezing Protocols:Programmable rate-controlled systems eliminate operator-dependent temperature excursions. Biobanks in California and Massachusetts deploy integrated robotic handling for master cell bank production.
- Storage Equipment:Vapor-phase liquid nitrogen dewars with automated level monitoring reduce sample loss risk. Coastal facilities in the United States Gulf region face hurricane-related supply disruption exposure.
- Thawing Methods:Algorithmic warming rate optimization using machine learning reduces viability variance. Emerging platforms from Swiss and Japanese equipment vendors target stem cell therapy applications.
Cryoprotectants anchor current practice. Thawing Methods enable next-generation quality thresholds.
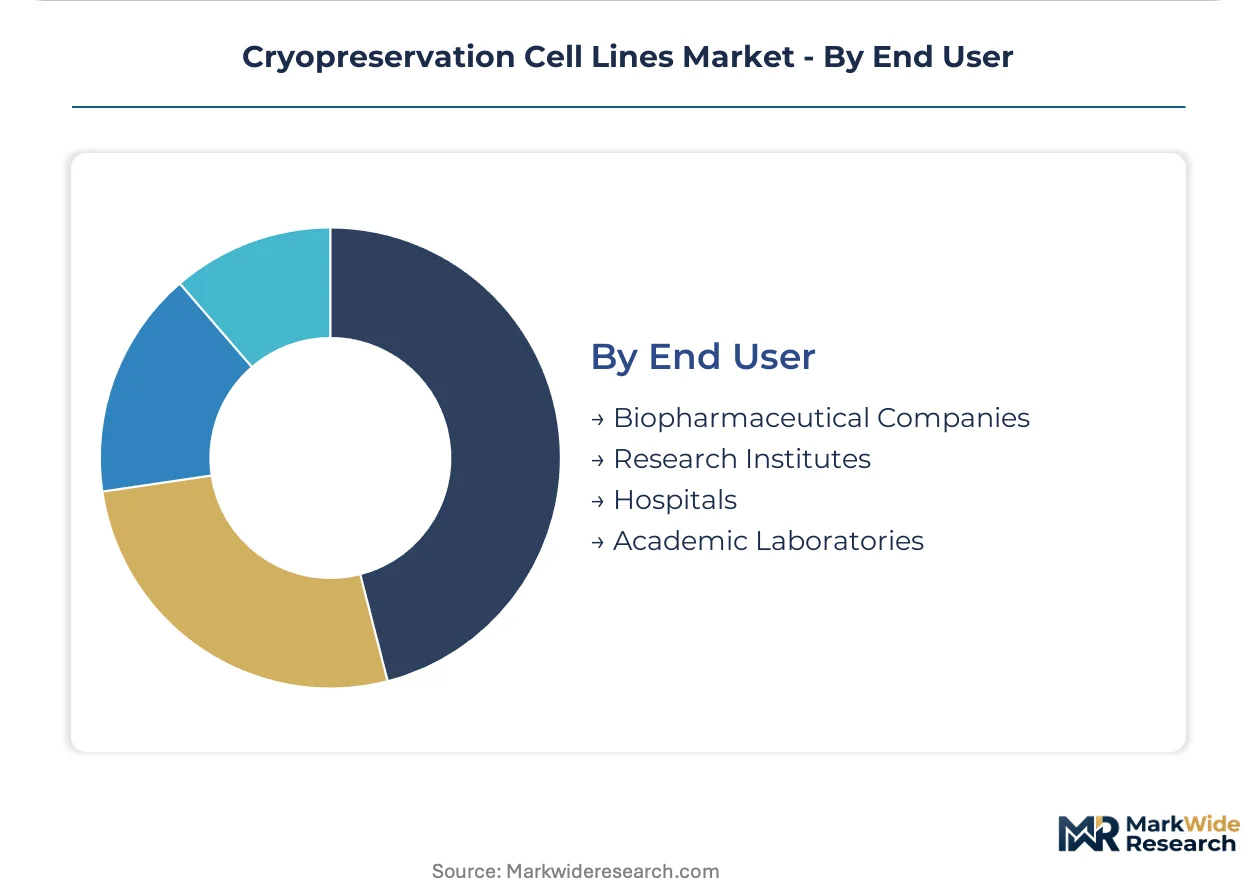
End User:
Customer type dictates service bundling preferences, with biopharmaceutical sponsors consolidating procurement while academic investigators unbundle storage from characterization.
- Biopharmaceutical Companies:Integrated outsourcing of master cell bank construction to accredited third-party repositories. Sponsors in the United States and Switzerland prioritize vendors with dual ISO 20387 and cGMP certifications.
- Research Institutes:Federated procurement through consortia reduces per-sample storage costs. National Cancer Institute-designated centers increasingly specify logistics providers independently from analytical testing protocols.
- Academic Laboratories:Investigator-initiated trials drive demand for characterized human pluripotent stem cell repositories. Federally funded programs in the United States expand viability testing services.
- Hospitals:Cell therapy treatment centers require point-of-care thaw capabilities with documented chain-of-custody. Academic medical centers in Germany and Japan pioneer decentralized banking models.
Biopharmaceutical Companies concentrate spending power today. Hospitals represent the distributed demand frontier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Greater Boston anchors cell banking infrastructure, with Massachusetts biotech clusters driving demand for ISO 20387-accredited repositories serving allogeneic therapy pipelines.
United States
Contract research organizations in North Carolina and Texas expand vapor-phase capacity for commercial-scale master cell bank construction. FDA cGMP standards mandate full traceability from donor consent through cryogenic storage. Academic medical centers in California federate procurement through shared services organizations to reduce per-sample storage costs.
Germany
Biobanks in Heidelberg and Munich preserve legacy hybridoma collections amid recombinant antibody displacement. EMA cell-based medicinal product guidelines pull gene therapy developers toward certified third-party repositories. Contract manufacturing organizations in Baden-Württemberg maintain characterized repositories for recombinant protein production.
Switzerland
Gene therapy CDMOs in Basel deploy automated controlled-rate freezing platforms to support IND-enabling studies. Swissmedic requirements for clinical-grade designation mandate potency assay documentation. Equipment vendors in Zurich pioneer algorithmic warming rate optimization for stem cell therapy applications.
Japan
Academic medical centers in Tokyo and Osaka pioneer decentralized banking models with point-of-care thaw capabilities. METI-funded stem cell repositories expand characterization services for investigator-initiated trials. Biobanks in Kansai preserve induced pluripotent stem cell lines under JIS-documented quality management systems.
India
Domestic contract research organizations in Hyderabad and Bengaluru build GMP-compliant cell banking capacity for CAR-T developers. CDSCO accelerated approval pathways attract emerging therapeutic sponsors targeting South Asian markets. HiMedia Laboratories in Mumbai anchors regional cryoprotectant media supply chains.
Cryopreservation Cell Lines Market Competitive Environment
Global majors compete with regional champions across cold-chain infrastructure and cryoprotectant chemistry. The vendor base separates into three tiers: integrated life science conglomerates with end-to-end distribution networks, specialized bioprocessing material suppliers with validated formulation expertise, and regional equipment fabricators with cost-optimized storage systems. Consolidation pressures concentrate procurement decisions among sponsors requiring dual ISO 20387 and cGMP certifications. Dominant competitive moves include strategic partnerships for master cell bank construction and geographic expansion into emerging therapy clusters.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Merck KGaA exemplify the integrated infrastructure archetype, with the former representing end-to-end cold-chain dominance and the latter anchoring cryoprotectant chemistry leadership. Lonza Group Ltd. occupies a position within the custom-engineering tier, serving gene therapy developers with high-margin cell-line services. These three entities collectively illustrate how accreditation depth and documented quality management systems determine vendor selection in therapeutic manufacturing procurement.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| BioLife Solutions, Inc. |
| Corning Incorporated |
| Lonza Group Ltd. |
| Sartorius AG |
| PromoCell GmbH |
| HiMedia Laboratories Pvt. Ltd. |
| STEMCELL Technologies Canada Inc. |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between clinical-grade and research-use-only cell lines manifests in parallel supply chain configurations, with ISO 20387-accredited repositories commanding three-to-five-fold price premiums over academic biobanks while sourcing cryoprotectant media from validated chemistry suppliers rather than commodity distributors. This divergence tightens as FDA cGMP potency thresholds force gene therapy developers to consolidate procurement with vendors holding dual certification, compressing margins for repositories lacking documented quality management systems.
Pricing Analysis
Input-cost pass-through from dimethyl sulfoxide-free cryoprotectant chemistry and liquid nitrogen vapor-phase infrastructure dominates contract-based long-term offtake structures, with price differentiation anchored in ISO 20387 accreditation depth and cGMP certification tier. Academic medical centers exhibit highest price sensitivity due to federated procurement constraints, while allogeneic cell therapy sponsors absorb premium pricing for traceability documentation. Cost compression in research-grade storage is intensifying because of unbundled logistics contracts, though clinical-grade master cell bank construction retains pricing power through mandatory donor eligibility documentation.
Supply Chain Analysis
Liquid nitrogen supply rests on industrial gas production clusters concentrated in the United States Gulf Coast, Germany, and Japan, with cryoprotectant chemistry anchored in Swiss and German specialty chemical producers and automated freezing equipment sourced from Japanese and Swiss equipment fabricators. Raw material dependencies span dimethyl sulfoxide and glycerol formulations, programmable rate-controlled freezing systems, and vapor-phase dewar infrastructure. Single-source vulnerability in Gulf Coast nitrogen production exposes coastal biobanks to hurricane-related disruption. Distribution runs through accredited third-party repositories with validated cold-chain integrity to biopharmaceutical sponsors and academic consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where procurement consolidation among allogeneic cell therapy developers favors vendors with documented ISO 20387 and cGMP certification depth over commodity storage providers.
For Market Incumbents: Cement accreditation differentiation by deepening backward integration into cryoprotectant chemistry manufacturing and expanding vapor-phase capacity in hurricane-exposed geographies to mitigate single-source nitrogen risk. Threat of automated thaw optimization platforms from Swiss and Japanese equipment vendors demands preemptive partnership with algorithmic warming rate developers to preserve master cell bank construction margins. For New Entrants and Emerging Players: Enter via India's CDSCO accelerated approval pathway, where domestic GMP-compliant cell banking capacity remains underdeveloped relative to emerging CAR-T sponsor demand. White-space targets include research-use-only to clinical-grade conversion services for existing academic cell lines and machine learning-driven thaw optimization for high-value stem cell applications. Go-to-market positioning should emphasize ISO 20387 requalification expertise over commodity storage. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized bioprocessing material suppliers with validated cryoprotectant formulation expertise and regional equipment fabricators with cost-optimized storage systems. Long-term viability over the next decade hinges on regulatory enforcement intensity for clinical-grade designation. Signal to monitor: FDA issuance of final guidance on feeder-free human pluripotent stem cell characterization panels.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 20387 Accreditation Investment | Dual certification with cGMP unlocks gene therapy CDMO procurement consolidation in Massachusetts and California. |
| Backward Integration into Cryoprotectant Chemistry | In-house dimethyl sulfoxide-free formulation capability captures margin from Merck KGaA and BioLife Solutions. |
| Geographic Expansion into India | CDSCO-aligned GMP capacity addresses CAR-T developer demand in Hyderabad and Bengaluru. |
| Machine Learning Thaw Optimization Partnership | Algorithmic warming rate control reduces post-thaw viability variance for stem cell therapy applications. |
| Research-to-Clinical Grade Conversion Service Launch | Requalification of academic lines under ISO 20387 captures margin from unbundled biobank procurement. |
Study Parameters
Multiple input streams — structured interviews with cell banking executives, regulatory affairs leads at gene therapy CDMOs, and procurement managers at academic medical centers, combined with FDA cGMP guidance documents, EMA cell-based medicinal product guidelines, and ISO 20387 accreditation databases — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from ClinicalTrials.gov allogeneic therapy registrations, SEC filings of diversified life science conglomerates, and trade data on cryoprotectant chemical imports.
Data-stream reconciliation across product type, application, technology, and end-user dimensions enabled segmentation-specific growth trajectory modeling across the projection horizon. CAGRs were derived from elasticity analysis of biopharmaceutical pipeline expansion against regulatory compliance cost inflation. Industry-specific forecast inputs incorporated liquid nitrogen supply concentration risk and automation penetration rates in controlled-rate freezing protocols.
Inputs from accredited repository certification databases and CDSCO regulatory filings were available through the study window; gaps in real-time inventory visibility across distributed master cell bank architectures introduce uncertainty bands around commercial-scale capacity expansion timelines. Forecasts reflect assumptions regarding enforcement consistency for clinical-grade designation. Material deviation in FDA final guidance timing or EMA guideline revision scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
Asia-Pacific Stem Cell Therapy Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
Engineered T Cells Market
Cell & Gene Therapy
Retinal Gene Therapy Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
Cell Reprogramming Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market
Cell & Gene Therapy
Stem Cell Manufacturing Market
Cell & Gene Therapy
Cell and Gene Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market