
 North America Stem Cell Market | 2026-2036
North America Stem Cell Market Size, Share, and Industry Trends Forecast 2026-2036
North America Stem Cell Market Analytics
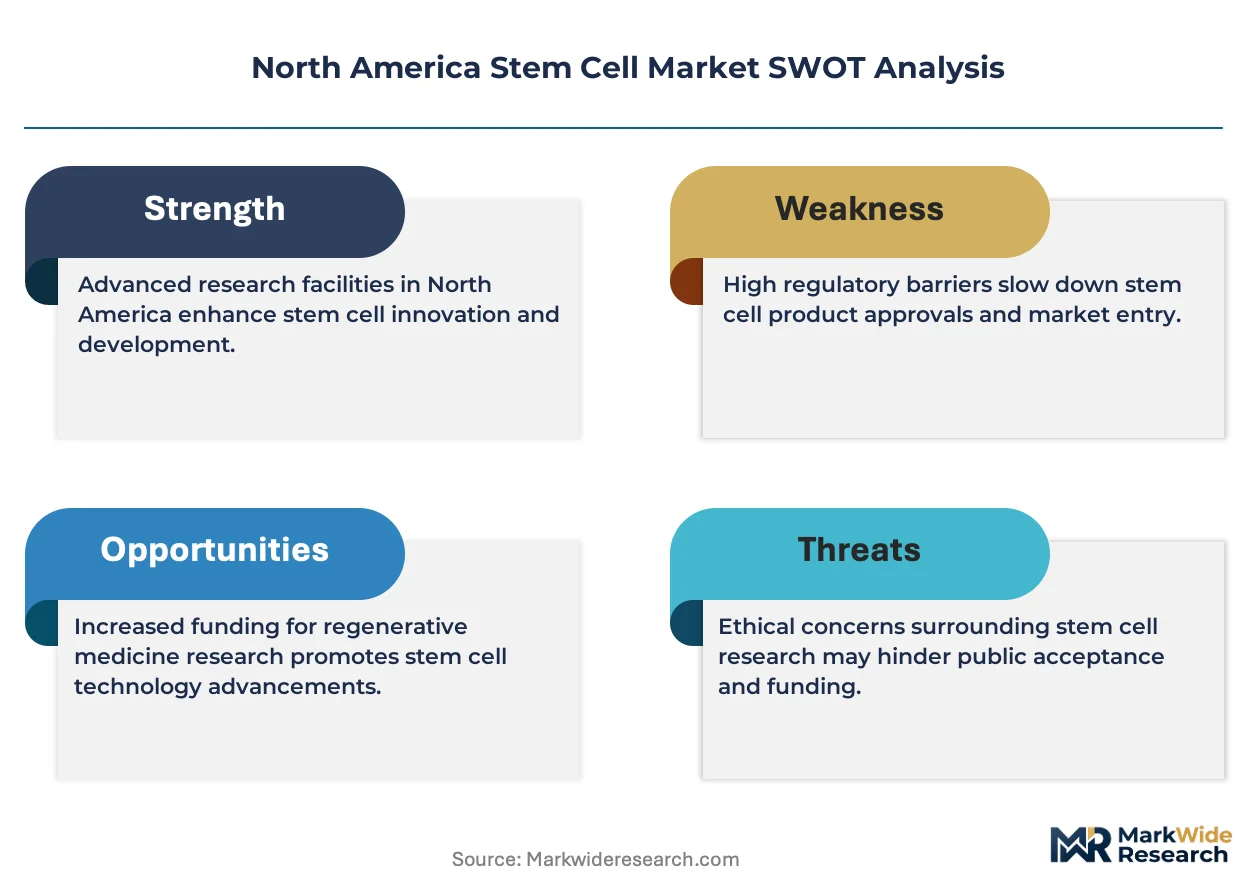
FDA's regenerative medicine advanced therapy (RMAT) designation is expanding the cost-of-entry calculus for commercial stem cell developers by streamlining review pathways and reducing regulatory uncertainty. Thermo Fisher Scientific leverages its reagent and instrument portfolio to anchor supply chain control across research and clinical-grade workflows. Becton, Dickinson and Company sustains competitive positioning through automated cell sorting and isolation platforms. Lineage Cell Therapeutics specializes in allogeneic cell therapy manufacturing, differentiating its pipeline against autologous approaches.
North America stem cells comprise undifferentiated biological units capable of self-renewal and lineage-specific differentiation, typically maintained in defined media formulations at 37°C with 5% CO2 for therapeutic and research applications. Adult stem cells occupy the largest revenue pool due to established clinical safety profiles and lower ethical barriers, while induced pluripotent stem cells represent the fastest-expanding category as reprogramming efficiencies improve and GMP-compatible protocols mature. Regenerative medicine applications command premium pricing relative to drug development, reflecting longer development horizons and higher reimbursement potential for approved cell therapies.
FDA, Health Canada, and ISO 20399 standards collectively shape product specifications, donor screening requirements, and cross-border material transfer protocols across the North American market. Health Canada's biologics and genetic therapies directorate enforces comparable but distinct manufacturing and distribution rules that create dual-compliance obligations for multi-jurisdictional operators. Stakeholders must monitor evolving FDA guidance on genome-edited stem cell products and prepare for potential harmonization pressures between US and Canadian traceability requirements.
Market Dynamics
FDA's regenerative medicine advanced therapy designation is compressing clinical trial timelines and redrawing competitive entry barriers across North American stem cell development pipelines.
Growth Catalysts
- RMAT Designation:FDA's streamlined review pathway reduces regulatory uncertainty for cell therapy developers, accelerating commercialization timelines for qualifying products.
- California Biotech Clustering:Research institutions and venture-backed startups concentrate near Stanford and UCSF, creating dense knowledge spillovers and specialized talent pools.
- Allogeneic Manufacturing Scale-Up:Standardized cell banks enable batch production at lower per-dose costs than patient-specific autologous approaches.
Market Restraints
- Donor Material Scarcity:Qualified tissue sourcing remains concentrated among limited FDA-registered cord blood banks and tissue establishments.
- GMP Facility Capital Intensity:Cleanroom infrastructure and environmental monitoring systems require substantial upfront investment before revenue generation.
- Health Canada Dual Compliance:Biologics and genetic therapies directorate rules create parallel validation requirements for cross-border operators.
Strategic Opportunities
- Texas Medical Center Expansion:Houston's institutional research capacity offers underutilized clinical trial infrastructure for late-stage cell therapy studies.
- ISO 20399 Harmonization:Emerging standards for ancillary materials create first-mover advantages for suppliers achieving early certification.
- AI-Driven Cell Characterization:Machine learning integration with flow cytometry and imaging platforms accelerates potency assay development.
Industry Challenges
- GMP-Trained Workforce Gap:Cell therapy manufacturing requires hybrid skill sets combining biological science with pharmaceutical quality systems that remain scarce.
- Legacy Electronic System Integration:Paper-based batch records and disconnected data lakes impede real-time release testing and continuous process verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Stem Cell Market |
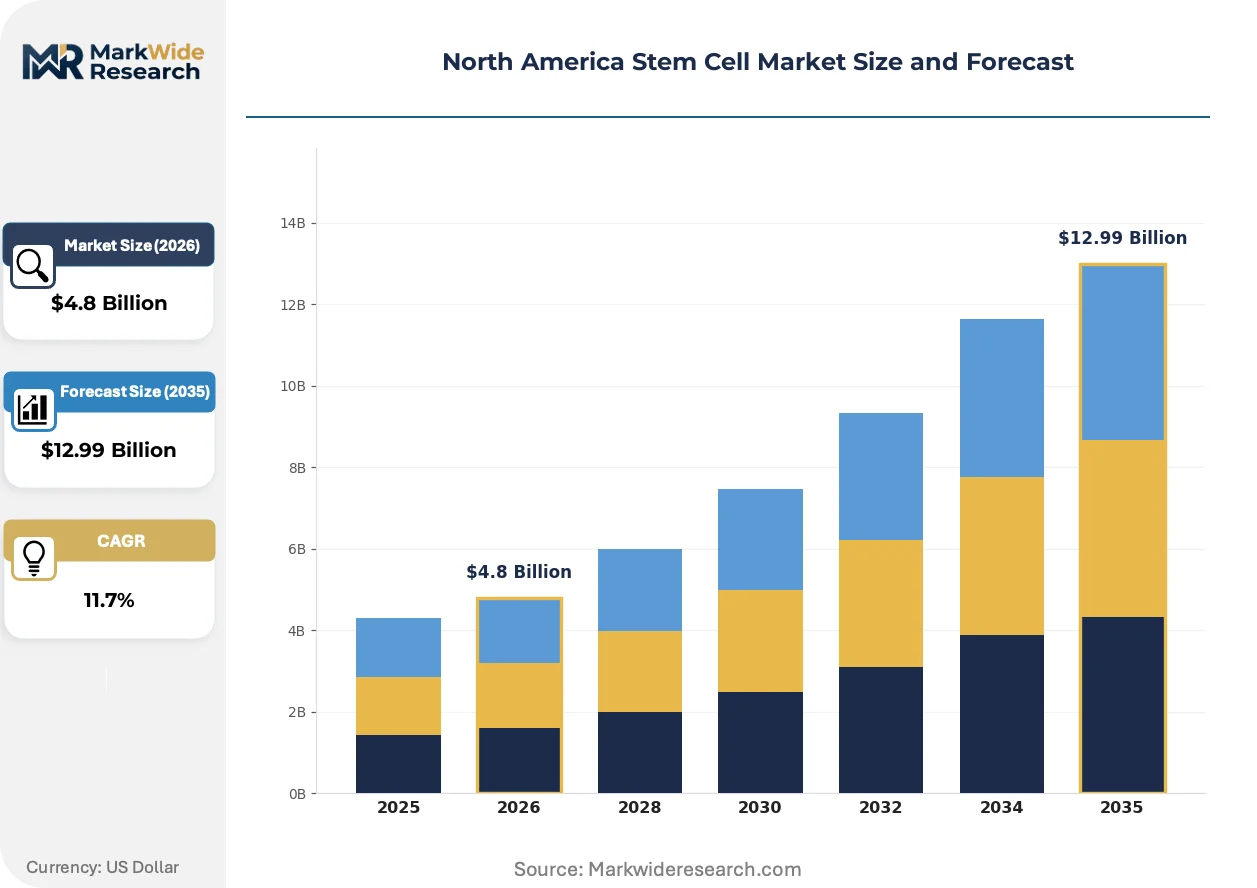
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embryonic Stem Cells, Adult Stem Cells, Induced Pluripotent Stem Cells, Cancer Stem Cells Application: Regenerative Medicine, Tissue Engineering, Drug Development, Disease Modeling End User: Pharmaceutical Companies, Research Institutions, Hospitals, Biotech Firms Technology: Cell Culture Techniques, Stem Cell Isolation, Genetic Manipulation, Bioreactors |
| Companies Covered | Thermo Fisher Scientific, Becton, Dickinson and Company, Merck KGaA, Lineage Cell Therapeutics, Inc., STEMCELL Technologies, Lonza Group Ltd, Bristol-Myers Squibb Company, Miltenyi Biotec, Bio-Techne Corp, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Stem Cell Market Evolving Landscape
Automation and closed-system manufacturing are displacing open culture workflows across North American stem cell production, reshaping facility design and operational economics.
Closed bioreactor systems with integrated perfusion control is overtaking planar culture vessels in commercial-scale pluripotent stem cell expansion. Contract manufacturers serving pharmaceutical clients are adopting these platforms to reduce contamination risk and labor intensity. This technology is overtaking manual handling requirements and enabling single-operator oversight of thousand-liter equivalent production runs.
FDA's evolving guidance on genome-edited stem cell products is forcing developers to establish comprehensive off-target analysis protocols earlier in development cycles. The agency's pre-submission meetings now routinely address editing reagent qualification and clonal derivation documentation. Cell therapy sponsors with CRISPR-modified pipelines are responding by building dedicated genome integrity assessment capabilities in-house rather than outsourcing.
Biopharmaceutical procurement departments are consolidating stem cell material suppliers to reduce qualification burden and audit frequency. Large pharmaceutical buyers are replacing fragmented reagent sourcing with preferred partnership agreements covering media, matrices, and characterization services. This concentration is most visible among Massachusetts and California-based developers with multiple parallel IND programs requiring consistent raw material supply.
North America Stem Cell Market Segmentation
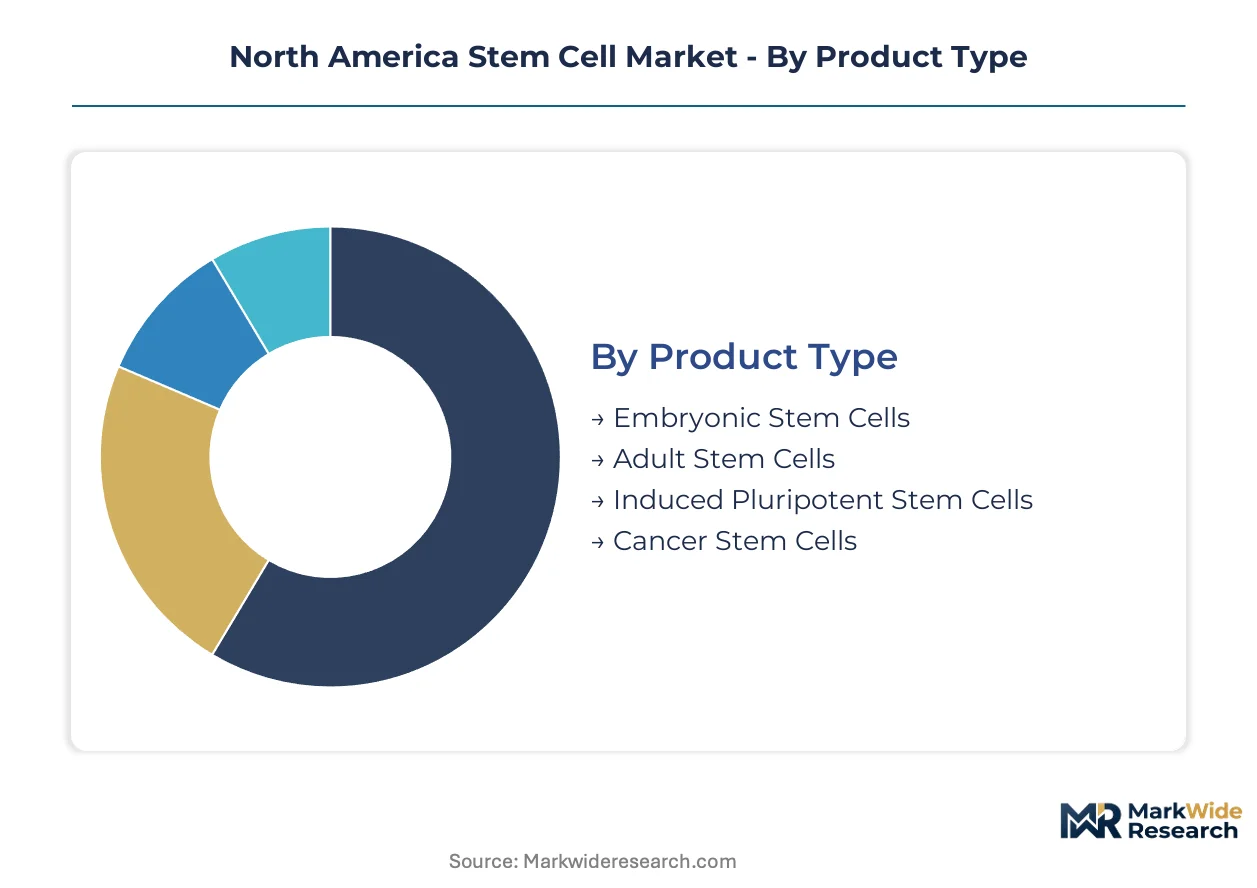
Stem cell procurement decisions in North America hinge on regulatory clearance status, manufacturing scalability, and therapeutic application maturity. Buyers evaluate segments through the lens of FDA pathway feasibility and reimbursement potential rather than research novelty alone.
Product Type:
Cost tier differentiation separates segments with established clinical safety data from those carrying higher development risk and corresponding pricing premiums.
- Adult Stem Cells:Hematopoietic and mesenchymal lineages sourced from bone marrow, adipose tissue, and cord blood carry extensive clinical safety documentation. Demand concentrates among pharmaceutical sponsors seeking lower-risk IND pathways, constrained by qualified donor material scarcity at FDA-registered tissue establishments.
- Induced Pluripotent Stem Cells:Somatic cell reprogramming yields patient-matched or allogeneic pluripotent lines without embryonic sourcing. California biotech clusters near Stanford and UCSF drive adoption, though GMP-compatible protocol maturation remains uneven across contract manufacturers.
- Embryonic Stem Cells:Blastocyst-derived lines maintain research utility for developmental biology and early-stage disease modeling despite restricted federal funding eligibility.
- Cancer Stem Cells:Tumor-initiating cell populations enable oncology target validation and resistance mechanism studies in academic and pharmaceutical screening programs.
Adult stem cells lead on scale; induced pluripotent stem cells lead on momentum.
Application:
Margin structure varies sharply across segments, with therapeutic applications commanding premium pricing relative to research-tool revenue pools.
- Regenerative Medicine:Cell replacement therapies for degenerative conditions require decade-long development horizons and specialized manufacturing infrastructure. Texas Medical Center expansion in Houston offers underutilized late-stage clinical trial capacity for sponsors navigating this segment.
- Drug Development:Stem cell-derived models accelerate toxicity screening and target validation prior to animal studies. Massachusetts-based pharmaceutical procurement departments consolidate suppliers to reduce qualification burden across multiple parallel IND programs.
- Tissue Engineering:Scaffold-integrated cellular constructs address organ replacement and reconstructive surgical applications with complex biomanufacturing requirements.
- Disease Modeling:Patient-derived iPSC lines replicate pathophysiology for rare disease research and precision medicine stratification in academic settings.
Drug development leads on scale; regenerative medicine leads on margin expansion potential.
End User:
Customer type determines volume scale and specification stringency, with commercial manufacturers imposing stricter GMP documentation than academic purchasers.
- Pharmaceutical Companies:Large-cap sponsors drive standardization through preferred partnership agreements covering media, matrices, and characterization services. Procurement consolidation reduces audit frequency but increases supplier qualification barriers.
- Research Institutions:Stanford, UCSF, and peer institutions prioritize experimental flexibility and early access to novel cell lines over manufacturing scale.
- Hospitals:Academic medical centers with cell therapy programs require clinical-grade material for investigator-initiated trials and compassionate use protocols.
- Biotech Firms:Venture-backed developers cluster in California's biotech corridor, sourcing materials for platform validation and Series B-stage IND preparation.
Pharmaceutical companies lead on volume concentration; biotech firms lead on growth velocity.
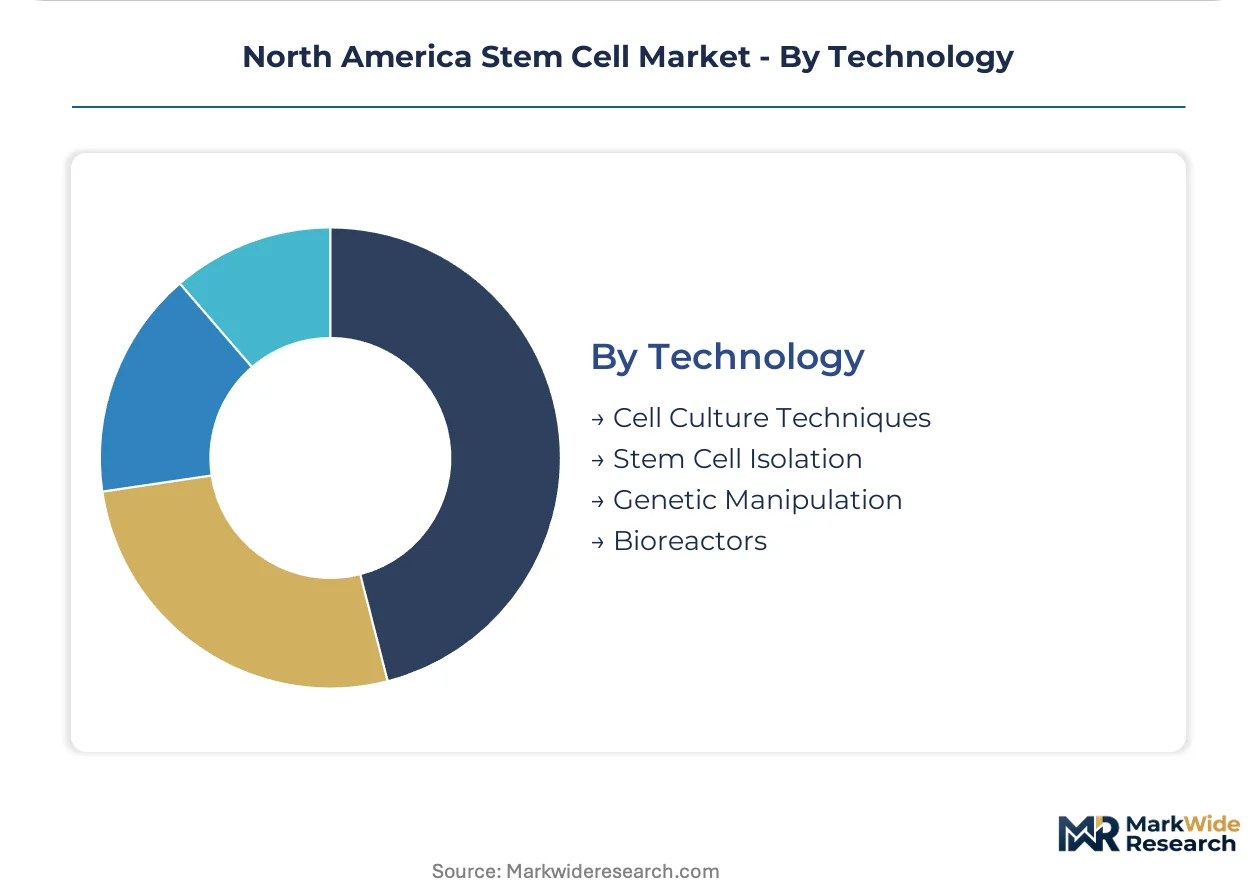
Technology:
Supply concentration among platform vendors shapes competitive dynamics, with closed-system automation displacing manual workflows.
- Bioreactors:Perfusion-controlled closed systems enable thousand-liter equivalent pluripotent stem cell expansion with single-operator oversight. Thermo Fisher Scientific and Becton Dickinson anchor supply chain control through integrated instrument and consumable portfolios.
- Cell Culture Techniques:Defined media formulations and feeder-free substrates reduce lot-to-lot variability for clinical applications. FDA modernization initiatives around cell and gene therapy review pathways compress timeline requirements for culture system validation.
- Stem Cell Isolation:Automated cell sorting platforms reduce contamination risk and labor intensity in commercial-scale manufacturing.
- Genetic Manipulation:CRISPR editing and clonal derivation capabilities require dedicated genome integrity assessment infrastructure to satisfy evolving FDA guidance on off-target analysis.
Cell culture techniques lead on installed base; bioreactors lead on replacement cycle momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stem cell research and commercialization in North America trace their modern lineage to federal funding decisions and early academic breakthroughs that concentrated expertise in specific metropolitan corridors.
United States
California's biotech corridor generates substantial demand through Stanford and UCSF research institutions alongside venture-backed startups. FDA's RMAT designation streamlines review pathways for qualifying cell therapies, compressing trial timelines. The Texas Medical Center in Houston offers underutilized late-stage clinical trial infrastructure for regenerative medicine sponsors.
Canada
Health Canada's biologics and genetic therapies directorate enforces manufacturing and distribution rules that create dual-compliance obligations for cross-border operators. ISO 20399 standards adoption proceeds among ancillary material suppliers serving the Canadian market. Toronto and Vancouver house emerging cell therapy research clusters with ties to American pharmaceutical sponsors.
Mexico
Clinical trial cost advantages attract North American sponsors seeking patient recruitment for stem cell studies. COFEPRIS regulatory frameworks for advanced therapies continue evolving toward alignment with FDA standards. Guadalajara and Mexico City concentrate contract research organizations supporting biopharmaceutical development programs.
North America Stem Cell Market Competitive Landscape
The competitive structure tilts toward diversified life science conglomerates with integrated reagent and instrument portfolios. Market concentration remains moderate, with several large-cap players controlling supply chain nodes while specialized cell therapy developers occupy niche positions. Three archetypes dominate: platform-anchored conglomerates, allogeneic manufacturing specialists, and research-grade material suppliers. Capacity expansion and strategic partnerships represent the primary competitive moves, with preferred supplier agreements replacing fragmented procurement relationships.
Among platform-anchored conglomerates, Thermo Fisher Scientific and Becton, Dickinson and Company exemplify the integrated instrument-and-consumable model that controls research and clinical-grade workflows. Lineage Cell Therapeutics occupies a position within the allogeneic manufacturing specialist tier, differentiating against autologous approaches through standardized cell bank production. These three represent distinct strategic positions without implying specific market share or performance claims.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Becton, Dickinson and Company |
| Merck KGaA |
| Lineage Cell Therapeutics, Inc. |
| STEMCELL Technologies |
| Lonza Group Ltd |
| Bristol-Myers Squibb Company |
| Miltenyi Biotec |
| Bio-Techne Corp |
| Others |
Value Network & Pricing Analysis
Qualified donor material costs cascade through three distinct pricing tiers as raw tissue sourcing from FDA-registered cord blood banks concentrates among limited certified establishments. GMP facility capital intensity upstream compresses margins for contract manufacturers while pharmaceutical procurement consolidation downstream extracts volume discounts from preferred suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates stem cell procurement, separating clinical-grade allogeneic cell banks from research-grade iPSC lines and basic characterization reagents. Price differentiation hinges on FDA master file documentation status and ISO 20399 ancillary material certification, with premium tiers commanding substantial markups for validated GMP protocols. Pricing pressure stems from biopharmaceutical procurement departments consolidating fragmented supplier relationships into single-source preferred partnerships. Academic medical centers exhibit highest price sensitivity due to constrained grant funding, while large-cap pharmaceutical sponsors prioritize supply security over unit cost.
Supply Chain Analysis
Donor tissue sourcing rests on FDA-registered establishments concentrated in the United States, with Canadian biologics and genetic therapies directorate rules creating parallel compliance tracks for cross-border operators. Critical inputs span defined media formulations, recombinant growth factors, and xeno-free matrices from specialized chemical suppliers. Single-source vulnerability runs through qualified cord blood bank networks where donor screening capacity lags demand growth. Distribution runs through direct manufacturer relationships with pharmaceutical sponsors and contract research organization intermediaries serving academic institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America stem cell market functions as a geographic-arbitrage play where Health Canada dual-compliance costs deter US operators from northern expansion while Mexican clinical trial infrastructure offers cost-advantaged patient recruitment.
For Market Incumbents: Cement supply chain control through captive sourcing agreements with FDA-registered tissue establishments and backward integration into GMP facility infrastructure. Thermo Fisher Scientific and Becton Dickinson anchor positions through integrated instrument-consumable portfolios that raise switching costs for pharmaceutical clients. Threat of automated closed-system bioreactor displacement demands continuous R&D investment in perfusion control technologies. Certification investment in ISO 20399 standards creates first-mover advantages as ancillary material requirements harmonize. For New Entrants and Emerging Players: The gap between premium clinical-grade and economy research-grade pricing creates entry space for mid-tier GMP-compatible iPSC suppliers targeting Series B-stage biotech firms. Texas Medical Center expansion offers underutilized late-stage clinical trial capacity where sponsor demand exceeds local service provision. AI-driven cell characterization capabilities present the most penetrable technology wedge, with machine learning potency assay development remaining fragmented among boutique analytics providers. Go-to-market positioning should emphasize rapid GMP protocol validation against autologous manufacturing timelines. For Investors and Strategic Acquirers: Roll-up economics work for allogeneic manufacturing specialists because standardized cell bank production enables batch economics that autologous approaches cannot replicate, creating scalable platform value. Five-to-ten year viability hinges on FDA RMAT designation pipeline maturation and genome-edited product approval precedents. Acquisition targets should display dedicated genome integrity assessment capabilities and established FDA pre-submission meeting histories. Watch FDA guidance finalization on off-target analysis protocols as the critical inflection signal for CRISPR-modified pipeline valuations.| Strategic Initiative | Industry Significance |
|---|---|
| RMAT Designation Pursuit | FDA's streamlined review pathway accelerates commercialization timelines for qualifying regenerative medicine products. |
| Allogeneic Cell Bank Scale-Up | Standardized batch production reduces per-dose costs below patient-specific autologous manufacturing approaches. |
| ISO 20399 Certification Investment | Early ancillary material standardization compliance creates preferred supplier status with consolidated pharmaceutical procurement. |
| AI-Driven Potency Assay Development | Machine learning integration with flow cytometry platforms compresses characterization timelines for IND submissions. |
| Texas Medical Center Partnership | Houston's underutilized clinical trial infrastructure offers late-stage study capacity for regenerative medicine sponsors. |
Research Methodology
Bottom-up end-user modeling reconciled against top-down supply-side tracking forms the analytical core, combining primary interviews with cell therapy manufacturing executives, regulatory affairs leads at pharmaceutical sponsors, GMP facility operators, and hospital procurement managers with secondary validation. FDA filings, Health Canada biologics submissions, ClinicalTrials.gov records, and ISO certification databases anchor quantitative segmentation. Cross-reference against SEC 10-K disclosures from listed life science conglomerates and venture financing databases for private biotech firms ensures revenue estimate calibration.
Input-output matrices map stem cell procurement flows across product type, application, end user, and technology segments throughout the forecast period. Modeled dimensions span adult versus pluripotent stem cell sourcing, regenerative medicine versus drug development application maturity, pharmaceutical company versus research institution customer type, and bioreactor versus planar culture technology adoption. CAGRs derive from regression analysis of historical procurement volume against FDA approval pathway timelines and GMP facility capacity expansion announcements. Forecast inputs incorporate RMAT designation success rates and genome-edited product guidance evolution.
Caveats apply where FDA guidance finalization on genome-edited stem cell products or Health Canada-US harmonization pressures could materially shift the outlook. Donor material scarcity at qualified tissue establishments and GMP-trained workforce availability present specific revision triggers for capacity expansion assumptions. A small set of regulatory guidance, certification standard adoption, and clinical trial readout triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Viral Vector and Plasmid DNA Manufacturing Market
Cell & Gene Therapy
Regenerative Therapies Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Viral Vector Development Market
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
Cell Reprogramming Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Cell Therapy Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Mesenchymal Stem Cells Market