
 Biological Drugs Market | 2026-2036
Biological Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Biological Drugs Market Intelligence
The bundling of companion diagnostics with targeted monoclonal antibodies is recalibrating buyer choice toward integrated treatment solutions. This shift favors companies with diverse portfolios. F. Hoffmann-La Roche Ltd leverages its diagnostics and pharma divisions to lead in personalized oncology. Amgen sustains its market position through large-scale manufacturing capabilities for complex biologics. AbbVie dominates the immunology space with its established product lines.
Biological drugs are large-molecule therapeutics derived from living organisms, such as mammalian cell cultures. Produced via complex bioprocessing techniques like recombinant DNA technology, their primary purpose is to treat diseases with high specificity. Monoclonal antibodies represent the largest product type, valued for their precise targeting of disease pathways. Gene therapies are the fastest-growing category, driven by advances in treating rare genetic disorders.
Regulatory oversight from bodies like the US FDA, the European Medicines Agency (EMA), and Japan's PMDA is stringent. These agencies mandate rigorous proof of efficacy, safety, and manufacturing consistency for market approval. Navigating the evolving patent landscape and managing the lifecycle of blockbuster drugs against emerging biosimilar competition remain critical strategic challenges for incumbents.
Market Dynamics
The convergence of advanced bioprocessing and genomics is the central structural force shaping the biological drugs market. This enables the development of highly targeted therapies, shifting the industry's focus from broad-spectrum treatments toward personalized medicine for specific genetic markers.
Growth Catalysts
- Favorable Regulatory Pathways:The EMA's PRIME scheme and the FDA's accelerated approval pathway expedite market access for innovative biologics, particularly in oncology and rare diseases, by shortening review timelines for promising therapies.
- Bioprocessing Advances:Improvements in recombinant DNA technology and high-density mammalian cell culture systems enhance manufacturing yields and product consistency, making complex biologics like monoclonal antibodies more commercially viable.
- Demographic Shifts:Aging populations in developed nations such as Germany and Japan are increasing the prevalence of chronic conditions like rheumatoid arthritis and cancer, driving sustained demand for effective biologic treatments.
Market Restraints
- High Manufacturing Costs:The substantial expense of bioprocessing, including specialized cell culture media and complex purification chromatography, creates high barriers to entry and limits affordability in markets lacking robust reimbursement structures.
- Supply Chain Concentration:Heavy reliance on a small number of specialized contract development and manufacturing organizations (CDMOs) for cell therapy production creates potential bottlenecks and supply chain vulnerabilities.
- Inherent Immunogenicity:The potential for some large-molecule drugs to trigger an immune response in patients can limit long-term efficacy and necessitate extensive, costly post-market safety monitoring to manage adverse events.
Strategic Opportunities
- Emerging Market Expansion:Underpenetrated markets in Latin America and Southeast Asia offer significant growth potential as healthcare spending increases and regulatory bodies like Brazil's ANVISA align their guidelines with international standards.
- New Therapeutic Platforms:The application of mRNA technology beyond vaccines into therapeutics for oncology and autoimmune disorders presents a major opportunity for creating versatile, platform-based drug development pipelines.
- AI in Drug Discovery:Integrating artificial intelligence with high-throughput screening can accelerate the identification of novel biologic targets and predict clinical trial outcomes, significantly shortening the R&D cycle.
Industry Challenges
- Specialized Talent Scarcity:A shortage of skilled bioprocess engineers and computational biologists with expertise in bioinformatics creates a critical talent bottleneck, slowing both process development and manufacturing scale-up activities.
- Intellectual Property Disputes:Navigating the dense and overlapping patent landscape surrounding foundational technologies like CRISPR and blockbuster monoclonal antibodies frequently leads to complex and costly litigation.
- Manufacturing Scale-Up Complexity:The transition from clinical-scale to commercial-scale production for autologous cell therapies poses immense logistical and technical challenges, especially in ensuring batch-to-batch consistency and chain of custody.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biological Drugs Market |
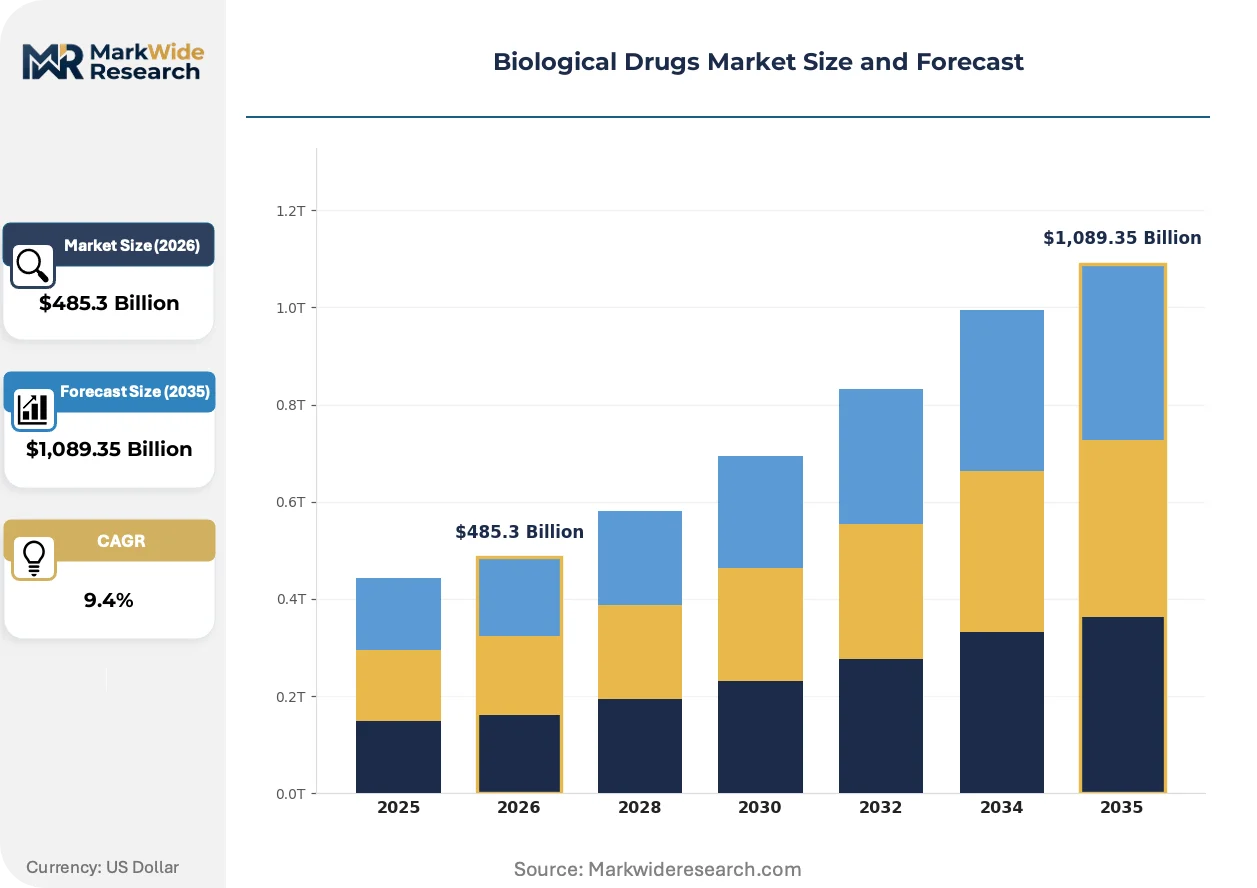
| Market Size in 2026 | $485.3 Billion |
| Market Size in 2035 | $1,089.35 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Recombinant Proteins, Gene Therapies, Fusion Proteins Application Area: Oncology, Immunology, Rare Diseases, Infectious Diseases, Endocrinology End User: Hospitals, Specialty Clinics, Research Laboratories, Contract Research Organizations, Diagnostic Centers Delivery Technology: Subcutaneous Injection, Intravenous Infusion, Intramuscular Injection, Nasal Spray, Oral Delivery |
| Companies Covered | AbbVie, Amgen, Eli Lilly and Company, F. Hoffmann-La Roche Ltd, Novartis AG, Pfizer Inc, Johnson & Johnson, Sanofi, Celltrion, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biological Drugs Market Strategic Shifts & Innovations
The expansion of platform technologies is fundamentally altering the development and application of biological drugs. This shift moves the industry away from single-product pipelines toward versatile systems capable of addressing multiple diseases with greater speed and efficiency.
Cell-free protein synthesis provides a rapid method for producing biologics without the constraints of living cells. Pharmaceutical developers focused on oncology and infectious disease are adopting this technology to accelerate preclinical candidate screening. This innovation is rewriting the economics of early-stage drug discovery by decoupling protein production from the time-consuming complexities of cell culture.
Harmonization efforts, guided by bodies like the International Council for Harmonisation (ICH), are streamlining clinical trial data requirements across major markets. This reduces duplicative testing for drug developers seeking simultaneous approval from the FDA, EMA, and Japan's PMDA. The biosimilar segment is most affected, as a unified evidence standard accelerates market entry and intensifies competition.
Patient-centric logistics models are gaining traction for advanced cell and gene therapies. This disrupts the traditional centralized hospital distribution network by enabling administration at local infusion centers or even a patient's home. The shift is most visible in the United States for treating rare genetic disorders, where it reduces the significant travel and time burden on patients and their families.
Biological Drugs Market Segmentation
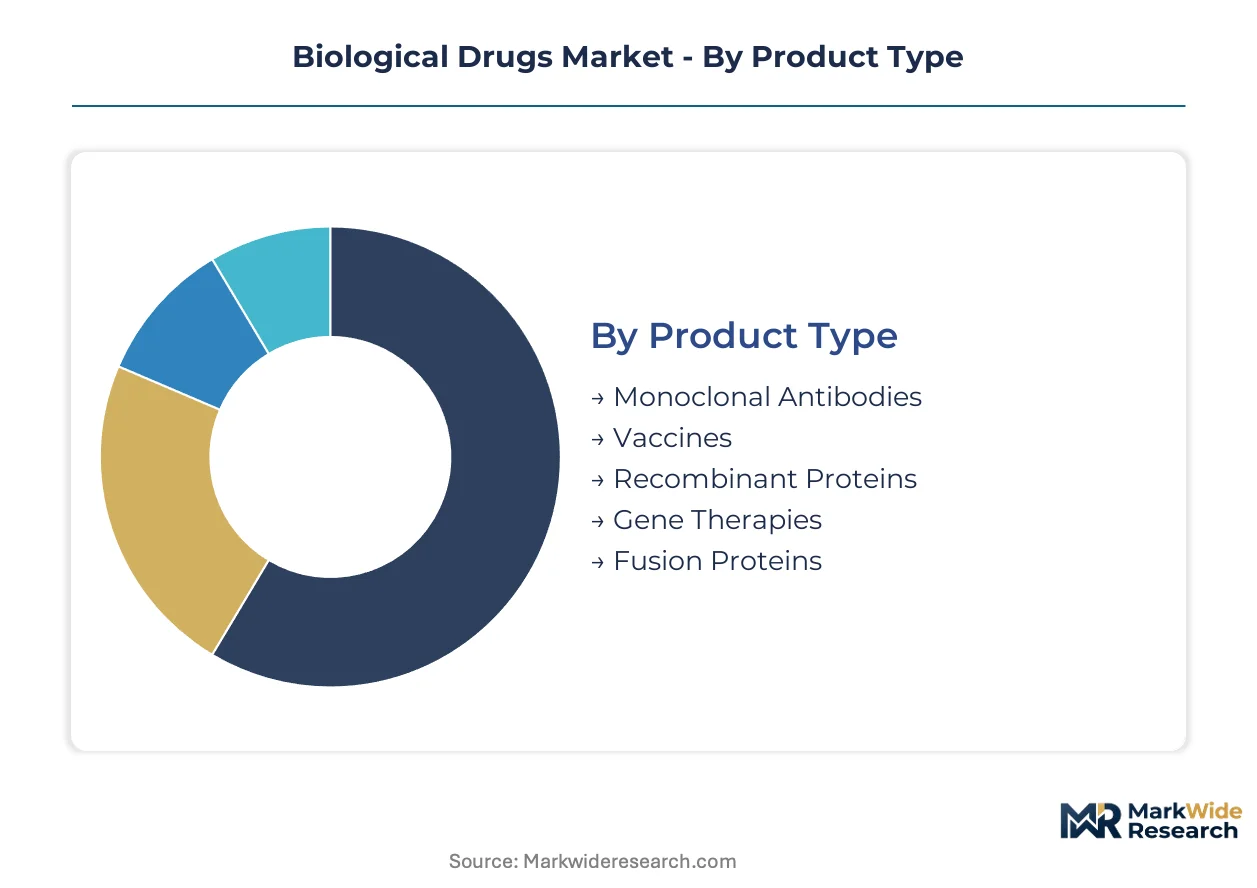
Understanding the distinct segments within the biological drugs market is crucial for strategic resource allocation and targeted product development. Each category reflects unique technological approaches, therapeutic applications, and patient administration pathways, shaping competitive dynamics and investment priorities across the industry.
Product Type:
The product type segmentation highlights the spectrum from highly standardized, broadly applicable biologics to increasingly customized, patient-specific therapies.
- Monoclonal Antibodies:These large-molecule proteins are engineered to bind specifically to target antigens on cells, neutralizing pathogens or modulating immune responses. Demand concentrates in oncology and immunology, driven by their precise targeting of disease pathways.
- Gene Therapies:These advanced biologics introduce genetic material into a patient's cells to treat or prevent disease, often addressing the root cause of genetic disorders. Demand is particularly strong for rare genetic disorders, propelled by significant scientific breakthroughs and regulatory support.
- Vaccines:Biological preparations stimulate the immune system to provide acquired immunity against infectious diseases, preventing future infections.
- Recombinant Proteins:Proteins produced through genetic engineering, such as insulin or growth hormones, replace deficient natural proteins or provide therapeutic effects.
- Fusion Proteins:These engineered proteins combine functional domains from two or more distinct proteins, often enhancing therapeutic efficacy or pharmacokinetic properties.
Most installed capacity flows through Monoclonal Antibodies. Expansion is steepest in Gene Therapies.
Application Area:
The application area segmentation delineates the primary therapeutic targets, reflecting the diverse disease burdens addressed by biological drugs.
- Oncology:This segment encompasses biologics used to treat various forms of cancer, including solid tumors and hematological malignancies, often through targeted cell destruction or immune modulation. Demand is robust in the United States and Germany, supported by high cancer prevalence and advanced treatment infrastructure.
- Immunology:Biologics in this category manage immune-mediated inflammatory diseases such as rheumatoid arthritis, Crohn's disease, and psoriasis by modulating the immune system. AbbVie maintains a strong market position here with its established product lines addressing chronic conditions.
- Rare Diseases:This segment focuses on therapies for conditions affecting a small percentage of the population, often genetic in origin, where conventional treatments are limited.
- Infectious Diseases:Biologics here target pathogens like viruses and bacteria, including vaccines and antibody therapies, to prevent or treat infections.
- Endocrinology:This area includes biological drugs for hormonal disorders, such as diabetes (insulin) and growth hormone deficiencies.
Oncology applications command the largest share of market value. Rare Diseases exhibit the fastest growth trajectory.
End User:
The end user segmentation reflects where biological drugs are primarily administered and utilized, highlighting the diverse points of care and research within the healthcare ecosystem.
- Hospitals:These institutions serve as primary sites for administering complex biological drugs, particularly those requiring close medical supervision, specialized equipment, or inpatient care. Hospitals handle a high volume of intravenous infusions for acute and severe conditions.
- Specialty Clinics:These outpatient facilities focus on specific disease areas, offering specialized care and administering biologics for chronic conditions or complex treatments. Patient-centric logistics models are increasingly enabling administration at these local centers, reducing patient travel burden.
- Research Laboratories:These entities conduct fundamental and applied research into biological mechanisms, drug discovery, and preclinical development of novel biologics.
- Contract Research Organizations:CROs provide outsourced research and development services to pharmaceutical and biotechnology companies, including clinical trial management and regulatory support for biologics.
- Diagnostic Centers:These facilities perform diagnostic tests, including companion diagnostics bundled with targeted monoclonal antibodies, to guide treatment decisions for personalized medicine.
Hospitals represent the largest end-user segment for biological drug administration. Specialty Clinics are gaining share due to evolving patient care models.
Delivery Technology:
The delivery technology segmentation categorizes how biological drugs are administered to patients, ranging from traditional injection methods to emerging, less invasive approaches.
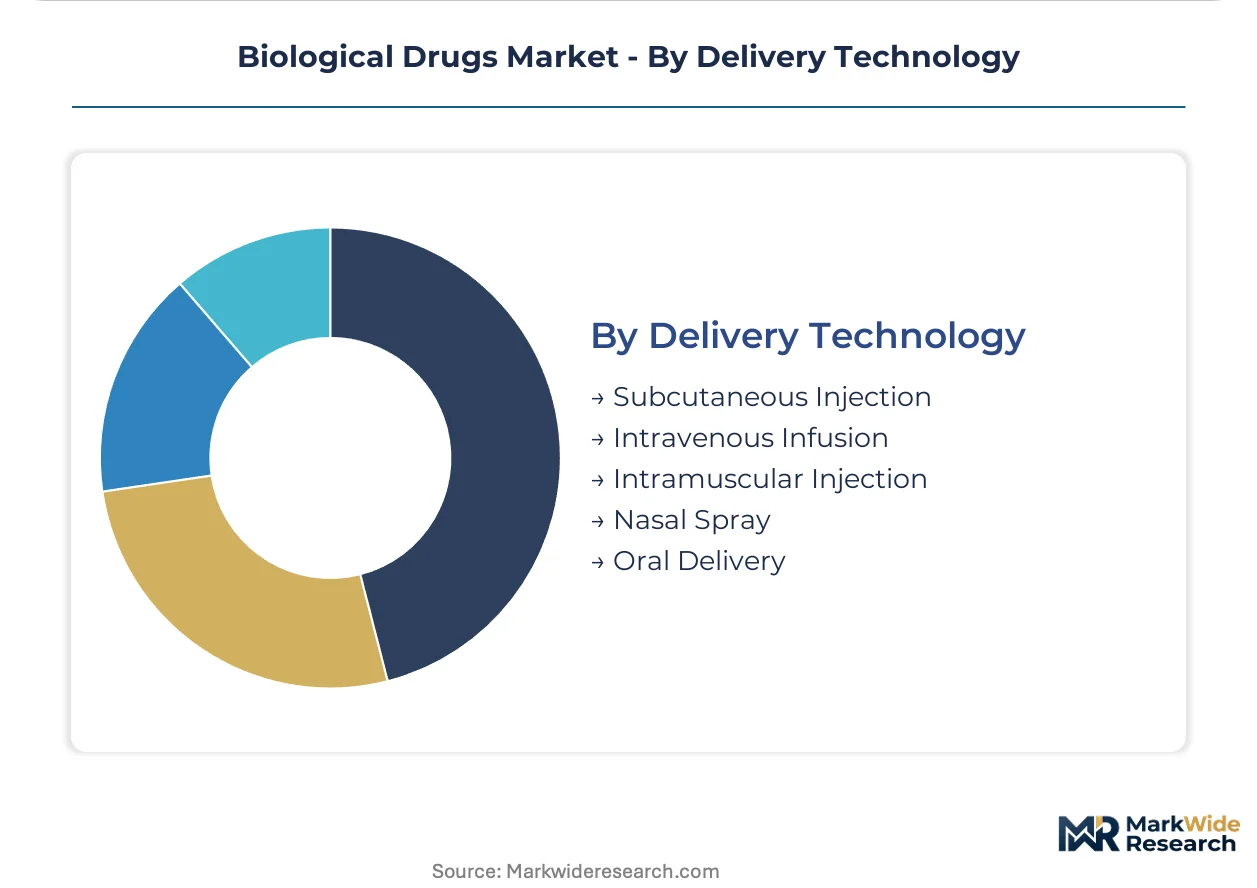
- Subcutaneous Injection:This method involves injecting the drug into the fatty tissue beneath the skin, often allowing for self-administration and greater patient convenience for chronic conditions. Demand is rising for biologics that can be safely and effectively delivered this way, improving patient adherence.
- Intravenous Infusion:This technique delivers the drug directly into a vein, ensuring rapid and complete bioavailability, often used for high-dose or complex biologics requiring controlled administration. Hospitals remain central to managing these infusions for acute and severe conditions.
- Intramuscular Injection:This delivery route involves injecting the drug into a muscle, typically for vaccines or certain long-acting biologics.
- Nasal Spray:This non-invasive method delivers drugs through the nasal mucosa, offering a systemic effect or local action in the respiratory tract.
- Oral Delivery:This highly convenient, non-invasive route involves taking the drug by mouth, though it presents significant challenges for large-molecule biologics due to gastrointestinal degradation and poor absorption.
Intravenous Infusion remains the dominant delivery method for many complex biologics. Subcutaneous Injection is expanding rapidly due to patient preference and self-administration capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The genesis and subsequent scaling of biological drug development found its earliest footing in nations with robust biomedical research ecosystems. These pioneering regions continue to drive innovation and demand for advanced therapies, particularly in complex disease areas. Regulatory support and significant R&D investment underpin their market leadership.
United States
Demand for biological drugs in the United States stems from high cancer prevalence and advanced healthcare. The FDA's accelerated approval pathway expedites market entry for novel biologics. The Boston-Cambridge biotech hub remains a global epicenter for biopharmaceutical innovation.
Germany
Germany exhibits strong demand for biological treatments due to its aging demographic and R&D investment. The EMA's PRIME scheme accelerates access for promising medicines. Biopharma clusters in Munich and Frankfurt drive complex biologics manufacturing and clinical research.
Japan
Japan's aging population creates sustained demand for biological drugs, especially for chronic and rare conditions. The PMDA's robust framework ensures stringent quality and safety. Pharmaceutical centers in Tokyo and Osaka drive advanced research into gene and monoclonal antibody therapies.
Switzerland
Switzerland sustains high demand for biologics, fueled by elevated per capita healthcare spending and innovation. Swissmedic provides comprehensive regulatory oversight for drug development. The Basel region serves as a global pharmaceutical R&D hub, attracting significant investment.
China
China's expanding healthcare access and chronic disease burden drive significant demand for biological drugs. The NMPA has streamlined approval processes for innovative biologics. Biopharmaceutical parks in the Yangtze River Delta and Beijing rapidly scale manufacturing and R&D capabilities.
Biological Drugs Market Key Industry Players
Premium-margin players sit above commodity-margin players across the drug development lifecycle, reflecting varying levels of R&D intensity and manufacturing complexity. The market structure is moderately consolidated, with a few large pharmaceutical companies holding significant shares in key therapeutic areas. Strategic archetypes include integrated biopharma giants, specialized biotech innovators, and contract manufacturing organizations. Dominant competitive moves involve portfolio diversification into novel therapeutic platforms and strategic partnerships for co-development.
Within the integrated biopharma giant archetype, F. Hoffmann-La Roche Ltd, a Swiss-based multinational, exemplifies leadership in personalized oncology. US-based Amgen occupies a strong position through its large-scale biomanufacturing capabilities for complex biologics. AbbVie, another US-based pharmaceutical company, anchors the immunology space with its established product lines, demonstrating market stability through long-standing therapeutic solutions. These entities represent the diverse strategies employed by major players to sustain market presence and drive innovation across the biological drugs landscape.
| Leading Market Players |
|---|
| AbbVie |
| Amgen |
| Eli Lilly and Company |
| F. Hoffmann-La Roche Ltd |
| Novartis AG |
| Pfizer Inc |
| Johnson & Johnson |
| Sanofi |
| Celltrion |
| Others |
Cost & Logistics Intelligence
Integrated biopharma giants, often publicly traded, dictate significant pricing power through their extensive R&D investments and established market presence. Their strategic decisions directly influence supply chain resilience and cost structures across the biological drugs market.
Pricing Analysis
Value-based pricing models increasingly dominate the biological drugs market, reflecting the high clinical efficacy and specificity of novel therapies. Price differentiation stems from factors like demonstrated patient outcomes and market exclusivity periods for patented biologics. Pricing softness runs through established monoclonal antibody segments due to intensifying biosimilar competition, particularly in Europe. Hospitals and public payers exhibit high price sensitivity, while patients with rare diseases often face limited alternatives.
Supply Chain Analysis
Skilled bioprocess engineering talent availability in manufacturing hubs like the United States, Germany, and Switzerland critically influences the biological drugs supply chain. This chain relies heavily on specialized cell culture media and complex purification chromatography resins. Supply chain vulnerability stems from heavy reliance on a small number of specialized contract development and manufacturing organizations (CDMOs). Distribution runs through a hybrid model, combining direct hospital delivery for complex infusions with specialized third-party logistics for patient-centric home administration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biological drugs market presents a geographic-arbitrage opportunity, particularly given the cost differential in manufacturing complex biologics between established Western markets and emerging Asian biopharmaceutical hubs. Companies can optimize production footprints.
For Market Incumbents: Lock in long-term supply agreements for critical raw materials to mitigate supply chain volatility and ensure consistent production. Diversify product pipelines into emerging therapeutic platforms like mRNA technology to counter biosimilar erosion in established monoclonal antibody markets. Invest in advanced bioprocessing technologies to enhance manufacturing yields. This proactive stance protects against intellectual property disputes and talent scarcity.
For New Entrants and Emerging Players: A significant price-point gap exists between premium patented biologics and more affordable biosimilar versions, creating market entry opportunities. Target underpenetrated markets in Southeast Asia and Latin America with cost-effective biosimilars for immunology and oncology applications. Focus on developing platform technologies for rapid iteration and regulatory alignment with ANVISA for expedited market access. This strategy leverages increasing healthcare spending and harmonized guidelines.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap biotechs specializing in novel gene therapy platforms or advanced bioprocessing solutions. The long-term viability of the biological drugs market remains robust, driven by unmet medical needs in chronic and rare diseases. Target companies with strong intellectual property portfolios and demonstrated clinical trial success in oncology or rare genetic disorders. The signal to watch is the successful commercialization of cell and gene therapies beyond initial niche indications.
| Strategic Initiative | Industry Significance |
|---|---|
| Pipeline Diversification | Expands market reach into new therapeutic areas, reducing reliance on single blockbuster drugs. |
| Bioprocessing Technology Upgrade | Enhances manufacturing efficiency and product consistency for complex large-molecule biologics. |
| Regulatory Approval Pathway Acceleration | Expedites market access for innovative therapies through FDA and EMA fast-track schemes. |
| Strategic Partnerships for Co-development | Leverages external expertise and shares R&D costs for novel gene therapies. |
| Emerging Market Expansion | Captures new patient populations and revenue streams in regions like Latin America. |
Research Approach
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided primary insights into market dynamics. This qualitative data was triangulated with extensive secondary research from sources like FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. A rigorous bottom-up and top-down approach ensured comprehensive market sizing and validation across all segments.
A multi-layered analytical framework, combining bottom-up market sizing with top-down validation, projected market evolution across the analysis window. Segmentation dimensions modeled included product type, application area, end user, delivery technology, and regional regulatory clusters. Compound annual growth rates were derived from historical trends, projected clinical pipeline advancements, and anticipated regulatory approvals. Key inputs included R&D investment trends and biosimilar market penetration rates.
Caveats apply where unforeseen clinical trial failures or major shifts in reimbursement policies could materially shift the outlook. Forecasts reflect documented assumptions regarding technological advancements and regulatory stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
Human Immunodeficiency Virus (HIV) Drugs Market
Biopharmaceuticals
Human Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Human Insulin Drugs Market
Biopharmaceuticals
Rapid Acting Insulin Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Heparin API Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Human Insulin Market
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Russia Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
PCSK9 Inhibitors Market
Biopharmaceuticals
North America Contraceptives Market
Biopharmaceuticals
Glycosylated Peptide Market
Biopharmaceuticals
Echinocandins Market