
 Stem Cell Reconstructive Market | 2026-2036
Stem Cell Reconstructive Market Size, Share, and Industry Trends Forecast 2026-2036
Stem Cell Reconstructive Market Outlook
GMP-grade manufacturing standards is bifurcating the Stem Cell Reconstructive market into contract-manufactured and in-house production tiers. Mesoblast leverages its proprietary allogeneic platform to dominate commercial-scale cell therapy supply. Vericel Corporation anchors the autologous segment through its cartilage repair specialization in orthopedic applications. Smith+Nephew competes across wound care and sports medicine channels with integrated biologics portfolios.
Stem Cell Reconstructive therapies deploy living cellular material, typically mesenchymal stromal cells cultured under serum-free conditions at controlled oxygen tension, to regenerate damaged tissue matrices in bone, cartilage, and soft tissue defects. Orthopedics leads application demand where intra-articular delivery of expanded chondrocytes addresses osteochondral lesions unresponsive to microfracture. Mesenchymal cell types capture the dominant share of active clinical programs due to their immunomodulatory profile and established isolation protocols from bone marrow and adipose tissue. Delivery mode selection increasingly stratifies by tissue target, with local injection dominating superficial defects and intravenous routes expanding in systemic inflammatory conditions.
The FDA's regenerative medicine advanced therapy designation and the EU's MDR framework collectively shape trial design, manufacturing compliance, and reimbursement pathways across the United States and European markets. Health Canada's cellular therapy guidance and Japan's PMDA conditional approval framework add further jurisdictional complexity for multi-region sponsors. China's NMPA biologics licensing requirements and India's CDSCO stem cell guidelines create additional regulatory checkpoints for market entry. Stakeholders must monitor evolving GMP inspection harmonization between FDA and EMA to anticipate supply chain qualification costs and timeline risks.
Market Dynamics
GMP-grade manufacturing standards are bifurcating the Stem Cell Reconstructive market into contract-manufactured and in-house production tiers, forcing sponsors to commit capital to dedicated cleanroom infrastructure or surrender margin to specialized CDMOs.
Growth Catalysts
- FDA's regenerative medicine advanced therapy designation:This framework compresses clinical trial timelines and accelerates priority review pathways for qualifying cell therapies in the United States.
- Orthopedic trauma centers:These facilities are expanding autologous stem cell protocols for cartilage regeneration, embedding cellular therapies into standard surgical workflows for osteochondral defects.
- Adipose-derived protocols:German university hospitals have integrated these harvesting and expansion methods into reconstructive surgery departments, validating standardized processing for soft tissue applications.
Market Restraints
- Serum-free media costs:The shift from fetal bovine serum to defined, xeno-free culture media has tripled raw material input costs for mesenchymal stromal cell expansion.
- EMA-FDA GMP inspection divergence:Non-harmonized facility qualification standards force dual-track compliance investments, extending supply chain qualification timelines for multi-region sponsors.
- Microfracture persistence:This established bone marrow stimulation technique retains strong payer preference and surgeon familiarity for small osteochondral lesions, limiting addressable patient pools.
Strategic Opportunities
- Systemic inflammatory conditions:Intravenous delivery routes for mesenchymal stromal cells are expanding beyond local orthopedic injection into Crohn's disease and graft-versus-host disease applications.
- Japan's PMDA conditional approval framework:This pathway permits early commercialization with post-market efficacy confirmation, reducing capital-at-risk for novel allogeneic platforms.
- Wound care biologics integration:Diabetic foot ulcer and burn centers present underpenetrated channels where living cellular matrices displace acellular skin substitutes.
Industry Challenges
- Cellular therapy manufacturing technicians:The specialized workforce required for aseptic processing, in-process testing, and closed-system bioreactor operation commands premium compensation and experiences high turnover.
- ISO 14644 cleanroom capex:Grade B manufacturing suites with isolator technology require substantial upfront investment, compressing returns for mid-scale autologous operators.
- Intellectual property thickets:Overlapping patent estates covering mesenchymal stromal cell isolation methods, expansion media formulations, and delivery devices complicate freedom-to-operate assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stem Cell Reconstructive Market |
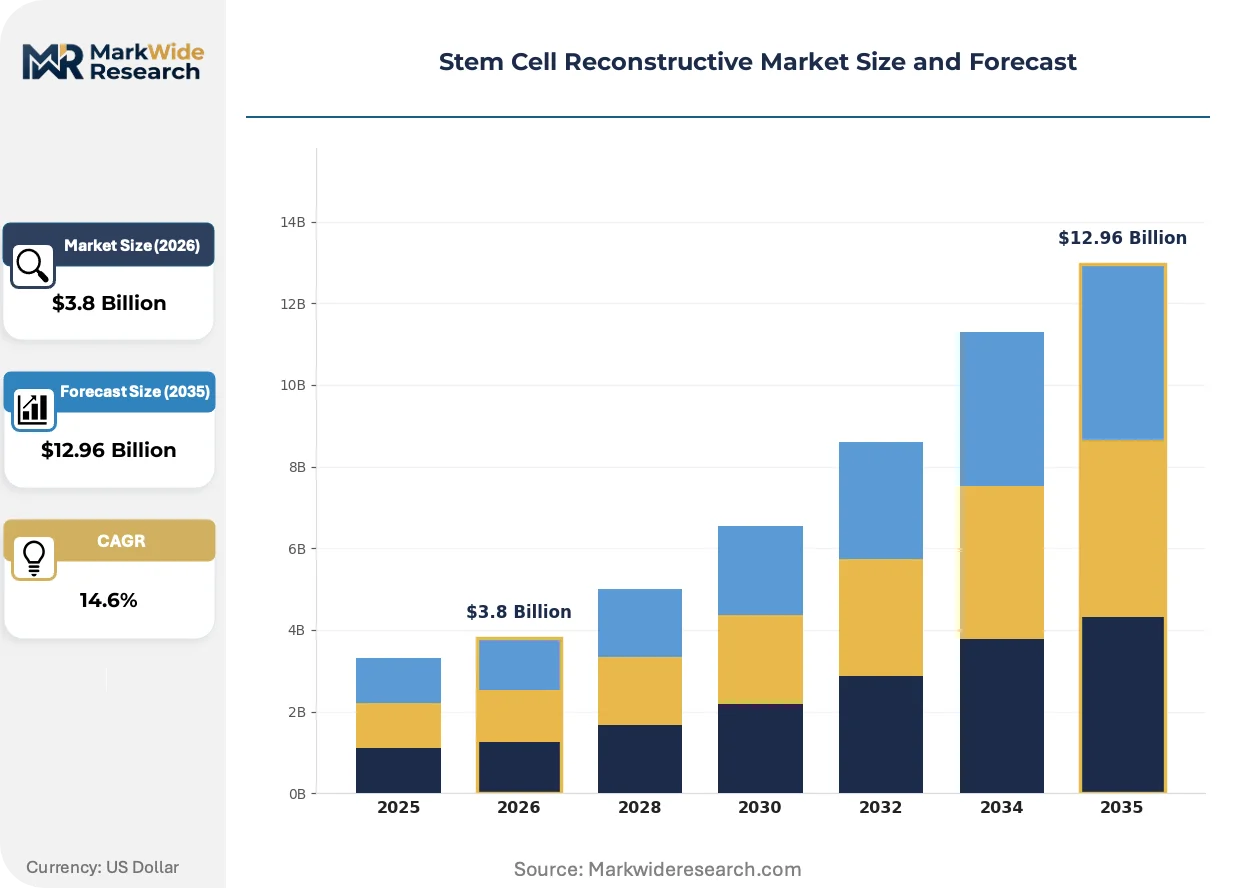
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Orthopedics, Cardiology, Neurology, Cosmetic Surgery Delivery Mode: Intravenous, Intra-articular, Subcutaneous, Local Injection Cell Type: Mesenchymal, Hematopoietic, Pluripotent, Adipose-Derived End User: Hospitals, Research Institutes, Specialty Clinics, Surgical Centers |
| Companies Covered | Mesoblast, Vericel Corporation, Athersys, Osiris Therapeutics, MEDIPOST, Smith+Nephew, Thermo Fisher Scientific, Cynata Therapeutics, Cellular Biomedicine Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stem Cell Reconstructive Market Strategic Shifts
Manufacturing automation and closed-system bioprocessing are displacing manual open-culture methods, while regulatory science advances are compressing the evidence-generation timeline for novel cellular constructs.
Serum-free, chemically defined expansion media is bifurcating the supplier landscape between legacy fetal bovine serum vendors and synthetic formulation specialists. Academic research groups and early-stage biotechs are adopting defined media rapidly to satisfy journal and investor scrutiny. This transition is compressing the addressable market for animal-derived reagents while elevating process consistency and regulatory defensibility for sponsors pursuing BLA submissions.
The EU's Medical Device Regulation (MDR) is reclassifying combination products incorporating viable cells, forcing sponsors to generate clinical evidence under notified body supervision rather than competent authority review. This industrial consequence extends development timelines and increases documentation burdens for wound care and orthopedic matrices. German and French sponsors are responding by front-loading clinical trials and engaging notified bodies earlier in design dossier preparation.
Hospital procurement committees are consolidating vendor relationships for advanced therapy medicinal products, replacing fragmented physician-driven purchasing with centralized value analysis frameworks. Integrated delivery networks in the United States are negotiating multi-year supply agreements that bundle cellular therapy with supporting surgical hardware and post-operative monitoring. This concentration is most visible in academic medical centers where orthopedic and plastic surgery departments coordinate joint sourcing decisions.
Stem Cell Reconstructive Market Segmentation
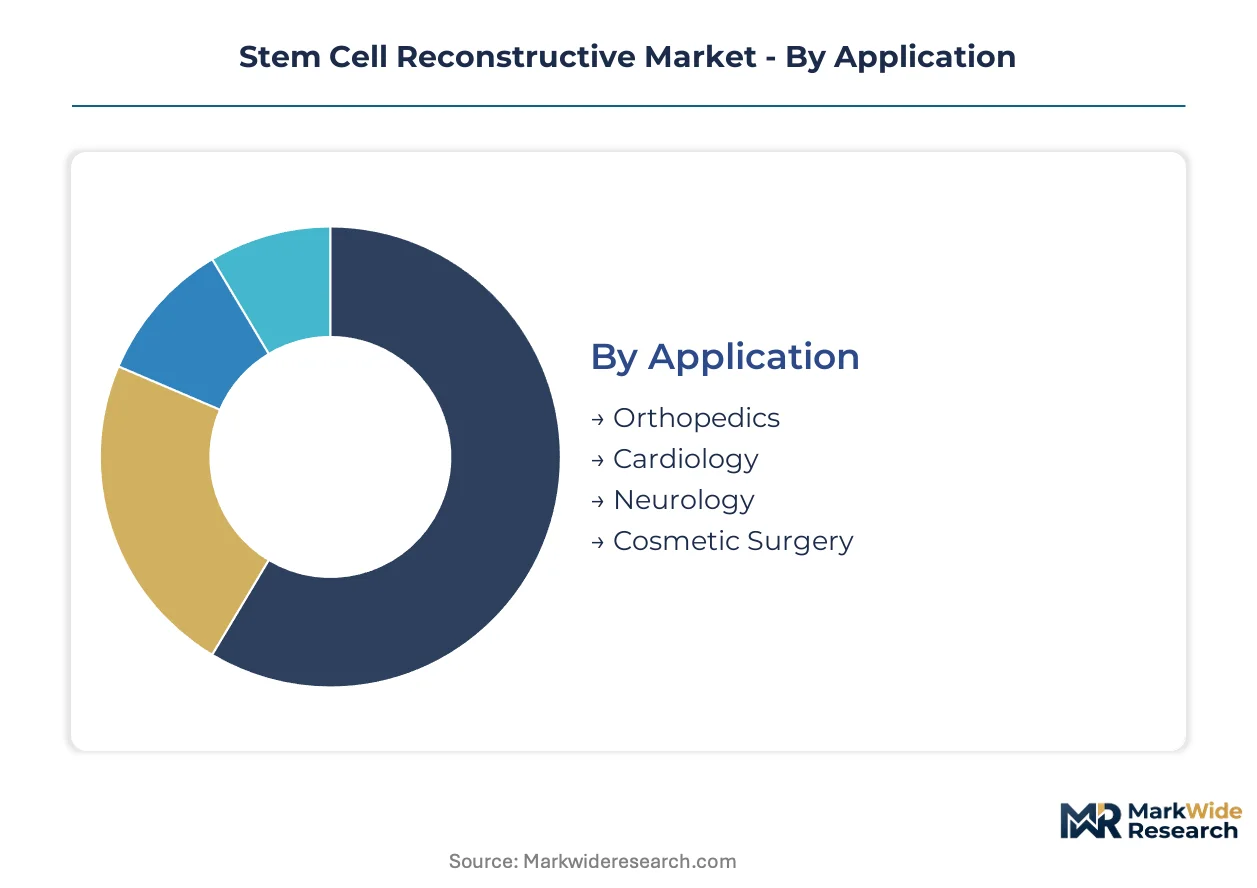
Segmentation in the Stem Cell Reconstructive market determines manufacturing scale, regulatory pathway, and reimbursement strategy. Orthopedic applications demand localized delivery infrastructure distinct from systemic cardiology protocols.
Application:
Channel distribution varies sharply: orthopedics flows through hospital surgical suites and ambulatory surgery centers, while cosmetic surgery concentrates in private clinic networks with direct-pay models.
- Orthopedics:Intra-articular delivery of expanded chondrocytes targets osteochondral lesions in trauma centers and sports medicine departments. German university hospitals have embedded autologous protocols into standard cartilage repair workflows, validating serum-free expansion methods.
- Cardiology:Intravenous and intracoronary routes deploy mesenchymal stromal cells for ischemic tissue repair. Clinical demand clusters in United States academic medical centers pursuing FDA regenerative medicine advanced therapy designation for priority review pathways.
- Neurology:Intrathecal and intracerebral delivery approaches address spinal cord injury and neurodegenerative conditions.
- Cosmetic Surgery:Adipose-derived protocols dominate facial rejuvenation and soft tissue augmentation through outpatient clinic channels.
Orthopedics dominates installed base. Cosmetic Surgery is where expansion concentrates.
Delivery Mode:
Cost tier stratification separates premium catheter-guided delivery from standard injection protocols, with reimbursement rates scaling to procedural complexity.
- Intravenous:Systemic administration of allogeneic mesenchymal stromal cells targets graft-versus-host disease and Crohn's disease. Japan's PMDA conditional approval framework accelerates commercialization for novel intravenous platforms.
- Intra-articular:Direct joint injection of expanded chondrocytes and stromal cells addresses cartilage defects. Orthopedic trauma centers in the United States have standardized this delivery for lesions unresponsive to microfracture.
- Subcutaneous:Depot formation enables sustained release in wound care and soft tissue applications.
- Local Injection:Superficial delivery targets diabetic foot ulcers and burn reconstruction with minimal instrumentation.
Intra-articular commands the highest procedure volume. Intravenous is climbing the fastest toward systemic inflammatory indications.
Cell Type:
Application focus determines sourcing strategy: autologous harvests require patient-matched logistics while allogeneic platforms enable centralized manufacturing.
- Mesenchymal:Bone marrow and adipose-derived stromal cells offer established immunomodulatory profiles with serum-free expansion protocols. Demand concentrates in orthopedic and cardiology applications where immunoprivilege reduces rejection risk.
- Hematopoietic:CD34+ progenitor cells target vascular regeneration and blood disorder reconstruction.
- Pluripotent:Induced pluripotent stem cells enable directed differentiation toward specialized tissue lineages.
- Adipose-Derived:Lipoaspirate processing yields stromal vascular fraction for soft tissue and cosmetic applications.
Mesenchymal dominates installed base. Adipose-Derived is where expansion concentrates.
End User:
Customer type shapes procurement: integrated delivery networks negotiate bundled agreements while independent surgical centers prioritize per-procedure flexibility.
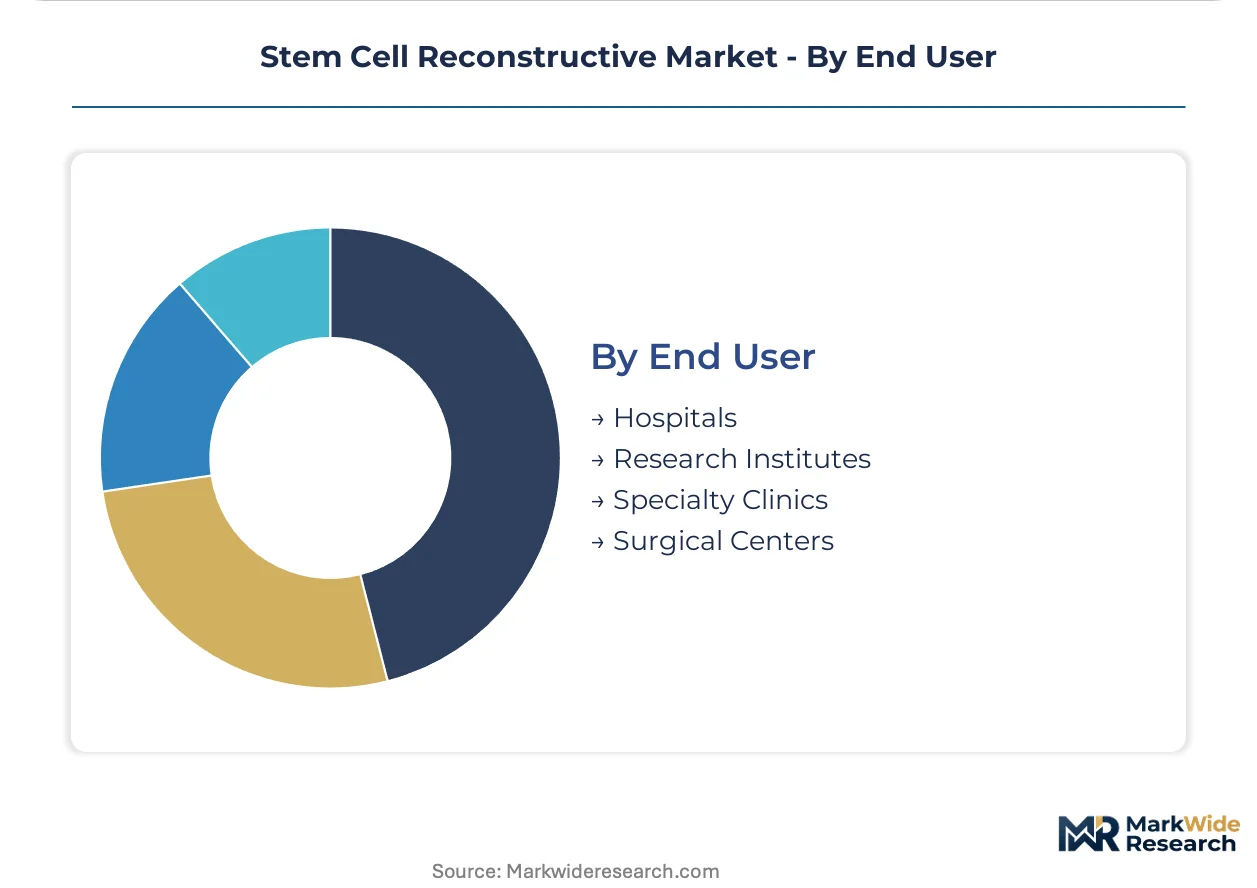
- Hospitals:Academic medical centers and community hospitals anchor demand through orthopedic, cardiology, and wound care departments. Centralized value analysis frameworks are replacing fragmented physician-driven purchasing for advanced therapy medicinal products.
- Research Institutes:Early-phase clinical trials and protocol development occur in university-affiliated facilities with GMP pilot suites.
- Specialty Clinics:Cosmetic and anti-aging centers operate on direct-pay models outside reimbursement systems.
- Surgical Centers:Ambulatory facilities concentrate same-day orthopedic and soft tissue procedures.
Hospitals dominate installed base. Specialty Clinics is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in stem cell reconstructive therapies favor net-importing jurisdictions with advanced hospital infrastructure over manufacturing hubs. Trade flows concentrate specialized cellular products toward clinical centers in high-income markets while raw biologics and processing equipment move in reverse.
United States
FDA's regenerative medicine advanced therapy designation compresses clinical trial timelines for qualifying cell therapies. Orthopedic trauma centers in Boston and Philadelphia have embedded autologous protocols into standard cartilage repair workflows. The National Institutes of Health funds mesenchymal stromal cell research through dedicated translational grants.
Germany
University hospitals in Berlin and Heidelberg integrate adipose-derived protocols into reconstructive surgery departments. The EU Medical Device Regulation reclassifies combination products with viable cells, extending documentation requirements for wound care matrices. EMA-FDA GMP inspection divergence forces dual-track compliance investments from multi-region sponsors.
Japan
PMDA's conditional approval framework permits early commercialization with post-market efficacy confirmation. Tokyo and Osaka academic medical centers anchor demand for intravenous mesenchymal stromal cell therapies in systemic inflammatory conditions. METI subsidizes closed-system bioprocessing equipment for domestic manufacturers.
China
NMPA biologics licensing requirements create additional regulatory checkpoints for imported cellular therapies. Shanghai and Beijing hospitals concentrate demand for orthopedic applications while Shenzhen biotech clusters develop allogeneic platform technologies. The country's dual carbon goals pressure serum-free media suppliers to reduce cold-chain energy intensity.
United Kingdom
London and Cambridge research institutes drive early-phase clinical trials with GMP pilot suites. The Medicines and Healthcare products Regulatory Agency aligns with EMA standards while maintaining independent facility inspection protocols. NHS procurement committees consolidate vendor relationships for advanced therapy medicinal products across orthopedic and wound care departments.
Stem Cell Reconstructive Market Competitive Environment
Concentration sits with allogeneic platform developers and autologous specialists serving distinct manufacturing scales. The market structure bifurcates between commercial-scale cell therapy suppliers and mid-scale operators serving regional hospital networks. Two strategic archetypes dominate: integrated biologics portfolios spanning wound care and sports medicine channels, and pure-play cellular therapy developers with proprietary expansion platforms. Competitive moves center on CDMO partnerships to avoid cleanroom capital expenditure and strategic positioning for FDA priority review pathways.
Among the named players, Mesoblast and Vericel Corporation exemplify the platform specialization archetype, with the former representing allogeneic commercial-scale supply and the latter anchoring autologous orthopedic applications. Athersys occupies a position within the intravenous systemic delivery segment. These three companies illustrate how manufacturing approach and delivery mode selection stratify competitive positioning in the reconstructive cellular therapy market.
| Leading Market Players |
|---|
| Mesoblast |
| Vericel Corporation |
| Athersys |
| Osiris Therapeutics |
| MEDIPOST |
| Smith+Nephew |
| Thermo Fisher Scientific |
| Cynata Therapeutics |
| Cellular Biomedicine Group |
| Others |
Value Chain & Pricing Dynamics
FDA's regenerative medicine advanced therapy designation gates both supply qualification and price differentiation, requiring sponsors to invest in GMP-grade cleanroom infrastructure before commanding premium reimbursement tiers for cellular therapies. Hospital procurement committees exploit this barrier to consolidate vendor relationships around qualified suppliers with validated manufacturing protocols.
Pricing Analysis
Academic medical center buyers anchor contract-based long-term offtake structures that bundle cellular therapy with surgical hardware and post-operative monitoring. Pricing stratifies across premium GMP-certified tiers, standard in-house production tiers, and economy contract-manufactured tiers based on certification level and volume scale. Cost compression in the standard tier is intensifying because serum-free media inputs have tripled raw material expenses. Independent surgical centers exhibit highest price sensitivity while integrated delivery networks negotiate least.
Supply Chain Analysis
Cold-chain logistics costs for viable cellular products draw from specialized courier networks and temperature-controlled transport infrastructure spanning United States, Germany, and Japan trade lanes. Raw material dependencies center on serum-free expansion media, closed-system bioreactors, and isolator-grade cleanroom equipment. Single-source vulnerability concentrates in qualified CDMO capacity for aseptic processing. Distribution runs through hospital central pharmacies and academic medical center value analysis frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Stem Cell Reconstructive market is entering a cyclical recovery phase as orthopedic trauma centers rebuild surgical volumes deferred during pandemic-period capacity constraints.
For Market Incumbents: Fortify manufacturing scale advantages through backward integration into serum-free media formulation to offset input cost inflation. Lock in multi-year supply agreements with integrated delivery networks before Japan's PMDA conditional approval framework accelerates competitor entry. Prioritize GMP inspection harmonization investments to reduce dual-track compliance costs across FDA and EMA jurisdictions. For New Entrants and Emerging Players: FDA's regenerative medicine advanced therapy designation offers a certification fast-track for qualifying allogeneic platforms seeking priority review pathways. Target wound care biologics integration as the most penetrable channel where diabetic foot ulcer centers remain underpenetrated by living cellular matrices. Pursue CDMO partnerships to avoid ISO 14644 cleanroom capital expenditure while validating manufacturing protocols. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across autologous production tiers as Grade B manufacturing suites with isolator technology require substantial upfront investment. Long-term viability favors allogeneic platform developers with commercial-scale cell therapy supply capabilities. Monitor Japan's PMDA conditional approval framework as the signal for inflection in early commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA's regenerative medicine advanced therapy designation compresses clinical trial timelines for qualifying sponsors. |
| Manufacturing Scale-Up | Closed-system bioprocessing equipment displaces manual open-culture methods in GMP-grade facilities. |
| Backward Integration | In-house serum-free media formulation reduces dependency on triple-cost synthetic reagent suppliers. |
| Hospital System Partnership | Integrated delivery networks consolidate vendor relationships through centralized value analysis frameworks. |
| Reimbursement Strategy | Priority review pathways align cellular therapy pricing with surgical hardware bundling in orthopedic channels. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with cell therapy manufacturing technicians, regulatory affairs leads at multi-region sponsors, hospital procurement managers, and GMP facility directors; and secondary validation against FDA filings, EMA inspection reports, ClinicalTrials.gov entries, and hospital procurement databases. Bottom-up and top-down triangulation cross-referenced manufacturing capacity announcements with reimbursement pathway documentation.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning application focus, delivery mode selection, cell type sourcing strategy, and end-user procurement structure. CAGRs were derived from installed base expansion rates and replacement demand patterns. Industry-specific forecast inputs incorporated GMP facility qualification timelines and conditional approval pathway utilization rates.
Underlying assumptions cover sustained orthopedic trauma center surgical volume recovery and serum-free media cost stabilization, with deviation risk concentrated in EMA-FDA inspection divergence extending supply chain qualification timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Oncolytic Virotherapy Market
Cell & Gene Therapy
Cell Therapy Technologies Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
Global Lentiviral Vectors Market
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Nucleic Acid and Gene Therapies in Neuromuscular Disorders Market
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
Ipilimumab Market
Cell & Gene Therapy
Cell and Gene Therapy CDMO Market
Cell & Gene Therapy
Global T-Cell Acute Lymphoblastic Leukemia Treatment Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
RNA Therapy Clinical Trials Market
Cell & Gene Therapy
Global Umbilical Cord Blood (UCB) Stem Cell Market