
 Global Hairy Cell Leukemia Drugs Market | 2026-2036
Global Hairy Cell Leukemia Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hairy Cell Leukemia Drugs Market Foresight
Oncology treatment centers is rebalancing toward specialty hematology clinics as first-line purine analog administration shifts from general hospitals to dedicated cancer centers. F. Hoffmann-La Roche Ltd anchors its position through monoclonal antibody R&D intensity across European and North American markets. AstraZeneca leverages broad oncology infrastructure to compete in relapsed and refractory segments. Novartis AG dominates BRAF inhibitor development for mutation-positive patient subsets.
Hairy cell leukemia drugs comprise targeted therapeutic agents designed to eliminate malignant B-lymphocytes characterized by distinctive cytoplasmic projections, with purine analogs such as cladribine inducing durable remission through interference with DNA synthesis and repair. These agents serve the primary commercial purpose of extending progression-free survival in a rare chronic lymphoproliferative disorder. Purine analogs sustain the largest revenue share due to decades of clinical validation and established reimbursement pathways. Monoclonal antibodies represent the fastest-growing category as rituximab biosimilars and novel CD20-directed agents expand access. BRAF inhibitors command premium pricing in biomarker-selected populations where vemurafenib-class agents demonstrate transformational response rates.
FDA orphan drug designation and EMA priority medicines framework accelerate market access for novel hairy cell leukemia therapies while imposing stringent pharmacovigilance requirements on post-approval safety monitoring. NMPA and PMDA maintain distinct bioequivalence standards for generic purine analogs that shape manufacturing investment decisions across Asia-Pacific supply chains. Stakeholders must monitor evolving minimal residual disease endpoints as regulatory agencies integrate molecular remission criteria into label expansion requirements.
Market Dynamics
The hairy cell leukemia drugs market pivots on regulatory acceleration pathways that compress development timelines for rare hematologic malignancies while intensifying post-approval surveillance obligations.
Growth Catalysts
- FDA Orphan Drug Designation:The accelerated review framework reduces clinical trial duration for novel purine analogs and targeted biologics, enabling earlier patient access in the United States.
- Minimal Residual Disease Endpoints:Regulatory agencies now integrate molecular remission criteria into label expansion requirements, driving investment in companion diagnostic development.
- Specialized Leukemia Care Networks:First-line purine analog administration concentrates in dedicated cancer centers across Germany, Japan, and the United States, creating concentrated demand pools for high-efficacy therapies.
Market Restraints
- API Supply Concentration:Active pharmaceutical ingredient manufacturing for cladribine and pentostatin clusters in limited Asia-Pacific facilities, exposing supply chains to single-source vulnerabilities.
- Biosimilar Erosion Pressure:Rituximab biosimilar entry compresses pricing power for CD20-directed monoclonal antibodies in European markets governed by EMA interchangeability guidelines.
- Small Patient Populations:Ultra-rare disease prevalence restricts commercial scale, forcing manufacturers to absorb high per-patient development costs across limited addressable volumes.
Strategic Opportunities
- EMA Priority Medicines Framework:The scheme offers enhanced scientific advice and accelerated assessment for innovative therapies addressing unmet hematologic needs.
- BRAF Inhibitor Biomarker Expansion:Vemurafenib-class agents command premium positioning in mutation-positive subsets, with companion diagnostic adoption widening addressable patient identification.
- Home-Based Administration Models:Subcutaneous formulation development for purine analogs enables treatment delivery outside infusion centers, reducing healthcare system burden.
Industry Challenges
- Pharmacovigilance Infrastructure:Post-approval safety monitoring for accelerated-approval therapies demands specialized hematologic adverse event detection capabilities that strain smaller manufacturers.
- Cross-Border Reimbursement Harmonization:Divergent health technology assessment methodologies between NICE, IQWiG, and ICER create fragmented market access timelines for novel agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hairy Cell Leukemia Drugs Market |
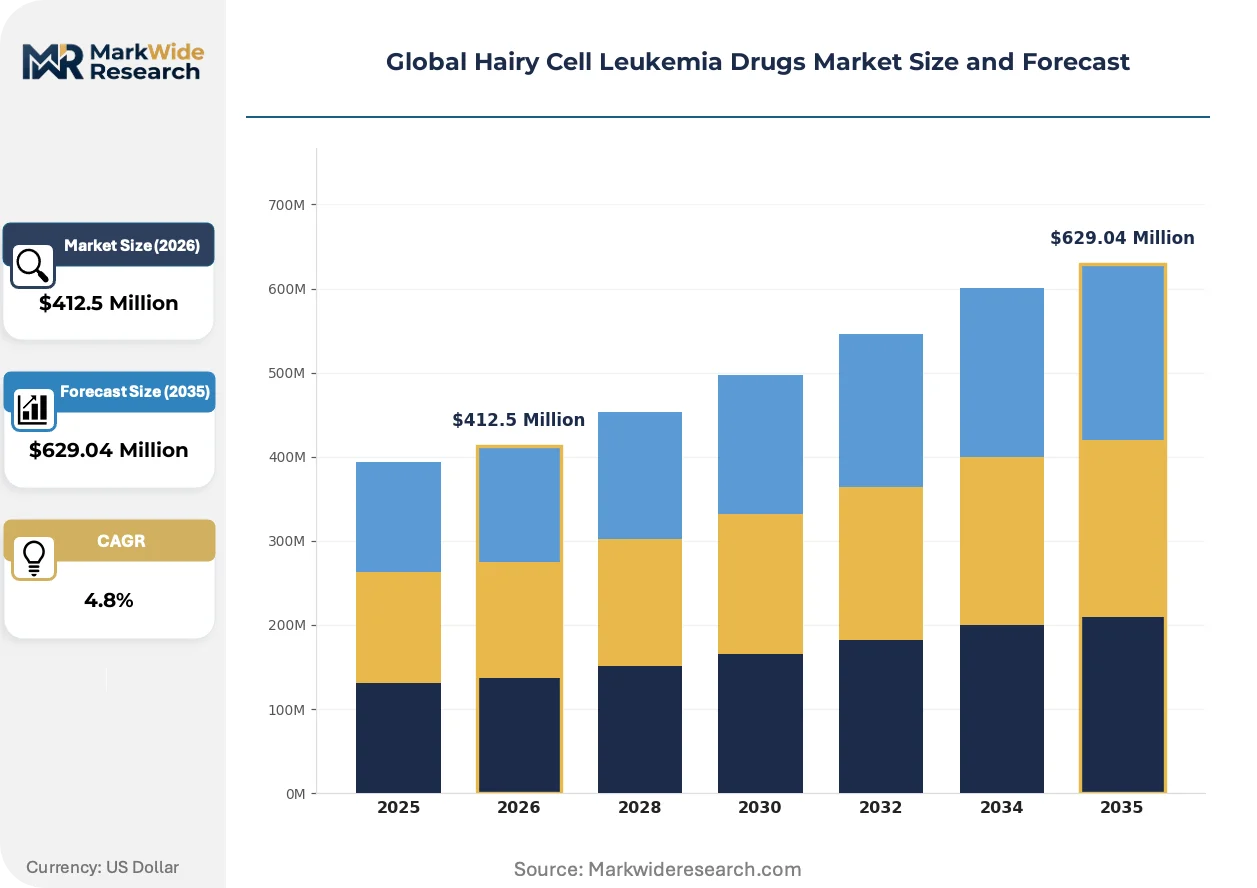
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $629.04 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Type: Purine Analogs, Monoclonal Antibodies, Interferons, BRAF Inhibitors, MEK Inhibitors Therapy Area: First-line Treatment, Relapsed/Refractory Cases, Minimal Residual Disease, Maintenance Therapy End User: Hematology Clinics, Cancer Treatment Centers, Research Hospitals, Specialty Oncology Centers Delivery Mode: Intravenous Injection, Subcutaneous Injection, Oral Administration, Combination Therapy |
| Companies Covered | F. Hoffmann-La Roche Ltd, AstraZeneca, Novartis AG, Amgen Inc, Gilead Sciences, Pfizer Inc, Johnson & Johnson, Teva Pharmaceutical Industries Ltd, AbbVie Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hairy Cell Leukemia Drugs Market Shifts & Advancements
Next-generation sequencing integration and real-world evidence generation are compressing traditional clinical development paradigms while reshaping stakeholder value demonstration requirements.
Next-generation sequencing platforms are decentralizing mutation profiling for BRAF V600E detection, enabling community oncology practices to identify biomarker-positive candidates without centralized laboratory referral. Community hematology clinics in the United States and Germany are adopting point-of-care testing within eighteen-month implementation cycles. This capability compression is decentralizing patient identification and shortening time-to-treatment initiation.
EMA's integration of real-world evidence into regulatory decision-making for rare hematologic malignancies permits post-approval efficacy confirmation through registry data rather than mandatory Phase IV trials. The industrial consequence shifts investment toward robust patient outcome tracking infrastructure. Biomarker-selected therapy segments respond by embedding prospective observational studies into commercial launch planning.
Consolidated purchasing by integrated delivery networks in the United States is displacing traditional wholesaler-mediated distribution for high-cost oncology injectables. Specialty pharmacy direct-to-provider models capture growing volume share, particularly for oral BRAF inhibitors. This channel restructuring concentrates contracting leverage among three national pharmacy benefit managers.
Global Hairy Cell Leukemia Drugs Market Segmentation
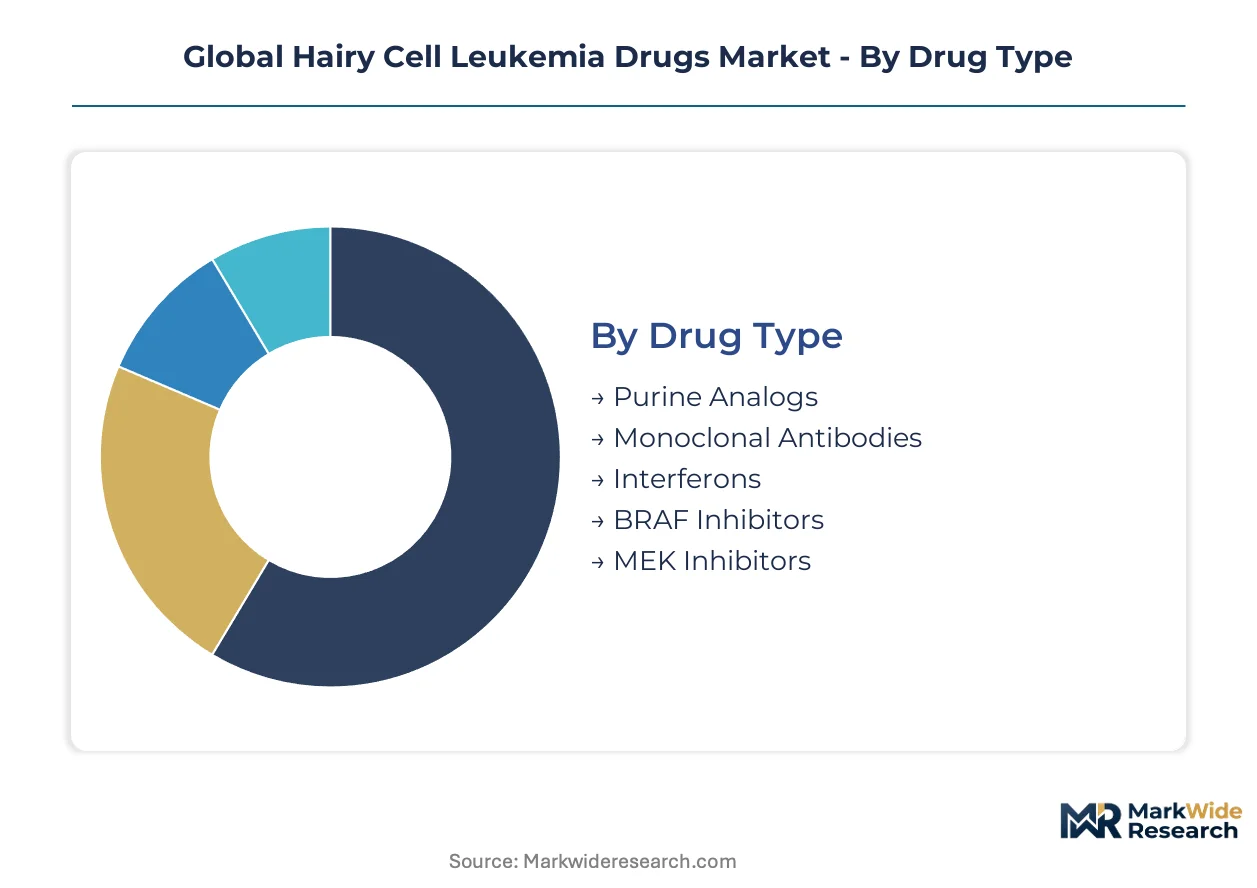
Segmentation in the hairy cell leukemia drugs market reveals how supply chain configuration, clinical workflow integration, and regulatory pathway selection shape competitive positioning across therapeutic categories. Manufacturers align formulation development and distribution investments with the specific operational requirements of each segment.
Drug Type:
Active pharmaceutical ingredient manufacturing concentrates in distinct geographic clusters that determine competitive dynamics across therapeutic modalities.
- Purine Analogs:Cladribine and pentostatin formulations induce durable remission through DNA synthesis interference. Demand concentrates in hematology clinics across Germany, Japan, and the United States where established reimbursement pathways support first-line administration. Supply vulnerability persists due to API manufacturing concentration in limited Asia-Pacific facilities.
- Monoclonal Antibodies:CD20-directed agents including rituximab and biosimilar variants deplete malignant B-lymphocyte populations through targeted immunomodulation. Cancer treatment centers in the United States and European markets drive volume as combination protocols expand, though EMA interchangeability guidelines accelerate pricing compression.
- Interferons:Historical standard-of-care agents now deployed primarily in resource-constrained settings or patient subpopulations with contraindications to purine analogs.
- BRAF Inhibitors:Vemurafenib-class agents command premium positioning in mutation-positive subsets identified through companion diagnostic testing.
- MEK Inhibitors:Emerging combination partners for BRAF-mutant disease under investigation in relapsed and refractory populations.
Purine analogs absorb the bulk of installed manufacturing capacity; monoclonal antibodies are expanding most quickly as biosimilar penetration broadens access.
Therapy Area:
Clinical trial design and regulatory submission strategies diverge sharply based on treatment sequencing and response assessment endpoints.
- First-line Treatment:Initial disease management protocols prioritize purine analog monotherapy or combination with rituximab to achieve complete hematologic remission. Specialized leukemia care networks in Germany and Japan concentrate patient volume and shape protocol standardization.
- Relapsed/Refractory Cases:Progressive or resistant disease segments demand salvage therapies with novel mechanisms, driving investment in BRAF inhibitor development and combination immunotherapy approaches.
- Minimal Residual Disease:Molecular remission endpoints now integrated into FDA and EMA label expansion requirements, compelling companion diagnostic co-development.
- Maintenance Therapy:Extended treatment protocols for high-risk residual disease subsets remain under clinical investigation with limited commercial penetration.
First-line treatment commands the largest addressable patient volume; minimal residual disease endpoints are gaining regulatory traction fastest.
End User:
Site-of-care migration from general hospitals to specialized facilities is restructuring distribution and contracting relationships.
- Hematology Clinics:Dedicated B-cell malignancy centers concentrate expertise in purine analog administration and adverse event management. Germany's specialized clinic network and Japan's designated cancer care hospitals anchor regional demand.
- Cancer Treatment Centers:Comprehensive oncology institutions integrate hairy cell leukemia protocols within broader lymphoma service lines, particularly across United States National Cancer Institute-designated centers.
- Research Hospitals:Academic medical centers conduct early-phase trials for novel agents and biomarker-selected therapies.
- Specialty Oncology Centers:Community-based infusion facilities expanding capacity for biologic administration outside traditional hospital settings.
Hematology clinics capture the majority of first-line purine analog volume; specialty oncology centers are scaling fastest as subcutaneous formulations enable decentralized care.
Delivery Mode:
Formulation innovation targets healthcare system efficiency and patient convenience as competitive differentiators.
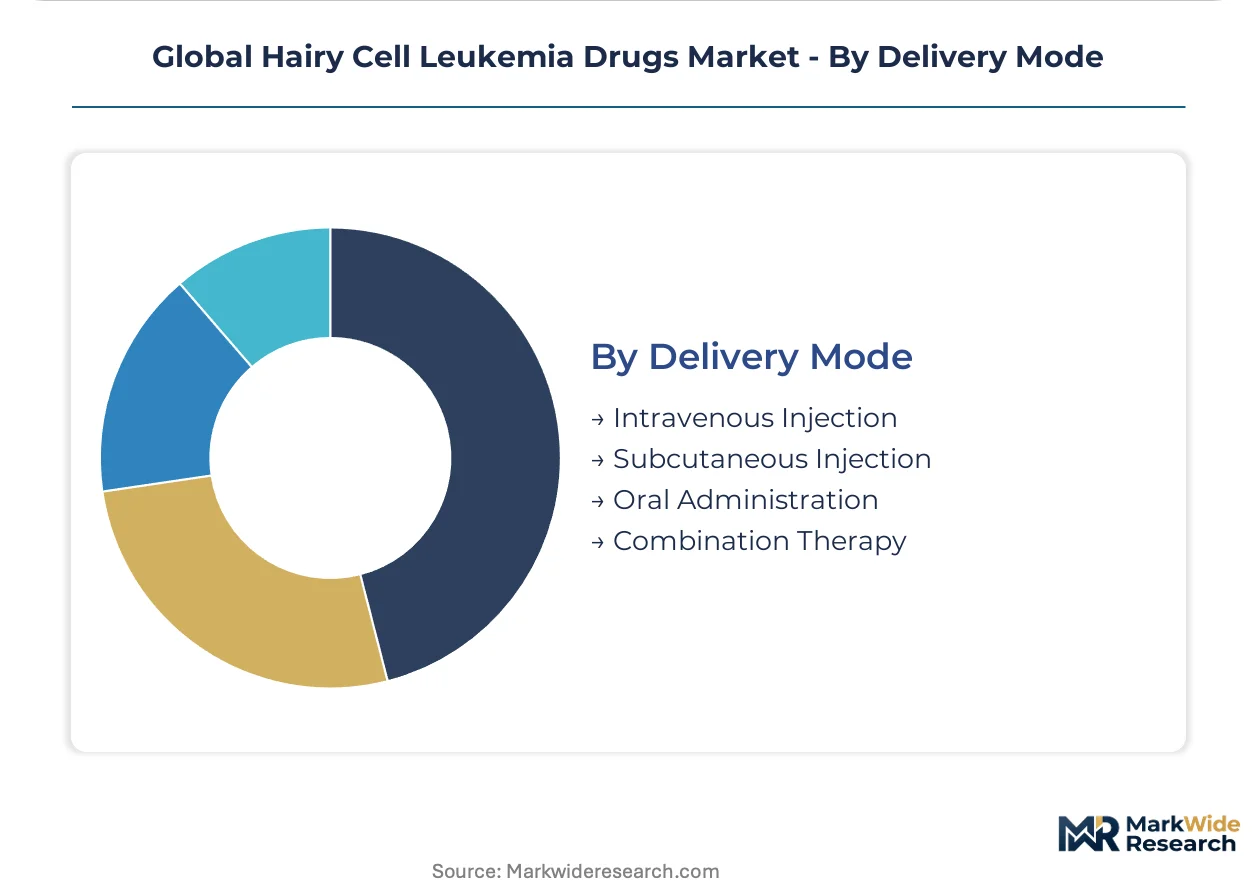
- Intravenous Injection:Hospital-based infusion of cladribine and rituximab requires specialized nursing infrastructure and remains standard for combination protocols. United States cancer centers and German university hospitals maintain the largest installed infusion capacity.
- Subcutaneous Injection:Alternative administration routes for select monoclonal antibodies reduce treatment duration and facility burden, with adoption accelerating in outpatient oncology settings.
- Oral Administration:BRAF inhibitors and emerging small molecules enable home-based therapy, reshaping pharmacy benefit management and specialty pharmacy distribution.
- Combination Therapy:Sequential or concurrent administration of purine analogs with monoclonal antibodies requires coordinated scheduling and monitoring protocols.
Intravenous injection retains the largest procedure volume; oral administration is climbing the fastest as targeted small molecules expand their approved indications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized economic zones for pharmaceutical manufacturing in Singapore and tax-advantaged research corridors in Massachusetts concentrate clinical trial infrastructure and API production for rare hematology indications. These designated zones attract orphan drug developers through accelerated approval facilitation and R&D credits.
United States
Demand concentrates in National Cancer Institute-designated centers across Boston, Houston, and Seattle where purine analog administration protocols standardize. FDA orphan drug designation provides seven-year market exclusivity and tax credits for clinical trials. The Research Triangle Park corridor in North Carolina anchors contract manufacturing for cladribine API.
Germany
Specialized leukemia care networks in Munich, Heidelberg, and Essen drive first-line treatment volume for B-cell malignancies. EMA priority medicines framework accelerates assessment timelines for innovative hematologic therapies. The Rhine-Main biotechnology cluster near Frankfurt houses companion diagnostic development for BRAF mutation testing.
Japan
Designated cancer care hospitals in Tokyo, Osaka, and Nagoya concentrate expertise in monoclonal antibody combination protocols. PMDA maintains distinct bioequivalence standards for generic purine analogs that shape formulation investment. The Kansai region's pharmaceutical manufacturing belt supplies domestic demand for interferon alternatives.
Switzerland
Basel anchors monoclonal antibody R&D intensity through integrated biotechnology campuses. Swissmedic operates accelerated authorization pathways for therapies addressing ultra-rare hematologic conditions. The Lake Geneva corridor connects clinical research organizations with specialized hematology clinics in Lausanne and Geneva.
India
CDSCO's orphan drug regulations are evolving to mirror FDA frameworks, attracting contract research investment to Hyderabad and Bangalore. Active pharmaceutical ingredient manufacturing for cladribine concentrates in Gujarat's pharmaceutical special economic zones. Mumbai's clinical trial infrastructure expands capacity for biosimilar rituximab studies.
Global Hairy Cell Leukemia Drugs Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated biopharmaceutical companies commanding premium positioning in targeted biologics while generic API suppliers capture volume in established purine analogs. The competitive structure tiers into three archetypes: multinational oncology platforms with broad hematology infrastructure, rare disease specialists with accelerated regulatory expertise, and biosimilar manufacturers exploiting EMA interchangeability guidelines. Dominant competitive moves include strategic partnerships for companion diagnostic co-development and geographic expansion into concentrated leukemia care networks.
Among Swiss-headquartered pharmaceutical conglomerates, F. Hoffmann-La Roche Ltd and Novartis AG exemplify the multinational oncology platform archetype through established monoclonal antibody and targeted therapy portfolios. AstraZeneca represents the rare disease specialist positioning with infrastructure optimized for relapsed and refractory hematologic indications. These three entities anchor competitive dynamics in biomarker-selected therapy segments and combination protocol development.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| AstraZeneca |
| Novartis AG |
| Amgen Inc |
| Gilead Sciences |
| Pfizer Inc |
| Johnson & Johnson |
| Teva Pharmaceutical Industries Ltd |
| AbbVie Inc |
| Others |
Supply & Pricing Matrix
Subcutaneous formulation development for purine analogs is compressing site-of-care costs while concentrating manufacturing investment in facilities capable of sterile injectable production. This dual shift simultaneously reduces per-treatment facility overhead and raises barriers to API supply diversification.
Pricing Analysis
Short lead-time premiums for BRAF inhibitor companion diagnostic bundles command pricing power against standard procurement cycles for purine analogs. Three-tier pricing structure across premium biomarker-selected therapies, standard monoclonal antibody protocols, and economy interferon alternatives reflects efficacy differentiation and reimbursement tiering. Pricing pressure stems from rituximab biosimilar entry under EMA interchangeability guidelines. Hematology clinics in Germany exhibit highest price sensitivity due to IQWiG reference pricing, while United States specialty pharmacies absorb premium positioning for oral targeted agents.
Supply Chain Analysis
Dual-sourcing mandates from United States cancer treatment centers and German university hospitals require qualified suppliers for cladribine API across at least two geographic origins. Active pharmaceutical ingredient manufacturing draws from India, China, and limited European facilities for pentostatin and cladribine intermediates. Supply chain risk centers on single-source fermentation capacity for purine analog precursors. Distribution runs through specialty pharmacy direct-to-provider channels for oral BRAF inhibitors, with traditional wholesaler mediation persisting for hospital-based infusion products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hairy cell leukemia drugs market sits in a targeted biologics transition phase, with next-generation sequencing-enabled patient selection replacing empiric chemotherapy protocols as the dominant treatment paradigm.
For Market Incumbents: Extend companion diagnostic co-development partnerships to lock in biomarker-selected therapy positioning before regulatory agencies mandate molecular remission endpoints for label expansion. Consolidate API supply relationships through backward integration into fermentation capacity or captive supply agreements with Indian and Chinese manufacturers to mitigate single-source vulnerability. Prioritize pharmacovigilance infrastructure investment to satisfy FDA post-approval surveillance obligations for accelerated-approval pathways. For New Entrants and Emerging Players: Next-generation sequencing platform integration offers a technology-first wedge into community hematology clinic settings where point-of-care BRAF V600E testing remains underdeployed. Target relapsed and refractory patient populations in Japan's designated cancer care hospitals where PMDA bioequivalence standards create formulation differentiation opportunities. Pursue licensing agreements for subcutaneous delivery technologies to bypass infusion center capacity constraints. For Investors and Strategic Acquirers: Exit pathways concentrate in rare disease specialist acquisitions by multinational oncology platforms seeking accelerated regulatory expertise. Long-term viability hinges on biomarker-selected therapy segments where companion diagnostic adoption widens addressable patient identification. Watch for EMA integration of real-world evidence into label expansion requirements as the inflection signal for registry infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Companion Diagnostic Co-Development | FDA and EMA now integrate molecular remission criteria into label expansion requirements for novel agents. |
| Subcutaneous Formulation Investment | Home-based administration models reduce healthcare system burden and expand community clinic addressable volume. |
| API Supply Backward Integration | Cladribine and pentostatin manufacturing concentration in limited Asia-Pacific facilities creates single-source vulnerability. |
| Real-World Evidence Infrastructure | EMA permits post-approval efficacy confirmation through registry data rather than mandatory Phase IV trials. |
| Specialty Pharmacy Channel Expansion | Integrated delivery networks in the United States displace traditional wholesaler-mediated distribution for high-cost oncology injectables. |
Research Methodology
FDA orphan drug filings, EMA priority medicines framework documentation, and ClinicalTrials.gov protocol records formed the secondary backbone for therapeutic pipeline assessment. Primary interviews with drug development executives, regulatory affairs leads, formulary directors at United States cancer centers, and payer access specialists validated commercial assumptions. Bottom-up patient volume estimates by treatment line and administration route triangulated against top-down market sizing from API production capacity and specialty pharmacy dispensing data.
Historical trendline analysis of purine analog and monoclonal antibody revenue trajectories informed baseline growth assumptions across the projection horizon. The analytical framework modeled segmentation by drug type, therapy area, end-user facility type, and delivery mode. CAGRs derived from fitted growth curves adjusted for regulatory approval timelines and biosimilar entry patterns. Forecast inputs included biomarker prevalence rates, companion diagnostic adoption curves, and site-of-care migration trends.
Several conditions sit outside the modeled scope, including unforeseen regulatory rejection of molecular remission endpoints, abrupt API supply disruptions from geopolitical events, and radical shifts in United States reimbursement policy for oral oncology agents. Forecasts reflect assumptions regarding stable orphan drug exclusivity periods and continued EMA-EMA mutual recognition. A model refresh is warranted upon material change in FDA post-approval surveillance requirements or EMA real-world evidence integration standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Antibody Production Market
Biopharmaceuticals
1-Step RT-PCR Kits Market
Biopharmaceuticals
Neurodegenerative Diseases Drugs Market
Biopharmaceuticals
Bio-Identical Hormones Replacement Therapy Market
Biopharmaceuticals
Global Bioengineered Protein Drugs Market
Biopharmaceuticals
Global Tick-Borne Encephalitis Inactivated Vaccine Market
Biopharmaceuticals
Recombinant Human Serum Albumin Market
Biopharmaceuticals
RNA Targeting Small Molecule Drug Discovery Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Primary Biliary Cholangitis (PBC) Therapeutics Market
Biopharmaceuticals
Sezary Syndrome Market
Biopharmaceuticals
Generic Injectables Market
Biopharmaceuticals
Chronic Phase Markers Market
Biopharmaceuticals
Interleukin-6 (IL-6) Inhibitors Market