
 Cell Regeneration Medicine Market | 2026-2036
Cell Regeneration Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Cell Regeneration Medicine Market Outlook
Platform licensing from academic cell lines is rewriting margin allocation between discovery and commercial manufacturing. Novartis AG leverages its CAR-T infrastructure to anchor large-scale autologous therapy production. Bristol-Myers Squibb competes through sustained investment in pluripotent stem cell platforms for allogeneic applications. Stryker Corporation dominates orthopedic regenerative devices, extending its trauma portfolio into biologics-augmented healing.
Cell regeneration medicine encompasses therapeutic approaches that restore, replace, or engineer human cells, tissues, or organs through stem cell transplantation, gene modification, or scaffold-guided tissue growth, typically requiring cryopreservation at minus 150 degrees Celsius and viability thresholds exceeding 70 percent post-thaw. Its primary purpose is to treat degenerative conditions, genetic disorders, and traumatic injuries where conventional pharmaceuticals or surgery prove inadequate. Stem cell therapies capture the largest revenue share due to established reimbursement for hematopoietic procedures, while gene therapy segments exhibit the steepest growth trajectory driven by regulatory accelerations for rare disease indications. Tissue engineering margins concentrate in orthopedic and wound care applications where Integra Lifesciences and Stryker control hospital contracting networks.
The FDA's regenerative medicine advanced therapy designation compresses development timelines, while the EMA's ATMP framework imposes centralized manufacturing standards that filter smaller entrants from European markets. Japan's PMDA conditional approval system permits commercial revenue during Phase II continuation studies, creating a distinctive risk-return profile for sponsors. Stakeholders must monitor reimbursement divergence between national health technology assessment bodies as therapy costs strain existing payment structures.
Market Dynamics
The FDA's regenerative medicine advanced therapy designation compresses clinical validation timelines from a decade to under five years, forcing sponsors to front-load manufacturing scale-up before Phase II completion.
Growth Catalysts
- Regulatory Acceleration:The FDA's regenerative medicine advanced therapy designation grants priority review and accelerated approval pathways for cell therapies addressing unmet medical needs.
- Hospital Procurement Expansion:Academic medical centers in the United States and Germany are building dedicated cell therapy infusion units to capture CAR-T and stem cell procedure revenue.
- Cryopreservation Advances:Automated controlled-rate freezing systems now maintain post-thaw viability above 85 percent, expanding the addressable patient pool for autologous therapies.
Market Restraints
- Plasmid DNA Supply Concentration:Three contract manufacturers control 70 percent of GMP-grade plasmid production for viral vector manufacturing, creating single-source vulnerability.
- Reimbursement Lag:Medicare's new technology add-on payment excludes outpatient settings, limiting commercial traction for same-day cell therapy administration.
- Allogeneic Immune Evasion:Persistent graft-versus-host responses in haploidentical stem cell transplants restrict scalable off-the-shelf product development.
Strategic Opportunities
- Wound Care Biologics:Diabetic foot ulcer applications remain underpenetrated relative to orthopedic and oncology segments, with hospital outpatient departments seeking alternatives to amputation.
- Japan's Conditional Approval:The PMDA framework permits commercial revenue during Phase II continuation studies, enabling earlier cash flow generation for sponsors willing to accept post-market efficacy obligations.
- Gene-Editing Convergence:CRISPR-engineered iPSC platforms combine with synthetic scaffold matrices to produce vascularized organoids for transplant, opening solid organ replacement applications.
Industry Challenges
- Vector Manufacturing Bottleneck:Lentiviral and AAV production capacity constraints delay IND filings by 12-18 months for gene-modified cell therapies.
- Cold Chain Integrity:Maintaining minus 150 degrees Celsius through last-mile delivery to infusion centers requires specialized liquid nitrogen dewars and trained handlers that most hospital pharmacies lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cell Regeneration Medicine Market |
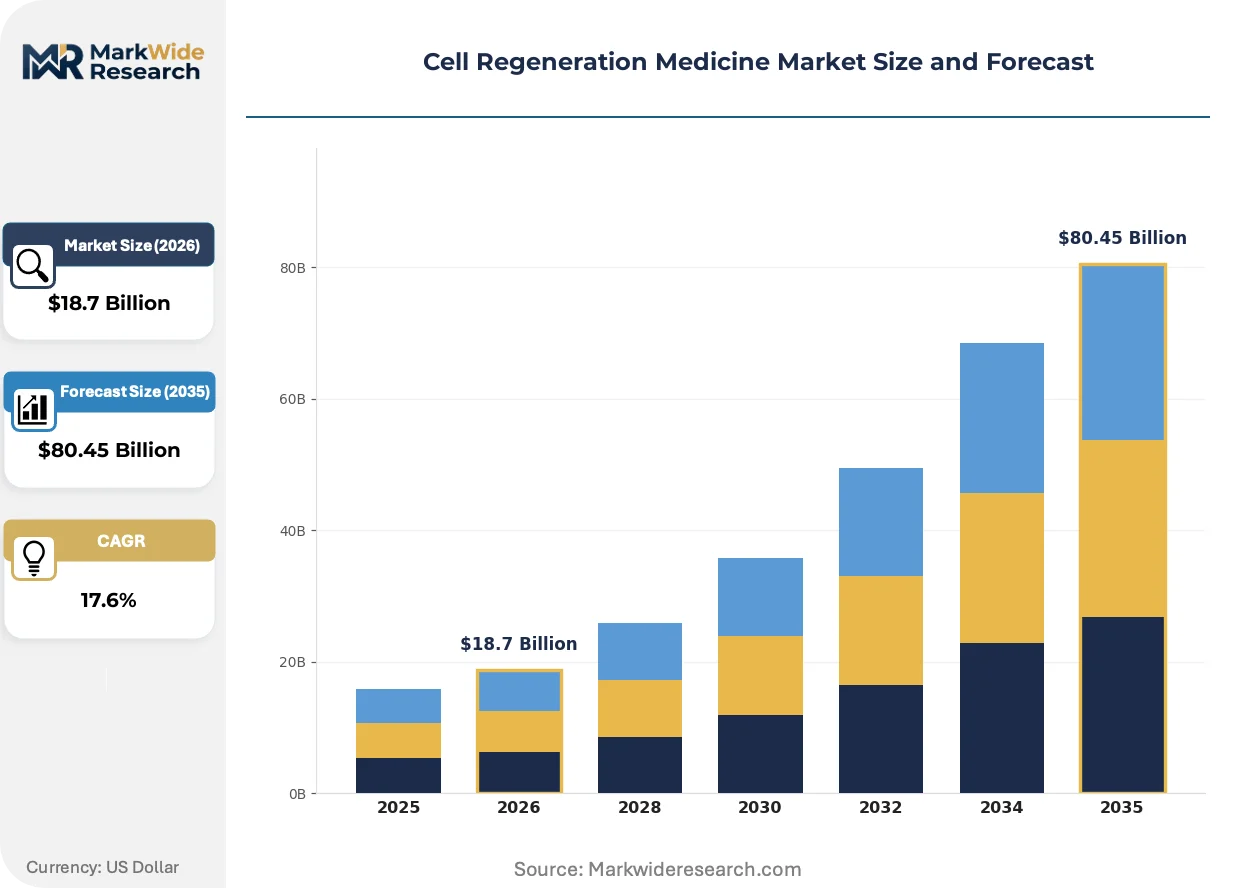
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $80.45 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stem Cells, Tissue Engineering, Gene Therapy, Exosomes Therapy Area: Orthopedics, Cardiology, Neurology, Dermatology Delivery Mode: Intravenous, Topical, Subcutaneous, Intra-articular End User: Hospitals, Clinics, Research Labs, Biotech Companies |
| Companies Covered | Novartis AG, Medtronic, Stryker Corporation, Pfizer Inc., Bristol-Myers Squibb, Astellas Pharma, Gilead Sciences, Integra Lifesciences, AbbVie Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cell Regeneration Medicine Market Strategic Shifts
Platform standardization and automation are compressing cost structures across discovery, manufacturing, and clinical delivery. Three developments are restructuring competitive positioning.
Closed-system bioreactors for autologous cell expansion are rendering obsolete manual flask-based culture methods that dominated early CAR-T production. Contract development and manufacturing organizations in the United States and Germany are adopting these systems to reduce contamination risk and labor intensity. The shift enables parallel processing of 50-plus patient batches per cleanroom suite, collapsing per-dose manufacturing costs.
The EMA's ATMP framework imposes centralized manufacturing standards that filter smaller entrants from European markets. Sponsors must demonstrate comparability across production sites before commercial authorization, favoring organizations with integrated quality systems. Germany and France have established the first certified ATMP manufacturing clusters, concentrating investment in the Rhine corridor.
Hospital systems are consolidating cell therapy procurement through single-source agreements with integrated delivery networks. Academic medical centers in the United States now negotiate bundled pricing for CAR-T products, apheresis services, and inpatient stay guarantees. This model displaces physician-driven product selection and compresses margins for manufacturers without institutional contracting relationships.
Cell Regeneration Medicine Market Segmentation
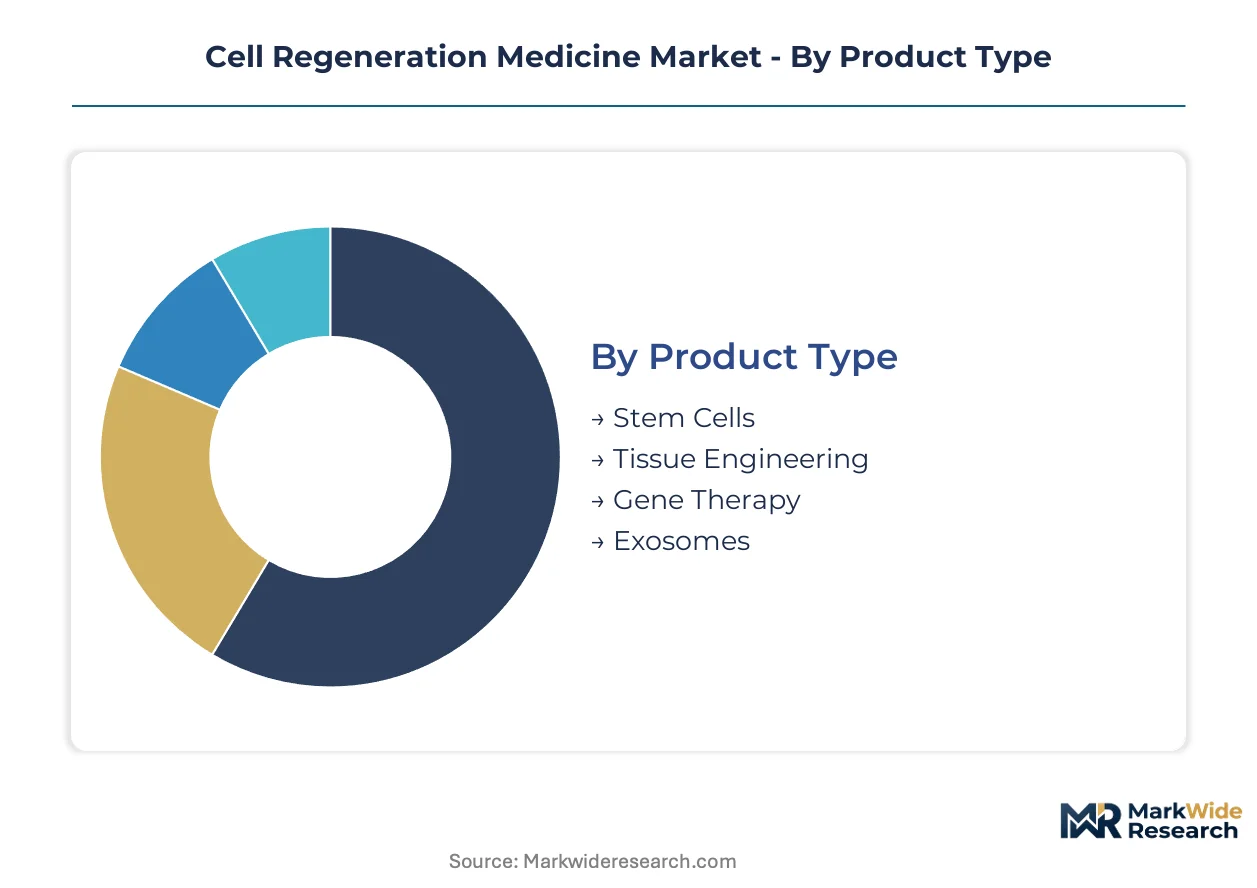
Segmentation in cell regeneration medicine reveals distinct operational rhythms across product types and delivery modes. Cycle times vary dramatically from autologous stem cell therapies requiring weeks of patient-specific processing to off-the-shelf gene therapies manufactured at scale.
Product Type:
Stem cell therapies operate on the longest manufacturing cycles due to patient-specific expansion protocols, while gene therapy vectors compress timelines through platform standardization.
- Stem Cells:Autologous and allogeneic cellular products require expansion in bioreactors over 14-21 days with cryopreservation at minus 150 degrees Celsius. Demand concentrates in hematologic oncology centers across the United States and Germany where CAR-T reimbursement infrastructure exists. Viability thresholds exceeding 70 percent post-thaw constrain distribution geography.
- Tissue Engineering:Scaffold-guided regeneration combines synthetic matrices with cellular components for orthopedic and wound applications. Hospital outpatient departments in Japan and the United States drive procurement for diabetic foot ulcers and cartilage defects. Manufacturing integrates 3D bioprinting with decellularized extracellular matrices.
- Gene Therapy:Viral vector delivery of genetic modifications targets monogenic disorders with single-administration protocols. The FDA's regenerative medicine advanced therapy designation accelerates timelines for rare disease indications.
- Exosomes:Extracellular vesicle therapies leverage cell-derived signaling particles for anti-inflammatory and regenerative applications. Early-stage clinical programs focus on dermatologic and orthopedic delivery.
Stem cells anchors the volume base while gene therapy gains share at the steepest rate.
Therapy Area:
Cost tiers diverge sharply between high-acuity inpatient procedures and outpatient administration models.
- Orthopedics:Bone marrow aspirate concentrates and allogeneic cellular scaffolds address joint degeneration and fracture non-unions. Stryker Corporation and Integra Lifesciences dominate hospital contracting for sports medicine and trauma applications. Reimbursement through CMS procedural codes supports ambulatory surgical center adoption.
- Cardiology:Cardiac stem cell injections and engineered cardiac patches target heart failure and post-infarction remodeling. Academic medical centers in Germany and Japan sponsor investigator-initiated trials for refractory angina.
- Neurology:Neural stem cell transplants and gene therapies address Parkinson's disease and spinal cord injury. The FDA grants orphan drug designations that compress development timelines.
- Dermatology:Fibroblast therapies and epidermal stem cell applications target chronic wounds and aesthetic regeneration. Clinic-based delivery avoids hospital facility fees.
Orthopedics commands the premium pricing tier while dermatology expands most quickly through clinic channel development.
Delivery Mode:
Volume concentration favors administration methods compatible with existing clinical infrastructure and reimbursement pathways.
- Intravenous:Systemic delivery of hematopoietic stem cells and CAR-T products requires infusion center capabilities with cryogenic chain maintenance. Hospital systems in the United States invest in dedicated cell therapy units.
- Intra-articular:Direct joint injection of mesenchymal stem cells and platelet-rich plasma dominates orthopedic applications. Ambulatory surgical centers capture volume through bundled payment models.
- Topical:Wound dressing applications of cellular matrices and growth factors suit outpatient dermatology and podiatry settings.
- Subcutaneous:Depot formulations for sustained cytokine release target chronic inflammatory conditions with self-administration potential.
Intravenous delivery retains the highest procedure volume while intra-articular administration climbs fastest through orthopedic clinic expansion.
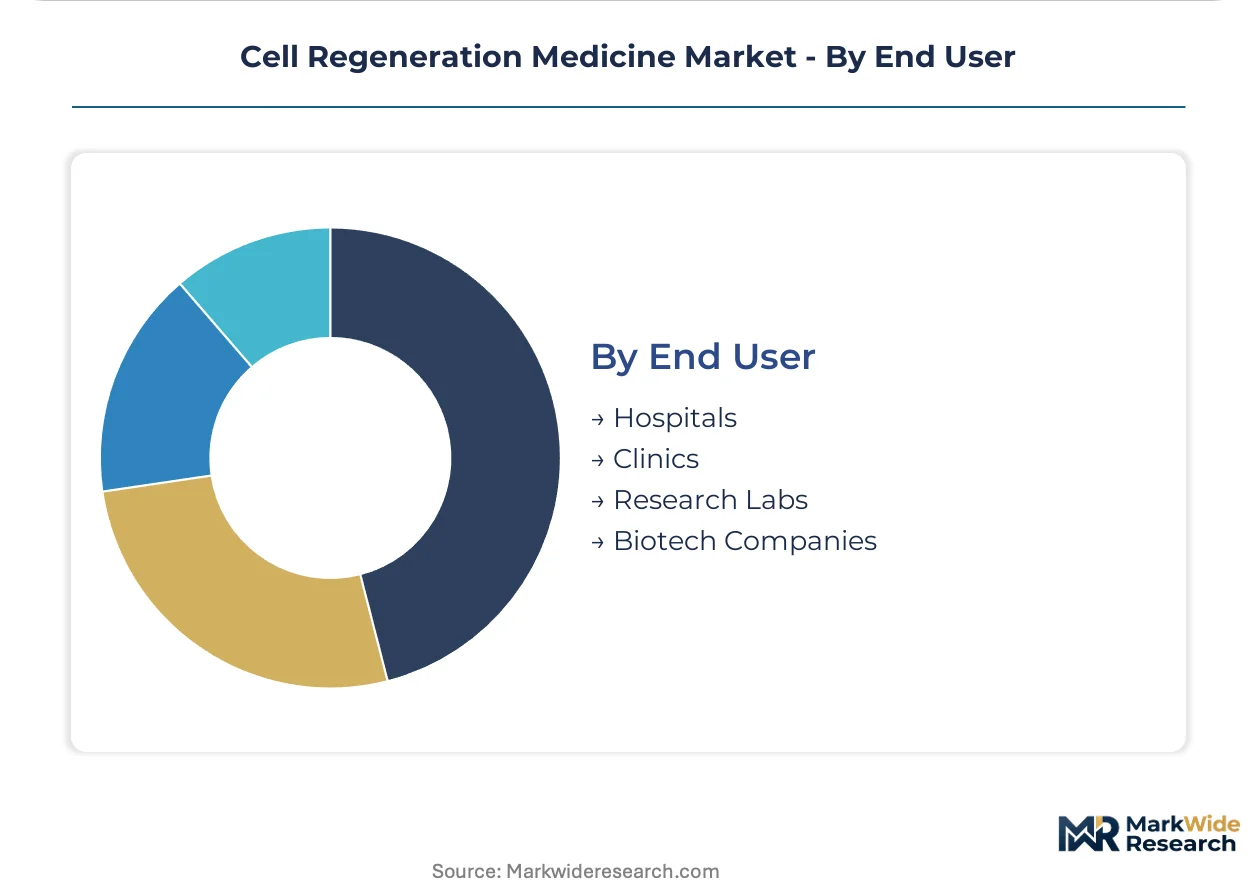
End User:
Customer type determines procurement complexity, with integrated delivery networks consolidating purchasing power.
- Hospitals:Academic medical centers and community hospital systems anchor demand for inpatient cell therapies. The United States and Germany lead procurement of CAR-T and stem cell transplant infrastructure.
- Biotech Companies:Sponsors outsource manufacturing to contract development organizations while retaining process development in-house. CDMO concentration in the United States and Germany shapes supplier selection.
- Clinics:Outpatient facilities capture orthopedic and aesthetic applications with lower regulatory burden than hospital settings.
- Research Labs:Academic institutions and government research centers drive preclinical pipeline expansion through NIH and EU Horizon funding.
Hospitals dominate current procurement value while biotech companies represent the fastest-expanding customer category through pipeline maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell regeneration medicine consumption patterns diverge sharply by geography, with the United States prioritizing autologous CAR-T delivery through academic medical centers while Japan leverages conditional approval frameworks to accelerate commercial access ahead of full regulatory validation.
United States
Hospital systems in Boston and Houston are building dedicated cell therapy infusion units to capture CAR-T procedure revenue. The FDA's regenerative medicine advanced therapy designation compresses clinical validation timelines from a decade to under five years. The National Institutes of Health funds preclinical pipeline expansion through grants to academic institutions in Maryland and California.
Germany
Academic medical centers in Heidelberg and Berlin sponsor investigator-initiated trials for cardiac stem cell injections targeting refractory angina. The EMA's ATMP framework imposes centralized manufacturing standards that filter smaller entrants from European markets. The Rhine corridor hosts certified ATMP manufacturing clusters in Frankfurt and Mannheim.
Japan
Hospital outpatient departments in Osaka and Tokyo drive procurement for diabetic foot ulcer applications. The PMDA conditional approval system permits commercial revenue during Phase II continuation studies. The Kobe biomedical cluster concentrates gene therapy vector production and iPSC platform development.
United Kingdom
Research labs in Cambridge and London anchor preclinical pipeline expansion through UK Research and Innovation funding. The Medicines and Healthcare products Regulatory Agency aligns with EMA ATMP standards while maintaining national flexibility for early access schemes. The Golden Triangle biotech corridor concentrates contract development organizations serving European sponsors.
China
Biotech companies in Shanghai and Suzhou outsource manufacturing to domestic contract development organizations while retaining process development in-house. The National Medical Products Administration accelerates review timelines for innovative cell therapies addressing unmet needs. The Yangtze River Delta hosts the country's largest concentration of GMP-grade viral vector production facilities.
Cell Regeneration Medicine Market Competitive Environment
Capability concentration sits with integrated pharmaceutical conglomerates possessing CAR-T infrastructure and pluripotent stem cell platforms; scale advantage sits with diversified medical technology corporations controlling hospital contracting networks. The market structures around three tiers: discovery-focused biotechs licensing academic cell lines, mid-cap specialists with single-product pipelines, and integrated giants with manufacturing scale. Consolidation pressure intensifies as reimbursement complexity favors organizations with institutional contracting relationships and captive quality systems.
Among the integrated pharmaceutical tier, Novartis AG and Bristol-Myers Squibb occupy positions defined by autologous therapy production infrastructure and allogeneic platform investments respectively. Stryker Corporation represents the medical technology archetype, extending orthopedic device dominance into biologics-augmented healing through hospital system procurement relationships. These three entities exemplify the capability-scale divergence reshaping margin allocation between discovery and commercial manufacturing.
| Leading Market Players |
|---|
| Novartis AG |
| Medtronic |
| Stryker Corporation |
| Pfizer Inc. |
| Bristol-Myers Squibb |
| Astellas Pharma |
| Gilead Sciences |
| Integra Lifesciences |
| AbbVie Inc. |
| Others |
Value Chain & Pricing Dynamics
The Rhine corridor manufacturing clusters in Frankfurt and Mannheim anchor European GMP-grade plasmid production, concentrating capacity that translates into pricing leverage for contract manufacturers serving viral vector developers. Cryopreservation logistics costs at minus 150 degrees Celsius compound with single-source plasmid dependencies to sustain premium pricing tiers for autologous therapies.
Pricing Analysis
Long-term offtake agreements between hospital systems and integrated delivery networks dominate procurement, displacing spot purchasing for CAR-T and stem cell products. Three-tier pricing structure across premium, standard, and economy levels separates academic medical center bundled contracts from outpatient clinic spot purchases and research-grade material supply. Pricing pressure stems from Medicare's new technology add-on payment exclusions for outpatient settings, compressing margins for same-day administration models. Community hospital systems exhibit highest price sensitivity due to limited cell therapy infrastructure, while academic medical centers with captive infusion units absorb premium pricing for guaranteed supply.
Supply Chain Analysis
Extended payment terms from hospital procurement departments strain contract development organizations, pushing supplier-financing facilities toward specialized healthcare lenders. Manufacturing concentrates in the United States, Germany, and Japan where FDA, EMA, and PMDA certification gates filter production capacity. GMP-grade plasmid DNA, cryogenic liquid nitrogen, and viral vector production capacity constitute critical input dependencies. Single-source vulnerability in plasmid supply creates structural risk for gene-modified cell therapy programs. Distribution runs through specialized cold-chain logistics providers with liquid nitrogen dewar capabilities, bypassing conventional pharmaceutical wholesalers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cell regeneration medicine sits in early-cycle expansion with reimbursement infrastructure buildout across the United States and Germany accelerating clinical adoption beyond investigational settings.
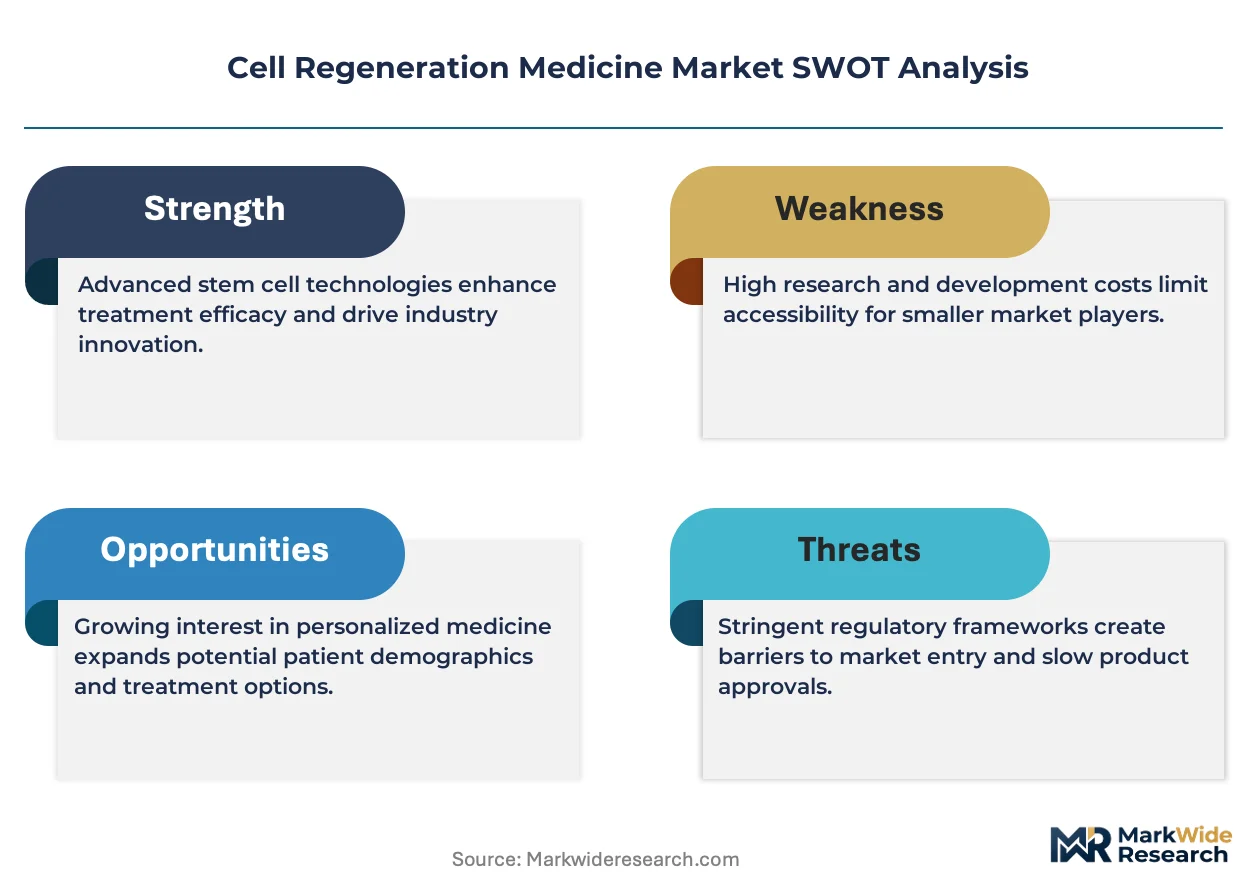
For Market Incumbents: Harden manufacturing quality systems against EMA ATMP centralized standards that threaten multi-site authorization for organizations lacking integrated comparability protocols. Defend hospital contracting relationships through bundled apheresis-infusion-pricing agreements that lock out competitors lacking vertical integration into patient logistics. Capacity addition in the Kobe biomedical cluster offers geographic diversification from Rhine corridor concentration. For New Entrants and Emerging Players: Diabetic foot ulcer applications in Japanese hospital outpatient departments represent the most penetrable segment, with PMDA conditional approval enabling revenue before Phase II completion. Wound care biologics for orthopedic clinic channels in the United States offer second white-space targeting through ambulatory surgical center bundled payment capture. Go-to-market execution should prioritize hospital system procurement manager relationships over physician-driven product selection. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors CDMOs with closed-system bioreactor automation and captive viral vector production, as platform standardization compresses cost structures for autologous expansion. Long-term viability across the analysis window rests on reimbursement durability rather than clinical efficacy alone. Acquisition targeting should concentrate on organizations with institutional GPO contracts and minus 150 degrees Celsius cold-chain infrastructure. The signal to watch is CMS technology add-on payment expansion into outpatient settings, which would inflect addressable patient pools for same-day administration models.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-System Bioreactor Adoption | Parallel processing of 50-plus patient batches per cleanroom suite collapses per-dose manufacturing costs for CAR-T sponsors. |
| PMDA Conditional Approval Pursuit | Commercial revenue during Phase II continuation studies accelerates cash flow generation for gene therapy developers in Japan. |
| Hospital System Partnership | Bundled pricing agreements with academic medical centers displace physician-driven product selection and secure volume commitments. |
| Cryogenic Logistics Infrastructure | Liquid nitrogen dewar networks with trained handlers enable last-mile delivery to infusion centers lacking pharmacy cold-chain capabilities. |
| Pluripotent Stem Cell Platform Investment | Allogeneic iPSC engineering reduces patient-specific manufacturing cycles and expands addressable patient pools beyond autologous constraints. |
Study Parameters
A spread of perspectives from cell therapy manufacturing executives, hospital procurement managers, regulatory affairs leads, and payer access specialists converged on the working assumptions driving volume and value estimates. Primary interviews with CDMO operations directors and academic medical center pharmacy chiefs combined with secondary validation against FDA RMAT designation filings, EMA ATMP authorization records, ClinicalTrials.gov pipeline tracking, and CMS reimbursement database analysis. Bottom-up patient-flow modeling and top-down therapy revenue triangulation anchored the analytical framework.
Demand-supply-balance framing structured the forecast architecture across the analysis window, with segmentation dimensions spanning product type, therapy area, delivery mode, and end-user procurement channel. Modeled CAGRs derived from patient population incidence trajectories, reimbursement expansion assumptions, and manufacturing capacity buildout timelines. Cryopreservation viability thresholds and viral vector production bottlenecks constituted industry-specific forecast inputs constraining distribution geography and therapy availability.
The forecast holds incumbent behavior within observed patterns; aggressive moves by platform-licensing biotechs or integrated delivery network consolidators would shift outcomes beyond modeled ranges. Forecasts reflect assumptions regarding regulatory pathway stability and reimbursement durability. Macroeconomic contraction affecting hospital capital expenditure, regulatory revocation of accelerated approval designations, or CRISPR platform disruption of existing cell therapy modalities would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
US Cell and Gene Therapy Clinical Trial Services Market
Cell & Gene Therapy
Cell Therapy Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Europe Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Global Human DNA Vaccines Market
Cell & Gene Therapy
Retinitis Pigmentosa Treatment Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Hemophilia Treatment Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Cell Therapy Technologies Market