
 Plasmid Kits Market | 2026-2036
Plasmid Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Plasmid Kits Market Insights
High-purity endotoxin-free grade is collapsing the gap between research-use and GMP-compliant plasmid preparation workflows. QIAGEN leverages its silica-membrane IP to dominate bench-scale purification across academic core facilities. Thermo Fisher Scientific anchors the mid-throughput segment with automated magnetic bead systems that reduce hands-on time. New England Biolabs differentiates through enzyme-plus-kit bundles that lock in reagent compatibility for cloning workflows.
Plasmid kits are consumable systems containing lysis buffers, neutralization reagents, binding matrices, and elution solutions designed to isolate circular extrachromosomal DNA from bacterial cultures, typically yielding 20 micrograms to 10 milligrams depending on scale. These kits serve molecular biology workflows where template purity determines downstream success in sequencing, transfection, or viral packaging. Mini Kits occupy the highest volume tier due to routine cloning demand in academic settings, while Maxi Kits capture concentrated margin pools from gene therapy CDMOs running plasmid feeds for AAV and lentivirus production. Ultra Kits represent the fastest-growing category as cell-and-gene therapy developers seek endotoxin levels below 0.1 EU per microgram for regulatory filing.
FDA guidance on human gene therapy chemistry, manufacturing, and controls is elevating documentation burdens for plasmid suppliers seeking IND-enabling partnerships. ISO 13485 certification and EU GMP Annex 1 cleanroom standards are becoming baseline requirements for kit vendors serving European pharmaceutical clients. Stakeholders must monitor whether regional divergence in nucleic acid therapeutic regulation fragments qualification protocols or creates harmonization opportunities for cross-border kit distribution.
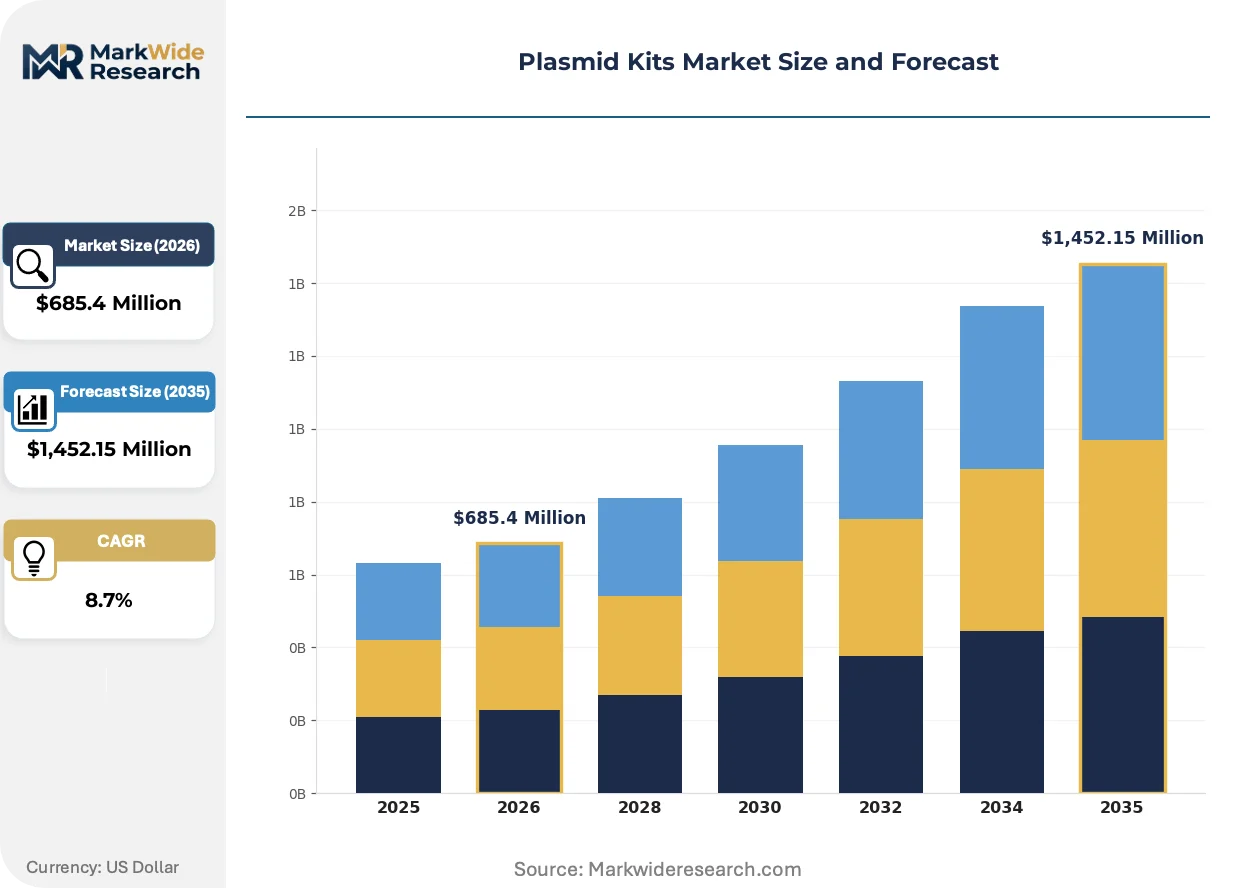
Market Dynamics
Gene therapy CDMOs are consolidating plasmid procurement around GMP-certified kit vendors as FDA purity benchmarks tighten for IND-enabling studies, compressing qualification timelines and locking out research-grade suppliers from clinical workflows.
Growth Catalysts
- AAV manufacturing scale-up:Viral vector producers in the United States are expanding captive plasmid feeds for gene therapy candidates, creating dedicated demand for endotoxin-free Maxi and Ultra kit formats.
- EMA's ATMP framework:The European Medicines Agency's advanced therapy medicinal products guidance is mandating documented plasmid provenance, pushing European pharmaceutical clients toward ISO 13485-certified kit vendors.
- Silica-membrane automation:Magnetic bead purification systems are reducing hands-on time in mid-throughput workflows, accelerating adoption across contract research organizations running high-volume cloning operations.
Market Restraints
- Lysozyme and RNase cost volatility:Enzyme inputs for lysis buffers face supply concentration from a limited base of fermentation suppliers, creating margin pressure for kit manufacturers.
- Cleanroom infrastructure scarcity:EU GMP Annex 1-compliant production facilities for clinical-grade kits concentrate in Germany and Switzerland, creating geographic bottlenecks for vendors seeking European market entry.
- Endotoxin detection limits:LAL assay variability at sub-0.1 EU per microgram thresholds creates batch rejection risk that research-grade kit formats cannot address.
Strategic Opportunities
- Indian CDMO expansion:India's PLI scheme for biopharmaceutical manufacturing is attracting gene therapy developers seeking lower-cost GMP plasmid production, creating demand for qualified kit suppliers.
- mRNA vaccine residual demand:Post-pandemic mRNA platform developers are repurposing plasmid infrastructure for personalized cancer vaccines, opening a new application vertical beyond viral vectors.
- Digital batch records:Cloud-based documentation systems are enabling kit vendors to offer regulatory-ready chain-of-custody packages that accelerate client audit timelines.
Industry Challenges
- GMP auditor shortage:Qualified personnel for ISO 13485 and EU GMP Annex 1 facility inspections are concentrated at legacy pharmaceutical sites, slowing certification timelines for emerging kit vendors.
- Plasmid stability during shipping:Temperature excursion risk for endotoxin-free eluates requires validated cold-chain infrastructure that smaller kit distributors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasmid Kits Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mini Kits, Midi Kits, Maxi Kits, Ultra Kits Application: Cloning, Gene Expression, DNA Sequencing, Transfection End User: Academic Institutions, Pharmaceutical Companies, Research Laboratories, Biotech Firms Packaging Type: Syringe Packs, Bulk Packs, Pre-filled Vials, Individually Packaged |
| Companies Covered | QIAGEN, Thermo Fisher Scientific, Merck KGaA, Promega Corporation, Zymo Research, Takara Bio, New England Biolabs, Agilent Technologies, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasmid Kits Market Trends and Innovations
Plasmid kit workflows are fragmenting into parallel tracks as research-grade automation converges with pharmaceutical-grade documentation requirements, forcing vendors to engineer dual-use platforms that bridge bench and GMP environments.
Alkaline lysis chemistry paired with anion exchange membranes is supplanting traditional silica spin columns in high-throughput bacterial processing, with gene therapy CDMOs adopting these systems for 24-hour plasmid turnaround on viral vector production schedules. The shift compresses downstream purification bottlenecks while reducing organic solvent waste volumes that complicate environmental compliance.
FDA's 2023 guidance on human gene therapy chemistry, manufacturing, and controls is elevating documentation burdens for plasmid suppliers seeking IND-enabling partnerships, requiring batch-level endotoxin certificates and raw material traceability that research-grade kit formats cannot provide. Cell-and-gene therapy developers are responding by consolidating procurement around vendors with established drug master files.
Consolidated vendor contracts are displacing fragmented reagent purchasing as biopharmaceutical procurement teams seek single-source accountability for plasmid quality failures that delay viral vector release. CDMOs in the United States are leading this consolidation, bundling kit supply with downstream analytics to compress vendor management overhead.
Plasmid Kits Market Segmentation
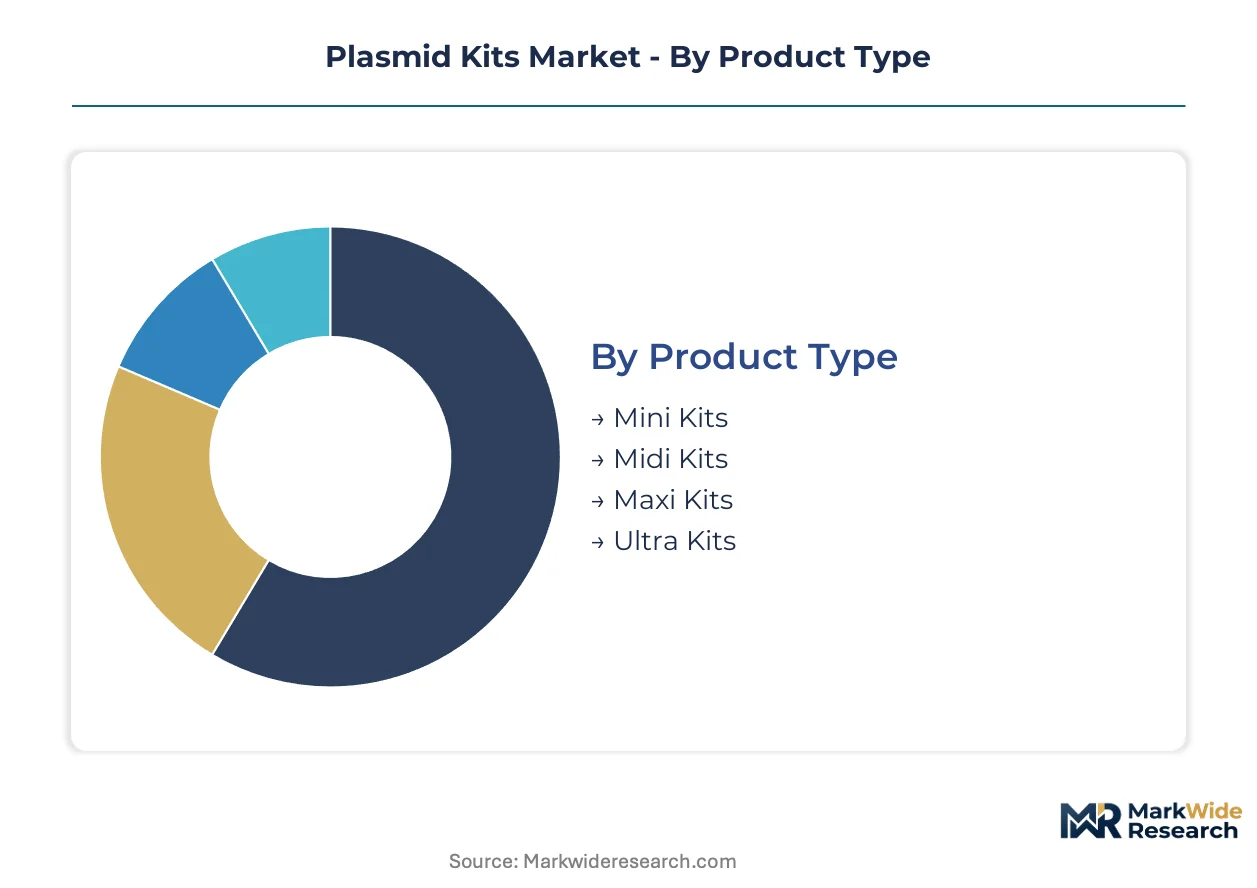
Plasmid kit segmentation reflects a bifurcation between high-volume research consumables and qualification-intensive clinical-grade formats. Channel strategy varies sharply across these tiers, with distributors dominating academic sales while direct vendor relationships govern pharmaceutical procurement.
Product Type:
Channel mix diverges by scale tier, with academic distributors pushing Mini formats through catalog sales while CDMOs negotiate direct supply agreements for Ultra-grade endotoxin-free production.
- Mini Kits:Bench-scale silica spin columns yielding 20-50 micrograms of plasmid DNA per prep. Academic core facilities in the United States purchase these through distributors like VWR and Fisher Scientific for routine cloning workflows where cost-per-prep dominates procurement decisions.
- Ultra Kits:Anion exchange membrane systems delivering endotoxin levels below 0.1 EU per microgram. Gene therapy CDMOs in Massachusetts and North Carolina require these for IND-enabling viral vector production, with vendors providing drug master file documentation alongside physical product.
- Midi Kits:Mid-scale purification for plasmid yields of 100-500 micrograms, bridging research and preclinical applications.
- Maxi Kits:High-capacity formats generating 1-10 milligrams, serving process development labs scaling toward GMP manufacturing.
By volume, Mini Kits leads. By growth pace, Ultra Kits is ahead.
Application:
Cost tier stratification separates commodity cloning reagents from premium transfection-grade products commanding 3-5x price multiples.
- Cloning:Routine subcloning and vector construction workflows consuming Mini Kit formats at highest velocity. Research laboratories prioritize cost efficiency over documentation depth.
- Transfection:Demands endotoxin-free plasmid for mammalian cell entry. Pharmaceutical companies in California and New Jersey pay premiums for certified low-endotoxin grades that eliminate cytotoxicity variables in gene therapy candidate screening.
- Gene Expression:Protein production workflows requiring high-purity template for bacterial or mammalian expression systems.
- DNA Sequencing:Sanger and next-generation sequencing preparation where template quality determines read accuracy.
Cloning generates the highest absolute volume. Transfection commands the steepest expansion trajectory as gene therapy pipelines mature.
End User:
Customer type determines margin structure, with academic buyers squeezing price points while biotech firms accept premium positioning for regulatory-ready documentation.
- Academic Institutions:Price-sensitive procurement through institutional purchasing cooperatives. Core facilities at universities in Texas and Pennsylvania negotiate volume discounts on Mini Kit formats for undergraduate teaching labs and principal investigator research groups.
- Pharmaceutical Companies:Integrated supply chain management with vendor qualification programs. Large-cap drug developers in Illinois and New York require ISO 13485-certified suppliers with established quality agreements and audit histories.
- Research Laboratories:Government and nonprofit institutes with hybrid procurement flexibility between distributor and direct channels.
- Biotech Firms:Venture-backed developers prioritizing speed-to-IND over unit cost, consolidating spend with single-source kit vendors offering bundled analytics.
Academic Institutions dominates unit volume. Pharmaceutical Companies is climbing the fastest as gene therapy manufacturing scales.
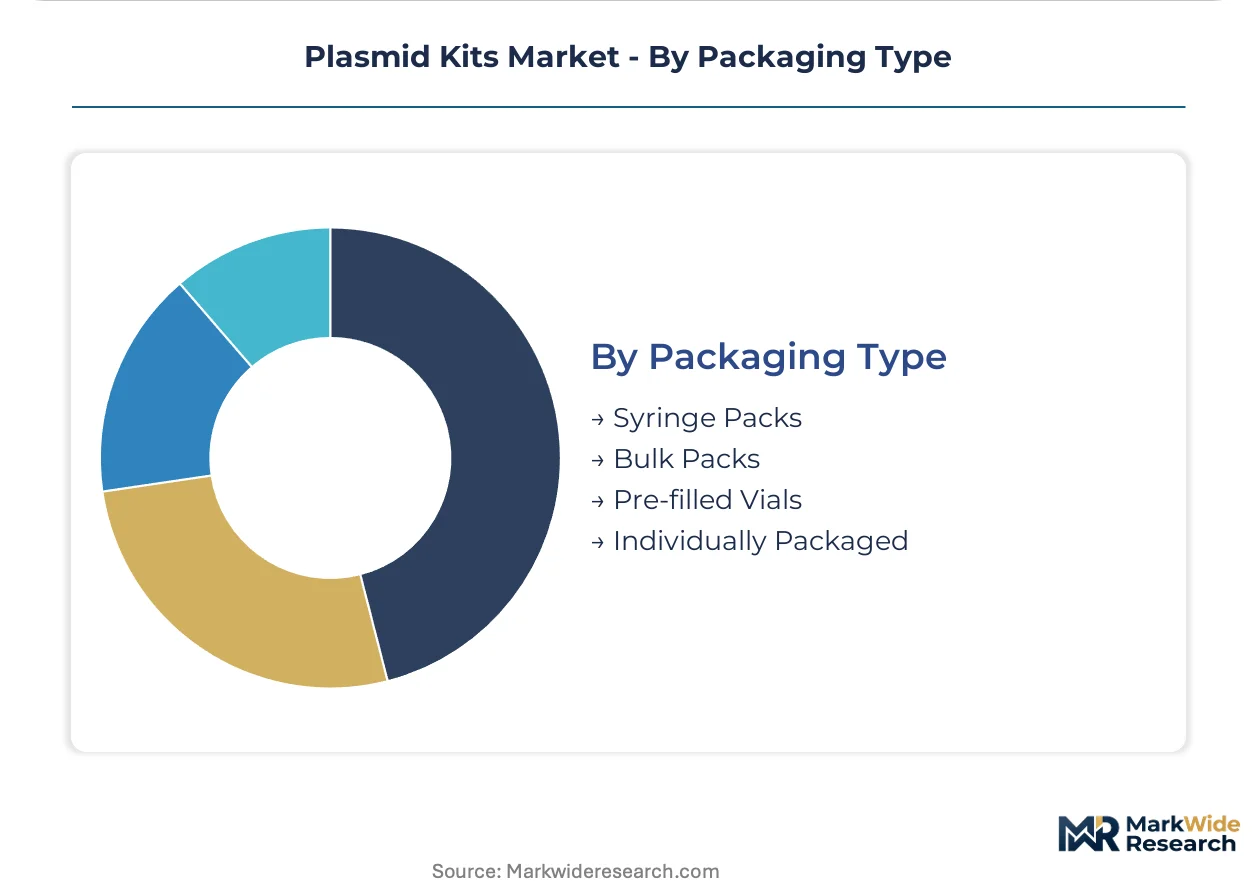
Packaging Type:
Supply concentration in Germany and Switzerland for EU GMP Annex 1-compliant filling operations shapes geographic availability of clinical-grade formats.
- Bulk Packs:Multi-prep containers reducing per-unit packaging cost for high-throughput academic core facilities. University of California system campuses purchase these for centralized genomics services processing thousands of bacterial cultures monthly.
- Pre-filled Vials:Single-use sterile containers eliminating reconstitution steps. CDMOs in Maryland and Massachusetts specify these for GMP environments where open-container manipulation risks contamination.
- Syringe Packs:Luer-lock compatible formats for direct injection into downstream purification systems.
- Individually Packaged:Unit-dose sterile barrier packaging for validated clinical workflows requiring lot-level traceability.
Bulk Packs leads by volume shipped. Pre-filled Vials is gaining share fastest as GMP manufacturing displaces research-grade workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German kit manufacturers export endotoxin-free Ultra formats to gene therapy CDMOs in Massachusetts and North Carolina, while Swiss filling operations supply pre-filled vials to European viral vector producers.
United States
FDA's 2023 gene therapy CMC guidance is tightening purity benchmarks for IND-enabling plasmid inputs. CDMOs in Massachusetts and North Carolina are expanding captive plasmid production capacity for AAV manufacturing. The National Institutes of Health funds academic core facilities purchasing Mini Kit formats through centralized procurement cooperatives.
Germany
EU GMP Annex 1 cleanroom standards concentrate clinical-grade kit filling operations in Baden-Württemberg and Bavaria. The country's national pharmaceutical regulator enforces documented plasmid provenance for advanced therapy medicinal products. Heidelberg and Munich host viral vector developers sourcing qualified endotoxin-free kits for lentivirus production.
Switzerland
Swissmedic certification requirements attract gene therapy developers seeking regulatory-ready documentation packages. Basel and Zurich house contract manufacturers specifying pre-filled vial formats for GMP environments. The country's precision manufacturing base supports automated magnetic bead purification system assembly.
India
The PLI scheme for biopharmaceutical manufacturing is drawing gene therapy developers toward lower-cost GMP plasmid production. CDSCO oversight is aligning with international nucleic acid therapeutic standards. Hyderabad and Bangalore clusters are emerging as demand centers for qualified kit suppliers serving export-oriented viral vector facilities.
United Kingdom
MHRA post-Brexit regulatory pathways are maintaining alignment with EMA ATMP frameworks for plasmid documentation. London and Cambridge biotech firms are consolidating procurement around ISO 13485-certified vendors. The Cell and Gene Therapy Catapult accelerates process development labs scaling toward GMP manufacturing workflows.
Plasmid Kits Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with publicly traded life science conglomerates anchoring the premium GMP segment while founder-held reagent houses dominate research-grade workflows. Market structure tilts toward consolidation at the clinical-grade extreme, where drug master file capabilities and audit histories create sticky vendor relationships. Three archetypes populate the competitive map: diversified conglomerates with end-to-end nucleic acid portfolios, enzymology specialists bundling reagent compatibility, and automation-focused system integrators. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as vendors seek to lock in CDMO procurement contracts before rival qualification timelines conclude.
Within the diversified conglomerate tier, QIAGEN and Thermo Fisher Scientific exemplify scale-driven positioning, while New England Biolabs occupies a specialist archetype emphasizing workflow integration. These three anchors demonstrate how geographic origin and corporate structure map to strategic emphasis: Dutch and American listed entities leverage global distribution infrastructure, while Massachusetts-based private operations concentrate on reagent-bundle stickiness.
| Leading Market Players |
|---|
| QIAGEN |
| Thermo Fisher Scientific |
| Merck KGaA |
| Promega Corporation |
| Zymo Research |
| Takara Bio |
| New England Biolabs |
| Agilent Technologies |
| Bio-Rad Laboratories |
| Others |
Pricing and Supply Chain Analysis
Magnetic bead purification systems replacing silica spin columns in mid-throughput workflows are redrawing manufacturing geography toward Swiss precision automation clusters while compressing per-prep pricing in the United States academic segment. This substitution simultaneously elevates capital requirements for kit vendors and fragments price-setting power between legacy membrane suppliers and automated platform integrators.
Pricing Analysis
Next-generation anion exchange membrane systems command 40-60% premiums over prior-generation silica spin columns, while economy-grade Mini Kits face persistent price erosion from distributor consolidation. Three-tier pricing structure across premium endotoxin-free, standard research-grade, and economy bulk-pack levels stratifies the market by certification depth. Pricing pressure stems from enzyme input cost volatility concentrated among European fermentation suppliers. Academic institutions exhibit highest price sensitivity, while gene therapy CDMOs prioritize documentation over unit cost.
Supply Chain Analysis
Germany and Switzerland anchor clinical-grade kit filling operations under EU GMP Annex 1 standards, while the United States concentrates research-grade manufacturing and magnetic bead system assembly. Lysozyme and RNase enzymes draw from a limited base of fermentation suppliers in Denmark and the Netherlands, creating single-source vulnerability for lysis buffer components. Distribution runs through academic distributors for Mini formats and direct vendor relationships for Ultra-grade clinical supply. Tariff exposure on European-sourced cleanroom components threatens margin stability for US-based kit assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plasmid kits market sits in early-cycle recovery as gene therapy manufacturing capacity expansion drives qualified kit demand following pandemic-era mRNA infrastructure overbuild. FDA purity benchmark tightening for IND-enabling studies provides the cyclical justification for vendor investment in GMP certification capacity.
For Market Incumbents: Consolidate procurement relationships with Massachusetts and North Carolina CDMOs through bundled analytics offerings that lock out research-grade competitors from clinical workflows. Deepen backward integration into endotoxin-free water and buffer production to offset European enzyme supplier concentration. Prioritize ISO 13485 certification maintenance as EMA ATMP documentation requirements stiffen vendor qualification barriers.
For New Entrants and Emerging Players: Lead with digital batch record capabilities that compress audit timelines for biotech firms seeking speed-to-IND, targeting venture-backed developers in Cambridge and South San Francisco with cloud-based chain-of-custody packages. Penetrate India's PLI-subsidized viral vector facilities before incumbent qualification timelines conclude, offering pre-filled vial formats aligned with CDSCO emerging standards.
For Investors and Strategic Acquirers: The market sits at a capacity-constrained phase that favors acquisition of GMP-certified specialists with established drug master files over research-grade volume players. Long-term viability hinges on regulatory documentation depth rather than manufacturing scale alone. Watch FDA warning letter trends for plasmid suppliers as an inflection signal for vendor consolidation urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| EU GMP Annex 1 Certification Investment | Unlocks pharmaceutical procurement contracts requiring documented cleanroom compliance for ATMP production. |
| Magnetic Bead Automation Platform Launch | Captures mid-throughput CRO demand in Massachusetts and North Carolina viral vector process development labs. |
| Drug Master File Establishment | Accelerates IND-enabling partnerships by pre-positioning regulatory documentation for FDA gene therapy CMC reviews. |
| Indian CDMO Supply Agreement | Secures foothold in PLI-subsidized biopharmaceutical manufacturing clusters ahead of competitor qualification. |
| Digital Batch Record Integration | Reduces client audit burden through cloud-based traceability systems aligned with FDA data integrity guidance. |
Research Methodology
Operator-level perspectives from gene therapy CDMO procurement directors, academic core facility managers, regulatory affairs leads at viral vector developers, and GMP quality auditors anchored the qualitative base. Secondary validation drew from FDA gene therapy CMC guidance documents, EMA ATMP framework publications, ClinicalTrials.gov plasmid-dependent trial registrations, and ISO 13485 certification databases. Bottom-up demand modeling across kit format tiers triangulated against top-down plasmid DNA production capacity estimates from viral vector manufacturing announcements.
Sensitivity analysis tested forecast outputs against alternative scenarios for FDA purity benchmark implementation timing and European enzyme supply disruption probability. The analytical framework segmented volume and value across product type, application, end user, and packaging format dimensions, with regional regulatory cluster as an additional modeling layer. CAGRs were derived from fitted growth curves incorporating AAV manufacturing scale-up trajectories and mRNA platform repurposing trends for personalized cancer vaccines.
The analysis sits within stated boundaries; outcomes outside sustained gene therapy clinical trial advancement or prolonged GMP auditor scarcity would require recalibration. Forecasts reflect assumptions regarding FDA-EMA regulatory harmonization persistence and cleanroom infrastructure buildout rates in Germany and Switzerland. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
Single-Use Bioreactor Bag Integrity and Leak Test Equipment Market
Biotechnology Equipment
Biodetectors and Accessories Market
Biotechnology Equipment
Cell Lysis Market
Biotechnology Equipment
Global Viral RNA Extraction Kit Market
Biotechnology Equipment
Transfection Reagents Market
Biotechnology Equipment
Small-Scale Bioreactors Market
Biotechnology Equipment
Moving Bed Bioreactor Market
Biotechnology Equipment
Global Biotechnology Reagents Market
Biotechnology Equipment
Global Biotechnology Market
Biotechnology Equipment
Automated Cell Culture Equipment Market
Biotechnology Equipment
United States Transfection Technologies Market
Biotechnology Equipment
IVF Workstation Market
Biotechnology Equipment
Ultracentrifuges Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Analytical Instrumentation in Life Science Market