
 Global Duchenne Muscular Dystrophy Drugs Market | 2026-2036
Global Duchenne Muscular Dystrophy Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Duchenne Muscular Dystrophy Drugs Market Foresight
Patient monitoring and long-term follow-up services bundled with one-time gene therapies is recalibrating revenue models away from chronic dosing. Sarepta Therapeutics leverages its early-mover position in exon-skipping and gene therapy platforms to anchor premium pricing power. PTC Therapeutics sustains diversified exposure across small-molecule and gene therapy modalities, while NS Pharma competes through regulatory exclusivity in Japanese and North American markets.
Duchenne muscular dystrophy therapeutics comprise pharmaceutical and biologic interventions targeting dystrophin restoration, inflammation suppression, and downstream pathophysiology mitigation in patients with X-linked recessive mutations. Gene therapy products deliver micro-dystrophin constructs via adeno-associated viral vectors to enable functional protein expression in skeletal and cardiac muscle. Exon-skipping agents currently occupy the most mature revenue tier with established reimbursement, while gene therapy represents the fastest-growing segment despite manufacturing complexity and durability questions. Corticosteroids retain volume leadership in emerging markets where advanced biologics remain inaccessible.
FDA accelerated approval pathways and EMA conditional marketing authorizations shape development priorities by rewarding surrogate endpoints that demonstrate dystrophin production. Pediatric hospital networks in Germany, the United Kingdom, and the United States serve as gatekeepers for patient access and real-world evidence generation. Stakeholders must weigh manufacturing scale commitments against evolving durability data and competitive readouts from late-stage pipeline assets.
Market Dynamics
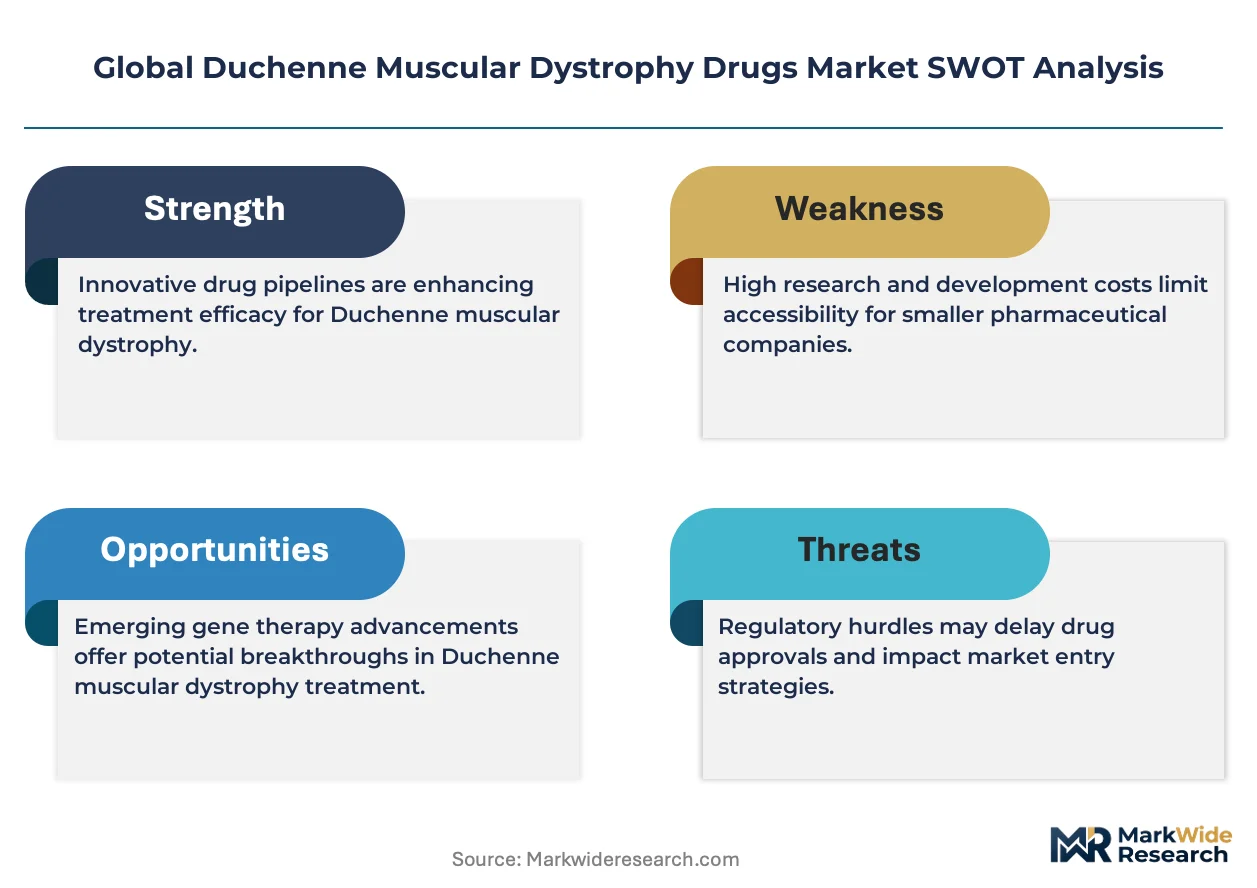
Gene therapy durability uncertainty is forcing developers to restructure clinical trial endpoints and post-market surveillance obligations. The FDA's accelerated approval framework rewards surrogate biomarker data while demanding lengthy confirmatory studies that reshape capital deployment timelines.
Growth Catalysts
- FDA Accelerated Approval Pathway:Surrogate endpoint acceptance compresses development timelines for dystrophin-restoration therapies. Pediatric treatment centers in the United States expand patient access infrastructure accordingly.
- Micro-dystrophin Vector Optimization:Improved adeno-associated viral delivery systems enhance transduction efficiency in cardiac and skeletal muscle tissue. Manufacturing scale-up investments follow platform validation milestones.
- Germany:University hospital networks in Munich and Heidelberg establish standardized neuromuscular care protocols that accelerate patient identification and therapy initiation timelines.
Market Restraints
- Plasmid DNA Supply Concentration:Limited qualified suppliers of GMP-grade plasmid vectors in North America and Europe create bottlenecks for viral vector production.
- EMA Conditional Marketing Authorization Requirements:Post-authorization efficacy studies impose ongoing clinical obligations that extend cost burdens beyond initial approval.
- Corticosteroid Standard of Care:Established chronic dosing regimens in emerging markets delay uptake of advanced biologics where healthcare budgets constrain reimbursement innovation.
Strategic Opportunities
- Brazil:ANVISA regulatory harmonization initiatives with FDA standards reduce duplicative filing requirements for gene therapy developers seeking Latin American market entry.
- Real-World Evidence Generation:Patient registries in the United Kingdom and France capture long-term functional outcomes that support label expansion and payer negotiations.
- Digital Biomarker Integration:Wearable accelerometry and smartphone-based functional assessments converge with telemedicine platforms to decentralize clinical monitoring.
Industry Challenges
- Gene Therapy Manufacturing Workforce:Scarcity of viral vector production specialists with GMP facility experience limits capacity expansion at contract manufacturing organizations.
- Cross-Border Sample Logistics:Temperature-controlled transport of patient-derived materials for autologous processing faces customs clearance friction between the United States and European Union member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Duchenne Muscular Dystrophy Drugs Market |
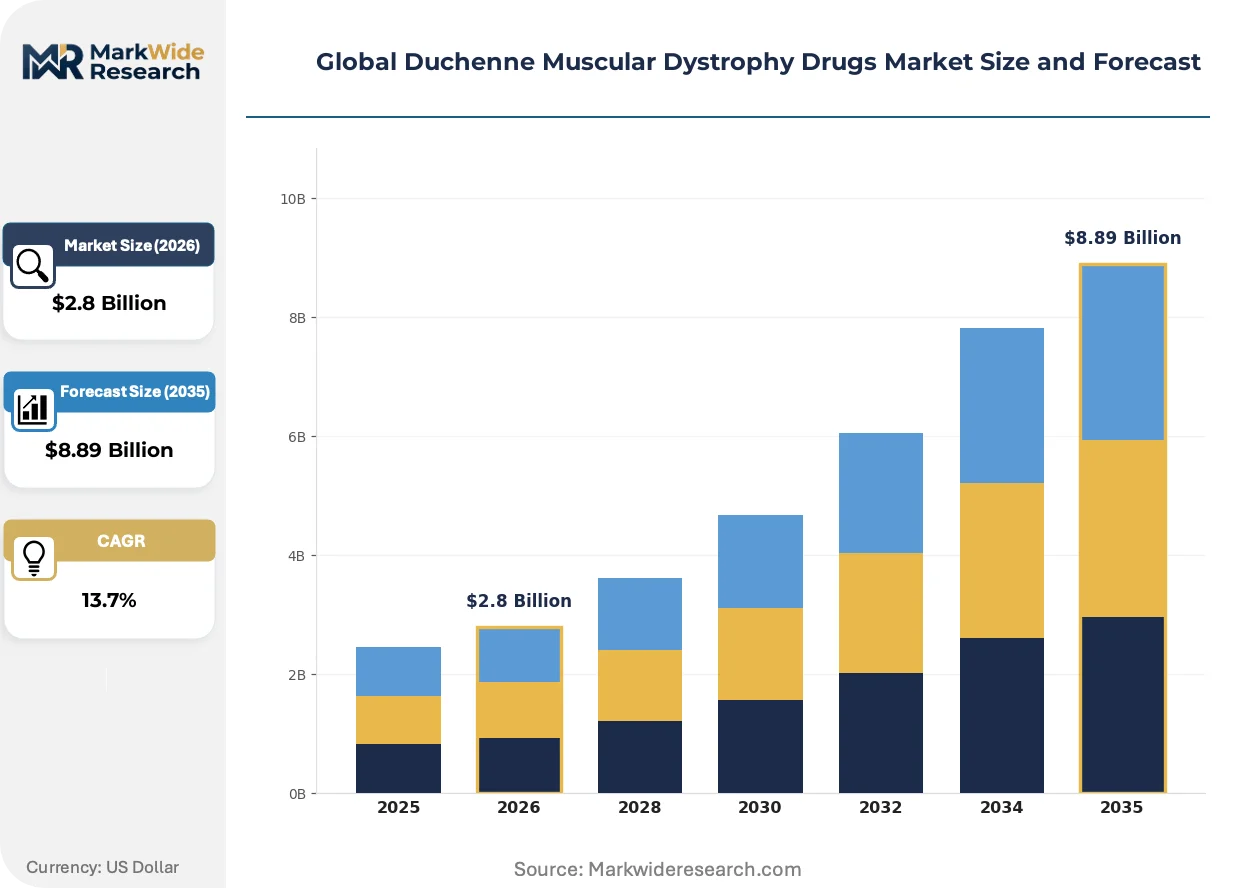
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $8.89 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Corticosteroids, Exon Skipping Agents, Utrophin Modulators, Anti-inflammatory Drugs Application: Cardiac Complications, Respiratory Support, Physical Rehabilitation, Neuromuscular Function Improvement, Skeletal Muscle Repair End User: Specialty Clinics, Research Institutions, Pediatric Hospitals, Neurology Centers, Genetic Counseling Centers Administration Route: Oral, Intravenous, Intramuscular, Subcutaneous, Intrathecal |
| Companies Covered | Sarepta Therapeutics, PTC Therapeutics, NS Pharma, ITALFARMACO S.p.A., Santhera Pharmaceuticals, FibroGen, Capricor Therapeutics, Catalyst Pharmaceuticals, Solid Biosciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Duchenne Muscular Dystrophy Drugs Market Shifts & Advancements
Next-generation delivery technologies and regulatory science advances are compressing the gap between mechanistic proof and functional clinical benefit. Developers now prioritize platforms that demonstrate measurable dystrophin restoration with durable expression profiles.
Dual-vector systems that split the micro-dystrophin coding sequence across two adeno-associated viral payloads are automating the packaging of larger therapeutic transgenes. Pediatric neuromuscular centers in Philadelphia and Boston adopt these platforms for early-phase trials. The technology is automating the resolution of payload size constraints that previously limited single-vector approaches.
REACH regulation updates in the European Union impose stricter disclosure requirements on viral vector manufacturing residuals and process-related impurities. Contract manufacturers in Germany and the Netherlands invest in analytical method development to meet evolving characterization standards. Exon-skipping oligonucleotide producers face the most significant compliance timeline pressure as they revalidate purification processes.
Hospital procurement committees increasingly unbundle gene therapy administration from long-term neuromuscular management contracts. United States children's hospitals in San Francisco and Cincinnati negotiate separate pricing for infusion logistics versus ongoing multidisciplinary care. This shift concentrates price transparency pressure on the one-time therapeutic dose while protecting margin on follow-up services.
Global Duchenne Muscular Dystrophy Drugs Market Segmentation
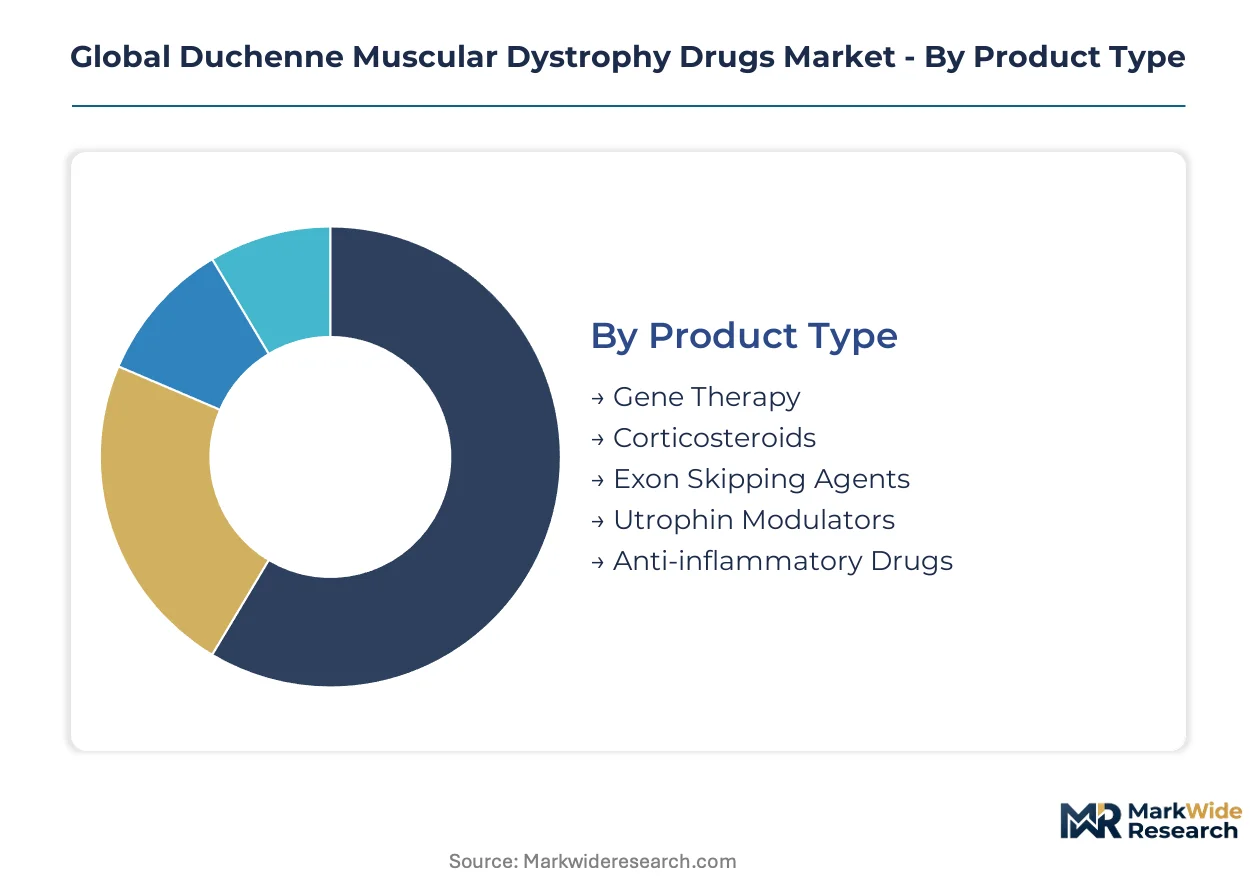
Segmentation in the Duchenne muscular dystrophy drugs market reveals how regulatory pathways, patient access infrastructure, and therapeutic mechanisms intersect to shape commercial viability. Distinct approval requirements and reimbursement frameworks apply across product modalities, creating tiered market entry barriers that concentrate investment in select segments.
Product Type:
FDA accelerated approval and EMA conditional authorization requirements vary sharply across these modalities, with gene therapy facing the most extensive chemistry, manufacturing, and controls scrutiny while corticosteroids navigate abbreviated pathways.
- Gene Therapy:Adeno-associated viral vectors deliver micro-dystrophin constructs to restore functional protein expression in skeletal and cardiac muscle. Demand concentrates in Boston, Philadelphia, and San Francisco pediatric treatment centers where specialized infusion infrastructure and long-term follow-up capabilities cluster.
- Corticosteroids:Chronic oral regimens of prednisone and deflazacort suppress inflammation and delay disease progression through established pharmacological mechanisms. Volume leadership persists in Brazil and India where healthcare budgets constrain access to advanced biologics and payer infrastructure favors generic substitution.
- Exon Skipping Agents:Antisense oligonucleotides enable selective mRNA splicing to restore reading frame and produce truncated but functional dystrophin.
- Utrophin Modulators:Small-molecule approaches upregulate utrophin as a functional dystrophin surrogate in muscle membrane stabilization.
- Anti-inflammatory Drugs:Adjunctive therapies target secondary pathophysiology including fibrosis and immune-mediated muscle damage.
Leading the category by volume: Corticosteroids. Growing fastest: Gene Therapy.
Application:
Clinical trial endpoints and payer value assessment frameworks prioritize functional outcomes differently across these indications, with cardiac and respiratory applications commanding premium reimbursement due to mortality impact.
- Cardiac Complications:Therapies targeting cardiomyopathy and arrhythmia prevention address the leading cause of mortality in Duchenne patients. German university hospital networks in Munich and Heidelberg drive adoption through standardized cardiac surveillance protocols that integrate emerging therapies into longitudinal care models.
- Respiratory Support:Interventions preserving pulmonary function extend survival and reduce hospitalization burden through mechanical ventilation alternatives and diaphragmatic strengthening. United Kingdom patient registries capture real-world respiratory outcomes that support NICE technology appraisals and label expansion negotiations.
- Physical Rehabilitation:Adjunctive pharmacological support for mobility preservation and contracture prevention.
- Neuromuscular Function Improvement:Primary dystrophin restoration approaches targeting muscle strength and ambulation.
- Skeletal Muscle Repair:Regenerative strategies addressing satellite cell dysfunction and muscle regeneration capacity.
Dominant by patient volume: Neuromuscular Function Improvement. Steepest expansion trajectory: Cardiac Complications.
End User:
Procurement authority and reimbursement decision-making diverge across these settings, with pediatric hospitals controlling gene therapy access while specialty clinics manage chronic corticosteroid prescribing.
- Specialty Clinics:Community-based neuromuscular practices coordinate chronic disease management and monitor treatment response between hospital-based interventions.
- Research Institutions:Academic medical centers conduct natural history studies and interventional trials that generate regulatory submission datasets.
- Pediatric Hospitals:Tertiary children's hospitals in Cincinnati and San Francisco administer one-time gene therapies through multidisciplinary teams. These institutions unbundle infusion logistics from longitudinal care, concentrating price transparency pressure on the therapeutic dose itself.
- Neurology Centers:Dedicated neuromuscular programs provide diagnostic confirmation and treatment initiation.
- Genetic Counseling Centers:Pre-symptomatic screening and family planning support services.
Highest procedure volume: Pediatric Hospitals. Fastest capacity expansion: Neurology Centers.
Administration Route:
Route selection determines manufacturing complexity, cold chain requirements, and site-of-care economics, with intravenous gene therapy demanding substantial infrastructure investment compared to oral chronic therapies.
- Intravenous:Systemic delivery of viral vectors and biologics enables broad tissue transduction but requires infusion center capacity and acute monitoring capabilities. Contract manufacturing organizations in Germany and the Netherlands scale GMP viral vector production to supply United States and European Union infusion networks.
- Oral:Corticosteroid and small-molecule administration supports patient adherence and decentralized prescribing. Emerging market access in Brazil depends on ANVISA regulatory harmonization initiatives that streamline filing requirements for oral formulations.
- Intramuscular:Localized delivery approaches targeting specific muscle groups.
- Subcutaneous:Alternative systemic delivery with reduced infusion center dependency.
- Intrathecal:Central nervous system targeting for cognitive and spinal cord manifestations.
Widest prescriber base: Oral. Most infrastructure-intensive: Intravenous.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gene therapy manufacturing concentrates in Germany and the Netherlands, while patient access infrastructure clusters around United States pediatric centers. Consumption patterns diverge sharply between markets with established reimbursement for advanced biologics and regions where corticosteroids retain volume leadership.
United States
FDA accelerated approval pathways compress development timelines for dystrophin-restoration therapies. The IRA price negotiation provisions reshape long-term revenue projections for gene therapy developers. Boston, Philadelphia, and San Francisco pediatric hospitals expand infusion center capacity and multidisciplinary care teams.
Germany
University hospital networks in Munich and Heidelberg establish standardized neuromuscular care protocols that accelerate patient identification. REACH regulation updates impose stricter disclosure requirements on viral vector manufacturing residuals. Contract manufacturers in the Netherlands and Germany invest in analytical method development for evolving characterization standards.
United Kingdom
NICE technology appraisals prioritize functional outcomes that support gene therapy reimbursement negotiations. Patient registries capture long-term respiratory and cardiac data that inform label expansion strategies. London and Cambridge research institutions conduct natural history studies generating regulatory submission datasets.
Japan
PMDA regulatory harmonization with FDA standards streamlines filing requirements for exon-skipping and gene therapy developers. METI funding programs support domestic manufacturing scale-up for viral vector production. Tokyo and Osaka pediatric neuromuscular centers adopt standardized cardiac surveillance protocols.
Brazil
ANVISA regulatory harmonization initiatives with FDA standards reduce duplicative filing requirements for gene therapy market entry. Healthcare budget constraints sustain corticosteroid volume leadership despite clinical guideline recommendations. São Paulo hospital procurement committees negotiate separate pricing for infusion logistics versus longitudinal care.
Global Duchenne Muscular Dystrophy Drugs Market Competitive Landscape
Top-tier vendors anchor gene therapy and exon-skipping platforms, while mid-tier developers compete through regulatory exclusivity in regional markets. The competitive structure concentrates around three strategic archetypes: platform-integrated biopharmaceuticals with manufacturing scale, specialty neuromuscular developers with regulatory pathway expertise, and emerging gene therapy players with vector optimization capabilities. Dominant competitive moves include strategic partnerships for manufacturing capacity access and portfolio diversification across small-molecule and biologic modalities.
Among United States-based platform developers, Sarepta Therapeutics and PTC Therapeutics exemplify the integrated biopharmaceutical archetype, occupying positions that span exon-skipping, gene therapy, and small-molecule modalities. NS Pharma represents the regulatory exclusivity-focused tier, anchoring market presence through Japanese and North American approval pathways. These three entities collectively illustrate how early-mover positioning in surrogate endpoint strategies and manufacturing scale commitments differentiate competitive standing.
| Leading Market Players |
|---|
| Sarepta Therapeutics |
| PTC Therapeutics |
| NS Pharma |
| ITALFARMACO S.p.A. |
| Santhera Pharmaceuticals |
| FibroGen |
| Capricor Therapeutics |
| Catalyst Pharmaceuticals |
| Solid Biosciences |
| Others |
Supply & Pricing Matrix
Captive viral vector production in Germany and the Netherlands anchors supply security and pricing power for gene therapy developers confronting GMP-grade plasmid scarcity. This backward integration choice concentrates margin control with platform-integrated biopharmaceuticals while contract manufacturers absorb residual price transparency pressure from unbundled infusion logistics.
Pricing Analysis
Price erosion across exon-skipping tiers traces to biosimilar entry dynamics and corticosteroid substitution in emerging markets. Three-tier pricing structure across premium gene therapy, standard exon-skipping, and economy corticosteroid levels stratifies by mechanism novelty and reimbursement sophistication. Cost-down pressure on one-time gene therapy doses accelerates because hospital procurement committees unbundle administration from longitudinal care. Emerging market buyers exhibit highest price sensitivity; United States pediatric hospitals demonstrate lowest sensitivity due to specialized infusion infrastructure and payer concentration.
Supply Chain Analysis
Workforce scarcity for viral vector production specialists constrains capacity expansion at contract manufacturing organizations in Germany, the Netherlands, and the United States. GMP-grade plasmid DNA supply concentrates in North American and European qualified suppliers, creating single-source vulnerability for AAV payload manufacturing. Raw material dependencies center on HEK293 cell banks, transfection reagents, and chromatography resins. Distribution runs through temperature-controlled logistics networks serving Boston, Philadelphia, and San Francisco pediatric infusion centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where manufacturing scale commitments and durability data generation determine competitive survival. Players pursue upstream control over GMP viral vector capacity as the decisive lever.
For Market Incumbents: To counter emerging dual-vector platform threats, Sarepta Therapeutics and PTC Therapeutics should deepen backward integration into plasmid DNA supply and expand cardiac-specific indication filings. Capacity addition in Germany and the Netherlands secures European market access against REACH regulation compliance timelines.
For New Entrants and Emerging Players: Enter via cardiac complication applications where functional outcome data commands premium reimbursement and competitive density remains lowest. Brazil offers the most penetrable geography through ANVISA regulatory harmonization with FDA standards. Go-to-market positioning should emphasize real-world evidence generation partnerships with United Kingdom patient registries.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-integrated biopharmaceutical acquisitions by large-cap rare disease specialists. Long-term viability hinges on durability data maturation across the analysis window. Acquisition targets should display vector optimization capabilities and established pediatric hospital relationships. The signal to watch is confirmatory study readouts from FDA accelerated approval mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | GMP viral vector capacity expansion in Germany and the Netherlands secures supply for FDA-accelerated approval timelines. |
| Regulatory Approval Pathway | EMA conditional marketing authorization demands post-authorization efficacy studies that reshape capital deployment. |
| Pipeline Diversification | Dual-vector systems targeting cardiac complications reduce payload size constraints and expand addressable indications. |
| Real-World Evidence Generation | United Kingdom and France patient registries capture long-term functional outcomes supporting NICE technology appraisals. |
| Strategic Partnership | Hospital procurement committee negotiations in San Francisco and Cincinnati unbundle gene therapy pricing from longitudinal care. |
Research Methodology
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, cross-referenced with formulary databases and hospital procurement records. Primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers validated commercial assumptions. Bottom-up and top-down triangulation reconciled patient population estimates with revenue projections across the analysis window.
Bottom-up modeling anchored volume forecasts to pediatric hospital capacity expansion in named United States cities and German university hospital network protocols. Top-down validation referenced IRA price negotiation provisions and EMA conditional authorization requirements as macro constraints. Segmentation dimensions included product modality, application indication, end-user setting, and administration route. CAGRs derived from slope analysis of dystrophin-restoration therapy adoption curves and corticosteroid volume persistence in emerging markets.
Revisions become necessary when gene therapy durability data diverges from surrogate endpoint assumptions or when plasmid DNA supply concentration triggers manufacturing bottlenecks. Forecasts reflect documented assumptions about FDA accelerated approval pathway stability and payer infrastructure evolution. Regulatory pathway modifications, manufacturing workforce scarcity intensification, or cross-border sample logistics friction represent specific risk factors. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Hemophilia Gene Therapy Market
Cell & Gene Therapy
Cancer Therapeutics Market
Cell & Gene Therapy
Ipilimumab Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Asia-Pacific Gene Therapy Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Retinitis Pigmentosa Treatment Market
Cell & Gene Therapy
B Cell Maturation Antigen Targeted Therapy Market
Cell & Gene Therapy
RNAI Technology Market
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
North America Cancer Vaccines Market
Cell & Gene Therapy
US Cell and Gene Therapy Clinical Trial Services Market