
 Gene Electroporators Market | 2026-2036
Gene Electroporators Market Size, Share, and Industry Trends Forecast 2026-2036
Gene Electroporators Market Insights
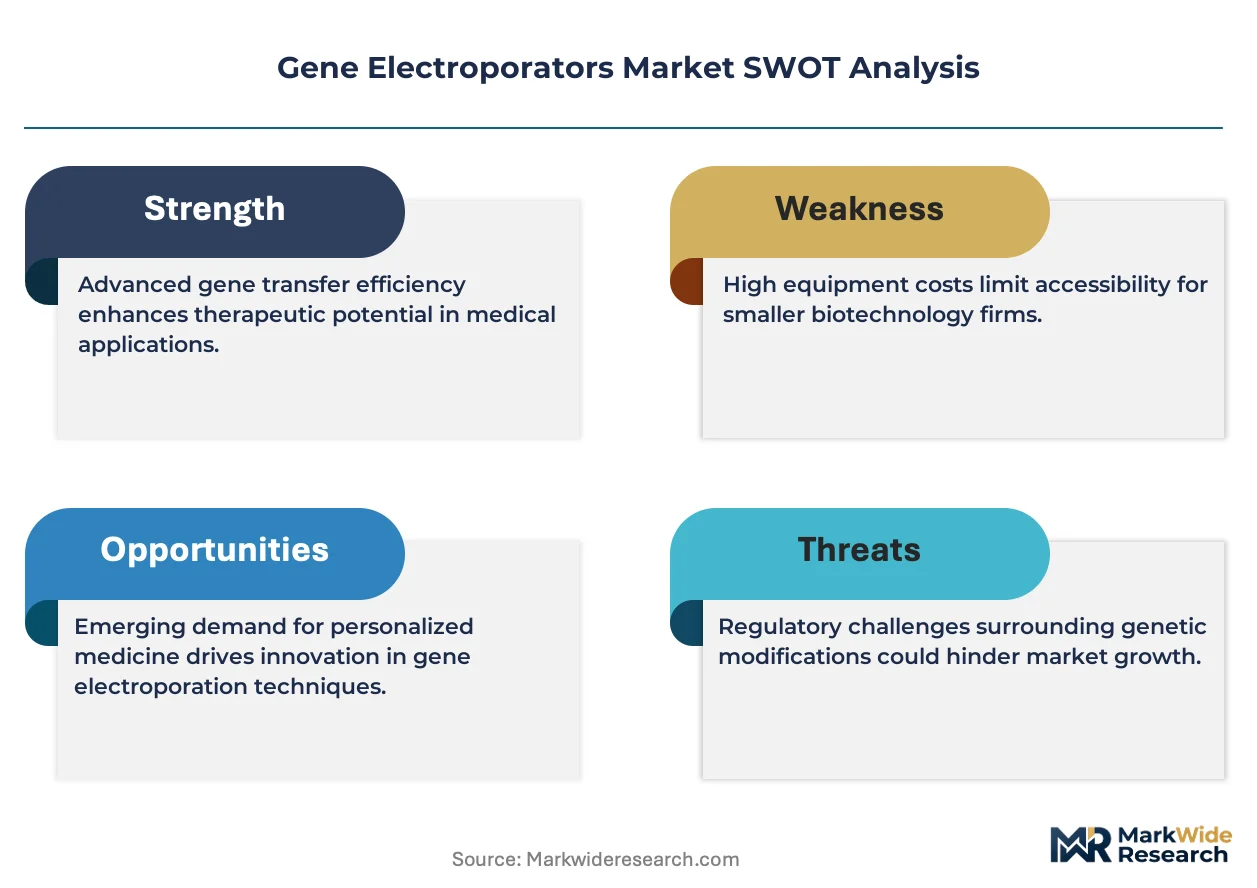
A capital-intensity divergence between players is bifurcating competitive dynamics in the gene electroporators landscape. Thermo Fisher Scientific leverages its integrated life sciences platform to sustain dominant positioning across research and clinical-grade instrument portfolios. Bio-Rad Laboratories anchors its presence through deep specialization in pulsed-field systems for cell transfection workflows. Lonza Group differentiates via upstream control over bioprocessing applications, occupying the high-value cell therapy manufacturing segment where electrical delivery precision determines regulatory outcomes.
Gene electroporators are electrical devices that apply controlled pulsed or continuous electric fields to transiently permeabilize cell membranes, enabling exogenous molecule entry with field strengths typically ranging from hundreds of volts per centimeter to several kilovolts per centimeter depending on cell type and application. Laboratory electroporators constitute the mature revenue base across academic settings, while micro electroporators represent the fastest-expanding category as miniaturization enables single-cell resolution in stem cell research and gene therapy development. Pulsed electric field technology leads installed capacity, though square wave technology commands premium positioning where transfection efficiency and cell viability trade-offs determine experimental success in DNA vaccination protocols.
FDA gene therapy guidance and EMA's ATMP framework shape electrical validation standards for clinical-grade electroporators, while ISO 13485 compliance requirements filter market access for manufacturers targeting pharmaceutical firms. Japan's PMDA imposes additional electromagnetic compatibility and biological safety testing on instruments destined for regenerative medicine applications. Stakeholders must monitor evolving electrical parameter disclosure mandates as regulators tighten traceability requirements for cell and gene therapy manufacturing workflows.
Market Dynamics
CRISPR workflow standardization in academic and clinical settings is compressing instrument replacement cycles while elevating electrical parameter validation requirements across procurement specifications.
Growth Catalysts
- EMA ATMP Framework:The EU's advanced therapy medicinal products regulation mandates traceable electrical delivery parameters, forcing pharmaceutical manufacturers to upgrade to validated electroporation systems.
- Cell Therapy Manufacturing Clusters:Concentrated bioprocessing facilities in the United States, Germany, and Japan require GMP-compliant instruments with documented field strength reproducibility.
- Square Wave Technology:Enhanced transfection efficiency in DNA vaccination protocols drives replacement of legacy pulsed-field systems in vaccine development pipelines.
Market Restraints
- Precision Electronics Supply Concentration:High-voltage pulse generators and specialized capacitors concentrate among a limited supplier base in Japan and Germany, creating input vulnerability.
- ISO 13485 Certification Timeline:Medical device quality management system compliance requires 12-18 month validation cycles that delay market entry for new manufacturers.
- Optical Transfection Substitution:Laser-based membrane permeabilization methods compete for single-cell applications in stem cell research, constraining micro electroporator pricing power.
Strategic Opportunities
- India CDSCO Pathway:The country's emerging gene therapy regulatory framework creates first-mover positioning for instrument manufacturers establishing local validation partnerships.
- Point-of-Care Manufacturing:Decentralized cell therapy production requires portable electroporation units with embedded compliance documentation.
- AI-Assisted Parameter Optimization:Machine learning integration with electroporation control systems enables adaptive field modulation based on real-time impedance feedback.
Industry Challenges
- Bioelectrical Engineering Talent Scarcity:The intersection of cell biology and high-voltage electronics engineering lacks trained practitioners, extending R&D timelines for instrument developers.
- Legacy System Integration:New electroporators must interface with existing laboratory information management systems and automated liquid handling platforms, complicating deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gene Electroporators Market |
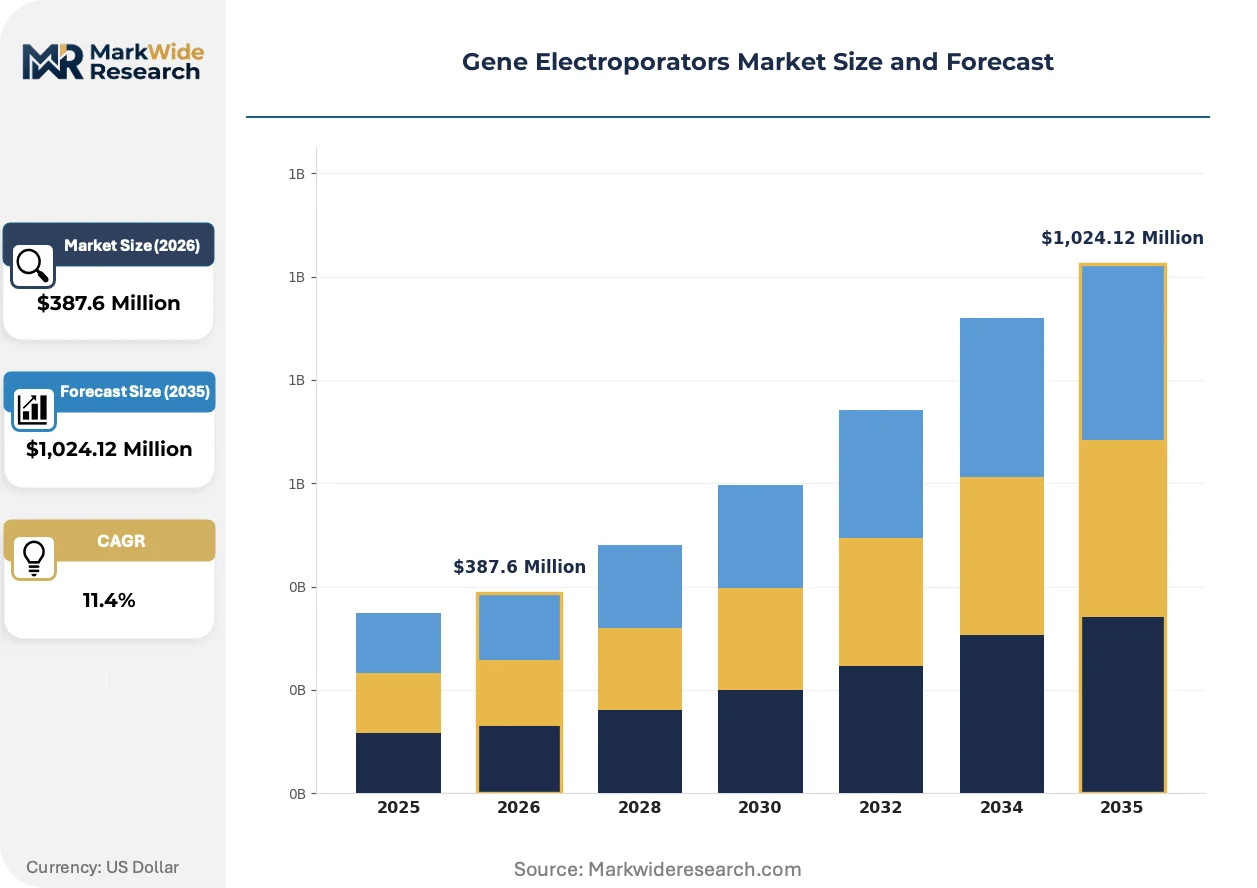
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laboratory Electroporators, Micro Electroporators, High-Voltage Electroporators, Portable Electroporators Application: Gene Therapy, DNA Vaccination, Cell Transfection, Stem Cell Research End User: Research Laboratories, Biotechnology Companies, Pharmaceutical Firms, Academic Institutions Technology: Pulsed Electric Field, Continuous Electric Field, Square Wave Technology, RF Electroporation |
| Companies Covered | Thermo Fisher Scientific, Bio-Rad Laboratories, Lonza Group, Eppendorf, MaxCyte, Harvard Bioscience, Nepa Gene, BEX Co., Ltd., Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gene Electroporators Market Trends and Innovations
Miniaturization and intelligent control systems are redefining competitive differentiation in gene electroporation, shifting value capture from hardware margins to software-enabled workflow integration.
Microfluidic electroporation platforms is bifurcating the research instrument category. These devices integrate cell handling and electrical delivery within single-use cartridges, eliminating manual transfer steps. Stem cell laboratories and gene therapy startups in the United States and Japan are adopting these systems at accelerated replacement cycles. The technology is bifurcating vendor revenue models toward consumable-anchored economics while compressing traditional benchtop instrument margins.
EMA's tightened electrical parameter disclosure requirements for ATMP manufacturing are reshaping instrument specification standards. The regulation now mandates documented pulse waveform capture and storage for each transfection batch. Pharmaceutical electroporator procurement in Germany, France, and Switzerland now prioritizes systems with embedded data integrity features. Manufacturers are responding by integrating blockchain-anchored audit trails and encrypted parameter logging.
Service unbundling from hardware sales is altering channel economics in the academic segment. Research institutions now demand à-la-carte calibration contracts and remote diagnostic access rather than bundled maintenance agreements. Distributors in the United States and United Kingdom are restructuring compensation to prioritize recurring service revenue over upfront instrument margins. This shift concentrates aftermarket relationships with specialized field service organizations possessing electrical engineering expertise.
Gene Electroporators Market Segmentation
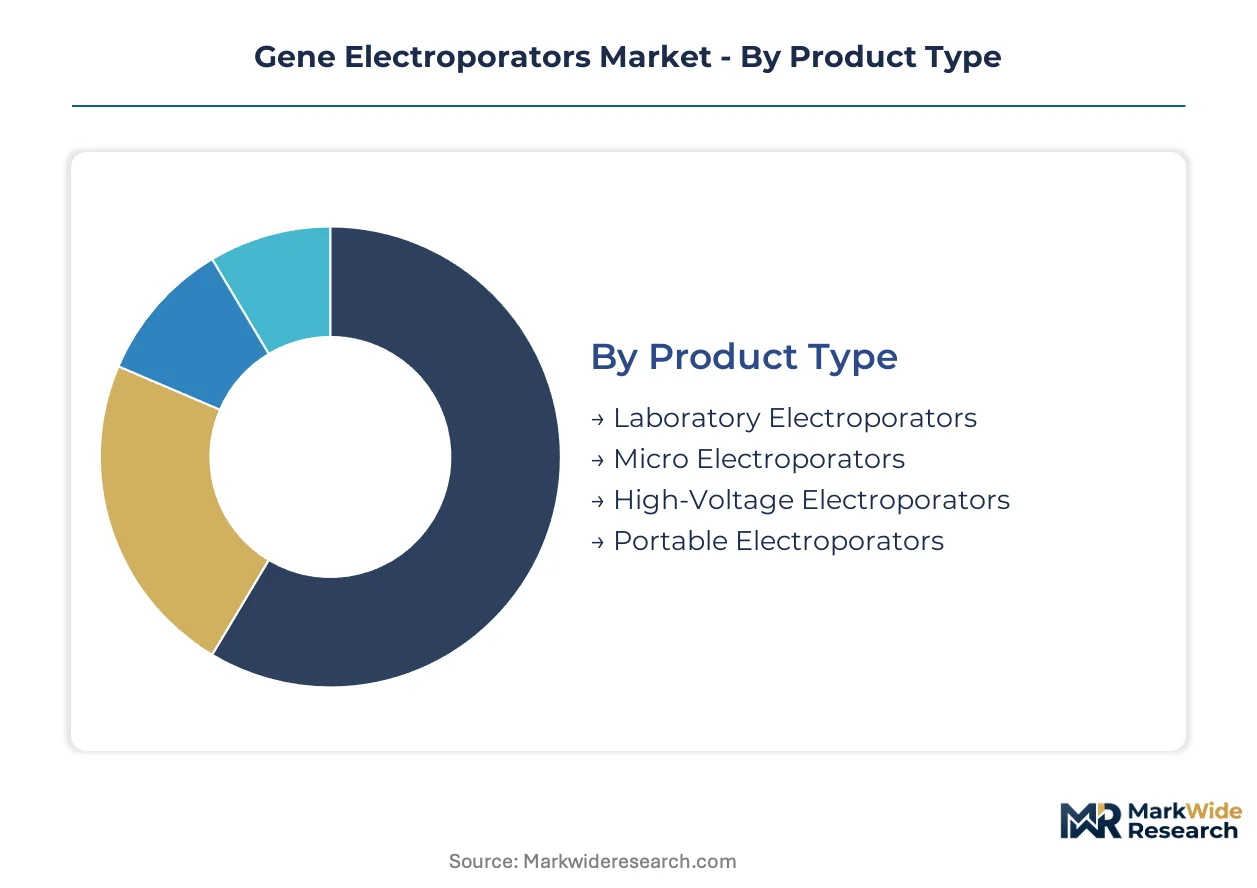
Electroporator procurement specifications diverge sharply across research and clinical environments, with regulatory validation requirements determining instrument category selection. Pharmaceutical manufacturers prioritize traceable electrical parameters over throughput metrics, while academic laboratories optimize for experimental flexibility and capital efficiency.
Product Type:
FDA and EMA validation mandates create tiered compliance requirements that stratify instrument demand across manufacturing and research settings.
- Laboratory Electroporators:Benchtop systems with modular electrode configurations dominate academic procurement in the United States and Germany. CRISPR workflow standardization at research universities drives replacement cycles as laboratories upgrade for higher-throughput nucleic acid delivery.
- Micro Electroporators:Miniaturized platforms achieving single-cell resolution through microfluidic integration. Stem cell laboratories in Japan and gene therapy startups in Germany adopt these systems for precise transfection control where cell viability determines experimental validity.
- High-Voltage Electroporators:Industrial-scale systems engineered for GMP-compliant cell therapy manufacturing with documented field strength reproducibility.
- Portable Electroporators:Battery-powered units enabling point-of-care cell modification in decentralized therapeutic settings.
Established volume favors laboratory electroporators; emerging adoption favors micro electroporators.
Application:
Cell therapy manufacturing economics concentrate investment in applications with direct regulatory pathways to commercial approval.
- Gene Therapy:Viral and non-viral vector delivery protocols requiring precise electrical parameter control for patient-grade cell modification. United States-based contract development organizations prioritize systems with embedded batch documentation to satisfy FDA gene therapy guidance.
- DNA Vaccination:Square wave electroporation enhances immunogen expression efficiency in prophylactic and therapeutic vaccine development. German and French vaccine manufacturers replace legacy pulsed-field systems to improve transfection consistency in clinical trials.
- Cell Transfection:General-purpose nucleic acid delivery for protein expression and functional genomics research.
- Stem Cell Research:Pluripotent cell modification requiring gentle electrical parameters to preserve differentiation capacity.
Gene therapy commands premium instrument specifications; DNA vaccination shows steepest expansion trajectory as vaccine platforms proliferate.
End User:
Procurement authority and validation requirements differ fundamentally between discovery research and commercial manufacturing organizations.
- Research Laboratories:Academic and government facilities prioritizing experimental versatility and capital cost containment. United States research institutions increasingly demand à-la-carte service contracts rather than bundled maintenance agreements.
- Biotechnology Companies:Venture-funded startups and mid-cap developers requiring scalable platforms that transition from discovery to preclinical stages.
- Pharmaceutical Firms:Large manufacturers with dedicated ATMP manufacturing facilities in Germany, Switzerland, and Japan. EMA electrical parameter disclosure mandates drive procurement of systems with encrypted audit trails and waveform capture capabilities.
- Academic Institutions:University core facilities serving multiple principal investigators with diverse experimental requirements.
Pharmaceutical procurement concentrates in validated high-value systems; biotechnology companies represent the fastest-climbing customer segment.
Technology:
Electrical waveform characteristics determine transfection efficiency, cell viability trade-offs, and regulatory qualification complexity.
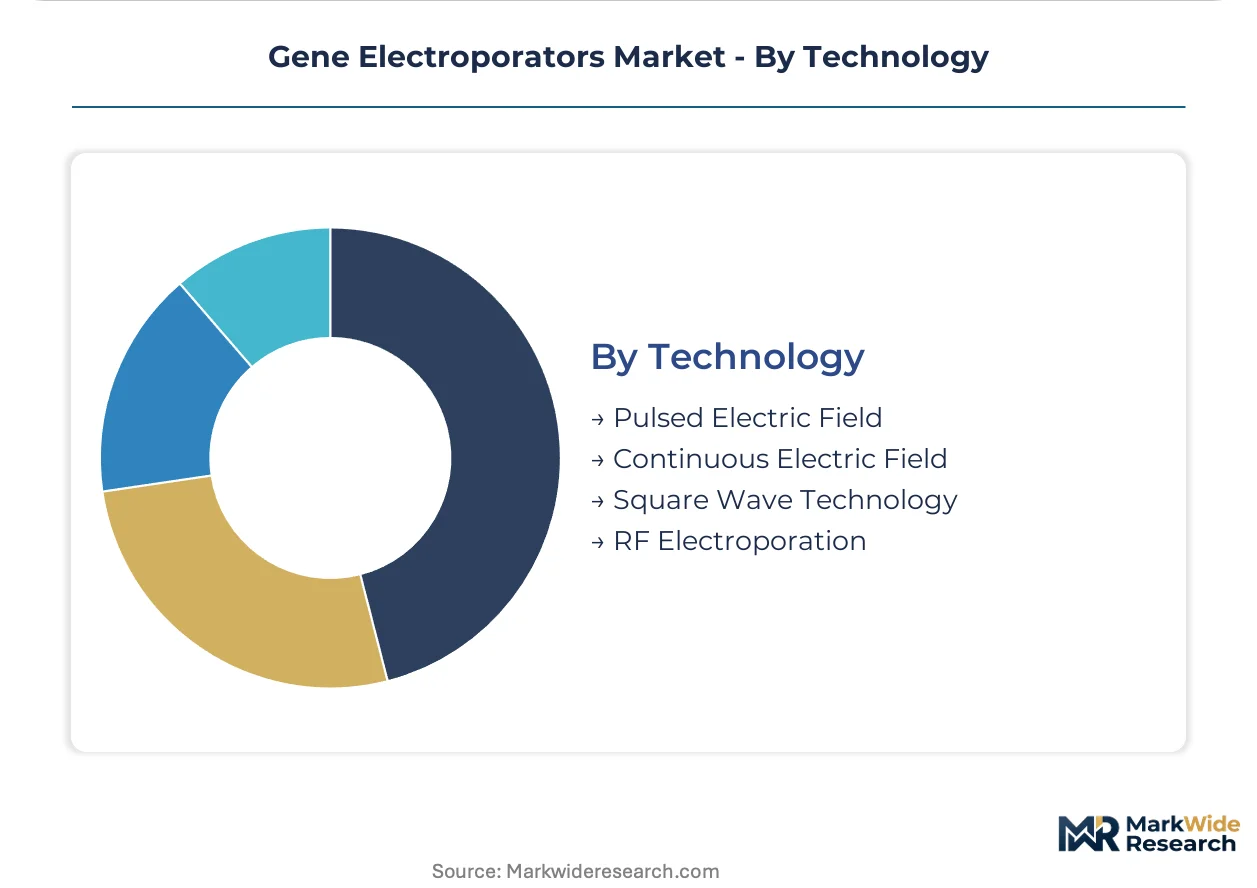
- Pulsed Electric Field:Exponential decay pulse generation constitutes the installed base across research settings. Legacy system replacement accelerates in European academic institutions as CRISPR protocols demand more precise electrical delivery control.
- Square Wave Technology:Precise pulse amplitude and duration control enables optimization of transfection efficiency versus cell mortality. Vaccine developers in Germany and cell therapy manufacturers in Japan command premium pricing for these systems where batch consistency determines regulatory approval.
- Continuous Electric Field:Sustained field application for specific membrane permeabilization protocols in specialized research applications.
- RF Electroporation:Radio frequency-based delivery reducing thermal damage in sensitive primary cell applications.
Pulsed electric field technology holds established installed base; square wave systems gain share fastest in clinical-grade applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German and Swiss manufacturing clusters where EMA validation requirements command premium instrument specifications, while United States procurement optimizes for throughput scale over unit margins.
United States
Cell therapy contract development organizations in Greater Boston and the San Francisco Bay Area drive demand for GMP-compliant systems with embedded batch documentation. FDA gene therapy guidance mandates traceable electrical parameters for patient-grade cell modification. Manufacturing clusters in Maryland and North Carolina require instruments with encrypted audit trails to satisfy regulatory inspection protocols.
Germany
Vaccine developers in the Rhine-Ruhr region and cell therapy manufacturers in Baden-Württemberg prioritize square wave systems for transfection consistency. EMA's ATMP framework mandates documented pulse waveform capture and storage for each transfection batch. The Munich and Heidelberg biotech corridors concentrate procurement of high-throughput systems for CRISPR workflows.
Japan
Stem cell laboratories in the Kanto region and regenerative medicine facilities in Kansai drive adoption of micro electroporators for single-cell resolution applications. PMDA imposes additional electromagnetic compatibility and biological safety testing on instruments destined for cell therapy manufacturing. The Yokohama and Osaka clusters require GMP-compliant instruments with documented field strength reproducibility.
Switzerland
Pharmaceutical manufacturers in Basel and Zurich prioritize validated high-value systems with blockchain-anchored audit trails. Swissmedic alignment with EMA electrical parameter disclosure requirements shapes procurement specifications for ATMP manufacturing. The country's precision engineering heritage supports domestic demand for instruments with embedded data integrity features.
India
Research institutions in Maharashtra and Karnataka accelerate adoption of laboratory electroporators as CRISPR workflows standardize across academic settings. CDSCO's emerging gene therapy regulatory framework creates first-mover positioning for manufacturers establishing local validation partnerships. The Bangalore and Hyderabad biotech clusters represent the fastest-climbing demand segment for scalable platforms transitioning from discovery to preclinical stages.
Gene Electroporators Market Competitive Landscape
Concentration sits with diversified life sciences conglomerates that leverage integrated platforms to sustain positioning across research and clinical-grade portfolios. Three archetypes define competitive structure: platform conglomerates with upstream control over bioprocessing applications, pulsed-field specialists anchoring presence through deep workflow integration, and emerging microfluidic innovators capturing consumable-anchored revenue models. Dominant competitive moves include strategic partnerships for regulatory validation acceleration and backward integration into precision electronics supply chains.
Among diversified platform providers, Thermo Fisher Scientific and Bio-Rad Laboratories exemplify archetypes spanning research through clinical applications. Lonza Group occupies a position within the bioprocessing-integrated tier where electrical delivery precision determines regulatory outcomes. Eppendorf and MaxCyte represent specialists in modular and high-throughput configurations respectively. Japanese manufacturers Nepa Gene and BEX Co., Ltd. anchor the precision electronics tier with concentration in pulsed-field and micro electroporation technologies. Harvard Bioscience and Merck KGaA sit within the diversified research instrumentation and chemical supply tiers.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Bio-Rad Laboratories |
| Lonza Group |
| Eppendorf |
| MaxCyte |
| Harvard Bioscience |
| Nepa Gene |
| BEX Co., Ltd. |
| Merck KGaA |
| Others |
Pricing and Supply Chain Analysis
Square wave generator adoption in clinical-grade systems is displacing legacy pulsed-field architectures, simultaneously shifting procurement toward Japanese and German precision electronics suppliers while compressing margins on standardized laboratory instruments. This substitution dynamic concentrates pricing power with vendors controlling high-voltage pulse generation capabilities, while research-tier manufacturers face cost compression from optical transfection alternatives.
Pricing Analysis
The customization-premium spread separates GMP-validated systems with encrypted audit trails from modular benchtop configurations. Pricing stratifies across premium, standard, and economy tiers based on FDA/EMA certification grade and embedded data integrity features. Cost compression in the research segment is intensifying because microfluidic consumable-anchored models displace traditional instrument sales. Academic laboratories exhibit highest price sensitivity; pharmaceutical ATMP manufacturers show lowest sensitivity due to regulatory compliance requirements.
Supply Chain Analysis
Extended lead times for high-voltage capacitors and precision pulse generators now stretch 16-24 weeks, constraining instrument assembly schedules. Manufacturing draws from concentrated precision electronics suppliers in Japan and Germany, with secondary sourcing from South Korean semiconductor foundries. Critical dependencies include specialized high-voltage MOSFETs, ceramic capacitors, and microfluidic cartridge substrates. Single-source vulnerability in Japanese capacitor supply creates exposure to trade flow disruptions. Distribution runs through specialized life sciences distributors with field service engineering capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene electroporator incumbents must defend against optical transfection and laser-based membrane permeabilization methods that capture single-cell applications in stem cell research. Substitution defense requires preemptive moves to secure precision electronics supply and embed software-enabled workflow integration.
For Market Incumbents: Compound regulatory validation advantages by accelerating EMA ATMP framework pre-certification for next-generation systems. Secure backward integration into high-voltage pulse generator supply through captive partnerships with Japanese precision electronics manufacturers. Deepen software companion development for AI-assisted parameter optimization to create switching costs against optical transfection substitutes. For New Entrants and Emerging Players: Remote diagnostic and à-la-carte calibration service gaps in the academic segment offer white-space entry points. Target United States research institutions with unbundled service contracts that specialized field service organizations currently under-serve. Pursue point-of-care portable electroporator development for decentralized cell therapy manufacturing, leveraging India's emerging CDSCO pathway for first-mover regulatory positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed precision electronics specialists possessing high-voltage pulse generation IP. Five-to-ten year viability hinges on regulatory validation moats rather than hardware margins alone. Monitor EMA electrical parameter disclosure mandate enforcement intensity as the inflection signal for premium system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Certification Investment | EMA ATMP framework compliance accelerates pharmaceutical procurement cycles in Germany and Switzerland. |
| Backward Integration into Pulse Electronics | Captive supply of Japanese high-voltage capacitors insulates against 16-24 week lead time volatility. |
| AI-Assisted Parameter Optimization Launch | Machine learning integration with impedance feedback enables adaptive field modulation for CRISPR workflows. |
| Microfluidic Consumable Platform Development | Single-use cartridge economics capture recurring revenue from stem cell laboratories in Japan. |
| Point-of-Care Portable System Development | Battery-powered units address decentralized cell therapy manufacturing demand in United States clusters. |
Research Methodology
Cross-validation between primary interviews with bioprocessing engineers and secondary validation through FDA gene therapy guidance documents anchors the qualitative findings. The research team conducted structured discussions with cell therapy manufacturing directors, regulatory affairs specialists at ATMP facilities, academic core facility managers, and precision electronics procurement leads. Secondary sources included EMA ATMP framework publications, ISO 13485 certification databases, PMDA electromagnetic compatibility standards, and customs trade data for high-voltage electronic components. Bottom-up instrument shipment analysis triangulates against top-down pharmaceutical capital expenditure tracking.
Sensitivity analysis around CRISPR workflow adoption rates and EMA enforcement intensity tests forecast robustness across the projection horizon. The analytical framework models segmentation dimensions including product type, application, end user, and technology waveform characteristics. CAGRs derive from installed base replacement cycle analysis and emerging segment penetration curves. Industry-specific inputs include cell therapy manufacturing cluster expansion timelines and square wave technology substitution rates in vaccine development pipelines.
Forecasts assume regulatory continuity in FDA gene therapy guidance and EMA ATMP framework enforcement; material policy shifts in Japan's PMDA regenerative medicine standards or India's CDSCO emerging pathway would require re-modeling. Specific risk factors include precision electronics supply disruption and optical transfection technology advancement. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Regenerative Therapies Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Drug Delivery in Cancer Market
Cell & Gene Therapy
Cell Therapy Market
Cell & Gene Therapy
Autologous Cell Therapy Market
Cell & Gene Therapy
Global Cell and Gene Therapy Manufacturing Services Market
Cell & Gene Therapy
Niemann-Pick Disease Type C (NPC) Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market
Cell & Gene Therapy
Cell Therapy Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Global Cancer Vaccine Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Drugs Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Asia-Pacific Gene Therapy Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Protein Degeneration Therapy Market
Cell & Gene Therapy
RNAI Technology Market