
 Autologous Cell Therapy Market | 2026-2036
Autologous Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Autologous Cell Therapy Market Intelligence
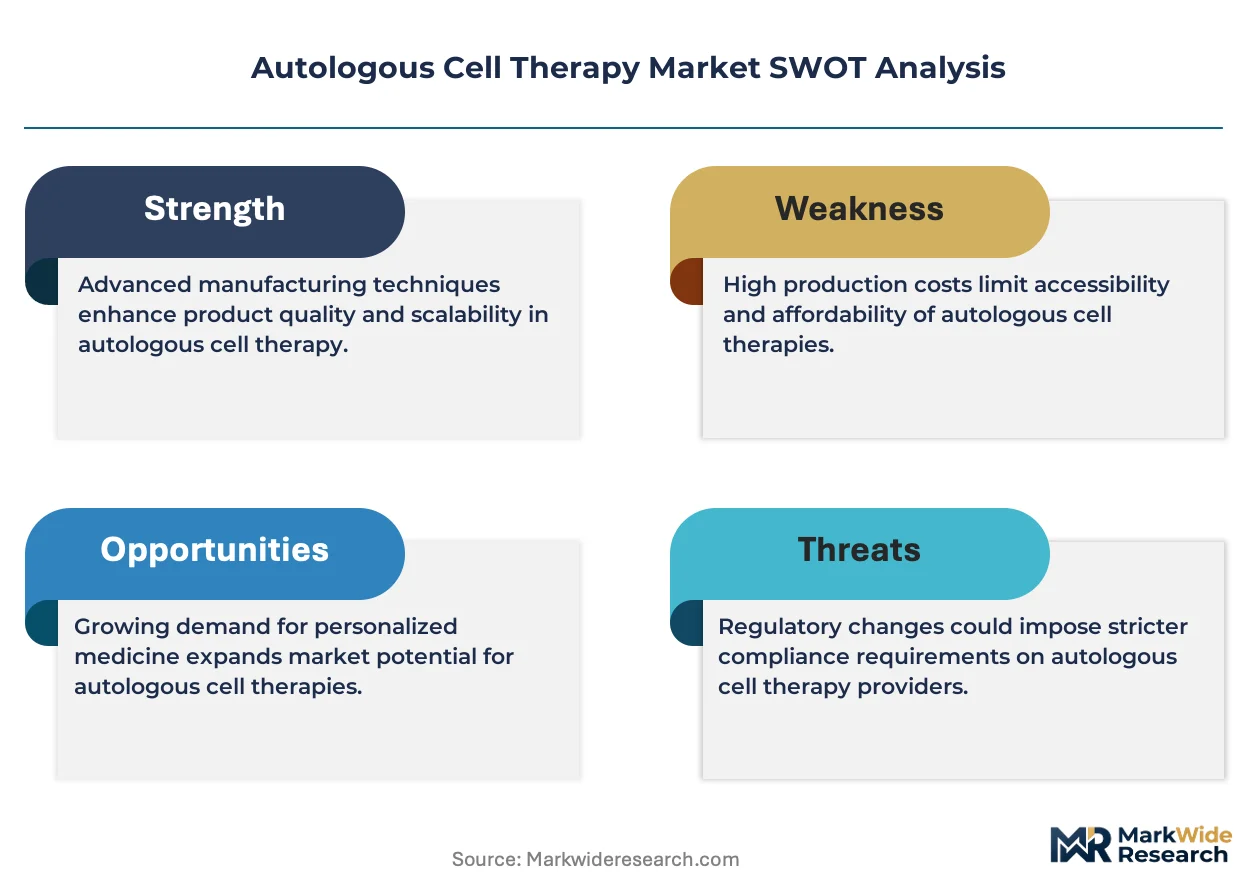
A shortage of certified cell-processing technicians is redrawing manufacturing capacity maps across the autologous cell therapy sector. Novartis AG leverages its established viral vector supply network to secure production slots at contract development organizations. Gilead Sciences, Inc. sustains dual-site manufacturing for its approved lymphoma therapies, reducing patient wait times. Bristol-Myers Squibb Company anchors its position through integrated apheresis-to-infusion logistics platforms that control cold-chain handoffs.
Autologous cell therapy involves harvesting a patient's own cells, expanding or modifying them ex vivo, and reinfusing them to treat disease. The process demands ISO 5 cleanroom environments, cryopreservation at minus 150 degrees Celsius, and chain-of-identity tracking across each batch. T cell products command the dominant revenue share given CAR-T approvals in hematologic malignancies, while platelet-rich plasma applications in orthopedics represent a mature, lower-margin segment. Stem cell therapies for cardiology remain pre-commercial but attract concentrated R&D investment from specialized clinics.
FDA's regenerative medicine advanced therapy designation and EMA's priority medicines pathway create divergent market access timelines across jurisdictions. ISO 14644 cleanroom standards and FACT-JACIE accreditation requirements filter which treatment centers qualify to administer commercial products. Stakeholders must monitor payer evidence requirements as health technology assessment bodies tighten criteria for patient-specific therapies.
Market Dynamics
Manufacturing capacity for patient-specific cell therapies concentrates at fewer than two dozen ISO 5-certified facilities worldwide, creating a supply chokepoint that shapes competitive positioning more than R&D pipelines.
Growth Catalysts
- FDA Regenerative Medicine Advanced Therapy designation:This pathway compresses clinical development timelines by enabling earlier approval based on surrogate endpoints, accelerating commercialization for qualifying autologous products.
- Academic medical center expansion:Oncology departments at major teaching hospitals are building in-house apheresis and cryopreservation capabilities, reducing reliance on centralized manufacturing networks.
- Automated cell processing platforms:Closed-system bioreactors and robotic fill-finish lines are displacing manual cleanroom operations, expanding batch throughput at existing facilities.
Market Restraints
- Viral vector supply concentration:Lentiviral and retroviral vector production remains captive to a handful of contract manufacturers, with lead times extending twelve to eighteen months for new entrants.
- Reimbursement uncertainty:Medicare's inpatient prospective payment system bundles CAR-T therapy into diagnosis-related groups, creating margin pressure at community hospitals.
- Cryopreservation logistics:Liquid nitrogen supply chains and vapor-phase storage infrastructure require specialized trucking networks that fragment distribution economics.
Strategic Opportunities
- Point-of-care manufacturing:Decentralized cell processing at treatment centers could eliminate cold-chain complexity and reduce vein-to-vein times from weeks to days.
- EMA priority medicines pathway:European accelerated review creates a twelve-month regulatory arbitrage window for first movers in solid tumor indications.
- Platelet-rich plasma standardization:Orthopedic and sports medicine clinics seek cGMP-grade preparation systems to replace variable bedside centrifugation protocols.
Industry Challenges
- Chain-of-identity verification:Patient-specific tracking across apheresis, manufacturing, and infusion requires interoperable software systems that most hospitals lack.
- FACT-JACIE accreditation timelines:Treatment centers face eighteen-to-twenty-four-month certification processes before qualifying to administer commercial CAR-T products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Autologous Cell Therapy Market |
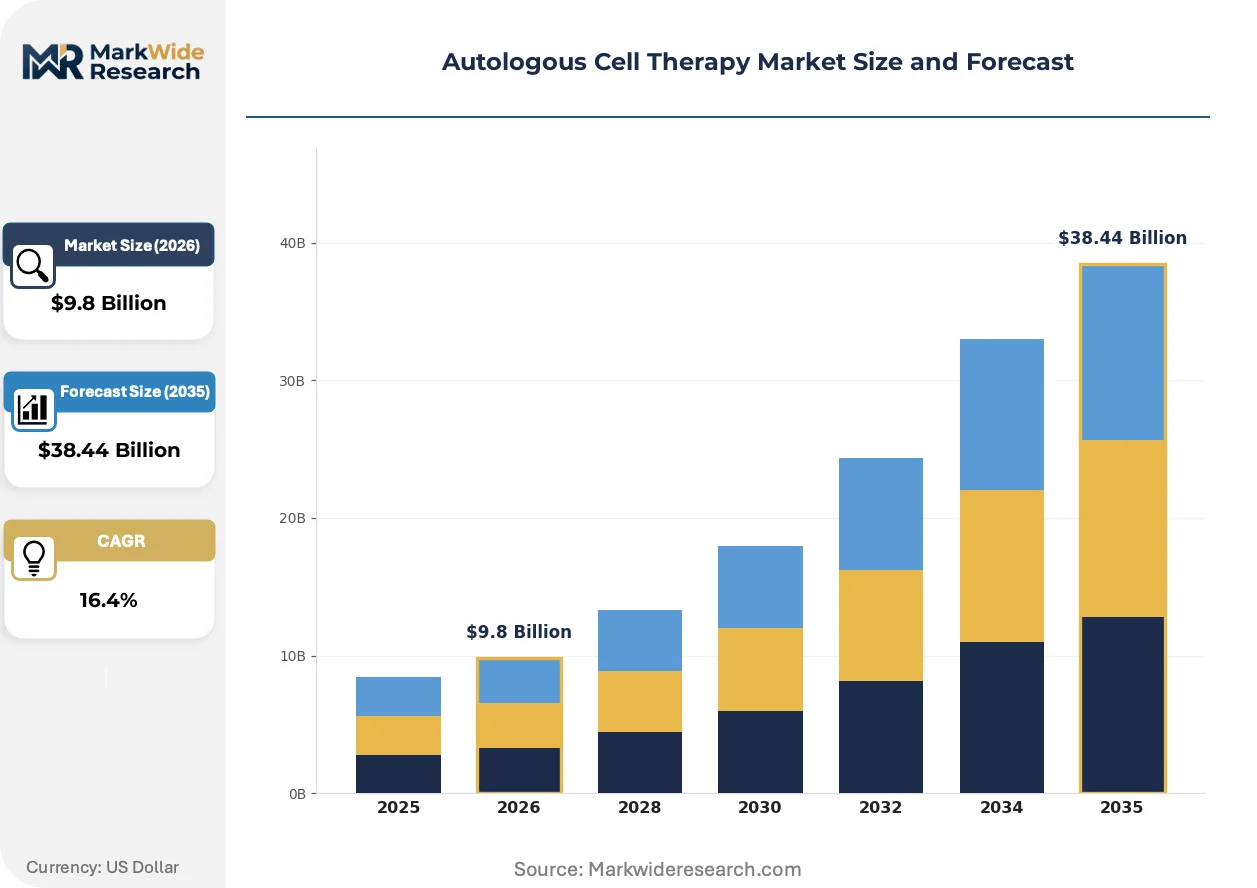
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $38.44 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stem Cells, T Cells, Platelet-Rich Plasma, Dendritic Cells Application: Oncology, Orthopedics, Cardiology, Dermatology End User: Hospitals, Research Institutes, Clinics, Cell Banks Delivery Mode: Intravascular, Topical, Injectable, Intralesional |
| Companies Covered | Novartis AG, Gilead Sciences, Inc., Bristol-Myers Squibb Company, Vericel Corporation, Pharmicell Co., Ltd., Johnson & Johnson, Holostem Terapie Avanzate S.r.l., BrainStorm Cell Therapeutics, Autolus Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Autologous Cell Therapy Market Strategic Shifts & Innovations
Process intensification and digital integration are reshaping how autologous therapies move from bench to bedside, with automation reducing the labor intensity that has constrained scale-up.
Allogeneic platform technologies are bifurcating competitive investment in the cell therapy space. Off-the-shelf products promise manufacturing economies that patient-specific therapies cannot match. Large pharmaceutical sponsors are redirecting capital toward universal donor cell lines, while specialized biotech firms double down on autologous personalization as a differentiation anchor.
EMA's revised good manufacturing practice Annex 1 requirements for sterile medicinal products took full effect in 2023, mandating continuous environmental monitoring and barrier technology upgrades. European manufacturing sites face capital expenditure thresholds that favor larger contract organizations over hospital-affiliated cell processing labs. German and Swiss treatment centers are consolidating procurement through shared services organizations to amortize compliance costs.
Hospital buyers are unbundling logistics services from product pricing, negotiating separate contracts for cryogenic transport and chain-of-custody documentation. This procurement fragmentation favors specialized cold-chain providers with healthcare-specific certifications over general freight forwarders. The United States exhibits the most advanced contract segmentation, with Medicare Advantage plans driving standardization of outcome metrics tied to reimbursement.
Autologous Cell Therapy Market Segmentation
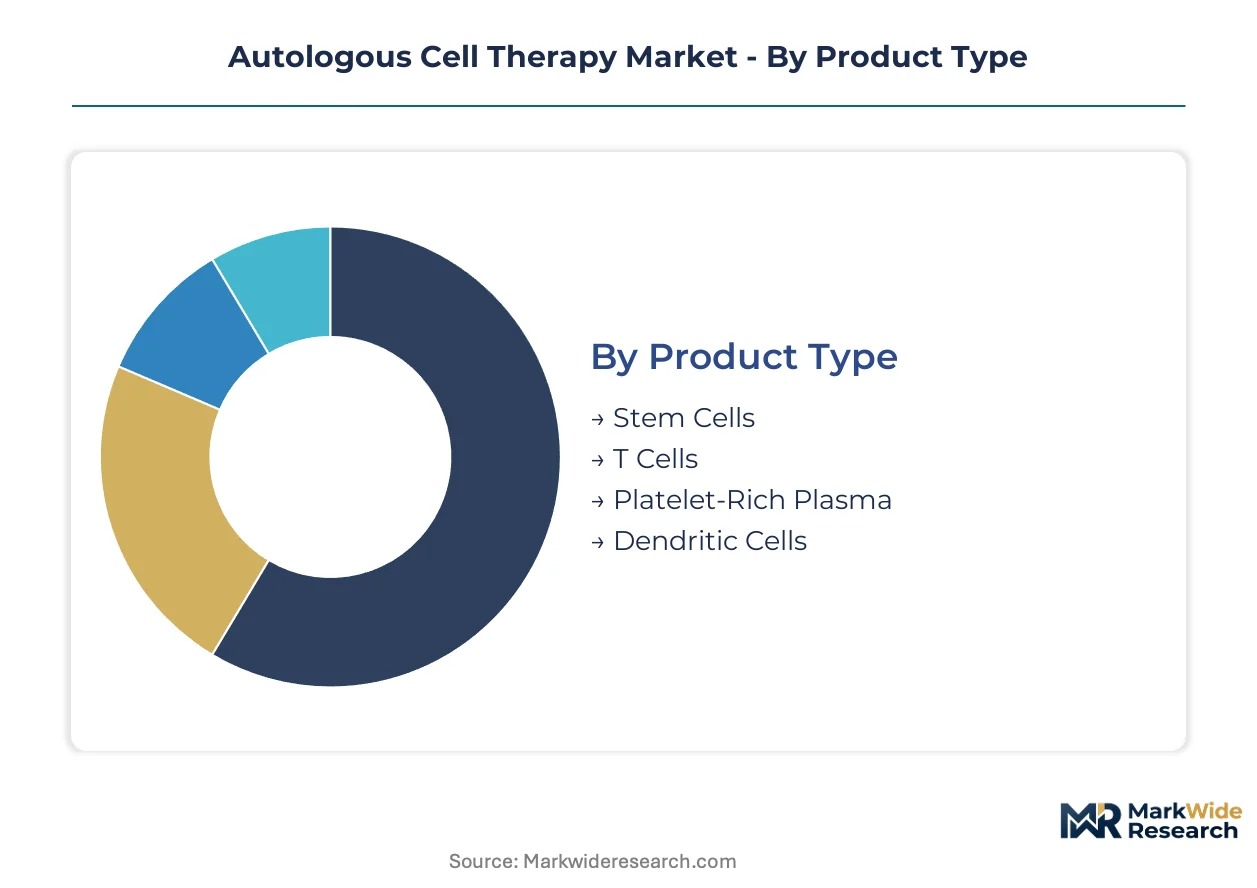
Segmentation in autologous cell therapy reveals how manufacturing complexity, reimbursement pathways, and clinical infrastructure reshape competitive boundaries across patient-specific product categories. Distinct margin profiles emerge from the interplay of cleanroom certification requirements and treatment center accreditation timelines.
Product Type:
Margin pools concentrate where viral vector engineering demands and cryopreservation infrastructure create the steepest barriers to competitive entry.
- T Cells:CAR-T constructs require lentiviral transduction and ISO 5 cleanroom expansion protocols. Demand clusters at academic medical centers in the United States pursuing FDA regenerative medicine advanced therapy designations, with Medicare reimbursement decisions directly shaping hospital procurement volumes.
- Stem Cells:Mesenchymal and hematopoietic progenitor populations demand extended ex vivo culture periods and rigorous potency release assays. Cardiology applications in German and Swiss specialized clinics attract concentrated R&D investment despite pre-commercial status, while orthopedic bone marrow concentrates sustain steadier procedural volumes.
- Platelet-Rich Plasma:Autologous blood fractionation for musculoskeletal regeneration operates at lower regulatory thresholds with bedside centrifugation protocols.
- Dendritic Cells:Ex vivo antigen loading for therapeutic vaccination remains largely investigational with limited commercial manufacturing scale.
The dominant share belongs to T Cells, while Stem Cells is closing the gap fastest through cardiology pipeline expansion.
Application:
Application-level profitability diverges sharply between inpatient CAR-T administration with bundled reimbursement and outpatient orthopedic procedures with fee-for-service clarity.
- Oncology:Hematologic malignancy indications command premium pricing supported by FDA accelerated approval pathways and dedicated inpatient prospective payment system adjustments. United States treatment centers drive volume concentration, though EMA priority medicines pathway creates regulatory arbitrage opportunities for European solid tumor entrants.
- Orthopedics:Sports medicine and degenerative joint applications leverage established platelet-rich plasma protocols with shorter vein-to-vein timelines. Demand distributes across ambulatory surgery centers and specialized clinics seeking cGMP-grade preparation systems to replace variable bedside processing.
- Cardiology:Ischemic tissue regeneration trials remain phase II-constrained with manufacturing scale-up pending positive readouts.
- Dermatology:Autologous fibroblast and melanocyte applications serve niche aesthetic and vitiligo segments with limited therapeutic reimbursement.
Oncology retains the revenue concentration lead, though Orthopedics is expanding most quickly through outpatient procedural adoption.
End User:
End user economics hinge on FACT-JACIE accreditation status and the capital intensity of apheresis-to-infusion infrastructure.
- Hospitals:Academic medical centers anchor commercial CAR-T administration through integrated apheresis, cryopreservation, and infusion capabilities. United States health systems negotiate separate logistics contracts for cryogenic transport as Medicare Advantage plans standardize outcome metrics.
- Research Institutes:Early-phase clinical trial execution and process development services support pipeline progression without commercial manufacturing scale.
- Clinics:Orthopedic and dermatology-focused facilities drive platelet-rich plasma volume through lower-regulatory-threshold procedures.
- Cell Banks:Cryogenic storage and chain-of-identity documentation services fragment across specialized providers with healthcare-specific certifications.
Hospitals command the installed base advantage, while Clinics are gaining share fastest through point-of-care processing economics.
Delivery Mode:
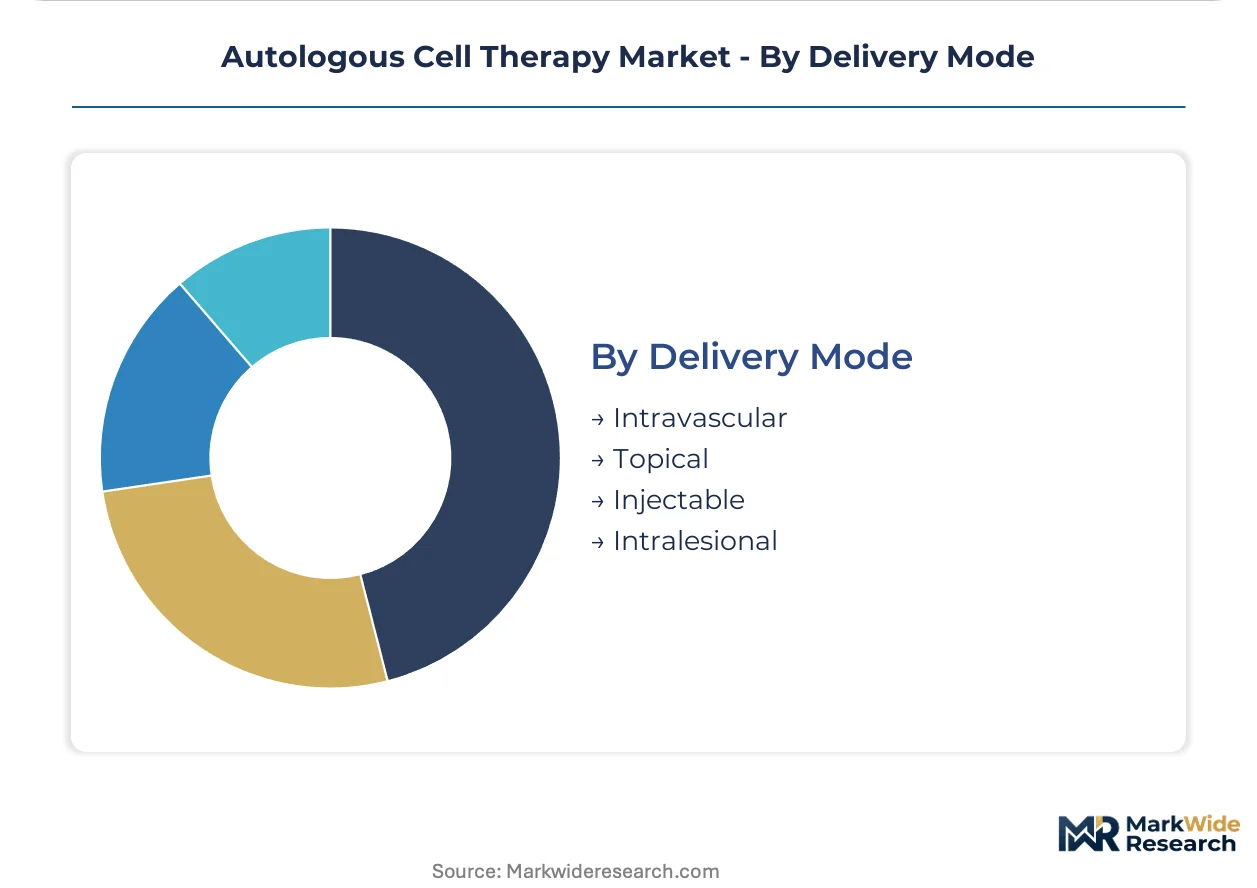
Delivery complexity scales with vascular access requirements and the precision of anatomical targeting.
- Intravascular:Systemic CAR-T infusion demands intensive care monitoring for cytokine release syndrome, concentrating administration at tertiary centers with ECMO backup capabilities.
- Injectable:Intra-articular and soft tissue deposition protocols dominate orthopedic applications with ambulatory feasibility.
- Topical:Dermatologic cell suspensions serve limited wound healing and aesthetic indications.
- Intralesional:Direct tumor or tissue injection requires image-guided delivery systems with restricted commercial penetration.
Intravascular delivery holds the current volume lead, though Injectable modes are climbing the fastest through sports medicine clinic expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States hospitals administer CAR-T therapies through bundled Medicare reimbursement, while German clinics pursue stem cell cardiology under EMA accelerated pathways. Swiss treatment centers consolidate procurement through shared services to amortize compliance costs.
United States
Academic medical centers in Boston and Houston scale in-house apheresis capabilities to reduce vein-to-vein timelines. FDA's regenerative medicine advanced therapy designation compresses clinical development for qualifying autologous products. The Medicare inpatient prospective payment system shapes hospital procurement budgets, with Medicare Advantage plans driving standardization of outcome metrics.
Germany
Specialized cardiology clinics in Berlin and Munich attract concentrated R&D investment for pre-commercial stem cell therapies. EMA's revised GMP Annex 1 requirements mandate continuous environmental monitoring upgrades. German treatment centers consolidate procurement through shared services organizations to amortize compliance capital expenditure thresholds.
Switzerland
Swissmedic oversees manufacturing sites facing capital expenditure barriers that favor larger contract organizations. Swiss treatment centers leverage cross-border patient flows from neighboring jurisdictions. Basel and Zurich anchor cryogenic logistics networks serving alpine clinic clusters.
United Kingdom
London's academic medical centers build integrated apheresis-to-infusion platforms controlling cold-chain handoffs. The Medicines and Healthcare products Regulatory Agency aligns with EMA pathways post-Brexit transition. Oxford and Cambridge clusters concentrate early-phase clinical trial execution.
Japan
PMDA's regenerative medicine framework creates distinct market access timelines for autologous products. Tokyo and Osaka hospitals develop automated cell processing capabilities to displace manual cleanroom operations. Japanese treatment centers face eighteen-to-twenty-four-month accreditation processes before qualifying for commercial administration.
Autologous Cell Therapy Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with manufacturing capacity concentration mattering more than pipeline breadth. Viral vector supply networks and cryopreservation logistics platforms separate the upper tier from aspirants. Strategic archetypes include integrated pharmaceutical sponsors with established CDMO relationships, specialized biotech firms doubling down on patient-specific personalization, and contract manufacturers securing ISO 5 certification scarcity. Dominant competitive moves center on dual-site manufacturing investments and backward integration into viral vector production.
Among established pharmaceutical sponsors, Novartis AG, Gilead Sciences, Inc., and Bristol-Myers Squibb Company exemplify the integrated leader archetype. Novartis occupies a position anchored by viral vector supply network control. Gilead Sciences sits within the tier defined by manufacturing redundancy strategies. Bristol-Myers Squibb represents the logistics-integrated model through apheresis-to-infusion platform investments.
| Leading Market Players |
|---|
| Novartis AG |
| Gilead Sciences, Inc. |
| Bristol-Myers Squibb Company |
| Vericel Corporation |
| Pharmicell Co., Ltd. |
| Johnson & Johnson |
| Holostem Terapie Avanzate S.r.l. |
| BrainStorm Cell Therapeutics |
| Autolus Therapeutics |
| Others |
Cost & Logistics Intelligence
Automated cell processing platforms displacing manual cleanroom labor are redrawing supply geography toward ISO 5-certified hubs while compressing per-batch cost structures across the autologous cell therapy sector. This substitution dynamic concentrates manufacturing investment in the United States and Germany, where contract organizations amortize platform capital against premium pricing for patient-specific viral vector transduction services.
Pricing Analysis
Long-term offtake contracts dominate CAR-T procurement between academic medical centers and integrated pharmaceutical sponsors, with spot purchasing limited to emergency viral vector slots. Price differentiation hinges on FACT-JACIE accreditation tier and cold-chain service bundling, with Medicare Advantage plans driving outcome-based adjustments. Cost compression in community hospital tiers is intensifying because bundled diagnosis-related group reimbursement caps procedure margins. Research institutes exhibit highest price sensitivity; tertiary centers with ECMO capabilities show lowest.
Supply Chain Analysis
Inventory lead times for lentiviral vectors extend twelve to eighteen months, constraining batch scheduling at contract development organizations. Supply concentrates in the United States, Germany, and Switzerland, with viral vector production drawing from plasmid DNA, packaging cell lines, and fetal bovine serum inputs. Single-source vulnerability pervades gamma-retroviral vector manufacturing. Distribution runs through cryogenic logistics specialists with healthcare-specific certifications rather than general freight forwarders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autologous cell therapy represents high-growth disruption as FDA's regenerative medicine advanced therapy designation compresses development timelines for patient-specific oncology products.
For Market Incumbents: Shield market position through backward integration into viral vector production and dual-site manufacturing redundancy across United States hubs. Allogeneic platform technologies from emerging biotech firms threaten autologous personalization margins; ISO 5 cleanroom capacity expansion anchors defensive moats. For New Entrants and Emerging Players: Anchor in orthopedic point-of-care manufacturing for platelet-rich plasma standardization, the most penetrable segment given lower regulatory thresholds. German and Swiss cardiology clinics present white-space opportunity for pre-commercial stem cell therapies. Go-to-market through cGMP-grade preparation system partnerships with ambulatory surgery centers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract development organizations holding scarce ISO 14644 certification. Long-term viability across a five-to-ten year window favors automated processing platform owners over manual cleanroom operators. Watch EMA priority medicines pathway approvals for European solid tumor entrants as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Site Manufacturing Scale-Up | Gilead Sciences sustains redundant production for lymphoma therapies, reducing patient wait times. |
| Viral Vector Supply Agreement | Novartis leverages established networks to secure production slots at contract organizations. |
| Integrated Logistics Platform Investment | Bristol-Myers Squibb controls apheresis-to-infusion cold-chain handoffs across hospital systems. |
| Automated Cell Processing Deployment | Closed-system bioreactors displace manual cleanroom operations, expanding batch throughput. |
| FACT-JACIE Accreditation Pathway | Treatment centers face eighteen-to-twenty-four-month certification before commercial CAR-T administration. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with cell therapy manufacturing executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and Medicare reimbursement databases. Bottom-up patient-volume modeling and top-down pharmaceutical sponsor revenue triangulation anchored market sizing.
Across the analysis window, forecasts applied treatment line, cell type, and regional regulatory cluster segmentation. CAGRs derived from patient population projections, approval timeline assumptions, and manufacturing capacity expansion schedules. Viral vector supply constraints and cryopreservation logistics fragmentation served as industry-specific forecast inputs.
Material uncertainties — regulatory pathway delays, reimbursement policy shifts, viral vector production bottlenecks — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
North America Stem Cell Therapy Market
Cell & Gene Therapy
Genetic Disorder Therapeutics Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market
Cell & Gene Therapy
Autologous Stem Cell and Non Stem Cell Based Therapies Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
Cell and Gene Therapy Clinical Trials Market
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
Global Gene Delivery Systems Market
Cell & Gene Therapy
Cell and Gene Therapy Bioreactor PAT and Analytics Test Platforms Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market