
 Automated Colony Picking Systems Market | 2026-2036
Automated Colony Picking Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Colony Picking Systems Market Outlook
The capital-intensity divergence between high-throughput robotic deployers and benchtop-focused suppliers is redrawing vendor tiering in this space. Tecan Trading leverages its liquid-handling heritage to sustain integrated workflow dominance across European pharma accounts. Hudson Robotics anchors its position through specialized colony-picking modules for synthetic biology pipelines. Hamilton Company competes on precision dispensing architectures that extend into microbial screening applications.
Automated colony picking systems integrate robotic manipulators, machine vision cameras, and software-controlled pipetting to identify, select, and transfer microbial colonies from agar plates based on morphological or fluorescence parameters, typically operating at throughputs exceeding 2,000 colonies per hour. These platforms serve primarily to eliminate manual picking variability in microbial culturing and genetic engineering workflows while generating traceable digital records for regulatory submission. Robotic systems capture the dominant installed base due to throughput requirements in pharmaceutical compound screening, though software solutions represent the fastest-expanding margin pool as laboratories seek AI-driven colony classification without full hardware replacement. Machine learning segments within technology are gaining traction for phenotype prediction, while drug discovery applications command premium pricing relative to environmental testing configurations.
FDA 21 CFR Part 11 electronic records requirements shape validation documentation demands for U.S. pharmaceutical buyers, while EU MDR traceability standards in Europe and ISO 13485 quality management frameworks govern equipment qualification protocols for clinical-adjacent workflows. Japan's PMDA guidelines for automated laboratory equipment add a third compliance layer for vendors serving Asia-Pacific biotech accounts. Stakeholders must monitor evolving AI validation standards from regulatory bodies as machine learning modules become embedded in colony classification workflows.
Market Dynamics
Machine vision classification is fragmenting hardware-centric procurement patterns as pharmaceutical buyers decouple AI software modules from full robotic platform replacements, compressing traditional equipment refresh cycles.
Growth Catalysts
- FDA 21 CFR Part 11:Electronic records mandates in the United States compel pharmaceutical laboratories to replace manual colony documentation with automated traceable systems, accelerating validation-compliant hardware procurement.
- Synthetic biology pipelines:Engineered microorganism workflows demand higher-throughput colony screening than manual methods permit, pulling investment toward robotic integration in biotechnology facilities.
- Fluorescence-based screening:Advanced imaging protocols for phenotype detection expand addressable applications beyond traditional microbial culturing into protein engineering and directed evolution workflows.
Market Restraints
- Precision motion control components:Specialized robotic manipulators and high-resolution cameras concentrate supply among Japanese and German component suppliers, exposing buyers to extended lead times and input cost volatility.
- EU MDR traceability requirements:Equipment qualification protocols for clinical-adjacent workflows impose documentation burdens that elongate sales cycles and inflate vendor compliance costs.
- Benchtop automation substitutes:Lower-cost semi-automated colony picking devices satisfy throughput needs of mid-scale research laboratories, constraining addressable market for fully integrated robotic platforms.
Strategic Opportunities
- India biopharma expansion:CDSCO regulatory harmonization initiatives and domestic PLI scheme incentives for biotechnology manufacturing create entry pathways for automated colony picking vendors in contract research organizations.
- AI-software unbundling:Machine learning modules for colony classification enable vendors to penetrate installed bases without full hardware displacement, opening recurring revenue streams through subscription licensing.
- Environmental microbiome applications:Soil and water testing laboratories represent underpenetrated end-use verticals where regulatory monitoring mandates for biodiversity assessment drive automated screening demand.
Industry Challenges
- Mechatronics engineering talent:Shortage of specialists integrating robotic kinematics with biological laboratory protocols constrains vendor R&D velocity and field service capacity.
- ISO 13485 certification timelines:Quality management system audits for clinical-adjacent equipment deployments extend qualification periods, delaying revenue recognition and straining working capital.
- Legacy LIMS integration:Proprietary data formats from established laboratory information management systems create interoperability friction during automated colony picking system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Colony Picking Systems Market |
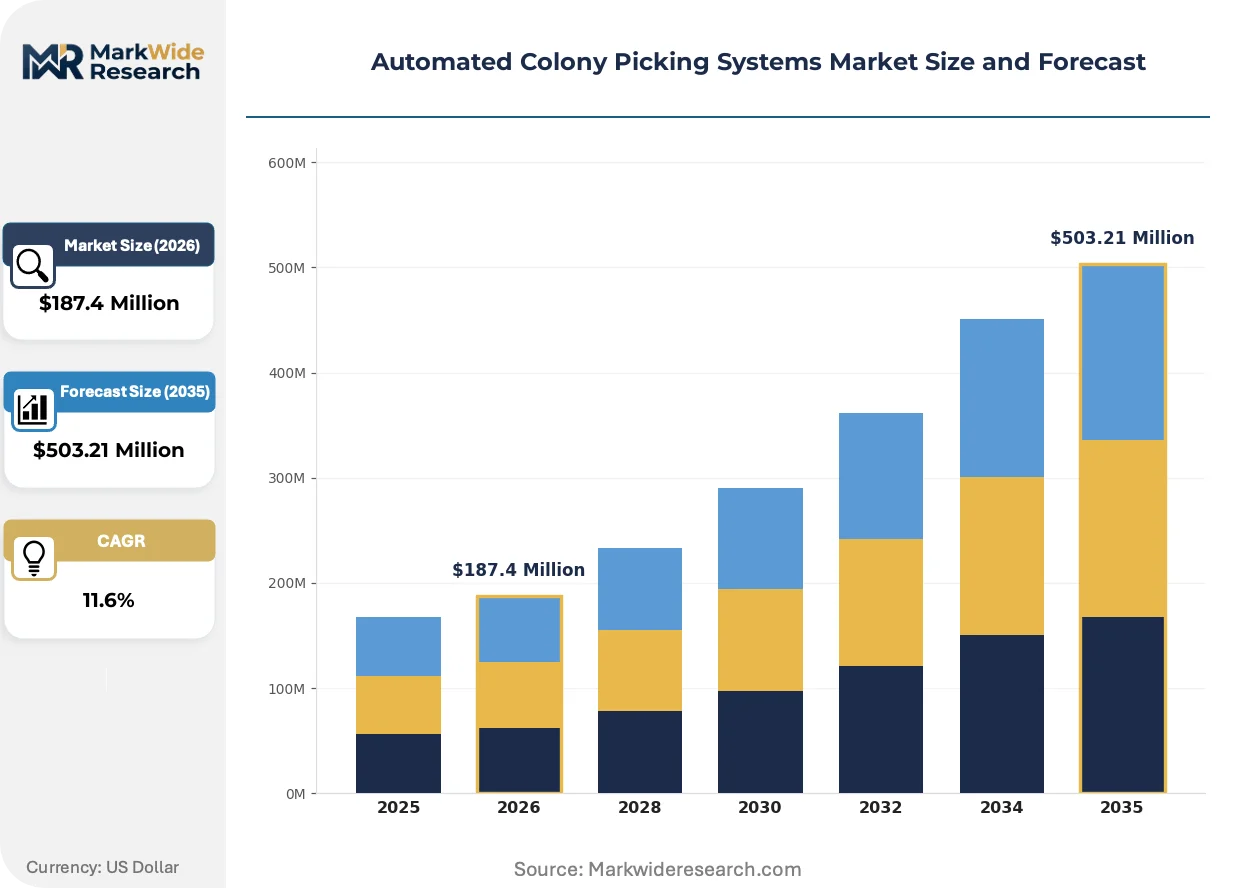
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Robotic Systems, Manual Systems, Hybrid Systems, Software Solutions End User: Research Laboratories, Pharmaceutical Companies, Academic Institutions, Biotech Firms Technology: Automated Robotics, Machine Learning, Vision Systems, Sensor Technologies Application: Microbial Culturing, Genetic Engineering, Drug Discovery, Environmental Testing |
| Companies Covered | Tecan Trading, Bio-Rad Laboratories, Hudson Robotics, Hamilton Company, Singer Instrument, Molecular Devices, SciRobotics, Becton, Dickinson and Company, Wagner Life Science, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Colony Picking Systems Market Strategic Shifts
Deep learning architectures are compressing traditional machine vision boundaries, enabling phenotype prediction without exhaustive manual training datasets. Three developments are reshaping competitive positioning.
Convolutional neural networks for colony morphology classification are fragmenting hardware procurement patterns. Contract research organizations now license AI software modules independently, deploying them across existing imaging infrastructure rather than committing to full robotic platform replacements. This decoupling erodes traditional equipment bundling economics and compresses vendor margin structures.
EU MDR traceability mandates are reshaping equipment validation documentation demands. Medical device-adjacent laboratory workflows now require serialized colony tracking from plate imaging through downstream processing, forcing vendors to embed blockchain or distributed ledger architectures into software stacks. German pharmaceutical accounts lead this compliance-driven specification shift.
Service unbundling is disrupting traditional capital equipment sales models. Biotechnology buyers now demand colony picking capacity through usage-based contracts rather than outright purchase, transferring operational risk to vendors. This pattern concentrates most acutely in Boston and San Diego cluster facilities where capital efficiency metrics govern procurement committee decisions.
Automated Colony Picking Systems Market Segmentation
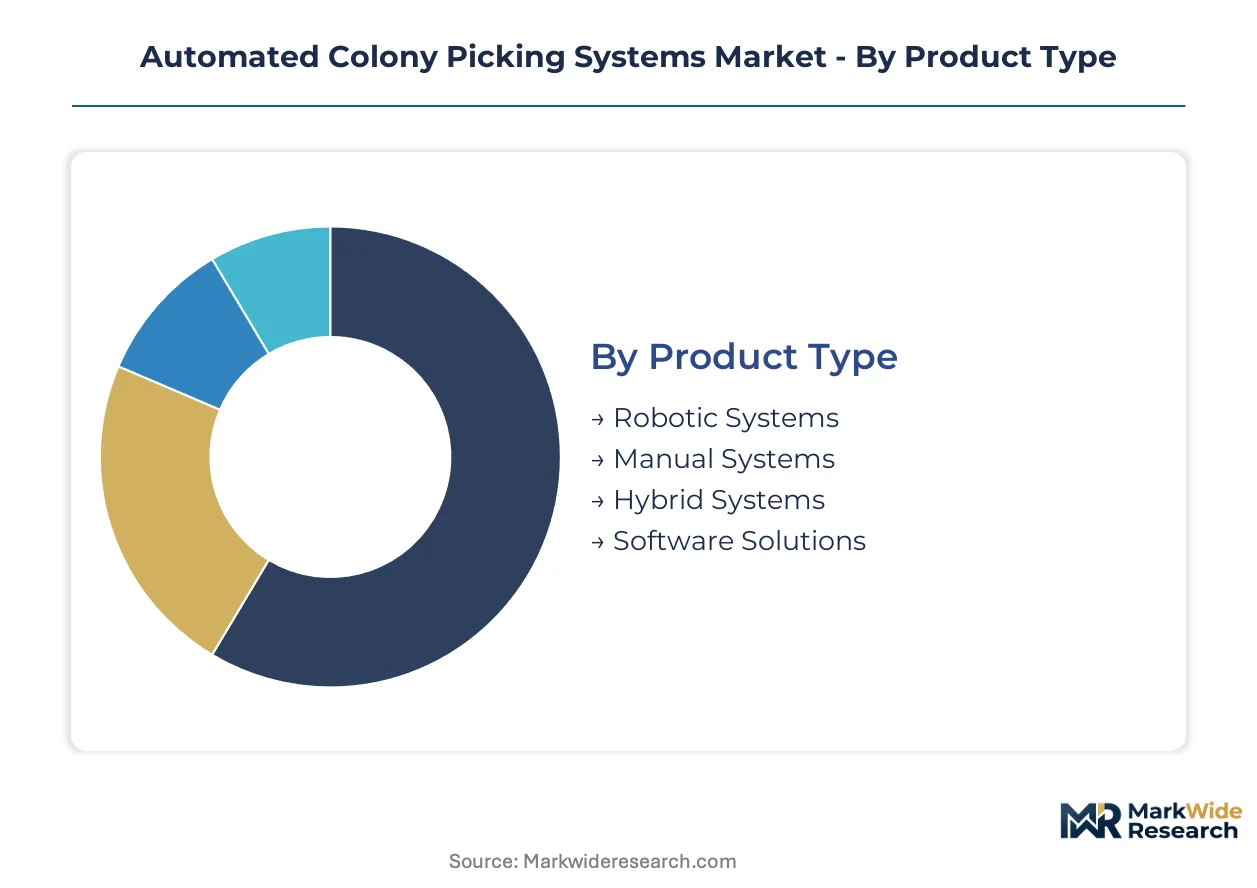
Automated colony picking systems fragment across hardware-software boundaries and end-use sophistication tiers. Procurement patterns diverge sharply between high-throughput pharmaceutical deployers and mid-scale research laboratories with constrained capital budgets.
Product Type:
Domestic demand concentrates in robotic platforms serving U.S. and German pharmaceutical clusters, while software solutions draw export-led traction from contract research organizations across India and Singapore seeking AI modules without hardware displacement.
- Robotic Systems:Integrated platforms combining multi-axis manipulators, high-resolution cameras, and precision pipetting architectures achieve throughputs exceeding 2,000 colonies per hour. Pharmaceutical compound screening operations in Boston and San Diego drive replacement cycles as FDA 21 CFR Part 11 compliance mandates obsolete manual documentation workflows.
- Software Solutions:Machine learning modules for colony morphology classification deploy across existing imaging infrastructure without full platform replacement. Biotechnology buyers in Cambridge and Basel license convolutional neural networks independently, compressing traditional equipment bundling economics.
- Hybrid Systems:Semi-automated configurations bridge manual precision and robotic throughput for mid-scale synthetic biology pipelines.
- Manual Systems:Basic picking stations persist in academic settings with minimal regulatory documentation requirements.
Robotic systems command the established base. The steepest expansion runs through software solutions.
End User:
Cost tier stratification separates premium pharmaceutical deployers from economy-focused academic purchasers, with biotech firms occupying the contested mid-market.
- Pharmaceutical Companies:Integrated robotic workflows serve high-throughput microbial screening with serialized colony tracking from plate imaging through downstream processing. EU MDR traceability mandates in Germany and FDA electronic records requirements in the United States impose validation documentation burdens that inflate procurement specifications.
- Biotech Firms:Synthetic biology pipelines demand engineered microorganism screening capacities beyond manual methods. Boston and San Diego cluster facilities increasingly procure through usage-based contracts rather than capital purchase, transferring operational risk to vendors.
- Research Laboratories:Environmental microbiome and soil biodiversity applications drive automated screening demand in underpenetrated testing verticals.
- Academic Institutions:Budget constraints favor benchtop automation substitutes over fully integrated platforms for basic microbial culturing instruction.
Pharmaceutical companies anchor revenue concentration. Biotech firms are climbing the fastest as synthetic biology investment accelerates.
Technology:
Volume deployment favors mature automated robotics, while machine learning segments capture expanding margin pools through phenotype prediction capabilities.
- Automated Robotics:Multi-axis kinematic systems with sub-millimeter positioning repeatability dominate installed bases. Japanese and German component suppliers concentrate supply of precision motion control elements, exposing buyers to extended lead times.
- Machine Learning:Deep learning architectures compress traditional machine vision boundaries, enabling phenotype prediction without exhaustive manual training datasets. AI validation standards from regulatory bodies remain unresolved as embedded classification modules proliferate.
- Vision Systems:High-resolution cameras with fluorescence detection protocols extend applications into protein engineering workflows.
- Sensor Technologies:Integrated force feedback and environmental monitoring ensure colony viability during transfer operations.
Automated robotics holds the volume base. Machine learning is gaining share fastest through software unbundling strategies.
Application:
Application maturity diverges between established microbial culturing protocols and emerging environmental testing configurations with divergent pricing structures.
- Drug Discovery:Compound screening workflows command premium pricing relative to other configurations. Pharmaceutical buyers in the United States and Switzerland require full audit trails for regulatory submission, driving integrated platform procurement.
- Genetic Engineering:CRISPR-enabled directed evolution pipelines demand high-throughput colony screening with morphological and fluorescence-based selection parameters. Contract research organizations in India expand capacity to serve international biotechnology clients.
- Microbial Culturing:Quality control applications in food and beverage testing leverage standardized protocols with lower customization requirements.
- Environmental Testing:Soil and water microbiome assessment for biodiversity monitoring represents underpenetrated demand with regulatory tailwinds from EU environmental directives.
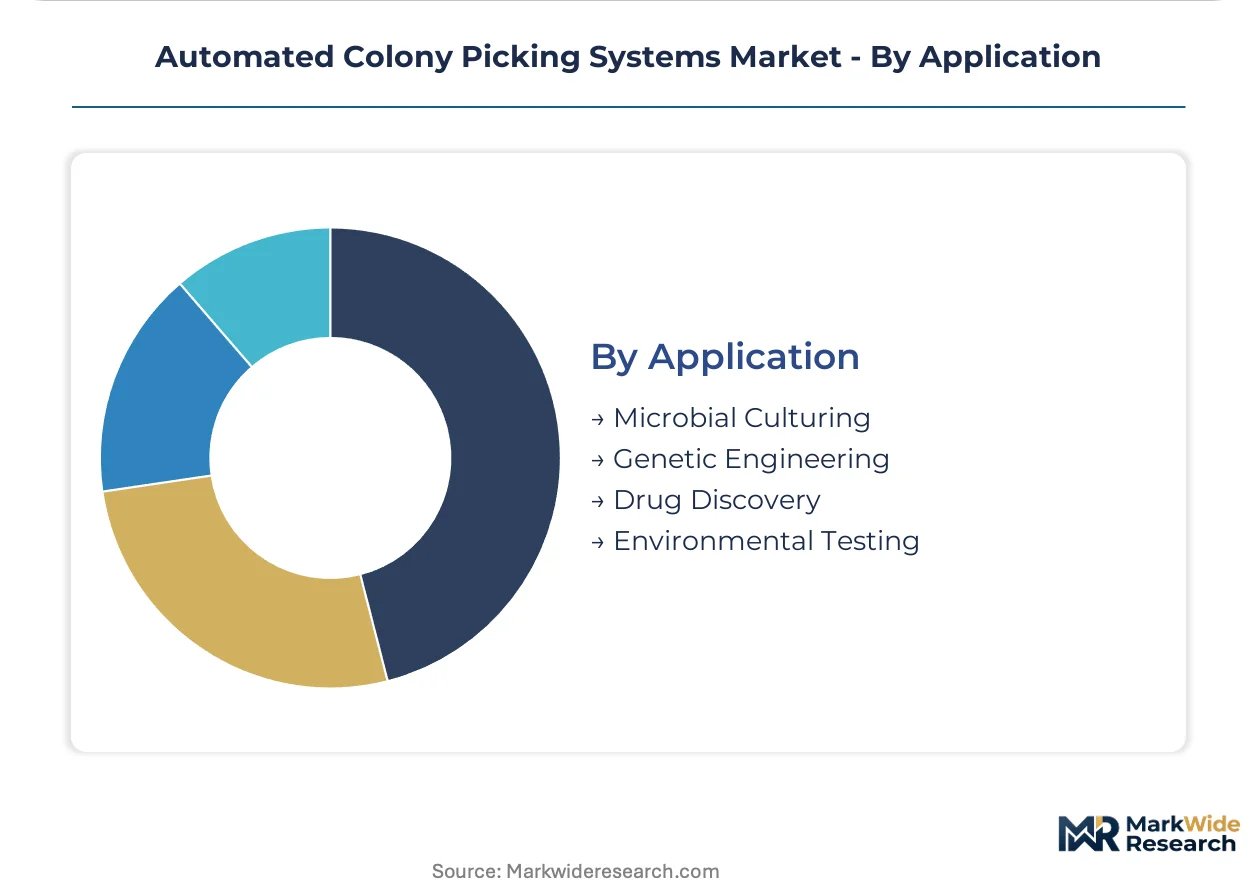
Drug discovery commands the established base. Environmental testing is expanding most quickly as monitoring mandates proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Swiss and German pharmaceutical clusters where EU MDR traceability mandates inflate equipment specifications, while Indian contract research organizations extract cost advantages through CDSCO-harmonized regulatory pathways.
United States
FDA 21 CFR Part 11 electronic records requirements compel pharmaceutical laboratories in Boston and San Diego to replace manual colony documentation with validated automated systems. Biotech cluster density drives usage-based procurement contracts that transfer operational risk to vendors. Synthetic biology pipelines in Cambridge facilities pull investment toward high-throughput robotic integration.
Germany
EU MDR traceability standards reshape equipment qualification protocols for clinical-adjacent laboratory workflows. Medical device-adjacent applications now require serialized colony tracking from plate imaging through downstream processing. Munich and Heidelberg pharmaceutical accounts lead adoption of blockchain-embedded software architectures for compliance documentation.
Switzerland
Swissmedic quality frameworks govern equipment validation for pharmaceutical compound screening operations. Basel biotech clusters command premium pricing for integrated robotic workflows with full audit trail capabilities. Precision dispensing requirements from protein engineering pipelines sustain demand for sub-millimeter positioning repeatability.
India
CDSCO regulatory harmonization initiatives and domestic PLI scheme incentives for biotechnology manufacturing create entry pathways for automated colony picking vendors. Contract research organizations in Hyderabad and Bangalore expand capacity to serve international synthetic biology clients. Cost-sensitive procurement favors software module licensing over full hardware replacement.
Japan
PMDA guidelines for automated laboratory equipment add compliance layers for vendors serving Asia-Pacific biotech accounts. Precision motion control component supply from domestic suppliers exposes buyers to extended lead times. Tokyo and Osaka pharmaceutical clusters integrate machine vision classification for phenotype prediction workflows.
Automated Colony Picking Systems Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes in this market. Swiss and German precision engineering specialists dominate high-throughput robotic platforms with integrated liquid-handling heritage, while mid-scale suppliers compete on benchtop automation substitutes. The vendor base stratifies into three tiers: integrated workflow providers, specialized colony-picking module fabricators, and AI-software unbundlers. Competitive intensity concentrates on M&A activity targeting machine learning capabilities and strategic partnerships for LIMS interoperability.
Within the integrated workflow tier, Tecan Trading and Hamilton Company exemplify precision dispensing architectures that extend into microbial screening applications. Hudson Robotics occupies a position among specialized module fabricators serving synthetic biology pipelines. These three anchors represent divergent strategic postures: liquid-handling heritage leverage, precision kinematics specialization, and dedicated colony-picking focus respectively.
| Leading Market Players |
|---|
| Tecan Trading |
| Bio-Rad Laboratories |
| Hudson Robotics |
| Hamilton Company |
| Singer Instrument |
| Molecular Devices |
| SciRobotics |
| Becton, Dickinson and Company |
| Wagner Life Science |
| Others |
Value Chain & Pricing Dynamics
Forty-five to ninety-day lead times for precision motion control components from Japanese and German suppliers concentrate pricing power among integrated workflow vendors while compressing margins for hardware-dependent entrants. This inventory exposure shapes procurement committee preferences toward usage-based contracts in biotech clusters.
Pricing Analysis
The customization-premium spread separates configured-to-order robotic platforms from standard benchtop configurations. Subscription licensing for AI software modules draws from SaaS-tiered structures, while hardware procurement follows project-based contracting with volume-scale discounts for pharmaceutical compound screening operations. Price differentiation hinges on FDA 21 CFR Part 11 validation documentation tier and ISO 13485 certification level. Pricing pressure stems from software unbundling as contract research organizations license machine learning modules independently. Academic institutions exhibit highest price sensitivity; Swiss and German pharmaceutical clusters show lowest.
Supply Chain Analysis
Just-in-time inventory strategies dominate among biotech firms in Boston and San Diego, while strategic stockpiling persists among German pharmaceutical accounts facing EU MDR qualification timelines. Component supply concentrates in Japan, Germany, and Switzerland for precision motion control elements. Raw material dependencies include high-resolution CMOS sensors, specialized robotic manipulators, and precision pipetting architectures. Single-source vulnerability from concentrated Japanese component suppliers exposes buyers to extended lead times. Distribution runs through direct vendor relationships with pharmaceutical procurement committees and laboratory equipment distributors serving mid-scale research facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent vendors must navigate substitution from AI-software unbundling that enables contract research organizations to deploy machine learning modules across existing imaging infrastructure without full platform replacement.
For Market Incumbents: Compound defensive positioning through backward integration into precision motion control component supply and captive development of machine learning classification modules. Vertical integration into sensor manufacturing mitigates lead-time exposure from Japanese suppliers. Certification investment in ISO 13485 quality management systems defends pharmaceutical account retention against emerging entrants.
For New Entrants and Emerging Players: Differentiate on environmental microbiome applications where regulatory monitoring mandates for biodiversity assessment create underpenetrated demand. Target soil and water testing laboratories in India and Singapore through CDSCO-harmonized regulatory pathways. Deploy software-first go-to-market strategies licensing convolutional neural networks without hardware displacement.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because FDA 21 CFR Part 11 and EU MDR traceability mandates create durable competitive moats around validated equipment vendors. Acquisition target archetype: specialized colony-picking module fabricators with synthetic biology pipeline relationships. Watch AI validation standards from regulatory bodies as inflection indicator for software margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine Learning Module Development | Enables phenotype prediction without exhaustive manual training datasets for contract research organizations. |
| Blockchain-Embedded Software Architecture | Satisfies EU MDR serialized colony tracking requirements for German pharmaceutical accounts. |
| Usage-Based Contract Offering | Transfers operational risk to vendors while matching capital efficiency metrics of Boston biotech clusters. |
| Precision Component Backward Integration | Reduces lead-time exposure from concentrated Japanese and German motion control suppliers. |
| CDSCO Regulatory Harmonization Partnership | Creates entry pathways for automated colony picking vendors in Indian contract research organizations. |
Study Parameters
Cross-validation between primary interviews with laboratory automation directors and secondary validation through FDA 510(k) filings anchors the qualitative findings in this analysis. Primary fieldwork engaged robotic systems engineers, pharmaceutical procurement managers, synthetic biology pipeline directors, and regulatory affairs specialists at equipment vendors. Secondary sources include EMA qualification documentation, ISO 13485 certification registries, and customs records for precision motion control component trade flows. Bottom-up triangulation across installed base estimates and top-down validation through vendor revenue disclosures ensure analytical robustness.
Sensitivity analysis around AI adoption velocity and regulatory harmonization timelines informs the projection framework across the analysis window. Segmentation dimensions modeled include product type tier, end-use sophistication level, technology architecture, and application vertical with regional regulatory cluster overlay. CAGRs derive from regression analysis against synthetic biology investment flows and pharmaceutical R&D expenditure patterns. Forecast inputs incorporate machine learning module penetration rates and EU MDR implementation timelines.
Forecasts assume regulatory continuity in FDA 21 CFR Part 11, EU MDR, and PMDA regimes; material policy shifts would require re-modeling. Specific risks include unresolved AI validation standards from regulatory bodies and precision component supply disruptions. Revision becomes warranted when software unbundling penetration crosses thresholds that compress traditional equipment bundling economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biotechnology Equipment
North America Life Science Tools Market
Biotechnology Equipment
PCR Consumables Market
Biotechnology Equipment
Biobank Equipment Market
Biotechnology Equipment
Global Polymerase Chain Reaction (PCR) Consumables Market
Biotechnology Equipment
Automated Cell Counting Market
Biotechnology Equipment
Global Biotechnology Reagents Market
Biotechnology Equipment
Cell Culture Media, Sera, and Reagents Market
Biotechnology Equipment
Lab Centrifuges Market
Biotechnology Equipment
Cartridges for RT-PCR Automatic Systems Market
Biotechnology Equipment
Biotechnology Instrumentation Market
Biotechnology Equipment
Bioreactors Accessories Market
Biotechnology Equipment
Single-Use Bioreactor Bag Integrity and Leak Test Equipment Market
Biotechnology Equipment
Cell Harvesting Systems Market
Biotechnology Equipment
Lab Automation for in-Vitro Diagnostics Market
Biotechnology Equipment
Global Biotechnology Market
Biotechnology Equipment
Global Bioprocess Container Market