
 North America Stem Cell Therapy Market | 2026-2036
North America Stem Cell Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Stem Cell Therapy Market Analytics
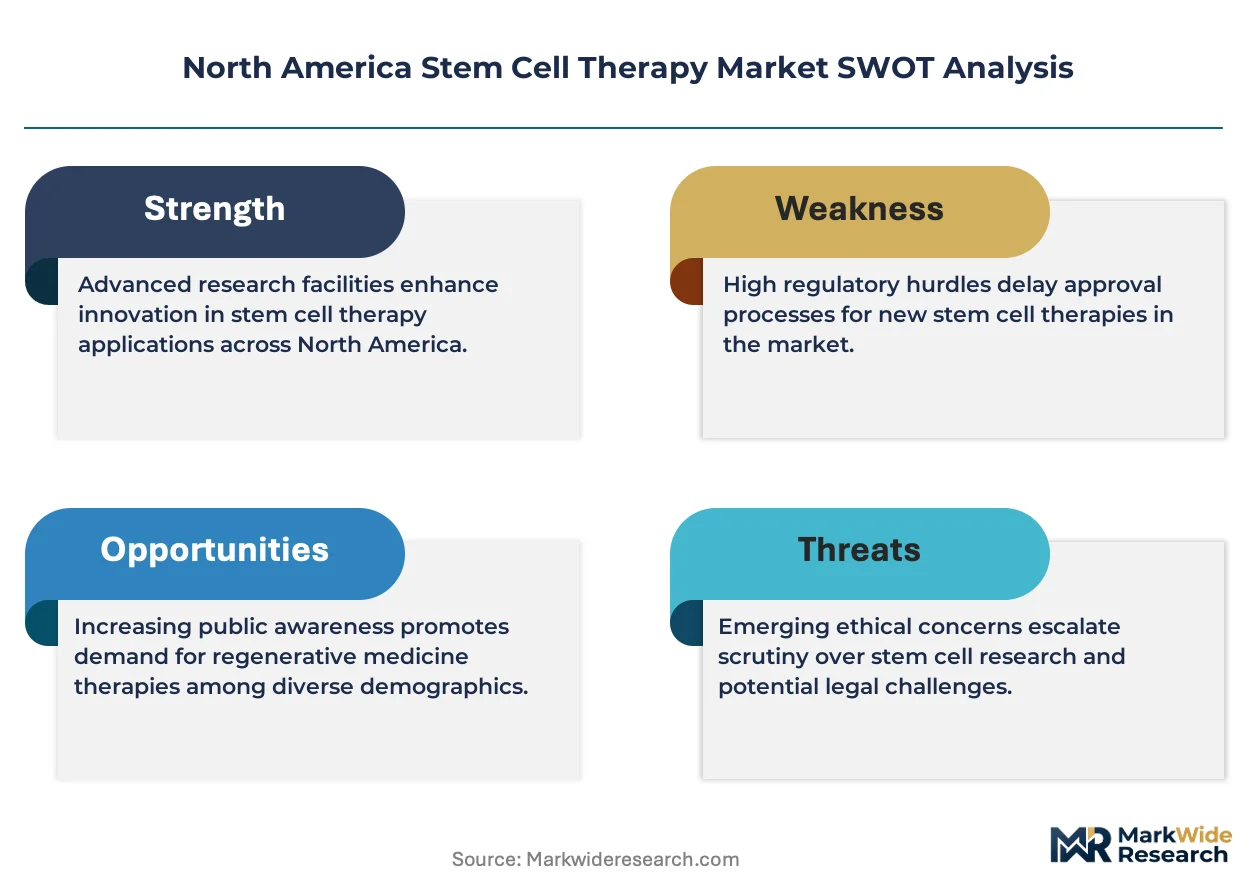
Hospital procurement channels for autologous cell therapies is narrowing as integrated delivery networks consolidate vendor relationships. Thermo Fisher Scientific leverages its cryopreservation infrastructure to sustain cold-chain dominance across the region. Novartis AG anchors its position through CAR-T manufacturing capacity in New Jersey and Pennsylvania. Bristol-Myers Squibb Company differentiates via its diversified cell therapy pipeline spanning hematologic and solid tumor indications.
Stem cell therapy deploys living, self-renewing progenitor cells derived from bone marrow, adipose tissue, umbilical cord blood, or reprogrammed somatic sources, expanded ex vivo under current Good Manufacturing Practice conditions to achieve defined potency, purity, and viability thresholds before infusion. The field serves primarily to regenerate damaged tissues, replace dysfunctional cell populations, and engineer immune responses against malignancies. Adult stem cells occupy the largest revenue pool owing to established extraction protocols and lower tumorigenic risk profiles, while induced pluripotent stem cells represent the fastest-expanding segment as reprogramming efficiencies improve and differentiation protocols standardize. Regenerative medicine applications command premium pricing due to chronic disease prevalence, though cancer treatment generates the highest absolute procedure volumes through approved CAR-T and TCR therapies.
FDA's Center for Biologics Evaluation and Research enforces donor eligibility, vector safety, and lot-release testing standards that dictate manufacturing investment levels and facility qualification timelines. Health Canada and the US National Institutes of Health jointly influence early-stage trial design through funding priorities and cooperative review frameworks. Stakeholders must monitor CMS reimbursement determinations for outpatient cell therapy administration, as coverage policies will determine site-of-service economics and patient access velocity across the forecast horizon.
Market Dynamics
FDA's regenerative medicine advanced therapy designation compresses clinical development timelines while integrated delivery networks consolidate vendor relationships, concentrating procurement leverage among fewer hospital systems across the Northeast corridor.
Growth Catalysts
- RMAT Designation:FDA's expedited pathway accelerates commercialization for qualifying cell therapies, reducing time-to-market by streamlining regulatory review phases.
- CAR-T Manufacturing Scale-Up:Academic medical centers in Massachusetts and New York are expanding GMP facility capacity to meet oncology department demand.
- CMS Reimbursement Clarity:Emerging coverage determinations for outpatient cell therapy administration improve site-of-service economics and patient access velocity.
Market Restraints
- Donor Eligibility Stringency:FDA's Center for Biologics Evaluation and Research enforces rigorous donor screening standards that extend facility qualification timelines and inflate lot-release testing costs.
- Cold-Chain Infrastructure Concentration:Cryopreservation capabilities cluster among limited third-party logistics providers, creating single-point vulnerability for autologous therapy distribution.
- Reprogramming Efficiency Ceilings:Current induced pluripotent stem cell protocols face differentiation consistency barriers that limit manufacturing yield predictability.
Strategic Opportunities
- Solid Tumor Indication Expansion:Hematologic malignancy success is creating clinical trial momentum for CAR-T applications in pancreatic and lung cancers.
- Adipose-Derived Protocol Standardization:Lipoaspirate extraction methods offer lower tumorigenic risk profiles than bone marrow harvests, opening outpatient clinic channels.
- NIH-Funded Cooperative Frameworks:Joint review initiatives with Health Canada accelerate early-stage trial design for cross-border patient recruitment.
Industry Challenges
- GMP Facility Talent Scarcity:Cell therapy manufacturing requires hybrid skill sets combining bioprocessing engineering with sterile operations expertise that outpaces training program output.
- Vector Safety Documentation:Lentiviral and retroviral construct characterization demands extensive biodistribution studies that strain analytical development timelines.
- Legacy EHR Integration:Patient tracking across apheresis, manufacturing, and infusion sites requires custom interoperability solutions absent from standard hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Stem Cell Therapy Market |
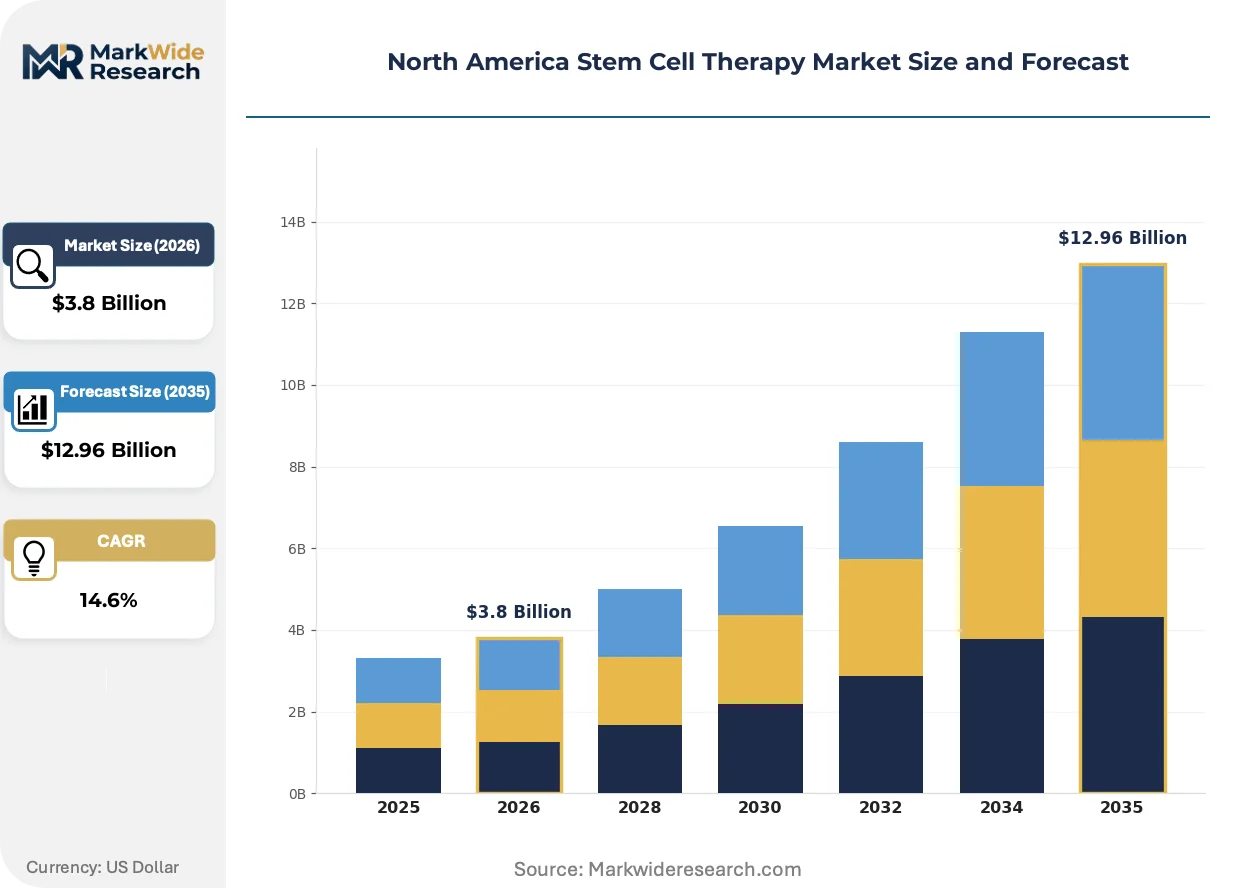
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Stem Cells, Embryonic Stem Cells, Induced Pluripotent Stem Cells, Cord Blood Stem Cells Application: Regenerative Medicine, Cancer Treatment, Cardiovascular Disorders, Orthopedic Disorders End User: Hospitals, Research Institutes, Biotech Companies, Academic Institutions Delivery Mode: Intravenous Injection, Local Administration, Direct Injection, Others |
| Companies Covered | Becton, Dickinson and Company, Thermo Fisher Scientific, Novartis AG, Bristol-Myers Squibb Company, Gilead Sciences (Kite Pharma), Fate Therapeutics, Mesoblast Ltd, Vertex Pharmaceuticals, Vericel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Stem Cell Therapy Market Evolving Landscape
Manufacturing automation and closed-system bioreactors are compressing production economics while digital supply chain tracking addresses chain-of-custody requirements for personalized therapies.
Closed-system automated bioreactors are replacing open culture vessels in GMP facilities, eliminating contamination risk and reducing cleanroom footprint requirements. Academic medical centers in Pennsylvania and New Jersey are adopting these platforms at pilot scale ahead of commercial manufacturing transfers. The shift is rendering obsolete manual cell culture expansion methods that previously required extensive operator intervention and environmental monitoring.
FDA's regenerative medicine advanced therapy designation creates parallel review pathways that compress the traditional phased clinical trial structure. This regulatory innovation enables earlier commercial dialogue and rolling submission strategies for qualifying therapies. Oncology indications with unmet need are responding fastest, with sponsors leveraging the designation to accelerate manufacturing process validation alongside clinical development.
Hospital procurement departments are consolidating vendor contracts into multi-year enterprise agreements that bundle apheresis collection, logistics, and manufacturing services. Integrated delivery networks in the Northeast corridor are displacing standalone transaction relationships with preferred partnership structures. Massachusetts-based oncology centers exhibit the most advanced procurement sophistication, negotiating outcome-aligned pricing tied to manufacturing success rates rather than per-procedure fees.
North America Stem Cell Therapy Market Segmentation
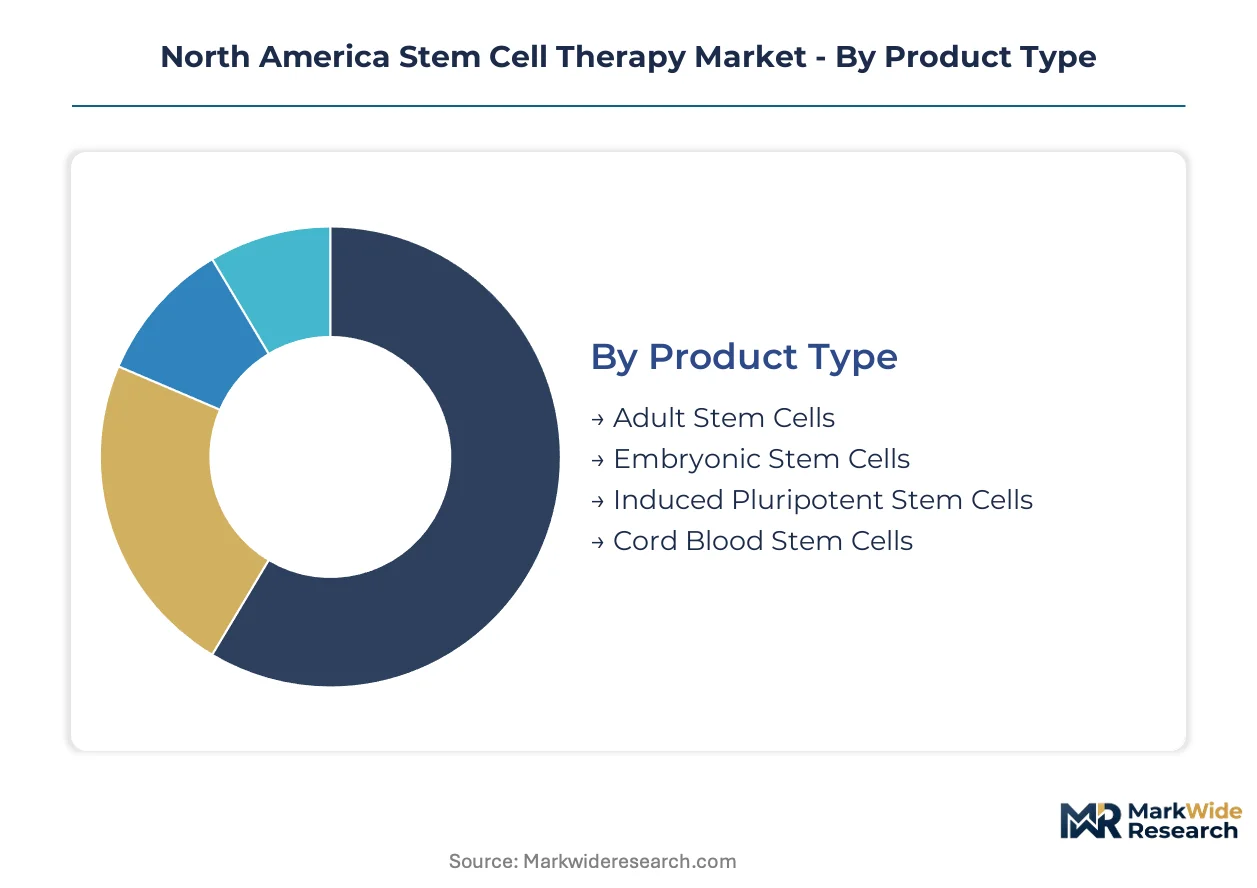
Segmentation in the North America stem cell therapy market reveals distinct procurement patterns, manufacturing requirements, and reimbursement pathways across cell sources, therapeutic targets, and institutional settings. Each dimension carries specific regulatory implications and capital intensity profiles that shape vendor selection and site-of-service economics.
Product Type:
Use-case spectrum spans autologous harvest protocols with established reimbursement codes to allogeneic platforms requiring novel manufacturing infrastructure and donor registries.
- Adult Stem Cells:Derived from bone marrow, adipose tissue, or peripheral blood with established extraction protocols and lower tumorigenic risk profiles. Demand concentrates in orthopedic and cardiovascular applications across Massachusetts and New York academic medical centers, driven by CMS coverage clarity for autologous procedures and mature GMP manufacturing standards.
- Induced Pluripotent Stem Cells:Reprogrammed somatic cells offering unlimited expansion potential and patient-matched immunocompatibility. Manufacturing investment is accelerating in Pennsylvania and New Jersey facilities, propelled by FDA's regenerative medicine advanced therapy designation enabling earlier-stage commercial dialogue for qualifying allogeneic platforms.
- Embryonic Stem Cells:Pluripotent lines with broad differentiation capacity facing ethical sourcing constraints and heightened regulatory scrutiny from the National Institutes of Health funding guidelines.
- Cord Blood Stem Cells:Hematopoietic progenitors banked at birth with established transplant protocols in pediatric oncology and emerging applications in regenerative indications.
The dominant share belongs to adult stem cells, while induced pluripotent stem cells are closing the gap fastest.
Application:
Cost tier stratification separates premium-priced chronic disease interventions from high-volume oncology procedures with established reimbursement pathways.
- Regenerative Medicine:Tissue repair applications targeting orthopedic, cardiovascular, and neurological conditions command premium pricing due to chronic disease prevalence and limited alternative therapies. Northeast corridor hospitals are expanding outpatient administration capacity, supported by emerging CMS coverage determinations for site-of-service economics.
- Cancer Treatment:CAR-T and TCR engineered cell therapies generate the highest absolute procedure volumes with established FDA approval pathways and dedicated manufacturing infrastructure. Novartis AG and Bristol-Myers Squibb Company anchor capacity in New Jersey and Pennsylvania, meeting oncology department demand at academic medical centers.
- Cardiovascular Disorders:Ischemic repair applications face clinical trial enrollment challenges and longer regulatory timelines compared to hematologic malignancy indications.
- Orthopedic Disorders:Autologous stem cell injections for joint repair operate in a reimbursement gray zone with variable private payer coverage across state lines.
Cancer treatment captures the highest procedure volume, with regenerative medicine applications commanding steepest expansion trajectory as chronic disease protocols mature.
End User:
Customer type determines procurement sophistication, with integrated delivery networks consolidating vendor relationships while research channels prioritize protocol flexibility over scale.
- Hospitals:Inpatient and outpatient facilities with apheresis collection capability, GMP manufacturing partnerships, and infusion infrastructure. Massachusetts-based oncology centers exhibit the most advanced procurement sophistication, negotiating outcome-aligned pricing tied to manufacturing success rates.
- Biotech Companies:Sponsors developing proprietary cell therapy platforms requiring contract manufacturing organization partnerships and regulatory submission support.
- Research Institutes:Early-stage protocol development with NIH funding priorities influencing trial design through cooperative review frameworks with Health Canada.
- Academic Institutions:Hybrid research-clinical entities expanding GMP facility capacity in the Northeast corridor to meet internal demand and external manufacturing contracts.
Hospitals retain procurement volume leadership, though biotech companies are gaining share fastest as sponsor-sponsored manufacturing displaces investigator-initiated production.
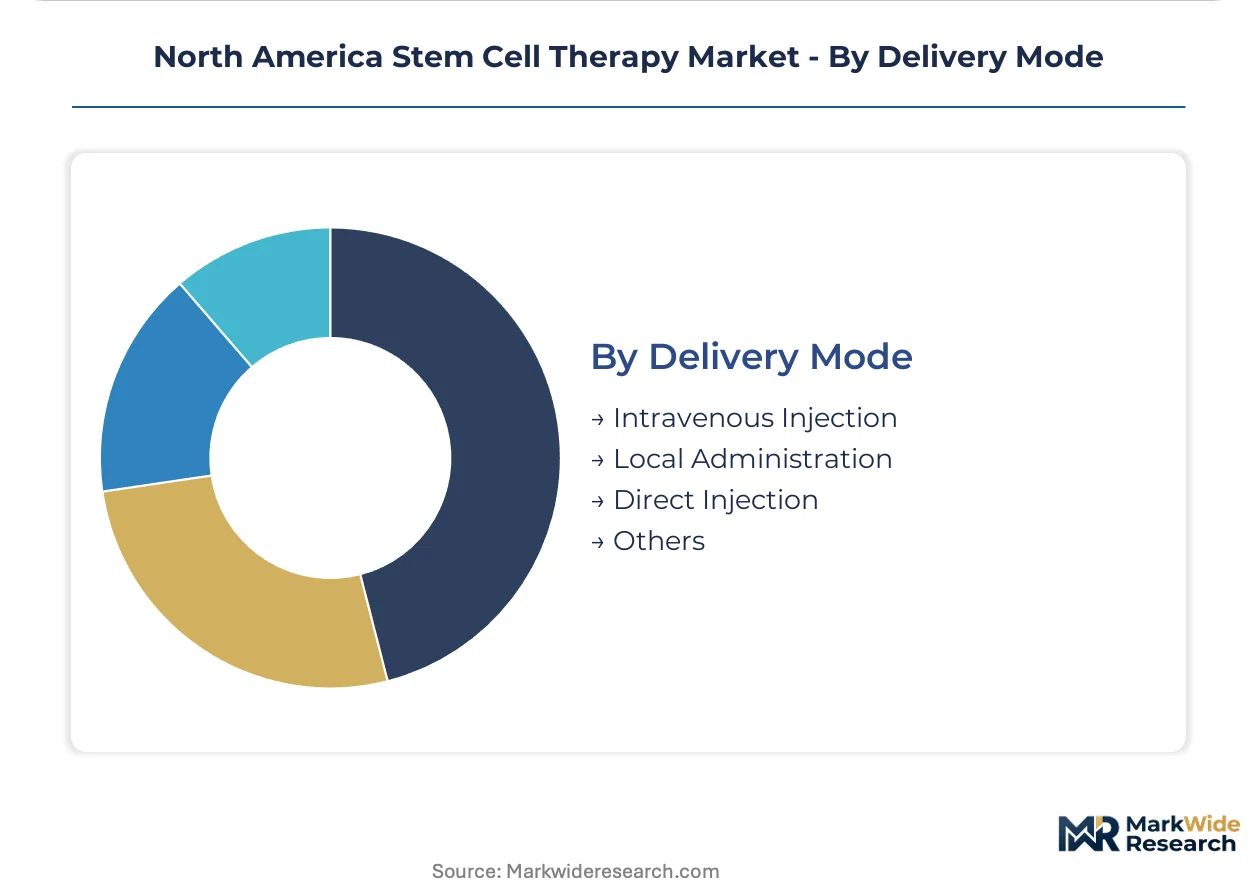
Delivery Mode:
Volume concentration in intravenous administration reflects oncology dominance, while direct injection protocols require specialized interventional infrastructure with limited site availability.
- Intravenous Injection:Systemic delivery standard for hematologic malignancy treatments with established nursing protocols and infusion center capacity. Demand clusters in academic medical centers with CAR-T experience and FDA-regulated cell processing capabilities.
- Direct Injection:Targeted administration to solid tumor sites or specific tissue compartments requiring interventional radiology or surgical collaboration. Adoption is limited by procedure complexity and site-specific training requirements.
- Local Administration:Topical or regional delivery for dermatologic and ophthalmic applications with distinct cold-chain and timing requirements.
- Others:Emerging routes including intrathecal and intra-arterial delivery under investigation for central nervous system and ischemic indications.
Intravenous injection maintains dominant utilization, with direct injection protocols climbing the fastest as solid tumor indications advance through clinical development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The I-95 pharmaceutical corridor linking Boston to Philadelphia underwrites North America's concentration in cell therapy development, with cold-chain logistics hubs and GMP manufacturing clusters distributed across this infrastructure backbone.
United States
FDA's RMAT designation accelerates commercial timelines for qualifying therapies, drawing sponsor investment toward Massachusetts and New York academic medical centers. CMS reimbursement determinations for outpatient administration reshape site-of-service economics across the Northeast corridor. Pennsylvania and New Jersey anchor CAR-T manufacturing capacity, with integrated delivery networks consolidating vendor relationships into multi-year enterprise agreements.
Canada
Health Canada's joint review frameworks with NIH accelerate early-stage trial design for cross-border patient recruitment. The country's national pharmaceutical regulator enforces donor eligibility standards aligned with FDA CBER guidelines, reducing regulatory friction for US-sponsored trials. Ontario and Quebec host emerging GMP facility investments targeting allogeneic platform manufacturing.
Mexico
COFEPRIS regulatory harmonization initiatives with FDA create pathways for clinical trial expansion into underserved patient populations. The national health regulator's accelerated review protocols attract sponsor interest for phase I/II site selection. Mexico City Metro and Nuevo León develop apheresis collection infrastructure to support regional manufacturing partnerships.
North America Stem Cell Therapy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying cryopreservation media, vectors, and automated bioreactors. The vendor structure concentrates among diversified life science conglomerates with captive manufacturing infrastructure and emerging cell therapy pure-plays dependent on contract manufacturing partnerships. Three archetypes dominate: integrated pharmaceutical conglomerates with CAR-T commercialization experience, diversified laboratory supply companies with cold-chain logistics dominance, and clinical-stage biotechs with induced pluripotent stem cell platforms. Competitive moves center on GMP facility capacity expansion in the Northeast corridor and strategic partnerships securing apheresis collection networks.
Among diversified laboratory supply companies, Thermo Fisher Scientific occupies a position exemplifying cryopreservation infrastructure dominance across the region. Within the pharmaceutical conglomerate tier, Novartis AG and Bristol-Myers Squibb Company represent archetypes of CAR-T manufacturing scale and diversified pipeline breadth respectively, with both anchoring capacity in New Jersey and Pennsylvania to serve oncology department demand at academic medical centers.
| Leading Market Players |
|---|
| Becton, Dickinson and Company |
| Thermo Fisher Scientific |
| Novartis AG |
| Bristol-Myers Squibb Company |
| Gilead Sciences (Kite Pharma) |
| Fate Therapeutics |
| Mesoblast Ltd |
| Vertex Pharmaceuticals |
| Vericel Corporation |
| Others |
Value Network & Pricing Analysis
New Jersey and Pennsylvania's CAR-T manufacturing cluster concentrates GMP capacity among Novartis AG and Bristol-Myers Squibb Company facilities, creating asymmetric pricing power for autologous cell therapies where production bottlenecks translate directly into premium capture for qualifying therapies with FDA's regenerative medicine advanced therapy designation.
Pricing Analysis
Volume-discount tiering structures separate academic medical center consortiums negotiating outcome-aligned pricing from standalone hospitals paying per-procedure fees. Price differentiation rests on manufacturing success rate guarantees versus transactional service bundles. Cost compression in autologous harvest protocols is intensifying as integrated delivery networks consolidate vendor relationships across the Northeast corridor. Biotech sponsors exhibit lowest price sensitivity due to RMAT-driven timeline acceleration, while outpatient clinics face highest sensitivity from CMS reimbursement uncertainty.
Supply Chain Analysis
Single-source vulnerability in cryopreservation media production between Thermo Fisher Scientific's regional distribution hubs and third-party logistics providers creates cold-chain fragility for personalized therapies. Geographic supply concentration centers on Massachusetts and New York for apheresis collection, Pennsylvania and New Jersey for GMP manufacturing, with Canada providing cross-border patient recruitment infrastructure. Raw material dependencies span lentiviral vector constructs, serum-free expansion media, and automated bioreactor platforms. Distribution runs through integrated delivery network enterprise agreements bundling collection, logistics, and manufacturing services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is emerging from a cyclical recovery driven by FDA's regenerative medicine advanced therapy designation compressing commercial timelines and restoring sponsor confidence after earlier clinical setbacks.
For Market Incumbents: Entrench manufacturing capacity advantages by expanding closed-system automated bioreactor deployment in New Jersey and Pennsylvania facilities before emerging biotechs achieve GMP qualification. Secure exclusive apheresis collection partnerships with Massachusetts and New York academic medical centers to lock in oncology department procurement channels against contract manufacturing organization competition. For New Entrants and Emerging Players: Pursue adipose-derived stem cell protocol standardization as the most penetrable white space, exploiting lower tumorigenic risk profiles to access outpatient clinic channels bypassing hospital GMP infrastructure requirements. Target Health Canada cooperative review frameworks for cross-border early-stage trial acceleration, leveraging joint NIH initiatives to reduce regulatory friction. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors induced pluripotent stem cell platform specialists with differentiated allogeneic manufacturing capabilities over hematologic malignancy-dependent CAR-T assets. Long-term viability hinges on solid tumor indication expansion success; monitor pancreatic and lung cancer clinical trial readouts as inflection indicators for platform scalability validation.| Strategic Initiative | Industry Significance |
|---|---|
| RMAT Designation Pursuit | FDA's expedited pathway compresses clinical development timelines for qualifying oncology therapies. |
| GMP Facility Automation | Closed-system bioreactor adoption eliminates contamination risk while reducing cleanroom footprint requirements. |
| Apheresis Network Partnership | Exclusive collection agreements with academic medical centers secure patient access velocity for autologous therapies. |
| Solid Tumor Pipeline Expansion | CAR-T applications in pancreatic and lung cancers represent highest-value indication diversification opportunity. |
| Cross-Border Trial Framework | Health Canada-NIH cooperative review accelerates patient recruitment across Canadian and US sites. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA Center for Biologics Evaluation and Research guidance documents, ClinicalTrials.gov protocol registrations, CMS reimbursement determinations, and integrated delivery network procurement contracts. Primary interviews engaged cell therapy manufacturing executives, hospital oncology department directors, regulatory affairs specialists at sponsor organizations, and GMP facility operations managers. Secondary validation drew from SEC 10-K disclosures, Health Canada joint review framework publications, and NIH funding priority announcements. Bottom-up procedure volume estimates triangulate against top-down market size assessments across the analysis window.
Forecast inputs span patient population incidence models, manufacturing facility capacity utilization rates, and CMS coverage determination timelines. Segmentation dimensions include cell source type, therapeutic application, end-user institutional category, and regional regulatory cluster. CAGRs derive from regression analysis of historical procedure growth patterns against sponsor pipeline progression milestones and GMP infrastructure investment cycles. Manufacturing automation adoption curves and RMAT designation award velocity inform trajectory assumptions throughout the projection horizon.
Sensitivities concentrate around FDA donor eligibility standard revisions, CMS reimbursement policy shifts for outpatient administration, and reprogramming efficiency breakthroughs in induced pluripotent stem cell protocols. Forecasts embed assumptions regarding cold-chain infrastructure stability and integrated delivery network consolidation velocity that operating reality may invalidate. Continuous validation against manufacturing success rate reporting and site-of-service economics is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
Global Lentiviral Vectors Market
Cell & Gene Therapy
RNA Therapy Clinical Trials Market
Cell & Gene Therapy
Viral Vector Production (Research-Use) Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Cell and Gene Therapy CDMO Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cancer Stem Cells Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market