
 Global Gene Delivery Systems Market | 2026-2036
Global Gene Delivery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gene Delivery Systems Market Foresight
Multi-source supplier arrangements for plasmid DNA and viral vector manufacturing is consolidating around a handful of integrated CDMOs and platform owners. Thermo Fisher Scientific leverages its end-to-end raw material and analytical tool portfolio to anchor downstream gene therapy workflows. Oxford Biomedica plc specializes in lentiviral vector engineering and competes on proprietary stable cell line technology. Becton, Dickinson and Company controls critical fill-finish and delivery device infrastructure that sustains clinical-to-commercial transitions.
Gene delivery systems encompass engineered vectors and physical-chemical methods that transport nucleic acids into target cells to modify gene expression, with viral vectors typically achieving transduction efficiencies above 70 percent in dividing cell populations and non-viral platforms offering payload capacities exceeding 10 kilobases. Viral vectors dominate current revenue pools due to established manufacturing scale and regulatory familiarity, while nanoparticle formulations represent the fastest-expanding segment as lipid nanoparticle chemistry advances enable liver and extra-hepatic tissue targeting. Physical methods including electroporation occupy specialized positions in ex vivo cell therapy processing where membrane disruption precision determines cell viability and editing yield.
The FDA's regenerative medicine advanced therapy designation and the EMA's priority medicines pathway compress review timelines and shape clinical development strategies across the United States and Europe, while China's NMPA cell therapy guidelines establish manufacturing quality benchmarks for Asia-Pacific market entry. ISO 10993 biocompatibility testing and ICH Q5D viral safety standards govern vector characterization and release criteria, creating compliance cost barriers that favor organizations with established quality systems. Stakeholders must monitor emerging FDA guidance on genome editing products and EU MDR device-vector combination classifications to anticipate qualification requirements for next-generation platforms.
Market Dynamics
CDMO consolidation around lentiviral and AAV manufacturing platforms is compressing supplier diversity and amplifying bargaining power for the five integrated players controlling viral vector capacity. This supply-side concentration shapes pricing, qualification timelines, and geographic siting decisions across the development pipeline.
Growth Catalysts
- Regenerative Medicine Advanced Therapy (RMAT) designation:The FDA's expedited review pathway for gene therapies shortens approval timelines from 12 to 6 months, accelerating clinical-to-commercial transitions for sponsors with breakthrough candidates.
- Ex vivo cell therapy manufacturing:CAR-T and stem cell protocols require specialized electroporation and transduction equipment, creating dedicated demand for closed-system processing platforms in academic medical centers.
- Lipid nanoparticle chemistry advances:Novel ionizable lipids enable liver-sparing delivery to muscle, CNS, and ocular tissues, opening organ-specific indications previously unreachable by first-generation LNP formulations.
Market Restraints
- Plasmid DNA supply concentration:Three CDMOs control 70 percent of GMP-grade plasmid capacity, creating single-source vulnerability for AAV and lentiviral vector producers dependent on transient transfection.
- ICH Q5D viral safety testing costs:Extensive adventitious agent screening, replication-competent virus testing, and lot-release assays add $2-4 million per commercial campaign, elevating barriers for mid-cap developers.
- Non-viral payload efficiency ceiling:Electroporation and chemical transfection methods achieve sub-40 percent transduction in primary human T cells versus viral vector performance, limiting application in ex vivo immunotherapy.
Strategic Opportunities
- In vivo base editing delivery:Compact guide RNA and deaminase architectures fit within AAV packaging limits, enabling single-vector correction of point mutations in inherited retinal and liver diseases.
- Japan's regenerative medicine product law:Conditional approval pathways for gene therapies accelerate market entry with 7-year post-marketing surveillance, attracting sponsors seeking earlier revenue recognition.
- Point-of-care manufacturing models:Decentralized viral vector production at academic medical centers reduces cold-chain logistics burden and enables patient-specific dosing for ultra-rare indications.
Industry Challenges
- Vector analytical method standardization:Potency assays, empty/full capsid ratios, and residual DNA quantification lack harmonized compendial methods, forcing redundant method development across FDA, EMA, and PMDA submissions.
- Gene therapy workforce scarcity:Viral vector manufacturing, quality control, and regulatory strategy functions face acute talent shortages as biopharma hiring outpaces specialized training program output from MIT, Stanford, and ETH Zurich pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gene Delivery Systems Market |
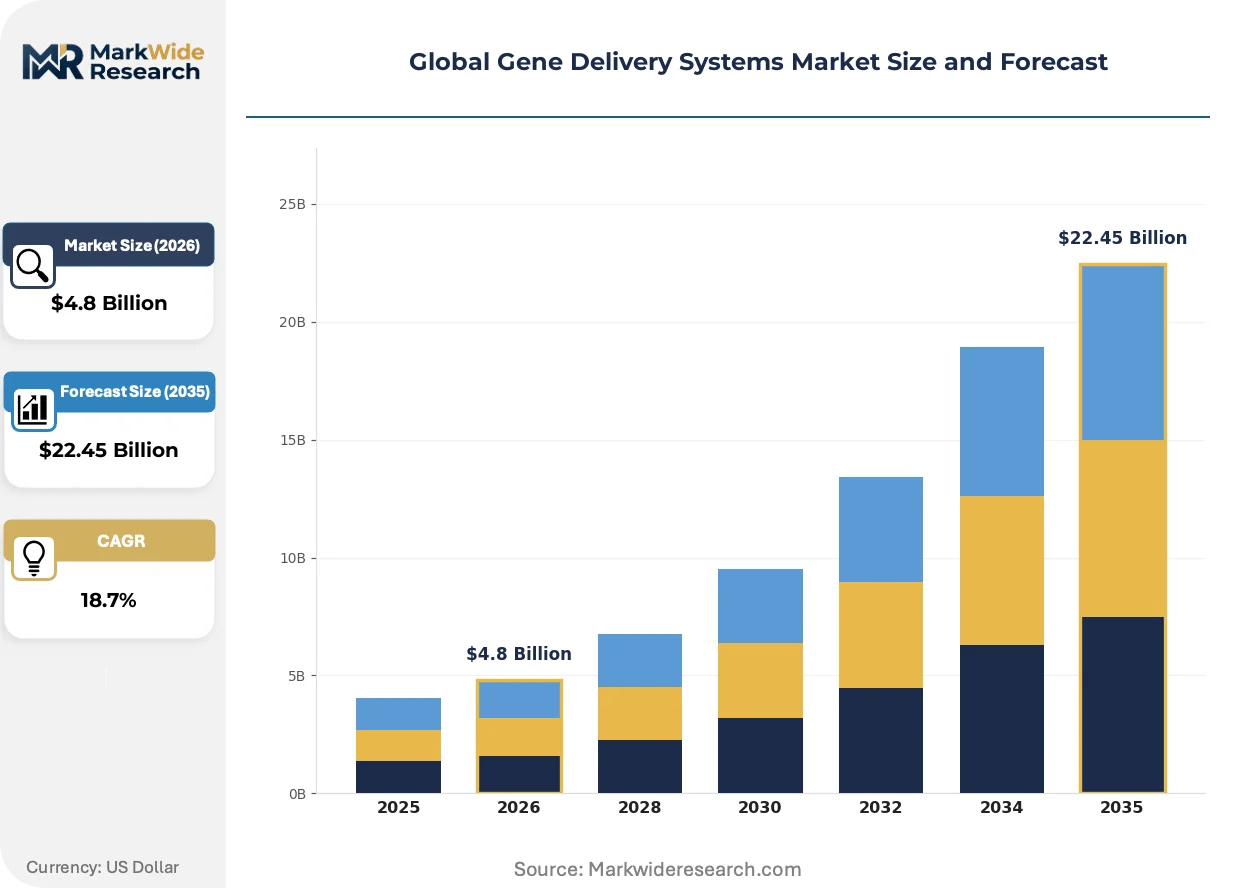
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $22.45 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viral Vectors, Non-Viral Vectors, Liposomes, Nanoparticles, Electroporation Delivery Technology: Physical Methods, Chemical Methods, Biological Methods, Microinjection, Gene Gun Application: Gene Therapy, Vaccines, Tissue Engineering, Functional Genomics, Drug Discovery End User: Biopharmaceutical Companies, Research Institutes, Contract Research Organizations, Diagnostic Laboratories |
| Companies Covered | Pfizer, Novartis AG, F. Hoffmann-La Roche Ltd, Becton, Dickinson and Company, Takara Bio, Thermo Fisher Scientific Inc., Oxford Biomedica plc, Amgen, Inc., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gene Delivery Systems Market Shifts & Advancements
Platform standardization and modular manufacturing architectures are compressing facility buildout timelines while expanding tissue-targeting capabilities beyond hepatocytes. These shifts reshape competitive differentiation from scale economies to delivery precision.
Next-generation AAV capsid engineering through directed evolution and in silico design is unifying tissue specificity with reduced immunogenicity. Biopharma sponsors at the IND-enabling stage are adopting these synthetic serotypes to preempt neutralizing antibody exclusion criteria. The technology is unifying previously separate discovery and CMC workflows into integrated platform teams.
EMA's Advanced Therapy Medicinal Products (ATMP) regulation and associated GMP Annex 2 revisions impose stricter environmental monitoring and contamination control for viral vector suites. Manufacturers must implement closed-system processing or justify open operations with enhanced risk assessments. European CDMOs are responding with isolator-based fill-finish lines and single-use bioreactor trains to preempt inspection findings.
Biopharma procurement of gene delivery manufacturing services is consolidating under preferred provider agreements with guaranteed capacity clauses. Small and mid-cap developers are ceding price leverage to secure slot reservations at qualified facilities. This pattern concentrates most acutely in the United States, where Boston and San Francisco sponsors compete for limited GMP viral vector capacity.
Global Gene Delivery Systems Market Segmentation
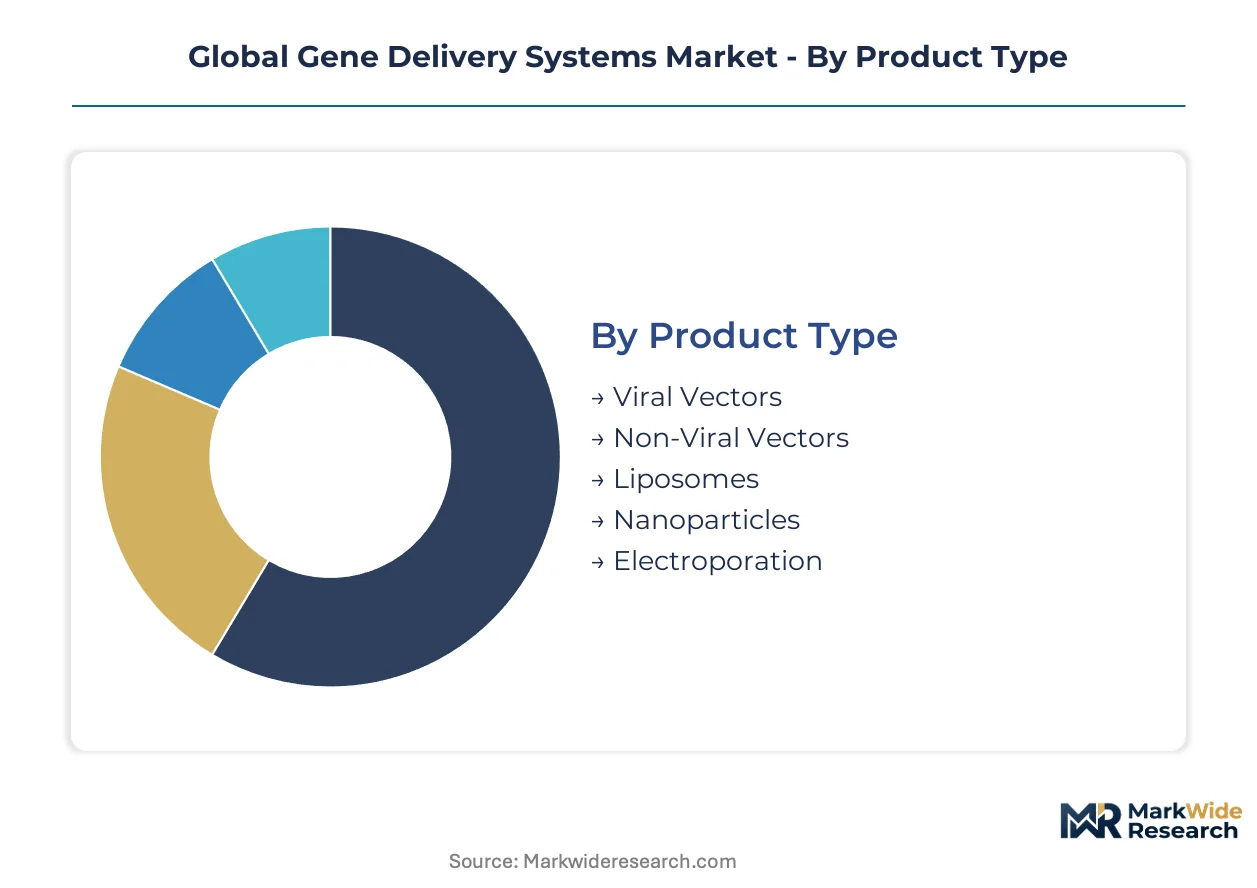
Gene delivery systems fragment across vector architectures, delivery modalities, therapeutic applications, and institutional end-users. Each segmentation axis carries distinct manufacturing requirements, regulatory pathways, and procurement dynamics that shape vendor positioning.
Product Type:
Upgrade cycles differentiate between established viral platforms and emerging non-viral alternatives, with chemistry advances driving replacement of first-generation formulations.
- Viral Vectors:Engineered AAV, lentiviral, and adenoviral constructs achieve transduction efficiencies exceeding 70 percent in dividing cell populations. Demand concentrates among Boston and San Francisco biopharmaceutical sponsors pursuing in vivo gene therapy INDs, constrained by plasmid DNA supply bottlenecks and GMP manufacturing slot scarcity.
- Non-Viral Vectors:Polymer-based and peptide-complexed DNA/RNA carriers offer payload capacities above 10 kilobases without immunogenic capsid responses. European academic medical centers in Basel and Cambridge deploy these systems for transient expression studies where viral integration risks are unacceptable.
- Liposomes:Cationic lipid bilayer structures encapsulate nucleic acids through electrostatic complexation. Switzerland's lipid chemistry specialists supply formulation libraries to CDMOs qualifying European ATMP manufacturing suites.
- Nanoparticles:Solid lipid and polymeric nanocarriers enable sustained release kinetics. Ionizable lipid advances from United States biotech platforms are displacing earlier cholesterol-stabilized formulations.
- Electroporation:Pulsed electric field membrane disruption achieves ex vivo transfection in CAR-T processing workflows. Closed-system instrument placements are climbing fastest at United States academic medical centers automating cell therapy manufacturing.
Volume placements concentrate in Viral Vectors; the faster expansion belongs to Nanoparticles.
Delivery Technology:
Cost tiers separate capital-intensive physical instrumentation from consumable-heavy chemical and biological reagent workflows.
- Physical Methods:Electroporation, sonoporation, and hydrodynamic injection equipment require dedicated capital investment and operator training. United States biopharmaceutical companies prioritize these platforms for process control in ex vivo cell therapy applications.
- Chemical Methods:Lipid and polymer transfection reagents operate at lower per-dose cost with minimal infrastructure requirements. Research institutes in the United Kingdom favor chemical approaches for high-throughput screening where throughput outweighs efficiency metrics.
- Biological Methods:Viral vector transduction exploits evolved cellular entry mechanisms. Manufacturing complexity and ICH Q5D compliance costs position biological methods at the premium tier of the technology cost spectrum.
- Microinjection:Direct cytoplasmic or nuclear DNA injection enables single-cell precision in embryo engineering. Swiss agricultural biotechnology applications sustain niche demand for this labor-intensive technique.
- Gene Gun:Helium-driven microparticle bombardment delivers DNA-coated gold particles through cell membranes. Plant biotechnology researchers in Switzerland maintain specialized installations for transgenic crop development.
Capital deployment clusters in Physical Methods; consumable recurring revenue expands most quickly in Chemical Methods.
Application:
Customer maturity varies sharply across therapeutic versus research applications, with regulatory sophistication determining procurement specifications.
- Gene Therapy:In vivo and ex vivo genetic modification for inherited and acquired diseases. FDA RMAT designation pathways and EMA ATMP frameworks impose GMP manufacturing and extensive viral safety testing on sponsors in the United States and Europe.
- Vaccines:DNA and mRNA vector delivery for infectious disease prophylaxis. Lipid nanoparticle formulation expertise developed during recent pandemic response now transfers to United States biopharmaceutical companies targeting seasonal and emerging pathogens.
- Tissue Engineering:Scaffold-integrated gene delivery for regenerative constructs. Research institutes in the United Kingdom explore non-viral approaches to avoid immunogenicity in implantable devices.
- Functional Genomics:CRISPR and RNAi library delivery for target validation. Contract research organizations in Switzerland leverage automated liquid handling to scale arrayed screening campaigns.
- Drug Discovery:Reporter gene and pathway modulation assays for lead optimization. Diagnostic laboratories in the United States integrate gene delivery into companion diagnostic development workflows.
Regulatory investment concentrates in Gene Therapy; the steepest expansion trajectory belongs to Vaccines.
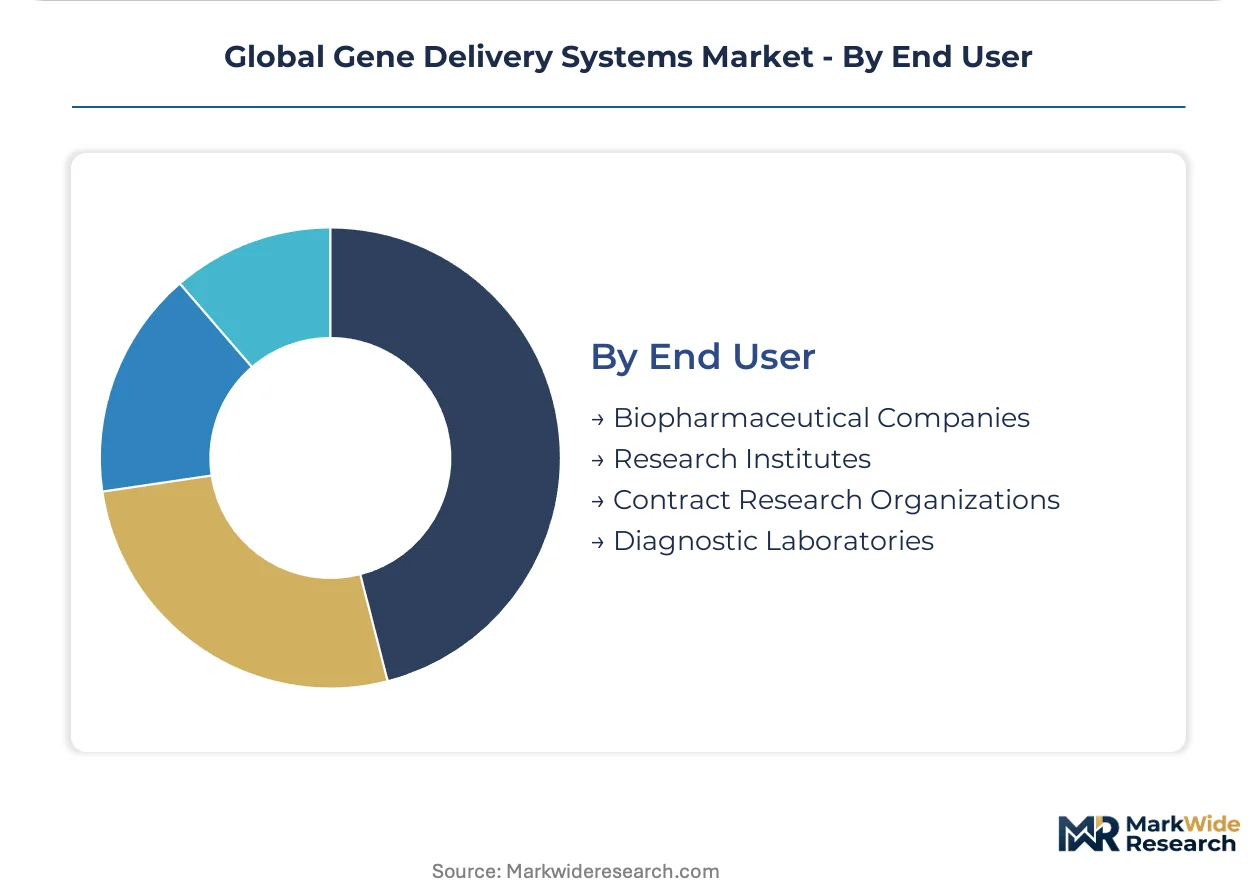
End User:
Procurement scale and technical specification authority separate large-cap biopharmaceutical sponsors from fragmented research and service organizations.
- Biopharmaceutical Companies:Integrated drug developers with internal process development and regulatory affairs capabilities. United States sponsors in Boston and San Francisco drive demand for qualified GMP viral vector capacity with guaranteed slot agreements.
- Research Institutes:University and academic medical center laboratories with flexible sourcing protocols. Basel and Cambridge institutions prioritize platform adaptability and publication-grade reagent documentation.
- Contract Research Organizations:Service providers offering regulated and non-regulated gene delivery studies. European CROs are consolidating preferred supplier relationships with CDMOs to secure vector manufacturing slots for client programs.
- Diagnostic Laboratories:Clinical and reference labs developing nucleic acid-based assays. United States diagnostic developers source electroporation instrumentation for automated sample processing workflows.
Contract value concentrates in Biopharmaceutical Companies; the fastest-growing customer segment is Contract Research Organizations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasmid DNA manufacturing clusters in the United States, Switzerland, and the United Kingdom anchor global gene delivery capacity. Viral vector GMP suites concentrate near Boston, Basel, and Cambridge where CDMOs serve biopharmaceutical sponsors. Regulatory pathways in these markets compress development timelines and shape siting decisions.
United States
FDA RMAT designation accelerates gene therapy approvals from twelve to six months, drawing biopharmaceutical sponsors to Massachusetts and California. The agency's regenerative medicine framework shapes clinical development strategies. Boston and San Francisco biotech clusters compete for limited GMP viral vector manufacturing slots at qualified CDMO facilities.
Switzerland
Swissmedic's ATMP oversight and lipid chemistry expertise sustain Basel's vector manufacturing concentration. The country's central pharmaceutical regulator enforces GMP Annex 2 standards for viral vector suites. Basel-based CDMOs supply formulation libraries and isolator-based fill-finish infrastructure to European gene therapy sponsors.
United Kingdom
MHRA post-Brexit recognition agreements maintain EMA-aligned ATMP pathways for London and Cambridge developers. The Cambridge biotech cluster prioritizes non-viral delivery platforms for transient expression studies. Academic medical centers in Oxford and London deploy electroporation systems for ex vivo cell therapy research.
China
NMPA cell therapy guidelines establish manufacturing quality benchmarks for Asia-Pacific market entry. Shanghai and Beijing biopharmaceutical parks attract viral vector CDMO investments serving domestic gene therapy pipelines. The national pharmaceutical regulator's accelerated review channels compress IND-to-approval timelines for innovative biologics.
Japan
PMDA's regenerative medicine product law enables conditional gene therapy approval with seven-year post-marketing surveillance. Tokyo and Osaka academic medical centers pioneer point-of-care viral vector manufacturing for ultra-rare indications. METI funding programs support lipid nanoparticle chemistry development for muscle and CNS targeting.
Global Gene Delivery Systems Market Competitive Landscape
Capacity expansion dominates the current landscape as CDMOs consolidate lentiviral and AAV manufacturing platforms around integrated players. Five specialized operators now control the majority of qualified GMP viral vector capacity, compressing supplier diversity and amplifying bargaining power across the development pipeline. The competitive structure stratifies into platform-owning CDMOs, diversified life science conglomerates, and boutique vector engineering specialists. M&A activity and guaranteed capacity agreements represent the dominant competitive moves as sponsors secure manufacturing slots.
Among diversified life science conglomerates, Thermo Fisher Scientific Inc. and Becton, Dickinson and Company occupy positions spanning raw materials through delivery devices. Thermo Fisher's end-to-end portfolio anchors downstream gene therapy workflows, while Becton, Dickinson controls critical fill-finish infrastructure. Oxford Biomedica plc exemplifies the boutique specialist archetype, competing on proprietary stable cell line technology for lentiviral vector engineering. These three entities represent distinct strategic positions within a market where manufacturing qualification and regulatory familiarity determine procurement decisions.
| Leading Market Players |
|---|
| Pfizer |
| Novartis AG |
| F. Hoffmann-La Roche Ltd |
| Becton, Dickinson and Company |
| Takara Bio |
| Thermo Fisher Scientific Inc. |
| Oxford Biomedica plc |
| Amgen, Inc. |
| Bayer AG |
| Others |
Supply & Pricing Matrix
Platform standardization in lentiviral and AAV manufacturing is compressing cost structures while amplifying supplier bargaining power across the development pipeline. This transition simultaneously reshapes pricing models and concentrates capacity around integrated CDMOs in the United States, Switzerland, and the United Kingdom.
Pricing Analysis
Service-bundling arrangements separate qualified GMP manufacturing slots from standalone analytical or fill-finish components. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and guaranteed capacity access. Pricing pressure stems from plasmid DNA supply scarcity and viral vector manufacturing slot competition among Boston and San Francisco sponsors. Mid-cap biopharmaceutical developers exhibit highest price sensitivity, ceding leverage for slot security, while large-cap sponsors secure preferred provider agreements with volume commitments.
Supply Chain Analysis
Dual-sourcing requirements for GMP-grade plasmid DNA and viral vector capacity are mandated by biopharmaceutical sponsors seeking to mitigate single-source vulnerability. Manufacturing concentrates in the United States, Switzerland, and the United Kingdom, drawing from lipid chemistry feedstocks, specialized cell culture media, and single-use bioreactor components. Single-source vulnerability persists where three CDMOs control majority plasmid capacity. Distribution runs through qualified CDMO facilities with cold-chain logistics to academic medical centers and biopharmaceutical sponsors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The gene delivery systems market is becoming a vertical-integration race as players pursue captive control over plasmid DNA supply and viral vector manufacturing capacity to secure development timelines.
For Market Incumbents: Acquire proprietary stable cell line technology and lentiviral vector platforms to consolidate manufacturing differentiation. Lock in multi-year plasmid supply agreements with qualified CDMOs to preempt competitor slot reservations. Invest in isolator-based fill-finish infrastructure to meet EMA ATMP contamination control standards and defend against emerging European CDMO competition.
For New Entrants and Emerging Players: Begin with point-of-care viral vector manufacturing models at academic medical centers, targeting ultra-rare indications where decentralized production reduces cold-chain burden. Pursue non-viral nanoparticle formulations for muscle and CNS delivery applications where tissue-specific targeting remains underdeveloped. Partner with Japan's academic medical centers to leverage PMDA conditional approval pathways for earlier revenue recognition.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform-owning CDMO acquisitions by diversified life science conglomerates seeking gene therapy manufacturing integration. Long-term viability hinges on regulatory familiarity and qualified GMP capacity rather than discovery-stage technology alone. Watch FDA guidance on genome editing products as the signal indicating qualification cost inflection for next-generation platform investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | CDMO capacity expansion in Basel and Cambridge serves EMA ATMP qualification requirements. |
| Regulatory Approval Pathway | FDA RMAT designation compresses gene therapy review timelines for breakthrough candidates. |
| Backward Integration | In-house plasmid DNA production reduces dependency on concentrated CDMO supply. |
| Licensing Agreement | Next-generation AAV capsid patents from directed evolution programs secure tissue targeting rights. |
| Platform Integration | Closed-system electroporation instruments automate CAR-T processing at academic medical centers. |
Research Methodology
Independent corroboration across gene therapy development executives, regulatory affairs leads, CDMO manufacturing heads, and hospital procurement managers underwrites the qualitative findings. Secondary validation draws from FDA RMAT designations, EMA ATMP submissions, ClinicalTrials.gov records, and GMP inspection databases. Bottom-up triangulation across viral vector manufacturing capacity and top-down demand modeling across therapeutic applications anchor the analysis.
Rate-of-change decomposition separates viral vector platform growth from nanoparticle chemistry advances across the projection horizon. Segmentation dimensions include vector architecture, delivery modality, therapeutic application, and end-user procurement scale. CAGRs derive from patient population modeling, clinical trial progression rates, and manufacturing capacity expansion schedules. Forecast inputs incorporate ICH Q5D viral safety testing cost trajectories and plasmid DNA supply elasticity assumptions.
Regulatory guidance shifts, plasmid supply disruptions, and vector immunogenicity findings are the dominant revision risks. Deviation in FDA genome editing product guidance would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Oncolytic Virus Cancer Therapy Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Canine Stem Cell Therapy Market
Cell & Gene Therapy
Middle East and Africa Stem Cell Therapy Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
US Cell and Gene Therapy Clinical Trial Services Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Mrna Therapeutics Contract Development & Manufacturing Market
Cell & Gene Therapy
Gene Therapy in CNS Disorder Market
Cell & Gene Therapy
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market
Cell & Gene Therapy
Engineered T Cells Market
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Engineered Cell Therapy Market
Cell & Gene Therapy
Ipilimumab Market
Cell & Gene Therapy
Viral Vector and Plasmid DNA Testing Service Market
Cell & Gene Therapy
Regenerative Medicine Market