
 High Density (HD) Cell Banking Market | 2026-2036
High Density (HD) Cell Banking Market Size, Share, and Industry Trends Forecast 2026-2036
High Density (HD) Cell Banking Market Foresight
Platform licensing revenue from automated cryopreservation systems is reshaping how vendors capture recurring value in the HD cell banking supply chain. Lonza Group leverages its integrated CDMO footprint to anchor large-scale master cell bank production for gene therapy sponsors. Thermo Fisher Scientific Inc. sustains technology leadership through controlled-environment storage hardware and biosafety testing services. Sartorius AG differentiates via single-use bioreactor systems that streamline upstream expansion before high-density banking.
High Density (HD) Cell Banking refers to the cryopreservation of mammalian cell populations at concentrations exceeding standard protocols, typically achieving cell densities above 10^7 cells per milliliter in controlled-rate frozen aliquots to maximize genetic stability and post-thaw viability for therapeutic manufacturing. Stem cell banking commands the largest value pool within cell type segmentation due to pluripotency requirements for regenerative medicine pipelines, while gene therapy application demand is expanding fastest as AAV and lentiviral vector producers require qualified master and working cell banks. Automated cryopreservation storage methods are displacing manual liquid nitrogen handling in pharmaceutical firm end-user facilities, driven by 21 CFR Part 11 compliance needs and sample chain-of-custody documentation.
FDA CMC guidance for cell and gene therapy products shapes HD cell banking standards through stringent characterization requirements for master cell banks submitted in IND applications. EMA's ATMP regulation and the EU GMP Annex 1 revision on sterile manufacturing further constrain facility design and environmental monitoring for European banking operations. ISO 20387 biobanking standards provide the quality management baseline that cross-border contract manufacturers must adopt to satisfy multiple national competent authorities. Stakeholders should monitor evolving FDA draft guidance on replication-competent virus testing and EMA qualification procedures for starting materials, as these will determine which banking providers retain market access.
Market Dynamics
Automated cryopreservation protocols are compressing contamination risk profiles while 21 CFR Part 11 compliance mandates force pharmaceutical end-users to abandon manual liquid nitrogen handling systems entirely.
Growth Catalysts
- FDA CMC Guidance Tightening:IND submission requirements for master cell bank characterization are compelling gene therapy sponsors to expand qualified banking capacity. The documentation burden favors vendors with established quality management systems.
- AAV Vector Manufacturing Scale-Up:Viral vector producers require cryopreserved master and working cell banks at densities exceeding 10^7 cells per milliliter to support commercial-scale gene therapy production.
- ISO 20387 Biobanking Standards:Cross-border contract manufacturers adopt these quality baselines to satisfy multiple national competent authorities, creating harmonized procurement criteria for banking services.
Market Restraints
- Liquid Nitrogen Supply Volatility:Cryopreservation infrastructure depends on stable industrial gas supply chains concentrated in Germany and the United States, exposing banking operations to input cost spikes and delivery interruptions.
- cGMP Facility Capital Intensity:Closed-system bioprocessing environments for high-density banking require specialized containment infrastructure that locks capital for extended depreciation cycles.
- Replication-Competent Virus Testing Burden:FDA draft guidance on expanded safety testing for viral vector master cell banks extends qualification timelines and elevates analytical validation costs.
Strategic Opportunities
- EU ATMP Regulatory Tailwind:The EMA's streamlined qualification procedures for starting materials in advanced therapy medicinal products creates market access advantages for banking providers with European manufacturing footprints.
- Stem Cell Pluripotency Banking:Regenerative medicine pipelines require qualified induced pluripotent stem cell banks, opening white space beyond traditional CHO and HEK293 banking services.
- Controlled-Rate Freezer Automation Convergence:Integration of biosafety testing workflows with automated cryopreservation hardware enables end-to-end platform licensing models that capture recurring revenue streams.
Industry Challenges
- Cell Culture Specialist Scarcity:cGMP-compliant high-density banking operations require personnel with combined expertise in aseptic processing, cryobiology, and regulatory documentation, a skill intersection with limited labor pool depth.
- Legacy Inventory System Integration:Pharmaceutical end-users face friction connecting automated cryopreservation hardware to existing LIMS and sample tracking infrastructure, complicating chain-of-custody documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Density (HD) Cell Banking Market |
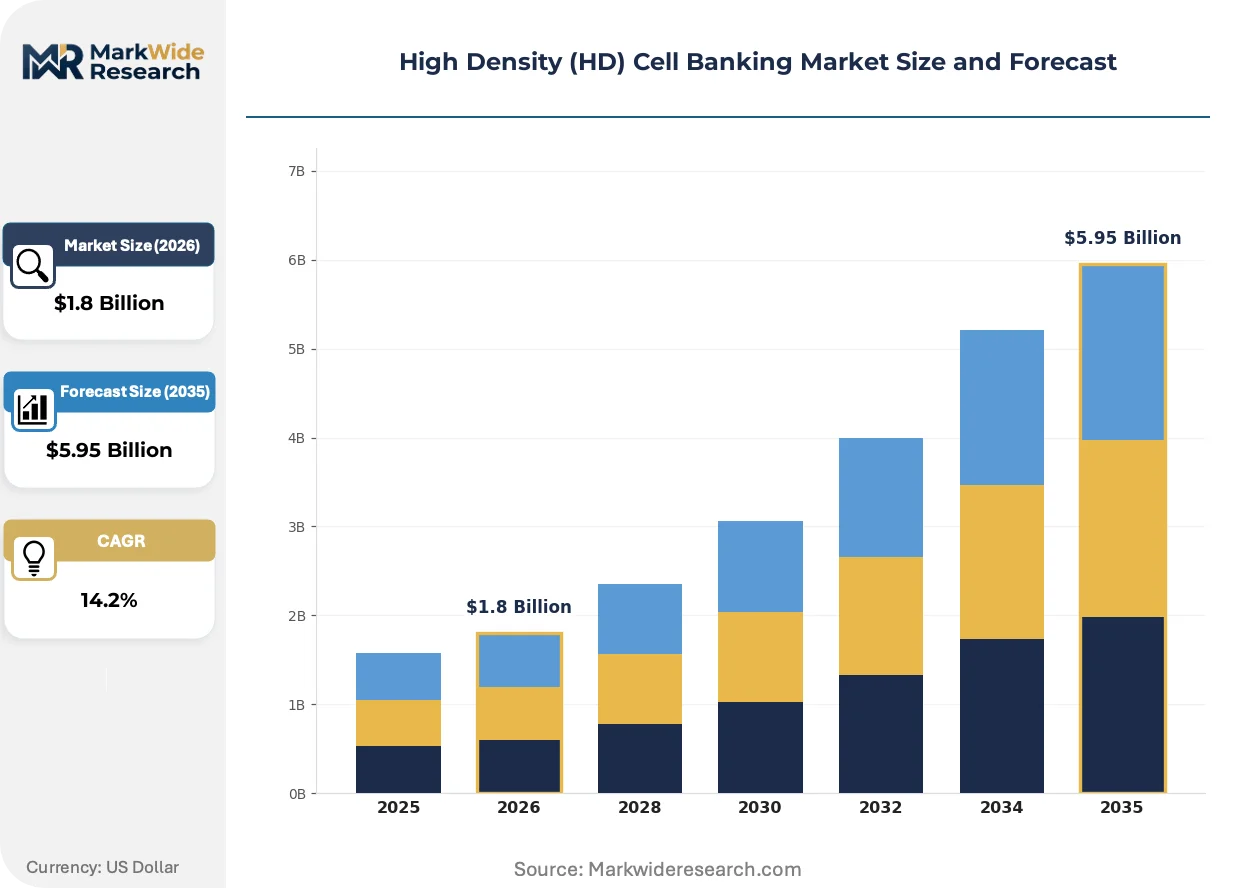
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Cell Type: Stem Cells, Immortalized Cells, Primary Cells, Hybridoma Cells Application: Bone Marrow Transplantation, Regenerative Medicine, Drug Development, Gene Therapy Storage Method: Liquid Nitrogen Freezing, Cryoprotectant-Based Storage, Lyophilization, Automated Cryopreservation End User: Biotechnology Companies, Research Institutions, Hospitals, Pharmaceutical Firms |
| Companies Covered | General Electric Company, Merck Millipore, Genzyme Corporation, Lonza Group, Thermo Fisher Scientific Inc., Repligen Corporation, Sartorius AG, Corning Incorporated, Pall Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Density (HD) Cell Banking Market Shifts & Advancements
Closed-system bioprocessing architectures are compressing contamination vectors while regulatory documentation automation reshapes vendor-customer contractual structures.
Controlled-rate freezing technology is migrating from pharmaceutical quality control laboratories into contract manufacturing organization production suites. Gene therapy CDMOs are adopting these systems at accelerated procurement cycles to meet IND submission deadlines. The technology shift is enabling platform licensing revenue models that displace traditional equipment sales with recurring per-sample service fees.
EMA's ATMP regulation revision tightens environmental monitoring requirements for sterile manufacturing zones used in master cell bank production. European banking facilities must upgrade HVAC and viable particle detection systems to maintain market access. Cell therapy sponsors with EU commercialization strategies are prioritizing banking partners with demonstrated Annex 1 compliance.
Buyers are consolidating vendor relationships around integrated platform providers that combine cryopreservation hardware, biosafety testing, and regulatory documentation services. Pharmaceutical firms are displacing fragmented procurement across multiple specialty suppliers with single-source master service agreements. The concentration pattern is most visible in United States gene therapy developer procurement, where IND timeline pressure favors streamlined vendor management.
High Density (HD) Cell Banking Market Segmentation
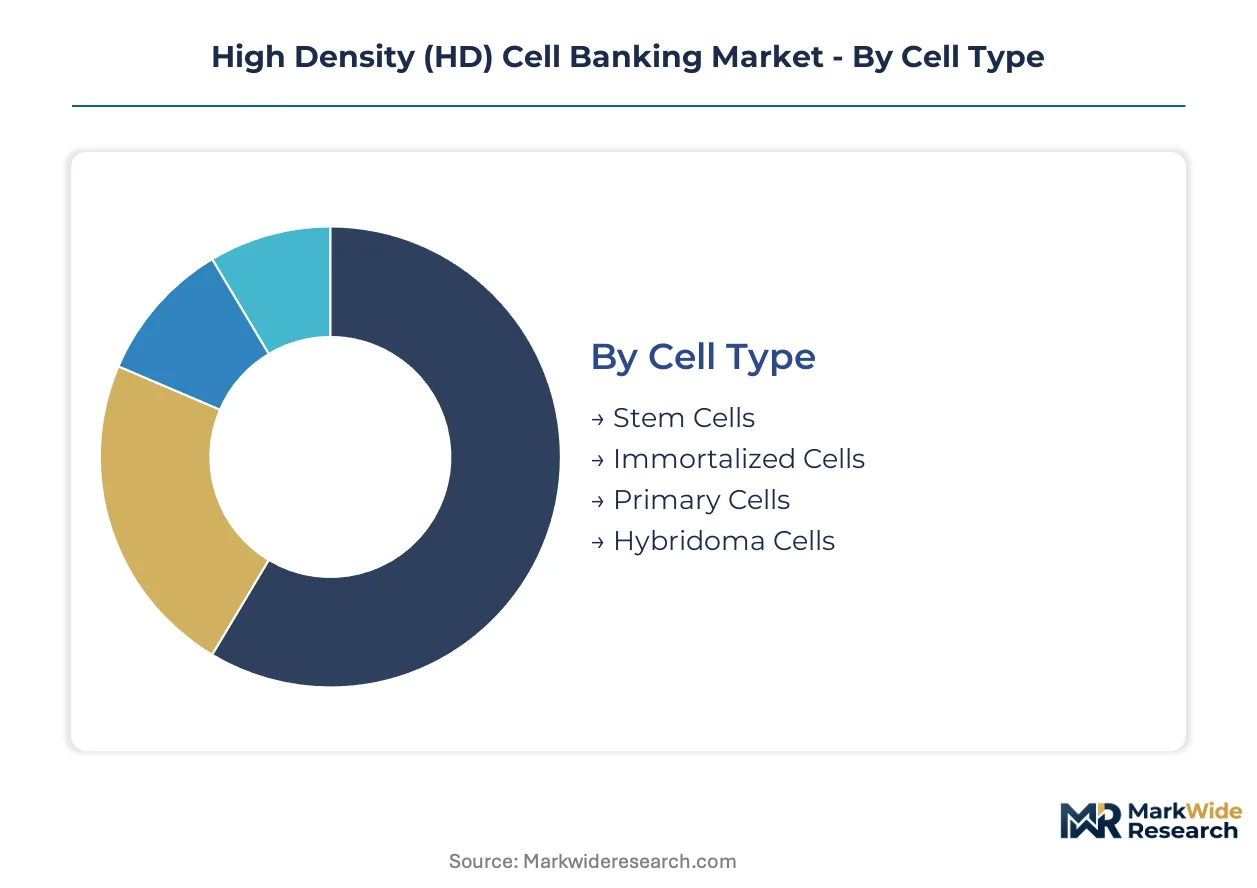
Segmentation in HD cell banking reveals distinct service intensity profiles across cell types and storage modalities. Each category carries unique equipment lifecycle demands and regulatory documentation burdens that reshape vendor-customer contractual structures.
Cell Type:
After-sales service intensity varies sharply by cell type, with pluripotent lines requiring ongoing characterization support and genetic stability monitoring that extends vendor relationships far beyond initial banking.
- Stem Cells:Induced pluripotent and embryonic stem cell banks demand rigorous karyotyping and teratoma formation assays to maintain therapeutic qualification. Gene therapy sponsors in the United States concentrate procurement here, driven by FDA IND submission timelines that require documented genetic stability across passage numbers. The service burden includes annual requalification and regulatory amendment support.
- Immortalized Cells:HEK293 and CHO derivative lines anchor commercial viral vector manufacturing with established master cell bank architectures. AAV producers require high-density cryopreservation exceeding 10^7 cells per milliliter to support fed-batch bioreactor seed trains, with vendor service contracts emphasizing rapid thaw validation and contamination testing turnaround.
- Primary Cells:Patient-derived fibroblasts and hematopoietic progenitors serve autologous cell therapy applications with limited expansion potential.
- Hybridoma Cells:Monoclonal antibody production lines retain niche demand in diagnostic and research reagent manufacturing.
Stem Cells holds the largest share; momentum sits with Immortalized Cells as viral vector manufacturing scales.
Application:
Application segmentation tracks divergent margin profiles, with clinical-stage therapeutic applications commanding premium pricing against research-use-only segments.
- Gene Therapy:AAV and lentiviral vector production requires qualified master and working cell banks with extensive replication-competent virus safety testing. United States-based CDMOs dominate procurement, with FDA CMC guidance tightening characterization documentation for IND submissions. The analytical validation burden creates sticky vendor relationships extending through commercial license.
- Regenerative Medicine:Allogeneic and autologous cell therapy pipelines require GMP-compliant stem cell banks with documented pluripotency maintenance. European sponsors leverage EMA ATMP streamlined qualification procedures, prioritizing banking partners with Annex 1 sterile manufacturing compliance and established starting materials dossiers.
- Bone Marrow Transplantation:Hematopoietic stem cell banking serves established clinical protocols with mature quality standards.
- Drug Development:Toxicology and pharmacokinetic screening drives demand for qualified hepatocyte and cardiomyocyte banks.
Gene Therapy captures the steepest expansion trajectory; Regenerative Medicine anchors current revenue concentration.
Storage Method:
Storage modality segmentation reflects capital deployment patterns, with automated systems displacing manual infrastructure through compliance-driven replacement cycles.
- Automated Cryopreservation:Controlled-rate freezing systems integrated with sample tracking software satisfy 21 CFR Part 11 electronic records requirements. Pharmaceutical firms in the United States are abandoning manual liquid nitrogen handling entirely, with platform licensing models replacing capital equipment purchases through per-sample service fees.
- Liquid Nitrogen Freezing:Conventional vapor-phase and liquid-phase storage retains installed base in research institutions with limited regulatory exposure.
- Cryoprotectant-Based Storage:DMSO and serum-free formulations balance post-thaw viability against cytotoxicity concerns in therapeutic applications.
- Lyophilization:Freeze-dried cell preservation remains experimental for mammalian systems, with limited commercial adoption outside microbial banking.
Automated Cryopreservation is gaining share fastest; Liquid Nitrogen Freezing retains the largest installed base.
End User:
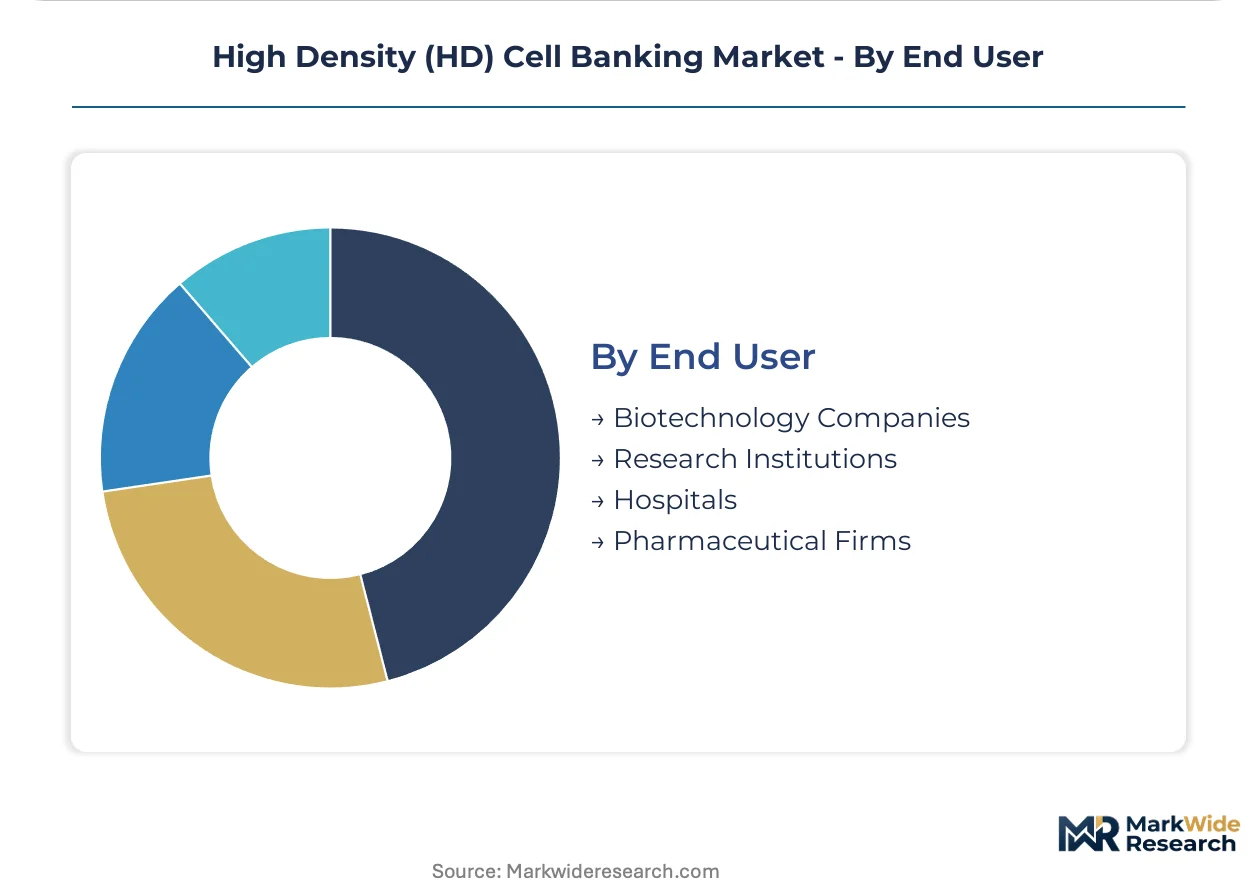
End user segmentation maps to procurement sophistication, with pharmaceutical firms driving standardization through master service agreements that consolidate fragmented vendor relationships.
- Pharmaceutical Firms:Gene therapy developers require integrated banking services combining cryopreservation hardware, biosafety testing, and regulatory documentation. These buyers consolidate procurement around single-source agreements with CDMOs like Lonza and Thermo Fisher, favoring vendors with demonstrated FDA Type II meeting support and IND amendment responsiveness.
- Biotechnology Companies:Venture-backed cell therapy sponsors prioritize flexible banking capacity with milestone-based scale-up terms.
- Research Institutions:Academic biobanks emphasize cost efficiency and multi-user access over cGMP compliance depth.
- Hospitals:Clinical cell therapy programs require point-of-care banking with chain-of-custody documentation for patient-specific applications.
Pharmaceutical Firms hold the largest share; Biotechnology Companies show the fastest procurement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes HD cell banking services through gene therapy CDMO partnerships at densities exceeding other geographies, while European sponsors prioritize EMA-aligned starting materials qualification and Asian markets emphasize cost-optimized stem cell repository scale.
United States
FDA IND submission timelines drive procurement of qualified master cell banks with 21 CFR Part 11 documentation systems. The agency's CMC guidance for cell and gene therapy products mandates extensive replication-competent virus safety testing. Greater Boston anchors viral vector manufacturing expansion, with CDMOs installing automated cryopreservation suites to meet sponsor deadlines.
Germany
EMA's ATMP regulation and EU GMP Annex 1 revision constrain sterile manufacturing facility design for banking operations. Industrial gas supply chains concentrated in the Rhine-Ruhr region expose cryopreservation infrastructure to input cost volatility. Bavaria's biotech corridor hosts contract manufacturers upgrading HVAC and viable particle detection systems for Annex 1 compliance.
Switzerland
Swissmedic's alignment with EMA procedures enables streamlined qualification for advanced therapy starting materials. The country's precision manufacturing heritage supports high-density banking equipment fabrication. Basel's pharmaceutical cluster integrates cryopreservation hardware with biosafety testing workflows for end-to-end platform offerings.
United Kingdom
Post-Brexit divergence from EU regulatory frameworks creates documentation complexity for cross-border banking services. The MHRA maintains ATMP oversight while sponsors navigate dual-track qualification requirements. London's cell therapy developers consolidate vendor relationships around integrated platform providers with demonstrated regulatory responsiveness.
China
NMPA's evolving cell therapy guidance shapes domestic banking standards through characterization requirements for clinical trial applications. Local sponsors prioritize indigenous master cell bank capacity to reduce import dependency. Shanghai's Zhangjiang Hi-Tech Park hosts bioreactor and cryopreservation equipment manufacturing for regional supply.
High Density (HD) Cell Banking Market Competitive Landscape
Capability concentration sits with integrated CDMOs possessing regulatory documentation expertise; scale advantage sits with diversified life science conglomerates with captive storage hardware portfolios. The market structures around three tiers: full-service contract manufacturers, equipment-and-service platform licensors, and specialized consumables suppliers. Consolidation pressures favor vendors with combined cryopreservation hardware, biosafety testing, and FDA Type II meeting support capabilities. Dominant competitive moves include strategic partnerships between equipment manufacturers and testing service providers, plus geographic expansion through qualified facility replication.
Within the integrated CDMO tier, Lonza Group and Thermo Fisher Scientific Inc. occupy positions anchoring large-scale master cell bank production for gene therapy sponsors. Sartorius AG exemplifies the equipment-specialist archetype, with single-use bioreactor systems streamlining upstream expansion before high-density banking operations. These three entities represent distinct strategic postures: full-service manufacturing partnership, controlled-environment storage and testing integration, and upstream process equipment specialization.
| Leading Market Players |
|---|
| General Electric Company |
| Merck Millipore |
| Genzyme Corporation |
| Lonza Group |
| Thermo Fisher Scientific Inc. |
| Repligen Corporation |
| Sartorius AG |
| Corning Incorporated |
| Pall Corporation |
| Others |
Supply & Pricing Matrix
Rhine-Ruhr industrial gas corridors anchor cryopreservation logistics costs, concentrating supply-side leverage among German and United States nitrogen suppliers while downstream price differentiation separates cGMP-compliant banking services from research-grade alternatives. This freight-cost geography compels contract manufacturers to absorb input volatility or pass through to gene therapy sponsors with long-term offtake agreements.
Pricing Analysis
Long-term offtake contracts dominate pharmaceutical procurement, with master service agreements locking in multi-year pricing for integrated cryopreservation, biosafety testing, and regulatory documentation bundles. Price differentiation separates FDA Type II meeting-ready vendors from research-grade suppliers through certification depth and IND amendment responsiveness. Cost compression in stem cell banking intensifies as induced pluripotent line characterization standardizes. Biotechnology companies exhibit highest price sensitivity due to milestone-dependent funding cycles, while commercial-stage gene therapy developers prioritize compliance reliability over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with Lonza Group, Thermo Fisher Scientific, and Sartorius AG, whose integrated platforms control qualified master cell bank production capacity across Switzerland, Germany, and the United States. Raw material dependencies center on liquid nitrogen supply, cryoprotectant formulations, and single-use bioreactor consumables. Single-source vulnerability in industrial gas supply chains concentrated in Germany exposes banking operations to delivery interruptions. Distribution runs through direct CDMO-sponsor partnerships with limited spot-market intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment moat, where FDA CMC documentation requirements and ISO 20387 quality baselines create switching costs that cement incumbent positions.
For Market Incumbents: Insulate market position through backward integration into cryopreservation hardware fabrication and captive biosafety testing capacity, neutralizing emerging platform licensors threatening service bundling advantages. Prioritize capacity addition in Greater Boston and Basel to anchor viral vector manufacturing clusters. Defend against automated cryopreservation specialists by embedding regulatory amendment responsiveness into standard service contracts. For New Entrants and Emerging Players: China's NMPA-aligned banking capacity represents underpenetrated territory where indigenous master cell bank demand outstrips qualified domestic supply. Target stem cell repository scale-up for allogeneic cell therapy sponsors seeking cost-optimized alternatives to Western CDMOs. Pursue joint venture structures with established equipment manufacturers to shortcut biosafety testing workflow integration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life science conglomerates with underutilized cryopreservation hardware divisions lacking regulatory documentation depth. Long-term viability hinges on platform licensing revenue displacement of capital equipment sales, favoring vendors with recurring service fee architectures. Monitor FDA draft guidance finalization on replication-competent virus testing as inflection signal for qualification timeline compression and vendor consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Documentation Automation | FDA 21 CFR Part 11 compliance mandates force pharmaceutical end-users toward integrated platform providers with electronic records capabilities. |
| Controlled-Rate Freezer Platform Licensing | Per-sample service fees displace capital equipment purchases, capturing recurring revenue from gene therapy CDMO procurement cycles. |
| EMA Annex 1 Facility Upgrades | European banking operations must upgrade HVAC and viable particle detection systems to maintain advanced therapy starting materials access. |
| Stem Cell Pluripotency Banking Expansion | Induced pluripotent stem cell characterization services open white space beyond traditional CHO and HEK293 banking architectures. |
| Liquid Nitrogen Supply Diversification | Industrial gas supply chain concentration in Germany and the United States exposes operations to input cost spikes and delivery risk. |
Research Methodology
A spread of perspectives from gene therapy development executives, regulatory affairs leads at CDMOs, bioprocess engineers, and hospital cell therapy program directors converged on the working assumptions underlying this analysis. Primary interviews combined with secondary validation from FDA CMC guidance documents, EMA ATMP qualification procedures, ISO 20387 biobanking standards, and SEC 10-K filings from listed life science conglomerates. Bottom-up cell banking capacity estimates triangulated against top-down gene therapy pipeline forecasts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning cell type, application, storage method, and end user. CAGRs derived from installed base replacement cycles for manual liquid nitrogen systems and viral vector manufacturing scale-up trajectories. Industry-specific inputs included IND submission timelines, replication-competent virus testing burden evolution, and automated cryopreservation adoption curves.
Practitioners should monitor FDA draft guidance finalization, EMA starting materials qualification procedure revisions, and liquid nitrogen supply chain disruptions for early signals of forecast revision. Quarterly review of IND submission rejection rates, CDMO capacity utilization disclosures, and cryopreservation equipment order backlogs is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Cellular Immunotherapy Market
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
Leukemia Therapeutics Treatment Market
Cell & Gene Therapy
Stem Cell Concentration System Market
Cell & Gene Therapy
RNA Therapy Clinical Trials Market
Cell & Gene Therapy
Stem Cell and Gene Therapy Biological Testing Market
Cell & Gene Therapy
Asia Pacific Cancer Biological Therapy Market
Cell & Gene Therapy
Europe Viral Vector Purification Market
Cell & Gene Therapy
Global Mrna Therapeutics Market
Cell & Gene Therapy
Inherited Orphan Blood Disorders Therapeutics Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Natural Killer (NK) Cell Therapeutics Market
Cell & Gene Therapy
Global Therapeutic Vaccines Market
Cell & Gene Therapy
Neoantigen Targeted Therapies Market
Cell & Gene Therapy
Stem Cell Therapy Market
Cell & Gene Therapy
North America Gene Therapy Market