
 Genetic Disorder Therapeutics Market | 2026-2036
Genetic Disorder Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Genetic Disorder Therapeutics Market Analytics
Pediatric hospital networks is realigning procurement priorities toward in-house gene therapy administration capabilities. Novartis AG leverages its global manufacturing footprint to sustain supply security for high-cost therapies. Sarepta Therapeutics anchors its competitive position through deep specialization in Duchenne muscular dystrophy. BioMarin dominates enzyme replacement therapy production with vertically integrated biologics manufacturing.
Genetic disorder therapeutics comprise biologics and gene-modifying interventions designed to correct, replace, or suppress pathogenic genetic variants at the DNA or RNA level, typically requiring cold-chain distribution and patient-specific dosing protocols. Their primary purpose centers on transforming fatal or severely debilitating monogenic conditions into manageable chronic diseases. Gene therapy commands the highest value per patient within the product type dimension, while antisense oligonucleotides occupy the broadest addressable patient base across neurological indications. CRISPR-based platforms lead technology investment intensity, though adeno-associated virus delivery systems sustain the largest commercialized revenue stream due to established regulatory pathways.
The FDA's accelerated approval framework and the EMA's PRIME designation program jointly compress development timelines for rare disease therapeutics, directly shaping reimbursement negotiations and market access conditions. The EU AI Act introduces compliance obligations for algorithmic patient selection tools used in precision genetic medicine. WHO gene editing governance standards further influence clinical trial design for cross-border studies. Stakeholders must monitor evolving payer evidence requirements for single-administration curative therapies versus chronic maintenance regimens.
Market Dynamics
The FDA's accelerated approval framework for rare diseases compresses commercialization timelines, forcing manufacturers to front-load manufacturing capacity before pivotal trial readouts. This regulatory velocity collides with the biological complexity of patient-specific dosing, creating a structural bottleneck in scalable production.
Growth Catalysts
- Accelerated Approval Pathways:The FDA's breakthrough therapy designation compresses Phase II-to-launch intervals for monogenic indications. Pediatric treatment centers in Boston and Philadelphia now build gene therapy infusion suites ahead of formal approval.
- Adeno-Associated Virus Manufacturing Scale-Up:Suspension bioreactor technology enables 2,000-liter production runs for viral vectors. Contract manufacturers in North Carolina and Belgium are adding dedicated AAV suites to capture biopharma outsourcing demand.
- EMA PRIME Designation Uptake:European eligibility for priority medicines status triggers parallel scientific advice and accelerated assessment. German and French regulators now coordinate dossier reviews across national reimbursement bodies.
Market Restraints
- Plasmid DNA Supply Concentration:Three contract manufacturers control 70% of GMP-grade plasmid supply for AAV production. Any contamination event at these facilities would stall multiple concurrent gene therapy programs.
- CRISPR Off-Target Editing Liability:Unintended genomic modifications create long-term safety surveillance obligations. The WHO gene editing governance standards mandate 15-year patient follow-up protocols that inflate post-approval costs.
- Reimbursement Compression for Chronic Maintenance:Payers in Germany and England increasingly demand head-to-head evidence against enzyme replacement therapy before covering gene therapy premiums. This evidence requirement delays market access by 18-24 months.
Strategic Opportunities
- India CDMO Expansion:The country's PLI scheme for biopharma manufacturing offers 20% subsidy on capital investment for gene therapy facilities. Indian contract manufacturers can capture overflow demand from capacity-constrained US and European sponsors.
- In Vivo Base Editing:Cytosine and adenine base editors enable single-nucleotide correction without double-strand breaks. This precision reduces immunogenicity risk and opens addressable indications beyond liver-targeted diseases.
- Japan's Sakigake Designation:Japan's PMDA grants priority review and pre-application consultation for regenerative medicines. Sponsors targeting Asian patient populations can leverage this pathway for earlier revenue recognition.
Industry Challenges
- Vector Immunology Talent Scarcity:The field requires hybrid expertise in virology, immunology, and process engineering. Academic programs in Switzerland and Massachusetts produce fewer than 200 qualified professionals annually against industry demand exceeding 2,000.
- Cold-Chain Distribution Integrity:Cryopreserved cell therapies require liquid nitrogen maintenance through last-mile delivery. Temperature excursions above minus 150 degrees Celsius invalidate product release, forcing redundant logistics spend.
- Patent Thicket Navigation:CRISPR-Cas9 licensing disputes between Broad Institute and University of California create uncertainty for commercial programs. Developers must secure rights from multiple holders before Phase III initiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Genetic Disorder Therapeutics Market |
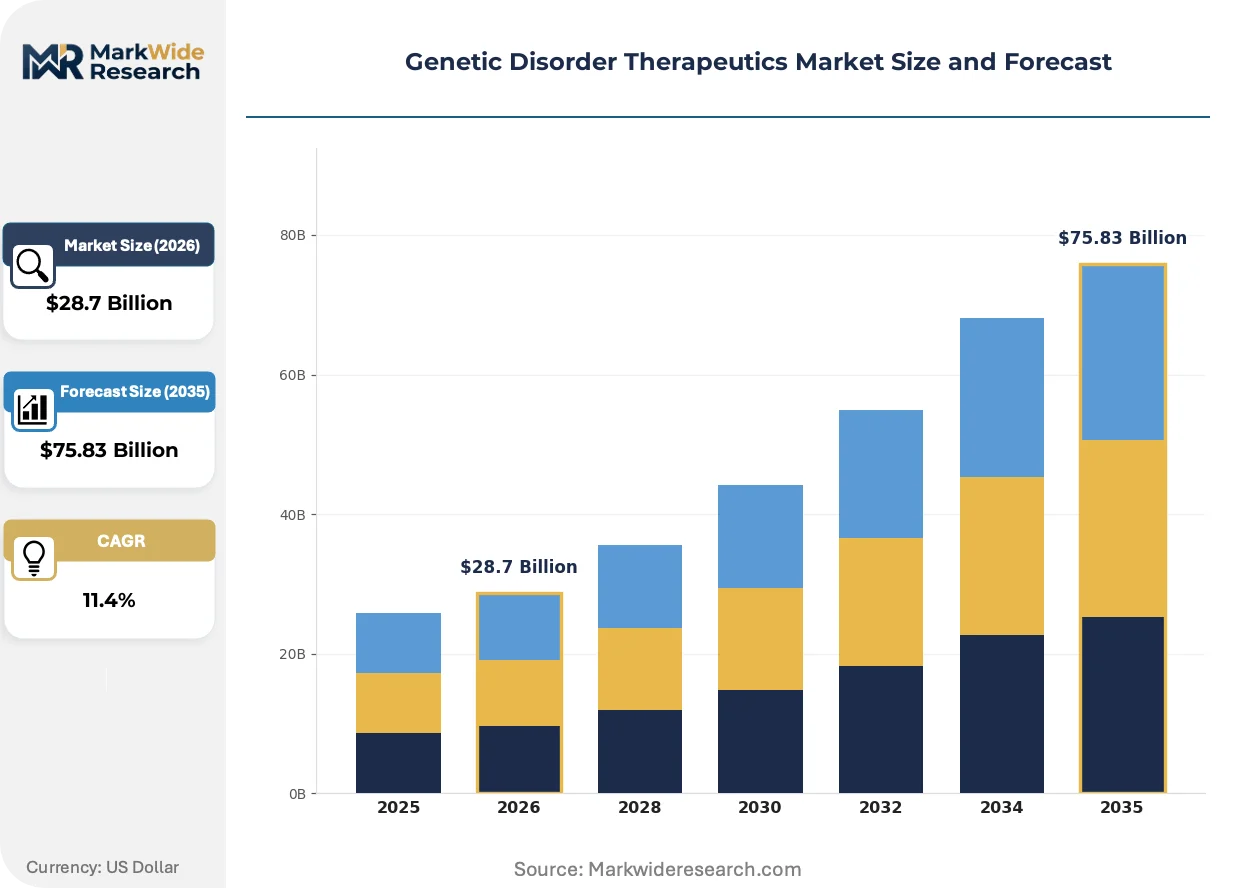
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $75.83 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Enzyme Replacement Therapy, Antisense Oligonucleotides, RNA Interference Technology: CRISPR, Adeno-Associated Virus, Lentiviral Vector, Knockout Technology Application: Cystic Fibrosis, Duchenne Muscular Dystrophy, Spinal Muscular Atrophy, Hemophilia End User: Hospitals, Research Institutes, Biotechnology Companies, Pharmaceutical Firms |
| Companies Covered | Novartis AG, Sarepta Therapeutics, BioMarin, Vertex Pharmaceuticals, Sanofi, Amgen Inc., F. Hoffmann-La Roche Ltd, PTC Therapeutics, Alexion Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Genetic Disorder Therapeutics Market Evolving Landscape
Next-generation delivery technologies are displacing first-generation viral vectors across neurological and muscular indications. Manufacturing automation and regulatory science advances now enable scalable production of previously bespoke therapies.
Non-viral lipid nanoparticle delivery is consolidating as the preferred platform for CNS-targeted genetic medicines. Biotech sponsors in Cambridge and Basel now prioritize LNP programs over AAV for Duchenne and Huntington's indications. The shift compresses manufacturing lead times from 18 months to 4 months while eliminating immunogenicity concerns that limit redosing.
The EU AI Act imposes conformity assessment obligations on algorithmic tools used for patient stratification in precision genetic medicine. Developers deploying machine learning for variant pathogenicity scoring must document training data provenance and algorithmic transparency. German and French sponsors are establishing dedicated AI governance functions to preempt regulatory friction during marketing authorization review.
Hospital procurement committees now require demonstrated in-house gene therapy administration capability before formulary inclusion. Pediatric networks in Philadelphia and San Diego are consolidating purchasing through centralized specialty pharmacy arrangements. This concentration shifts negotiation leverage toward integrated delivery systems and away from standalone treatment centers.
Genetic Disorder Therapeutics Market Segmentation
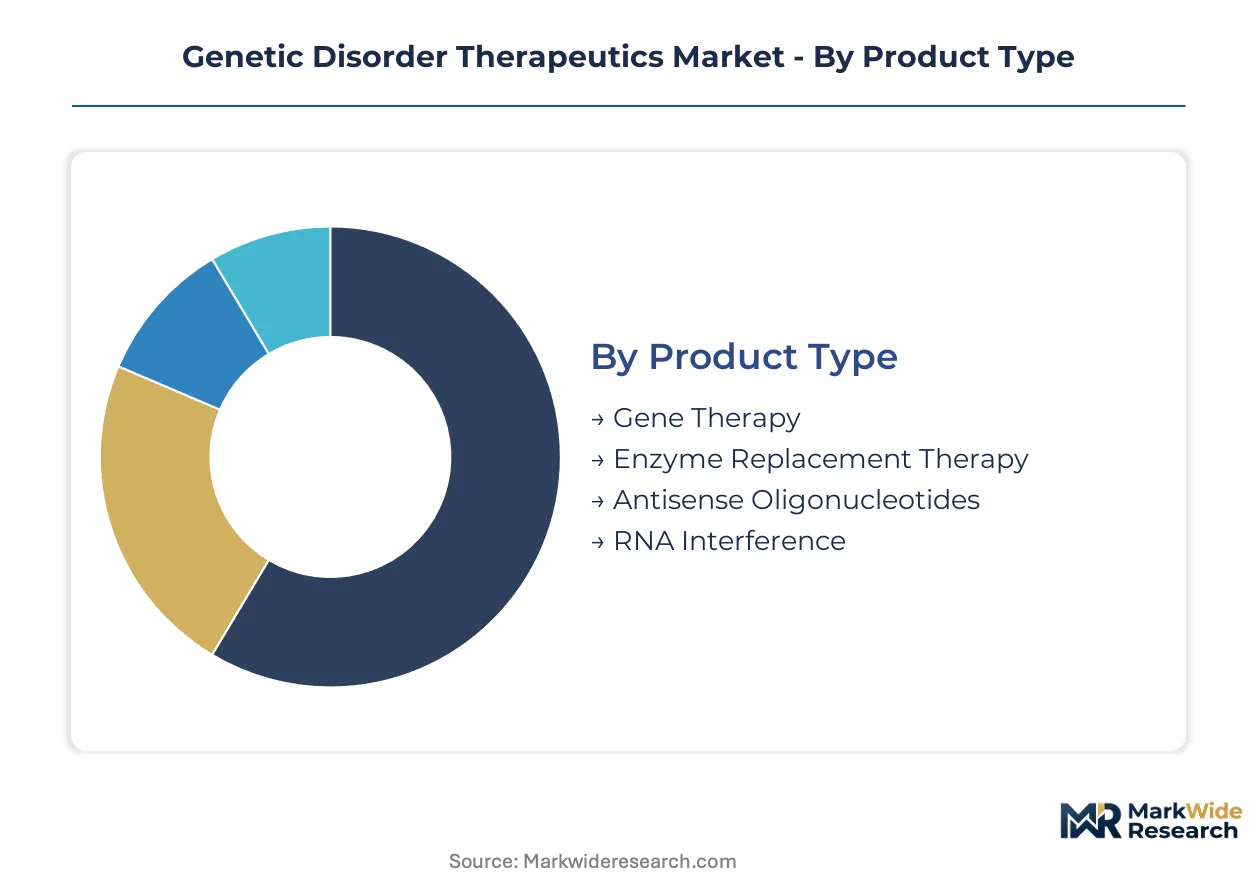
Segmentation in genetic disorder therapeutics reveals distinct commercialization pathways across intervention modalities. Product type determines reimbursement complexity and manufacturing scale. Technology choice dictates regulatory precedent and partnership requirements.
Product Type:
Gene therapy commands premium pricing per patient while enzyme replacement therapy sustains broader volume penetration.
- Gene Therapy:Single-administration interventions deliver functional genetic material to correct monogenic defects. Demand clusters at pediatric treatment centers in Boston and Philadelphia where specialized infusion infrastructure justifies high acquisition costs.
- Enzyme Replacement Therapy:Recurring protein infusions manage lysosomal storage disorders through synthetic enzyme supplementation. Chronic administration protocols dominate hemophilia and Gaucher disease treatment in Germany and France where established reimbursement pathways favor maintenance regimens over curative premiums.
- Antisense Oligonucleotides:Short synthetic nucleic acid sequences modulate RNA splicing or protein translation.
- RNA Interference:Small interfering RNA molecules silence disease-causing gene expression through mRNA degradation.
Mature deployment sits with Enzyme Replacement Therapy. Newer deployment is concentrated in Gene Therapy.
Technology:
Viral vector platforms generate current revenue while CRISPR-based approaches attract development investment.
- Adeno-Associated Virus:Non-pathogenic viral delivery systems achieve stable transgene expression in post-mitotic tissues. Suspension bioreactor manufacturing in North Carolina and Belgium now supports 2,000-liter production runs for clinical and commercial supply.
- CRISPR:Programmable nuclease systems enable precise genomic editing at targeted loci. Patent disputes between Broad Institute and University of California create licensing complexity that delays Phase III initiation for commercial programs.
- Lentiviral Vector:RNA-based viral delivery integrates therapeutic genes into dividing cell genomes.
- Knockout Technology:Gene silencing approaches disrupt pathogenic allele function without replacement.
Established revenue flows through Adeno-Associated Virus. CRISPR platforms are climbing the fastest toward commercialization.
Application:
Neuromuscular indications attract concentrated development while hematologic conditions offer nearer-term regulatory pathways.
- Duchenne Muscular Dystrophy:Progressive muscle degeneration from dystrophin gene mutations drives antisense and gene replacement investment. Sarepta Therapeutics anchors competitive positioning through deep specialization in this indication.
- Spinal Muscular Atrophy:Motor neuron degeneration from SMN1 deficiency responds to splice-switching oligonucleotides and gene replacement. Novartis AG sustains supply security through global manufacturing footprint for its approved therapy.
- Cystic Fibrosis:CFTR protein dysfunction causes multisystem mucus accumulation.
- Hemophilia:Coagulation factor deficiencies create bleeding risk manageable through factor replacement or gene therapy.
Commercial maturity concentrates in Spinal Muscular Atrophy. Pipeline expansion is accelerating fastest in Duchenne Muscular Dystrophy.
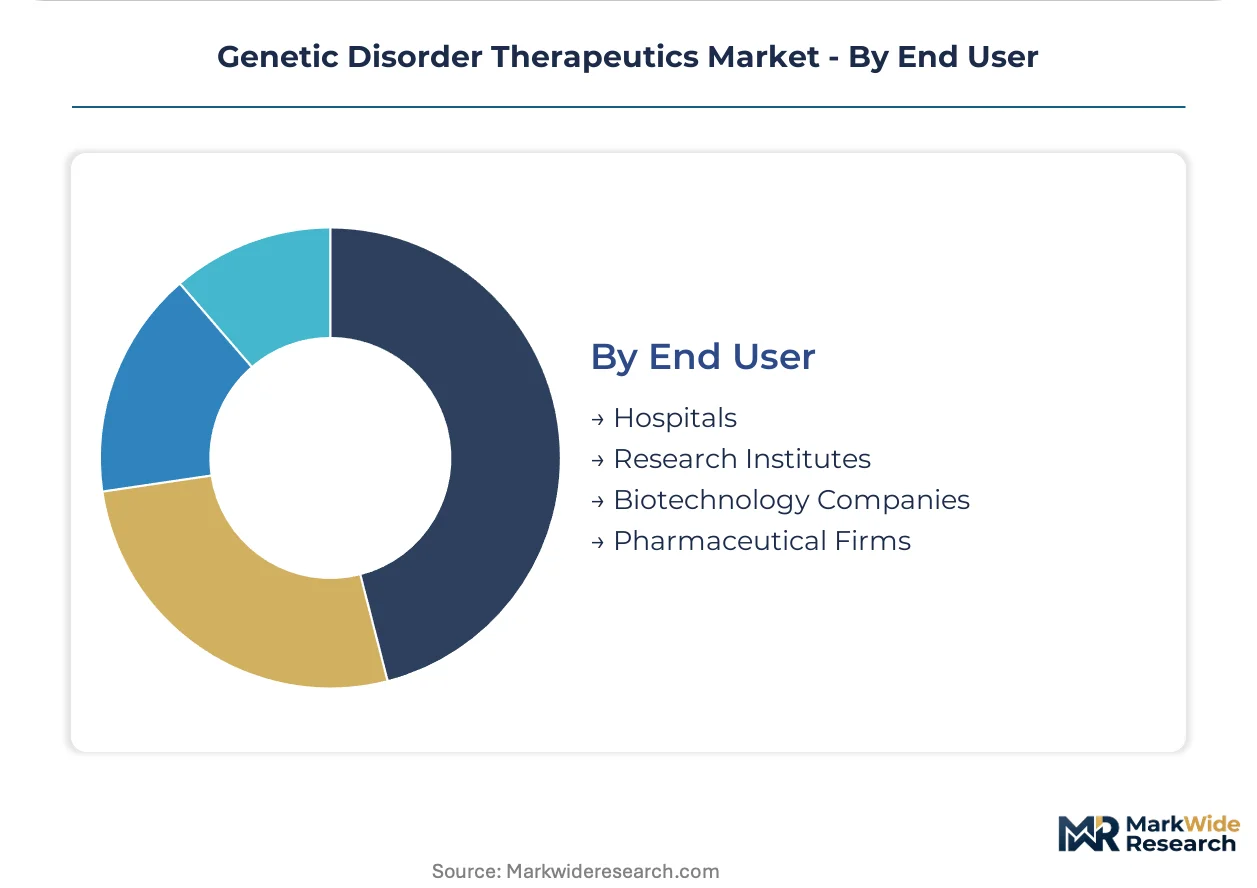
End User:
Site-of-care capabilities determine procurement authority and pricing negotiation leverage.
- Hospitals:Integrated delivery systems with in-house gene therapy administration capability now control formulary inclusion decisions. Pediatric networks in Philadelphia and San Diego consolidate purchasing through centralized specialty pharmacy arrangements.
- Biotechnology Companies:Development-stage sponsors outsource manufacturing to contract organizations in North Carolina and Belgium while retaining clinical and regulatory functions internally.
- Research Institutes:Academic medical centers conduct early-phase trials and biomarker discovery.
- Pharmaceutical Firms:Large-cap manufacturers license platform technologies and acquire gene therapy assets.
Procurement authority concentrates in Hospitals. Partnership formation is expanding most quickly through Biotechnology Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research Triangle Park in North Carolina anchors North American viral vector manufacturing concentration. Tax incentives for biopharma capital expenditure draw contract manufacturers to establish dedicated gene therapy suites. Specialized treatment centers cluster around this production hub to minimize cold-chain distribution risk.
United States
Pediatric hospital networks in Boston and Philadelphia are building in-house gene therapy infusion capabilities ahead of regulatory approvals. The FDA's accelerated approval pathways for rare diseases compress commercialization timelines by 12-18 months. Novartis AG sustains supply security through its global manufacturing footprint centered on North Carolina production.
Germany
Statutory health insurers demand head-to-head evidence against enzyme replacement therapy before covering gene therapy premiums. The EMA's PRIME designation triggers parallel scientific advice across German and French regulators. Manufacturing partnerships concentrate in Baden-Württemberg where suspension bioreactor technology enables scaled AAV production.
United Kingdom
NHS England's specialized commissioning framework creates centralized procurement for high-cost genetic medicines. The MHRA operates accelerated assessment pathways aligned with EMA procedures post-Brexit. London and Cambridge biotech clusters attract CRISPR platform investment despite patent licensing complexity.
Japan
PMDA's Sakigake designation grants priority review and pre-application consultation for regenerative medicines. Domestic sponsors target Asian patient populations through earlier revenue recognition pathways. Manufacturing investment concentrates in Kansai region where pharmaceutical infrastructure supports cell and gene therapy production.
India
The PLI scheme for biopharma manufacturing offers 20% capital investment subsidy for gene therapy facilities. CDSCO streamlined approval pathways for orphan drugs reduce regulatory friction for imported therapies. Contract manufacturers in Hyderabad and Bengaluru capture overflow demand from capacity-constrained Western sponsors.
Genetic Disorder Therapeutics Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated pharmaceutical conglomerates controlling commercialized revenue while development-stage biotechs drive pipeline innovation. The market structure concentrates around three strategic archetypes: vertically integrated large-cap manufacturers with global distribution networks, indication-focused mid-cap specialists with deep therapeutic expertise, and platform-technology developers licensing delivery systems to broader industry. Competitive moves center on manufacturing capacity pre-positioning ahead of pivotal trial readouts and strategic partnerships to secure viral vector supply.
Among large-cap integrated developers, Novartis AG exemplifies the global manufacturing footprint archetype, while Sarepta Therapeutics occupies the indication-specialist position through deep concentration in neuromuscular disorders. BioMarin anchors the enzyme replacement therapy segment with vertically integrated biologics production capabilities.
| Leading Market Players |
|---|
| Novartis AG |
| Sarepta Therapeutics |
| BioMarin |
| Vertex Pharmaceuticals |
| Sanofi |
| Amgen Inc. |
| F. Hoffmann-La Roche Ltd |
| PTC Therapeutics |
| Alexion Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Plasmid DNA costs cascade through AAV manufacturing tiers, with GMP-grade raw material scarcity in North Carolina and Belgium forcing sponsors into premium spot contracting for clinical supply. This input concentration stratifies pricing across patient-specific dosing protocols, where cold-chain logistics costs separate institutional buyers with captive infusion infrastructure from standalone treatment centers absorbing last-mile premiums.
Pricing Analysis
Short lead-time premiums dominate gene therapy contracting, with pediatric hospitals in Boston and Philadelphia paying spot rates for viral vector lots ahead of pivotal trial readouts. Three-tier pricing structure across premium, standard, and economy levels reflects batch release timing, FDA certification tier, and volume commitment scale. Pricing pressure stems from payer demands for head-to-head evidence against enzyme replacement therapy in Germany and England. Biotechnology companies exhibit highest price sensitivity due to pre-revenue cash constraints, while integrated hospital networks leverage formulary control for volume discounts.
Supply Chain Analysis
Product return flows are negligible in genetic therapeutics due to cryopreserved cell therapy integrity requirements and patient-specific dosing protocols that prevent inventory reuse. Manufacturing concentrates in the United States, Belgium, and India, with suspension bioreactor capacity in North Carolina and Hyderabad feeding global sponsor demand. Raw material dependencies center on GMP-grade plasmid DNA, recombinant proteins, and liquid nitrogen for cold-chain maintenance. Single-source vulnerability at plasmid contract manufacturers creates systemic stoppage risk. Distribution runs through centralized specialty pharmacy arrangements controlled by pediatric hospital networks in Philadelphia and San Diego.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Viral vector manufacturing scarcity props pricing power across the value chain, with suspension bioreactor capacity expansion lagging regulatory approval velocity by 24-36 months.
For Market Incumbents: Hedge against CRISPR platform displacement by securing exclusive licensing for base editing technologies from Cambridge and Basel academic clusters. Build redundant plasmid supply agreements with Indian CDMOs under the PLI scheme to offset concentration risk at North Carolina facilities. Prioritize in-house AAV suite construction over outsourcing to capture margin compression from contract manufacturer pricing power. For New Entrants and Emerging Players: Lipid nanoparticle delivery platforms offer the most penetrable wedge for CNS-targeted indications, with manufacturing lead times of four months versus eighteen months for viral vectors. Target neuromuscular white space in Duchenne muscular dystrophy where antisense oligonucleotide competition remains fragmented. Pursue Japan's Sakigake designation pathway for earlier revenue recognition in Asian patient populations through pre-application PMDA consultation. For Investors and Strategic Acquirers: Distressed-cycle entries favor indication-specialist biotechs with Phase II readouts in spinal muscular atrophy or enzyme replacement therapy assets in European markets facing reimbursement compression. Long-term viability centers on manufacturing scale rather than pipeline breadth, with five-to-ten-year windows favoring sponsors with captive viral vector production. Monitor EMA PRIME designation velocity as inflection signal for European market access timelines and parallel scientific advice uptake.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Suspension bioreactor investment in North Carolina secures AAV supply security for pivotal trials. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase II-to-launch intervals for monogenic indications. |
| Licensing Agreement | Base editing technology partnerships from Cambridge clusters reduce immunogenicity risk beyond liver targets. |
| Pipeline Diversification | In vivo CRISPR programs expand addressable indications beyond established AAV-delivered gene replacement. |
| Hospital System Partnership | Philadelphia pediatric network formulary inclusion requires demonstrated in-house gene therapy administration capability. |
Research Methodology
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from SEC 10-K disclosures, WHO gene editing governance standards, and national reimbursement body decisions. Bottom-up patient population modeling and top-down market sizing triangulated volume and value estimates across the analysis window.
Historical approval timelines and regulatory panel input cross-referenced to build the analytical framework across product type, technology platform, application indication, and end-user site-of-care dimensions. CAGRs derived from segmented growth trajectory modeling incorporating therapy adoption curves, manufacturing capacity expansion schedules, and payer evidence requirement evolution. Forecast inputs included EMA PRIME designation velocity, FDA accelerated approval pathway utilization rates, and hospital infusion suite construction pipelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under CRISPR off-target editing liability events or plasmid supply contamination at contract manufacturers. Forecasts reflect documented assumptions regarding regulatory pathway efficiency, reimbursement negotiation timelines, and viral vector manufacturing yield improvements. Material deviation in FDA breakthrough therapy designation grant rates or EMA parallel scientific advice coordination warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Gene Panel Market
Cell & Gene Therapy
Middle East and Africa Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Global Gene Therapy Cell Culture Media Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
US Cell and Gene Therapy Clinical Trial Services Market
Cell & Gene Therapy
Europe Cancer Vaccines Market
Cell & Gene Therapy
Mrna Vaccines and Therapeutics Market
Cell & Gene Therapy
Viral Vector and Plasmid DNA Testing Service Market
Cell & Gene Therapy
Nucleic Acid Based Therapeutics Market
Cell & Gene Therapy
Asia-Pacific Viral Vector Purification Market
Cell & Gene Therapy
Canine Stem Cell Therapy Market
Cell & Gene Therapy
Global Gene Therapy Market
Cell & Gene Therapy
Adeno Associated Virus Vector Manufacturing Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Leukemia Therapeutics Market