
 Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market | 2026-2036
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market Analytics
The pediatric hepatology vertical is restructuring treatment demand as specialized children's hospitals expand dedicated cholestasis programs. Mirum Pharmaceuticals leverages its ileal bile acid transporter inhibitor portfolio to anchor rare liver disease positioning. Albireo Pharma competes through sustained R&D intensity in bile acid modulation science. Novartis differentiates via global manufacturing scale and established rare disease distribution networks.
Progressive Familial Intrahepatic Cholestasis Type 2 represents an autosomal recessive disorder caused by ABCB11 gene mutations impairing bile salt export pump function, resulting in progressive cholestasis and end-stage liver disease requiring transplant intervention. Novel therapeutics command the fastest-growing segment as gene-targeted and RNA-based modalities advance through clinical pipelines, while ursodeoxycholic acid occupies the mature volume base despite limited efficacy in severe phenotypes. Hospital pharmacies dominate distribution channels due to infusion requirements and specialist oversight, though online platforms are gaining traction for chronic oral maintenance therapies.
FDA orphan drug incentives and EMA PRIME eligibility frameworks shape development economics by compressing regulatory timelines and extending market exclusivity for sponsors. The EU AI Act and GDPR impose emerging compliance burdens on digital biomarker collection and patient registry data flows across multinational trials. Stakeholders must monitor pipeline transitions from symptomatic management to disease-modifying mechanisms as clinical endpoints evolve.
Market Dynamics
Gene-targeted therapeutics are restructuring competitive positioning in Progressive Familial Intrahepatic Cholestasis Type 2 treatment, as sponsors pivot from symptomatic bile acid modulation toward disease-modifying mechanisms that alter transplant dependency trajectories.
Growth Catalysts
- EMA PRIME Eligibility:Accelerated assessment pathways compress development timelines for rare liver disease sponsors seeking early conditional approval in European markets.
- Pediatric Hepatology Centers:Dedicated children's hospital programs in the United States and Germany are expanding specialized cholestasis clinics that concentrate prescriber expertise and patient access.
- RNA-Based Modalities:Emerging antisense and siRNA platforms target ABCB11 gene expression directly, opening mechanistic categories beyond conventional bile acid management.
Market Restraints
- Ultra-Rare Prevalence Constraints:Patient identification challenges and fragmented diagnosis across primary care networks limit addressable population visibility for sponsors.
- Transplant Center Concentration:Liver transplant capacity clusters in tertiary academic medical centers, creating geographic access barriers that delay intervention timing.
- Limited Biomarker Validation:Surrogate endpoints for bile acid reduction lack standardized regulatory acceptance across FDA and EMA review divisions.
Strategic Opportunities
- Japan's Orphan Drug Framework:PMDA priority review vouchers and extended exclusivity provisions attract sponsors to a market with established rare disease infrastructure.
- Digital Biomarker Integration:Wearable liver function monitoring and remote patient registries enable decentralized trial designs that reduce site burden.
- Gene Therapy Convergence:AAV vector delivery combined with CRISPR editing platforms promises single-intervention cures that displace chronic pharmacologic management.
Industry Challenges
- Pediatric Trial Design Complexity:Ethical constraints on placebo-controlled studies in progressive liver disease populations complicate pivotal trial execution.
- Supply Chain Cold-Chain Integrity:Biologic and cell-based therapies require specialized logistics infrastructure that few hospital pharmacies currently maintain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market |
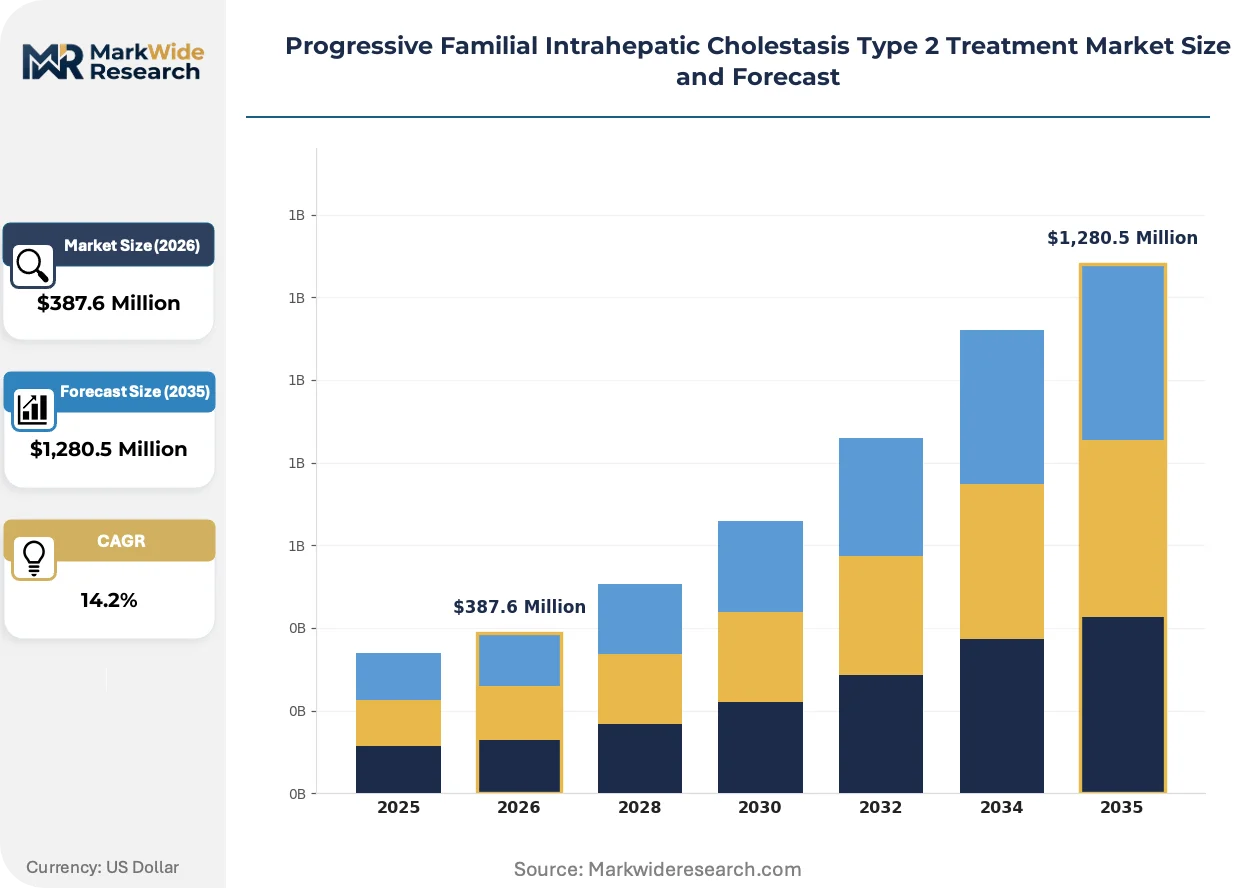
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ursodeoxycholic Acid, Liver Transplantation, Supportive Therapy, Novel Therapeutics Administration Route: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Clinics, Research Institutes, Homecare Distribution Channel: Pharmacies, Hospital Pharmacies, Online Platforms, Specialty Stores |
| Companies Covered | Mirum Pharmaceuticals, Albireo Pharma, Novartis, Sanofi, Teva Pharmaceutical Industries Ltd., AbbVie, Takeda Pharmaceutical Company, Pfizer, Ipsen Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market Evolving Landscape
RNA interference platforms are actively displacing small-molecule dominance in rare cholestasis pipelines, while regulatory frameworks on both sides of the Atlantic compress approval pathways. These shifts are compressing development timelines and redrawing competitive boundaries between established hepatology players and gene therapy specialists.
Antisense oligonucleotide therapies targeting ABCB11 mRNA degradation are expanding into first-line treatment positioning previously occupied by bile acid sequestrants. Pediatric hepatology centers in Germany and the United States are adopting these modalities for severe phenotypes unresponsive to ursodeoxycholic acid. This expansion is compressing the addressable window for conventional symptomatic management and accelerating transplant deferral timelines.
FDA's Rare Disease Endpoint Advancement Pilot and EMA's PRIME eligibility framework are streamlining evidentiary requirements for progressive familial intrahepatic cholestasis therapies. Sponsors now negotiate novel surrogate endpoints earlier in development, reducing Phase III duration and patient exposure. Gene-targeted modalities with disease-modifying claims face the steepest compliance burden under these accelerated pathways.
Hospital pharmacy procurement is consolidating around integrated specialty distributors that bundle infusion services with chronic oral therapy fulfillment. Online platforms are capturing maintenance prescription volume previously handled through inpatient discharge workflows, particularly in the United States where home nursing integration is most mature. This channel rotation is most visible in markets with established rare disease nursing networks.
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market Segmentation
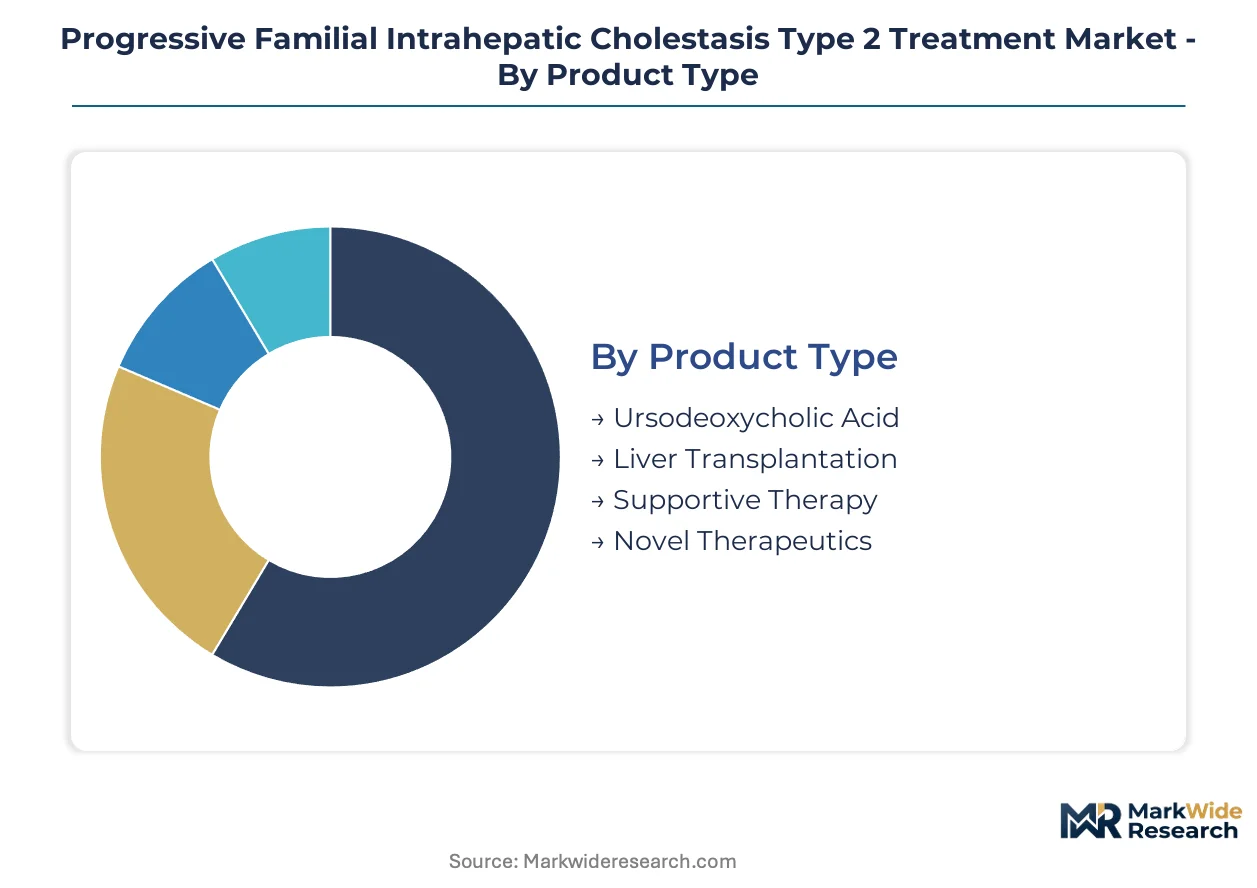
Progressive Familial Intrahepatic Cholestasis Type 2 treatment demand fragments across intervention maturity, with legacy symptomatic management anchoring volume while gene-targeted modalities capture premium positioning. Understanding these segment boundaries clarifies where development capital concentrates versus where clinical practice lags.
Product Type:
Novel therapeutics command premium pricing and development attention, while mature interventions sustain base volume through established reimbursement pathways.
- Novel Therapeutics:Gene-targeted and RNA-based modalities including antisense oligonucleotides and siRNA platforms directly modulate ABCB11 expression. Demand concentrates in pediatric hepatology centers across Germany and the United States where transplant deferral justifies premium acquisition costs.
- Ursodeoxycholic Acid:A hydrophilic bile acid that displaces toxic endogenous bile salts from hepatocyte membranes, forming the chronic maintenance backbone. Volume concentrates in markets with mature rare disease pharmacy networks where prescriber familiarity sustains first-line positioning despite limited efficacy in severe phenotypes.
- Liver Transplantation:Definitive intervention for end-stage disease requiring specialized surgical infrastructure and lifelong immunosuppression.
- Supportive Therapy:Nutritional supplementation and pruritus management addressing symptom burden without disease modification.
Mature deployment sits with Ursodeoxycholic Acid. Newer deployment is concentrated in Novel Therapeutics.
Administration Route:
Route selection tracks therapy mechanism and patient stability, with chronic oral regimens dominating maintenance phases and parenteral delivery reserved for acute intervention.
- Oral:Bile acid modulators and maintenance therapies formulated for gastrointestinal absorption, enabling home-based administration. Demand clusters in the United States where integrated home nursing networks support chronic rare disease management outside institutional settings.
- Intravenous:Acute decompensation management and peri-transplant support requiring controlled infusion environments. Concentration follows tertiary liver center geography in Germany and Japan where specialized hepatology nursing maintains infusion capability.
- Subcutaneous:Emerging delivery for RNA-based therapeutics and biologics requiring depot absorption.
- Topical:Localized pruritus relief addressing cutaneous bile acid deposition symptoms.
Institutional capacity anchors Intravenous delivery. Patient preference and nursing infrastructure are expanding Oral and Subcutaneous adoption fastest.
End User:
Care setting fragmentation reflects disease progression stage, with diagnosis and acute management concentrating in specialized centers while stable phases shift toward decentralized models.
- Hospitals:Comprehensive diagnostic workup, transplant evaluation, and acute complication management requiring multidisciplinary hepatology teams. Volume concentrates in academic medical centers across the United States, Germany, and Japan where ABCB11 genetic testing and liver biopsy capacity co-locate.
- Homecare:Chronic therapy administration and monitoring for stable patients on oral regimens, enabled by remote nursing support. Expansion tracks rare disease nursing network maturity, particularly in US markets with established specialty pharmacy integration.
- Clinics:Outpatient hepatology follow-up and routine monitoring.
- Research Institutes:Natural history studies and clinical trial execution for novel therapeutic development.
Acute intervention remains hospital-centered. Chronic management is migrating toward Homecare where nursing infrastructure permits.
Distribution Channel:
Channel selection follows therapy complexity and patient acuity, with integrated specialty distributors capturing biologic volume and digital platforms penetrating maintenance oral prescriptions.
- Hospital Pharmacies:Inpatient dispensing for acute therapies, transplant protocols, and investigational access programs. Procurement concentrates in centers with cold-chain biologic handling capability, particularly German university hospitals and US children's hospital networks.
- Online Platforms:Chronic oral maintenance fulfillment with home delivery and adherence monitoring. Growth tracks specialty pharmacy digital infrastructure maturity in the United States, where integrated rare disease platforms bundle nursing support with medication shipment.
- Pharmacies:Community dispensing for standard supportive therapies and nutritional supplements.
- Specialty Stores:Medical nutrition and ancillary support product distribution.
Complex therapy distribution runs through Hospital Pharmacies. Online Platforms are capturing maintenance prescription volume fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Orphan drug tax credits and rare disease research zones concentrate development activity in three distinct national markets. Specialized pediatric hepatology infrastructure and accelerated regulatory pathways determine where sponsors prioritize clinical investment and commercial launch sequencing.
United States
FDA orphan drug designation grants seven-year market exclusivity and tax credits for qualified clinical trial expenditures. The National Institutes of Health maintains the Rare Diseases Clinical Research Network with dedicated cholestasis natural history studies. Boston Children's Hospital and Cincinnati Children's Hospital Medical Center anchor the pediatric hepatology cluster where gene-targeted therapy trials concentrate.
Germany
EMA PRIME eligibility compresses assessment timelines for medicines addressing unmet medical need in rare liver diseases. The German Federal Ministry of Education and Research funds the National Action Plan for Rare Diseases through university hospital networks. Heidelberg and Hamburg university hospitals coordinate the European reference network for rare liver disorders.
Japan
PMDA priority review vouchers and extended orphan drug exclusivity provisions attract sponsors to a market with established rare disease infrastructure. The Ministry of Health, Labour and Welfare maintains the Orphan Drug Designation Program with tax incentives and waived review fees. Tokyo and Osaka academic medical centers concentrate pediatric hepatology expertise and transplant evaluation capacity.
United Kingdom
NICE highly specialized technology evaluations provide dedicated funding pathways for ultra-rare disease treatments. The NHS England specialized commissioning framework designates supra-regional pediatric hepatology centers. Birmingham and London hospital networks manage the national cholestasis patient registry and coordinate transplant referral pathways.
Switzerland
Swissmedic maintains accelerated authorization procedures for orphan medicines with conditional approval options. The Swiss Federal Office of Public Health integrates rare disease treatments into mandatory health insurance through specialized lists. Basel and Zurich university hospitals anchor the national hepatology research consortium with gene therapy trial participation.
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated biopharmaceutical companies controlling novel therapeutic development while generic manufacturers supply the ursodeoxycholic acid maintenance base. The vendor structure concentrates around three archetypes: gene-targeted modality specialists, established hepatology portfolio owners, and rare disease commercialization platforms. Consolidation activity targets RNA platform capabilities and pediatric rare disease market access infrastructure.
Among the gene-targeted modality specialists, Mirum Pharmaceuticals and Albireo Pharma exemplify the bile acid modulation science anchor position, while Novartis occupies the scale-driven integrated pharmaceutical archetype with established rare disease distribution networks. These three entities represent distinct competitive vectors—platform specialization, scientific focus, and global commercial infrastructure—that sponsors must navigate when positioning novel ABCB11-targeted interventions.
| Leading Market Players |
|---|
| Mirum Pharmaceuticals |
| Albireo Pharma |
| Novartis |
| Sanofi |
| Teva Pharmaceutical Industries Ltd. |
| AbbVie |
| Takeda Pharmaceutical Company |
| Pfizer |
| Ipsen Pharma |
| Others |
Value Network & Pricing Analysis
EMA PRIME eligibility and FDA orphan drug tax credit programs gate qualified supply access for gene-targeted PFIC2 therapies, concentrating premium-tier pricing power with sponsors demonstrating accelerated regulatory navigation and cold-chain biologic handling capability.
Pricing Analysis
Short lead-time premiums for gene therapy vector manufacturing command substantial markups over standard biologics, while spot inventory of ursodeoxycholic acid trades at commodity discounts. Three-tier pricing structure across gene-modified, RNA-based, and small-molecule modalities tracks clinical differentiation and transplant deferral claims. Price differentiation hinges on FDA breakthrough therapy designation status and pediatric exclusivity extension eligibility. Cost compression in the mature ursodeoxycholic acid segment is intensifying due to generic manufacturer entry, while gene-targeted therapies face limited price sensitivity among transplant-averse pediatric hepatology centers.
Supply Chain Analysis
Good Manufacturing Practice certification for viral vector production and ABCB11-targeted biologics gates supplier qualification, limiting active pharmaceutical ingredient sourcing to specialized contract manufacturers in the United States, Germany, and Switzerland. Plasmid DNA, cell culture media, and lipid nanoparticle formulations constitute critical input dependencies. Single-source vulnerability concentrates in AAV vector production suites, where capacity constraints create allocation risk for pivotal trial supply. Distribution runs through integrated specialty pharmacy networks that bundle cold-chain logistics with patient nursing support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Gene therapy platform consolidation is accelerating as RNA modality specialists absorb manufacturing scale limitations and transplant center access bottlenecks force subscale competitors toward exit.
For Market Incumbents: Acquire RNA interference platform capabilities to anchor disease-modifying positioning against emerging CRISPR editing competitors. Expand pediatric hepatology center contracting in Germany and the United States to lock transplant referral pathways before gene therapy convergence displaces chronic pharmacologic management. FDA Rare Disease Endpoint Advancement Pilot participation secures accelerated approval leverage. For New Entrants and Emerging Players: EMA PRIME eligibility in European markets opens a window for antisense oligonucleotide developers seeking conditional approval ahead of full Phase III completion. Target Japan's orphan drug framework for priority review voucher capture and extended exclusivity positioning. Partner with established rare disease commercialization platforms to bypass hospital pharmacy procurement consolidation barriers. For Investors and Strategic Acquirers: First FDA approval of an ABCB11-targeted gene therapy is the leading indicator that transplant deferral economics will restructure the entire therapeutic hierarchy. Five-to-ten year viability favors vertically integrated gene therapy specialists with captive viral vector manufacturing and pediatric rare disease market access infrastructure. Watch PMDA priority review voucher issuance velocity as Japan market entry timing signal.| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | Captive AAV vector production in Massachusetts and North Carolina reduces single-source dependency for clinical supply. |
| Pediatric Hepatology Center Partnership | Cincinnati Children's and Boston Children's anchor transplant referral control and natural history data access. |
| EMA PRIME Eligibility Pursuit | Accelerated assessment compresses development timelines for antisense oligonucleotide candidates in European markets. |
| Digital Biomarker Integration | Wearable liver function monitoring enables decentralized trial designs that reduce site burden and patient travel. |
| Japan Orphan Drug Designation | PMDA priority review vouchers and tax incentives attract sponsors to established rare disease infrastructure in Tokyo and Osaka. |
Research Methodology
Independent corroboration across pediatric hepatology specialists, regulatory affairs leads at rare disease sponsors, hospital pharmacy procurement managers, and payer access specialists underwrites the qualitative findings. Primary interviews with drug development executives and formulary directors combined with secondary validation from FDA orphan drug designations, EMA PRIME eligibility records, ClinicalTrials.gov entries, and hospital procurement databases established segment boundaries. Bottom-up patient population modeling and top-down revenue triangulation anchored market size estimates.
Rate-of-change decomposition across the analysis window disaggregated value expansion into price, volume, and mix effects by treatment line, administration route, end-user setting, and regional regulatory cluster. CAGRs derived from log-linear trend fitting to historic trajectory and pipeline transition assumptions. Forecast inputs incorporated gene therapy regulatory approval probability, transplant center capacity constraints, and bile acid biomarker validation status.
The model assumes a particular technology adoption path; alternative pathways for CRISPR-based ABCB11 correction would alter the outlook by accelerating transplant deferral timelines and compressing RNA modality commercial windows. Forecasts reflect assumptions regarding regulatory endpoint acceptance and pediatric trial enrollment rates. A model refresh is warranted upon material change in FDA gene therapy guidance or EMA accelerated assessment criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Autologous Cell Therapy Market
Cell & Gene Therapy
Cellular Reprogramming Tools Market
Cell & Gene Therapy
Mesenchymal Stem Cells Market
Cell & Gene Therapy
Sandhoff Disease Therapeutics Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
RNAI Technology Market
Cell & Gene Therapy
Oncolytic Virus Therapy Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Hemophilia Gene Therapy Market
Cell & Gene Therapy
Cryopreservation Cell Lines Market
Cell & Gene Therapy
EMEA Cancer Biological Therapy Market
Cell & Gene Therapy
Cell and Gene Supply Chain Services Market
Cell & Gene Therapy
Cell Therapy Raw Materials Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
North America Gene Therapy Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market