
 Sezary Syndrome Market | 2026-2036
Sezary Syndrome Market Size, Share, and Industry Trends Forecast 2026-2036
Sezary Syndrome Market Analysis
Next-generation sequencing in circulating tumor DNA monitoring is rewriting clinical trial design for cutaneous T-cell lymphomas. Bristol Myers Squibb Company leverages its cell therapy infrastructure to sustain leadership in advanced mycosis fungoides and Sezary syndrome protocols. Novartis AG anchors its position through targeted therapy pipelines, while Kyowa Kirin competes with antibody-based platforms in relapsed settings.
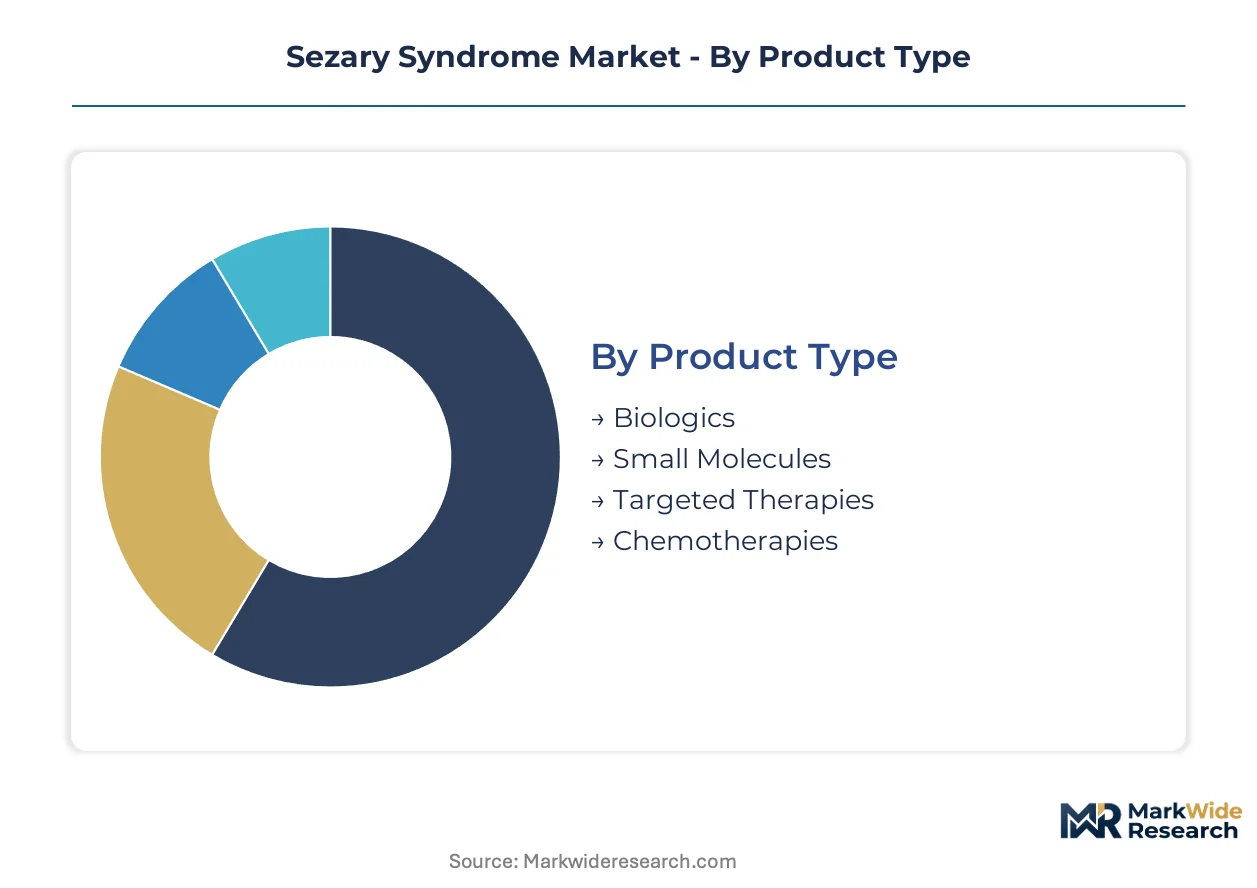
Sezary syndrome is an aggressive leukemic variant of cutaneous T-cell lymphoma characterized by erythroderma, generalized lymphadenopathy, and clonal expansion of malignant T-cells in skin, blood, and lymph nodes, with diagnostic thresholds requiring Sezary cell counts exceeding one thousand per microliter or CD4-positive T-cell clonality by flow cytometry. Biologics command the deepest margin pools among product types due to manufacturing complexity and orphan pricing structures, while targeted therapies represent the fastest-expanding segment as monoclonal antibodies and histone deacetylase inhibitors displace conventional chemotherapies in second-line and relapsed treatment stages.
The FDA's accelerated approval and breakthrough therapy designations shape development economics for rare hematologic malignancies, while the EMA's orphan drug framework governs European market access and pricing negotiations for Sezary syndrome therapeutics. REACH compliance and EMA Good Manufacturing Practice standards further constrain active pharmaceutical ingredient sourcing and contract manufacturing site qualification. Stakeholders must weigh regulatory pathway selection against payer evidence requirements as novel mechanisms advance from first-in-human studies toward confirmatory trials.
Market Dynamics
The Sezary Syndrome Market pivots on FDA accelerated approval pathways that compress development timelines for rare hematologic malignancies, compressing the gap between first-in-human data and confirmatory trial initiation while reshaping how sponsors allocate capital across pipeline stages.
Growth Catalysts
- Breakthrough Therapy Designation:The FDA's expedited review framework compresses regulatory timelines for novel T-cell lymphoma protocols, enabling faster patient access to investigational agents.
- ctDNA Monitoring:Next-generation sequencing in circulating tumor DNA is rewriting clinical trial endpoints, allowing real-time efficacy assessment and adaptive trial designs.
- Specialty Clinic Concentration:United States referral centers for cutaneous T-cell lymphoma aggregate sufficient patient volumes to support single-site enrollment for orphan indication trials.
Market Restraints
- Manufacturing Complexity:Biologics production requires single-use bioreactor systems and specialized cold-chain infrastructure that constrains batch scale-up.
- Orphan Pricing Scrutiny:Payer pushback on histone deacetylase inhibitor reimbursement creates access friction in European markets governed by EMA orphan frameworks.
- Diagnostic Threshold Rigidity:Sezary cell count requirements exceeding one thousand per microliter limit trial eligibility and delay treatment initiation in early leukemic progression.
Strategic Opportunities
- Companion Diagnostic Integration:CD4-positive T-cell clonality assays by flow cytometry enable patient stratification and precision therapy selection in relapsed settings.
- Antibody Platform Expansion:Monoclonal antibody constructs targeting malignant T-cell markers offer white space beyond histone deacetylase inhibitor mechanisms.
- EMA Parallel Scientific Advice:Coordinated FDA-EMA development programs streamline regulatory strategy for sponsors pursuing transatlantic market access.
Industry Challenges
- Cell Therapy Manufacturing Talent:Scarce expertise in chimeric antigen receptor T-cell production limits contract development and manufacturing organization capacity.
- Confirmatory Trial Design:Small patient populations complicate randomized controlled study execution, forcing reliance on single-arm trials with surrogate endpoints.
- REACH Compliance Burden:Active pharmaceutical ingredient sourcing under ECHA standards constrains supplier qualification timelines and increases documentation overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sezary Syndrome Market |
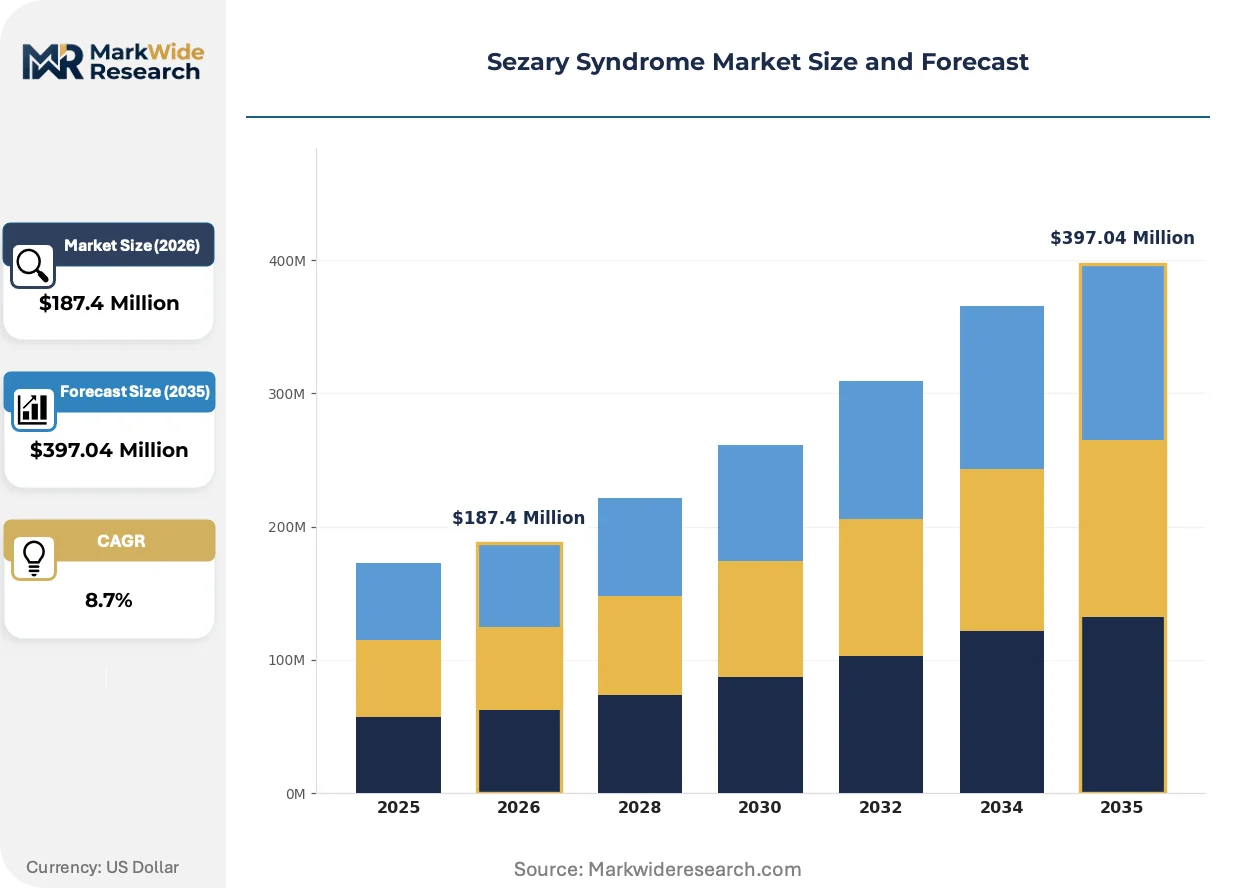
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Small Molecules, Targeted Therapies, Chemotherapies Treatment Stage: First-Line Therapy, Second-Line Therapy, Relapsed Therapy, Maintenance Therapy Administration Route: Oral, Intravenous, Subcutaneous, Topical End User: Hospitals, Specialty Clinics, Home Care, Research Institutions |
| Companies Covered | GSK plc, Bristol Myers Squibb Company, F-Hoffmann La Roche Ltd, Pfizer Inc., Novartis AG, Johnson and Johnson Services, Inc., Kyowa Kirin, Eisai Co., Ltd., Seagen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sezary Syndrome Market Emerging Trajectories
Cell therapy infrastructure investments are reshaping competitive positioning in advanced mycosis fungoides and Sezary syndrome, while regulatory convergence between FDA and EMA frameworks accelerates development economics for rare hematologic malignancies.
Chimeric antigen receptor T-cell platforms are collapsing the distinction between autologous and allogeneic manufacturing approaches, with academic medical centers in the United States adopting decentralized production models to reduce vein-to-vein timelines. Bristol Myers Squibb leverages existing cell therapy infrastructure to compress manufacturing scale-up for leukemic cutaneous T-cell lymphoma indications. This convergence is collapsing traditional barriers between transplant centers and community oncology practices.
EMA orphan drug framework revisions tighten evidentiary standards for market exclusivity while the FDA's accelerated approval pathway maintains flexibility on surrogate endpoints. Sponsors now face divergent payer evidence requirements across the Atlantic, with German AMNOG assessments demanding harder clinical outcomes than FDA-mandated progression-free survival data. Histone deacetylase inhibitors encounter steeper access negotiations in France and Italy than in United States commercial and Medicare channels.
Specialty pharmacy distribution is consolidating patient access pathways, with limited distribution networks replacing traditional wholesale models for high-cost biologics. Payers in the United States mandate white-bagging or buy-and-bill restrictions that displace physician office infusion for oral targeted therapies. This channel compression concentrates volume with three national specialty pharmacy operators and reduces site-of-care flexibility for erythroderma patients requiring coordinated dermatology and hematology management.
Sezary Syndrome Market Segmentation
Sezary syndrome treatment protocols fragment across manufacturing complexity, clinical setting requirements, and reimbursement pathways. Understanding segment turnover velocity helps sponsors allocate capital between established margin pools and emerging therapeutic modalities.
Product Type:
Cycle times vary sharply: small molecules move from synthesis to pharmacy shelves in months, while biologics require years of cell-line development and viral clearance validation.
- Biologics:Monoclonal antibodies and fusion proteins manufactured in mammalian cell cultures command premium reimbursement due to orphan pricing structures and batch-to-batch consistency requirements. Demand clusters at United States academic medical centers with established cold-chain infrastructure and prior authorization expertise for high-cost oncology agents.
- Targeted Therapies:Histone deacetylase inhibitors and monoclonal constructs directed at malignant T-cell surface markers displace conventional protocols in relapsed settings. United States specialty clinics drive adoption fastest where FDA accelerated approval pathways compress prescriber education cycles.
- Small Molecules:Oral formulations with simpler chemistry routes and generic substitution exposure.
- Chemotherapies:Established cytotoxic regimens facing displacement by mechanism-driven alternatives.
Biologics dominate installed base. Targeted therapies are where expansion concentrates.
Treatment Stage:
Patient flow dynamics shape segment economics: first-line protocols serve incident cases with standardized eligibility, while later stages capture refractory populations willing to tolerate experimental toxicity profiles.
- First-Line Therapy:Standard-of-care regimens for newly diagnosed erythroderma with confirmed Sezary cell thresholds. United States cutaneous T-cell lymphoma referral centers aggregate sufficient volume to support protocol optimization and real-world evidence generation.
- Relapsed Therapy:Investigational agents accessed through expanded access programs and single-site trials for progressive disease after histone deacetylase inhibitor failure. FDA breakthrough therapy designation accelerates prescriber familiarity with novel mechanisms in this setting.
- Second-Line Therapy:Bridge protocols between standard care and salvage options.
- Maintenance Therapy:Long-term disease control with tolerability-weighted regimens.
First-line therapy anchors prescription volume. Relapsed therapy is climbing the fastest.
Administration Route:
Site-of-care economics drive route selection: oral agents shift financial risk to pharmacy benefit managers, while infused products retain buy-and-bill margins for hospital outpatient departments.
- Intravenous:Infused biologics requiring supervised administration in hematology-oncology suites with hypersensitivity monitoring capabilities. United States hospital outpatient departments defend this segment through white-bagging restrictions and specialty pharmacy carve-outs.
- Oral:Histone deacetylase inhibitors and small-molecule targeted agents enabling community-based management of erythroderma. Payer step-therapy protocols increasingly mandate oral sequence before IV escalation.
- Subcutaneous:Self-administered biologics with lower cold-chain burden than IV equivalents.
- Topical:Localized skin-directed therapy for limited erythroderma prior to systemic progression.
Intravenous dominates current revenue. Oral is gaining share fastest.
End User:
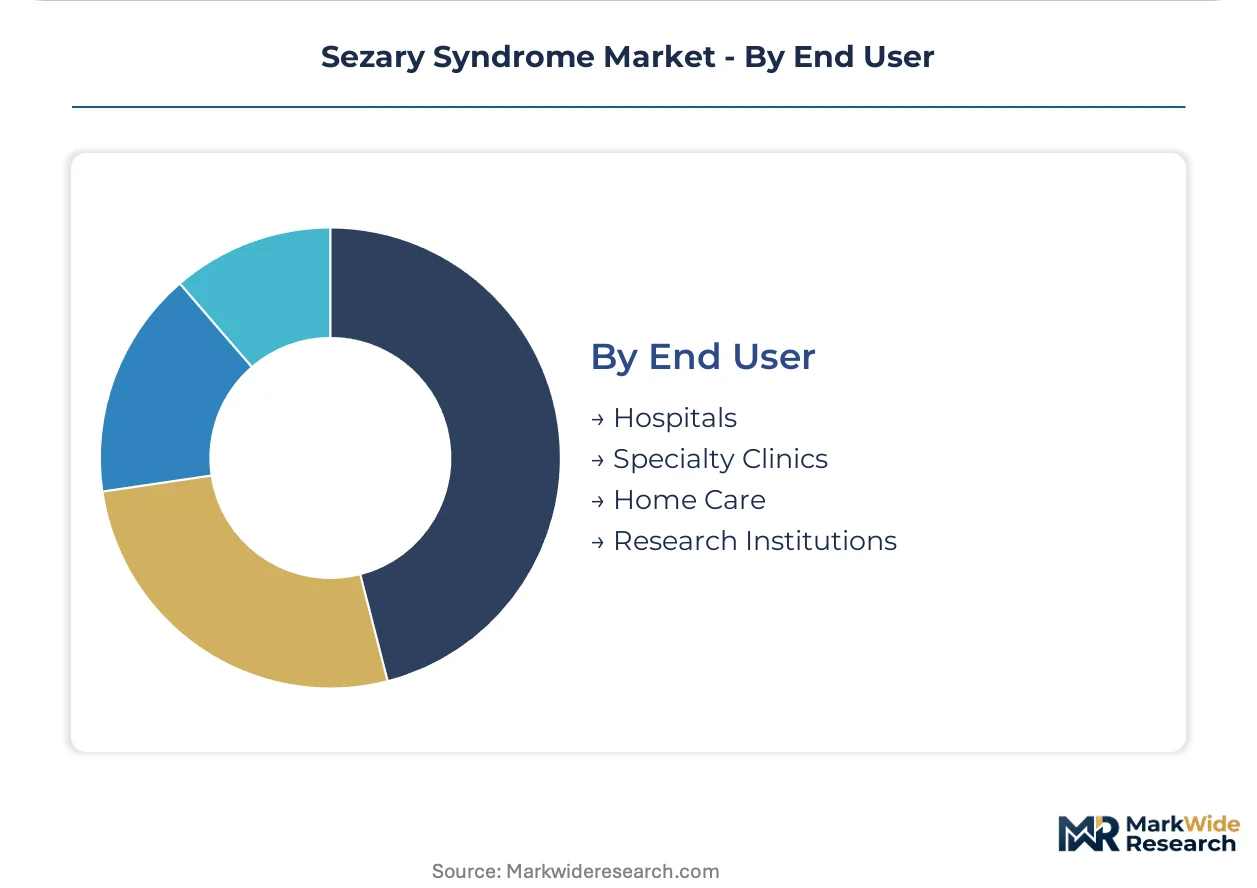
Care setting determines patient capture economics: hospitals bundle infusion services with diagnostic workup, while specialty clinics compete on dermatology-hematology coordination speed.
- Specialty Clinics:Dedicated cutaneous T-cell lymphoma programs combining dermatopathology expertise with flow cytometry capabilities for Sezary cell enumeration. United States metropolitan referral networks concentrate these sites in Boston, New York, and Houston clusters.
- Hospitals:Academic medical centers with cell therapy infrastructure and chimeric antigen receptor T-cell manufacturing partnerships. These sites capture complex cases exceeding specialty clinic protocol eligibility.
- Home Care:Subcutaneous and oral administration with nursing support for geographically dispersed erythroderma patients.
- Research Institutions:Early-phase trial sites with next-generation sequencing capacity for ctDNA monitoring.
Hospitals dominate installed base. Specialty clinics are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based cutaneous T-cell lymphoma referral centers export clinical expertise and trial protocols to European and Asian academic medical centers, establishing a unidirectional knowledge corridor that shapes diagnostic standards and treatment sequencing across recipient geographies.
United States
FDA breakthrough therapy designation and accelerated approval pathways compress development timelines for novel T-cell lymphoma protocols. The Orphan Drug Act provides tax credits and market exclusivity incentives that sustain biologics manufacturing investments. Boston, New York, and Houston clusters concentrate specialty clinics with integrated flow cytometry capabilities and chimeric antigen receptor T-cell manufacturing partnerships.
Germany
G-BA assessments under AMNOG frameworks demand harder clinical outcomes than progression-free survival surrogates, creating access friction for histone deacetylase inhibitors. REACH compliance constrains active pharmaceutical ingredient sourcing and contract manufacturing site qualification timelines. Heidelberg and Munich academic medical centers anchor European referral networks for erythroderma patients requiring Sezary cell enumeration by flow cytometry.
France
ANSM pricing negotiations and HAS transparency commission reviews create steeper access barriers for orphan oncology agents than United States commercial channels. EMA orphan drug framework revisions tighten evidentiary standards for market exclusivity renewal. Paris and Lyon metropolitan areas concentrate dermatopathology expertise with next-generation sequencing capacity for circulating tumor DNA monitoring in clinical trials.
United Kingdom
NICE technology appraisals and Cancer Drugs Fund access schemes govern reimbursement for relapsed cutaneous T-cell lymphoma therapies. MHRA post-Brexit regulatory divergence from EMA frameworks creates parallel submission requirements for sponsors. London and Manchester referral networks aggregate sufficient patient volumes for single-site enrollment in expanded access programs for progressive disease after standard-care failure.
Japan
PMDA sakigake designation system accelerates review timelines for innovative hematologic malignancy therapies with domestic development components. National health insurance price listing negotiations occur annually, compressing launch-to-reimbursement intervals for orphan indications. Tokyo and Osaka academic medical centers adopt decentralized chimeric antigen receptor T-cell production models to reduce vein-to-vein timelines for leukemic progression patients.
Sezary Syndrome Market Vendor Landscape
Channel-controlling players compete with product-specialist players across a market structure concentrated among large-cap pharmaceutical companies with cell therapy infrastructure and targeted therapy pipelines. The vendor base clusters around three strategic archetypes: integrated biopharmaceutical conglomerates with rare disease divisions, cell therapy platform specialists leveraging autologous manufacturing capabilities, and antibody-focused biotechnology firms targeting relapsed T-cell lymphoma settings. Dominant competitive moves include strategic partnerships between academic medical centers and contract development and manufacturing organizations, plus portfolio diversification into companion diagnostic integration.
Within the integrated biopharmaceutical tier, Bristol Myers Squibb Company and Novartis AG exemplify archetypes combining cell therapy infrastructure with global regulatory submission capabilities. Kyowa Kirin occupies a position among antibody-platform specialists targeting malignant T-cell surface markers in relapsed settings. These three entities represent contrasting approaches to manufacturing scale-up and payer evidence generation for orphan hematologic malignancies.
| Leading Market Players |
|---|
| GSK plc |
| Bristol Myers Squibb Company |
| F-Hoffmann La Roche Ltd |
| Pfizer Inc. |
| Novartis AG |
| Johnson and Johnson Services, Inc. |
| Kyowa Kirin |
| Eisai Co., Ltd. |
| Seagen Inc. |
| Others |
Supply Flow & Price Mechanics
Single-source dependency on Chinese active pharmaceutical ingredient manufacturers determines both the spread between originator biologics and biosimilar candidates and the geographic configuration of cold-chain distribution networks. REACH compliance burdens and FDA import alert exposure compress margin pools for sponsors lacking backward integration into mammalian cell culture production.
Pricing Analysis
Next-generation chimeric antigen receptor T-cell therapies command substantial premiums over established histone deacetylase inhibitors, while prior-generation chemotherapies face accelerating price erosion. Three-tier pricing structure across premium biologics, standard targeted therapies, and economy cytotoxic regimens reflects manufacturing complexity and orphan exclusivity status. Cost compression in the chemotherapy tier is intensifying because of mechanism-driven displacement by monoclonal antibodies. Community oncology practices demonstrate highest price sensitivity due to buy-and-bill margin compression, while academic medical centers with cell therapy infrastructure exhibit lowest sensitivity due to bundled reimbursement for complex cases.
Supply Chain Analysis
Extended payment terms from United States specialty pharmacy operators strain contract manufacturing organization cash cycles, forcing reliance on supply-chain finance facilities backed by pharmaceutical distributor credit lines. Bioreactor equipment concentrates in United States, Germany, and Switzerland, while viral vector production draws from United Kingdom and Singapore facilities. Supply chain risk centers on single-source vulnerability for proprietary cell lines and viral clearance validation protocols. Distribution runs through limited specialty pharmacy networks with white-bagging restrictions displacing traditional wholesale models for infused biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Histone deacetylase inhibitors face substitution pressure from emerging antibody-drug conjugates and allogeneic cell therapy platforms, requiring incumbents to defend established revenue streams through manufacturing moats and regulatory exclusivity.
For Market Incumbents: Entrench position through captive viral vector production capacity and proprietary cell line development, insulating against supply disruption and enabling accelerated scale-up for breakthrough therapy-designated candidates. Prioritize EMA parallel scientific advice submissions to compress transatlantic regulatory timelines and preempt biosimilar entry in European markets. For New Entrants and Emerging Players: Relapsed Sezary syndrome populations after histone deacetylase inhibitor failure represent the most penetrable entry point, with single-site academic medical center trials enabling real-world evidence generation before confirmatory study investment. Companion diagnostic integration for CD4-positive T-cell clonality assays offers differentiation against mechanism-agnostic competitors. For Investors and Strategic Acquirers: Antibody-platform specialists with validated malignant T-cell surface marker targeting and existing Bristol Myers Squibb or Novartis partnership history present the most attractive acquisition archetype for portfolio diversification. Watch FDA accelerated approval conversion rates to full approval as the critical signal for cell therapy platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | ctDNA monitoring endpoints accelerate FDA breakthrough therapy designation timelines for novel T-cell lymphoma protocols. |
| Manufacturing Scale-Up | Single-use bioreactor investments in Boston and Houston clusters compress vein-to-vein timelines for CAR-T production. |
| Regulatory Approval Pathway | EMA orphan drug framework revisions tighten evidentiary standards, favoring sponsors with parallel FDA submission capabilities. |
| Companion Diagnostic Integration | Flow cytometry assay partnerships enable patient stratification and precision therapy selection in relapsed settings. |
| Licensing Agreement | Academic medical center technology transfers provide access to decentralized CAR-T production models and proprietary cell lines. |
Methodological Framework
The analysis maps biologics manufacturing, targeted therapy development, and diagnostic platform sub-sectors, each validated through regulatory affairs specialists, formulary directors at United States payers, and cell therapy manufacturing executives. Primary interviews with hospital procurement managers and payer access specialists combined with secondary validation against FDA filings, ClinicalTrials.gov records, EMA submission documents, and specialty pharmacy distribution data. Bottom-up patient flow modeling and top-down orphan oncology market sizing triangulate volume and value estimates.
Fixed assumptions include sustained FDA accelerated approval pathway availability, stable orphan drug exclusivity periods, and continued concentration of cutaneous T-cell lymphoma referral centers in United States metropolitan clusters across the analysis window. Segmentation dimensions encompass product type, treatment stage, administration route, and end-user setting. CAGRs derive from patient incidence projections, therapy penetration curves, and pricing trajectory modeling for mechanism-driven displacement patterns.
Macroeconomic conditions sit as an overlay; deviation in biologics reimbursement policy, specialty pharmacy consolidation pace, or cell therapy manufacturing talent availability would shift the trajectory. Regulatory pathway modifications, payer evidence requirement changes, or technological disruption in allogeneic cell platforms would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Anti-Neprilysin Market
Biopharmaceuticals
Antibody Drug Conjugates Market
Biopharmaceuticals
Insulin API Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Global Interferons Market
Biopharmaceuticals
Global Breast Cancer Drugs Market
Biopharmaceuticals
Asia-Pacific Plant-Based Biologics Market
Biopharmaceuticals
Nfkb P65 Antibody Market
Biopharmaceuticals
Asia-Pacific Insulin Pens Market
Biopharmaceuticals
Oseltamivir Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Ewing Sarcoma Drugs Market
Biopharmaceuticals
South Korea Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Acitretin Market
Biopharmaceuticals
Plasma Protease C1-Inhibitor Market
Biopharmaceuticals
Antibody Production Market