
 Climbing Harness Market | 2026-2036
Climbing Harness Market Size, Share, and Industry Trends Forecast 2026-2036
Climbing Harness Market Analytics
Aftermarket service revenue from harness inspection, recertification, and guided replacement programs is narrowing the margin gap against pure equipment sales. Petzl leverages its vertically controlled distribution network across alpine retail channels to sustain premium positioning. Black Diamond anchors its competitive stance through concentrated R&D spending on load-bearing ergonomics. Mammut differentiates via specialized manufacturing partnerships with European textile mills for high-tenacity webbing.
A climbing harness is a load-distribution system constructed from woven synthetic webbing, typically nylon or polyester, with a rated breaking strength exceeding 15 kN, designed to secure a climber to a rope or anchor point during fall arrest, suspension, or positioning operations. Sit harnesses dominate commercial volume due to their versatility across rock climbing and industrial rope-access applications, while full-body configurations command higher unit margins in professional tree care and confined-space rescue sectors. Nylon retains the largest material share for its abrasion resistance and dynamic elongation properties, though Kevlar-reinforced variants are gaining traction in high-heat and cut-risk environments.
CE marking under the EU's Personal Protective Equipment Regulation and UIAA safety standards govern product certification for harnesses sold in Europe, while the US market falls under OSHA fall-protection directives and ANSI Z359 standards for work-at-height equipment. These frameworks mandate periodic third-party testing, which elevates compliance costs for new entrants and reinforces incumbent quality reputations. Stakeholders must monitor evolving material disclosure requirements and regional enforcement intensities to calibrate certification investments against market access timelines.
Market Dynamics
Lightweight Kevlar-nylon composite webbing is compressing traditional nylon supply chains while forcing recalibration of load-testing protocols across certification bodies. Manufacturers must now balance material innovation against UIAA and OSHA validation timelines.
Growth Catalysts
- Climbing gym infrastructure expansion:Indoor facility construction across the United States and Germany is generating institutional bulk purchasing contracts for sit harness configurations.
- OSHA fall-protection directive enforcement:Stricter workplace-at-height compliance in industrial rope-access sectors is mandating harness replacement cycles and inspection documentation.
- Recreational participation surge:Post-pandemic outdoor enrollment programs in Colorado and Chamonix are accelerating first-time buyer penetration among urban demographics.
Market Restraints
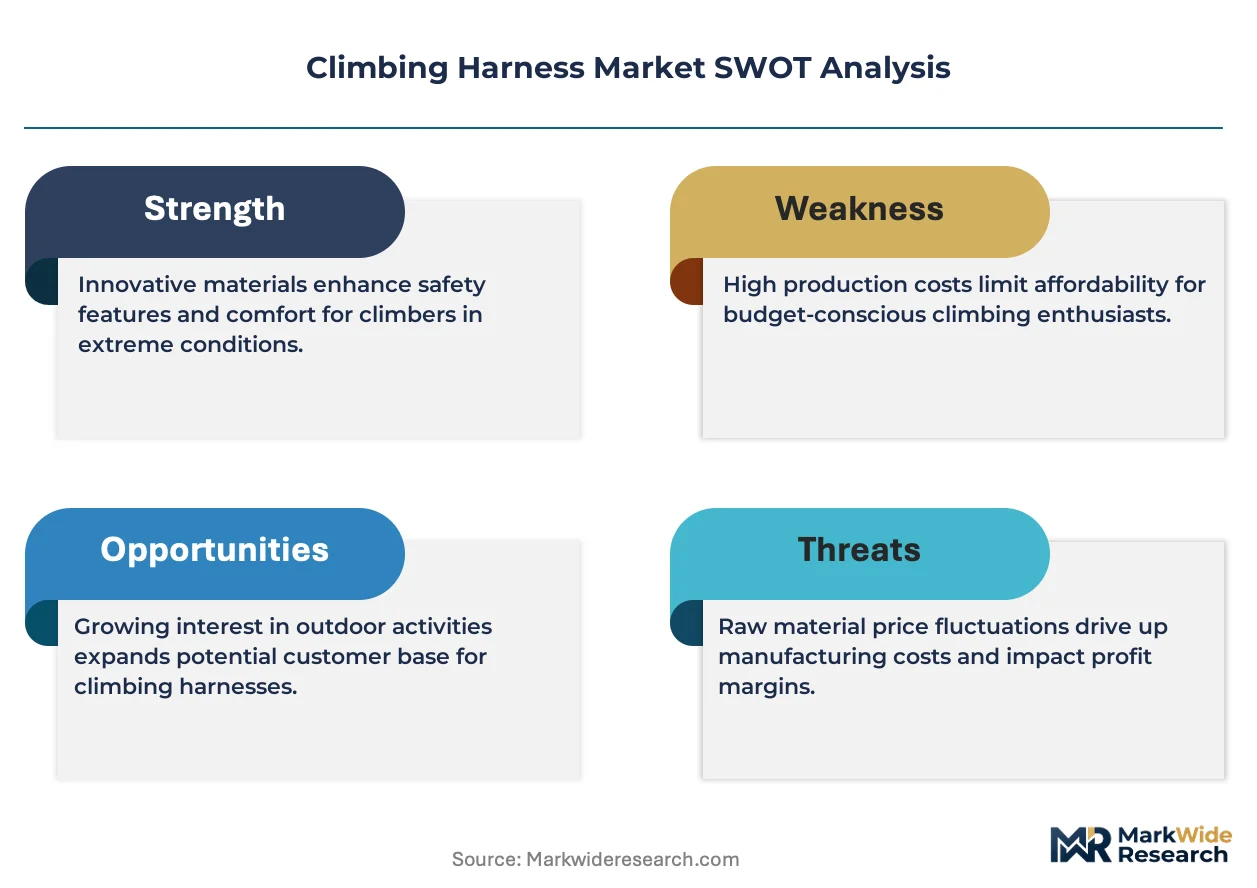
- Petrochemical input volatility:Nylon 6,6 resin prices fluctuate with crude oil benchmarks, squeezing margin stability for webbing manufacturers.
- Asian textile concentration:High-tenacity yarn production clusters in Zhejiang Province create single-source vulnerability for European harness assemblers.
- CE marking compliance costs:EU Personal Protective Equipment Regulation third-party testing fees exceed $15,000 per SKU, elevating barriers for niche entrants.
Strategic Opportunities
- Indian outdoor retail underpenetration:Himalayan guiding operators in Uttarakhand and Himachal Pradesh lack certified distribution partnerships for technical rescue configurations.
- Rental program digitization:Subscription-based harness pooling for university climbing programs is displacing individual ownership in California and British Columbia.
- EU Green Deal material disclosure:Recycled-content mandates for synthetic textiles are creating first-mover advantage for closed-loop nylon suppliers.
Industry Challenges
- Certified inspector talent scarcity:UIAA-accredited harness evaluators are concentrated in Alpine Europe, creating service backlogs for North American gym operators.
- Load-bearing ergonomics R&D capex:Biomechanical testing labs require six-figure investments for fall-simulation equipment validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Climbing Harness Market |
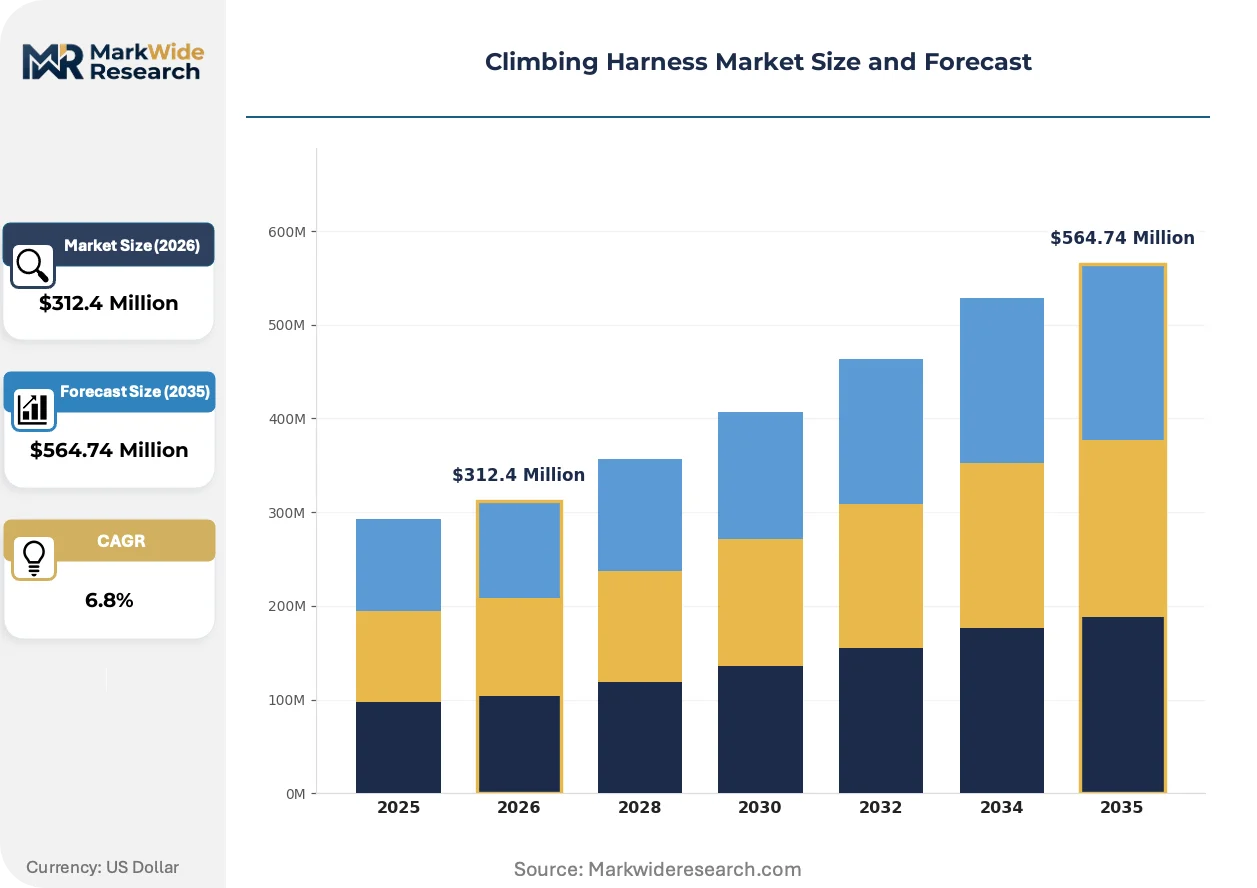
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Full-Body, Chest, Sit, Sport Material: Nylon, Polyester, Kevlar, Cotton Application: Rock Climbing, Mountaineering, Tree Care, Abseiling End User: Athletes, Outdoor Enthusiasts, Professionals, Recreational Users |
| Companies Covered | Petzl, Black Diamond, Arc'teryx, Mammut, Camp USA, Edelrid, Grivel, Singing Rock, Trango, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Climbing Harness Market Evolving Landscape
Embedded sensor technology and predictive wear algorithms are transforming how climbers and safety managers assess equipment lifecycle. These developments compress replacement decision timelines while generating new data-service revenue streams.
Load-cell integration into harness tie-in points is digitizing real-time force measurement during falls and weighted hangs. Alpine rescue teams in Switzerland and Yosemite Search and Rescue are piloting Bluetooth-enabled units that transmit peak-impact data to mobile dashboards. This capability is digitizing traditional paper-based inspection logs and enabling condition-based replacement triggers rather than calendar-driven discard protocols.
REACH substance restriction updates are phasing out certain flame-retardant treatments used in high-heat industrial harness variants. German textile mills serving Mammut and Edelrid supply chains must reformulate coating chemistries by registration deadlines. Professional tree-care operators in Bavaria and Austria face temporary SKU gaps as manufacturers revalidate webbing performance under revised chemical safety dossiers.
Rental and guided-program procurement is displacing individual direct-to-consumer purchases among institutional buyers. University outdoor recreation departments in the Pacific Northwest and Rocky Mountain states now source harness fleets through multi-year service agreements bundling equipment, inspection, and replacement logistics. This model concentrates buyer power with fewer decision-makers while elevating vendor stickiness through integrated safety compliance management.
Climbing Harness Market Segmentation
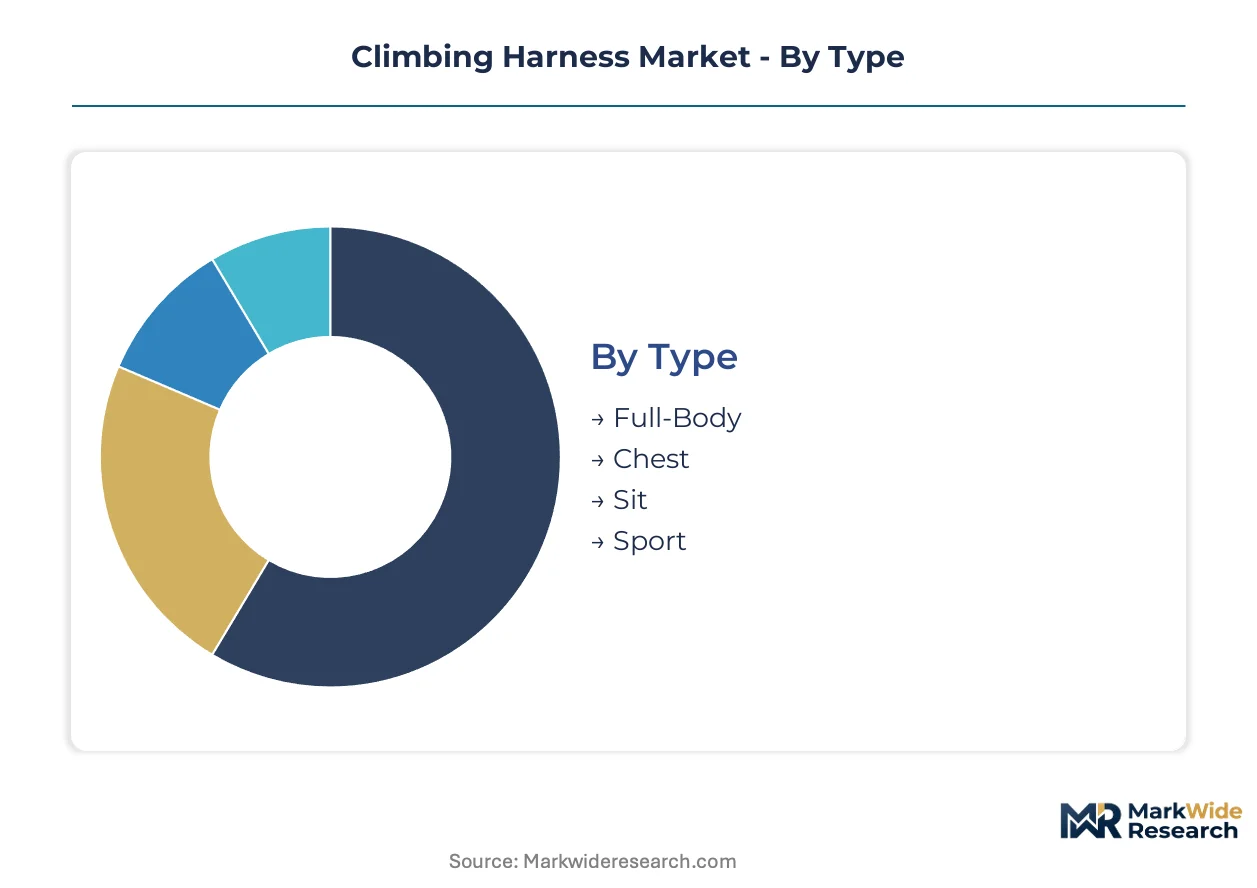
Segmentation in the climbing harness market determines service attach rates, replacement cadences, and certification complexity. Each category carries distinct margin profiles and aftermarket revenue potential that reshape vendor go-to-market economics.
Type:
After-sales-service intensity varies sharply across harness configurations, with institutional bulk contracts demanding inspection protocols that dwarf individual consumer replacement cycles.
- Sit:Woven nylon or polyester webbing forming a waist-and-leg-loop configuration rated for 15 kN minimum breaking strength. Demand concentrates in United States climbing gym chains and German alpine clubs where institutional procurement mandates biannual recertification programs.
- Full-Body:Shoulder-integrated load distribution systems combining chest and sit elements for vertical orientation stability. Professional tree-care operators in Austria and confined-space rescue teams in Switzerland drive specification requirements for extended dorsal D-ring positioning.
- Chest:Upper-torso stabilization units typically paired with sit harnesses for fall-arrest compliance. Yosemite Search and Rescue and industrial rope-access contractors in Colorado specify these for work-positioning redundancy.
- Sport:Minimalist waist-belt configurations optimized for weight reduction and rapid donning. Recreational climbers in Chamonix and Bishop, California favor these for single-pitch cragging where packability outweighs all-day comfort.
By volume, Sit leads. By growth pace, Sport is ahead.
Material:
Cost tier stratification follows raw material performance premiums, with high-tenacity synthetics commanding price multiples that compress at volume scale.
- Nylon:Polyamide 6,6 fiber dominating commercial production for dynamic elongation and abrasion resistance. United States and European gym operators standardize on this for rental fleet durability against high-cycle use.
- Kevlar:Aramid-reinforced webbing delivering cut resistance and thermal stability exceeding 400°C. Industrial fire-rescue units in Germany and high-heat foundry applications in Pennsylvania specify these despite 40% price premiums.
- Polyester:Lower-moisture-absorption alternative to nylon with reduced stretch characteristics. Coastal climbing operations in British Columbia and Pacific Northwest guiding services prefer these for wet-environment dimensional stability.
- Cotton:Natural-fiber legacy construction retained for historical reenactment and specialty theatrical rigging. Niche demand in California film production and Bavarian museum education programs sustains minimal volume.
By volume, Nylon leads. By margin expansion, Kevlar is climbing the fastest.
Application:
Customer type concentration dictates procurement channel mix, with professional segments consolidating through safety-service integrators while recreational buyers fragment across retail.
- Rock Climbing:Technical vertical ascension on natural or artificial formations requiring dynamic fall-arrest capability. United States climbing gym construction in Texas and Colorado generates institutional sit-harness demand with bundled inspection contracts.
- Mountaineering:Multi-day alpine expeditions necessitating glacier-travel and crevasse-rescue compatibility. Himalayan guiding operators in Uttarakhand and European alpine clubs drive full-body configuration specifications for load-bearing versatility.
- Tree Care:Arborist work-positioning and chainsaw-at-height operations mandating EN 358 and ANSI Z133 compliance. Professional contractors in Austria and Bavaria face SKU transitions as REACH flame-retardant reformulations progress.
- Abseiling:Controlled descent operations spanning recreational canyoning and industrial rope-access training. University outdoor programs in California and British Columbia source these through subscription-based rental pooling models.
By volume, Rock Climbing leads. By contract value concentration, Tree Care is expanding most quickly.
End User:
Volume-maturity dynamics separate established athlete segments from emerging recreational penetration where first-time buyer education costs elevate customer acquisition spend.
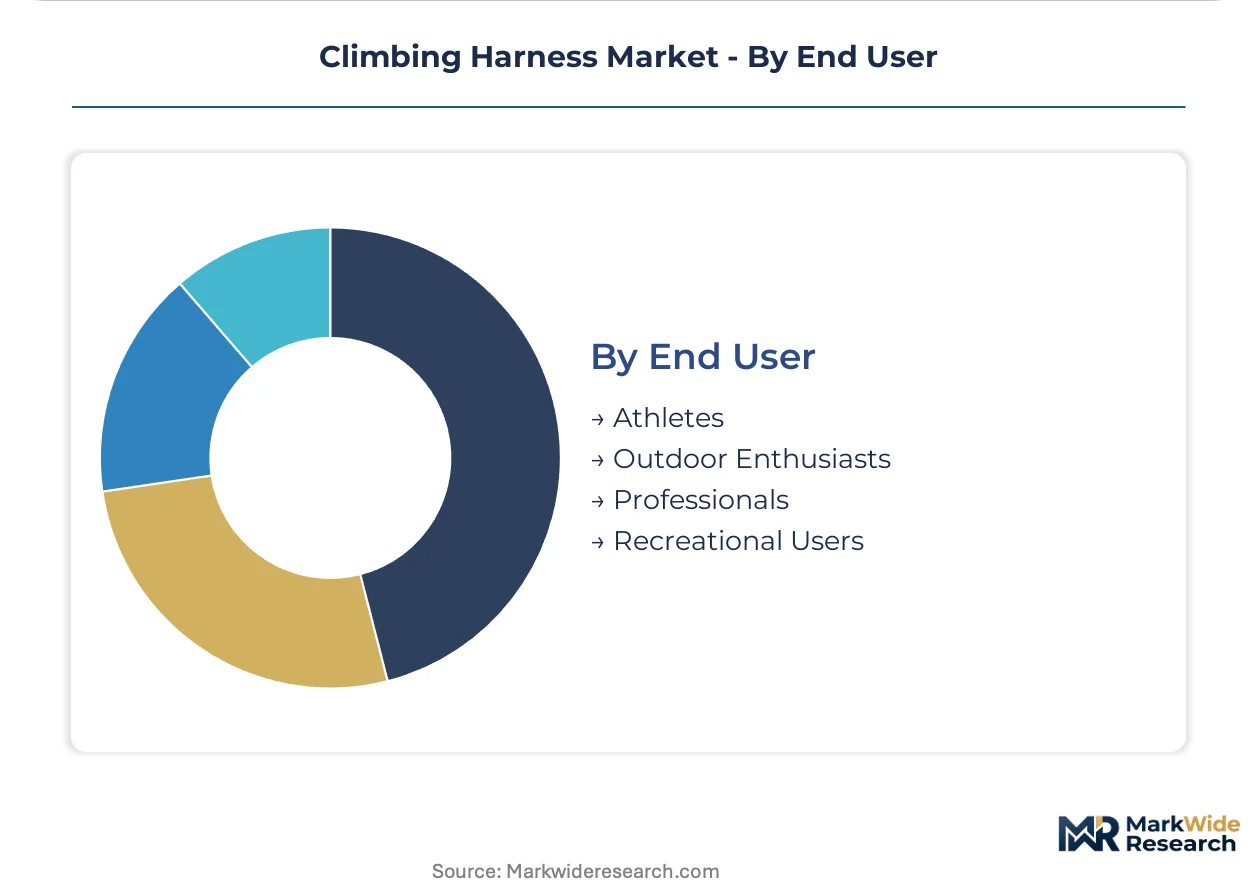
- Outdoor Enthusiasts:Self-directed recreational climbers purchasing through specialty retail or direct-to-consumer channels. Post-pandemic enrollment surges in Colorado and Chamonix accelerate harness adoption among urban demographics without prior technical exposure.
- Professionals:Industrial rope-access technicians, arborists, and rescue personnel subject to employer-mandated equipment standards. OSHA enforcement in United States construction sectors and EU PPE Regulation compliance in Germany tighten replacement cycle documentation requirements.
- Athletes:Competitive sport climbers and sponsored alpinists representing low-volume, high-visibility specification influence. International Federation of Sport Climbing competition standards in Seoul and Salt Lake City drive minimalist weight-reduction priorities.
- Recreational Users:Casual gym climbers and guided-experience participants with limited technical independence. Rental program digitization at University of Washington and University of British Columbia displaces individual ownership among this cohort.
By volume, Outdoor Enthusiasts leads. By service-revenue attachment, Professionals is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in climbing harness procurement varies sharply by geography. Institutional buyers in Germany accept premium pricing for bundled inspection services, while recreational purchasers in India prioritize entry-level configurations. Established regulatory enforcement in North America and Europe sustains compliance-driven replacement cycles that emerging markets have yet to replicate.
United States
Climbing gym chains in Texas and Colorado drive institutional bulk purchasing for sit harness configurations with biannual recertification contracts. OSHA fall-protection directive enforcement mandates documented harness replacement cycles across industrial rope-access sectors. Denver and Salt Lake City anchor the country's competitive sport climbing specification influence through International Federation of Sport Climbing events.
Germany
Alpine club procurement and professional tree-care contractor demand concentrate full-body configuration specifications. REACH substance restriction updates are phasing out legacy flame-retardant treatments, forcing Bavarian textile mills to reformulate coating chemistries. Munich and Stuttgart host the country's densest clusters of UIAA-accredited harness evaluators and biomechanical testing facilities.
France
Post-pandemic outdoor enrollment programs in Chamonix accelerate first-time buyer penetration among urban demographics without prior technical exposure. CE marking under the EU Personal Protective Equipment Regulation governs product certification with third-party testing fees exceeding $15,000 per SKU. The Auvergne-Rhône-Alpes region sustains specialized manufacturing partnerships for high-tenacity webbing.
India
Himalayan guiding operators in Uttarakhand and Himachal Pradesh lack certified distribution partnerships for technical rescue configurations, creating underpenetration in professional segments. The country's national standards body maintains limited enforcement of personal protective equipment certification for outdoor recreation. Himalayan mountaineering clusters around Manali and Rishikesh rely on informal import channels for full-body harness specifications.
Switzerland
Alpine rescue teams pilot Bluetooth-enabled load-cell integration for real-time force measurement during falls and weighted hangs. Swissmedic and EU PPE Regulation alignment sustain premium positioning for domestic manufacturers serving professional segments. Interlaken and Zermatt concentrate guided-program procurement that displaces individual direct-to-consumer purchases.
Climbing Harness Market Competitive Landscape
Vertically integrated specialists and brand-centric equipment houses split the market into distinct competitive spheres. The vendor base clusters around alpine heritage positioning versus scale-driven manufacturing efficiency. Three archetypes dominate: European alpine-heritage houses with controlled distribution networks, North American outdoor-lifestyle brands with concentrated R&D spending, and Asian contract assemblers serving private-label programs. Competitive moves concentrate on strategic partnerships with textile mills and backward integration into webbing production.
Within the alpine-heritage tier, Petzl, Mammut, and Black Diamond exemplify contrasting strategic postures. Petzl anchors premium positioning through its vertically controlled distribution network across alpine retail channels. Mammut occupies a position defined by specialized manufacturing partnerships with European textile mills for high-tenacity webbing. Black Diamond sits within the North American outdoor-lifestyle cluster, representing concentrated R&D spending on load-bearing ergonomics without the captive textile supply of its European counterparts.
| Leading Market Players |
|---|
| Petzl |
| Black Diamond |
| Arc'teryx |
| Mammut |
| Camp USA |
| Edelrid |
| Grivel |
| Singing Rock |
| Trango |
| Others |
Value Network & Pricing Analysis
Zhejiang Province's high-tenacity yarn production clusters concentrate upstream bargaining power with Asian textile mills, compressing margin pools for European harness assemblers who must absorb petrochemical volatility or surrender pricing control to institutional buyers.
Pricing Analysis
Aftermarket service revenue from inspection and recertification programs drives lifetime value beyond initial equipment transactions. Three-tier pricing structure across premium, standard, and economy levels separates CE-marked professional configurations from gym rental fleet standards and entry-level recreational units. Cost compression in nylon 6,6 resin tiers is intensifying because crude oil benchmark volatility feeds directly into webbing manufacturing economics. University outdoor programs and Himalayan guiding operators exhibit highest price sensitivity, while alpine rescue teams and industrial rope-access contractors accept premium positioning for bundled compliance documentation.
Supply Chain Analysis
Extended payment terms from European brand houses to Zhejiang yarn suppliers are tightening working capital cycles across the supplier base. Geographic supply concentration centers on China for high-tenacity nylon fiber, Germany for specialized coating chemistries, and Vietnam for cut-and-sew assembly operations. Raw material dependencies rest on petrochemical-derived polyamide resins, aramid fiber for Kevlar-reinforced variants, and REACH-compliant flame-retardant treatments. Single-source vulnerability in Zhejiang yarn production creates structural risk for just-in-time European assembly. Distribution runs through vertically controlled alpine retail networks for premium tiers and direct institutional contracting for gym and university fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through university outdoor program consolidation and climbing gym chain expansion, fragmenting decision-making authority away from individual consumers toward procurement committees with bundled service expectations.
For Market Incumbents: Entrench premium positioning through captive textile partnerships with European mills that insulate against Zhejiang supply disruption. Deepen backward integration into high-tenacity webbing production to capture margin pools currently flowing to Asian yarn suppliers. Defend against rental-program digitization by embedding sensor-enabled lifecycle tracking that locks institutional buyers into proprietary inspection ecosystems.
For New Entrants and Emerging Players: Pursue white-space expansion in Indian Himalayan guiding corridors where certified distribution partnerships remain underdeveloped. Target Uttarakhand and Himachal Pradesh technical rescue configurations where informal import channels dominate. Leverage EU Green Deal recycled-content mandates as regulatory entry wedge against incumbents with legacy nylon supply chains.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across embedded sensor and predictive wear algorithm development, favoring scaled R&D platforms over niche assembly operations. Long-term viability over the coming decade hinges on data-service revenue attachment rates rather than pure equipment margin sustainability. Acquisition target archetype: European alpine-heritage houses with dormant textile partnerships ripe for operational reactivation. Signal to watch: UIAA certification body endorsement timelines for Bluetooth-enabled load-cell integrations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Webbing Production | Captures margin pools from Zhejiang yarn suppliers while insulating against petrochemical volatility. |
| Sensor-Enabled Lifecycle Tracking Launch | Locks university and gym buyers into proprietary inspection ecosystems displacing paper-based logs. |
| REACH-Compliant Coating Reformulation | Maintains German and Austrian market access as flame-retardant substance restrictions phase in. |
| Himalayan Distribution Partnership Expansion | Secures first-mover positioning in Uttarakhand and Himachal Pradesh technical rescue segments. |
| Recycled-Content Nylon Certification | Captures EU Green Deal first-mover advantage ahead of mandated synthetic textile disclosure requirements. |
Research Methodology
A spread of perspectives from harness manufacturing executives, UIAA certification body representatives, university outdoor program procurement directors, and alpine rescue team equipment officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against UIAA safety standard documentation, OSHA fall-protection directive filings, and EU Personal Protective Equipment Regulation compliance databases. Trade flow analysis from customs records and SEC 10-K disclosures from publicly traded outdoor equipment houses anchored supply-side quantification. Bottom-up segment sizing triangulated against top-down macroeconomic demand indicators.
Demand-supply balance modeling across the analysis window incorporated harness type, material composition, application vertical, and end-user category segmentation dimensions. CAGRs were derived from slope-intercept trajectory fitting against historical participation rates and institutional procurement cycle documentation. Climbing gym construction permits, university outdoor program enrollment figures, and industrial rope-access workforce certification data served as industry-specific forecast inputs.
Sensitivities concentrate around petrochemical input volatility, REACH substance restriction enforcement timelines, and UIAA sensor-technology certification adoption rates. Forecasts reflect documented assumptions regarding recreational participation trajectories and institutional procurement consolidation patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Outdoor and Adventure Activities
Adventure Gear Market
Outdoor and Adventure Activities
North America Personal Watercraft Market
Outdoor and Adventure Activities
Skiing Equipment Market
Outdoor and Adventure Activities
Spain Sports Tourism Market
Outdoor and Adventure Activities
Motorized Pool Tube Market
Outdoor and Adventure Activities
Hiking Gear and Equipment Market
Outdoor and Adventure Activities
Hammocks Market
Outdoor and Adventure Activities
Outdoor Backpack Market
Outdoor and Adventure Activities
Parasailing Equipment Market
Outdoor and Adventure Activities
Wakeboard Market
Outdoor and Adventure Activities
Global Water Bikes Market
Outdoor and Adventure Activities
Global Climbing Shoes Market
Outdoor and Adventure Activities
US Spectator Sports Market
Outdoor and Adventure Activities
Global Climbing Holds Market
Outdoor and Adventure Activities
Trekking Poles Market
Outdoor and Adventure Activities
Adventure Sports and Activities Market