
 Waist Support Belt Market | 2026-2036
Waist Support Belt Market Size, Share, and Industry Trends Forecast 2026-2036
Waist Support Belt Market Analytics
CE marking under the EU Medical Device Regulation is consolidating compliance costs for waist support belt exporters targeting European healthcare channels. 3M leverages its materials science portfolio to engineer breathable compression fabrics that outperform commodity alternatives. BraceAbility anchors its position through specialized sizing algorithms that reduce return rates in direct-to-consumer channels. Mueller competes on brand recognition built through decades of sports medicine distribution.
A waist support belt is a wearable orthopedic device constructed from woven elastic, neoprene foam, or rigid polymer stays, designed to limit lumbar range of motion and redistribute mechanical load across the abdominal cavity. Manufacturing involves die-cutting laminated composites, sewing hook-and-loop closures, and heat-bonding structural stays into fabric pockets. Elastic belts dominate hospital procurement for post-operative stabilization due to standardized reimbursement codes, while neoprene variants capture sports and fitness applications where thermal retention and proprioceptive feedback command premium positioning. Compression belts serve occupational safety buyers who prioritize uniform pressure distribution during repetitive lifting tasks.
The FDA's 510(k) database governs clinical claims for medical-grade lumbar supports, while OSHA's voluntary ergonomics guidelines influence employer purchasing criteria for workplace injury prevention. ISO 13485 certification shapes supplier qualification thresholds for private-label contracts with pharmacy chains and medical distributors. Stakeholders must monitor evolving CMS durable medical equipment coverage determinations and state-level workers' compensation fee schedules that directly impact reimbursement-driven demand.
Market Dynamics
Employer-mandated ergonomics programs across manufacturing and logistics sectors are consolidating procurement authority into occupational health departments, compressing vendor selection cycles and elevating clinical validation requirements over commodity pricing.
Growth Catalysts
- OSHA Voluntary Ergonomics Guidelines:Employer compliance initiatives in warehousing and construction are mandating lumbar support equipment for repetitive lifting tasks, driving standardized bulk procurement.
- Aging Workforce Demographics:Sustained replacement cycles in industrial sectors with elevated median worker age are expanding the addressable base for preventive orthopedic wearables.
- Neoprene Thermal Retention Technology:Sports medicine and fitness applications are commanding premium positioning through enhanced proprioceptive feedback mechanisms.
Market Restraints
- Petrochemical Input Volatility:Neoprene foam and synthetic elastic fabrics face cost pressure from crude oil derivative pricing swings, compressing margin stability for mid-tier manufacturers.
- FDA 510(k) Clearance Timelines:Clinical validation requirements for medical-grade claims extend product development cycles by 12-18 months versus unregulated fitness variants.
- Generic Compression Garment Substitution:Unbranded elastic wraps and retail athletic belts compete on price for non-reimbursed consumer segments.
Strategic Opportunities
- Direct-to-Consumer Sizing Algorithms:Specialized fit-technology platforms are reducing return rates in e-commerce channels, unlocking geographic expansion beyond traditional medical distribution.
- EU Medical Device Regulation CE Marking:Consolidated compliance pathways for European healthcare channels are creating first-mover advantages for certified exporters.
- Post-Operative Stabilization Protocols:Standardized reimbursement codes for elastic belts in hospital procurement are embedding products into surgical recovery pathways.
Industry Challenges
- ISO 13485 Certification Talent Scarcity:Quality management system expertise for medical device manufacturing is concentrated among legacy orthopedic suppliers, constraining new market entry.
- Legacy Hook-and-Loop Integration:Heat-bonding and die-cutting equipment for laminated composite production requires capital outlays that disadvantage smaller contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waist Support Belt Market |
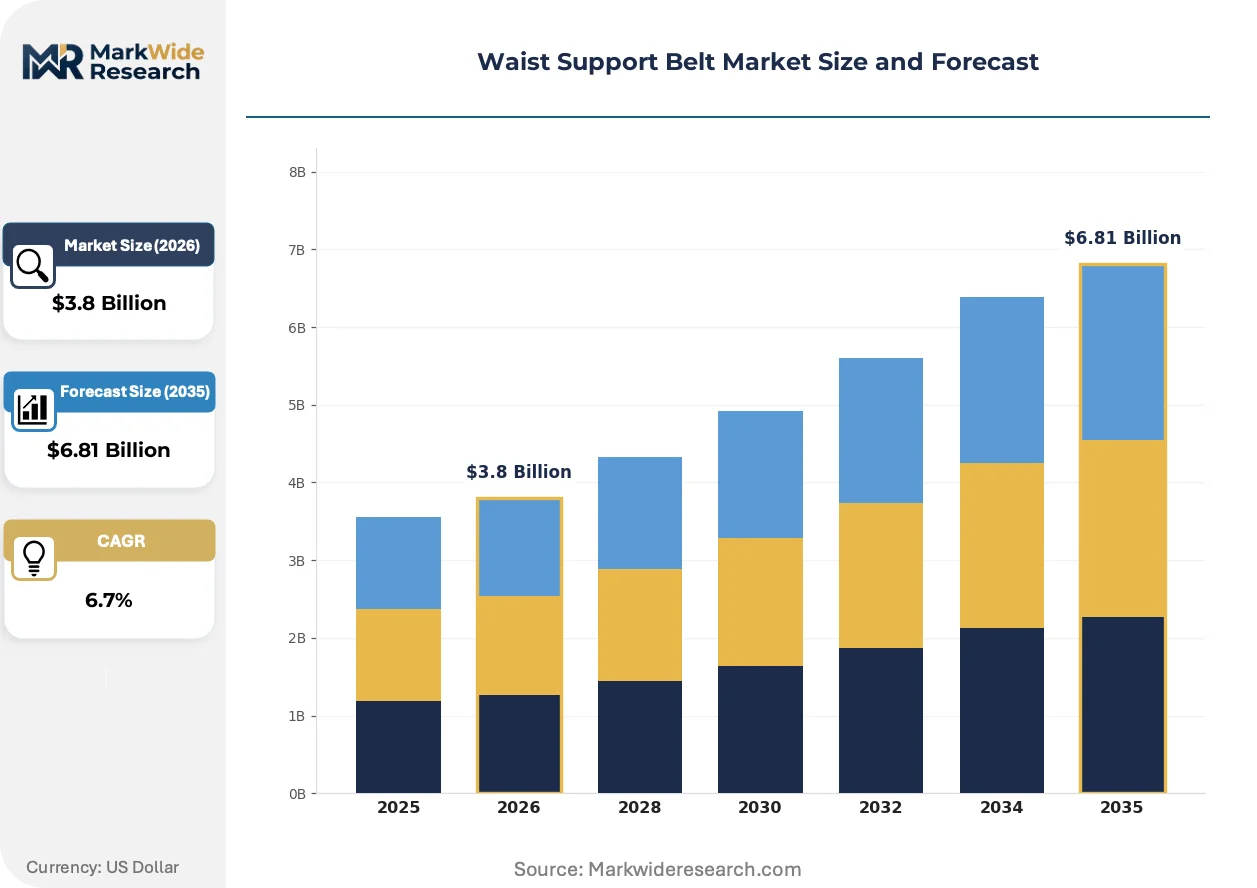
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Elastic Belts, Neoprene Belts, Adjustable Belts, Compression Belts Application: Medical Uses, Sports & Fitness, Occupational Safety, Posture Correction Target User: Athletes, Office Workers, Rehabilitation Patients, Elderly Individuals Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Wholesale Distributors |
| Companies Covered | RiptGear, Vive Health, 3M, Aspen, BraceAbility, Mueller, Toros Group, MAXAR, NyOrtho, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waist Support Belt Market Evolving Landscape
Breathable compression fabrics and smart textile integration are displacing commodity neoprene constructions, while regulatory harmonization across FDA and EU MDR pathways is reshaping competitive qualification thresholds.
Sensor-embedded waist support belts are converging with remote patient monitoring platforms, enabling real-time posture analytics and compliance tracking. Physical therapy chains and workers' compensation insurers are piloting these systems for outcome verification. The technology is converging with telehealth reimbursement models to compress traditional durable medical equipment distribution layers.
REACH compliance and EU MDR technical documentation requirements are elevating chemical safety testing for neoprene and adhesive components. Manufacturers serving European healthcare channels must demonstrate biocompatibility and substance restriction adherence beyond legacy self-certification. Sports medicine suppliers targeting Germany and France are restructuring supply chains to secure notified body partnerships.
Hospital procurement committees are consolidating vendor lists around suppliers with dual FDA 510(k) clearance and ISO 13485 certification, displacing uncertified alternatives from formulary consideration. Group purchasing organizations in the United States are embedding clinical evidence requirements into contract terms. This concentration is most visible in integrated delivery networks across Texas and California, where standardization mandates are narrowing supplier pools.
Waist Support Belt Market Segmentation
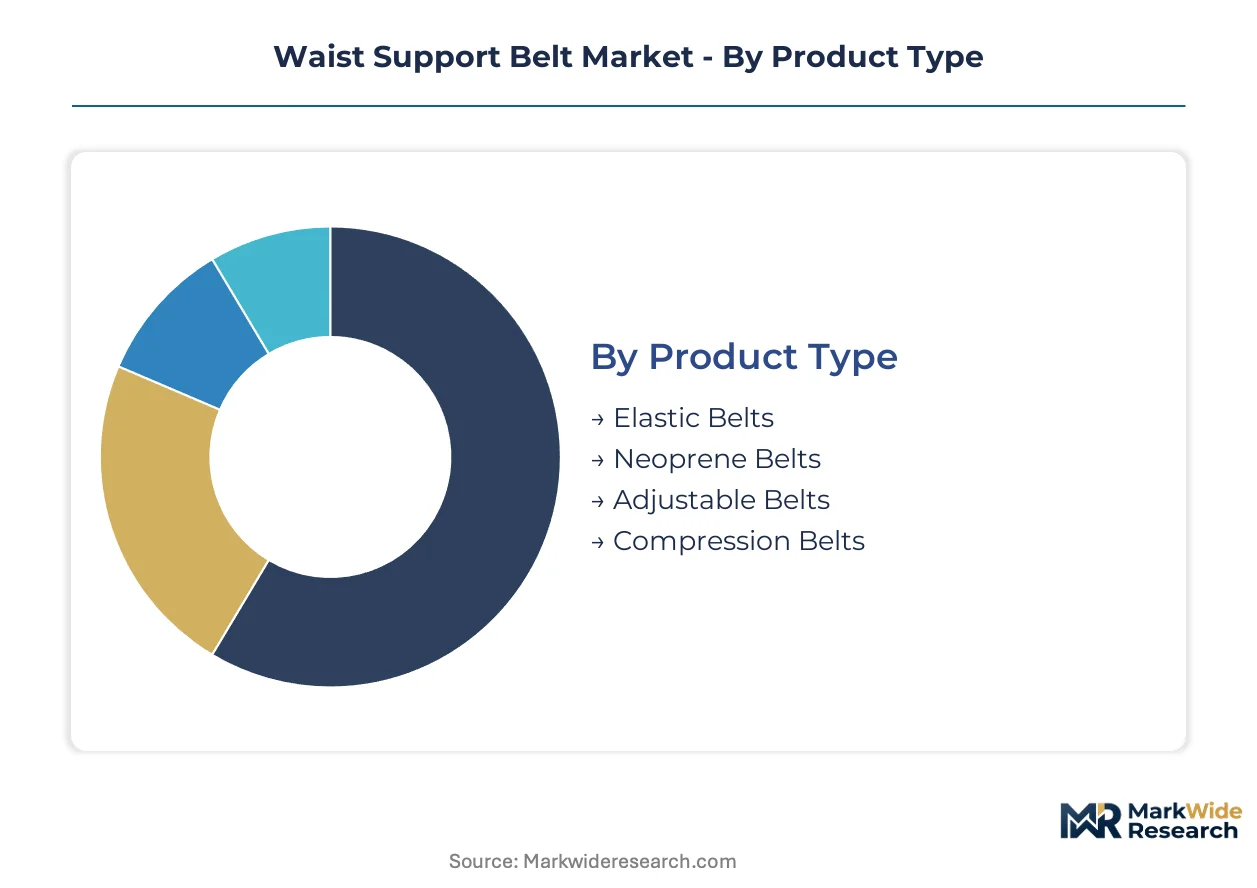
Waist support belt procurement diverges sharply across buyer contexts, with medical reimbursement codes, employer safety mandates, and direct-to-consumer fitness preferences creating distinct demand pools. Manufacturers must align product specifications, certification levels, and channel strategies to each segment's validation requirements and price sensitivity.
Product Type:
Material composition dictates clinical eligibility, thermal performance, and pricing tier, with buyers selecting based on intended use environment and regulatory pathway requirements.
- Elastic Belts:Constructed from woven synthetic elastic with integrated polymer stays, these devices deliver uniform circumferential pressure for post-operative stabilization. Hospital procurement committees in the United States prioritize elastic constructions due to established CMS durable medical equipment reimbursement codes that embed them into surgical recovery protocols.
- Neoprene Belts:Laminated foam-core constructions with nylon facing provide thermal retention and enhanced proprioceptive feedback during dynamic movement. Sports medicine applications and fitness consumers drive demand for neoprene variants, though petrochemical input volatility compresses margin stability for manufacturers dependent on crude oil derivatives.
- Adjustable Belts:Modular hook-and-loop systems with removable stays allow circumference modification across patient populations.
- Compression Belts:Uniform pressure distribution designs target occupational safety buyers managing repetitive lifting tasks in warehousing and logistics environments.
Elastic belts lead on scale through hospital formulary penetration; neoprene belts lead on momentum through fitness channel expansion.
Application:
End-use context determines regulatory burden, distribution channel, and clinical evidence requirements, with medical and occupational segments demanding certified products while fitness and posture segments accept consumer-grade alternatives.
- Medical Uses:FDA 510(k) cleared devices for post-surgical lumbar stabilization and chronic back pain management require ISO 13485 certified manufacturing and biocompatibility testing. Integrated delivery networks in Texas and California are consolidating vendor lists around dual-certified suppliers, displacing uncertified alternatives from hospital procurement consideration.
- Sports & Fitness:Performance-oriented designs emphasize thermal retention, moisture management, and aesthetic branding for athletic consumers. Direct-to-consumer sizing algorithms are reducing return rates in e-commerce channels, unlocking geographic expansion beyond traditional medical distribution for fitness-focused suppliers.
- Occupational Safety:Employer-mandated ergonomics programs in manufacturing and logistics sectors mandate lumbar support for repetitive lifting tasks, with OSHA voluntary guidelines influencing standardized bulk procurement.
- Posture Correction:Consumer-grade devices target sedentary office workers and remote employees seeking preventive support during prolonged sitting.
Medical uses anchor revenue through reimbursement-driven replacement cycles; sports and fitness applications are climbing the fastest through premium positioning and digital channel growth.
Target User:
User physiology and activity profile shape sizing requirements, compliance expectations, and durability specifications, with rehabilitation and elderly segments demanding specialized fit systems.
- Athletes:High-performance constructions prioritize breathability, range-of-motion preservation, and rapid donning-doffing for training and competition environments.
- Office Workers:Discreet, low-profile designs accommodate business attire while providing postural cueing during extended seated work.
- Rehabilitation Patients:Post-surgical and injury-recovery users require graduated compression protocols and physician-supervised fitting to prevent complications.
- Elderly Individuals:Arthritic hands and limited flexibility necessitate front-closure designs, extended pull tabs, and lightweight materials for independent application.
Rehabilitation patients generate highest per-unit pricing through medical certification; elderly individuals represent expanding volume through demographic aging and Medicare coverage expansion.
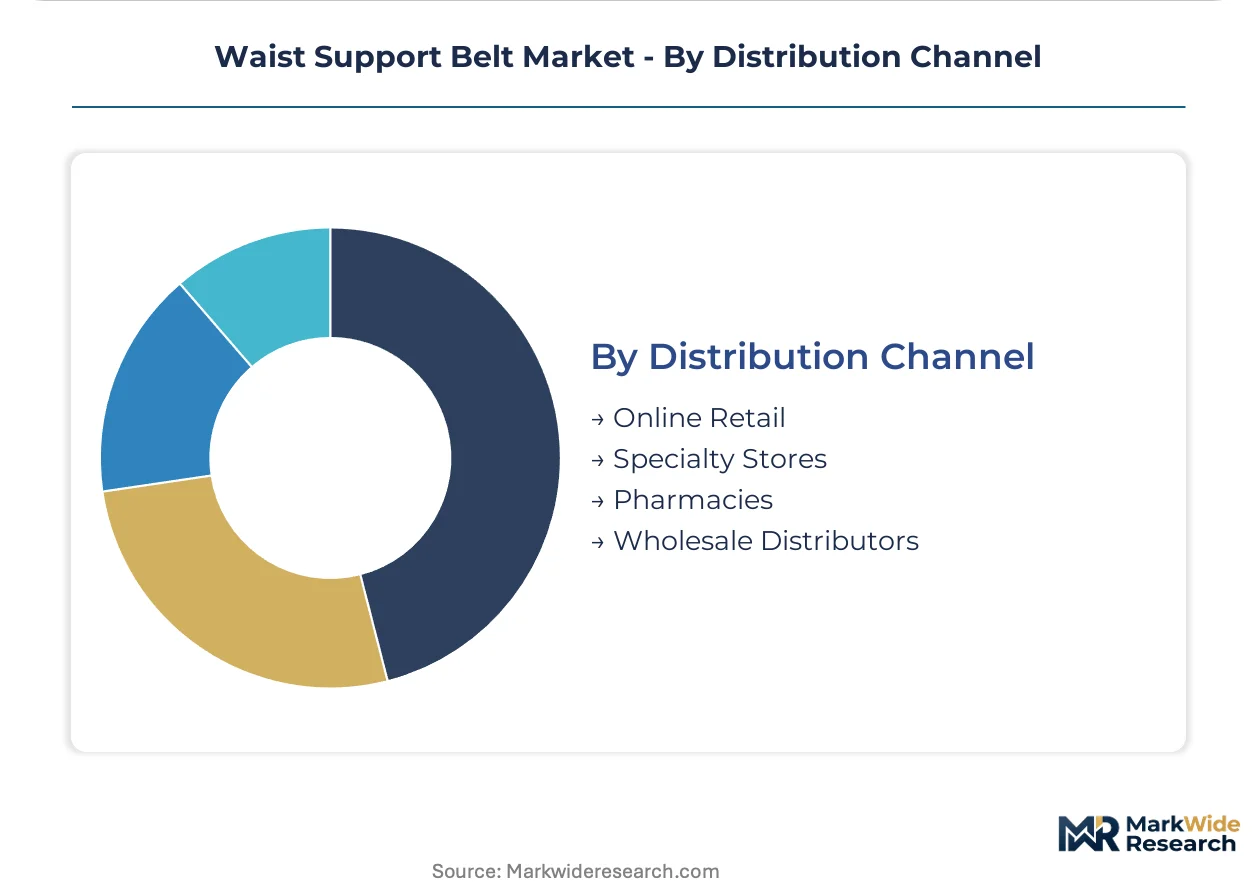
Distribution Channel:
Channel selection determines margin structure, customer acquisition cost, and regulatory exposure, with medical and wholesale channels requiring certification while online retail enables geographic reach.
- Online Retail:E-commerce platforms enable direct-to-consumer distribution with specialized fit-technology reducing return rates, though generic compression garment substitution pressures pricing for unbranded alternatives.
- Specialty Stores:Sports medicine and orthopedic retailers provide professional fitting services and clinical credibility for premium positioning.
- Pharmacies:Chain and independent drugstores capture convenience-driven purchases with private-label contracts requiring ISO 13485 supplier qualification.
- Wholesale Distributors:Medical and industrial supply aggregators serve hospital procurement committees and employer safety programs with volume pricing and consolidated logistics.
Wholesale distributors concentrate medical and occupational volume; online retail is gaining share fastest through algorithmic personalization and telehealth convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Workforce aging and employer-mandated ergonomics programs concentrate procurement authority in occupational health departments across industrialized economies. Manufacturing and logistics sectors in the United States, Germany, China, Japan, and Brazil sustain replacement cycles for lumbar support equipment.
United States
Employer-mandated ergonomics programs in warehousing and logistics sectors drive standardized bulk procurement of lumbar support equipment. OSHA voluntary guidelines influence purchasing criteria for workplace injury prevention across manufacturing facilities. Texas and California integrated delivery networks are consolidating vendor lists around dual FDA 510(k) cleared and ISO 13485 certified suppliers.
Germany
Industrial manufacturing and automotive assembly sectors with elevated median worker age expand preventive orthopedic wearable procurement. EU Medical Device Regulation CE marking requirements consolidate compliance costs for medical-grade waist support belt distribution. Bavaria and Baden-Württemberg automotive clusters are embedding lumbar support equipment into occupational safety protocols for repetitive lifting tasks.
China
Expanding logistics and e-commerce fulfillment sectors generate demand for occupational safety equipment including compression belts. NMPA medical device registration shapes clinical validation requirements for products targeting hospital procurement channels. Yangtze River Delta manufacturing hubs are standardizing lumbar support provision in employer-mandated ergonomics programs.
Japan
Aging workforce demographics in manufacturing and construction sectors sustain replacement cycles for preventive orthopedic wearables. METI industrial safety standards influence employer purchasing criteria for workplace injury prevention equipment. Kanto region logistics and distribution centers are consolidating procurement authority into occupational health departments for bulk lumbar support acquisition.
Brazil
Expanding manufacturing and agribusiness sectors with elevated workplace injury rates drive demand for occupational lumbar support equipment. ANVISA medical device registration requirements shape product development timelines for clinical-grade variants. São Paulo state industrial corridors are mandating ergonomic equipment provision in employer safety programs for repetitive material handling tasks.
Waist Support Belt Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across material science, orthopedic fabrication, and sports medicine distribution channels. The vendor base stratifies into three tiers: multinational materials conglomerates leveraging composite research portfolios, specialized orthopedic device manufacturers with ISO 13485 certified production, and direct-to-consumer fitness brands competing on algorithmic sizing and digital channel reach. Dominant competitive moves include backward integration into breathable compression fabric engineering and strategic partnerships with telehealth platforms for remote patient monitoring convergence.
Within the materials science tier, 3M anchors positioning through engineered fabric portfolios that outperform commodity alternatives. Among specialized orthopedic fabricators, BraceAbility and Mueller occupy distinct positions—BraceAbility exemplifies direct-to-consumer fit-technology platforms while Mueller represents decades-long sports medicine distribution heritage. These three companies illustrate the competitive spectrum from upstream material innovation through specialized clinical validation to consumer brand recognition.
| Leading Market Players |
|---|
| RiptGear |
| Vive Health |
| 3M |
| Aspen |
| BraceAbility |
| Mueller |
| Toros Group |
| MAXAR |
| NyOrtho |
| Others |
Value Network & Pricing Analysis
Employer-mandated ergonomics programs in the United States and Germany are consolidating procurement authority into occupational health departments, forcing manufacturers to absorb ISO 13485 certification costs and biocompatibility testing expenses that compress margins for uncertified competitors.
Pricing Analysis
Bundled professional fitting services command 40-60% premiums over unbundled direct-to-consumer sales in medical and occupational channels. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k) cleared devices with clinical validation from fitness-grade alternatives and generic elastic wraps. Pricing pressure stems from petrochemical input volatility affecting neoprene foam costs. Occupational safety buyers exhibit highest price sensitivity due to standardized bulk procurement mandates, while post-surgical rehabilitation patients demonstrate lowest sensitivity through reimbursement-driven replacement cycles.
Supply Chain Analysis
Workforce availability constraints in China, Vietnam, and Bangladesh are elevating labor costs for cut-and-sew operations and heat-bonding equipment operation. Raw material dependencies center on petroleum-derived neoprene foam, synthetic elastic yarns, and polymer structural stays sourced from petrochemical suppliers. Single-source vulnerability concentrates in specialized notified body partnerships required for EU MDR CE marking. Distribution runs through wholesale medical distributors and group purchasing organizations serving hospital procurement committees and employer safety programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The waist support belt market functions as a stable compounder anchored by aging workforce demographics across industrialized economies that sustain replacement cycles regardless of macroeconomic cycles.
For Market Incumbents: Acquire specialized fit-technology platforms to reduce e-commerce return rates and defend against direct-to-consumer fitness brands. Deepen backward integration into breathable compression fabric engineering to offset petrochemical cost volatility. Prioritize dual FDA 510(k) and ISO 13485 certification maintenance as hospital procurement committees consolidate vendor lists. For New Entrants and Emerging Players: Enter via telehealth platform partnerships for remote patient monitoring convergence, targeting posture correction applications among sedentary office workers as the most penetrable white-space segment. Leverage algorithmic sizing tools to unlock geographic expansion beyond traditional medical distribution channels. Position against generic compression garment substitution through proprietary material claims. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized orthopedic fabricators possessing ISO 13485 certified production and established notified body relationships for EU MDR compliance. Long-term viability across a 5-10 year horizon rests on reimbursement code stability and employer ergonomics mandate expansion. Monitor CMS durable medical equipment coverage determinations as the primary inflection indicator for medical-grade demand trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks European healthcare channel access for certified exporters. |
| Hospital System Partnership | Integrated delivery networks in Texas and California consolidate procurement around dual-certified suppliers. |
| Software Companion Development | Sensor-embedded belts with posture analytics integrate with remote patient monitoring platforms. |
| Reimbursement Strategy | CMS durable medical equipment code embedding secures standardized hospital procurement. |
| Backward Integration | In-house breathable compression fabric production reduces petrochemical input exposure. |
Research Methodology
Coverage spans the United States, Germany, China, Japan, and Brazil, with primary inputs from each market combining interviews with hospital procurement managers, occupational health directors, biomedical engineers, GPO contracts managers, and sports medicine distributors. Secondary validation draws from FDA 510(k) database filings, EU MDR technical documentation, CMS durable medical equipment coverage determinations, OSHA voluntary ergonomics guidelines, and customs trade data. Bottom-up segment sizing triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. Segmentation dimensions modeled include material composition, application context, target user physiology, and distribution channel structure. CAGRs derive from regression analysis against workforce aging trajectories, employer ergonomics program penetration, and reimbursement policy evolution. Industry-specific forecast inputs incorporate petrochemical price indices and notified body certification timelines.
Inputs from regulatory filings and hospital procurement databases were available through the study window; gaps in real-time employer safety program spending introduce uncertainty bands around occupational segment projections. Forecasts reflect documented assumptions regarding OSHA guideline adoption rates and EU MDR enforcement consistency. Material deviation in CMS coverage determinations, petrochemical price spikes, or notified body capacity constraints warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Bicycle Tire Market
Sports Equipment
Running Gear Market
Sports Equipment
Backboard Market
Sports Equipment
Bicycle Pumps Market
Sports Equipment
Winter Sporting Goods Market
Sports Equipment
Fencing Equipment Market
Sports Equipment
Global Golf Rangefinders Market
Sports Equipment
Stadium Seating Market
Sports Equipment
Tetherball Market
Sports Equipment
Trampoline Market
Sports Equipment
Europe Running Gear Market
Sports Equipment
Surfboard Market
Sports Equipment
Sandbells Market
Sports Equipment
Surfing Equipment Market
Sports Equipment
Bicycle Crankset Market
Sports Equipment
Global Golf Training Aids Market