
 Asia Pacific Weight Management Market | 2026-2036
Asia Pacific Weight Management Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Weight Management Market Insights
Multi-source ingredient procurement is expanding across the Asia Pacific Weight Management Market as brands reduce reliance on single-country raw material dependencies. Herbalife Nutrition Ltd. leverages direct-selling networks spanning Indonesia and the Philippines to sustain channel control in emerging markets. Nestlé Health Science anchors premium positioning through science-backed meal replacement formulations. Abbott Laboratories competes in clinical nutrition segments with hospital-grade weight management protocols.
Asia Pacific weight management encompasses products and services designed to regulate body composition through caloric control, metabolic intervention, and physical activity modulation, typically involving macronutrient-balanced formulations with protein content ranging from fifteen to thirty grams per serving and glycemic index specifications below fifty-five. Meal replacements occupy the highest margin pool due to recurring subscription models and clinical validation requirements, while fitness trackers represent the fastest-growing product type as wearable sensor accuracy improves and integration with telehealth platforms deepens. Online platforms now dominate delivery mode growth, displacing traditional retail stores in South Korea and Australia where smartphone penetration exceeds ninety percent.
Japan's Consumer Affairs Agency enforces strict functional food labeling standards under the Foods with Function Claims system, compelling manufacturers to submit clinical evidence before marketing weight management benefits. Australia's TGA regulates weight loss supplements as complementary medicines, requiring ingredient safety assessments that filter out non-compliant entrants. China's SAMR oversees both direct-sales licensing and health food blue-hat registration, creating dual compliance barriers for foreign brands. Stakeholders must monitor evolving cross-border e-commerce regulations and telehealth reimbursement policies as digital delivery channels reshape competitive access across Southeast Asian markets.
Market Dynamics
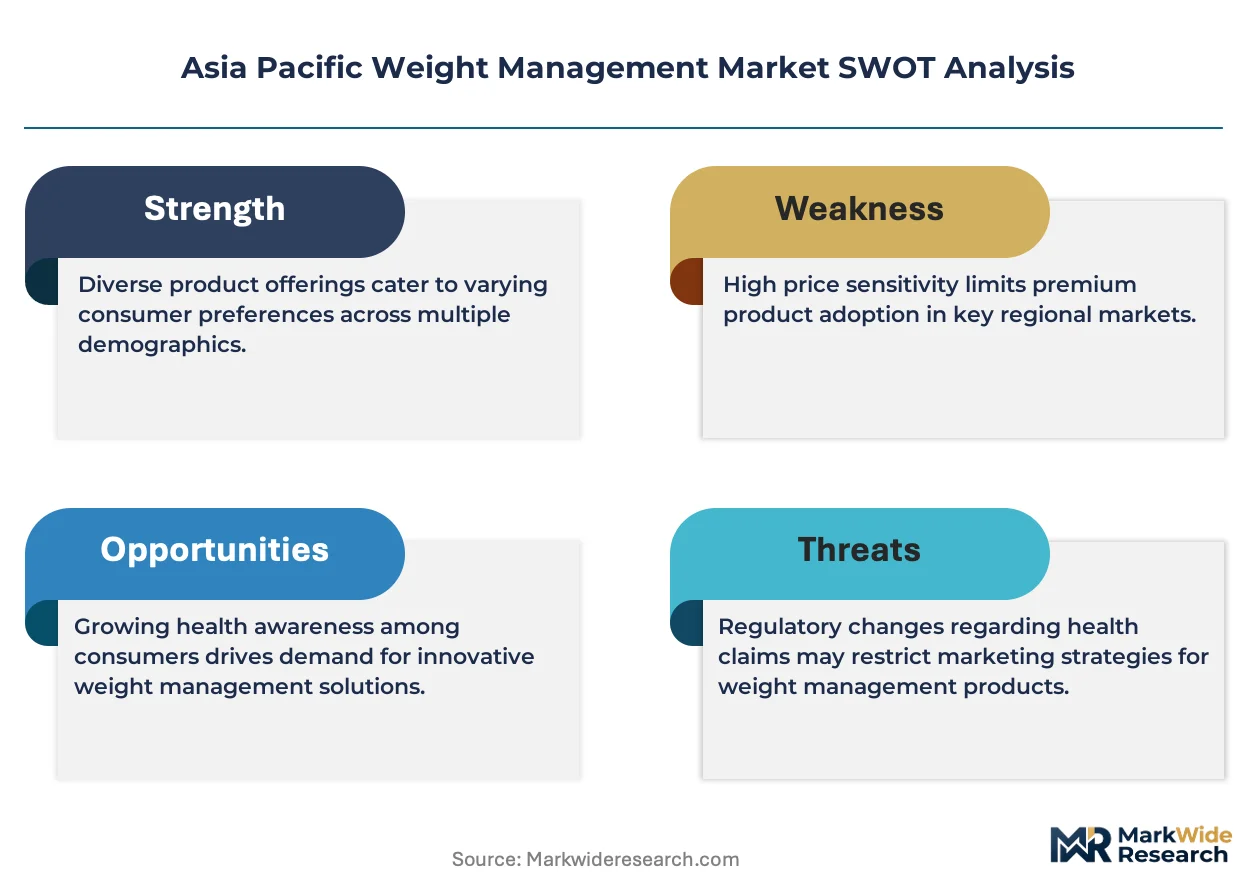
China's SAMR dual licensing framework for direct-sales and health food registration is forcing foreign weight management brands into multi-year compliance timelines, compressing market entry velocity while domestic competitors exploit regulatory familiarity.
Growth Catalysts
- Japan's Foods with Function Claims system:Clinical evidence requirements for functional food labeling are elevating product credibility standards and filtering out unsubstantiated competitors.
- Corporate wellness mandates:South Korean and Japanese employers are expanding structured weight management benefits as part of occupational health obligations.
- Telehealth platform integration:Wearable sensor accuracy improvements are deepening connectivity between fitness trackers and remote coaching services.
Market Restraints
- Raw material concentration risk:Heavy reliance on single-country whey protein and botanical extract sourcing creates supply vulnerability during trade disruptions.
- Clinical validation costs:Japan's PMDA and Australia's TGA evidence requirements impose capital barriers that exclude smaller formulation entrants.
- Substitute threat from whole foods:Fresh prepared meal delivery services are capturing consumers seeking unprocessed alternatives to packaged meal replacements.
Strategic Opportunities
- India's tier-two urban expansion:Rising disposable incomes in cities like Pune and Ahmedabad are creating first-time demand for structured weight management programs.
- Cross-border e-commerce liberalization:Southeast Asian markets are relaxing import restrictions on health supplements through digital trade corridors.
- AI-nutrition convergence:Machine learning personalization engines are enabling real-time macronutrient adjustment based on metabolic response data.
Industry Challenges
- Dual certification timeline compression:Brands must simultaneously navigate China's blue-hat registration and direct-sales licensing, stretching compliance teams across incompatible documentation standards.
- Supply chain reconfiguration friction:Multi-source ingredient procurement requires rebuilding quality assurance protocols for secondary botanical suppliers in Vietnam and Thailand.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Weight Management Market |
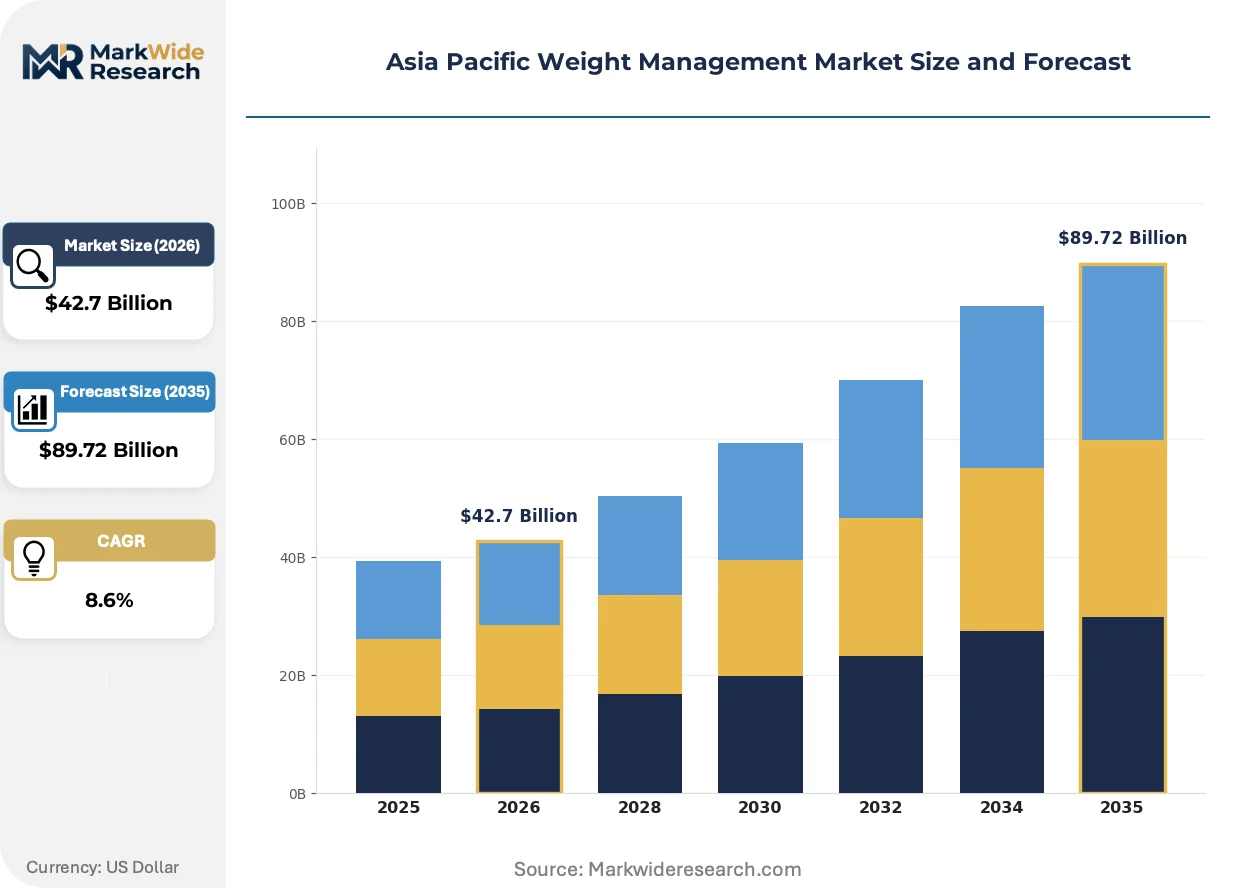
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $89.72 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weight Loss Supplements, Meal Replacements, Exercise Equipment, Fitness Trackers End User: Individuals, Healthcare Professionals, Fitness Centers, Corporates Delivery Mode: Retail Stores, Online Platforms, Direct Sales, Distributors Price Tier: Premium, Mid-Range, Economical, Budget |
| Companies Covered | Herbalife Nutrition Ltd., Nestlé Health Science, WW International, Inc., GNC Holdings LLC, Amway Corporation, Abbott Laboratories, Ajinomoto Co., Inc., Himalaya Wellness Company, Johnson & Johnson, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Weight Management Market Trends and Innovations
Digital biomarker integration is reshaping how weight management services capture and monetize physiological data, shifting value capture from product sales to subscription-based metabolic coaching.
Continuous glucose monitoring wearables are electrifying personalized nutrition programming. Urban professionals in Shanghai and Singapore are adopting CGM-enabled meal planning at accelerating rates. This sensor proliferation is compressing the feedback loop between consumption and metabolic response, enabling real-time dietary intervention.
Australia's TGA complementary medicine reforms are tightening ingredient safety assessment protocols for weight loss supplements. Manufacturers must now submit enhanced toxicological data for novel botanical extracts. This regulatory elevation is disproportionately affecting import-dependent brands while favoring domestic formulators with established TGA relationships.
Subscription bundling is consolidating previously fragmented spending on fitness apps, meal kits, and coaching services. Direct-to-consumer platforms in South Korea are displacing pharmacy retail as the primary channel for meal replacement purchases. This channel migration is most pronounced in Seoul and Busan, where smartphone penetration enables seamless subscription management.
Asia Pacific Weight Management Market Segmentation
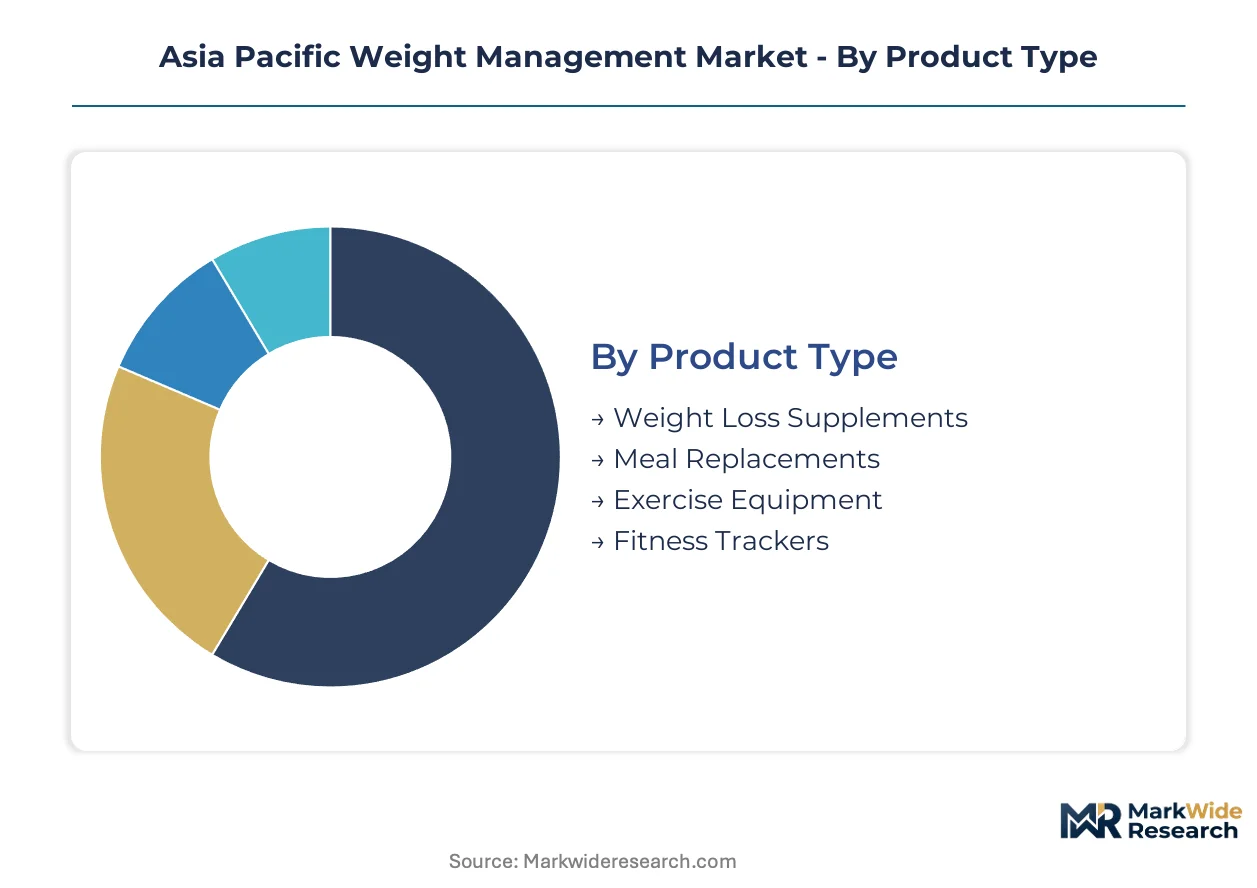
Weight management solutions across Asia Pacific span divergent technological maturity and purchasing power gradients. Segmentation reveals how protein formulation science, sensor hardware, and channel economics partition addressable demand across urban income tiers.
Product Type:
Protein content specifications and glycemic index targets define competitive positioning across formulation categories.
- Meal Replacements:Macronutrient-balanced formulations deliver fifteen to thirty grams of protein per serving with glycemic indices below fifty-five. China's tier-one cities concentrate demand as urban professionals seek clinically validated, recurring subscription solutions for metabolic control.
- Fitness Trackers:Wearable sensor accuracy improvements enable real-time biometric feedback integration with telehealth coaching platforms. Seoul and Singapore lead adoption where smartphone penetration exceeds ninety percent and digital health infrastructure supports continuous data monetization.
- Weight Loss Supplements:Botanical extracts and micronutrient complexes target metabolic intervention through appetite modulation and thermogenic pathways.
- Exercise Equipment:Connected hardware ranging from resistance systems to cardiovascular machines supports physical activity modulation with performance tracking integration.
Mature deployment sits with Meal Replacements. Newer deployment is concentrated in Fitness Trackers.
End User:
Purchasing authority and reimbursement pathways segment demand across institutional and consumer channels.
- Individuals:Direct consumers in Japan and South Korea drive premium self-pay spending for personalized nutrition and digital coaching subscriptions. Japan's Foods with Function Claims system elevates credibility requirements, filtering unsubstantiated products from consideration sets.
- Corporates:South Korean and Japanese employers expand structured weight management benefits under occupational health mandates. Corporate wellness program procurement favors vendors with direct-selling infrastructure and multi-site service capability.
- Healthcare Professionals:Hospitals and clinics prescribe clinical-grade protocols for metabolic intervention and post-surgical weight management.
- Fitness Centers:Gyms and studios bundle coaching with equipment access, creating hybrid service-product offerings for member retention.
Volume concentration rests with Individuals. Margin expansion is concentrated in Corporates.
Delivery Mode:
Channel economics and regulatory licensing requirements determine competitive access and customer acquisition costs.
- Online Platforms:Smartphone penetration above ninety percent in South Korea and Australia enables subscription bundling of apps, meal kits, and coaching services. Direct-to-consumer platforms displace pharmacy retail in Seoul and Busan through seamless mobile purchase journeys.
- Direct Sales:Indonesia and the Philippines sustain channel control for brands leveraging established representative networks. China's SAMR dual licensing framework for direct-sales and health food registration compresses foreign brand entry velocity.
- Retail Stores:Traditional pharmacy and hypermarket channels retain relevance in markets with lower digital payment penetration.
- Distributors:Third-party logistics networks serve fragmented geographic demand across Southeast Asian archipelagos and rural catchments.
Established infrastructure sits with Direct Sales. Channel migration is accelerating fastest in Online Platforms.
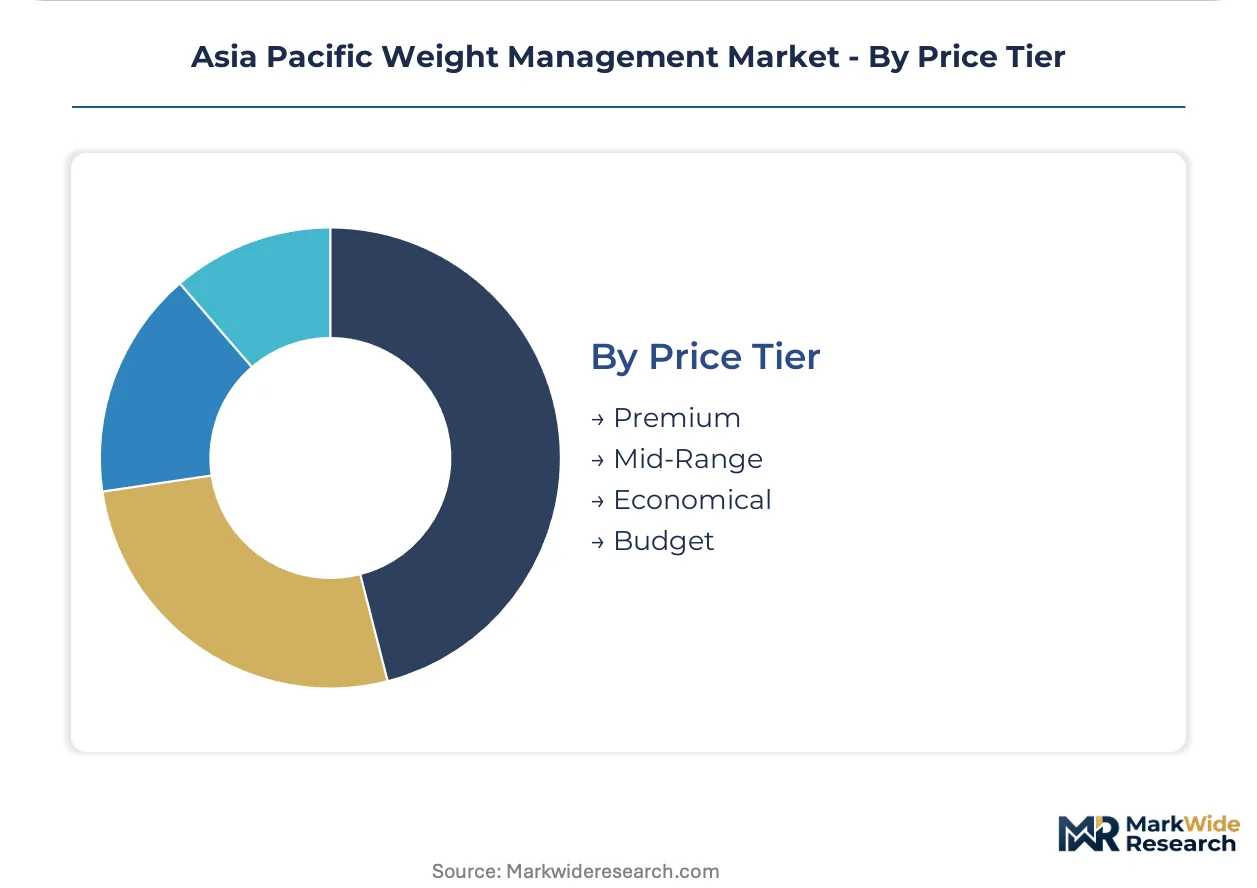
Price Tier:
Certification grade and clinical validation depth stratify purchasing across income distributions.
- Premium:Science-backed formulations with hospital-grade protocols and PMDA or TGA clinical evidence command reimbursement-adjacent positioning. Australia's TGA complementary medicine reforms tighten toxicological data requirements, favoring domestic formulators with established regulatory relationships.
- Mid-Range:Quality-assured products with functional claims documentation target urban professionals seeking efficacy without clinical prescription requirements.
- Economical:Basic macronutrient formulations serve price-sensitive demand in India's tier-two cities like Pune and Ahmedabad where first-time structured program adoption is emerging.
- Budget:Entry-level supplements and generic fitness equipment address mass-market trial and occasional use patterns.
Revenue concentration sits with Premium. Volume expansion is climbing fastest in Economical.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Whey protein and botanical extract sourcing concentrates in Australia and New Zealand, anchoring raw material supply for Asia Pacific formulation networks. This feedstock geography shapes manufacturing cost structures and trade corridor dependencies across the region.
China
Tier-one cities including Shanghai and Beijing drive premium demand for integrated digital fitness and personalized nutrition subscriptions. SAMR enforces dual licensing for direct-sales and health food blue-hat registration, compressing foreign brand entry timelines. Yangtze River Delta manufacturing clusters now host domestic competitors exploiting regulatory familiarity to accelerate product launches.
Japan
Corporate wellness mandates under occupational health obligations expand structured weight management benefits through employer procurement. The Consumer Affairs Agency enforces Foods with Function Claims standards requiring clinical evidence submission before marketing functional benefits. Kanto region employers in Tokyo and Yokohama lead adoption of clinically validated meal replacement programs.
South Korea
Seoul and Busan concentrate demand where smartphone penetration enables seamless subscription management for direct-to-consumer platforms. MFDS regulates health functional foods with stringent safety assessment protocols. The Seoul Capital Area hosts telehealth platform integration between wearable sensors and remote metabolic coaching services.
India
Rising disposable incomes in Pune and Ahmedabad create first-time demand for structured weight management programs in tier-two urban centers. FSSAI nutrition labeling requirements for packaged foods reshape product formulation standards nationwide. Maharashtra and Gujarat manufacturing zones adapt supply chains to meet domestic sourcing preferences for botanical extracts.
Australia
TGA complementary medicine reforms tighten toxicological data requirements for weight loss supplements, favoring domestic formulators with established regulatory relationships. Sydney and Melbourne anchor clinical-grade protocol development for hospital-adjacent nutrition positioning. New South Wales and Victoria host premium-tier brands leveraging reimbursement-adjacent credibility.
Asia Pacific Weight Management Market Competitive Landscape
Strategic partnerships dominate the current landscape as brands navigate multi-jurisdictional compliance barriers. The vendor base organizes around three tiers: multinational nutrition conglomerates with clinical validation infrastructure, direct-selling specialists leveraging representative networks, and domestic formulators exploiting regulatory familiarity. Two strategic archetypes predominate: science-backed premium positioning anchored by hospital-grade protocols, and channel-control models sustaining emerging market penetration through established distributor relationships. Competitive moves concentrate on geographic licensing arrangements and portfolio diversification into adjacent metabolic health categories.
Within the direct-selling archetype, Herbalife Nutrition Ltd. and Amway Corporation occupy positions sustained by representative network density across Indonesia and the Philippines. Nestlé Health Science and Abbott Laboratories anchor the clinical-validation tier, exemplifying science-backed formulation positioning. Himalaya Wellness Company represents domestically-rooted botanical expertise navigating India's FSSAI compliance environment.
| Leading Market Players |
|---|
| Herbalife Nutrition Ltd. |
| Nestlé Health Science |
| WW International, Inc. |
| GNC Holdings LLC |
| Amway Corporation |
| Abbott Laboratories |
| Ajinomoto Co., Inc. |
| Himalaya Wellness Company |
| Johnson & Johnson |
| Others |
Pricing and Supply Chain Analysis
Continuous glucose monitoring integration into subscription coaching bundles is compressing per-unit hardware margins while elevating lifetime customer value, simultaneously concentrating procurement leverage among sensor manufacturers in South Korea and Japan. This technology shift forces brands to rebalance upfront device pricing against recurring service revenue, reshaping supplier negotiations toward volume commitment structures.
Pricing Analysis
Subscription bundling of coaching apps, meal replacements, and wearable data services now dominates pricing architecture across Seoul and Singapore, with unbundled hardware sales confined to trial-tier entry points. Price differentiation separates PMDA-validated formulations from functional-claim products lacking clinical dossiers. Pricing pressure stems from fresh prepared meal delivery services capturing consumers seeking unprocessed alternatives. Corporate wellness procurement in Tokyo shows lowest price sensitivity; India's tier-two cities exhibit highest.
Supply Chain Analysis
Freight cost volatility from Australia and New Zealand whey protein corridors is compressing formulation margins for brands without forward contracting discipline. Raw material sourcing concentrates in Australian dairy zones, Chinese botanical cultivation regions, and Thai herbal processing facilities. Supply chains draw from single-country whey dependencies and Vietnam-Thailand secondary botanical suppliers. Single-source protein vulnerability intensifies during trade disruptions. Distribution runs through direct-selling representative networks in Indonesia and the Philippines alongside direct-to-consumer platforms in South Korea.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market consolidation is accelerating as Japan's PMDA and Australia's TGA clinical validation costs exclude smaller formulation entrants, forcing sub-scale players toward acquisition or exit.
For Market Incumbents: Lock in multi-year whey protein offtake agreements with Australian suppliers to neutralize commodity volatility exposure. Deepen vertical integration into botanical extraction capabilities across Thailand and Vietnam to secure secondary supplier qualification ahead of TGA toxicological data mandates. Channel control through direct-selling infrastructure in Indonesia and the Philippines remains defensible against digital-native entrants. For New Entrants and Emerging Players: Tier-two Indian corporate wellness buyers in Pune and Ahmedabad represent underserved procurement demand with limited incumbent penetration. Cross-border e-commerce corridors into Southeast Asian markets offer lower regulatory friction than SAMR dual licensing. AI-nutrition personalization engines enable differentiated positioning without capital-intensive clinical trial infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by multinational nutrition conglomerates seeking direct-selling network density. Long-term viability favors brands with established PMDA or TGA clinical dossiers and recurring subscription revenue exceeding sixty percent of mix. Watch for telehealth reimbursement policy shifts as inflection signals for digital coaching platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Investment | PMDA dossier submission elevates product credibility above functional-claim competitors in Japan. |
| Direct-Sales Network Expansion | Representative density in Indonesia and the Philippines sustains channel control against digital platforms. |
| Botanical Supplier Diversification | Secondary qualification in Vietnam and Thailand reduces single-country extract dependency risk. |
| Telehealth Platform Integration | Wearable sensor connectivity with remote coaching deepens customer lifetime value in Seoul. |
| Corporate Wellness Contracting | Employer procurement mandates in Tokyo and Yokohama anchor recurring revenue stability. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with nutrition product development executives, regulatory affairs leads at functional food manufacturers, corporate wellness procurement managers, and direct-selling network operators. Bottom-up demand modeling across product categories triangulated against top-down macroeconomic indicators and healthcare expenditure trends.
Granularity-level modeling operated at country-city tier for demand estimation, product-format level for pricing analysis, and channel-mode level for distribution economics. Segmentation dimensions included formulation type, delivery mode, end-user category, and price tier. CAGRs were derived from trend extrapolation adjusted for regulatory event probabilities and technology adoption curves. Forecast inputs incorporated SAMR licensing timeline data, FSSAI labeling implementation schedules, and smartphone penetration trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to telehealth reimbursement policy shifts, cross-border e-commerce regulatory liberalization, and trade corridor disruptions affecting whey protein supply. Forecasts reflect assumptions about clinical validation cost trajectories and corporate wellness mandate expansion rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Health and Wellness
Smart Wellness Market
Health and Wellness
Weight Loss and Weight Management Market
Health and Wellness
Europe Health and Wellness Market
Health and Wellness
Health and Wellness Products Market
Health and Wellness
Smart Breathing Trainer Market
Health and Wellness
Sports and Fitness Biohacking Market
Health and Wellness
Weight Control Products Market
Health and Wellness
Europe Weight Management Market
Health and Wellness
GCC Weight Management Market
Health and Wellness
Brain Fitness Market
Health and Wellness
Global Body Fat Reduction Market
Health and Wellness
Yoga Market
Health and Wellness
GCC Weight Loss Market
Health and Wellness
Australia and New Zealand Corporate Wellness Market
Health and Wellness
UAE Weight Loss Market
Health and Wellness
Weight Management Market