
 Australia Wearables Market | 2026-2036
Australia Wearables Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Wearables Market Outlook
Subscription-based health monitoring services is decoupling hardware sales from recurring revenue in the Australia wearables sector. Apple Inc. leverages its ecosystem lock-in to sustain premium pricing across integrated wellness platforms. Samsung Electronics Co. Ltd anchors its local position through Galaxy Watch compatibility with Australia's My Health Record infrastructure. Garmin Ltd specializes in ruggedized GPS-enabled devices that dominate outdoor recreation segments across Tasmania and Queensland.
Wearables encompass body-worn electronic devices incorporating sensors, microprocessors, and wireless connectivity modules to capture physiological or environmental data with power consumption typically below one watt continuous draw. These devices serve commercial purposes spanning fitness optimization, chronic disease management, and workplace safety compliance in mining and construction sectors. Smartwatches command the largest revenue pool among product types, while wearable medical devices capture the fastest growth trajectory as TGA approvals expand for atrial fibrillation detection and continuous glucose monitoring. Fitness enthusiasts remain the most mature end-user category, whereas seniors represent an underpenetrated segment where simplified interfaces and fall-detection capabilities are reshaping product development priorities.
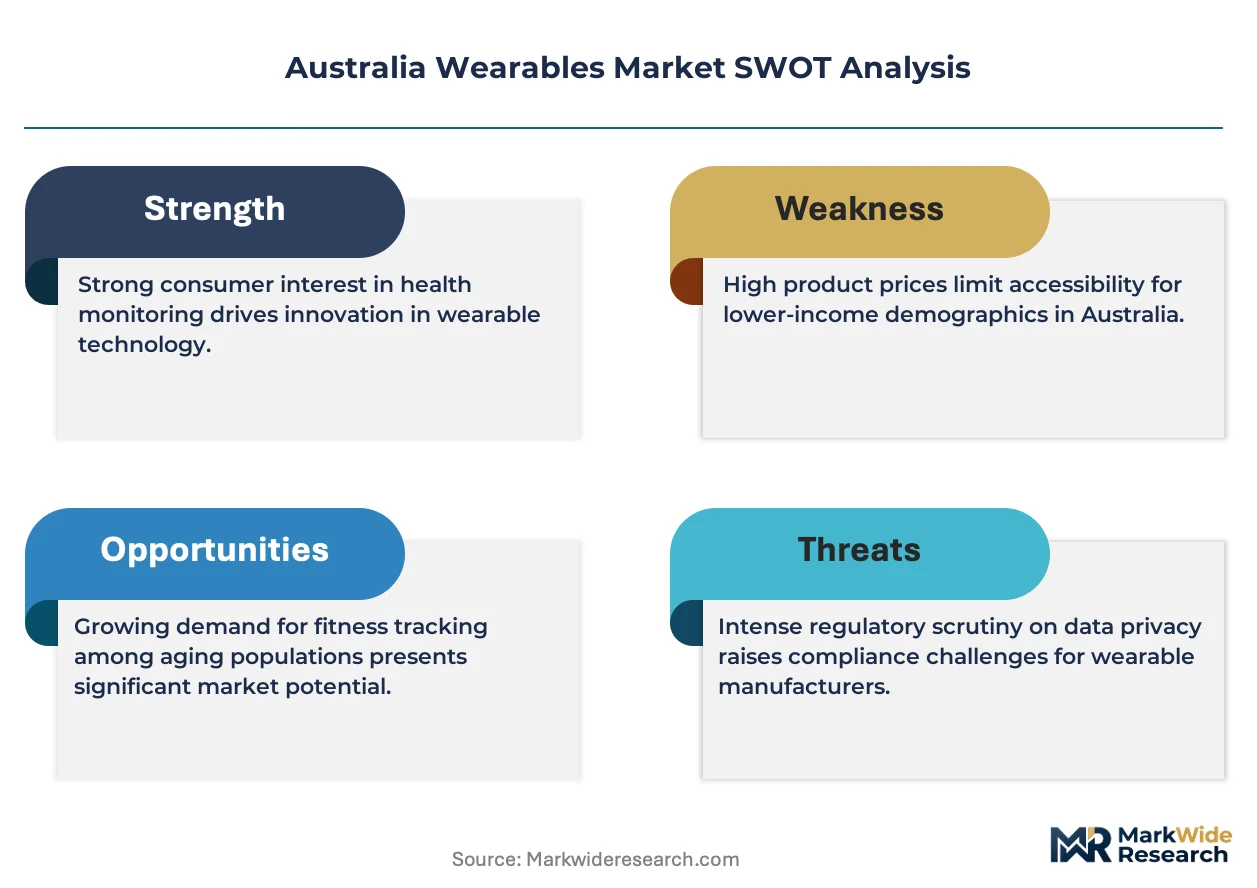
TGA Software as a Medical Device frameworks and the Australian Privacy Principles under the Privacy Act shape data governance obligations for health-connected wearables, compelling vendors to localize cloud storage and encryption protocols. The Therapeutic Goods Administration's evolving cybersecurity guidance for connected medical devices is raising compliance barriers for imported products lacking Australian-specific risk assessments. Stakeholders must monitor how Medicare reimbursement policies for remote patient monitoring redefine which wearable categories qualify for clinical subsidy pathways.
Market Dynamics
Clinical-grade wearables migration from hospitals to home settings is restructuring procurement patterns across Australian healthcare networks, with TGA Software as a Medical Device pathways compressing regulatory timelines for connected health devices.
Growth Catalysts
- TGA SaMD Framework:Streamlined registration pathways for Software as a Medical Device accelerate market entry timelines for continuous glucose monitoring and atrial fibrillation detection wearables.
- My Health Record Integration:Galaxy Watch compatibility with Australia's national health infrastructure creates seamless data interoperability that drives hospital network procurement decisions.
- Remote Patient Monitoring:Medicare reimbursement policy evolution for home-based clinical monitoring expands addressable patient populations beyond traditional hospital settings.
Market Restraints
- Cloud Localization Costs:Australian Privacy Principles mandate domestic data storage and encryption protocols, raising operational overhead for vendors lacking Australian infrastructure.
- Cybersecurity Compliance Barriers:TGA's evolving connected medical device guidance requires Australian-specific risk assessments that imported products frequently lack.
- Senior User Interface Complexity:Current device ecosystems prioritize feature density over simplified interaction design, limiting penetration in Australia's aging demographic cohort.
Strategic Opportunities
- Queensland and Tasmania Outdoor Segments:Ruggedized GPS-enabled device demand in remote recreation and mining safety applications remains underserved by clinical-focused vendors.
- Fall-Detection Capability Expansion:Simplified alert systems for independent seniors represent unmet need in residential aged care transition pathways.
- Subscription Revenue Decoupling:Hardware-agnostic health monitoring services create recurring revenue streams that reduce customer acquisition cost dependence on device replacement cycles.
Industry Challenges
- Clinical Validation Timelines:TGA evidence requirements for novel biomarker algorithms extend development cycles beyond consumer electronics refresh rates.
- Interoperability Fragmentation:Proprietary data formats across competing wellness platforms impede seamless patient record integration with New South Wales and Victoria hospital networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Wearables Market |
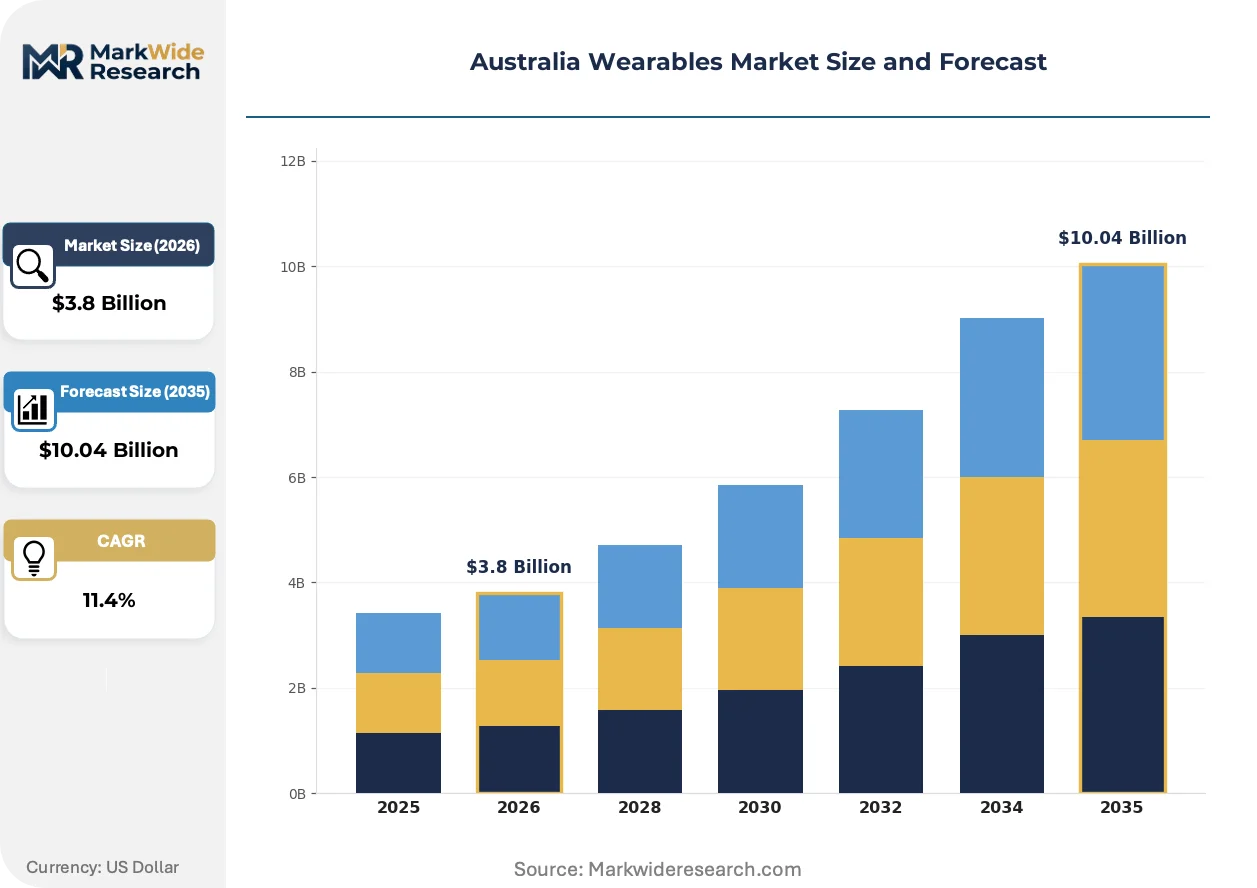
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smartwatches, Fitness Trackers, Smart Glasses, Wearable Medical Devices End User: Fitness Enthusiasts, Healthcare Patients, Technology Adopters, Seniors Deployment: In-Band, Standalone, Integrated Systems, Cloud-Based Technology: Bluetooth, NFC, RFID, Wi-Fi |
| Companies Covered | Apple Inc., Samsung Electronics Co. Ltd, Huawei Technologies Co. Ltd, Nuheara Limited, OPPO Guangdong Mobile Telecommunications Corp., Ltd., Garmin Ltd, Tfive Pty Ltd., Fitbit Inc., Xiaomi Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Wearables Market Strategic Shifts
Sensor miniaturization and edge computing integration are enabling physiological monitoring capabilities that previously required dedicated medical equipment, compressing the boundary between consumer wellness and clinical-grade devices.
Photoplethysmography sensor arrays is modularizing across smartwatch form factors, enabling blood oxygen saturation and irregular rhythm detection in devices priced at consumer electronics tiers. Hospital procurement teams in Victoria are piloting these sensors for post-discharge cardiac monitoring, collapsing the traditional separation between hospital-grade and home-use monitoring equipment. This compression is modularizing vendor business models around software subscriptions rather than hardware margins.
TGA's cybersecurity guidance for connected medical devices mandates Australian-specific risk documentation that imported wearables must satisfy before market authorization. Device manufacturers lacking local regulatory expertise face extended compliance timelines that advantage established players with dedicated Australian regulatory affairs functions. The guidance most acutely affects atrial fibrillation detection algorithms, where real-world performance validation requires domestic clinical data collection.
Healthcare procurement teams in New South Wales are unbundling device acquisition from data analytics subscriptions, separating capital expenditure from operational technology spending. This purchasing pattern shift pressures vendors to demonstrate standalone software value independent of hardware lock-in. The unbundling is most visible in remote patient monitoring contracts, where hospital networks negotiate multi-vendor sensor compatibility against centralized analytics platforms.
Australia Wearables Market Segmentation
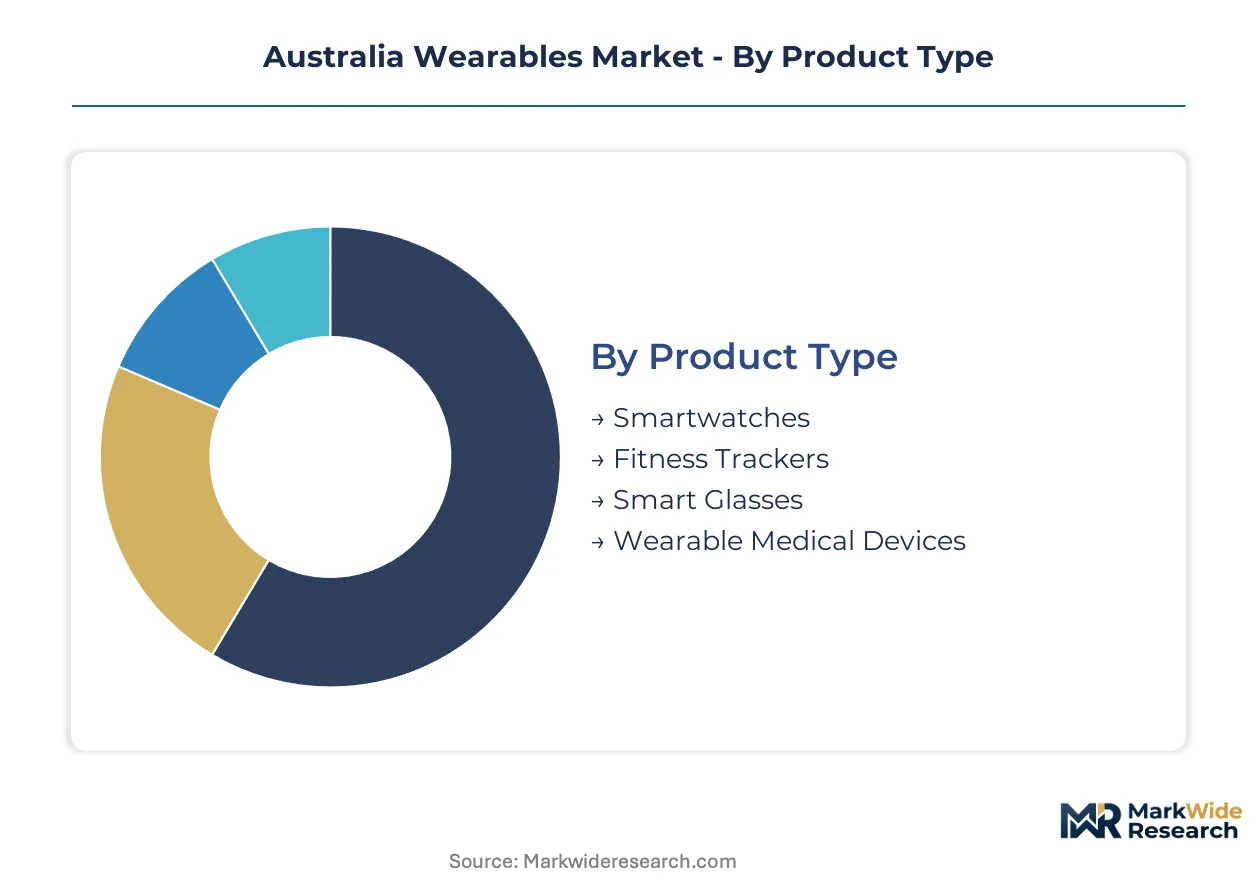
Wearables segmentation in Australia reflects divergent buyer priorities across consumer wellness, clinical applications, and industrial safety contexts. Procurement patterns vary sharply between hospital networks seeking TGA-validated devices and recreational users prioritizing GPS accuracy and battery longevity.
Product Type:
Price-performance positioning determines channel strategy and margin structure across hardware categories.
- Smartwatches:Multi-sensor platforms integrate photoplethysmography arrays, accelerometers, and gyroscopes within wrist-worn form factors. New South Wales and Victoria hospital networks pilot these for post-discharge cardiac monitoring, collapsing traditional boundaries between consumer and clinical tiers.
- Wearable Medical Devices:TGA Software as a Medical Device frameworks govern continuous glucose monitors and atrial fibrillation detection systems with clinical-grade accuracy requirements. Medicare reimbursement policy evolution for remote patient monitoring accelerates procurement timelines across Australian healthcare networks.
- Fitness Trackers:Stripped-down sensor packages prioritize step counting, sleep staging, and basic heart rate monitoring at accessible price points.
- Smart Glasses:Optical waveguide displays overlay navigation and workflow data for mining and construction safety applications.
Volume sits with smartwatches; growth tilts toward wearable medical devices.
End User:
User sophistication and technical support requirements shape distribution channel selection and interface design investment.
- Healthcare Patients:Chronic disease management applications demand seamless My Health Record integration and caregiver alert systems. TGA regulatory pathways compress registration timelines for home-based clinical monitoring devices.
- Seniors:Fall-detection capabilities and simplified alert interfaces address residential aged care transition needs. Current device ecosystems prioritize feature density over interaction simplicity, constraining penetration.
- Fitness Enthusiasts:Performance optimization drives demand for VO2 max estimation, recovery metrics, and training load balancing.
- Technology Adopters:Early access to beta features and developer APIs motivates purchase decisions ahead of mainstream availability.
Revenue concentrates with healthcare patients; expansion potential peaks with seniors.
Deployment:
Data sovereignty requirements and IT infrastructure maturity dictate architecture selection across buyer segments.
- Cloud-Based:Australian Privacy Principles mandate domestic data storage and encryption protocols, raising operational overhead for vendors lacking local infrastructure. Hospital procurement teams unbundle device acquisition from analytics subscriptions.
- Standalone:Edge processing eliminates connectivity dependencies for remote recreation and mining safety applications across Queensland and Tasmania.
- In-Band:Smartphone-tethered configurations reduce hardware cost and battery burden for price-sensitive consumer segments.
- Integrated Systems:Enterprise fleet management platforms consolidate multi-vendor sensor feeds into centralized analytics dashboards.
Adoption clusters around cloud-based architectures; standalone deployment gains traction in connectivity-constrained environments.
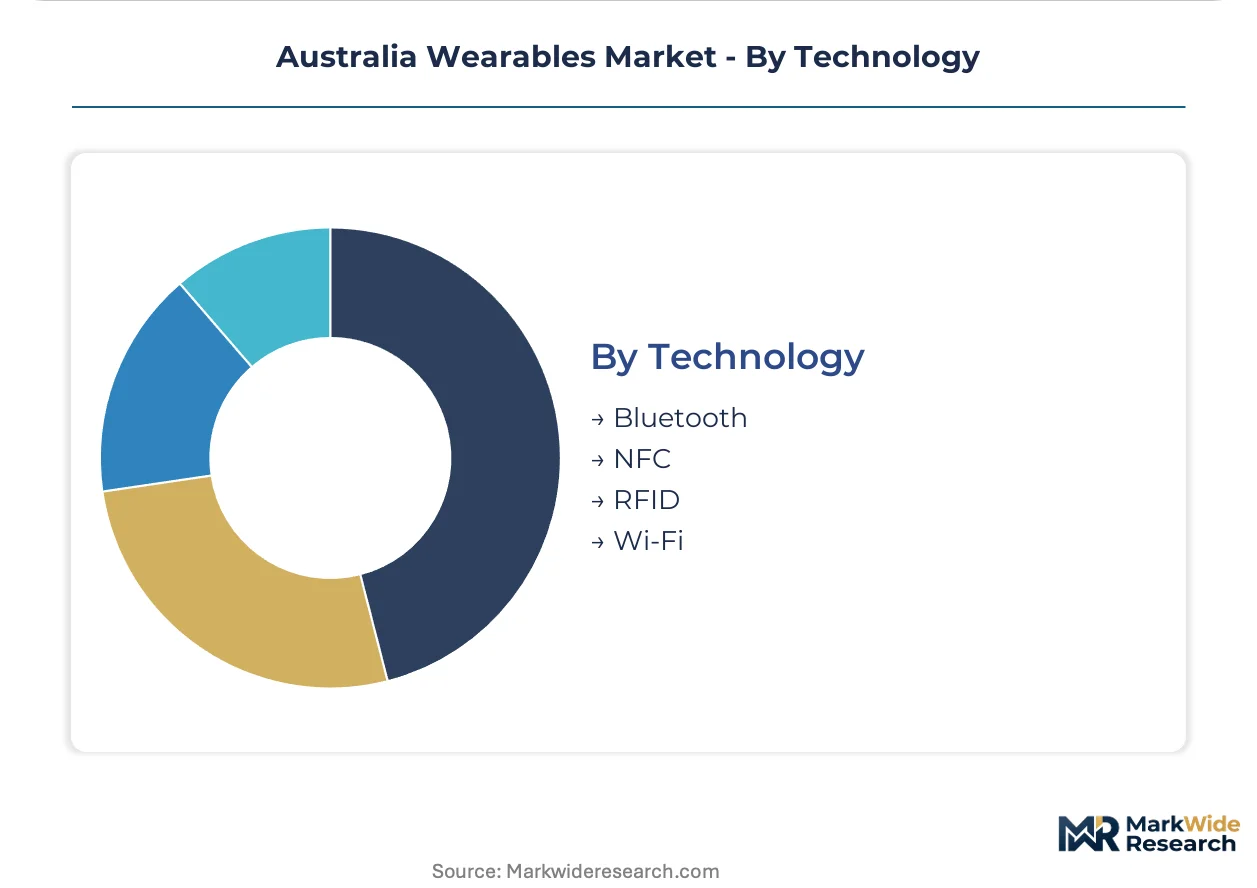
Technology:
Connectivity protocol selection balances range, power consumption, and interoperability requirements against use case demands.
- Bluetooth:Low-energy variants dominate smartwatch and fitness tracker connectivity with sub-milliwatt power draw during idle states. TGA cybersecurity guidance for connected medical devices mandates Australian-specific risk documentation affecting protocol implementation.
- Wi-Fi:Higher throughput supports firmware updates and bulk data offload in clinical settings with reliable infrastructure.
- NFC:Contactless pairing and payment authentication enable streamlined onboarding experiences.
- RFID:Passive tag integration supports workplace safety compliance tracking in mining and construction sectors.
Bluetooth anchors installed base; Wi-Fi expands fastest in hospital network deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic consumption concentrates in coastal metropolitan corridors while component sourcing and manufacturing partnerships extend across Asia-Pacific supply networks. New South Wales and Victoria generate the majority of procurement demand from hospital networks and digital health clusters. Queensland and Tasmania present distinct outdoor recreation and industrial safety segments that diverge from clinical-focused procurement patterns.
New South Wales
Sydney-based hospital networks drive procurement of remote patient monitoring solutions with TGA-validated continuous glucose monitoring systems. The state's digital health clusters align with Australian Privacy Principles mandating domestic cloud storage for patient data. Procurement teams in Greater Sydney unbundle device acquisition from analytics subscriptions, reshaping vendor contract structures.
Victoria
Melbourne's medical technology corridor accelerates pilot programs for post-discharge cardiac monitoring using photoplethysmography-enabled smartwatches. TGA Software as a Medical Device frameworks compress registration timelines for local developers. The state's hospital procurement consortia negotiate multi-vendor sensor compatibility against centralized analytics platforms.
Queensland
Mining safety compliance and remote recreation applications generate demand for ruggedized GPS-enabled devices with standalone edge processing. The state's connectivity-constrained environments favor battery-optimized hardware over cloud-dependent architectures. Procurement from Brisbane-based industrial distributors emphasizes workplace safety tracking over clinical biomarker monitoring.
Western Australia
Resource sector procurement prioritizes workplace safety wearables with RFID integration for personnel tracking across remote extraction sites. The state's sparse population density limits hospital network scale but drives specialized industrial applications. Perth-based mining operators negotiate fleet management platforms consolidating multi-vendor sensor feeds.
South Australia
Adelaide's emerging medtech manufacturing base attracts partnerships for TGA-compliant device assembly serving national distribution. The state's lower operational costs appeal to vendors establishing Australian regulatory affairs functions. Local procurement remains modest compared to eastern states but supports specialized component sourcing for clinical-grade wearables.
Australia Wearables Market Competitive Environment
Capital-heavy producers compete with asset-light designers across hardware manufacturing and software platform layers. The market structure tilts toward ecosystem-integrated technology conglomerates with dedicated Australian regulatory affairs capabilities. Three archetypes dominate: vertically integrated hardware-software platforms, specialized clinical device manufacturers, and ruggedized industrial equipment suppliers. Competitive moves center on TGA compliance infrastructure investment and subscription revenue model decoupling from hardware refresh cycles.
Within the ecosystem-integrated tier, Apple Inc. and Samsung Electronics Co. Ltd occupy positions defined by national health infrastructure compatibility and consumer platform lock-in. Garmin Ltd anchors the ruggedized specialization vector for outdoor and industrial segments. These three entities exemplify divergent strategic postures: premium consumer wellness platform dominance, clinical interoperability leadership, and purpose-built hardware for connectivity-constrained environments.
| Leading Market Players |
|---|
| Apple Inc. |
| Samsung Electronics Co. Ltd |
| Huawei Technologies Co. Ltd |
| Nuheara Limited |
| OPPO Guangdong Mobile Telecommunications Corp., Ltd. |
| Garmin Ltd |
| Tfive Pty Ltd. |
| Fitbit Inc. |
| Xiaomi Corporation |
| Others |
Value Chain & Pricing Dynamics
Photoplethysmography sensor miniaturization is compressing production economics while concentrating component sourcing among Taiwanese semiconductor foundries and Chinese MEMS manufacturers, simultaneously lowering bill-of-materials costs and tightening vendor dependency on Asia-Pacific supply nodes for wrist-worn health monitoring platforms.
Pricing Analysis
Margin tightening in the wearable medical device tier reflects TGA Software as a Medical Device compliance costs and domestic cloud infrastructure investments mandated by Australian Privacy Principles. Three-tier pricing structure across premium ecosystem-integrated, standard multi-function, and economy fitness-tracker levels separates Apple and Samsung's platform lock-in from Garmin's specialized outdoor positioning and Xiaomi's stripped-down sensor packages. Healthcare procurement teams in New South Wales and Victoria exhibit lowest price sensitivity due to Medicare reimbursement pathways, while consumer fitness segments face acute pressure from subscription-service bundling that decouples hardware margins from recurring revenue.
Supply Chain Analysis
Freight cost volatility from Shanghai and Shenzhen ports to Australian distribution centers is elevating landed costs for Bluetooth module and lithium-polymer battery shipments, compressing distributor margins on imported finished goods. Component sourcing concentrates in China, Taiwan, and South Korea for display panels, application processors, and biometric sensors. Raw material dependencies span rare-earth magnets for haptic feedback, cobalt for battery cathodes, and sapphire glass for premium watch faces. Single-source vulnerability in advanced node semiconductor fabrication threatens production continuity for atrial fibrillation detection algorithms requiring edge-computing capability. Distribution runs through Melbourne and Sydney-based electronics wholesalers serving hospital procurement consortia and retail channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Clinical-grade sensor calibration capacity bottlenecks at TGA-accredited testing facilities are propping pricing power for vendors with established Australian regulatory affairs functions, constraining rapid market entry for imported competitors lacking localized validation infrastructure.
For Market Incumbents: Anchor market position through backward integration into cloud infrastructure serving Australian Privacy Principles compliance, while expanding TGA pre-submission consultation pipelines to accelerate Software as a Medical Device registration timelines for continuous glucose monitoring algorithms. Defensive priorities center on locking hospital network procurement consortia in New South Wales and Victoria through multi-year remote patient monitoring contracts that bundle device supply with analytics subscriptions, neutralizing emerging entrants lacking established My Health Record interoperability. For New Entrants and Emerging Players: The price-point gap between premium ecosystem-integrated smartwatches and economy fitness trackers creates entry space for mid-tier clinical-grade devices with simplified senior-facing interfaces. Target Queensland and Tasmania's ruggedized outdoor segments where Garmin's GPS specialization leaves room for mining safety compliance wearables with RFID personnel tracking. Go-to-market leverage rests on direct engagement with Brisbane-based industrial distributors rather than competing for hospital procurement cycles dominated by incumbent ecosystem players. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by ecosystem-integrated technology conglomerates seeking TGA regulatory expertise and Australian cloud infrastructure. Long-term viability hinges on subscription revenue decoupling from hardware refresh cycles, favoring asset-light software platform developers over capital-intensive device manufacturers. Acquisition target archetype: specialized clinical algorithm developers with domestic real-world performance validation datasets. Signal to monitor: Medicare reimbursement policy expansion for home-based atrial fibrillation detection as inflection indicator for addressable patient population scaling.| Strategic Initiative | Industry Significance |
|---|---|
| TGA SaMD Pre-Submission Investment | Accelerates market authorization timelines for continuous glucose monitoring and cardiac rhythm detection algorithms. |
| Australian Cloud Infrastructure Localization | Satisfies Privacy Act data sovereignty requirements for hospital network procurement compliance. |
| My Health Record Integration Development | Creates seamless interoperability that drives Victoria and New South Wales hospital procurement decisions. |
| Subscription Revenue Model Decoupling | Reduces customer acquisition cost dependence on device replacement cycles in hardware-agnostic health monitoring. |
| Queensland Mining Safety Partnership | Captures ruggedized GPS-enabled device demand in workplace safety compliance and remote recreation applications. |
Study Parameters
Multi-period observation of TGA registration timelines, Medicare reimbursement policy evolution, and hospital procurement contract structures anchored the trend analysis, supplemented by interviews with biomedical engineers at New South Wales and Victoria hospital networks, regulatory affairs specialists at TGA-accredited testing facilities, procurement managers at Group Purchasing Organizations, and channel sales directors at Melbourne and Sydney-based electronics distributors. Secondary validation drew from TGA Software as a Medical Device guidance documents, Australian Privacy Principles regulatory filings, hospital procurement database extracts, and Medicare Benefits Schedule updates. Bottom-up device shipment estimates triangulated against top-down healthcare IT spending projections.
Segment-weighting across product type, end user, deployment architecture, and connectivity technology dimensions informed the analytical framework throughout the projection horizon. CAGRs derived from regression analysis of historical TGA approval velocity, hospital procurement cycle timing, and consumer electronics replacement patterns. Industry-specific forecast inputs incorporated photoplethysmography sensor cost curves and cloud infrastructure pricing trajectories for Australian data center operations.
Inputs from TGA regulatory databases and hospital procurement records were available through the study window; gaps in real-world clinical performance validation datasets for novel biomarker algorithms introduce uncertainty bands around wearable medical device adoption assumptions. Forecasts reflect documented assumptions regarding Medicare reimbursement expansion and cybersecurity guidance evolution. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wearable Fitness Technology
Smart Insole Market
Wearable Fitness Technology
Smart Fitness Trackers Market
Wearable Fitness Technology
North America Wearable Sensors Market
Wearable Fitness Technology
North America Smart Watch Market
Wearable Fitness Technology
Global GPS Watch Tracker Market
Wearable Fitness Technology
Wearable Devices in Sports Market
Wearable Fitness Technology
Breathing Wear Market
Wearable Fitness Technology
Wearable Band Market
Wearable Fitness Technology
Smart Sports Bracelet Market
Wearable Fitness Technology
Thermal Comfort Wearables Market
Wearable Fitness Technology
United States Wearable Sensors Market
Wearable Fitness Technology
Fitness Tracker for Heart Rate Market
Wearable Fitness Technology
Wearable Inertial Sensors Market
Wearable Fitness Technology
Swim Watches Market
Wearable Fitness Technology
Pedometer Market
Wearable Fitness Technology
Smart Wearable Gloves Market