
 Auger Drilling Market | 2026-2036
Auger Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Auger Drilling Market Intelligence
CE marking conformity for equipment sold in Europe is rotating market access towards manufacturers with documented safety and performance testing protocols. Herrenknecht AG specializes in large-scale, custom-engineered drilling solutions for complex geological conditions. Vermeer Corporation competes effectively in the utility installation segment with its specialized horizontal drilling systems. Caterpillar Inc. leverages its vast dealer network to supply vehicle-mounted augers to the construction sector.
Auger drilling is a mechanical excavation method that employs a rotating helical screw blade to remove material from a borehole. The technique's efficiency is determined by the auger's diameter and flight pitch, which are selected based on soil type. Its primary industrial purpose is creating holes for construction foundations, utility poles, and geotechnical surveys. Vehicle-mounted augers command the largest share within construction applications, while handheld units are prevalent in environmental sampling and agricultural sectors.
Operator safety regulations from bodies like the US Occupational Safety and Health Administration (OSHA) mandate specific machine guarding and training protocols. Concurrently, equipment standards including Europe's CE marking and China's GB standards dictate market access through stringent performance and safety benchmarks. Future competitive advantage will hinge on developing auger systems that comply with increasingly varied regional environmental noise and emissions requirements.
Market Dynamics
The tension between standardized, high-volume utility work and specialized, large-scale geotechnical projects is bifurcating the market. This pressures equipment design and supply chains, rewarding manufacturers who can serve either niche effectively.
Growth Catalysts
- Urban Infrastructure Expansion:Rapid urbanization in India and Brazil drives demand for utility installation and foundation construction.
- Geotechnical Survey Mandates:Stricter adherence to ISO standards for soil analysis on large infrastructure projects compels more precise drilling.
- Renewable Energy Projects:The development of solar and wind farms requires extensive auger drilling for foundations and cable trenching.
Market Restraints
- High Capital Cost:The initial investment for large, vehicle-mounted auger systems is a significant barrier for smaller construction contractors.
- Skilled Operator Scarcity:A shortage of certified operators for complex equipment restricts operational capacity and increases labor costs.
- Input Price Volatility:Fluctuations in the price of high-strength steel and diesel fuel create unpredictable operating expenses.
Strategic Opportunities
- Environmental Remediation:Demand for soil sampling and monitoring well installation in contaminated site cleanups opens a specialized application.
- Equipment Electrification:Developing battery-powered augers can meet stricter urban noise and emissions regulations, creating a new product category.
- Telematics Integration:Embedding IoT sensors for remote monitoring offers new revenue through subscription-based maintenance services.
Industry Challenges
- Regional Certification Compliance:Navigating divergent requirements of Europe's CE marking and China's GB standards adds significant testing and documentation overhead.
- Worksite Safety Enforcement:Ensuring adherence to OSHA machine guarding protocols across numerous temporary construction sites is a logistical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auger Drilling Market |
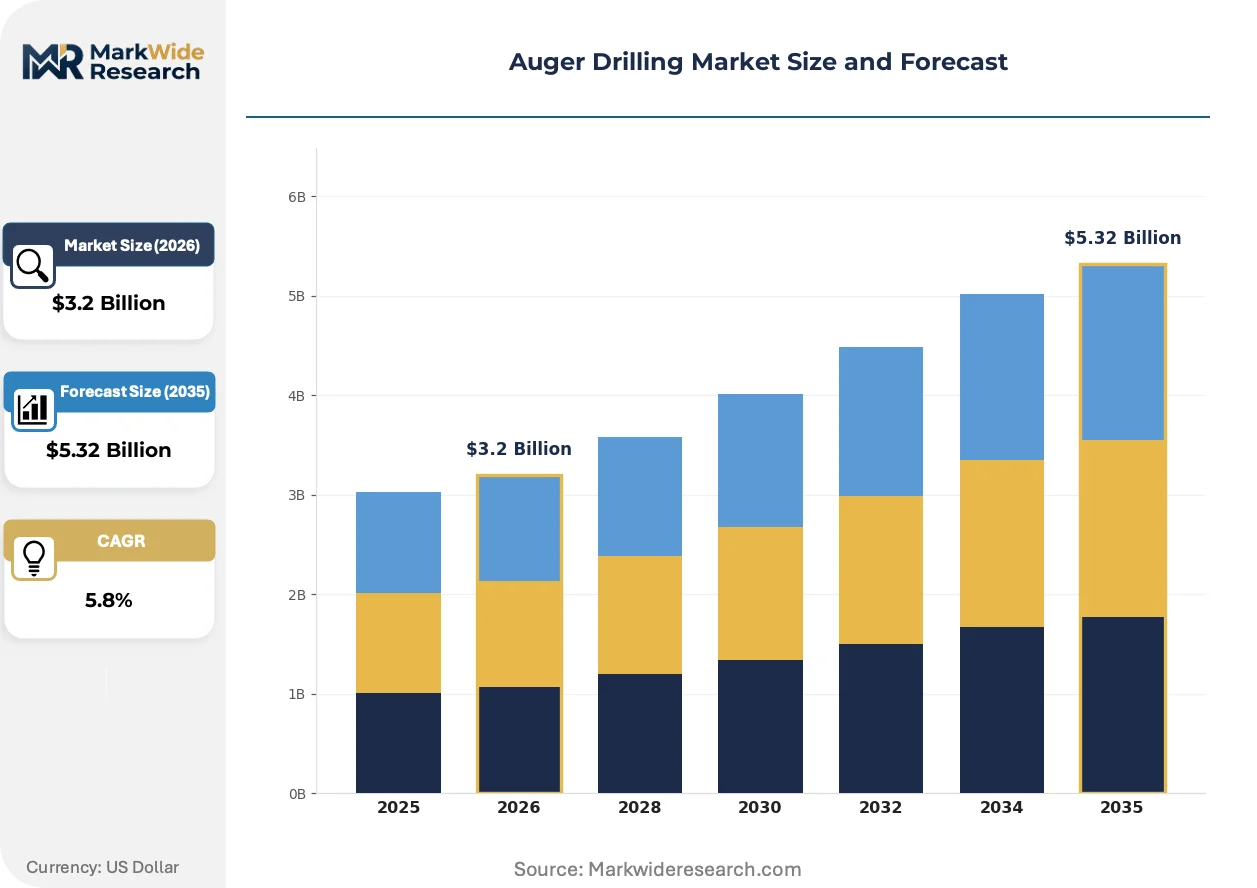
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.32 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Augers, Vehicle-Mounted Augers, Portable Augers, Tractor-Mounted Augers, Spiral Augers Technology: Hydraulic, Pneumatic, Electric, Fuel-Powered, Manual Application: Geotechnical Surveys, Environmental Sampling, Construction Foundations, Agricultural Land Preparation, Utility Installations End User: Construction Firms, Environmental Agencies, Agricultural Operators, Utility Contractors, Research Institutions |
| Companies Covered | Terex Corporation, Herrenknecht AG, Vermeer Corporation, Sollami Company, Sysbohr GmbH, Caterpillar Inc., The Toro Company, Barbco Inc., Liebherr Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auger Drilling Market Strategic Shifts & Innovations
Equipment intelligence and regulatory compliance are jointly defining the next generation of auger drilling systems. This shift favors manufacturers capable of integrating digital technologies while meeting increasingly stringent regional safety and environmental mandates.
Automated drilling control systems use real-time soil sensors and machine learning to optimize rotation and torque. Large civil engineering firms are adopting these systems to improve accuracy on complex geotechnical projects. This technology is fragmenting the market between basic mechanical rigs and advanced, digitally-controlled systems with different performance tiers.
Europe's Machinery Directive, enforced via CE marking, requires rigorous risk assessments and documented safety features. This regulation raises the entry barrier, forcing non-EU manufacturers to invest in design changes and testing. The utility installation segment is most affected, as contractors specify CE-compliant equipment to mitigate liability.
A shift from equipment purchase to short-term rental models is gaining traction among small to mid-sized construction firms. This allows contractors to access specialized augers for specific projects without high capital outlay. The trend is most visible in North American and European urban construction markets where project flexibility is valued.
Auger Drilling Market Segmentation
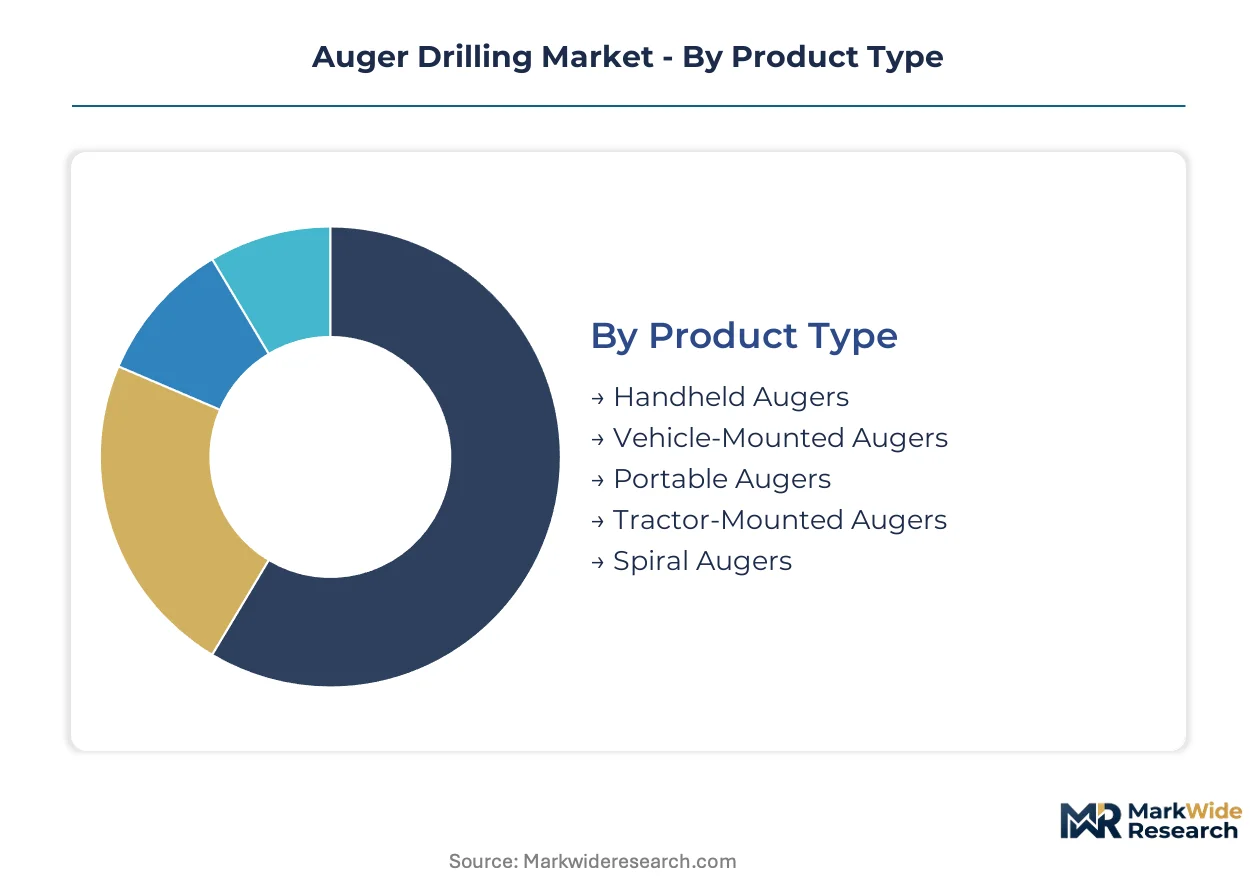
The auger drilling market differentiates across various dimensions, reflecting the diverse operational needs of its end-users. Understanding these segments is critical for manufacturers to tailor equipment and services, addressing specific performance requirements and regulatory compliance across different regions.
Product Type:
Certain product types exhibit distinct geographic footprints, with vehicle-mounted systems dominating large-scale domestic infrastructure projects while handheld units find broader international adoption in specialized environmental work.
- Vehicle-Mounted Augers:These systems integrate directly onto truck or tractor chassis, providing substantial power and mobility for heavy-duty drilling tasks. Demand concentrates in developed economies like the United States and Germany, driven by large-scale public works and commercial construction projects requiring deep foundations.
- Handheld Augers:Compact and manually operated, these augers are suitable for smaller diameter holes and remote locations. They are widely used in environmental sampling and agricultural applications across diverse global markets, including emerging economies where portability is a key driver.
- Portable Augers:Designed for easier transport than vehicle-mounted units, these systems offer a balance of power and mobility for mid-range drilling tasks.
- Tractor-Mounted Augers:These augers attach to agricultural tractors, primarily serving the farming sector for fence posts, planting, and soil preparation.
- Spiral Augers:Characterized by their continuous flighting, these augers efficiently remove soil and are often used for continuous flight auger (CFA) piling in soft ground conditions.
Vehicle-Mounted Augers commands the established base. The steepest expansion runs through Handheld Augers.
Technology:
The cost tiering across auger drilling technologies influences market access, with premium solutions offering advanced performance for complex tasks, while economy options cater to basic operational needs.
- Hydraulic:These systems utilize fluid pressure to generate high torque and thrust, providing robust power for large-diameter and deep drilling applications. They are favored in heavy construction and geotechnical engineering for their precision and control.
- Electric:Battery-powered or corded electric augers offer quieter operation and zero direct emissions, making them increasingly relevant for urban projects and environmental remediation. Demand for electric systems is rising in Europe due to stringent noise and emissions regulations.
- Pneumatic:Air-powered augers are often used in mining and tunneling for their ability to operate in hazardous environments and for rock drilling.
- Fuel-Powered:Gasoline or diesel engines provide independent power for augers, offering high mobility and power for various applications, particularly in remote areas.
- Manual:These basic, hand-operated augers are cost-effective for small-scale tasks, including gardening and minor environmental sampling.
The market gravitates towards Hydraulic for efficiency, while Electric secures specialized niches.
Application:
Specific application segments drive distinct demand patterns for auger drilling equipment, with some areas requiring high precision and others prioritizing high volume and speed.
- Construction Foundations:This application involves drilling holes for building pilings, piers, and other structural supports in commercial and residential developments. Large-scale infrastructure projects in India and Brazil heavily rely on auger drilling for foundational work.
- Utility Installations:Augers create trenches and boreholes for laying underground utilities such as water pipes, gas lines, and fiber optic cables. Rapid urbanization globally, particularly in Southeast Asia, fuels consistent demand for utility installation equipment.
- Geotechnical Surveys:Augers are used to collect soil samples and conduct subsurface investigations for engineering design and environmental assessments.
- Environmental Sampling:This application involves drilling shallow boreholes to collect soil and groundwater samples for contamination analysis and monitoring.
- Agricultural Land Preparation:Farmers use augers for tasks like planting trees, installing fence posts, and preparing soil for various crops.
Construction Foundations drives significant volume, with Utility Installations demonstrating rapid growth potential.
End User:
The volume of auger drilling equipment consumed varies significantly across end-user categories, with large construction and utility sectors representing the highest demand.
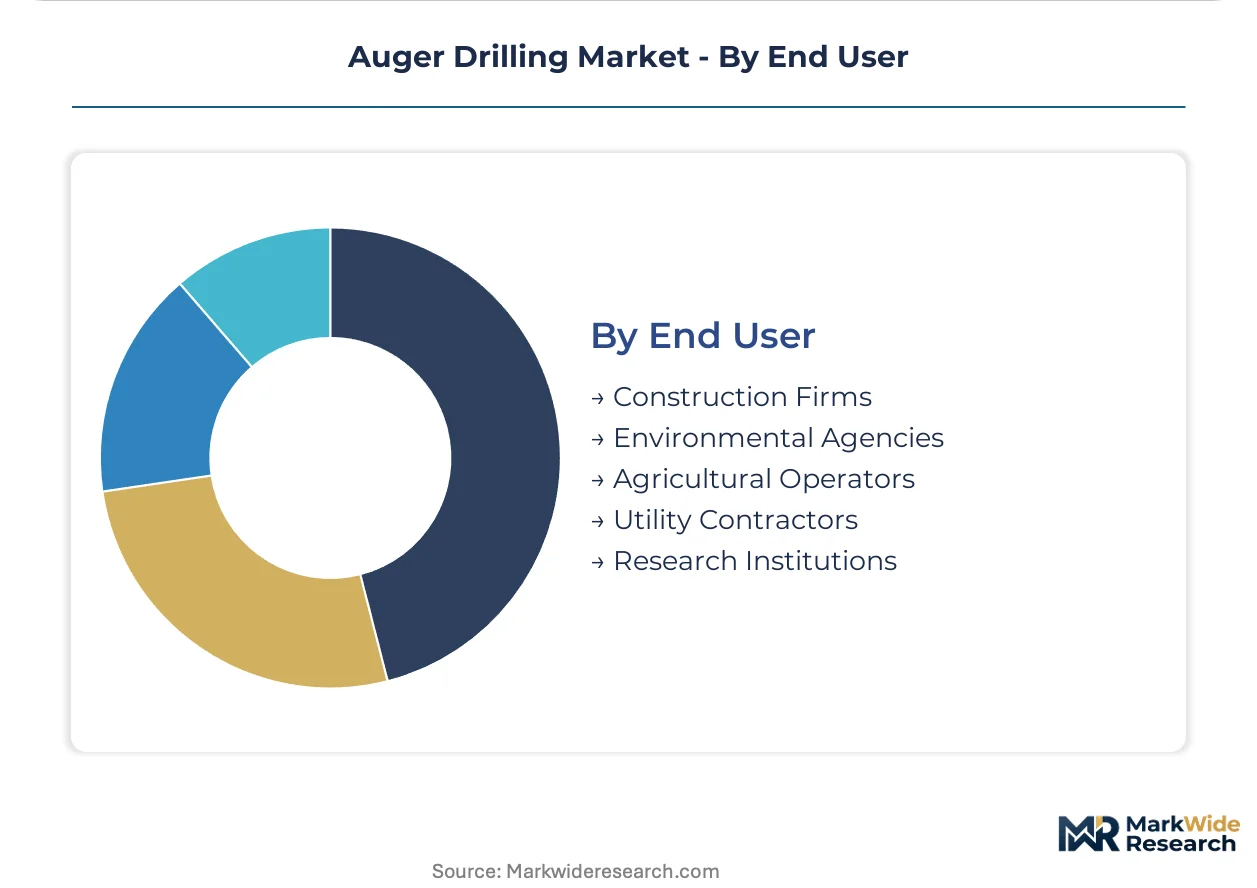
- Construction Firms:These entities represent the largest end-user segment, utilizing augers for a wide range of projects from residential buildings to large infrastructure developments. Their demand is directly tied to the overall health of the construction industry.
- Utility Contractors:Specializing in the installation and maintenance of underground infrastructure, these contractors frequently employ auger drilling for new utility lines and repairs. Their operational efficiency is critical for urban development.
- Environmental Agencies:These organizations use augers for site assessments, remediation projects, and long-term monitoring of soil and groundwater conditions.
- Agricultural Operators:Farmers and agricultural businesses use augers for tasks related to crop production, livestock management, and land improvement.
- Research Institutions:Universities and research bodies utilize augers for geological studies, soil science, and archaeological excavations.
Construction Firms represents a foundational demand source, and Utility Contractors indicates future market diversification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government policies and infrastructure development initiatives significantly influence auger drilling demand across diverse regions. Stricter adherence to geotechnical survey standards, such as those outlined by ISO, for large-scale infrastructure projects necessitates more precise drilling in rapidly developing urban centers. Regulatory frameworks like Europe's CE marking also shape regional equipment demand and market access.
India
Rapid urbanization in India drives substantial demand for utility installation and construction foundations. The government's "Smart Cities Mission" compels significant infrastructure upgrades, requiring extensive drilling for new utilities. Major urban centers like Delhi-NCR experience concentrated activity for metro expansions and high-rise developments.
Brazil
Brazil's urban infrastructure expansion fuels consistent demand for auger drilling, particularly for utility installations and foundational work. National infrastructure programs aim to modernize existing networks and build new ones across the country. São Paulo, as a major economic hub, sees intensive construction and utility projects utilizing advanced drilling techniques.
United States
The United States construction sector utilizes auger drilling extensively for building foundations and utility line installations. OSHA regulations mandate specific machine guarding and training protocols, influencing equipment design and procurement. Texas, with its ongoing energy and residential construction booms, represents a significant market for vehicle-mounted augers.
Germany
Germany's market for auger drilling emphasizes precision engineering and compliance with stringent European standards. The Machinery Directive, enforced via CE marking, requires rigorous risk assessments for equipment sold in the region. Bavaria, a hub for industrial manufacturing, sees demand for specialized drilling solutions in infrastructure and geotechnical projects.
China
China's vast infrastructure projects and urban development initiatives generate immense demand for auger drilling equipment. National GB standards dictate market access through stringent performance and safety benchmarks for all machinery. The Yangtze River Delta region, with its dense urban centers, is a focal point for large-scale construction and utility installations.
Auger Drilling Market Key Industry Players
Listed leaders compete with private specialists across technology integration and market reach within the auger drilling industry. The market structure bifurcates between manufacturers serving high-volume utility work and those providing specialized, large-scale geotechnical solutions. Strategic archetypes include global diversified industrial conglomerates, niche drilling equipment specialists, and regional solution providers. Dominant competitive moves involve enhancing equipment intelligence through telematics and ensuring compliance with varied regional certification standards.
Within the large-scale custom-engineered solutions tier, Herrenknecht AG, a German-based company, exemplifies advanced drilling technology for complex geological conditions and bespoke infrastructure projects. Vermeer Corporation, known for its specialized horizontal drilling systems, occupies a strong position in the utility installation segment, catering to the growing demand for underground infrastructure. Caterpillar Inc., a global industrial conglomerate, anchors the vehicle-mounted auger segment by leveraging its extensive dealer network to supply the broader construction sector with robust machinery. These firms collectively represent the diverse approaches to product development and market penetration.
| Leading Market Players |
|---|
| Terex Corporation |
| Herrenknecht AG |
| Vermeer Corporation |
| Sollami Company |
| Sysbohr GmbH |
| Caterpillar Inc. |
| The Toro Company |
| Barbco Inc. |
| Liebherr Group |
| Others |
Cost & Logistics Intelligence
Economies of scale in auger manufacturing dictate supply concentration, which in turn establishes price floors for high-volume equipment. This dynamic influences market access for smaller producers and impacts overall pricing stability.
Pricing Analysis
CE marking certification creates the primary spread in auger drilling equipment pricing, differentiating European market access. The dominant pricing model is transactional per-unit, with differentiation driven by equipment customization levels and after-sales service bundles. Pricing pressure stems from the increasing availability of lower-cost vehicle-mounted augers from Asian manufacturers. Smaller construction contractors exhibit the highest price sensitivity, often opting for rental models.
Supply Chain Analysis
Extended lead times for specialized hydraulic components impact inventory management across the auger drilling supply chain. Geographic supply concentration centers in Germany for precision engineering, China for high-volume manufacturing, and the United States for heavy-duty vehicle integration. Raw material dependencies include high-strength steel, specialized hydraulic fluids, and diesel engines. Regulatory restrictions on emissions in Europe pose a structural risk to fuel-powered equipment supply. Distribution primarily runs through extensive dealer networks and specialized rental fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation in auger drilling presents opportunities for specialized solutions, driven by divergent demands for utility installations and complex geotechnical projects.
For Market Incumbents: Shield existing market share by investing in advanced telematics integration to offer subscription-based maintenance services, countering threats from new entrants offering digitally enhanced systems. Consolidate regional manufacturing hubs to optimize logistics and meet varied regional certification standards like ISO and GB regulations. This strategy leverages existing dealer networks for competitive advantage.
For New Entrants and Emerging Players: A service-layer gap exists in providing integrated data analytics for real-time drilling optimization, underserved by traditional manufacturers. Target the environmental remediation segment in North America with battery-powered portable augers, focusing on urban noise and emissions regulations. A direct-to-consumer sales model with flexible rental options can penetrate this niche effectively.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among firms offering telematics-enabled maintenance contracts and specialized rental fleets. Seek acquisition targets with strong intellectual property in automated drilling controls or a robust presence in rapidly urbanizing markets like India and Brazil. The signal to watch is the adoption rate of electric augers in European infrastructure projects.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Telematics Integration | Enhances operational efficiency and creates new subscription-based service revenue streams for equipment manufacturers. |
| Battery-Powered Auger Development | Meets stricter urban noise and emissions regulations, opening new product categories for environmental applications. |
| Regional Manufacturing Hub Expansion | Optimizes logistics and ensures compliance with diverse regional standards, strengthening market access for key players. |
| Specialized Rental Fleet Investment | Catapults market penetration among small to mid-sized contractors by reducing their initial capital outlay. |
| Automated Drilling Control R&D | Improves accuracy and efficiency on complex geotechnical projects, attracting large civil engineering firms. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with industry stakeholders and extensive secondary research. Primary insights were gathered from construction firm executives, utility project managers, drilling equipment engineers, and environmental consultants. Secondary data sources included ISO standards documents, OSHA reports, national infrastructure development plans, and specialized industry association publications. The findings were triangulated using both bottom-up and top-down analytical approaches.
The forecasting boundary extended across the projection horizon, modeling market dynamics over a multi-year period. Segmentation dimensions included product type, technology, application, end-user, and regional regulatory compliance. Compound Annual Growth Rates were derived from historical trends and projected demand drivers. Key forecast inputs included urban population growth rates in emerging economies and global infrastructure spending indices.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in raw material price volatility and unforeseen shifts in environmental regulations. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Global Connected Mining Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Impact Crusher Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Digger Machinery Market
Mining Equipment
Europe Drilling Rig Market
Mining Equipment
Mine Hoisting Systems Market
Mining Equipment
Kazakhstan Mining Market
Mining Equipment
Russia Mining Equipment Market
Mining Equipment
Mining Remanufacturing Components Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Rock Drill Shank Adaptor Market
Mining Equipment
Global Automated Mining Equipment Market
Mining Equipment
Africa Mining Market
Mining Equipment
Excavator Drill Market