
 Portable Boring Machines Market | 2026-2036
Portable Boring Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Boring Machines Market Analytics
Modular component architecture is pivoting buyer preference toward field-reconfigurable boring systems that swap between horizontal and vertical orientations without full machine replacement. Climax Portable Machine & Welding Systems leverages its deep specialization in on-site machining to dominate rental channel relationships with energy sector contractors. DMG MORI sustains technology leadership through precision spindle integration drawn from its stationary machine tool heritage. SANY competes aggressively on manufacturing scale, using captive foundry capacity to compress lead times for export markets.
Portable boring machines are self-contained, transportable metalworking systems designed to restore or create precision cylindrical bores in oversized or immobilized workpieces, typically achieving tolerances of 0.001 inches through line-boring or end-facing operations. These machines deploy on construction sites, shipyards, and mining installations where workpiece transport to fixed machining centers proves economically unfeasible. Horizontal boring machines anchor current revenue as the default configuration for pipeline repair and structural steel applications, while micro boring machines represent the fastest-expanding segment driven by precision demands in geotechnical instrumentation and confined-space utility work. Deep hole boring machines command premium positioning where aerospace and defense contractors require extended reach capabilities beyond standard portable formats.
OSHA lockout/tagout standards and EPA Tier 4 Final emissions regulations shape product development trajectories for diesel-hydraulic portable boring equipment sold into North American infrastructure markets. CE marking under the EU Machinery Directive governs access to European construction fleets, with particular scrutiny applied to acoustic emission thresholds for urban worksite deployment. Stakeholders must monitor evolving battery-electric powertrain certifications as municipal procurement policies increasingly restrict internal combustion equipment from zero-emission zones.
Market Dynamics
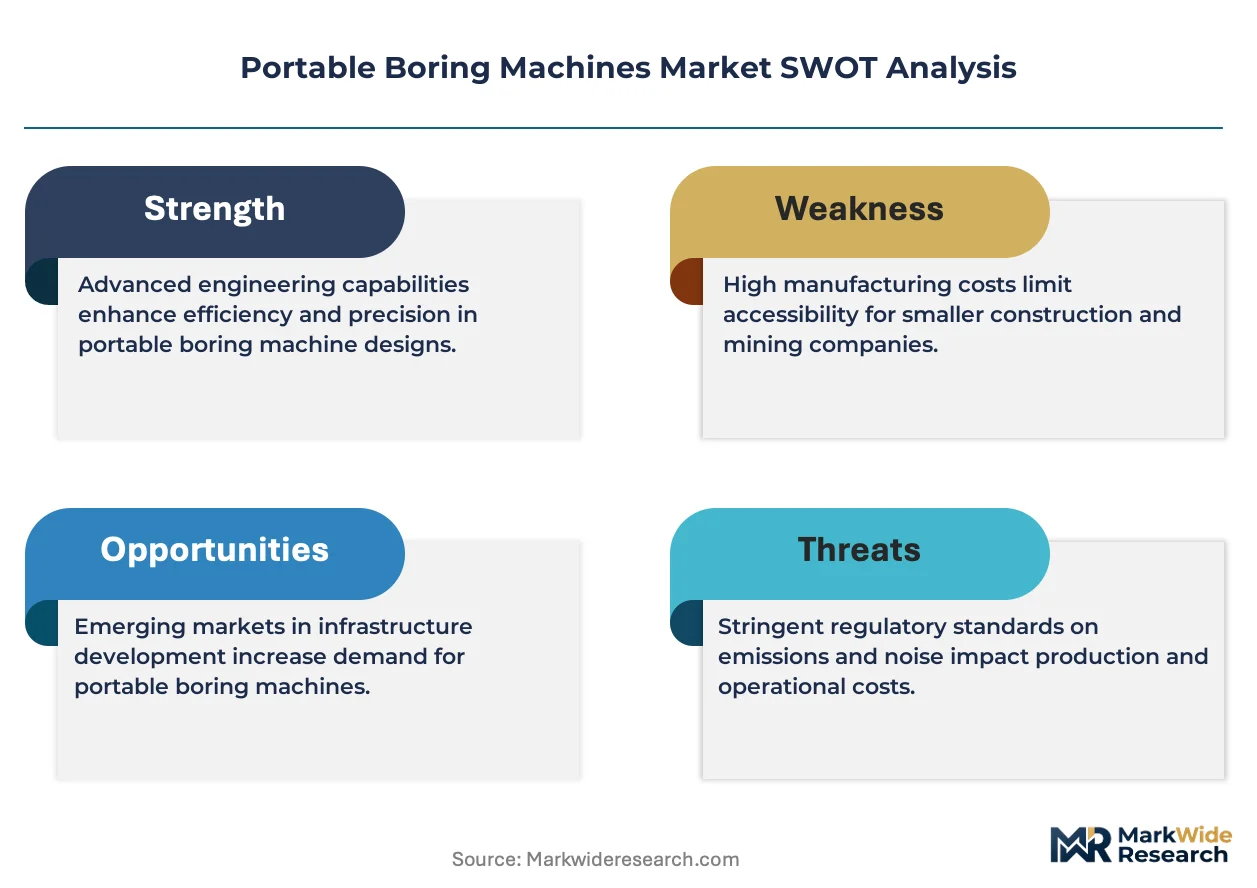
Utility network aging across industrialized economies is compressing replacement cycles for mobile boring systems while tightening emissions compliance forces diesel-hydraulic equipment redesign.
Growth Catalysts
- EPA Tier 4 Final mandates:North American infrastructure contractors face accelerated equipment turnover as legacy diesel systems lose zone access, pulling forward procurement timelines for compliant portable boring machines.
- Shale infrastructure maintenance:United States midstream operators deploy field-reconfigurable boring systems for pipeline repair, sustaining rental channel volume through episodic turnaround demand.
- Line-boring automation:Precision spindle integration from stationary machine tool heritage is migrating into portable formats, expanding addressable workpiece tolerances for on-site machining applications.
Market Restraints
- Steel input cost volatility:Foundry-grade castings and precision-machined components face commodity price swings that compress margin buffers for equipment manufacturers without captive metallurgical capacity.
- Acoustic emission thresholds:CE marking under the EU Machinery Directive imposes urban worksite noise limits that constrain diesel-hydraulic powertrain selection for European construction fleet deployment.
- Stationary machining substitution:Transport economics favor fixed CNC boring centers where workpiece mobility permits, capping portable system penetration in controlled manufacturing environments.
Strategic Opportunities
- Zero-emission zone procurement policies:Municipal restrictions on internal combustion equipment in European city centers create first-mover positioning for battery-electric portable boring platforms with certified powertrain architectures.
- Geotechnical instrumentation micro-boring:Confined-space utility work and precision subsurface sensor installation demand compact boring systems with sub-millimeter accuracy, opening premium pricing tiers.
- Horizontal-to-vertical field reconfiguration:Modular component architecture enables single-machine coverage of multiple boring orientations, reducing contractor capital intensity and expanding rental attach rates.
Industry Challenges
- On-site machining technician scarcity:Skilled operators capable of achieving 0.001-inch tolerances in uncontrolled field environments command wage premiums that inflate contractor labor costs.
- OSHA lockout/tagout certification timelines:Workplace safety training requirements for portable equipment deployment extend project mobilization schedules and complicate emergency repair response.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Boring Machines Market |
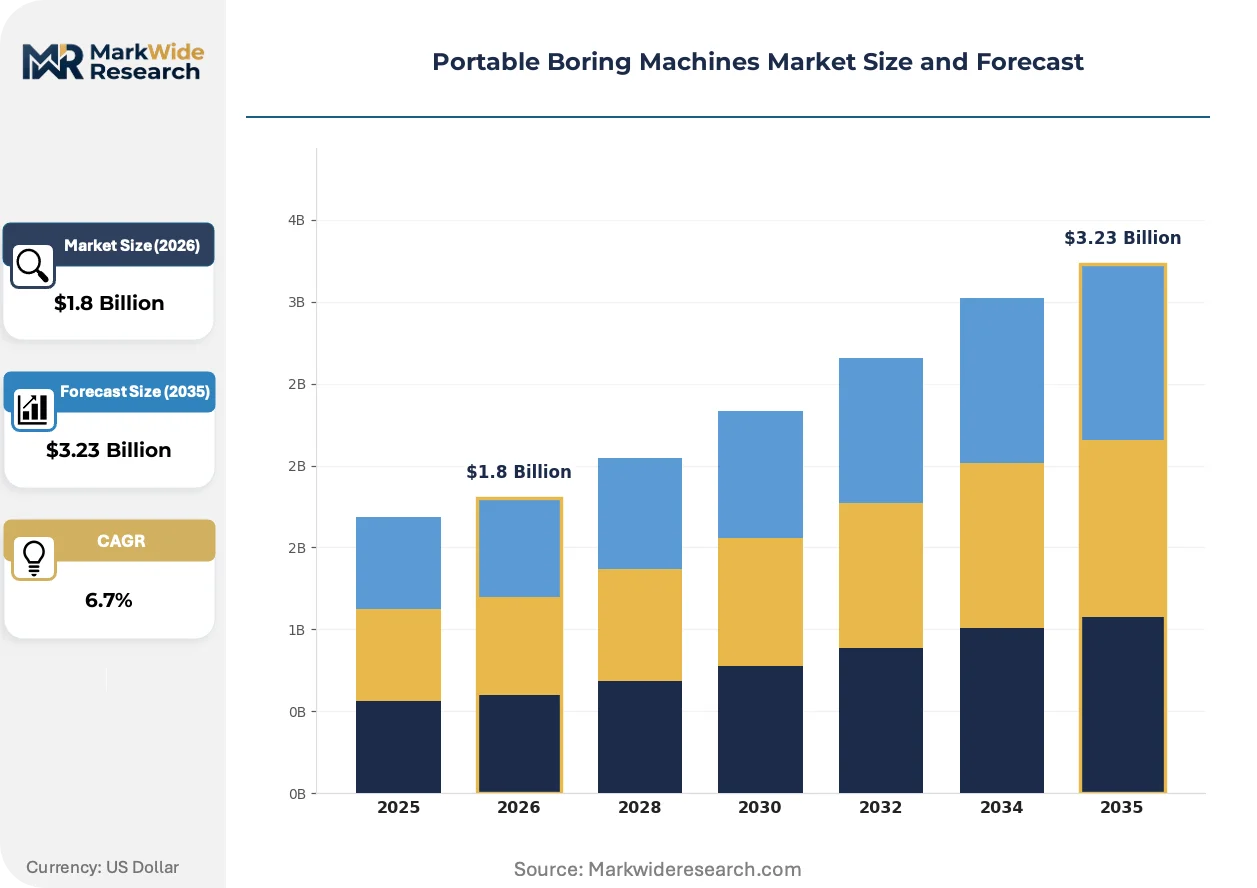
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Horizontal Boring Machines, Vertical Boring Machines, Micro Boring Machines, Deep Hole Boring Machines End User: Construction, Manufacturing, Infrastructure, Mining Technology: Electric, Hydraulic, Pneumatic, Manual Application: Geotechnical Investigation, Utility Installation, Pipeline Repair, Foundation Work |
| Companies Covered | Climax Portable Machine & Welding Systems, York Precision Machining, Prarie Dog Boring Equipment, Barbco, Robbins, Doosan Machine Tools, DMG MORI, SANY, XCMG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Boring Machines Market Evolving Landscape
Battery-electric powertrains and modular spindle architectures are actively displacing conventional diesel-hydraulic configurations while regulatory compliance windows compress product development cycles.
Brushless DC motor integration with lithium-iron-phosphate battery packs is decentralizing power generation for portable boring operations. Pipeline repair contractors in the United States are adopting these systems for indoor turnaround work where ventilation constraints prohibit diesel exhaust. This shift is decentralizing equipment deployment decisions from centralized fleet managers to individual site supervisors who specify powertrain format based on immediate worksite conditions.
REACH substance restrictions and EU Green Deal carbon border adjustments are tightening material traceability requirements for portable equipment sold into European construction markets. Manufacturers must document foundry supply chains and coating chemistries to maintain CE marking validity. German and French infrastructure contractors now prioritize equipment vendors with verified conflict-mineral-free metallurgy, compressing qualification timelines for non-compliant suppliers.
Rental channel consolidation among energy sector contractors is unbundling after-sales service from equipment procurement. Major pipeline operators in Texas and Alberta now contract maintenance separately from machine rental, forcing original equipment manufacturers to establish standalone service subsidiaries or cede margin to third-party repair networks. This unbundling is most advanced in North American shale basins where asset utilization rates justify dedicated field service teams.
Portable Boring Machines Market Segmentation
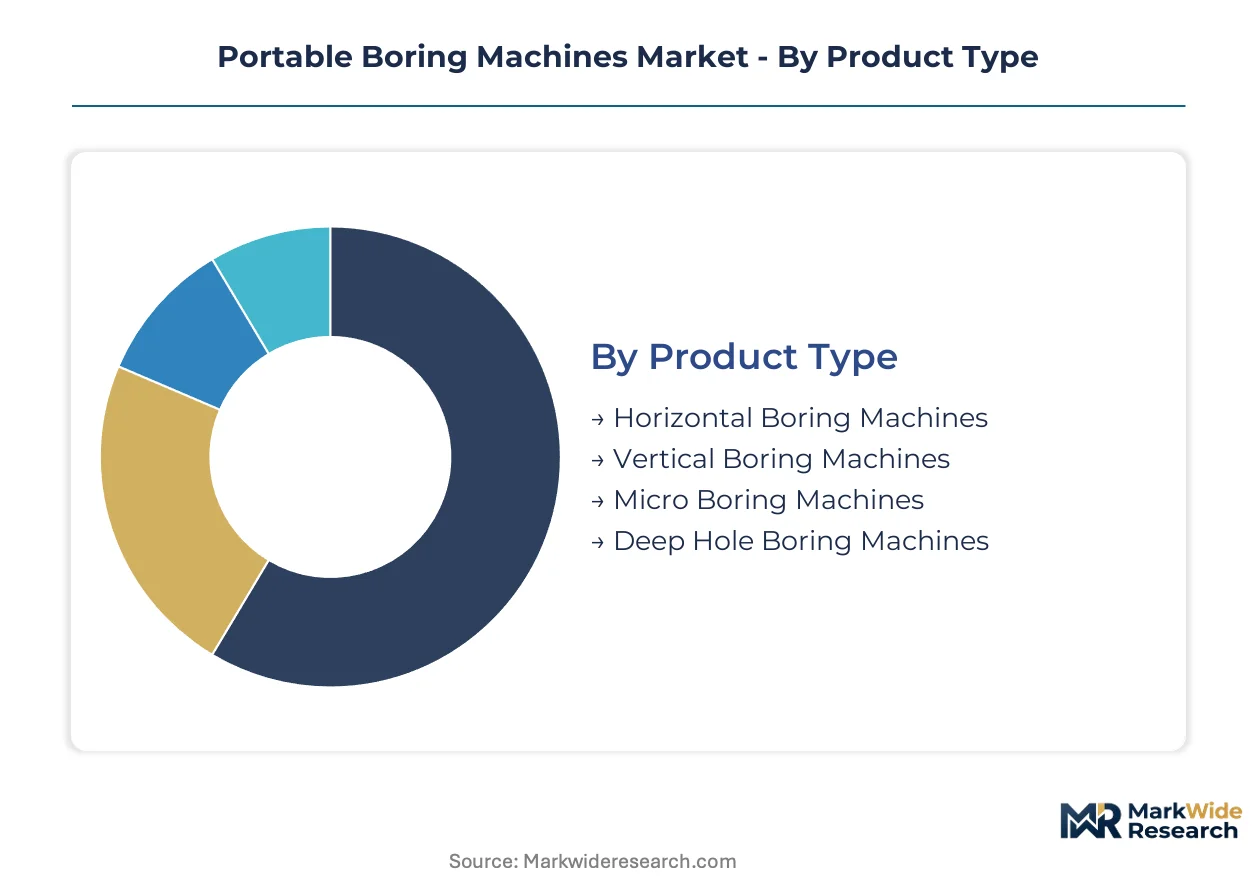
Portable boring machine procurement patterns diverge sharply across operational contexts, with powertrain format and bore orientation determining equipment selection for specific field conditions. Contractors segment their fleets by workpiece accessibility, tolerance requirements, and emissions compliance zones rather than purchasing generalized platforms.
Product Type:
Supply concentration among foundry-capable manufacturers favors horizontal configurations, while modular architecture investments are redrawing competitive boundaries between orientation-specific and field-reconfigurable systems.
- Horizontal Boring Machines:These systems deploy parallel to the ground plane for pipeline repair and structural steel applications, typically achieving 0.001-inch tolerances through line-boring operations. Demand concentrates in the United States where shale infrastructure maintenance sustains rental channel volume through episodic turnaround cycles.
- Micro Boring Machines:Compact units designed for confined-space utility work and precision subsurface sensor installation achieve sub-millimeter accuracy in geotechnical instrumentation applications. European municipal procurement policies in zero-emission zones are accelerating battery-electric configurations for urban worksite deployment.
- Vertical Boring Machines:Perpendicular-axis systems address foundation work and heavy equipment mounting surface restoration where gravity-fed cutting action improves stability.
- Deep Hole Boring Machines:Extended-reach configurations serve aerospace and defense contractors requiring bore depths beyond standard portable formats, commanding premium positioning for specialized applications.
Horizontal boring machines absorb the bulk of installed capacity; micro boring machines are expanding most quickly.
End User:
Cost tier differentiation separates capital-intensive mining deployments from price-sensitive municipal infrastructure contracts, with manufacturing applications occupying a mid-tier equipment specification band.
- Construction:General contractors deploy portable boring systems for structural steel erection and equipment foundation remediation where workpiece immobility precludes shop-based machining. United States commercial building retrofits sustain replacement demand as aging mechanical systems require precision bore restoration.
- Infrastructure:Municipal water system operators and transportation authorities specify emission-compliant powertrains for urban worksite access, with European cities restricting internal combustion equipment from zero-emission zones. Battery-electric platforms are gaining procurement preference for tunnel and bridge maintenance contracts.
- Manufacturing:Industrial plant maintenance teams utilize portable systems for in-situ machinery repair, balancing tolerance requirements against transport economics for workpiece mobility decisions.
- Mining:Open-pit and underground operations demand ruggedized hydraulic platforms for dragline bucket pin restoration and crusher frame machining in remote site conditions.
Infrastructure commands the largest equipment procurement budget; mining exhibits the steepest specification premium per unit.
Technology:
Application context determines powertrain selection, with ventilation constraints and emissions regulations forcing technology transitions faster than equipment replacement cycles would otherwise dictate.
- Hydraulic:Diesel-hydraulic systems dominate pipeline repair and mining applications where high torque requirements exceed electric motor capacity. EPA Tier 4 Final mandates are accelerating turnover of legacy diesel platforms in United States infrastructure markets.
- Electric:Brushless DC motor integration with lithium-iron-phosphate battery packs is displacing conventional powertrains for indoor turnaround work. Pipeline repair contractors in Texas and Alberta specify these systems where ventilation constraints prohibit diesel exhaust.
- Pneumatic:Compressed-air systems serve explosive atmosphere applications in petrochemical facilities where spark-free operation is mandatory.
- Manual:Hand-cranked units persist in precision geotechnical instrumentation where power source availability is unreliable and bore diameters remain small.
Hydraulic systems retain the majority of installed base; electric platforms are climbing the fastest.
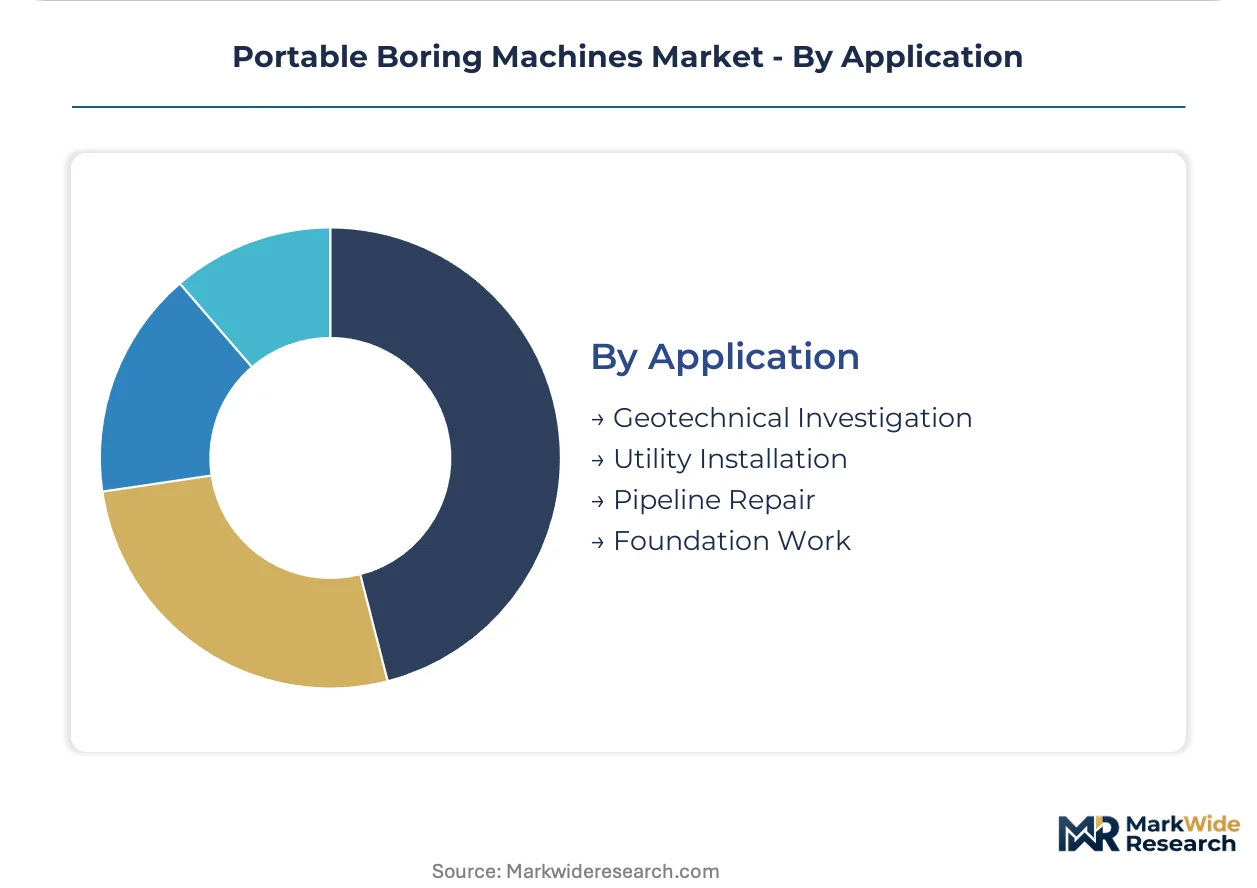
Application:
Volume concentration in pipeline repair contrasts with precision-premium positioning in geotechnical investigation, with foundation work spanning both specification tiers depending on project scale.
- Pipeline Repair:Midstream operators in United States shale basins deploy field-reconfigurable boring systems for flange facing and valve seat restoration during scheduled turnarounds. Rental channel relationships with energy sector contractors sustain episodic demand patterns.
- Geotechnical Investigation:Precision subsurface sensor installation requires compact boring systems with sub-millimeter accuracy for instrumentation boreholes in confined urban utility corridors. European municipal contracts prioritize equipment vendors with verified conflict-mineral-free metallurgy.
- Utility Installation:Water and gas distribution contractors bore horizontal passages beneath roadways and structures without surface excavation, with emissions compliance determining powertrain selection for city center work.
- Foundation Work:Heavy equipment mounting surface restoration and structural bearing seat machining demand larger bore diameters and extended reach capabilities.
Pipeline repair absorbs the bulk of equipment utilization hours; geotechnical investigation commands the fastest equipment specification evolution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized manufacturing zones in Germany and industrial corridors in Texas concentrate portable boring machine procurement, with regulatory compliance windows forcing faster equipment turnover than natural replacement cycles would dictate.
United States
Shale infrastructure maintenance in Texas and Pennsylvania sustains rental channel demand for field-reconfigurable boring systems. EPA Tier 4 Final emissions mandates accelerate diesel-hydraulic equipment replacement timelines. Houston anchors energy sector contractor procurement, with midstream operators deploying mobile systems for pipeline turnaround work.
Germany
Automotive and heavy machinery plant maintenance drives precision spindle demand for in-situ machinery repair. CE marking under the EU Machinery Directive imposes strict acoustic emission thresholds for urban worksite deployment. Stuttgart and Munich industrial clusters prioritize equipment vendors with verified conflict-mineral-free metallurgy.
China
State-led infrastructure investment in high-speed rail and municipal water systems expands mobile boring equipment procurement. GB standards and MIIT equipment certification requirements govern domestic market access. Yangtze River Delta manufacturing bases concentrate foundry-capable producers serving export markets.
Japan
Shipyard maintenance and precision manufacturing sustain demand for compact boring systems with sub-millimeter accuracy. METI industrial equipment efficiency standards shape powertrain selection for domestic contractors. Nagoya and Osaka industrial corridors concentrate specialized machining service providers.
India
Rapid urbanization and metro rail construction drive utility installation boring equipment demand. BIS certification requirements and PLI scheme incentives for capital goods manufacturing reshape supplier qualification. Maharashtra and Gujarat industrial zones concentrate infrastructure contractor fleets.
Portable Boring Machines Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered equipment specifications. The vendor base spans captive foundry operators, precision spindle integrators, and rental channel specialists. Three archetypes dominate: scale-driven manufacturers with metallurgical backward integration, technology licensors leveraging stationary machine tool heritage, and field-service-oriented rental specialists. Competitive moves concentrate on modular architecture investments and standalone service subsidiary formation.
Among North American specialists, Climax Portable Machine & Welding Systems exemplifies the field-service-oriented archetype through its on-site machining focus. DMG MORI represents technology licensors drawing precision capabilities from stationary machine tool heritage. SANY anchors the scale-driven tier with manufacturing breadth and captive supply chain control. These three occupy distinct competitive positions without direct overlap in core capability emphasis.
| Leading Market Players |
|---|
| Climax Portable Machine & Welding Systems |
| York Precision Machining |
| Prarie Dog Boring Equipment |
| Barbco |
| Robbins |
| Doosan Machine Tools |
| DMG MORI |
| SANY |
| XCMG |
| Others |
Value Network & Pricing Analysis
EPA Tier 4 Final emissions mandates gate both qualified supply and premium-tier pricing access for portable boring machines, as compliance investments stratify manufacturers into certified and non-certified tiers with divergent pricing power. Foundry-capable producers with captive metallurgical capacity command price premiums while smaller fabricators face margin compression from certification costs.
Pricing Analysis
Cost compression in economy-tier hydraulic systems accelerates as steel input volatility erodes margin buffers for non-integrated manufacturers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from rental channel consolidation unbundling maintenance from equipment procurement. Municipal infrastructure contractors exhibit highest price sensitivity; aerospace and defense contractors show lowest sensitivity due to tolerance requirements.
Supply Chain Analysis
Regional distribution centers in Houston, Stuttgart, and Shanghai anchor hub-and-spoke patterns for spare parts and modular component fulfillment. Manufacturing concentrates in Germany, China, and the United States, with foundry-grade castings drawing from captive and merchant foundry networks. Supply chain risk centers on single-source vulnerability for precision spindle assemblies sourced from stationary machine tool heritage producers. Distribution runs through rental channel specialists and OEM-direct sales for large mining and energy contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where EPA Tier 4 Final certification creates a barrier-to-entry moat protecting incumbent manufacturers with established emissions-compliant platforms.
For Market Incumbents: Lock in rental channel relationships with energy sector contractors through standalone service subsidiary formation as maintenance unbundling accelerates. Deepen backward integration into foundry operations to defend margin position against steel input volatility. Battery-electric platform R&D represents the critical capability lever for zero-emission zone access. For New Entrants and Emerging Players: Capture geotechnical instrumentation micro-boring demand in European municipal markets where conflict-mineral-free metallurgy requirements compress qualification timelines for established suppliers. Battery-electric configurations for confined-space utility work offer the most penetrable white-space. Channel partnership with specialized machining service providers enables faster qualification than direct OEM competition. For Investors and Strategic Acquirers: First-mover battery-electric certifications from major German automotive plant maintenance contractors signal that premium positioning is shifting toward emission-compliant platforms. Long-term viability favors scale-driven manufacturers with captive foundry capacity or technology licensors with precision spindle heritage. Watch for standalone service subsidiary formation announcements as the leading indicator of rental channel consolidation maturity.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Architecture Investment | Field-reconfigurable systems reduce contractor capital intensity and expand rental attach rates across pipeline repair. |
| Battery-Electric Platform Certification | Zero-emission zone procurement policies in European city centers create first-mover positioning for compliant powertrains. |
| Standalone Service Subsidiary Formation | Rental channel unbundling in North American shale basins forces OEMs to capture maintenance margin directly. |
| Conflict-Mineral-Free Metallurgy Verification | EU Green Deal supply chain requirements compress qualification timelines for non-compliant foundry suppliers. |
| Precision Spindle Integration Partnership | Stationary machine tool heritage capabilities migrate into portable formats for sub-millimeter tolerance applications. |
Research Methodology
Independent corroboration across equipment procurement directors at pipeline operators, maintenance managers at municipal water utilities, and rental channel specialists underwrites the qualitative findings in this analysis. Primary interviews with plant engineers, aftermarket service heads, and OEM procurement teams combined with secondary validation from EPA regulatory filings, EIA infrastructure investment data, and EU Machinery Directive compliance databases. Bottom-up equipment shipment analysis and top-down infrastructure spending triangulation anchored market sizing.
Rate-of-change decomposition across product type, powertrain technology, end-user vertical, and regional regulatory cluster shaped the analytical framework throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, emissions compliance window timing, and rental channel volume elasticity. Shale infrastructure maintenance schedules and municipal water system upgrade pipelines served as industry-specific demand inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery-electric powertrain certification timelines and steel commodity price trajectories. Outputs reflect documented assumptions regarding regulatory enforcement consistency and contractor capital expenditure patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Digital Cutting Machine Market
Tools
Edge Bending Machine Market
Tools
Grinding Machines Market
Tools
Pruning Saw Market
Tools
Crimping Tool Market
Tools
Masonry Cleaners Market
Tools
Europe Paint Spray Guns Market
Tools
Water Pump Pliers Market
Tools
Vertical Milling Machine Market
Tools
Construction Anchors Market
Tools
Self-Clinching Fasteners Market
Tools
Cutting Tools Market
Tools
Tile Cutter Market
Tools
High-Speed Steel Metal Cutting Tools Market
Tools
Thread Milling Machine Market
Tools
Orbital Sanders Market