
 Mine Hoisting Systems Market | 2026-2036
Mine Hoisting Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Mine Hoisting Systems Market Insights
Modular shaft hoisting packages is rebalancing buyer preference away from standalone component procurement. ABB Ltd. leverages its integrated drives portfolio to bundle electrical and mechanical subsystems for greenfield projects. SIEMAG TECBERG Group anchors its position through deep specialization in friction winders for ultra-deep shafts. CITIC Heavy Industries Co., Ltd. competes on manufacturing scale, supplying complete hoist assemblies to state-backed mining operations across Asia.
Mine hoisting systems are electromechanical installations engineered to raise and lower personnel, ore, and equipment through vertical or inclined shafts, typically rated for loads exceeding 50 tonnes and operating depths beyond 3,000 meters in hard-rock conditions. Their primary purpose centers on enabling safe, continuous material transport from underground workings to surface processing facilities. Electric winders dominate capital expenditure across deep-shaft metal mining, while hydraulic technology captures retrofit demand in aging coal operations where shaft geometry limits electrical infrastructure upgrades. Underground elevators represent the fastest-growing product configuration as mechanized mining methods drive deeper ore body access.
ISO 19426 safety standards for mine hoists, China's GB/T 10599 conveyor specifications, and South Africa's Mine Health and Safety Act collectively define compliance thresholds for new installations and mandatory equipment overhauls. These frameworks elevate capital intensity for suppliers while creating barriers for unqualified entrants lacking certified design capabilities. Stakeholders must weigh the trade-off between incremental modernization of legacy mechanical winders and full-system electrification when planning decade-long asset deployments.
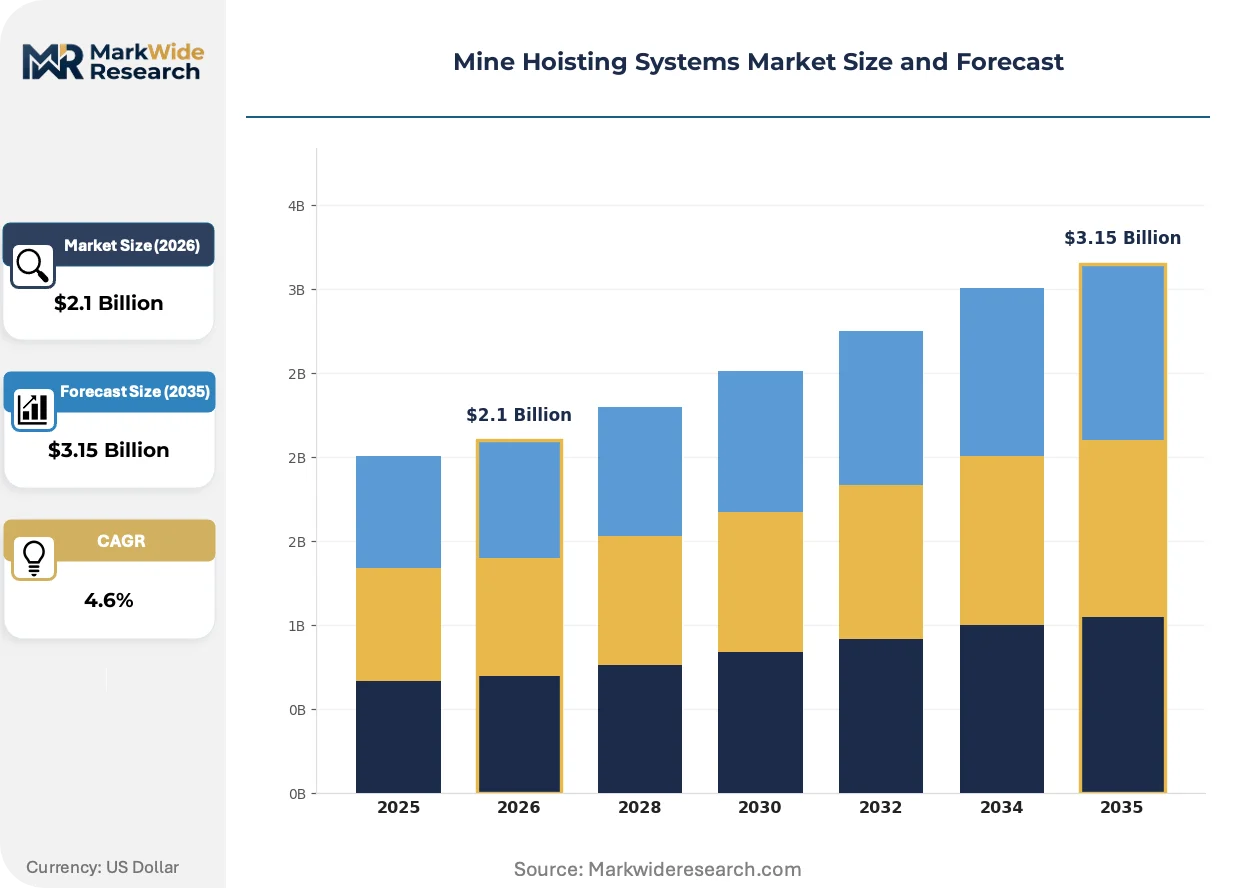
Market Dynamics
Stricter mine safety mandates from regulators in China, Australia, and South Africa are accelerating replacement cycles for aging shaft equipment while underground metal mining operations expand procurement of integrated hoisting packages.
Growth Catalysts
- Regulatory Replacement Cycles:China's GB/T 10599 conveyor specifications and South Africa's Mine Health and Safety Act mandate equipment overhauls that force capital deployment toward certified systems.
- Ultra-Deep Shaft Expansion:Mechanized mining methods in Chile's copper belt and Western Australia's iron ore districts drive demand for friction winders rated beyond 3,000 meters depth.
- Electrification Retrofits:Hydraulic-to-electric conversions in aging coal shafts where geometry permits infrastructure upgrades unlock secondary demand from stranded assets.
Market Restraints
- Capital Intensity Barriers:Full-system electrification requires decade-long asset deployment horizons that strain balance sheets at mid-tier mining operators.
- Specialized Supplier Concentration:Certified design capabilities for ISO 19426 compliance concentrate among established European and Asian manufacturers, limiting qualified entrants.
- Input Cost Volatility:Copper winding materials and high-grade steel forgings for drum assemblies expose project budgets to commodity price swings.
Strategic Opportunities
- Modular Package Adoption:Bundled electrical-mechanical subsystems displace standalone component procurement in greenfield projects across Indonesia and Mongolia.
- Underground Elevator Expansion:Personnel transport systems represent the fastest-growing product configuration as ore bodies deepen beyond conventional skip limits.
- Digital Monitoring Convergence:Integration of condition-based maintenance software with drive control systems creates recurring revenue streams through predictive service contracts.
Industry Challenges
- Certification Timeline Compression:ISO 19426 safety standard compliance testing extends lead times for custom shaft designs, squeezing project delivery windows.
- Electromechanical Integration Complexity:Legacy mechanical winders resist seamless retrofit with modern variable-frequency drives, requiring engineered workarounds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mine Hoisting Systems Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyors, Shaft Hoists, Underground Elevators, Winders Technology: Hydraulic, Electric, Pneumatic, Mechanical End User: Coal Mining, Metal Mining, Mineral Extraction, Quarrying Installation Type: Onshore, Offshore, Fixed, Mobile |
| Companies Covered | ABB Ltd., FLSmidth & Co. A/S, CITIC Heavy Industries Co., Ltd., SIEMAG TECBERG Group, Konecranes Plc, Columbus McKinnon Corporation, Ingersoll Rand Inc., Hepburn Engineering Inc., INCO Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mine Hoisting Systems Market Trends and Innovations
Digitalization of shaft operations is compressing maintenance cycles and enabling predictive intervention models that reduce unplanned downtime in deep mining environments.
Integrated drive-mechanical packages are unifying procurement specifications across greenfield projects. Mining operators in Western Australia's Pilbara region specify bundled electrical and mechanical subsystems from single-source suppliers to compress commissioning timelines. This convergence is unifying vendor accountability and reducing interface risk between formerly separate component purchases.
REACH and RoHS substance restrictions in the European Union are tightening material compliance for electrical insulation and bearing lubricants used in hoist winders. Manufacturers serving EU-bound projects must reformulate component specifications or risk exclusion from publicly tendered contracts. Underground metal mining operations in Sweden and Finland face the steepest compliance cost adjustments.
Buyer concentration among tier-one mining houses is consolidating specification authority and compressing supplier margins. Large operators in Chile's copper belt now mandate outcome-based performance guarantees rather than equipment-only purchases, transferring operational risk to vendors. This shift is most visible in long-term service agreements for friction winder maintenance at state-backed operations.
Mine Hoisting Systems Market Segmentation
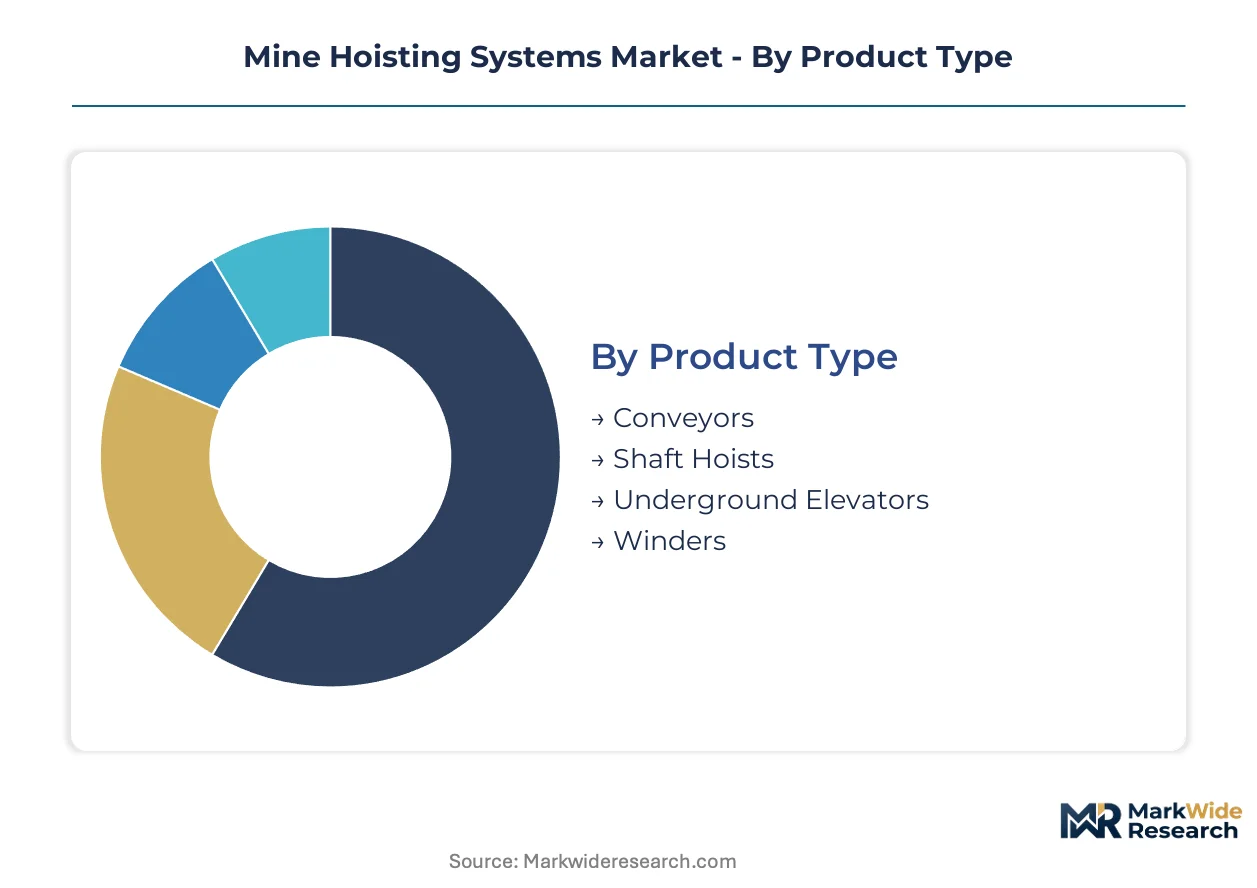
Segmentation in mine hoisting systems reveals how capital allocation splits between replacement cycles and greenfield expansion. Procurement patterns differ sharply between deep-shaft metal operations upgrading aging winders and coal producers pursuing hydraulic-to-electric retrofits.
Product Type:
Replacement cycles for aging shaft infrastructure are redirecting procurement toward integrated packages rather than standalone component purchases.
- Winders:Drum and friction configurations dominate capital deployment in ultra-deep metal mining, with drum winders rated beyond 3,000 meters depth anchoring procurement in Chile's copper belt. Electric drive integration with mechanical subsystems is compressing commissioning timelines for greenfield projects.
- Underground Elevators:Personnel transport systems are expanding most quickly as mechanized mining methods drive deeper ore body access beyond conventional skip limits. Western Australia's iron ore districts specify these for vertical shaft depths where skip haulage becomes impractical.
- Shaft Hoists:Skip and cage configurations serve mid-depth operations in South African platinum and gold mines.
- Conveyors:Continuous belt systems handle inclined shaft applications where vertical hoisting is uneconomical.
Winders sit at the top of the volume ranking, with underground elevators climbing the fastest.
Technology:
Cost tier differentiation separates mature hydraulic installations from premium electric systems requiring full infrastructure overhaul.
- Electric:Variable-frequency drive systems capture greenfield capital in deep-shaft metal mining, with ABB and SIEMAG TECBERG bundling electrical-mechanical subsystems. China's state-backed copper operations in Jiangxi province mandate electric configurations for new shafts exceeding 2,500 meters.
- Hydraulic:Legacy installations persist in aging coal shafts where geometry constrains electrical infrastructure upgrades. Poland's Silesian basin and Ukraine's Donetsk region retain hydraulic winders for retrofit cycles.
- Mechanical:Direct-drive configurations serve shallow quarrying operations with minimal automation requirements.
- Pneumatic:Compressed-air systems occupy niche applications in gassy mine environments where electrical ignition risks prohibit standard drives.
Electric technology commands the premium tier by installed value, while hydraulic retains the broadest installed base.
End User:
Application intensity varies with ore body depth, regulatory pressure, and mechanization levels across extraction categories.
- Metal Mining:Copper, gold, and platinum operations in Chile, South Africa, and Western Australia drive demand for friction winders rated at extreme depths. Mechanized block caving methods require continuous hoisting capacity that strains legacy equipment.
- Coal Mining:Underground thermal and metallurgical coal producers in China, Poland, and Indonesia balance replacement cycles against mine closure timelines. Stricter ventilation and safety mandates are accelerating hydraulic-to-electric conversions where shaft geometry permits.
- Mineral Extraction:Potash, salt, and diamond operations in Canada, Russia, and Botswana deploy specialized corrosion-resistant configurations.
- Quarrying:Surface and shallow underground limestone, granite, and aggregate producers specify lower-capacity drum winders with shorter design lives.
Metal mining generates the highest equipment value per installation, with coal mining presenting the largest addressable fleet for replacement.
Installation Type:
Supply concentration favors fixed onshore configurations, while mobility requirements create specification complexity for distributed operations.
- Fixed:Permanent shaft installations anchor procurement volumes, with concrete-headframe configurations dominating deep mining in Chile, Australia, and South Africa. These installations require decade-long asset planning and integrated drive-mechanical packages.
- Onshore:Land-based shaft operations encompass virtually all deep mining applications, from Zambia's Copperbelt to Sweden's Kiruna iron ore mine.
- Mobile:Portable skid-mounted winders serve exploration shafts and small-scale operations in Mongolia, Kazakhstan, and Peru's informal mining sector.
- Offshore:Subsea mining prototypes and experimental seabed extraction systems represent pre-commercial demand with unproven hoisting architectures.
Fixed installations dominate current procurement value, while mobile configurations address fleet flexibility needs in frontier mining jurisdictions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep-shaft mining traditions in South Africa established the foundational engineering standards for ultra-deep hoisting systems. Chile and Australia subsequently scaled friction winder deployments for copper and iron ore extraction. China now drives replacement volume through state-mandated safety overhauls.
Chile
Copper belt mechanization sustains procurement of friction winders rated beyond 3,000 meters depth. The national mining regulator enforces progressive shaft safety inspections that accelerate equipment refresh cycles. State-owned Codelco operations in the Atacama Desert specify integrated electrical-mechanical packages for new greenfield shafts.
Australia
Western Australia's Pilbara iron ore districts require continuous hoisting capacity for mechanized block caving methods. The country's national mining safety regulator mandates equipment certification under ISO 19426 standards for all new installations. BHP and Rio Tinto operations near Perth anchor demand for bundled drive-mechanical subsystems.
South Africa
Platinum and gold reef mining at extreme depths sustains replacement demand for aging drum winders. The Mine Health and Safety Act mandates mandatory equipment overhauls that force capital deployment toward certified systems. Anglo American Platinum operations in the Bushveld Complex drive specification authority for friction winder performance guarantees.
China
State-backed copper and coal operations in Jiangxi province mandate electric configurations for new shafts exceeding 2,500 meters. GB/T 10599 conveyor specifications and dual carbon goals accelerate hydraulic-to-electric conversions. CITIC Heavy Industries supplies complete hoist assemblies to state-owned mining enterprises across the country's central mining belt.
Poland
Aging coal shafts in the Silesian basin retain hydraulic winders where geometry constrains electrical infrastructure upgrades. The country's national mining regulator enforces ventilation and safety mandates that accelerate selective retrofit cycles. Kompania Węglowa operations near Katowice balance replacement investments against mine closure timelines.
Mine Hoisting Systems Market Competitive Landscape
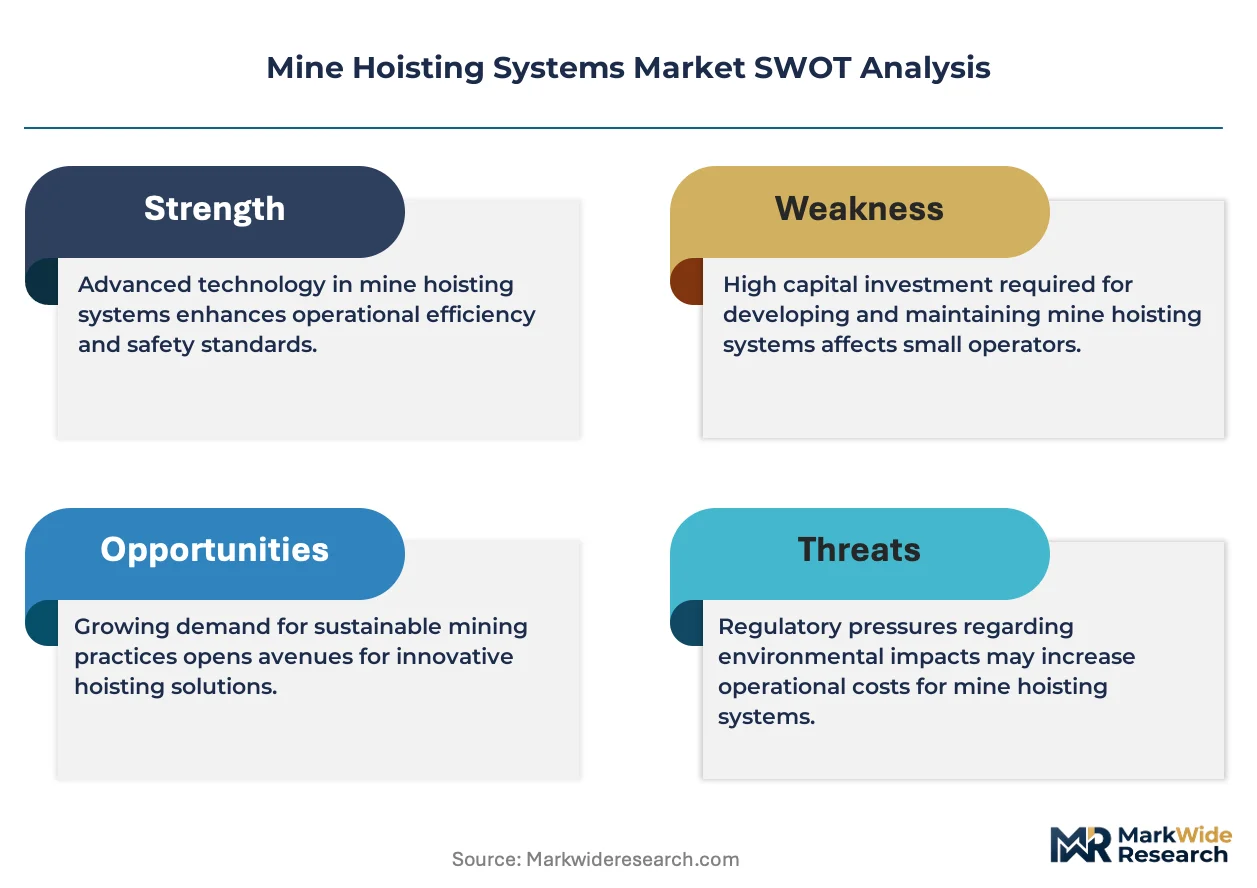
The competitive structure tilts toward integrated system bundlers over standalone component suppliers. European and Asian manufacturers concentrate certified design capabilities for ISO 19426 compliance, creating qualification barriers for unqualified entrants. Two strategic archetypes dominate: electrical drive specialists bundling mechanical subsystems, and deep-shaft friction winder specialists. Capacity expansion and strategic partnerships constitute the dominant competitive moves as operators seek to compress commissioning timelines.
Among diversified industrial conglomerates, ABB Ltd. and CITIC Heavy Industries Co., Ltd. exemplify scale-driven integration archetypes, while SIEMAG TECBERG Group occupies a position representing deep specialization in ultra-deep shaft applications. These three entities anchor the vendor landscape across distinct competitive vectors.
| Leading Market Players |
|---|
| ABB Ltd. |
| FLSmidth & Co. A/S |
| CITIC Heavy Industries Co., Ltd. |
| SIEMAG TECBERG Group |
| Konecranes Plc |
| Columbus McKinnon Corporation |
| Ingersoll Rand Inc. |
| Hepburn Engineering Inc. |
| INCO Engineering |
| Others |
Pricing and Supply Chain Analysis
Backward integration into copper winding and high-grade steel forging operations anchors both supply security and margin control for established European and Asian hoist manufacturers. CITIC Heavy Industries leverages captive production of drum assemblies to undercut modular competitors on state-backed contracts in China's Jiangxi province, while ABB Ltd. sources variable-frequency drives from consolidated European semiconductor foundries to protect premium pricing on integrated packages.
Pricing Analysis
Project-based contracting with performance-guarantee clauses dominates procurement for friction winders and underground elevators across Chile's copper belt and Western Australia's Pilbara region. Certification grade under ISO 19426 and after-sales service bundling separate premium integrated packages from standard mechanical-only configurations. Cost compression in mid-tier drum winders is intensifying because Chinese state-owned enterprises are consolidating specification authority around domestic suppliers. Junior mining operators in Mongolia and Kazakhstan exhibit the highest price sensitivity, whereas tier-one houses like BHP and Rio Tinto prioritize outcome-based accountability over unit cost.
Supply Chain Analysis
Freight costs for oversize drum assemblies and headframe components concentrate manufacturing proximity to end-use markets in China, Germany, and South Africa. Copper winding materials, high-grade steel forgings, and specialized bearings draw from Chilean mining output, Swedish specialty steel mills, and Japanese precision component suppliers. Single-source vulnerability in semiconductor-based drive controls creates exposure to foundry capacity constraints. Distribution runs through direct OEM relationships with tier-one mining houses and regional equipment distributors serving mid-tier operators in frontier jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as mechanized block caving methods at extreme depths force replacement of legacy hydraulic winders with certified electric configurations. Buyers now mandate integrated electrical-mechanical packages with decade-long performance guarantees, elevating specification thresholds for qualified suppliers.
For Market Incumbents: Acquire certified design capabilities for ISO 19426 compliance testing to compress lead times on custom shaft configurations. Incumbent suppliers must defend against Chinese state-backed manufacturers by embedding predictive maintenance software into drive control systems, creating recurring revenue streams that offset margin pressure from bundled procurement. Capacity addition in Indonesia and Mongolia addresses fleet flexibility demand from frontier mining operators. For New Entrants and Emerging Players: Digital-channel routes through mining equipment leasing platforms offer lower-friction access to mid-tier operators than direct OEM competition. New entrants should target mobile skid-mounted winders for exploration shafts in Peru's informal mining sector and Kazakhstan's distributed operations, where specification authority fragments across small-scale contractors. A rental-to-own go-to-market angle bypasses capital intensity barriers that strain balance sheets at junior mining houses. For Investors and Strategic Acquirers: Roll-up economics work for regional service specialists with certified maintenance capabilities because ISO 19426 compliance testing creates natural fragmentation in aftermarket support. Long-term viability hinges on exposure to ultra-deep shaft expansion in Chile and Western Australia rather than aging coal replacement cycles in Eastern Europe. Watch Codelco and BHP procurement announcements for integrated package adoption rates as the inflection indicator for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Critical Components | Captive supply of copper windings and steel forgings protects margins against commodity volatility from Chilean and Swedish suppliers. |
| Predictive Maintenance Software Integration | Condition-based monitoring contracts with Anglo American Platinum create recurring revenue beyond equipment-only sales. |
| Certification Investment for ISO 19426 Compliance | Testing capacity expansion compresses lead times for custom shaft designs demanded by Australia's national mining safety regulator. |
| Geographic Expansion into Frontier Mining Jurisdictions | Mobile winder deployments in Mongolia and Peru address fleet flexibility needs outside consolidated tier-one procurement. |
| Long-term Service Agreement Structuring | Outcome-based performance guarantees with Codelco transfer operational risk and lock out component-only competitors. |
Research Methodology
Bottom-up mining operator modeling reconciled against top-down supplier shipment tracking forms the analytical core of this study. Primary interviews with mine maintenance directors, plant engineers at state-owned copper operations, OEM procurement teams, and aftermarket service heads informed capacity utilization and replacement cycle assumptions. Secondary validation drew from customs records for hoist component trade flows, SEC filings of diversified industrial conglomerates, ISO certification databases, and national mining safety regulator enforcement disclosures. Triangulation across these sources reconciles divergent signals on greenfield capital deployment timing.
Historical trendline analysis of shaft depth expansion and mechanization adoption patterns anchored the projection framework across the modeling period. Segmentation dimensions modeled include product type configuration, technology tier, end-use extraction category, and regional regulatory cluster. CAGRs were derived from equipment procurement pipelines disclosed in mining operator capex guidance and supplier order backlogs, with specific weighting for electrification retrofit intensity in China's coal belt and friction winder deployment rates in Chile's Atacama Desert.
Regulatory enforcement delays, commodity price collapse triggering project deferrals, and breakthroughs in autonomous haulage systems that reduce vertical shaft dependency are the dominant revision risks to installed base forecasts. Stakeholders should weight assumptions against their own operating context and regional exposure to state-backed procurement consolidation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Kazakhstan Mining Market
Mining Equipment
Mine Scaler Market
Mining Equipment
Rotary Drilling Rig Market
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Crawler Drilling Machine Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Barite Crusher Market
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Mining Machinery Market
Mining Equipment
Mining Collectors Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Rock Drill Shank Adaptor Market