
 Saudi Arabia Prefab Wood Buildings Market | 2026-2036
Saudi Arabia Prefab Wood Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Prefab Wood Buildings Market Analytics
Multi-source procurement of engineered timber assemblies is consolidating as general contractors diversify away from sole-source concrete suppliers. Kirby Building Systems leverages its regional fabrication footprint to anchor large-scale commercial projects. TSSC competes through integrated panel manufacturing that controls material flow from lamination to site delivery. Red Sea International positions its modular offering to align with giga-project timelines requiring accelerated enclosure schedules.
Prefab wood buildings are factory-manufactured structures using cross-laminated timber, glulam beams, and precision-cut dimensional lumber engineered for seismic and thermal performance, then transported to site for rapid assembly. These systems serve Saudi Arabia's need for faster project delivery amid labor constraints and extreme climate exposure. Modular homes and timber frame structures dominate current volume, with custom wood designs capturing premium margin pools in luxury hospitality and branded residential schemes. Green building technology is gaining specification share as developers pursue environmental certification for NEOM and Red Sea Project assets.
SFDA and the Saudi Building Code govern structural material approvals and fire safety ratings for timber systems in habitable construction. MOHAP standards influence healthcare facility specifications where prefab wood is emerging in administrative and staff housing components. Stakeholders must monitor evolving municipal permitting timelines across Riyadh, Jeddah, and Dammam as local authorities build technical capacity to review non-conventional structural submissions.
Market Dynamics
The Saudi Arabia Prefab Wood Buildings Market is experiencing structural compression between giga-project acceleration timelines and limited domestic engineered timber fabrication capacity. This tension forces procurement models toward multi-source panel supply and drives specification of pre-certified modular systems that bypass lengthy municipal permitting queues.
Growth Catalysts
- NEOM linear city construction zones:The megaproject's phased delivery requirements favor factory-built timber modules that compress enclosure schedules by 40-60% versus cast-in-place concrete. Hospitality and residential clusters along the coast specify cross-laminated timber for rapid vertical assembly.
- Saudi Building Code energy efficiency provisions:Updated thermal performance mandates for commercial and residential envelopes accelerate specification of engineered wood assemblies with integrated insulation. Compliance-driven retrofit activity in Riyadh's existing stock adds incremental volume.
- Cross-laminated timber (CLT) fabrication advances:Regional producers now offer fire-rated CLT panels meeting SFDA structural approval standards. This material availability reduces reliance on European imports and compresses lead times for Red Sea Project developers.
Market Restraints
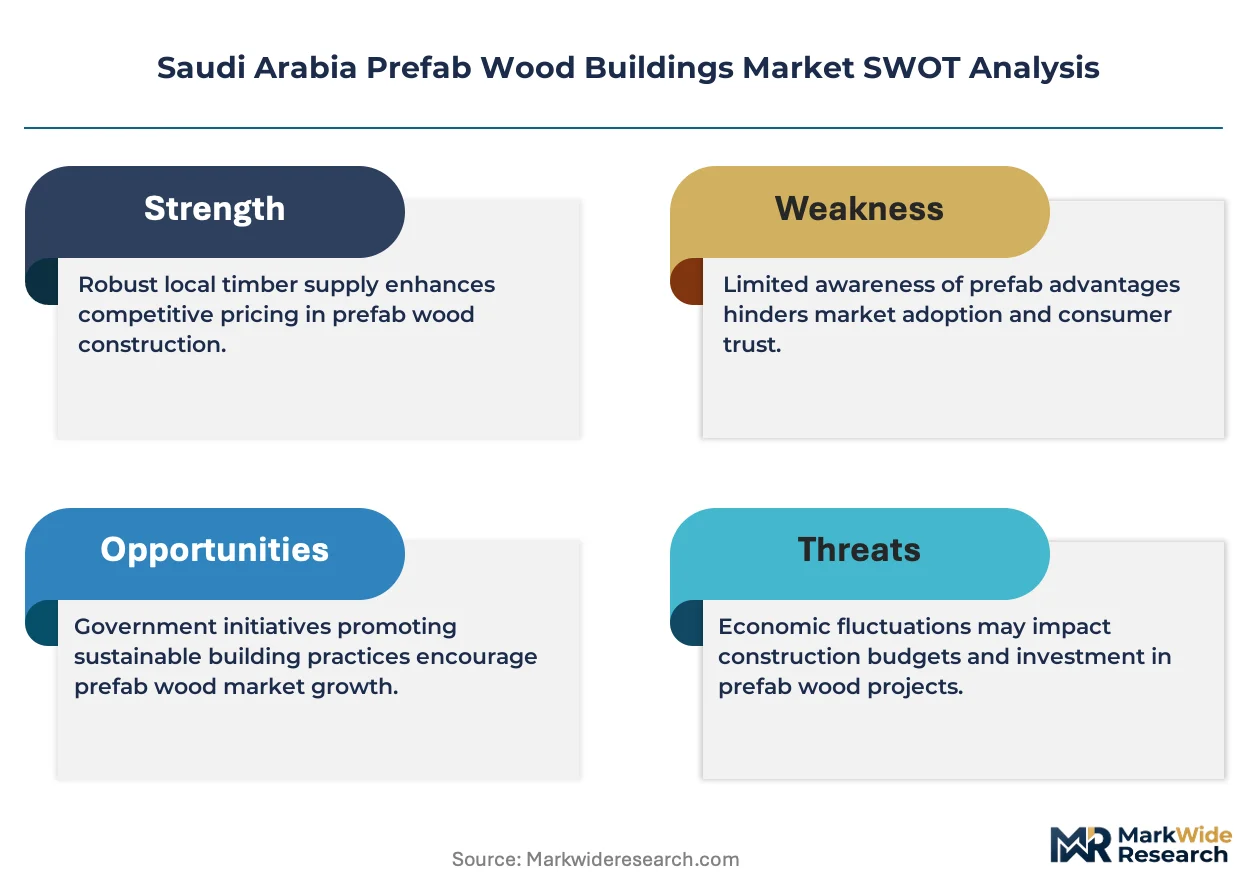
- Imported glulam beam cost volatility:European spruce and Nordic pine supply fluctuations expose Saudi contractors to 15-25% input price swings. Currency exposure against the euro amplifies budget uncertainty for fixed-price giga-project contracts.
- Single-source CLT panel concentration:Domestic fabrication capacity concentrates in Dammam industrial corridor facilities. Project delays cascade when fire-certification backlogs hit these limited production lines.
- Concrete substitution economics:Ready-mix concrete maintains 30-40% installed cost advantage for low-rise structures. Value engineering exercises frequently revert wood specifications to conventional systems unless sustainability certification mandates intervene.
Strategic Opportunities
- Asir Province mountain hospitality:Cooler highland climates suit timber construction aesthetically and thermally. Boutique resort developers seek prefabricated chalet systems that minimize on-site labor in remote terrain.
- Saudi Green Building Forum certification pathways:Emerging local equivalents to LEED and BREEAM create regulatory tailwinds for mass timber in commercial specifications. Early-mover developers capture brand differentiation in Riyadh's premium office segment.
- Digital fabrication-to-site logistics integration:BIM-to-CNC workflow convergence enables just-in-time panel delivery that reduces site inventory requirements. General contractors with captive logistics capabilities capture schedule risk premiums.
Industry Challenges
- Fire engineer certification scarcity:SFDA requires project-specific fire safety submissions for timber structures above two stories. Qualified local consultants command 3-4x standard structural engineering rates, compressing project margins.
- Municipal permitting timeline variability:Riyadh, Jeddah, and Dammam building departments exhibit inconsistent technical capacity to review non-conventional structural systems. Submission rejections trigger 8-14 week resubmission cycles that threaten giga-project milestones.
- Moisture management during summer transport:Engineered timber panels require climate-controlled flatbed logistics across 45°C+ interior routes. Inadequate protective protocols cause delamination claims that sour contractor-specifier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Prefab Wood Buildings Market |
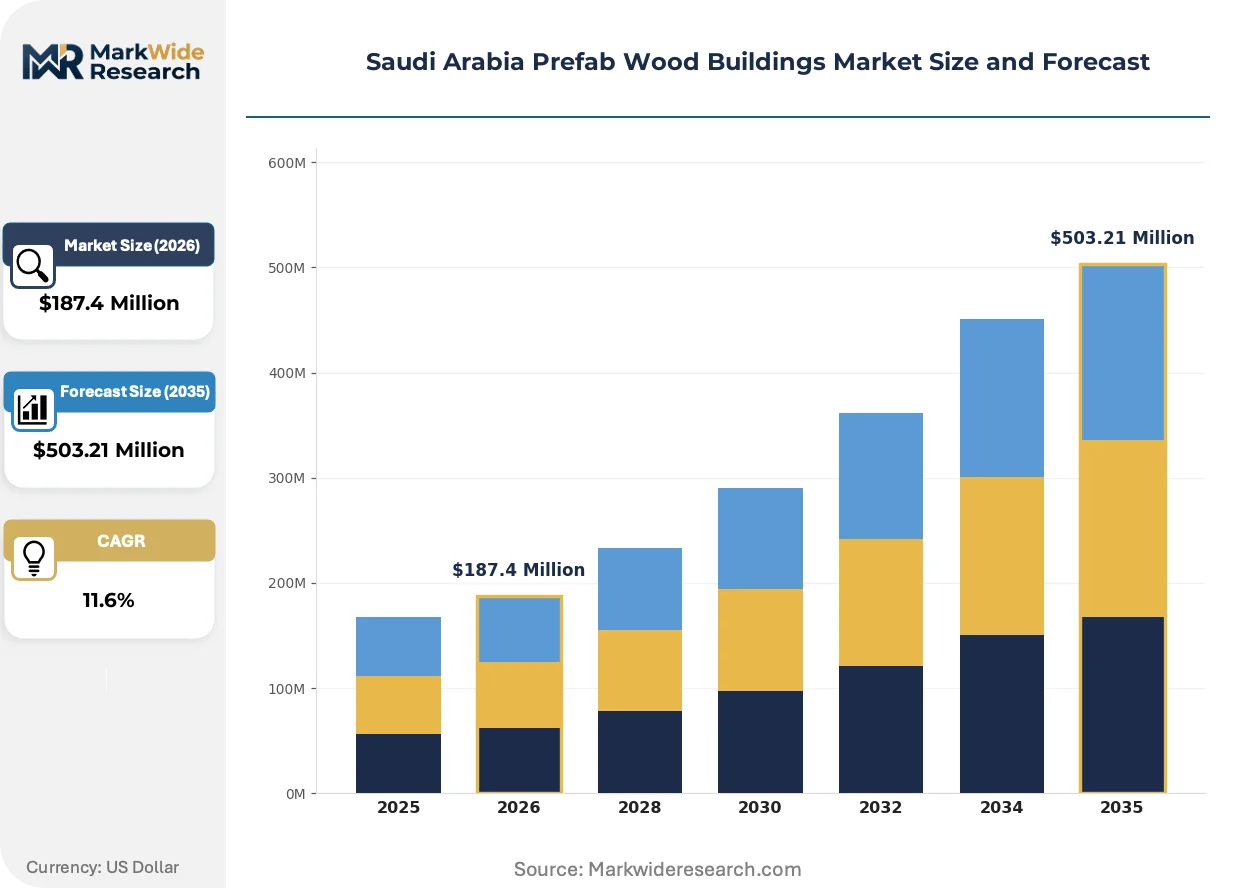
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Pre-Cut Cabins, Timber Frame Structures, Custom Wood Designs Application: Residential, Commercial, Educational, Recreational Technology: Green Building, Smart Design, Sustainable Materials, Prefabrication Techniques End User: Developers, Contractors, Homeowners, Government Agencies |
| Companies Covered | TSSC, Kirby Building Systems, DTH Prefab, Baradene Prefabricated Houses Co., Al-Tamimi Global Co. Ltd., Al Rashed, Newfab, Menco Group, Red Sea International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Prefab Wood Buildings Market Evolving Landscape
Digital fabrication workflows and regulatory harmonization are compressing traditional construction timelines while elevating material performance standards. Three concurrent shifts are restructuring how prefabricated timber reaches Saudi job sites.
Cross-laminated timber panel manufacturing is consolidating around automated CNC cutting and precision boring that eliminates field modification. Red Sea Project hospitality developers specify these pre-cut assemblies to hit accelerated enclosure milestones. The technology is consolidating procurement power with fabricators who control lamination-to-delivery logistics, marginalizing traditional lumber distributors.
SFDA's alignment with ISO structural timber standards is reducing duplicate testing burdens for imported engineered wood products. European and North American suppliers now submit single certification packages valid across Saudi Arabia's major municipalities. Healthcare facility developers under MOHAP jurisdiction are responding by expanding timber specifications into administrative wings previously reserved for concrete and steel.
General contractors are bundling design-assist services with fabrication procurement to compress pre-construction phases. This integrated delivery model displaces traditional design-bid-build sequences in NEOM and Red Sea Project portfolios. The shift is most visible in Riyadh's suburban masterplans, where master developers mandate single-point responsibility for envelope performance warranties.
Saudi Arabia Prefab Wood Buildings Market Segmentation
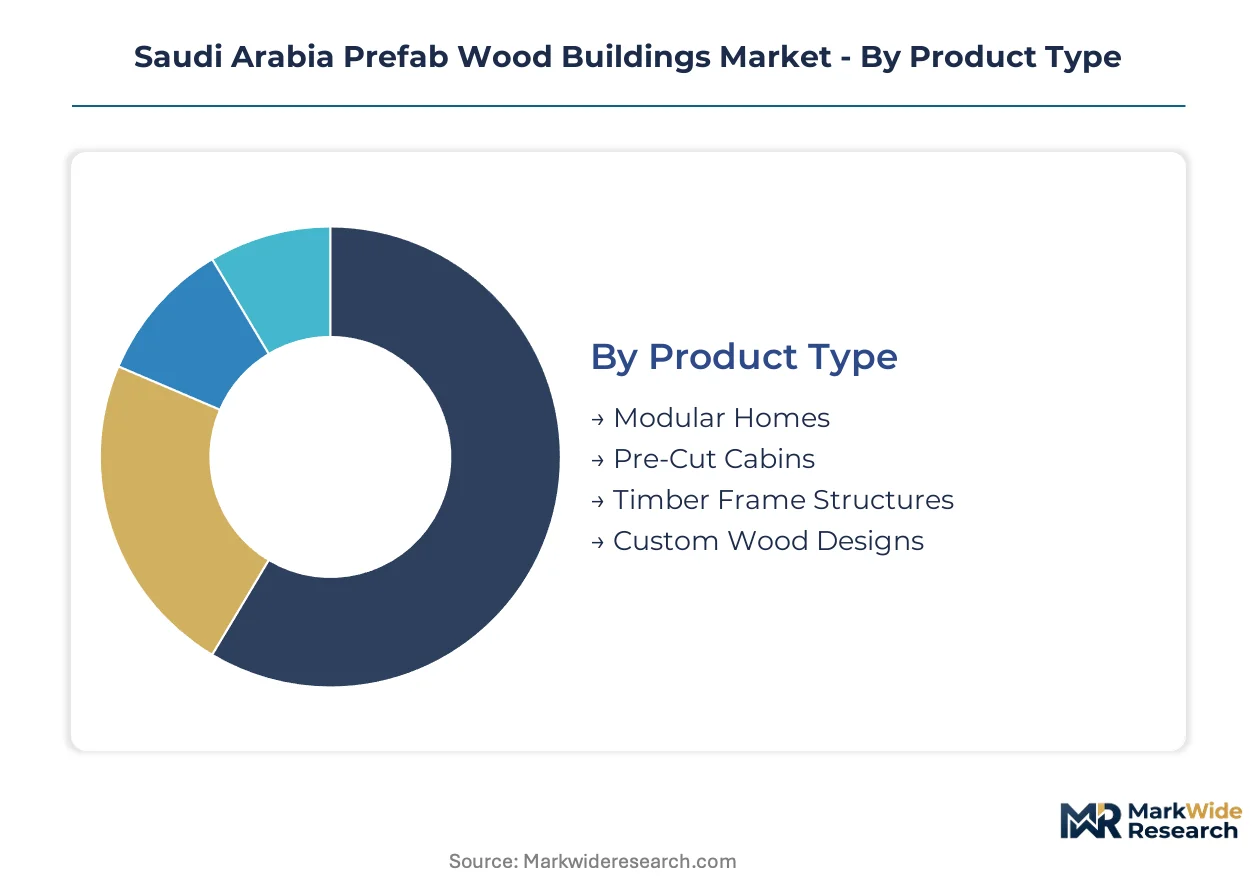
Segmentation in Saudi Arabia's prefab wood buildings market reveals how procurement priorities diverge across project scales and regulatory exposure. Developers balance customization depth against certification speed when selecting structural systems for NEOM's linear zones versus Riyadh's suburban masterplans.
Product Type:
Customization depth varies sharply across this category, from mass-produced volumetric modules to architecturally bespoke timber assemblies requiring project-specific engineering.
- Modular Homes:Factory-complete volumetric units with integrated MEP and finish packages ship as sealed modules for crane-set installation. Demand clusters in NEOM's residential clusters and Red Sea Project hospitality villages where accelerated weather-tight schedules command premium procurement. SFDA fire-certification requirements for multi-story stacking favor pre-tested module designs over site-adapted alternatives.
- Custom Wood Designs:Architecturally specified mass timber systems featuring exposed glulam frames and bespoke CLT geometries serve luxury hospitality and branded residential schemes. Asir Province boutique resort developers specify these for aesthetic differentiation in cooler highland climates where timber resonates with alpine positioning.
- Pre-Cut Cabins:Panelized wall and roof assemblies with pre-drilled connections enable rapid enclosure for remote site offices and temporary facilities.
- Timber Frame Structures:Post-and-beam skeletons with infill panels dominate low-rise suburban applications in Riyadh's new masterplan zones.
Leading the category by volume: Modular Homes. Growing fastest: Custom Wood Designs.
Application:
End-use exposure to municipal permitting intensity and sustainability certification mandates reshapes specification patterns across this dimension.
- Residential:Single-family and multi-family housing in Riyadh's suburban expansion zones specify prefab wood for speed-to-occupancy advantages. Saudi Building Code thermal envelope compliance drives engineered wood adoption over conventional framing in this segment.
- Commercial:Office and retail developments in Riyadh's premium districts pursue Saudi Green Building Forum certification pathways that specify mass timber for carbon accounting advantages. Developer brand differentiation in this segment supports higher procurement budgets for exposed structural wood aesthetics.
- Educational:School and university administrative buildings under MOHAP-adjacent standards are expanding timber specifications from temporary to permanent construction.
- Recreational:Red Sea Project coastal hospitality and Asir Province mountain resorts drive demand for prefabricated chalet and lodge systems.
Dominant by project count: Residential. Steepest expansion trajectory: Commercial.
Technology:
Certification tier and digital integration depth separate procurement classes in this dimension, from baseline code compliance to predictive building performance.
- Green Building:Systems engineered for Saudi Green Building Forum or equivalent environmental certification, featuring low-carbon material sourcing and operational energy optimization. NEOM and Red Sea Project assets mandate this tier for brand-aligned sustainability claims.
- Smart Design:BIM-integrated structural systems with embedded sensor readiness and predictive maintenance architecture. Riyadh masterplan developers specify this for long-term facility management outsourcing contracts.
- Sustainable Materials:FSC-certified timber and low-VOC finishes meeting SFDA material safety standards for healthcare-adjacent applications.
- Prefabrication Techniques:Standardized CNC production with lean manufacturing protocols serving cost-sensitive volume segments.
Highest specification rate in giga-projects: Green Building. Gaining specification share fastest: Smart Design.
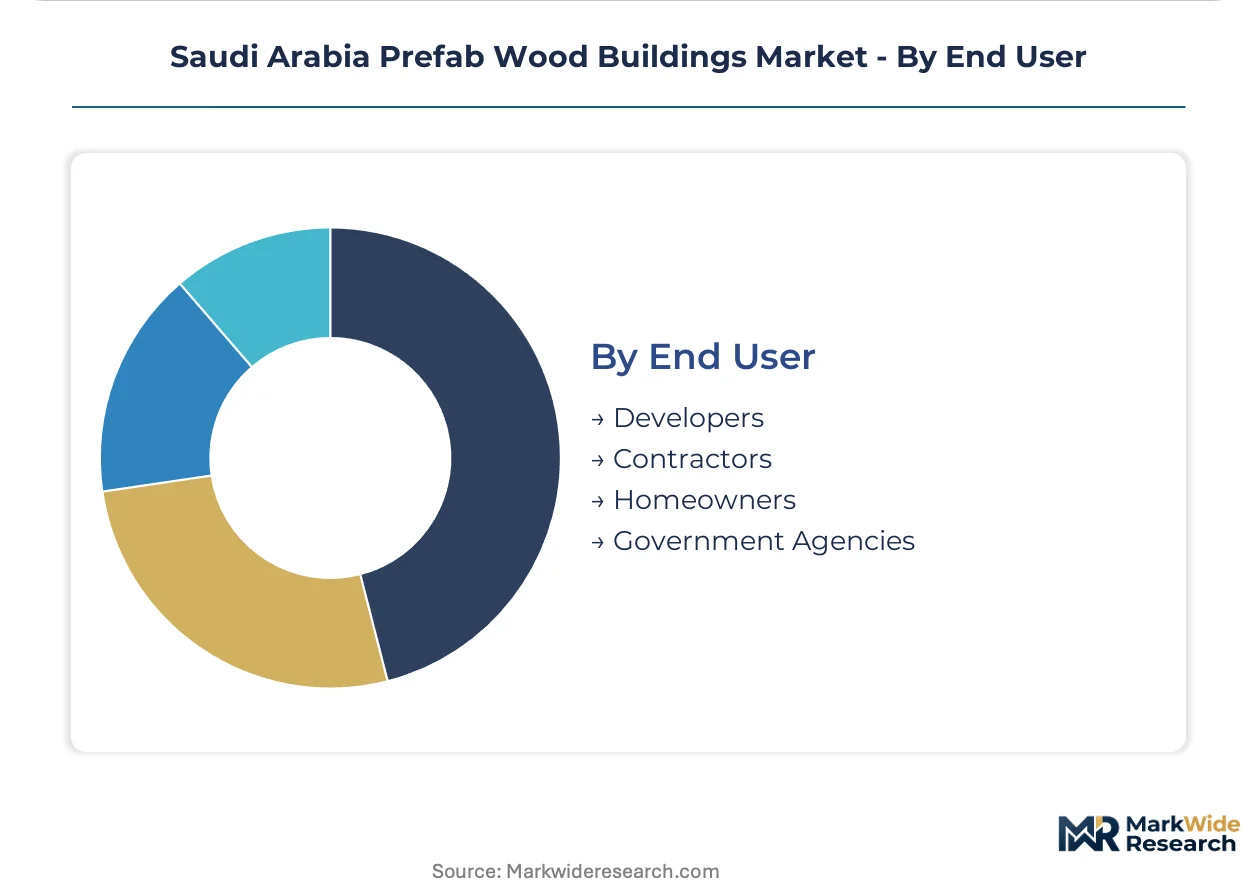
End User:
Procurement sophistication and risk tolerance distinguish buyer types, from integrated development platforms to fragmented individual purchasers.
- Developers:Master developers of NEOM, Red Sea Project, and Riyadh suburban zones drive category volume through multi-year framework agreements with prefabrication specialists. Their captive technical teams navigate SFDA certification and municipal permitting complexity that excludes smaller competitors.
- Contractors:General contractors with design-assist capabilities bundle fabrication procurement with construction management, displacing traditional bid-build sequences in commercial segments.
- Government Agencies:MOHAP and municipal housing initiatives specify prefab wood for staff housing and administrative facilities.
- Homeowners:Individual purchasers in custom residential segments face limited financing and certification support, constraining segment scale.
Controlling procurement volume: Developers. Expanding procurement sophistication: Contractors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Riyadh's suburban masterplans and NEOM's linear construction zones, with procurement patterns diverging sharply between established urban corridors and giga-project frontiers.
Riyadh
Masterplan developers in Riyadh's northern and eastern expansion zones specify prefab wood for accelerated occupancy timelines in single-family and multi-family housing. The Saudi Building Code's updated thermal envelope mandates drive engineered wood adoption over conventional framing in this segment. Fabrication procurement clusters around Dammam industrial corridor suppliers serving the capital's construction pipeline.
Eastern Province
Petrochemical sector administrative facilities and staff housing in Jubail and Dammam generate steady demand for modular timber systems. MOHAP standards influence healthcare-adjacent specifications where prefab wood emerges in non-clinical building components. Dammam's concentrated CLT fabrication capacity anchors regional supply chains, though fire-certification backlogs periodically constrain output.
Western Region
Jeddah's commercial developers pursue Saudi Green Building Forum certification pathways that specify mass timber for carbon accounting advantages in premium office segments. Municipal permitting timelines in Jeddah exhibit variable technical capacity for non-conventional structural reviews. The Red Sea coast hospitality corridor sits within this region, though NEOM procurement operates on distinct framework agreements.
NEOM Northwest
The linear city's phased delivery requirements favor factory-built timber modules that compress enclosure schedules versus cast-in-place alternatives. Hospitality and residential clusters along the coast specify cross-laminated timber for rapid vertical assembly. SFDA structural approval standards for fire-rated CLT panels reduce import dependency for this megaproject's procurement teams.
Asir Province
Cooler highland climates in Asir suit timber construction aesthetically and thermally for boutique resort development. Mountain hospitality developers seek prefabricated chalet systems that minimize on-site labor in remote terrain. This sub-region represents an emerging demand pocket distinct from the volume concentration in Riyadh and NEOM zones.
Saudi Arabia Prefab Wood Buildings Market Competitive Landscape
Capacity expansion dominates the current landscape as fabricators race to match giga-project procurement timelines. The vendor base organizes around three strategic archetypes: integrated panel manufacturers controlling lamination-to-delivery logistics, regional steel-building specialists diversifying into timber systems, and modular specialists aligned with hospitality and residential developers. Vertical integration and design-assist bundling represent the two competitive moves reshaping procurement relationships.
Among regional fabrication specialists, Kirby Building Systems and TSSC exemplify contrasting approaches to market positioning. Red Sea International occupies a position calibrated to accelerated enclosure schedules demanded by coastal hospitality developers. These three anchors represent the competitive spectrum spanning integrated manufacturing control, panel production specialization, and modular timeline alignment.
| Leading Market Players |
|---|
| TSSC |
| Kirby Building Systems |
| DTH Prefab |
| Baradene Prefabricated Houses Co. |
| Al-Tamimi Global Co. Ltd. |
| Al Rashed |
| Newfab |
| Menco Group |
| Red Sea International |
| Others |
Value Network & Pricing Analysis
Giga-project procurement teams' specification of fire-rated CLT panels for accelerated enclosure schedules forces supply response through limited domestic fabrication lines, compressing margins for contractors locked into fixed-price contracts while elevating premiums for certified modular systems.
Pricing Analysis
Volume concentrates in standardized modular homes where procurement runs through multi-year framework agreements with price compression from scale, while custom wood designs for Red Sea hospitality command 40-60% premiums driven by Saudi Green Building Forum certification tier and aesthetic customization depth. Price differentiation rests on SFDA fire-safety approval status and BIM-to-CNC integration level. Pricing pressure stems from European glulam import cost volatility against the euro. Developers show lowest price sensitivity in NEOM hospitality clusters; individual homeowners face acute financing constraints.
Supply Chain Analysis
SFDA structural approval and fire-certification gating concentrates engineered timber supply in the Dammam industrial corridor, with European imports filling certification backlogs. Raw material flows draw from Nordic pine and European spruce forests, regional lamination adhesives, and Saudi aluminum connection hardware. Single-source CLT panel vulnerability cascades delays when fire-certification queues extend. Distribution runs through captive logistics arms of integrated fabricators serving Riyadh masterplans and NEOM zones directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic CLT fabrication capacity bottlenecks prop pricing power for certified suppliers, creating asymmetric returns for operators with fire-rating pre-approval and Dammam corridor production access.
For Market Incumbents: Anticipate concrete substitution economics reverting wood specifications in low-rise Riyadh suburban housing unless sustainability mandates intervene; defend position by deepening backward integration into lamination adhesive production and securing captive Nordic pine offtake agreements to buffer euro currency exposure. For New Entrants and Emerging Players: Saudi Building Code energy efficiency provisions in Riyadh open a window for panelized envelope specialists with pre-certified thermal performance packages; target Asir Province mountain hospitality for aesthetic differentiation with lower permitting complexity, leveraging design-assist bundling to bypass incumbent logistics advantages. For Investors and Strategic Acquirers: The window for entry favors fabricators with existing SFDA fire-rating approvals and Dammam corridor real estate; acquisition candidates include regional steel-building specialists diversifying into timber systems with underutilized certification infrastructure. Watch for municipal permitting capacity buildout in Jeddah as inflection signal for demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Fire-Certification Pre-Approval Investment | Accelerates giga-project procurement timelines while locking out uncertified competitors from NEOM and Red Sea Project frameworks. |
| Backward Integration into Lamination Adhesive Production | Reduces import dependency and stabilizes input costs for CLT panel manufacturers facing European supply volatility. |
| Design-Assist Service Bundling | Compresses pre-construction phases for Riyadh masterplan developers seeking single-point envelope performance warranties. |
| Asir Province Mountain Hospitality Specialization | Captures boutique resort demand with lower municipal permitting complexity than coastal giga-projects. |
| Captive Logistics Capability Buildout | Enables just-in-time panel delivery across 45°C+ interior routes while reducing climate-controlled transport damage claims. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this study, supplemented by primary interviews with general contractors, giga-project procurement directors, SFDA compliance consultants, CLT fabrication plant managers, and municipal building department officials. Saudi Building Code amendments, SFDA structural timber approval databases, and engineered wood import manifests provided validation triangulation against bottom-up project pipeline tracking and top-down construction spending forecasts.
Data-stream reconciliation across shipment volumes, certification approval queues, and giga-project milestone schedules informed the analytical framework throughout the projection horizon. Segmentation dimensions modeled include product type, application, technology tier, and end-user procurement sophistication, with CAGRs derived from elasticity analysis against construction labor cost inflation and sustainability certification adoption curves. CLT fabrication capacity expansion timelines and municipal permitting velocity served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for BIM-to-CNC workflow integration; alternative pathways for digital fabrication standardization would alter the outlook for schedule compression premiums. Forecasts reflect assumptions on giga-project delivery continuity and euro-SAR exchange rate stability. A model refresh is warranted upon material change in SFDA fire-certification processing capacity or Saudi Green Building Forum mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
United Kingdom Data Center Construction Market
Building Construction
Japan Construction Market
Building Construction
UAE Transportation Infrastructure Construction Market
Building Construction
Global Modular Fabrication Market
Building Construction
Saudi Arabia Infrastructure Sector Market
Building Construction
Egypt Residential Construction Market
Building Construction
Germany Commercial Construction Market
Building Construction
China Modular Construction Market
Building Construction
India Prefabricated Buildings Market
Building Construction
Spain Prefabricated Buildings Market
Building Construction
UAE Facade Market
Building Construction
Middle East Data Center Construction Market
Building Construction
South Africa Prefabricated Buildings Market
Building Construction
Malaysia Construction Market
Building Construction
China Building Construction Market
Building Construction
United States Commercial Construction Market