
 Russia Mining Equipment Market | 2026-2036
Russia Mining Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Mining Equipment Market Analytics
Heavy-duty specification upgrades for Arctic-grade operations is unwinding across the Russia Mining Equipment Market as operators confront permafrost extraction challenges. Komatsu leverages its thermal management engineering to sustain market presence in extreme-climate deployments. UZTM Kartex anchors domestic supply through captive foundry capacity and Soviet-era fabrication infrastructure. Strommashina Corp specializes in grinding mill technology for gold and polymetallic concentrators in Eastern Siberia.
Russia mining equipment encompasses mechanized systems engineered for ore breaking, material transport, and mineral processing, typically rated for ambient temperatures spanning minus fifty to plus forty degrees Celsius with reinforced undercarriages and sealed electrical enclosures. The primary commercial purpose centers on sustaining extraction economics across remote deposits where labor scarcity and logistical isolation demand high machine availability. Excavators dominate capital allocation in open-pit coal and iron ore operations where bucket capacities exceeding twenty cubic meters define productivity benchmarks. Automation technology is expanding fastest among subterranean metal mines in the Kola Peninsula, driven by ventilation cost reduction and personnel safety mandates. Hydraulic systems retain installed-base dominance across drill and loader fleets, though electric power variants gain traction in grid-proximate Siberian basins where diesel logistics burden operating expenditures.
Rostekhnadzor enforces industrial safety rules for mining equipment through mandatory state registration and periodic recertification, directly shaping manufacturer compliance costs and product development roadmaps. Russia's Federal Agency on Technical Regulating and Metrology (Rosstandart) administers GOST-R and TR CU conformity assessment protocols that govern electromagnetic compatibility and mechanical safety for imported and domestically produced machinery. The Ministry of Industry and Trade coordinates import substitution programs that condition state procurement preferences on localized component thresholds. Stakeholders must monitor how sanctions-adjusted supply chains for German and Japanese drivetrain components reshape maintenance economics and fleet replacement timing across Russian mining subsidiaries.
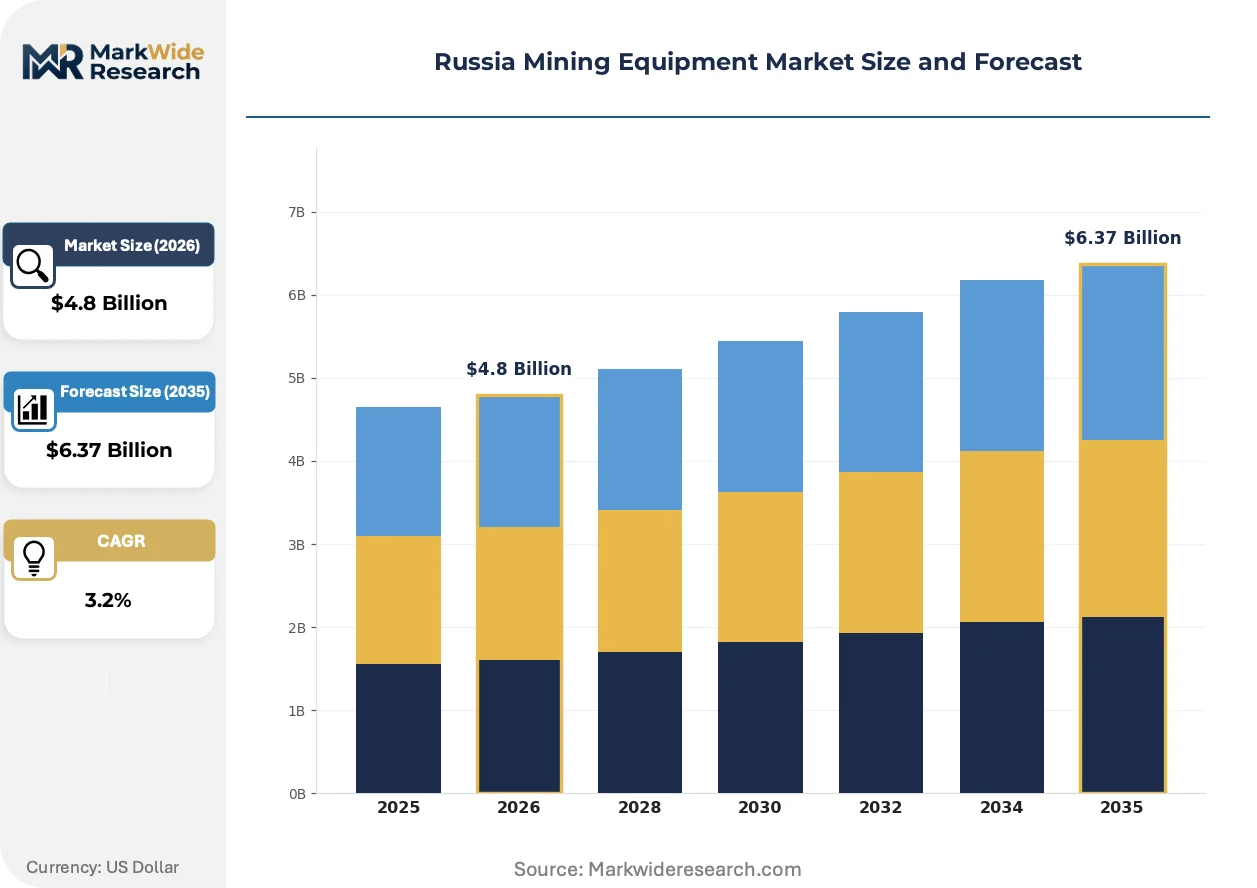
Market Dynamics
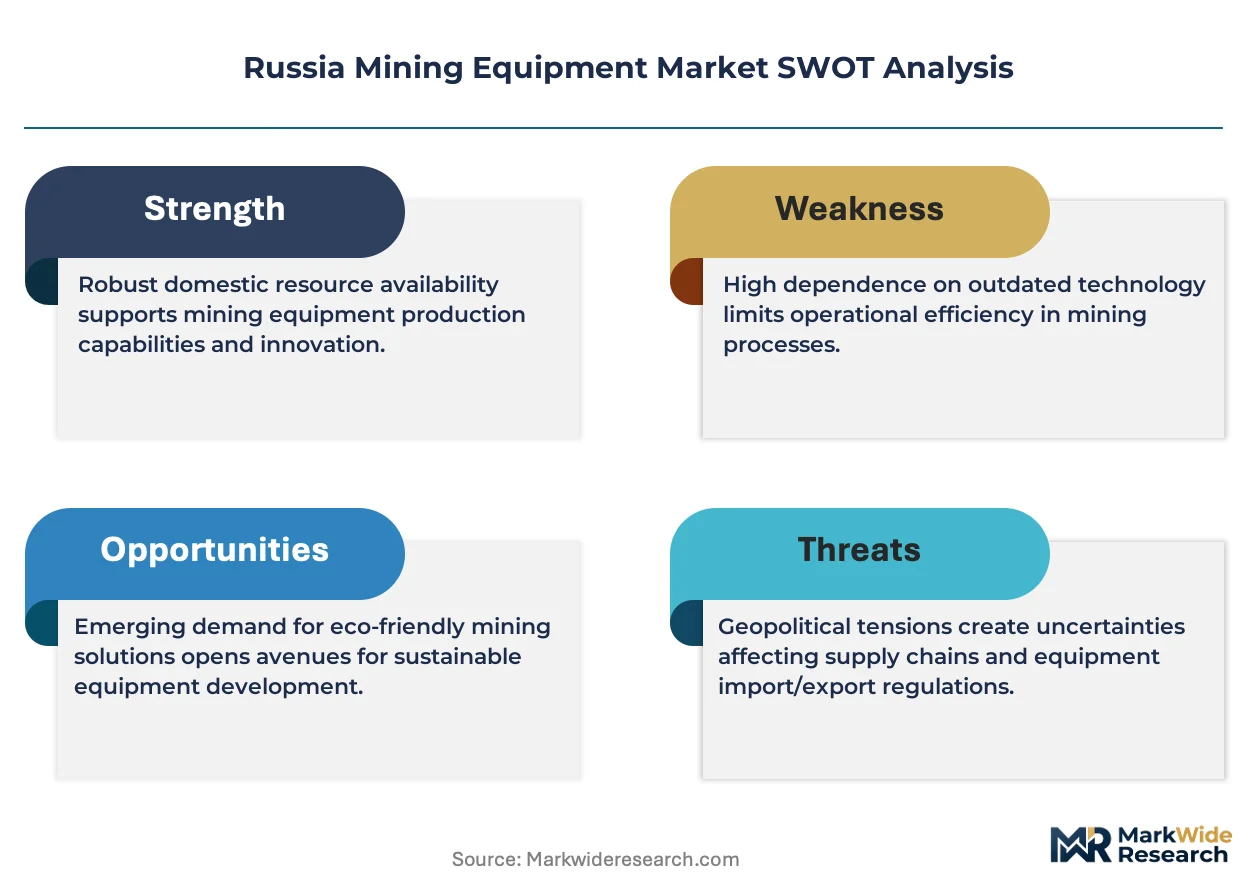
Rostekhnadzor's tightened industrial safety protocols are forcing accelerated fleet replacement cycles across Russia's subterranean coal and nickel operations, compressing capital deployment timelines for machinery with state registration certificates.
Growth Catalysts
- Arctic-grade thermal management:Komatsu's engineering adaptations for permafrost extraction are pulling demand for sealed electrical enclosures rated to minus fifty degrees Celsius across the Ural Federal District's open-pit iron ore complexes.
- TR CU explosion-proof mandates:Technical Regulation of the Customs Union certification requirements for subterranean machinery are creating replacement demand in Kuzbass underground coal operations where legacy fleets face forced retirement.
- Kola Peninsula automation:Ventilation cost reduction imperatives at Norilsk Nickel's deep ore bodies are accelerating remote-operated longwall shearer deployment, cutting personnel exposure hours.
Market Restraints
- German-Japanese drivetrain dependency:Sanctions-adjusted supply chains for hydraulic transmission components are extending lead times and inflating maintenance economics for Russian mining subsidiaries' existing fleets.
- Foundry capacity concentration:UZTM Kartex's captive Soviet-era fabrication infrastructure limits domestic competition, constraining price elasticity for roof supports and grinding mill components.
- Grid-proximate electrification limits:Diesel-hydraulic systems retain dominance in remote Eastern Siberian basins where transmission infrastructure gaps prevent electric power variant adoption.
Strategic Opportunities
- Far Eastern polymetallic concentrators:Strommashina Corp's grinding mill specialization positions domestic suppliers to capture gold processing equipment demand in underdeveloped Chukotka and Magadan deposits.
- Import substitution procurement preferences:Ministry of Industry and Trade localized component thresholds are creating preferential access for machinery meeting GOST-R conformity thresholds in state-tendered projects.
- Automation-conventional hybrid convergence:Integration of teleoperation interfaces with existing hydraulic loader fleets offers retrofit pathways for mid-tier operators avoiding full fleet replacement.
Industry Challenges
- Electromagnetic compatibility certification timelines:Rosstandart's TR CU assessment protocols for imported control systems are extending product launch cycles by twelve to eighteen months for foreign suppliers.
- Arctic logistics fragmentation:Permafrost road seasonality and Northern Sea Route ice window constraints are compressing delivery windows for oversized excavator components to Yakutia diamond operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Mining Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.37 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Drills, Crushers, Loaders Technology: Automation, Telemetry, Hydraulic Systems, Electric Power End User: Coal Industry, Metal Mining, Mineral Exploration, Oil Sands Installation: Onsite Assembly, Offsite Pre-Construction, Modular Systems, Retrofits |
| Companies Covered | Mitsubishi Corporation (Russia), Strommashina Corp, UZTM Kartex, Liebherr, FLSmidth, Uralmash, Kopeysk Machine Building Plant, Komatsu, Hitachi Construction Machinery, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Mining Equipment Market Evolving Landscape
Remote operation architectures are penetrating Russia's most hazardous extraction environments, driven by personnel safety mandates and ventilation cost pressures. Three interconnected developments are restructuring equipment specification and procurement patterns.
Teleoperated longwall systems are decomposing the traditional operator-cabin configuration in Kuzbass coal operations. SUEK and SDS-Ugol are piloting surface-control centers for deep seam extraction, eliminating underground personnel exposure to roof collapse and methane accumulation risks. This decomposition is compressing demand for conventional manned shearer cabins while expanding orders for fiber-optic communication backbone and real-time strata monitoring sensors.
Rostekhnadzor's 2024 amendments to industrial safety rules for mining equipment are mandating real-time methane concentration telemetry integration in all new subterranean machinery registrations. The regulation forces foreign and domestic manufacturers to embed certified gas detection arrays into hydraulic system enclosures, adding engineering cost but creating compliance differentiation for early adopters. Underground metal mines in the Kola Peninsula are responding fastest, integrating these systems into procurement specifications ahead of coal sector implementation timelines.
Equipment-as-service contracting is displacing outright purchase for mid-tier polymetallic operators in Eastern Siberia. Polymetal and Petropavlovsk are unbundling maintenance from capital acquisition, paying per-tonne processed fees that transfer availability risk to UZTM Kartex and Komatsu distributors. This shift concentrates most visibly in grid-proximate copper-porphyry complexes where electric power variants reduce fuel cost volatility exposure for service providers.
Russia Mining Equipment Market Segmentation
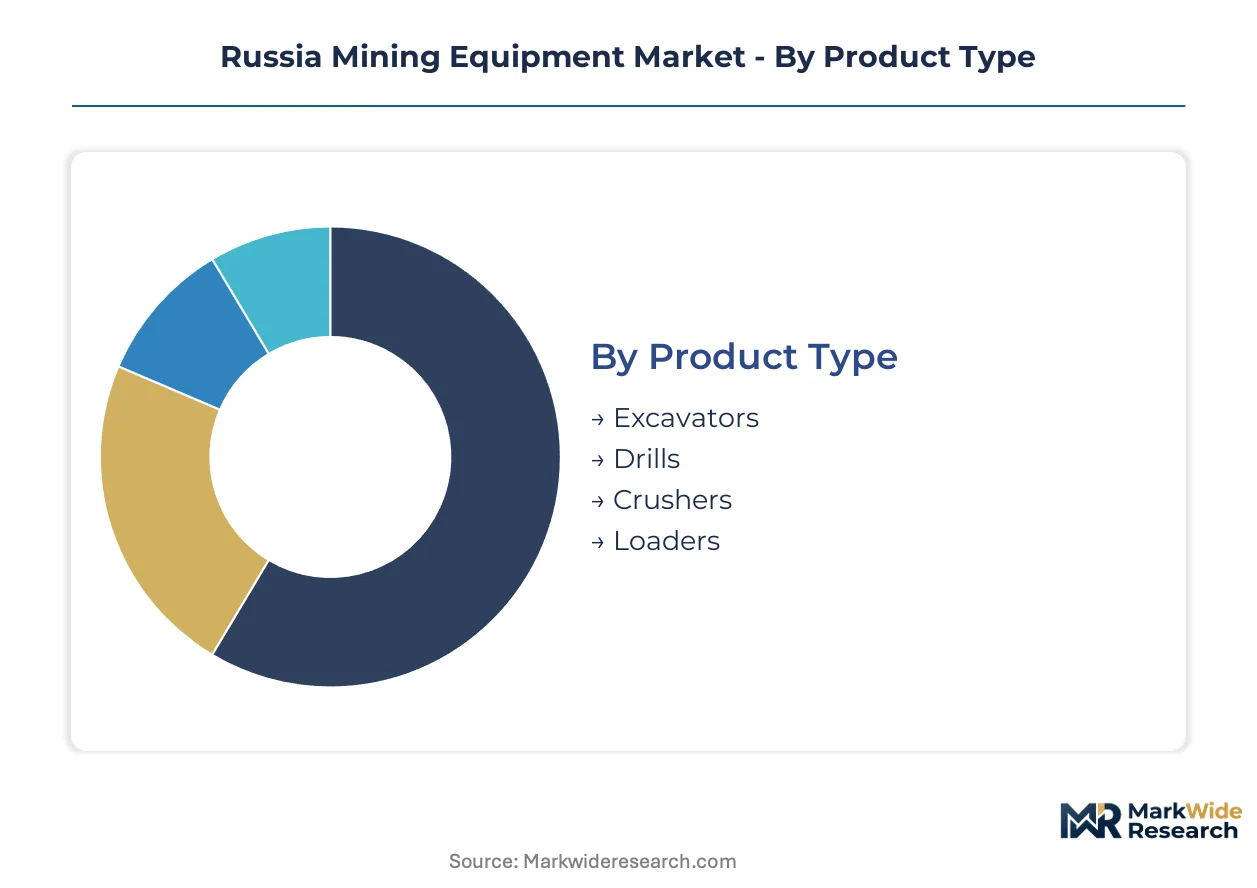
Equipment specification diverges sharply between domestic extraction basins and export-oriented mineral processing complexes. Segmentation reveals how sanctions-adjusted supply chains and Arctic-grade engineering requirements reshape procurement patterns across Russian mining subsidiaries.
Product Type:
Domestic fabrication capacity concentrates in heavy earthmoving equipment, while precision drilling systems remain import-dependent. Export-led segments face extended lead times for German-Japanese hydraulic components.
- Excavators:Bucket capacities exceeding twenty cubic meters dominate open-pit coal and iron ore operations in the Ural Federal District. Kuzbass operators prioritize reinforced undercarriages rated for permafrost extraction. Arctic-grade thermal management specifications from Komatsu anchor demand in this segment.
- Drills:Rotary and percussion systems for blasthole preparation feature sealed electrical enclosures compliant with TR CU explosion-proof mandates. Underground metal mines in the Kola Peninsula drive replacement cycles as Rostekhnadzor tightens methane telemetry requirements.
- Crushers:Jaw and gyratory configurations serve copper-porphyry concentrators.
- Loaders:Underground scooptrams face diesel-hydraulic dominance in Eastern Siberian grid gaps.
Excavators command the established base. The steepest expansion runs through drills as methane safety mandates force fleet renewal.
Technology:
Cost tier stratification separates premium automation systems from conventional hydraulic fleets. Mid-tier operators balance capital constraints against ventilation cost reduction imperatives.
- Automation:Teleoperated longwall shearers and remote loader control eliminate underground personnel exposure. SUEK and SDS-Ugol pilot surface-control centers in Kuzbass deep seams. Fiber-optic communication backbone and real-time strata monitoring sensors expand alongside manned cabin displacement.
- Telemetry:Rostekhnadzor's methane concentration monitoring mandates drive embedded gas detection arrays in hydraulic enclosures. Underground metal mines integrate these systems ahead of coal sector timelines.
- Hydraulic Systems:Installed-base dominance persists across drill and loader fleets.
- Electric Power:Grid-proximate Siberian basins enable traction where transmission infrastructure exists.
Hydraulic systems retain volume leadership. Automation gains share fastest as Norilsk Nickel deep ore bodies cut personnel exposure hours.
End User:
Application intensity varies by mineral type and extraction depth. Surface coal operations favor high-availability earthmoving fleets while deep metal mines prioritize ventilation-efficient automation.
- Coal Industry:Kuzbass underground operations drive longwall shearer and roof support demand. TR CU explosion-proof certification requirements compress replacement timelines for legacy fleets lacking state registration certificates.
- Metal Mining:Norilsk Nickel's nickel-copper operations in the Kola Peninsula sustain premium automation adoption. Remote-operated equipment cuts ventilation costs in deep ore bodies where personnel safety mandates intensify.
- Mineral Exploration:Portable drill rigs serve greenfield surveys in underdeveloped Chukotka deposits.
- Oil Sands:Specialized thermal extraction equipment addresses unique viscosity challenges.
Coal industry procurement anchors current volumes. Metal mining climbs the fastest as deep ore automation penetrates Norilsk Nickel complexes.
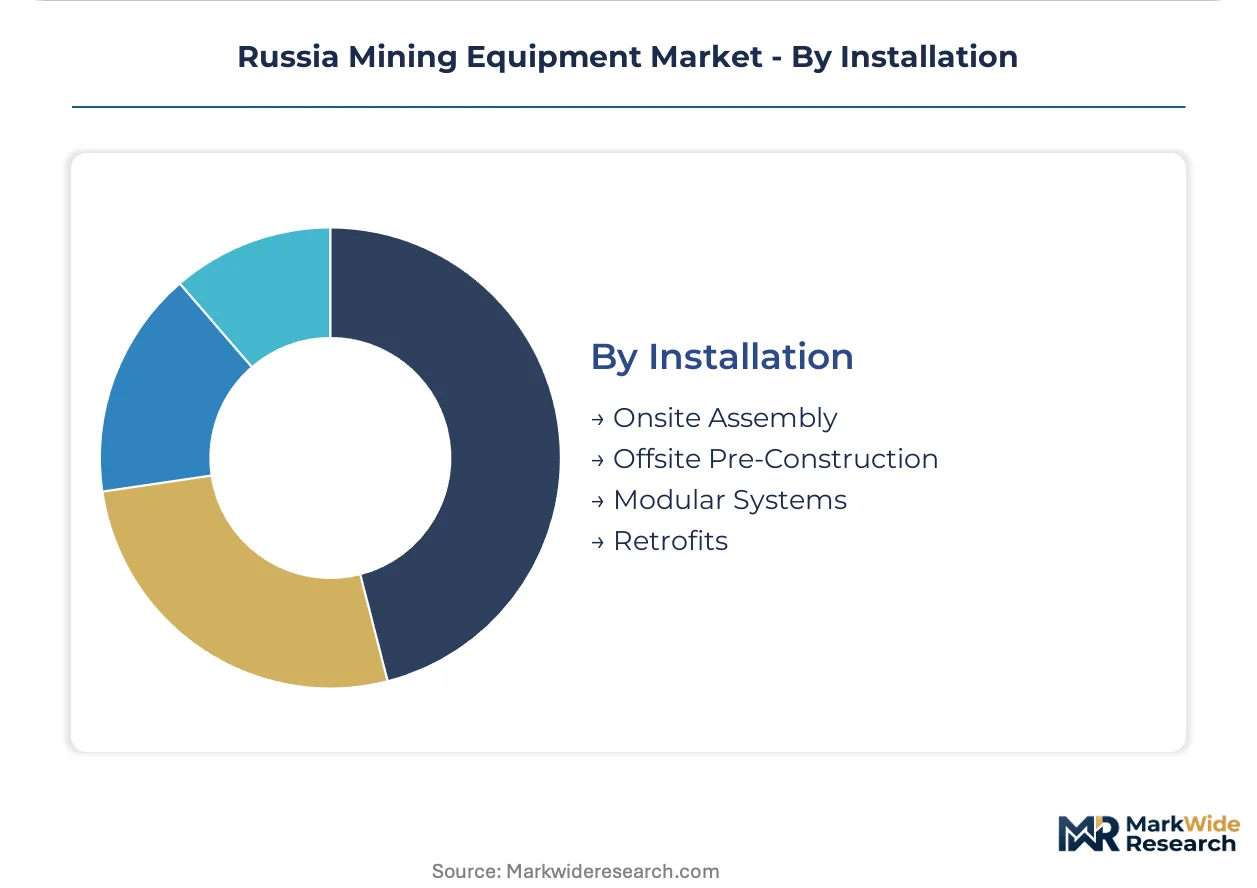
Installation:
Supply concentration in Soviet-era fabrication infrastructure shapes delivery modality tradeoffs. UZTM Kartex's captive foundry capacity influences domestic assembly economics.
- Onsite Assembly:Oversized excavator components for Yakutia diamond operations face Arctic logistics fragmentation. Permafrost road seasonality and Northern Sea Route ice windows compress delivery schedules for knockdown kits requiring field welding.
- Modular Systems:Pre-integrated grinding mill packages from Strommashina Corp reduce Eastern Siberian concentrator construction timelines. Gold and polymetallic processors in Chukotka and Magadan favor plug-and-play mineral processing circuits.
- Offsite Pre-Construction:Factory acceptance testing at Ural manufacturing clusters.
- Retrofits:Teleoperation interface integration extends hydraulic loader fleet life.
Onsite assembly holds the installed base. Modular systems expand most quickly as Far Eastern polymetallic deposits accelerate development timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented mineral processing complexes in Eastern Siberia and the Far East drive import dependency for precision components, while domestic fabrication clusters in the Ural Federal District anchor supply for heavy earthmoving equipment. Regional divergence reflects Soviet-era industrial geography and permafrost extraction challenges.
Kuzbass Region
Underground coal operations sustain demand for longwall shearers and roof supports rated to minus fifty degrees Celsius. Rostekhnadzor's industrial safety rules force accelerated replacement cycles for legacy fleets lacking state registration certificates. Kemerovo-based SUEK and SDS-Ugol pilot surface-control teleoperation centers, eliminating underground personnel exposure.
Kola Peninsula
Norilsk Nickel's nickel-copper deep ore bodies drive premium automation adoption for ventilation cost reduction. The Ministry of Industry and Trade's import substitution programs condition state procurement on localized component thresholds. Murmansk Oblast concentrators integrate real-time methane telemetry ahead of coal sector timelines.
Ural Federal District
Open-pit iron ore complexes prioritize Arctic-grade thermal management specifications for excavators exceeding twenty cubic meter bucket capacities. TR CU explosion-proof certification mandates reshape manufacturer compliance roadmaps. Chelyabinsk and Sverdlovsk Oblasts host UZTM Kartex's captive foundry infrastructure.
Yakutia
Diamond operations face compressed delivery windows for oversized excavator components due to permafrost road seasonality and Northern Sea Route ice constraints. Northern Sea Route infrastructure gaps extend lead times for knockdown kits requiring field welding. Mirny and Udachny processing plants favor modular grinding mill packages to reduce construction timelines.
Chukotka and Magadan
Underdeveloped gold and polymetallic deposits accelerate development timelines for plug-and-play mineral processing circuits. Diesel-hydraulic systems retain dominance where transmission infrastructure gaps prevent electric power variant adoption. Strommashina Corp's grinding mill specialization positions domestic suppliers to capture Far Eastern concentrator demand.
Russia Mining Equipment Market Competitive Landscape
Concentration sits with domestic heavy machinery fabricators leveraging Soviet-era industrial infrastructure. The competitive structure divides between import-dependent precision component suppliers and captive foundry operators. Two strategic archetypes dominate: vertically integrated domestic champions with backward control over casting and forging capacity, and foreign distributors adapting Arctic-grade engineering for extreme-climate deployments. Competitive moves center on import substitution alignment with Ministry of Industry and Trade procurement preferences and equipment-as-service contracting to transfer availability risk.
Among foreign distributors with Russian market presence, Komatsu and Liebherr occupy positions exemplifying premium-tier Arctic engineering adaptation. Within the domestic fabrication tier, UZTM Kartex and Strommashina Corp represent contrasting specialization models—heavy earthmoving concentration versus grinding mill technology for concentrator circuits. Kopeysk Machine Building Plant anchors the mid-tier roof support and longwall equipment segment. These four entities collectively illustrate how sanctions-adjusted supply chains and localized component thresholds reshape competitive positioning.
| Leading Market Players |
|---|
| Mitsubishi Corporation (Russia) |
| Strommashina Corp |
| UZTM Kartex |
| Liebherr |
| FLSmidth |
| Uralmash |
| Kopeysk Machine Building Plant |
| Komatsu |
| Hitachi Construction Machinery |
| Others |
Value Network & Pricing Analysis
Rostekhnadzor's industrial safety certification protocols gate both supplier qualification and price differentiation simultaneously, forcing foreign manufacturers to absorb extended compliance timelines while domestic fabricators leverage captive foundry capacity for cost positioning. Buyers face bifurcated sourcing economics where TR CU explosion-proof mandates compress options for subterranean fleets.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure with three-tier pricing stratification across premium Arctic-grade, standard compliance, and economy remanufactured tiers. Price differentiation rests on certification grade and after-sales service bundling, with premium tiers commanding substantial markups for minus fifty degrees Celsius thermal management. Cost compression in the economy tier is intensifying because sanctions-adjusted component lead times inflate maintenance economics for legacy hydraulic fleets. Junior polymetallic operators in Eastern Siberia exhibit highest price sensitivity, while Norilsk Nickel's deep ore automation programs demonstrate lowest sensitivity due to ventilation cost reduction imperatives.
Supply Chain Analysis
Germany and Japan anchor precision hydraulic transmission component fabrication, while Russia's Ural Federal District concentrates heavy casting and forging capacity through Soviet-era industrial infrastructure. Critical inputs include German-manufactured drivetrain assemblies, Japanese control electronics, and domestically sourced structural steel from Chelyabinsk metallurgical complexes. Single-source vulnerability runs through sanctions-restricted component channels, extending lead times for explosion-proof electrical enclosures. Distribution runs through UZTM Kartex's captive service network and Komatsu's distributor partnerships, with knockdown kit delivery dominating remote basin deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's mining equipment sector sits in early-cycle expansion as automation adoption penetrates deep ore bodies ahead of regulatory mandates, with teleoperation infrastructure representing the clearest penetration tailwind.
For Market Incumbents: Compound defensive positioning through backward integration into captive foundry capacity and Arctic-grade thermal management R&D to offset German-Japanese component substitution threats. Prioritize certification investment in TR CU methane telemetry integration to capture Rostekhnadzor-mandated replacement cycles ahead of foreign competitors facing Rosstandart assessment delays. For New Entrants and Emerging Players: Aftermarket service-layer gaps in remote Eastern Siberian basins offer white-space entry where incumbent distributors under-serve diesel-hydraulic maintenance demand. Target Chukotka and Magadan gold concentrators through modular grinding mill packages with embedded per-tonne processed contracting. Pursue equipment-as-service go-to-market structures that transfer availability risk and align with Polymetal's unbundled procurement preferences. For Investors and Strategic Acquirers: Rostekhnadzor's 2024 methane telemetry amendments reshape the acquisition landscape toward automation-ready asset bases with embedded compliance engineering. Long-term viability centers on five-to-ten year fleet replacement windows tied to state registration certificate renewal cycles. Target acquisition archetypes include vertically integrated domestic fabricators with captive casting capacity and established GOST-R conformity pathways. Monitor Ministry of Industry and Trade procurement preference threshold adjustments as the critical inflection signal for import substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Arctic-Grade Thermal Engineering Investment | Komatsu's sealed enclosure adaptations capture minus fifty degrees Celsius specifications across Ural iron ore complexes. |
| Teleoperation Infrastructure Deployment | SUEK's surface-control centers eliminate underground personnel exposure in Kuzbass deep seam operations. |
| Captive Foundry Capacity Expansion | UZTM Kartex's Soviet-era fabrication infrastructure constrains domestic competition for roof support components. |
| Equipment-as-Service Contracting | Polymetal's per-tonne processed fees transfer availability risk to distributors in grid-proximate copper-porphyry complexes. |
| TR CU Certification Pre-Positioning | Early methane telemetry integration creates compliance differentiation as Rostekhnadzor tightens subterranean machinery rules. |
Research Methodology
Two parallel data streams informed the analysis: primary engagement with equipment procurement directors, maintenance heads at Norilsk Nickel and SUEK, Rostekhnadzor certification specialists, and Uralmash engineering leads; alongside secondary validation through customs import records, Rosstandart conformity assessment databases, Ministry of Industry and Trade procurement registries, and sector-specific trade publications. Bottom-up fleet replacement modeling triangulated against top-down mineral production projections.
Across the projection horizon, the analytical framework segmented volume and value outputs by product type, technology tier, end-use mineral category, and federal district installation cluster. CAGRs derived from equipment replacement cycle analysis, regulatory mandate implementation timelines, and Arctic logistics capacity constraints. Industry-specific forecast inputs included permafrost road seasonality windows and Northern Sea Route ice coverage patterns affecting knockdown kit delivery schedules.
Forecasts assume regulatory continuity in Rostekhnadzor industrial safety rules and TR CU certification protocols; material policy shifts or sanctions regime adjustments would require re-modeling. Specific risks include electromagnetic compatibility certification timeline extensions for imported control systems and German-Japanese component supply disruption. Recalibration cycles align with material shifts in methane telemetry mandate implementation and Ministry of Industry and Trade localized content thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Hydraulic Drilling Rig Market
Mining Equipment
Underground Mining Equipment Market
Mining Equipment
Excavator Drill Market
Mining Equipment
Asia-Pacific Drill Pipe Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Smart Mining Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Crawler Excavator Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
Auger Drilling Market
Mining Equipment
Rock-Socketed Drilling Rig Market
Mining Equipment
Mining Equipment Parts and Attachments Market
Mining Equipment
Mining Drill Market