
 Excavator Drill Market | 2026-2036
Excavator Drill Market Size, Share, and Industry Trends Forecast 2026-2036
Excavator Drill Market Analytics
EPA Tier 4 Final and equivalent Euro Stage V standards is recalibrating the cost-of-entry calculus for diesel-powered excavator drill systems, forcing manufacturers to absorb after-treatment engineering expenses or cede share to electrified alternatives. Caterpillar Inc. leverages its integrated powertrain architecture to sustain compliance leadership across North American job sites. Bauer Maschinen GmbH anchors its position through deep specialization in foundation drilling attachments for crawler carriers. Komatsu Ltd. competes via hybrid drive development that narrows the torque gap between conventional diesel and full-electric platforms.
An excavator drill comprises a boom-mounted rotary drive attachment engineered to transmit torque through telescopic kelly bars or continuous flight augers, typically achieving rotational speeds of five to forty revolutions per minute and bore diameters spanning three hundred to three thousand millimeters for structural pile and ground-improvement applications. Hydraulic excavators dominate installed base volumes due to mature auxiliary circuit compatibility, yet electric technology leads incremental order growth as construction fleets face site-specific emission bans and utility-scale battery density improves. Mining end users concentrate demand in the large and extra-large size tiers where single-bore productivity governs total cost of ownership, while landscaping and agriculture segments fragment across small and medium units with lower utilization intensity.
FERC guidelines on linear infrastructure permitting and OSHA excavation safety mandates shape procurement specifications for utility-scale projects in the United States, while China's MEE enforces emission compliance windows that accelerate fleet turnover in provincial construction consortia. ISO 18758 performance measurement standards and IEC electrical safety certifications create dual compliance burdens for multinational suppliers serving cross-border contractors. Stakeholders must monitor regulatory divergence between emission-first jurisdictions and noise-restricted urban cores to align R&D spend with enforceable purchase criteria.
Market Dynamics
EPA Tier 4 Final and Euro Stage V emission standards are recalibrating the cost-of-entry calculus for diesel-powered excavator drill systems, forcing manufacturers to absorb after-treatment engineering expenses or cede share to electrified alternatives. This regulatory compression is reshaping equipment procurement patterns across construction fleets and mining operators.
Growth Catalysts
- Urban Tunneling Infrastructure:China's high-speed rail and metro expansion corridors concentrate demand for precision drilling attachments in confined underground environments.
- EPA Tier 4 Final Compliance:United States emission mandates accelerate fleet turnover among infrastructure contractors seeking compliant equipment for federal-funded projects.
- Hybrid Drive Development:Torque-gap narrowing between conventional diesel and full-electric platforms enables transitional adoption in emission-restricted job sites.
Market Restraints
- After-Treatment Cost Burden:Diesel particulate filters and selective catalytic reduction systems add fifteen to twenty-five percent to powertrain costs, compressing manufacturer margins.
- Battery Energy Density Limitations:Electric excavator drill systems face operational range constraints in remote mining applications lacking grid infrastructure.
- ISO 18758 Certification Complexity:Dual compliance burdens with IEC electrical safety standards create elongated approval timelines for multinational suppliers.
Strategic Opportunities
- Electrification in Noise-Restricted Urban Cores:European city centers with diesel bans create captive demand for battery-powered drilling platforms.
- Foundation Drilling Specialization:Deep foundation applications for wind turbine installations represent an underpenetrated vertical with high torque requirements.
- OSHA Excavation Safety Mandates:United States utility-scale projects face stricter operator protection standards, favoring automated drill monitoring systems.
Industry Challenges
- After-Sales Service Network Gaps:Electric powertrain maintenance requires technician retraining in high-voltage safety and battery management systems.
- Legacy Hydraulic Integration:Retrofitting electrified drill attachments onto existing excavator fleets demands custom auxiliary circuit modifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Excavator Drill Market |
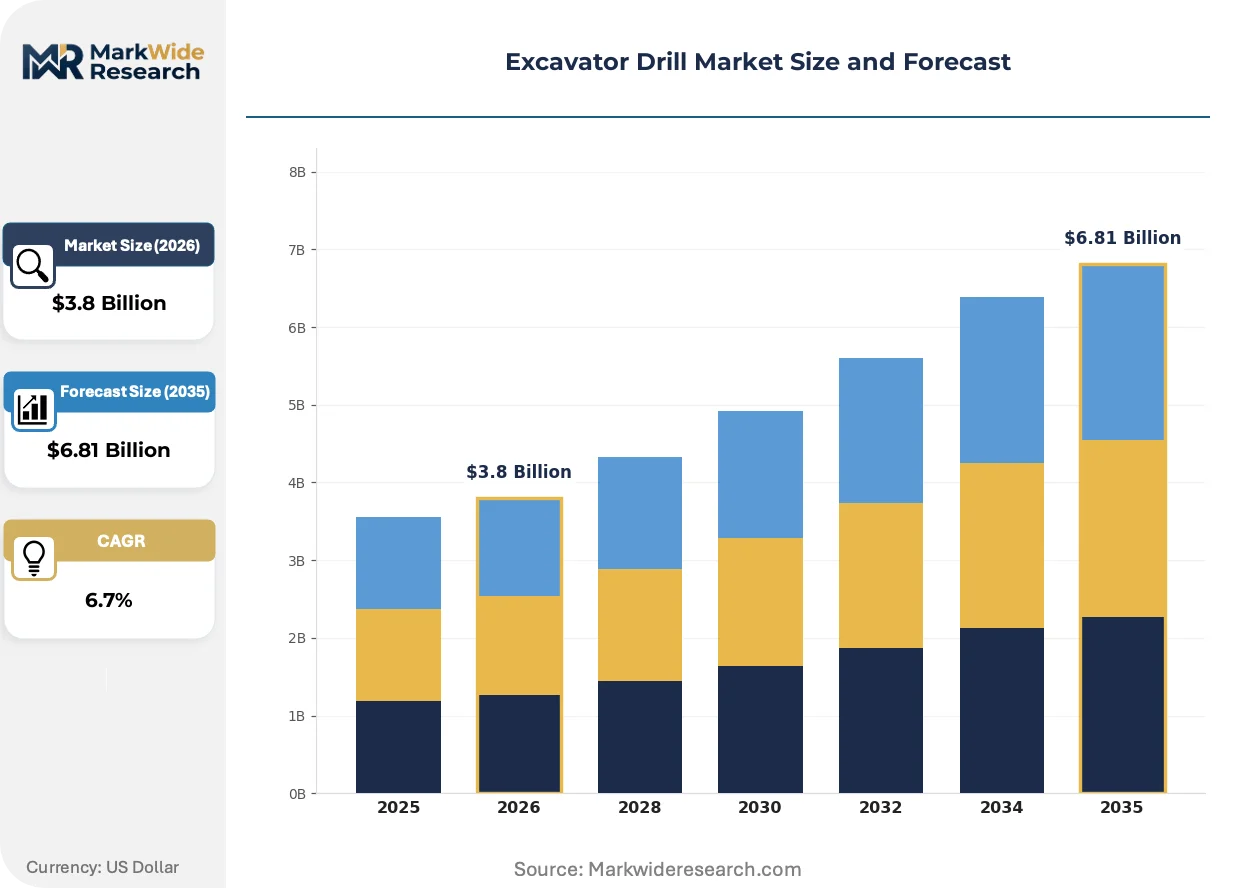
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Excavators, Mini Excavators, Crawler Excavators, Wheeled Excavators Technology: Electric, Diesel, Hybrid, Pneumatic End User: Construction, Mining, Agriculture, Landscaping Size: Small, Medium, Large, Extra Large |
| Companies Covered | Epiroc AB, Soilmec S.p.A., Bauer Maschinen GmbH, Junttan Oy, Auger Torque (UK) Ltd., Digga, Furukawa Co., Ltd., Caterpillar Inc., Komatsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Excavator Drill Market Evolving Landscape
Technology trajectories in the excavator drill market center on powertrain electrification, emission compliance engineering, and automation-enabled precision. These forces are compressing traditional equipment lifecycles while opening differentiated service models.
Telescopic kelly bar systems with integrated torque sensors are absorbing real-time drilling parameter feedback to enable automated depth and alignment control. Mining operators in Australia and Canada are piloting these platforms for blasthole consistency. The technology is absorbing routine operator judgment calls into machine-learning protocols, reducing bore deviation rates and labor dependency.
EU Stage V and EPA Tier 4 Final standards are forcing synchronous engineering investments across diesel after-treatment and electric powertrain architectures. Manufacturers serving cross-border contractors must maintain dual certification portfolios. North American rental fleets are responding by segmenting procurement between compliant diesel for rural deployment and electric units for urban emission zones.
Equipment-as-a-service models are unbundling capital expenditure from utilization risk for mid-tier contractors. Rental channels in Germany and Japan are displacing direct ownership with outcome-based contracts tying payments to meters drilled or pile completion. This shift concentrates fleet management expertise with specialized lessors while fragmenting end-user technical capabilities.
Excavator Drill Market Segmentation
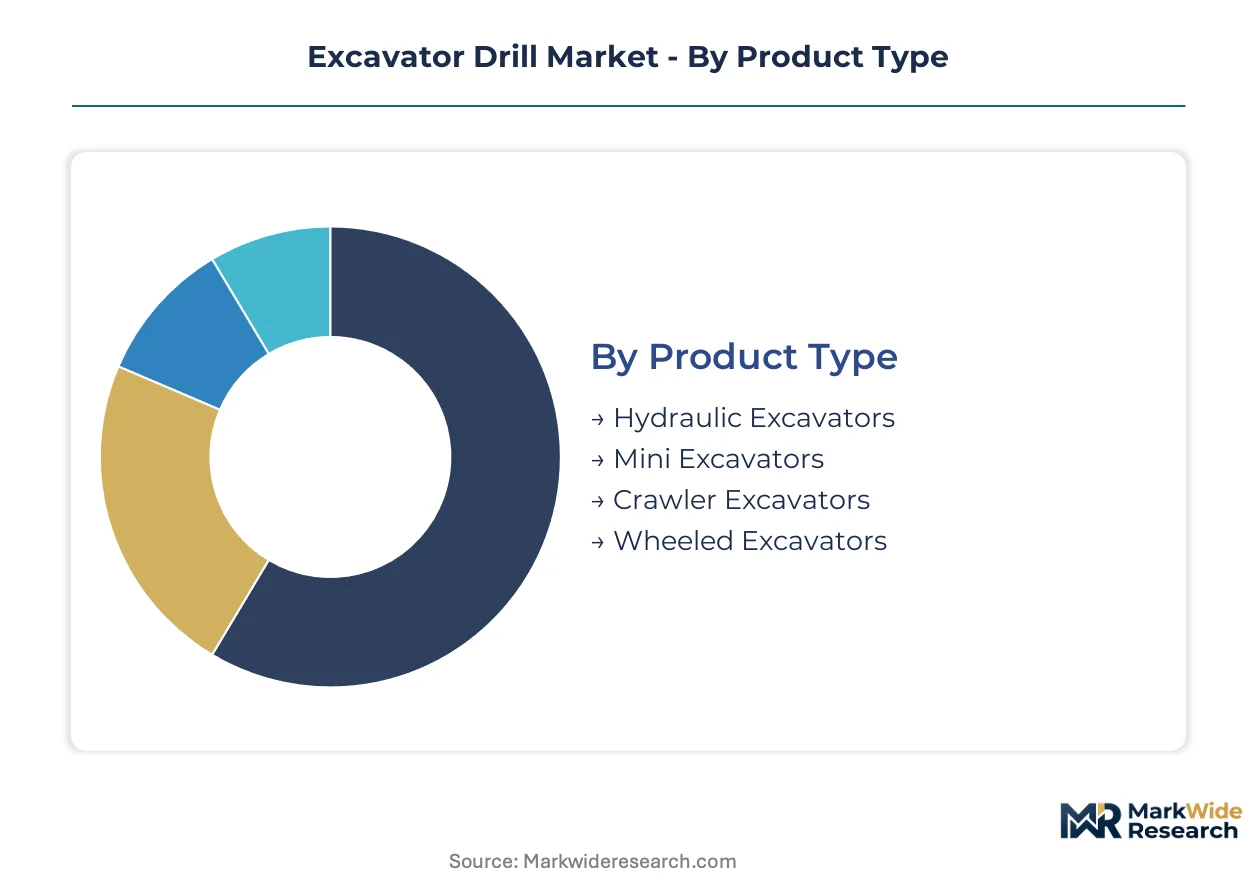
Excavator drill configurations fragment across powertrain architectures, carrier platforms, and duty-cycle intensity. Procurement patterns diverge sharply between fleet operators seeking utilization flexibility and specialized contractors optimizing for single-application torque delivery.
Product Type:
Hydraulic excavators command the installed base through mature auxiliary circuit standardization, while mini units capture premium pricing in confined-access deployment.
- Hydraulic Excavators:These systems leverage established auxiliary hydraulic circuits rated for continuous-duty rotary drives, achieving torque transmission efficiency above eighty-five percent in foundation drilling applications. Demand concentrates in China's high-speed rail corridors where multi-bore productivity governs project economics.
- Mini Excavators:Compact carrier platforms below six metric tons enable retrofit drilling attachments for residential foundation and landscaping applications. European urban cores with diesel bans are accelerating electric mini excavator adoption for noise-restricted drilling operations.
- Crawler Excavators:Tracked undercarriage systems distribute ground pressure for soft-soil drilling stability in wetland and coastal construction zones.
- Wheeled Excavators:Rubber-tired mobility suits rapid site-to-site relocation in road maintenance and utility-scale linear infrastructure projects.
Mature deployment sits with hydraulic excavators. Newer deployment is concentrated in mini excavators.
Technology:
Powertrain selection tracks regulatory enforcement intensity and site-specific emission constraints more than operational performance metrics.
- Electric:Battery-electric rotary drives eliminate after-treatment hardware while delivering instantaneous torque for precision alignment control. Foundation drilling contractors in German city centers with diesel bans are absorbing premium pricing for zero-emission platforms.
- Diesel:Compression-ignition powertrains with EPA Tier 4 Final after-treatment retain dominance in remote mining applications lacking grid infrastructure. Australian blasthole drilling operators prioritize single-bore productivity over emission compliance in unregulated territories.
- Hybrid:Parallel-hybrid architectures narrow the torque gap between conventional diesel and full-electric systems through regenerative auxiliary power. Japanese equipment lessors are segmenting hybrid units for transitional emission zones.
- Pneumatic:Compressed-air rotary drives serve explosive-atmosphere mining environments where electrical ignition risks are prohibited.
Established deployment centers on diesel systems. Expanding most quickly is electric technology.
End User:
Application intensity dictates size-tier selection and attachment specialization across divergent duty cycles.
- Construction:General building foundations and ground improvement projects absorb medium and large excavator drill configurations with telescopic kelly bar compatibility. US infrastructure contractors facing OSHA excavation mandates are specifying automated drill monitoring attachments.
- Mining:Blasthole consistency requirements drive demand for extra-large carriers with integrated torque feedback systems. Canadian operators in hard-rock extraction are piloting sensor-equipped kelly bars for deviation reduction.
- Agriculture:Irrigation well drilling and fence post installation utilize small excavator attachments with lower utilization intensity.
- Landscaping:Residential hardscaping and tree planting applications fragment across compact carrier platforms with limited bore diameter requirements.
Volume concentration rests with construction. Steepest expansion trajectory belongs to mining automation.
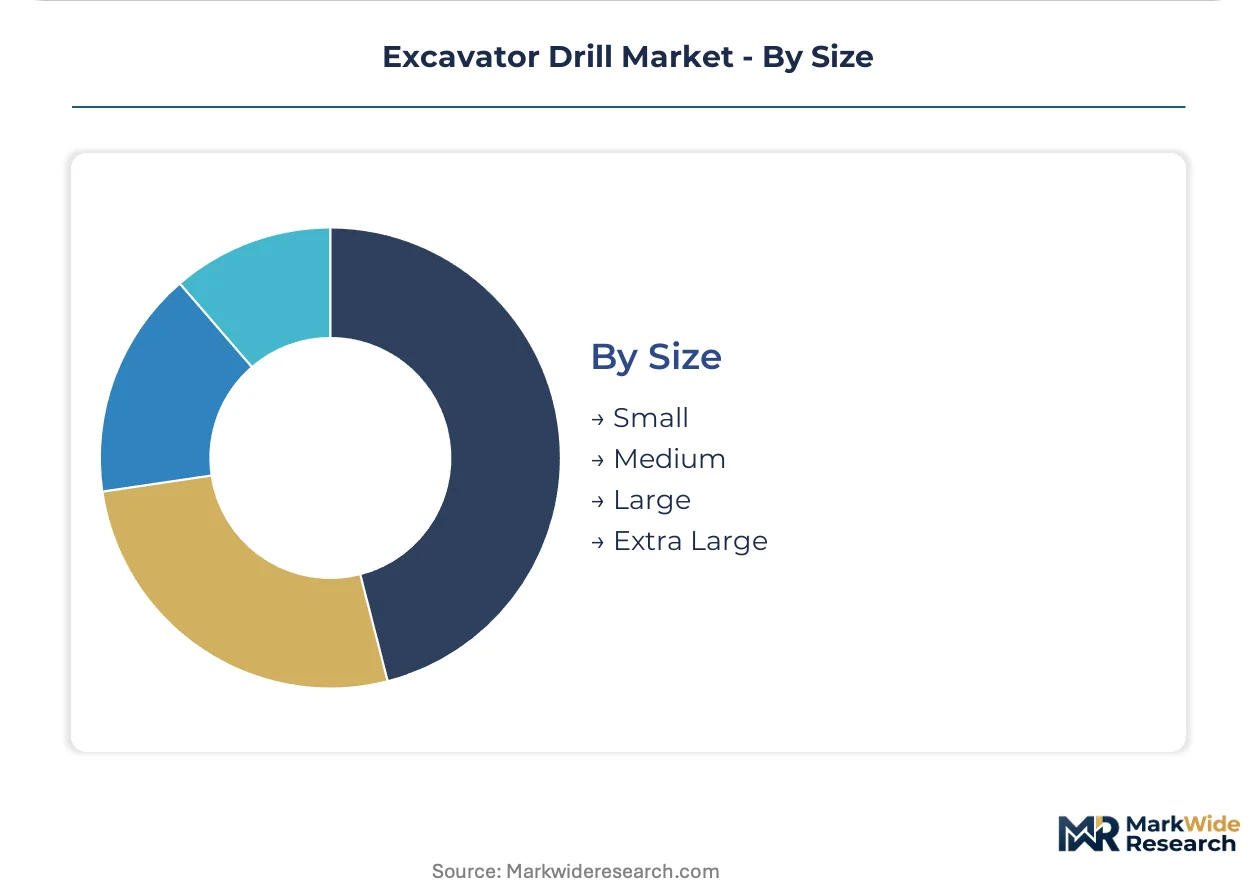
Size:
Carrier scale determines rotary drive torque capacity and kelly bar telescoping range for bore diameter flexibility.
- Large:Carriers above thirty metric tons accommodate dual rotary drives for simultaneous casing and auger rotation in deep foundation applications. Offshore wind turbine installations in the North Sea are specifying large excavator drills for monopile transition piece anchoring.
- Extra Large:Mining-class carriers exceeding fifty metric tons deliver sustained torque for blasthole diameters above three hundred millimeters in hard-rock conditions. Chilean copper extraction operations concentrate demand in this tier for single-pass drilling efficiency.
- Small:Compact carriers below ten metric tons serve utility trenching and residential piling with limited depth requirements.
- Medium:Mid-range platforms balance mobility and torque for general construction and road-building applications.
Revenue concentration aligns with extra large units. Penetration gains are fastest in medium sizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates the heaviest excavator drill deployment through high-speed rail and metro expansion corridors, while the United States and Germany anchor premium-tier demand through emission-compliant fleet renewal cycles.
United States
FERC linear infrastructure permitting and OSHA excavation safety mandates drive procurement specifications for utility-scale projects. EPA Tier 4 Final standards accelerate fleet turnover among infrastructure contractors seeking federally compliant equipment. Texas and California construction consortia absorb the largest volumes of emission-compliant rotary drive systems for urban tunneling applications.
China
Provincial construction consortia execute high-speed rail and metro expansion across dense urban corridors. MEE emission compliance windows compress fleet turnover timelines in state-owned construction enterprises. Yangtze River Delta municipalities specify precision drilling attachments for confined underground environments in Shanghai and Hangzhou metro extensions.
Germany
City-center diesel bans in Berlin, Munich, and Hamburg create captive demand for battery-powered drilling platforms. EU Stage V standards enforce synchronous after-treatment investments across diesel and electric powertrain portfolios. Foundation drilling contractors in the Rhine-Ruhr industrial cluster absorb premium pricing for zero-emission excavator drill configurations.
Australia
Mining operators in Western Australia and Queensland prioritize single-bore productivity in remote blasthole applications lacking grid infrastructure. Hard-rock extraction sites pilot sensor-equipped kelly bars for deviation reduction in Pilbara iron ore operations. Perth-based equipment lessors segment procurement between compliant diesel for rural deployment and electric units for urban emission zones.
Japan
Hybrid drive development narrows torque gaps between conventional diesel and full-electric platforms for transitional emission zones. METI industrial policy supports equipment-as-a-service models unbundling capital expenditure from utilization risk. Tokyo and Osaka metropolitan construction fleets absorb outcome-based contracts tying payments to meters drilled or pile completion.
Excavator Drill Market Competitive Landscape
German and Italian producers anchor the premium-tier specialization vector; Japanese and US conglomerates hold scale-driven positions through integrated powertrain architectures. The vendor base organizes around three strategic archetypes: foundation drilling specialists with deep attachment engineering, diversified construction equipment manufacturers with captive distribution, and regional fabricators serving price-sensitive retrofit demand. Competitive moves concentrate on hybrid powertrain licensing partnerships and electrified product line extensions into noise-restricted urban cores.
Within the foundation drilling specialist tier, Bauer Maschinen GmbH and Soilmec S.p.A. exemplify geographic concentration in European engineering centers. Caterpillar Inc. occupies a position among diversified manufacturers with integrated compliance capabilities across North American job sites. Epiroc AB sits within the mining-focused archetype, anchoring demand in Australian and Canadian hard-rock extraction applications. These three company types represent distinct competitive positioning vectors rather than direct segment overlap.
| Leading Market Players |
|---|
| Epiroc AB |
| Soilmec S.p.A. |
| Bauer Maschinen GmbH |
| Junttan Oy |
| Auger Torque (UK) Ltd. |
| Digga |
| Furukawa Co., Ltd. |
| Caterpillar Inc. |
| Komatsu Ltd. |
| Others |
Value Network & Pricing Analysis
Steel alloy and hydraulic component costs cascade through excavator drill manufacturing tiers, with EPA Tier 4 Final after-treatment engineering expenses compressing margins on diesel powertrains while battery cell pricing reshapes electric platform competitiveness across procurement segments.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning, as contractors facing OSHA-mandated project deadlines absorb markups for immediate equipment availability. Pricing separates EPA Tier 4 Final-compliant diesel systems from standard-tier configurations through certification-grade differentiation, while electric mini excavator attachments command premium positioning in German and Chinese urban cores with diesel bans. Cost compression in diesel after-treatment tiers is intensifying as manufacturers absorb engineering expenses to defend share against electrified alternatives. Small landscaping contractors exhibit highest price sensitivity, prioritizing retrofit attachment economics over integrated platform investments.
Supply Chain Analysis
China's domestic-content mandates for state-owned construction consortia are reshaping sourcing patterns, requiring local assembly of rotary drive systems for high-speed rail corridor deployment. Manufacturing concentrates in China, Germany, and Japan, with hydraulic pump and torque motor components drawing from specialized precision engineering clusters. Supply chain risk centers on single-source vulnerability for high-voltage battery management systems in electric powertrains. Distribution runs through equipment lessors and OEM captive dealer networks, with rental channels displacing direct ownership in German and Japanese metropolitan markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The excavator drill market operates as a cost-of-compliance arena where EPA Tier 4 Final and EU Stage V standards erect regulatory moats favoring manufacturers with integrated powertrain engineering capabilities.
For Market Incumbents: Deepen hybrid powertrain development to bridge torque gaps between diesel and electric platforms, capturing transitional demand in emission-restricted job sites. Expand aftermarket service networks for high-voltage battery management systems, addressing technician retraining gaps that threaten electric platform adoption. Anchor defensive positioning against Chinese state-owned entrants through certification leadership in IEC electrical safety standards.
For New Entrants and Emerging Players: Capture foundation drilling specialization for offshore wind turbine installations, an underpenetrated vertical with torque requirements unmet by generalist equipment. Target Australian and Canadian mining automation segments where sensor-equipped kelly bar demand outpaces incumbent supply. Pursue equipment-as-a-service licensing partnerships with regional lessors to bypass capital-intensive fleet ownership barriers.
For Investors and Strategic Acquirers: Japanese equipment lessor adoption of outcome-based contracts is the leading indicator that service-model unbundling will concentrate fleet management expertise with specialized lessors. Position acquisition screening toward foundation drilling attachment specialists with deep kelly bar engineering capabilities. Monitor EPA enforcement intensity on federally funded infrastructure projects as the signal for compliance-premium sustainability.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Development | Narrows torque gaps between diesel and electric platforms for transitional emission zones. |
| Foundation Drilling Specialization | Captures offshore wind turbine anchoring demand with high-torque kelly bar configurations. |
| Equipment-as-a-Service Expansion | Unbundles capital expenditure from utilization risk through outcome-based rental contracts. |
| Aftermarket Service Network Buildout | Addresses technician retraining gaps in high-voltage battery management systems. |
| Automated Drill Monitoring Integration | Aligns with OSHA excavation safety mandates for US utility-scale project specifications. |
Research Methodology
Trade association filings, customs import records, and equipment registration databases formed the secondary backbone, supplemented by primary interviews with maintenance directors at mining operators, procurement leads at infrastructure contractors, aftermarket service heads at regional lessors, and plant engineers at foundation drilling specialists. Bottom-up and top-down triangulation validated shipment volumes against powertrain production data and attachment retrofit rates.
Bottom-up modeling aggregated carrier platform shipments by size tier and powertrain architecture, while top-down analysis calibrated aggregate market value against rental fleet capitalization disclosures and OEM revenue segmentation. CAGRs derived from regression across technology adoption curves, regulatory compliance windows, and infrastructure investment cycles. Segmentation dimensions spanned product type, powertrain technology, end-use application, carrier size tier, and regional regulatory enforcement intensity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to battery energy density improvements, emission standard harmonization between jurisdictions, and mining commodity price volatility affecting fleet renewal cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mine Ventilation System Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Dewatering Aids for Mining Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Impact Crusher Market
Mining Equipment
DTH Drill Rig Market
Mining Equipment
Russia Mining Equipment Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Asia Pacific Mining Equipment Market
Mining Equipment
Global Tunneling and Rock Drilling Equipment Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
Mining Equipment Market
Mining Equipment
Latin America Mining Equipment Market
Mining Equipment
Global Large Mining Shovels Market
Mining Equipment
Mechanical Mine Clearance System Market