
 Mining Remanufacturing Components Market | 2026-2036
Mining Remanufacturing Components Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Remanufacturing Components Market Analysis
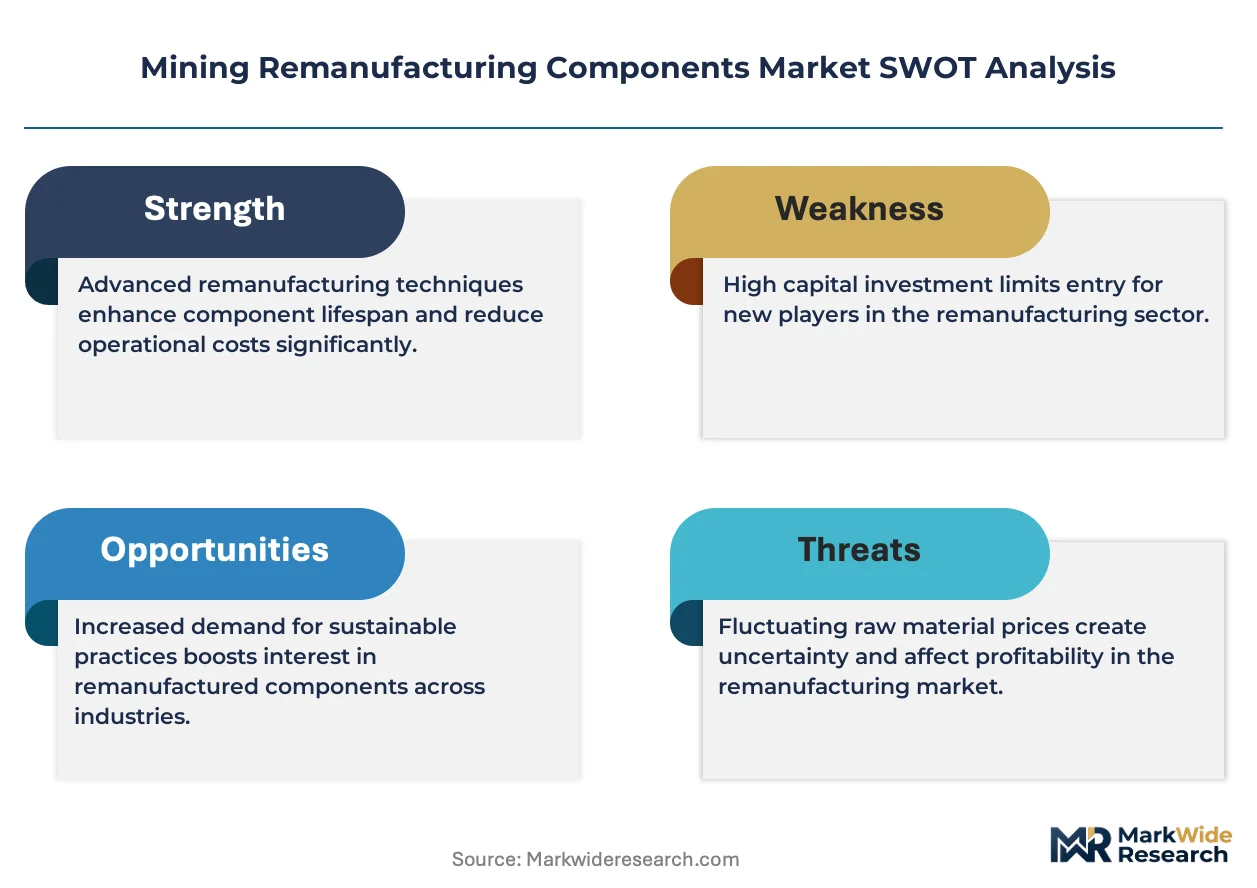
ISO 14001 environmental management certification is bifurcating the supplier base into qualified rebuilders and non-certified shops. Caterpillar leverages its global dealer network to control certified remanufacturing channels across multiple continents. Komatsu anchors its position through captive rebuild facilities tied to original equipment specifications. Sandvik specializes in hard-rock mining component remanufacturing, sustaining premium pricing through proprietary metallurgical processes.
Mining remanufacturing components encompass restored mechanical and hydraulic assemblies returned to OEM performance specifications through dimensional restoration, surface engineering, and functional testing. The process typically restores worn engine blocks, transmission gearsets, and hydraulic cylinder barrels to within original tolerance bands of 0.025 mm, delivering operating life equivalent to new components at 40-60% of replacement cost. Engines and transmissions dominate value pools due to capital intensity and core scarcity, while hydraulic cylinders represent the fastest-growing category as open-pit operations extend fleet cycles. CNC Machining underpins precision restoration across all component families, though 3D Printing is displacing conventional weld-repair methods for complex casting restoration in Australia and Canada.
EPA non-road diesel emissions standards and the EU F-Gas Regulation shape product specifications for remanufactured engines and climate-controlled cab components, respectively. ISO quality frameworks and MEE environmental compliance requirements in China govern cross-border trade in remanufactured mining equipment. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and right-to-repair legislation reshape the economics of OEM-controlled versus independent remanufacturing channels.
Market Dynamics
The mining remanufacturing components sector is consolidating around ISO 14001-certified rebuild capacity as environmental compliance becomes a non-negotiable procurement filter for tier-one mining operators.
Growth Catalysts
- EPA Tier 4 Final emissions standards:Non-road diesel engine regulations in the United States are mandating certified rebuild programs that restore engines to compliant specifications, expanding the addressable market for OEM-authorized remanufacturing.
- Pilbara iron ore fleet aging:Western Australia's remote operations face logistics costs that favor component restoration over new-unit delivery, concentrating replacement demand for transmissions and hydraulic assemblies.
- CNC machining precision gains:Dimensional restoration tolerances now reach 0.025 mm reliably, extending component life equivalence to new parts and validating remanufactured units for critical load-bearing applications.
Market Restraints
- Core scarcity in engine blocks:High-quality donor cores for large mining equipment are geographically concentrated in Australia and South Africa, creating supply bottlenecks for rebuilders outside these regions.
- EU F-Gas Regulation compliance costs:Climate-controlled cab component remanufacturing requires expensive refrigerant handling certification, raising fixed-cost barriers for independent shops serving European mining customers.
- 3D printing material limitations:Directed energy deposition processes for casting restoration remain restricted to nickel and cobalt alloys, excluding broader ferrous component families from additive repair methods.
Strategic Opportunities
- Canadian oil sands expansion:Alberta's remote extraction operations present underdeveloped demand for hydraulic cylinder remanufacturing, with fleet cycles extending due to capital discipline among operators.
- China MEE cross-border harmonization:Environmental compliance requirements for remanufactured equipment imports are creating pathways for certified foreign rebuilders to access domestic mining maintenance contracts.
- 3D printing-CNC hybrid workflows:Convergence of additive repair for complex geometries with precision machining for finish tolerances is enabling single-source restoration of previously unrepairable casting defects.
Industry Challenges
- Metallurgical engineering talent scarcity:Proprietary surface engineering processes for hard-rock mining components require specialized expertise that outpaces vocational training pipeline output in Australia and Canada.
- ISO 14001 certification timelines:Environmental management system audits extend 12-18 months, delaying market entry for independent rebuilders seeking tier-one mining supplier status.
- Legacy fleet data fragmentation:Component wear-pattern documentation from pre-digital-era equipment is incomplete, complicating predictive remanufacturing scheduling for mixed-age fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Remanufacturing Components Market |
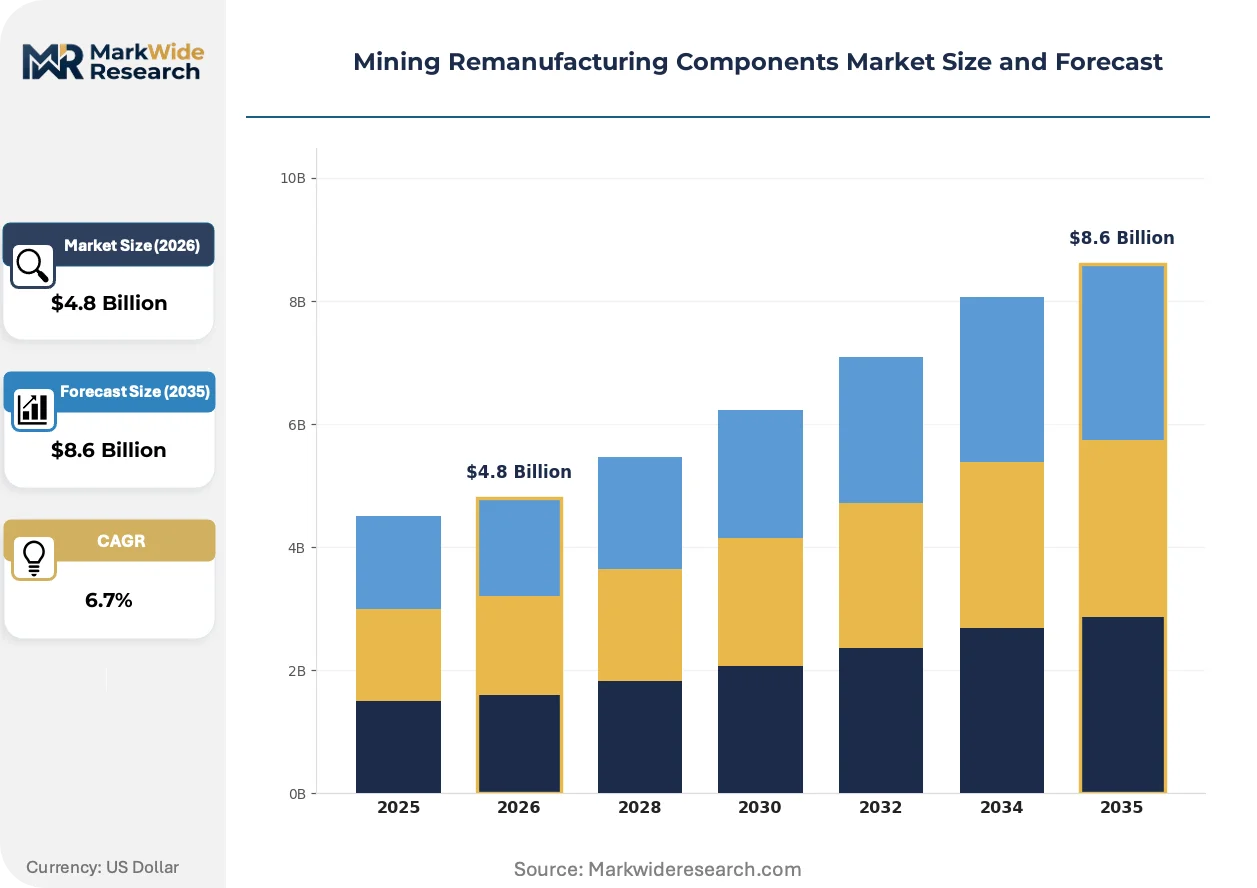
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Component Type: Engines, Transmissions, Hydraulic Cylinders, Pumps End Use Industry: Coal Mining, Metal Mining, Oil Sands, Quarrying Technology: 3D Printing, CNC Machining, Fabrication, Surface Treatment Service Type: Rebuilding, Refurbishing, Upgrading, Maintenance |
| Companies Covered | Liebherr, Atlas Copco, Caterpillar, Sandvik, Volvo Construction Equipment, Komatsu, Epiroc, Metso, Hitachi Construction Machinery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Remanufacturing Components Market Emerging Trajectories
Additive manufacturing methods are penetrating casting restoration workflows as precision demands outpace conventional weld-repair capabilities. Three developments are restructuring competitive positioning.
Directed energy deposition is supplanting traditional weld-repair methods for complex mining component castings. Australian rebuilders serving Pilbara iron ore operations are adopting laser-based metal deposition for cylinder head and transmission housing restoration. This technology is compressing turnaround times for previously scrapped components while reducing material waste in high-value alloy reclamation.
REACH substance restrictions are reshaping surface engineering chemistry for remanufactured hydraulic components. The European regulation's limitations on hexavalent chromium coatings are forcing rebuilders to adopt trivalent alternatives or plasma-transferred wire arc processes. Hydraulic cylinder remanufacturers serving EU mining markets are retooling plating lines to maintain component durability under stricter environmental standards.
Buyer preference is consolidating around certified rebuild programs with documented carbon footprint reduction. Mining procurement departments in Western Australia are embedding lifecycle emissions data into supplier scorecards, displacing price-only tender evaluation for critical rotating components. This behavioral shift favors OEM-authorized channels with traceable environmental management systems over independent rebuild shops.
Mining Remanufacturing Components Market Segmentation
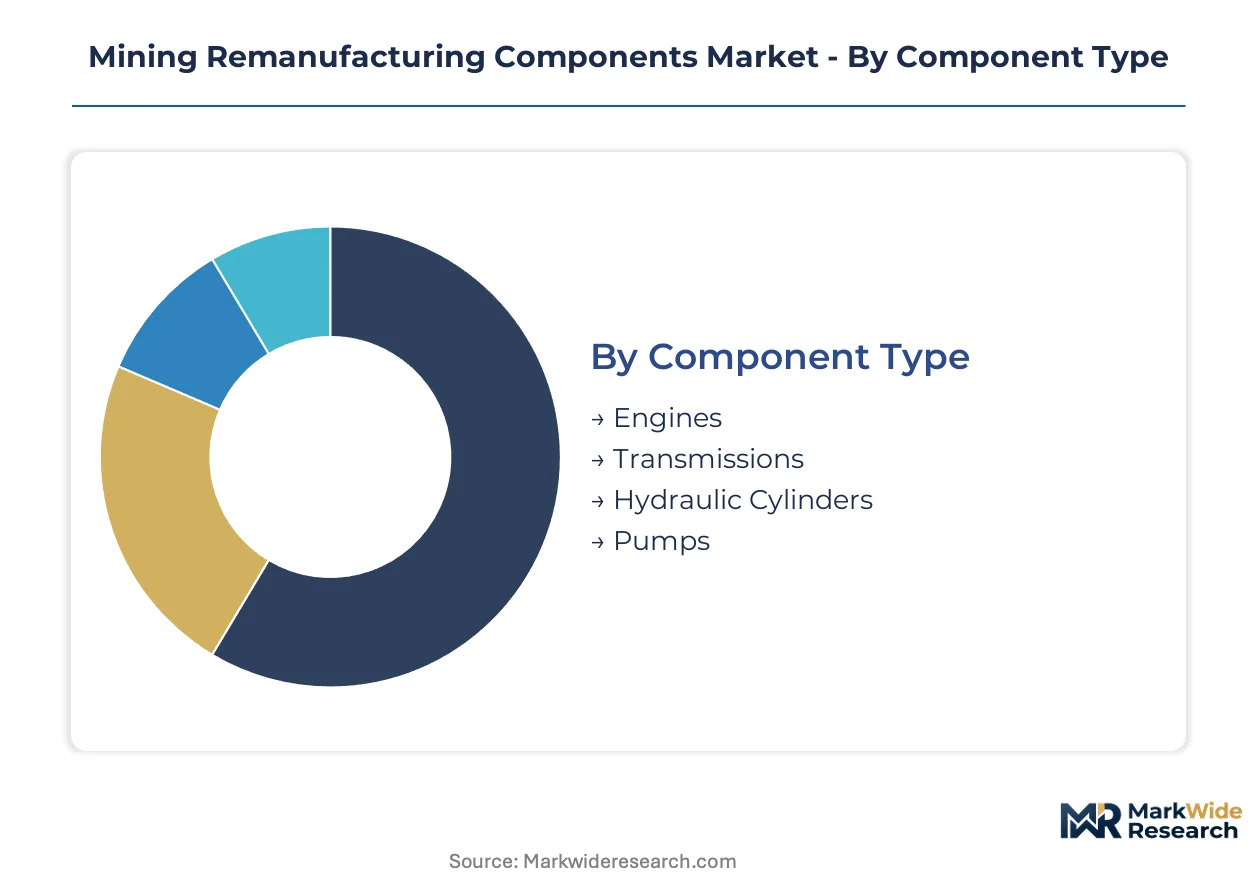
Component type and service tier determine channel economics in mining remanufacturing. Certified rebuild programs flow through OEM dealer networks, while independent shops capture refurbishment demand from mid-tier operators.
Component Type:
OEM-authorized channels dominate capital-intensive assemblies, with independent rebuilders capturing wear-part restoration.
- Engines:Large-displacement diesel blocks undergo dimensional restoration to EPA Tier 4 Final specifications. Western Australia's Pilbara iron ore belt concentrates replacement demand due to fleet age and remote logistics costs. Core scarcity constrains supply outside Australia and South Africa.
- Transmissions:Gearset and housing restoration requires CNC machining to 0.025 mm tolerances. Underground coal operations in Australia drive procurement through certified dealer networks seeking warranty-backed performance.
- Hydraulic Cylinders:Barrel and rod restoration for open-pit equipment represents the steepest expansion trajectory, with Canadian oil sands extending fleet cycles.
- Pumps:High-pressure hydraulic pump remanufacturing serves hard-rock mining applications.
By volume, engines lead. By growth pace, hydraulic cylinders are climbing the fastest.
End Use Industry:
Application severity dictates restoration frequency and certification requirements across extraction methods.
- Coal Mining:Underground operations in Australia generate sustained demand for emissions-compliant engine rebuilds. EPA standards mandate certified restoration programs, filtering procurement toward ISO 14001-qualified suppliers.
- Metal Mining:Iron ore extraction in Western Australia's Pilbara region favors component remanufacturing over new-unit procurement due to transportation economics and fleet standardization.
- Oil Sands:Alberta's remote extraction operations present underdeveloped demand for hydraulic cylinder remanufacturing as capital discipline extends equipment cycles.
- Quarrying:Aggregate operations utilize refurbishment services for mid-life equipment.
Coal mining commands the largest share of certified rebuild volume. Oil sands applications are expanding most quickly.
Technology:
Precision requirements and material constraints segment rebuild capabilities between additive and subtractive methods.
- 3D Printing:Directed energy deposition for complex casting restoration is displacing conventional weld-repair in Australian and Canadian operations. Laser-based metal deposition compresses turnaround for previously scrapped cylinder heads and transmission housings.
- CNC Machining:Subtractive precision finishing underpins all component families, delivering dimensional tolerances that validate remanufactured units for critical load-bearing applications.
- Fabrication:Structural component repair serves non-critical assemblies.
- Surface Treatment:REACH-compliant coating alternatives replace hexavalent chromium for EU-facing hydraulic components.
CNC machining anchors current volume. 3D printing is gaining share fastest in casting restoration.
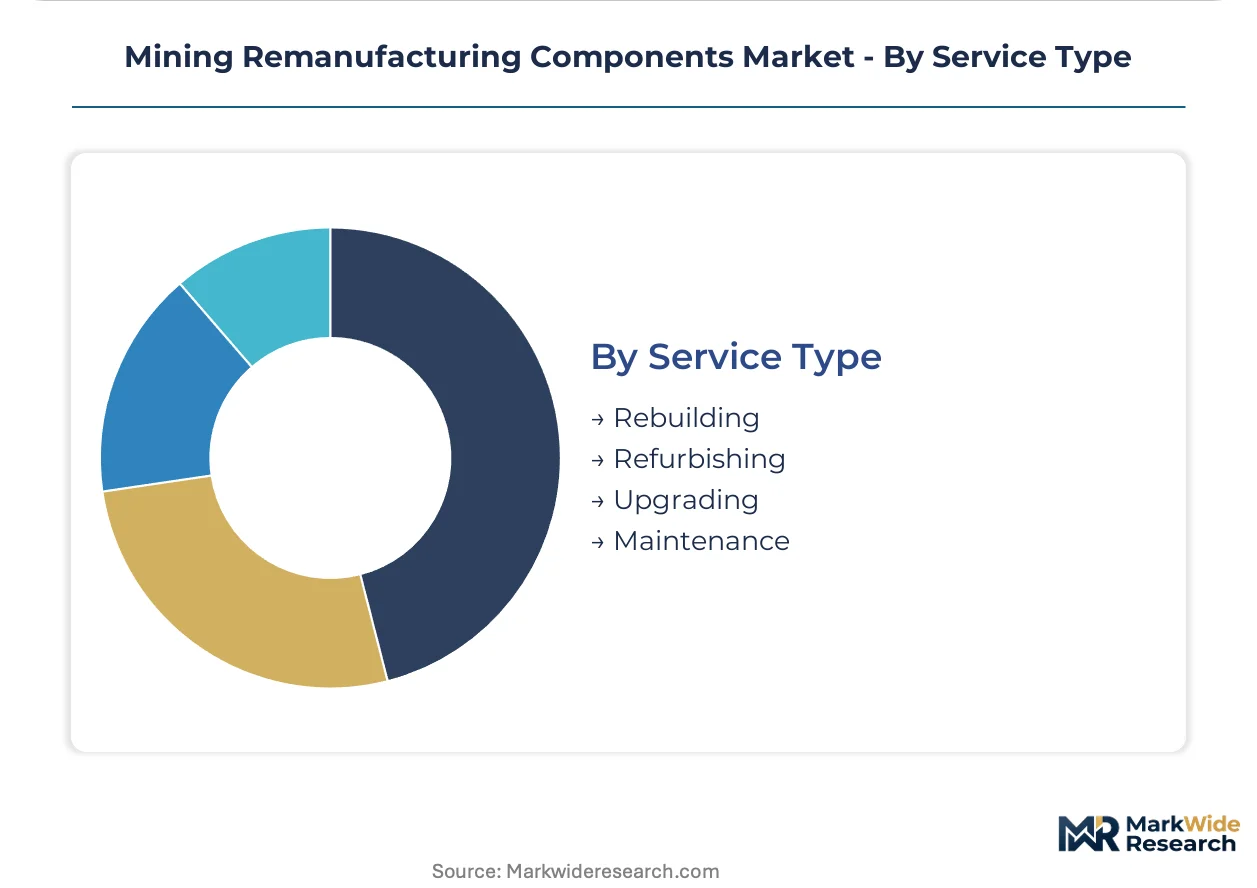
Service Type:
Customer capital availability and equipment criticality determine service tier selection across the mining fleet lifecycle.
- Rebuilding:Comprehensive restoration to OEM performance specifications delivers operating life equivalent to new components at 40-60% of replacement cost. Tier-one mining operators mandate certified rebuild programs with documented carbon footprint reduction.
- Refurbishing:Cosmetic and functional renewal for mid-life equipment serves quarrying and secondary mining applications.
- Upgrading:Emissions compliance retrofits and performance enhancements address regulatory deadlines.
- Maintenance:Preventive component exchange programs reduce unplanned downtime.
Rebuilding generates the highest revenue per transaction. Upgrading is accelerating as emissions deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara-to-Port Hedland heavy-haul rail corridor underwrites Australia's dominance in mining remanufacturing demand, moving iron ore from inland pits to export terminals with component-intensive fleet operations.
Australia
Western Australia's Pilbara iron ore belt concentrates replacement demand for remanufactured transmissions and hydraulic cylinders, driven by fleet age exceeding 15 years and 1,500-kilometer distances to nearest OEM distribution centers. EPA emissions standards for non-road diesel engines mandate certified rebuild programs, filtering procurement toward ISO 14001-qualified suppliers. Perth hosts the largest cluster of independent rebuilders serving Pilbara operations, with component restoration facilities concentrated around Kewdale industrial precinct.
United States
Appalachian underground coal operations and Powder River Basin surface mining sustain demand for emissions-compliant engine rebuilds, with EPA Tier 4 Final regulations expanding the addressable market for OEM-authorized remanufacturing. The Mine Safety and Health Administration enforces equipment certification requirements that favor documented rebuild programs over unverified component sources. Gillette, Wyoming anchors the Powder River Basin rebuild ecosystem, with component restoration shops concentrated to serve 24-hour continuous mining operations.
Canada
Alberta's oil sands extraction operations present underdeveloped demand for hydraulic cylinder remanufacturing, with capital discipline among operators extending fleet cycles beyond original depreciation schedules. Environment and Climate Change Canada regulates non-road diesel emissions through aligned standards with EPA Tier 4 Final requirements. Fort McMurray and Edmonton host the principal rebuild capacity serving Athabasca oil sands operations, with component logistics constrained by winter road access limitations.
South Africa
Platinum belt underground mining and Mpumalanga coal operations generate sustained demand for hard-rock component restoration, with core scarcity in engine blocks creating supply bottlenecks for regional rebuilders. The Department of Mineral Resources and Energy enforces equipment safety certifications that intersect with remanufacturing quality standards. Rustenburg and Witbank concentrate the country's rebuild infrastructure, serving deep-level platinum and gold operations with limited surface logistics alternatives.
China
Inner Mongolia coal mining and Shanxi province operations drive procurement of certified rebuild programs as domestic fleet age accelerates replacement demand. The Ministry of Ecology and Environment governs cross-border trade in remanufactured equipment through compliance requirements that create pathways for certified foreign rebuilders. Taiyuan and Ordos host state-backed remanufacturing industrial parks, with component restoration capacity expanding to serve state-owned mining enterprise maintenance contracts.
Mining Remanufacturing Components Market Vendor Landscape
Listed leaders compete with private specialists across certification tier and geographic coverage, with market structure consolidating around ISO 14001-qualified rebuild capacity as environmental compliance becomes a non-negotiable procurement filter. Three strategic archetypes dominate: OEM-captive rebuilders controlling authorized dealer networks, independent specialists capturing mid-tier refurbishment demand, and hybrid additive-subtractive technology integrators. Competitive moves concentrate on M&A to secure core supply pipelines and strategic partnerships to embed carbon-footprint documentation into procurement scorecards.
Within the OEM-captive tier, Caterpillar and Komatsu exemplify divergent approaches to channel control, with the former leveraging global dealer networks and the latter anchoring position through captive rebuild facilities tied to original equipment specifications. Sandvik occupies a position within hard-rock mining specialization, sustaining premium positioning through proprietary metallurgical process differentiation. These three companies represent the spectrum of competitive positioning available to scale players: network density, vertical integration depth, and technical specialization.
| Leading Market Players |
|---|
| Liebherr |
| Atlas Copco |
| Caterpillar |
| Sandvik |
| Volvo Construction Equipment |
| Komatsu |
| Epiroc |
| Metso |
| Hitachi Construction Machinery |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at ISO 14001-certified rebuild facilities in Western Australia and South Africa concentrates pricing power among qualified suppliers while setting cost floors that independent shops struggle to match. Tier-one mining operators in the Pilbara iron ore belt absorb premium pricing for documented carbon footprint reduction, whereas mid-tier quarrying operations gravitate toward uncertified refurbishment alternatives.
Pricing Analysis
Certification level creates the primary spread between OEM-authorized rebuild programs and independent shop offerings. Three-tier pricing structure across certified premium, standard refurbishment, and economy repair levels stratifies the market, with EPA Tier 4 Final compliance adding fixed-cost premiums to engine restoration. Pricing pressure stems from core scarcity in large-displacement diesel blocks, which tightens margins for rebuilders outside Australia and South Africa. Price sensitivity concentrates among aggregate quarrying operators with mid-life equipment cycles, while iron ore majors in Western Australia prioritize lifecycle emissions documentation over unit cost minimization.
Supply Chain Analysis
Inventory lead times for high-quality donor cores stretch 90-180 days for engine blocks, compressing working capital cycles for independent rebuilders. Supply concentrates in Australia, South Africa, and the United States, with geographic clustering of certified rebuild capacity around Perth, Rustenburg, and Gillette. Raw material dependencies include nickel and cobalt alloys for additive repair processes, high-grade steel forgings for transmission gearsets, and REACH-compliant coating chemistry for hydraulic cylinder restoration. Single-source vulnerability runs through proprietary metallurgical process suppliers serving hard-rock mining applications. Distribution runs through OEM dealer networks for certified programs and regional jobbers for independent refurbishment channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against new-unit procurement economics as logistics costs compress and OEM distribution networks expand into remote mining territories.
For Market Incumbents: Compound channel control through captive core supply pipelines in Australia's Pilbara region and Alberta's oil sands, where fleet aging sustains replacement demand. Deepen backward integration into surface engineering chemistry to offset REACH compliance cost inflation. Prioritize carbon-footprint documentation integration into procurement scorecards to defend against emerging independent shops with ISO 14001 certification. For New Entrants and Emerging Players: Anchor in hydraulic cylinder remanufacturing for Canadian oil sands operations, where capital discipline among operators extends fleet cycles beyond original depreciation schedules and certified rebuild capacity remains underdeveloped. Target mid-tier metal mining operations in China's Shanxi province as MEE cross-border harmonization creates pathways for foreign-certified rebuilders. Lead with 3D printing-CNC hybrid workflows to differentiate turnaround speed against established CNC-only competitors. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors additive-subtractive hybrid integrators with proprietary metallurgical capabilities over pure-play machining shops. Five-to-ten year viability hinges on carbon-border adjustment mechanism evolution and right-to-repair legislative momentum that could unlock independent channel share. Acquisition targets should demonstrate ISO 14001 certification progress and established core supply relationships in Australia or South Africa. Monitor EPA enforcement intensity on non-road diesel emissions as the critical inflection signal for certified rebuild program expansion.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 14001 Certification Investment | Environmental management certification unlocks tier-one mining procurement filters in Western Australia. |
| Core Supply Pipeline Acquisition | Donor engine block sourcing in South Africa and Australia reduces input volatility for rebuild programs. |
| 3D Printing-CNC Hybrid Deployment | Additive-subtractive workflows compress turnaround for previously unrepairable casting defects. |
| Carbon Footprint Documentation Integration | Lifecycle emissions data embedding displaces price-only tender evaluation for rotating components. |
| REACH-Compliant Surface Engineering Retooling | Trivalent chromium alternatives maintain hydraulic cylinder durability for EU-facing mining markets. |
Methodological Framework
Initial hypotheses were tested against primary input from mining maintenance directors, OEM aftermarket service heads, independent rebuilder operations managers, and procurement officers at tier-one iron ore operators and refined through secondary validation. Mining equipment trade association publications, EPA enforcement action databases, customs records for remanufactured component imports, and ISO certification registry data provided foundational triangulation. Bottom-up segment sizing across component types and service tiers was reconciled with top-down market value estimates derived from OEM disclosed aftermarket revenue patterns.
Variance decomposition across component type, service tier, end-use industry, and technology adoption curves structured the analytical framework over the projection horizon. CAGRs were derived from fitted growth curves anchored to fleet age demographics, replacement cycle extension patterns, and regulatory compliance deadline clustering. Modeled inputs included Pilbara iron ore production forecasts, Canadian oil sands capital expenditure intentions, and EPA Tier 4 Final enforcement trajectory assumptions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and fleet age assumptions; material deviation in carbon-border adjustment implementation or right-to-repair legislative outcomes would warrant model refresh. Specific risk factors include core supply disruption from mining production curtailments, additive manufacturing material cost volatility, and certification audit backlog delays. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Drilling Rigs Market
Mining Equipment
Mining Tester Market
Mining Equipment
Crawler Drilling Machine Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Global Automated Mining Equipment Market
Mining Equipment
Mining Shovel Market
Mining Equipment
Mine Hoisting Systems Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
Rock Duster Market
Mining Equipment
Mining Machinery Battery Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Mechanical Mine Clearance System Market