
 Atopic Dermatitis Market | 2026-2036
Atopic Dermatitis Market Size, Share, and Industry Trends Forecast 2026-2036
Atopic Dermatitis Market Intelligence
Multi-sourced biologic supply chains is broadening access to advanced atopic dermatitis therapies across major markets. Sanofi leverages its established immunology infrastructure to sustain manufacturing scale for IL-13 targeting agents. AbbVie Inc. anchors its position through deep R&D investment in JAK-selective pathways. Regeneron Pharmaceuticals Inc. differentiates via technology leadership in monoclonal antibody co-development models.
Atopic dermatitis constitutes a chronic inflammatory skin disorder characterized by epidermal barrier dysfunction, T-helper-2 immune skewing, and elevated serum IgE levels, with primary commercial purpose centered on symptom suppression and flare prevention. Biologics command the highest margin pools among product types due to targeted mechanism specificity and premium positioning. Topical delivery dominates volume throughput across patient segments, though injectable biologics capture disproportionate value concentration in severe disease management. Pediatric patients represent a structurally underserved end-user segment with limited approved options relative to adult populations.
FDA, EMA, and PMDA frameworks collectively shape clinical trial endpoints, labeling requirements, and post-market surveillance obligations for atopic dermatitis therapeutics, with pediatric study mandates particularly influencing development timelines. REACH and EU MDR compliance adds formulation chemistry and device- combination complexity for topical products entering European markets. Stakeholders must monitor evolving biosimilar entry dynamics and payer consolidation effects on access contracting.
Market Dynamics
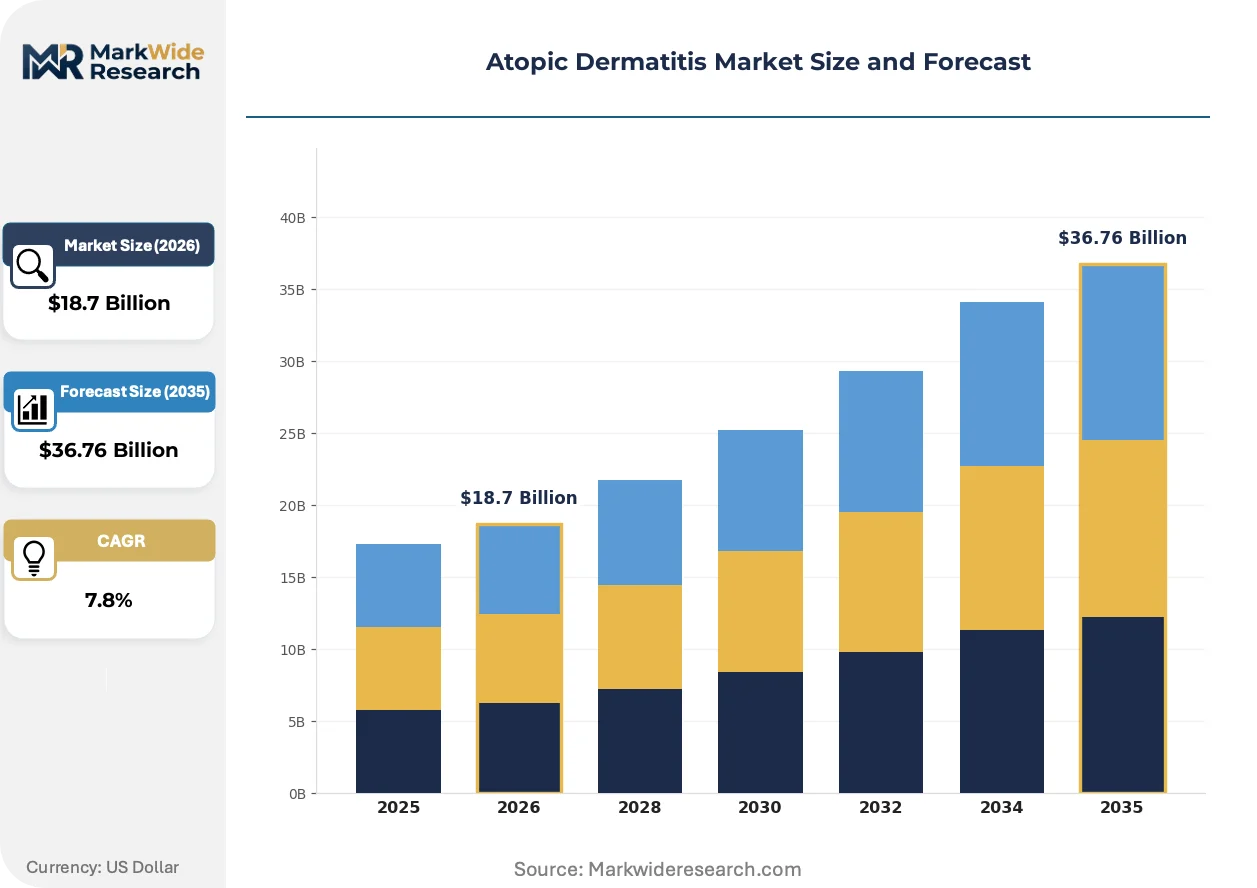
The atopic dermatitis market pivots on biologic therapy penetration into moderate-to-severe patient segments, with reimbursement arbitrage between public and private payers determining prescribing velocity across treatment settings.
Growth Catalysts
- Pediatric indication expansion:FDA and EMA mandates for juvenile study inclusion have matured into approved labels for biologics in patients aged six months and older, unlocking previously inaccessible volume pools.
- Topical JAK inhibitor portfolio development:Formulation chemistry advances are enabling non-steroidal chronic maintenance protocols that dermatology clinics prefer for long-term patient retention.
- German reimbursement maturation:The G-BA's structured benefit assessment pathways for novel therapeutics have compressed market access timelines relative to other European markets.
Market Restraints
- Biologic manufacturing concentration:Single-source dependence on mammalian cell culture facilities in Switzerland and Ireland creates supply vulnerability for IL-4/IL-13 targeting agents.
- Topical corticosteroid substitution:Generics and compounded pharmacy alternatives retain substantial share in mild-to-moderate disease management, compressing branded pricing power.
- EMA MDR compliance burden:Device-combination product requirements for topical delivery systems have extended regulatory timelines by 18-24 months for European market entry.
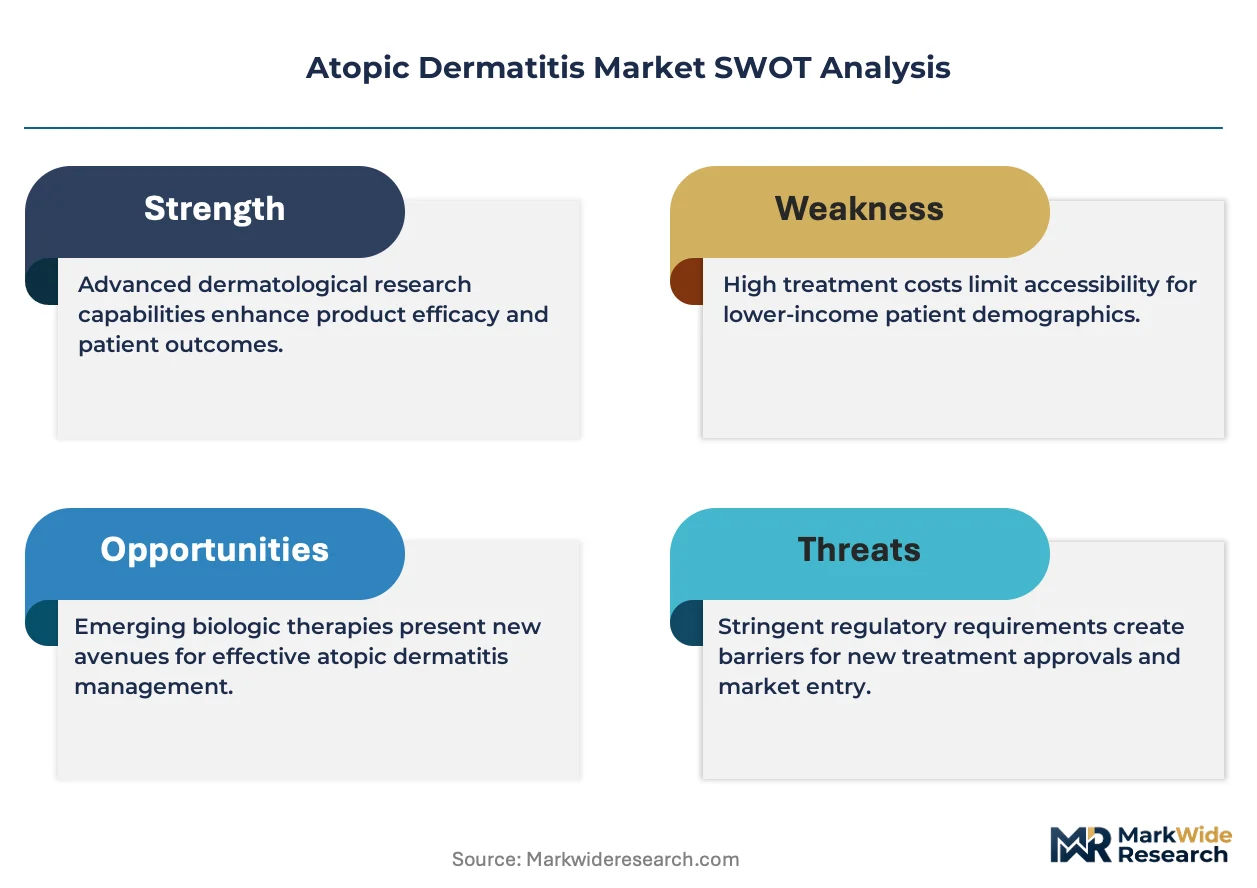
Strategic Opportunities
- Japan's severe disease segment:PMDA's streamlined review pathway for pediatric rare diseases positions the market for accelerated biologic uptake in refractory populations.
- Telemedicine-integrated prescribing:Remote dermatology platforms are creating direct-to-patient channels that bypass traditional clinic gatekeeping for maintenance therapy refills.
- Barrier repair-corticosteroid convergence:Fixed-dose combination formulations addressing both inflammation and epidermal dysfunction represent unoccupied positioning space.
Industry Challenges
- Specialized dermatology nursing shortages:Biologic administration training requirements exceed available injection-certified clinical staff in community practice settings.
- Legacy steroid-sparing protocol integration:Electronic health record systems require substantial reconfiguration to accommodate step-up/step-down algorithms that biologic eligibility demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atopic Dermatitis Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Calcineurin Inhibitors, PDE4 Inhibitors, Biologics Delivery Mode: Topical, Injectable, Systemic, Oral End User: Pediatric Patients, Adult Patients, Hospitals, Dermatology Clinics Application: Chronic Management, Acute Flare Treatment, Skin Care, Patient Education |
| Companies Covered | Sanofi, AbbVie Inc., Pfizer Inc., Regeneron Pharmaceuticals Inc., LEO Pharma, Novartis AG, Incyte Corporation, Galderma Laboratories, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atopic Dermatitis Market Strategic Shifts & Innovations
Atopic dermatitis therapeutics are converging on precision immunomodulation, with formulation science and diagnostic stratification advancing in parallel to enable individualized treatment sequencing.
Targeted cytokine pathway inhibition is consolidating clinical practice around IL-4Rα and IL-13 antagonists for moderate-to-severe disease. Dermatology clinics in the United States and Germany are adopting these agents as first-line systemic options within twelve months of diagnosis. This consolidation is compressing conventional immunosuppressant utilization and reshaping hospital formulary placement criteria.
REACH and EU MDR frameworks are tightening post-market surveillance obligations for topical products containing novel chemical entities. Manufacturers must now submit extended safety data packages for device-combination presentations such as metered-dose foam applicators. European dermatology clinics are responding by centralizing high-cost biologic prescribing within hospital outpatient departments to satisfy pharmacovigilance reporting requirements.
Patient-driven treatment switching is accelerating as digital health platforms enable real-time symptom tracking and telemedicine consultation. Direct-to-consumer channels are displacing traditional pharmacy fulfillment for maintenance topicals in urban United States markets. This behavioral shift concentrates most visibly in millennial patient cohorts who prioritize convenience over established prescriber relationships.
Atopic Dermatitis Market Segmentation
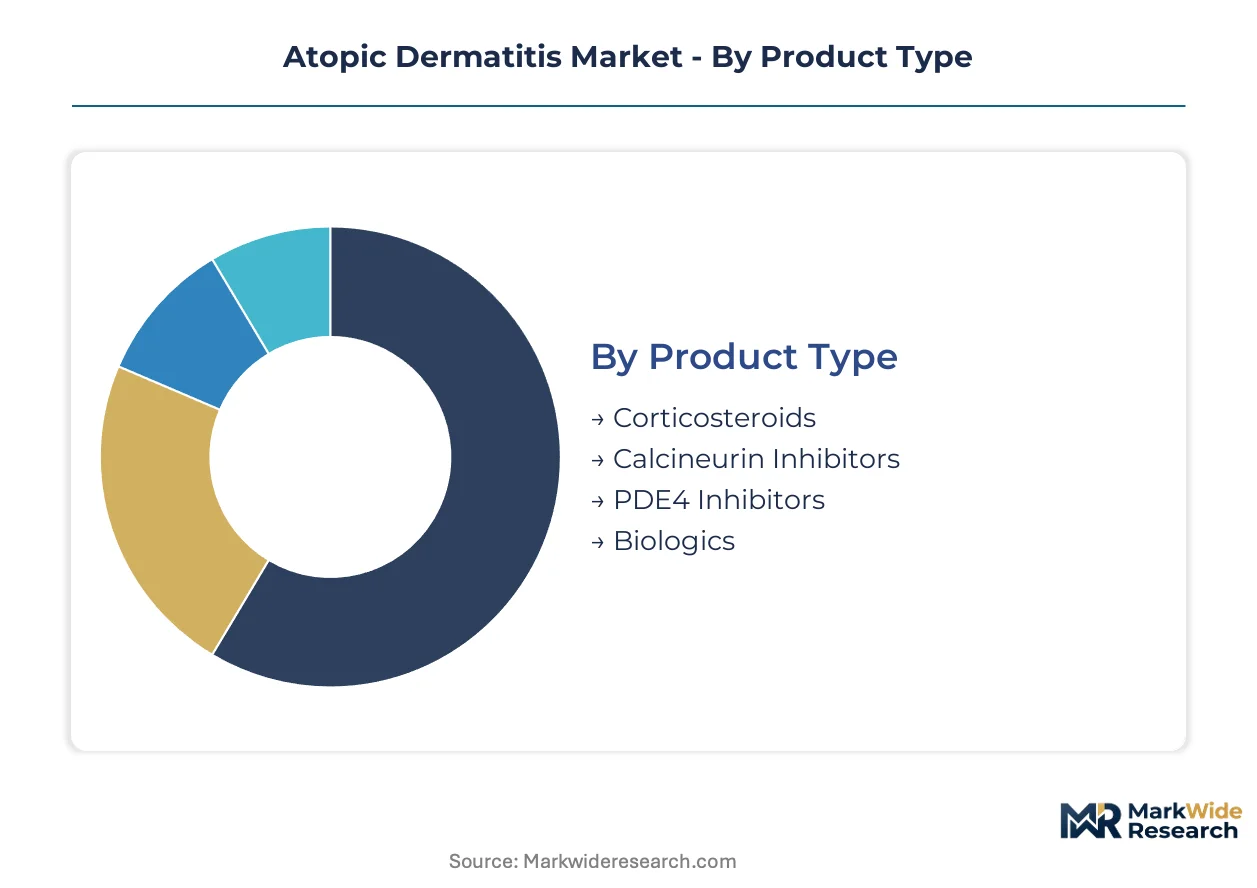
Atopic dermatitis therapeutics fragment across mechanism class, delivery format, and care setting in ways that determine margin capture and access strategy. Manufacturers must align pipeline investments with where prescribing authority and reimbursement velocity concentrate.
Product Type:
Standalone monotherapies dominate mild-to-moderate disease management, while biologics operate as embedded systemic anchors within combination protocols for severe populations.
- Biologics:Engineered monoclonal antibodies targeting IL-4Rα and IL-13 cytokine pathways deliver targeted immunomodulation with sustained dosing intervals. Demand concentrates in German hospital outpatient departments and United States academic medical centers where prior authorization infrastructure supports premium reimbursement. Pediatric indication expansion is compressing time-to-treatment initiation versus conventional immunosuppressants.
- Corticosteroids:Synthetic glucocorticoid formulations across potency classes provide rapid anti-inflammatory suppression for acute flares. Volume concentrates in community pharmacy channels and primary care prescribing across India and Brazil where cost sensitivity shapes formulary placement. Generic substitution and compounding pharmacy competition erode branded pricing power in mild disease segments.
- Calcineurin Inhibitors:Macrolactam derivatives tacrolimus and pimecrolimus offer steroid-sparing maintenance for sensitive skin areas.
- PDE4 Inhibitors:Small-molecule phosphodiesterase-4 antagonists enable non-steroidal chronic management with favorable safety profiles for long-term application.
Volume placements concentrate in corticosteroids; the faster expansion belongs to biologics.
Delivery Mode:
Route of administration determines patient autonomy, adherence architecture, and the clinical settings where prescribing decisions occur.
- Topical:Cream, ointment, and foam vehicles enable direct cutaneous application with minimized systemic exposure. Demand concentrates in United States retail pharmacy and direct-to-consumer channels where millennial patients prioritize convenience-driven refill automation. REACH and EU MDR compliance requirements for device-combination products have extended European regulatory timelines.
- Injectable:Subcutaneous and intravenous biologic administration requires specialized clinical infrastructure and cold-chain logistics. Volume concentrates in hospital outpatient departments across Germany and Japan where pharmacovigilance reporting obligations and reimbursement bundling create site-of-care stickiness. Nursing certification requirements constrain community practice penetration.
- Oral:Systemic small-molecule JAK inhibitors enable patient-administered chronic suppression without injection burden.
- Systemic:Conventional immunosuppressant protocols retain positioning for refractory cases where biologic access is delayed.
Prescription volume concentrates in topical formats; injectable delivery is climbing the fastest in value contribution.
End User:
Patient life-stage and care setting create divergent efficacy, safety, and access requirements that reshape product development priorities.
- Adult Patients:The largest addressable population spans mild intermittent disease through severe refractory cases requiring systemic intervention. Demand concentrates in United States dermatology clinics and telemedicine platforms where step-up treatment algorithms and prior authorization navigation determine therapy selection. Biologic penetration is compressing conventional immunosuppressant utilization within twelve months of diagnosis.
- Pediatric Patients:Patients aged six months through adolescence represent a structurally underserved segment with limited approved therapeutic options relative to disease prevalence. Volume concentrates in academic medical centers across Germany and Japan where FDA and PMDA pediatric study mandates have matured into approved biologic labels. Caregiver-administered topical regimens dominate maintenance management.
- Dermatology Clinics:Specialized outpatient settings concentrate biologic prescribing and complex case management.
- Hospitals:Inpatient and emergency departments manage acute severe flares and secondary infection complications.
Adult populations anchor current volume; pediatric indication expansion is gaining share fastest as regulatory pathways mature.
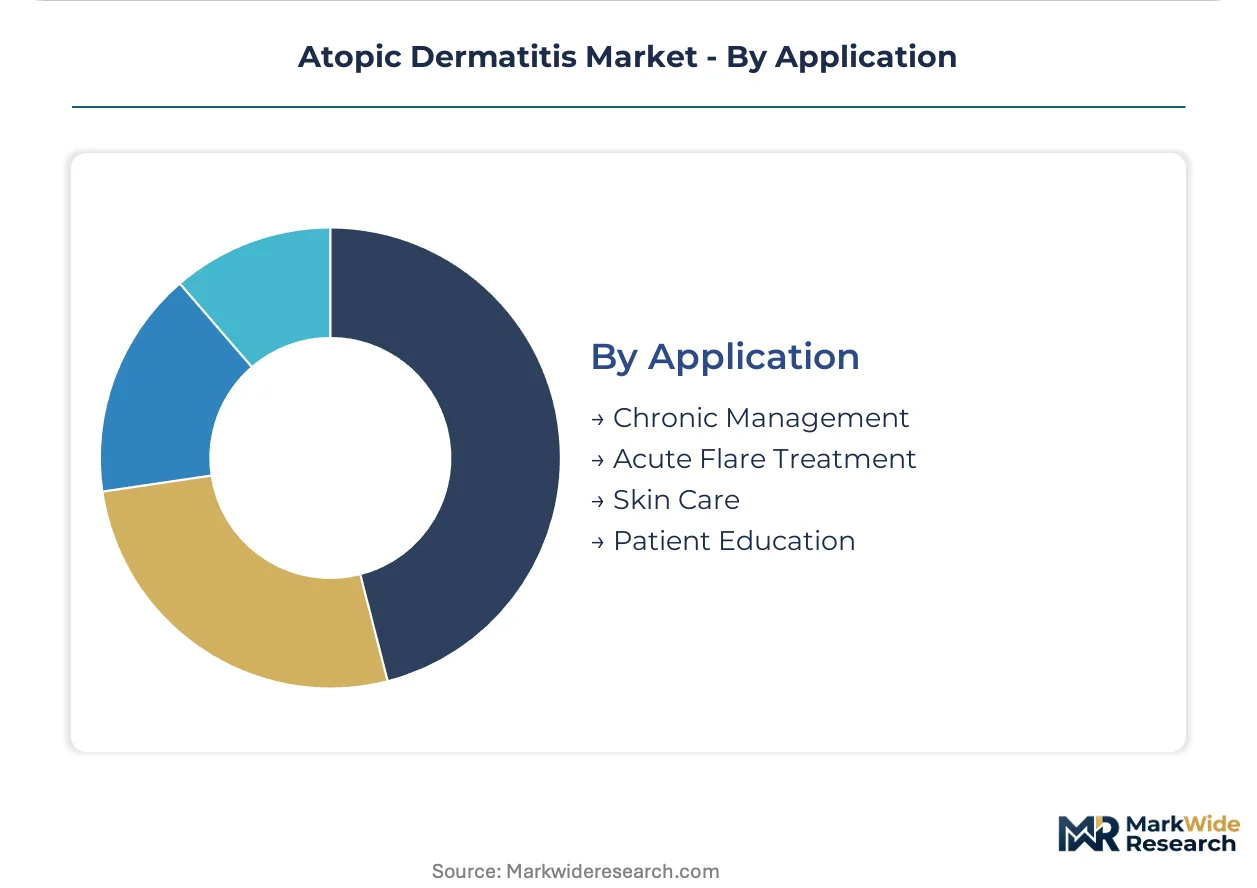
Application:
Clinical purpose determines dosing strategy, duration, and the economic models that govern reimbursement and patient cost-sharing.
- Chronic Management:Long-term maintenance protocols aim to sustain disease control, minimize flare frequency, and preserve quality of life. Demand concentrates in German statutory health insurance and United States Medicare Part D where structured benefit assessment pathways and formulary tier placement shape access. Non-steroidal topical options are displacing corticosteroid dependence for extended maintenance.
- Acute Flare Treatment:Short-term intensive intervention targets rapid symptom suppression during disease exacerbation. Volume concentrates in primary care and urgent care settings across India and United States retail clinic networks where prescribing velocity favors familiar generic corticosteroid options. Patient-driven switching through digital platforms is accelerating treatment-seeking behavior.
- Skin Care:Adjunctive barrier repair and emollient protocols support epidermal function restoration.
- Patient Education:Structured counseling on trigger avoidance and application technique improves adherence outcomes.
Chronic management captures the dominant volume share; acute flare protocols show the steepest expansion trajectory as digital health platforms compress time-to-treatment initiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for advanced atopic dermatitis therapeutics concentrates in markets with mature reimbursement infrastructure and established biologic prescribing pathways. Germany and the United States anchor volume due to structured prior authorization systems and hospital outpatient consolidation. Japan and emerging markets in Asia-Pacific represent acceleration vectors as regulatory frameworks mature.
United States
Dermatology clinics across the United States are expanding biologic adoption for moderate-to-severe patients within twelve months of diagnosis. FDA guidance on topical JAK inhibitors is reshaping product development pipelines and labeling requirements. Academic medical centers in Boston and the Research Triangle concentrate pediatric indication trials and pharmacovigilance reporting infrastructure.
Germany
The G-BA's structured benefit assessment pathways have compressed market access timelines for novel therapeutics relative to other European markets. EMA MDR compliance requirements for device-combination topical products extend regulatory timelines by 18-24 months. Hospital outpatient departments in Berlin and Munich centralize high-cost biologic prescribing to satisfy pharmacovigilance obligations.
Japan
PMDA's streamlined review pathway for pediatric rare diseases positions the severe disease segment for accelerated biologic uptake in refractory populations. METI industrial policy supports domestic manufacturing scale for monoclonal antibody production. The Kanto region around Tokyo concentrates specialist dermatology nursing capacity and injection-certified clinical staff training programs.
United Kingdom
NICE technology appraisals determine formulary placement and reimbursement velocity for biologic therapies across NHS trusts. MHRA post-Brexit regulatory autonomy enables accelerated approval pathways for innovative modalities. The Greater Manchester and London health systems pilot telemedicine-integrated prescribing models that bypass traditional clinic gatekeeping.
India
Primary care prescribing of generic corticosteroids dominates mild-to-moderate disease management due to cost sensitivity and limited prior authorization infrastructure. CDSCO accelerated approval pathways for orphan indications are expanding access to imported biologics in tier-1 cities. Mumbai and Delhi-NCR clusters concentrate dermatology specialist capacity and compounding pharmacy networks.
Atopic Dermatitis Market Key Industry Players
Portfolio diversification dominates the current landscape as incumbents balance biologic manufacturing scale with topical formulation development. The market structure consolidates around immunology-focused pharmaceutical conglomerates with established mammalian cell culture infrastructure and dermatology sales organizations. Three archetypes define competitive positioning: cytokine pathway specialists with antibody co-development capabilities, JAK-selective small-molecule developers with formulation chemistry depth, and broad immunology players leveraging cross-indication regulatory economies. M&A activity targets pediatric indication portfolios and device-combination topical assets, while strategic partnerships concentrate on telemedicine platform integration.
Among the cytokine pathway specialists, Sanofi and Regeneron Pharmaceuticals Inc. exemplify the monoclonal antibody co-development model, with the former anchoring manufacturing scale for IL-13 targeting agents. AbbVie Inc. occupies a distinct position within the JAK-selective tier, representing deep R&D investment in oral small-molecule pathways. These three entities collectively illustrate how mechanism-specific expertise, rather than geographic diversification, determines margin capture in moderate-to-severe disease management.
| Leading Market Players |
|---|
| Sanofi |
| AbbVie Inc. |
| Pfizer Inc. |
| Regeneron Pharmaceuticals Inc. |
| LEO Pharma |
| Novartis AG |
| Incyte Corporation |
| Galderma Laboratories |
| Eli Lilly and Company |
| Others |
Cost & Logistics Intelligence
Mammalian cell culture media costs cascade through biologics manufacturing into three distinct pricing tiers across the atopic dermatitis market. High-grade fetal bovine serum price volatility feeds directly into IL-4Rα and IL-13 antibody production economics, compressing margins for single-source manufacturers while amplifying pricing power for vertically integrated immunology conglomerates. The concentration of active pharmaceutical ingredient synthesis in Switzerland and Ireland creates geographic cost differentials that stratify end-product positioning.
Pricing Analysis
Volume concentrates in generic corticosteroids while margin pools accrue to biologics. Three-tier pricing structure across premium, standard, and economy levels separates branded biologics from JAK inhibitor small molecules and commodity topical generics. Price differentiation stems from FDA pediatric indication status and G-BA benefit assessment tier placement. Pricing pressure stems from German statutory health insurance reference pricing mechanisms. Primary care prescribers in India and Brazil exhibit highest price sensitivity; United States academic medical centers demonstrate lowest sensitivity due to prior authorization infrastructure.
Supply Chain Analysis
Direct-to-patient channels handle maintenance topical demand while hospital outpatient departments manage biologic administration. Supply concentrates in Switzerland, Ireland, and the United States for monoclonal antibody drug substance production. Raw material dependencies include fetal bovine serum, single-use bioreactor bags, and cold-chain logistics packaging. Single-source vulnerability in mammalian cell culture capacity creates exposure to facility contamination events. Distribution runs through specialty pharmacy networks for injectables and retail pharmacy plus direct-to-consumer platforms for topical formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biologic manufacturing scale requirements are forcing consolidation as capital intensity exceeds mid-cap balance sheet capacity. EMA MDR compliance burdens and pediatric study mandates compound the pressure, eliminating subscale topical developers without device-combination expertise.
For Market Incumbents: Hedge biologic revenue concentration by acquiring JAK-selective small-molecule portfolios or topical formulation assets with pediatric labels. Sanofi and AbbVie Inc. demonstrate viable positioning through cross-mechanism diversification. Defensive moves should prioritize backward integration into mammalian cell culture capacity in Switzerland or Ireland to secure supply continuity against single-source risks.
For New Entrants and Emerging Players: Telemedicine platforms represent the most penetrable channel for maintenance topical penetration in United States urban markets. White-space targets include fixed-dose barrier repair-corticosteroid combinations and caregiver-administered pediatric formulations. Go-to-market execution should anchor on direct-to-consumer refill automation partnerships that bypass traditional dermatology clinic gatekeeping.
For Investors and Strategic Acquirers: Distressed-cycle entries favor JAK inhibitor developers with EMA submissions pending in Germany. Long-term viability across the projection horizon rests on regulatory approval velocity rather than manufacturing scale. Acquisition targets should demonstrate completed pediatric study enrollment. The signal to watch is FDA guidance evolution on topical JAK inhibitor safety labeling as inflection indicator for portfolio revaluation.
| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Indication Expansion | FDA and PMDA study mandates unlock volume pools in academic medical centers. |
| Device-Combination Topical Development | EMA MDR compliance for metered-dose foam applicators extends European market exclusivity. |
| Telemedicine Platform Integration | Remote prescribing channels capture millennial patient cohorts seeking convenience-driven refill automation. |
| Biologic Manufacturing Scale-Up | Mammalian cell culture capacity in Switzerland secures supply continuity for IL-13 targeting agents. |
| Reimbursement Strategy Optimization | G-BA structured benefit assessment pathways in Germany compress market access timelines. |
Research Approach
Document review covered FDA filings, EMA submissions, ClinicalTrials.gov records, and German G-BA benefit assessment documents, complemented by interviews with drug development executives, regulatory affairs leads, formulary directors, and payer access specialists. Secondary validation drew from hospital procurement databases, CMS Medicare Part D utilization data, and SEC 10-K immunology segment disclosures. Bottom-up patient population modeling and top-down pharmaceutical market sizing were triangulated to constrain estimate variance.
Segmentation outputs across mechanism class, delivery mode, patient life-stage, and regional regulatory cluster were generated through the analytical framework. CAGRs were derived from patient prevalence projections, biologic penetration curve assumptions, and pricing elasticity estimates across the projection horizon. Forecast inputs incorporated German statutory health insurance reimbursement velocity, PMDA pediatric rare disease pathway approval rates, and United States prior authorization approval timelines.
Caveats apply where FDA guidance evolution on topical JAK inhibitor safety, EMA MDR implementation delays, or biosimilar entry dynamics could materially shift the outlook. Forecasts reflect assumptions around pediatric indication expansion velocity and telemedicine regulatory permanence. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Necrotizing Fasciitis Market
Specialty Medicine
Chronic Myelogenous Leukemia Treatment Market
Specialty Medicine
Inflammatory Diseases Market
Specialty Medicine
Axial Spondyloarthritis Treatment Market
Specialty Medicine
Global Primary Angle-Closure Glaucoma Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Adenomyosis Market
Specialty Medicine
Latin America Bladder Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Japan Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Specialty Generics Market
Specialty Medicine
Fatty Liver Treatment Market