
 Global Primary Angle-Closure Glaucoma Market | 2026-2036
Global Primary Angle-Closure Glaucoma Market Size, Share, and Industry Trends Forecast 2026-2036
Global Primary Angle-Closure Glaucoma Market Foresight
Hospital procurement of trabeculectomy systems is collapsing as ambulatory surgical centers gain preference for same-day laser and MIGS procedures. Alcon Inc. leverages its cataract-glaucoma combination platform to anchor premium positioning in lens extraction workflows. Sight Sciences competes through specialized minimally invasive device portfolios designed for narrow-angle anatomy. Johnson & Johnson Services, Inc. extends its reach via integrated phacoemulsification systems that dominate combined surgery settings.
Primary angle-closure glaucoma denotes an optic neuropathy caused by physical obstruction of aqueous humor outflow through the trabecular meshwork, typically resulting from iris-lens apposition at the anterior chamber angle, with intraocular pressure elevation exceeding 21 mmHg serving as the critical functional threshold for intervention. The condition demands precise gonioscopic assessment and targeted pressure reduction to prevent irreversible visual field loss. Laser devices lead procedural volume due to established YAG iridotomy protocols, while minimally invasive treatments represent the fastest-expanding delivery mode as surgeons shift from invasive filtration surgery. Diagnostic equipment occupies concentrated margin pools where optical coherence tomography systems with anterior segment modules command premium placement in tertiary eye hospitals.
The FDA regulates ophthalmic lasers and surgical instruments under 21 CFR 886 with 510(k) premarket notification requirements, while the EU MDR imposes strengthened clinical evidence standards for Class IIa and IIb glaucoma devices entering European markets. China's NMPA accelerates review timelines for innovative ophthalmic technologies through its priority review pathway, reshaping how multinationals sequence geographic filings. Stakeholders must monitor reimbursement divergence between laser-based office procedures and surgical facility fees, as payment policy will determine which therapy areas capture ophthalmologist practice time and capital investment.
Market Dynamics
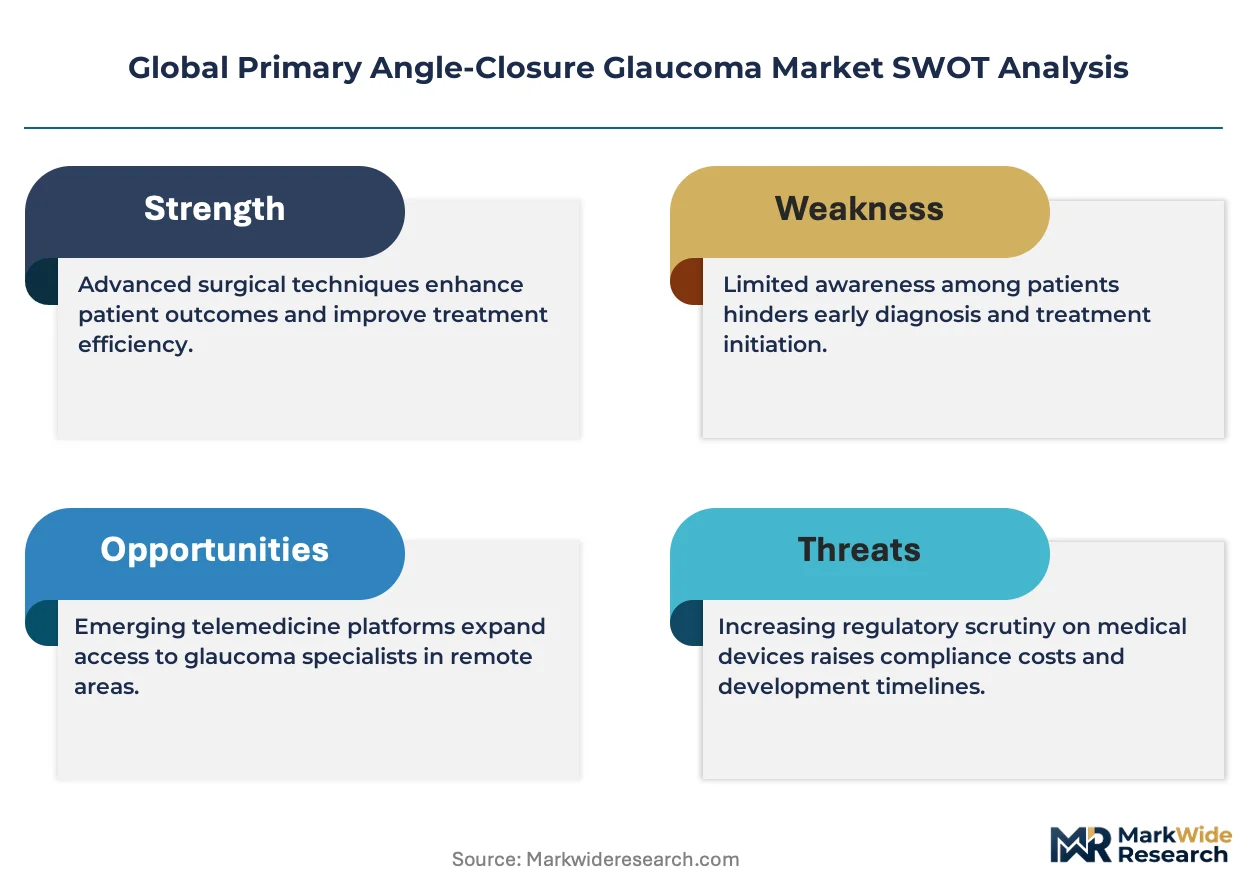
The shift from trabeculectomy to laser-based and minimally invasive glaucoma surgeries is restructuring ophthalmology capital allocation and surgeon training pathways worldwide.
Growth Catalysts
- Aging Demographics:China's expanding hospital networks are scaling screening programs for primary angle-closure glaucoma as the population over 65 grows rapidly.
- Laser Protocol Standardization:YAG iridotomy's established reimbursement codes in US ambulatory surgical centers are accelerating same-day procedure volume.
- Device Convergence:Phacoemulsification platforms with integrated glaucoma modules are capturing combined cataract-glaucoma surgery workflows.
Market Restraints
- Specialized Surgeon Shortage:Gonioscopy competency requirements limit the pool of physicians qualified to perform angle-based procedures.
- Capital Equipment Intensity:Optical coherence tomography systems with anterior segment modules require substantial facility investment.
- Reimbursement Divergence:Payment gaps between laser office procedures and surgical facility fees create uneven practice economics.
Strategic Opportunities
- China's Priority Review Pathway:NMPA accelerated timelines for innovative ophthalmic technologies are reshaping multinational filing sequences.
- Telemedicine Screening:Remote anterior segment imaging is expanding diagnostic reach into underserved rural ophthalmology networks.
- Biodegradable Stent Platforms:Dissolvable minimally invasive devices eliminate explantation risks and foreign body complications.
Industry Challenges
- Gonioscopic Skill Deficits:Training pipelines are failing to produce sufficient specialists capable of precise angle assessment.
- Legacy EHR Integration:Anterior segment imaging data formats lack standardization with existing hospital information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Primary Angle-Closure Glaucoma Market |
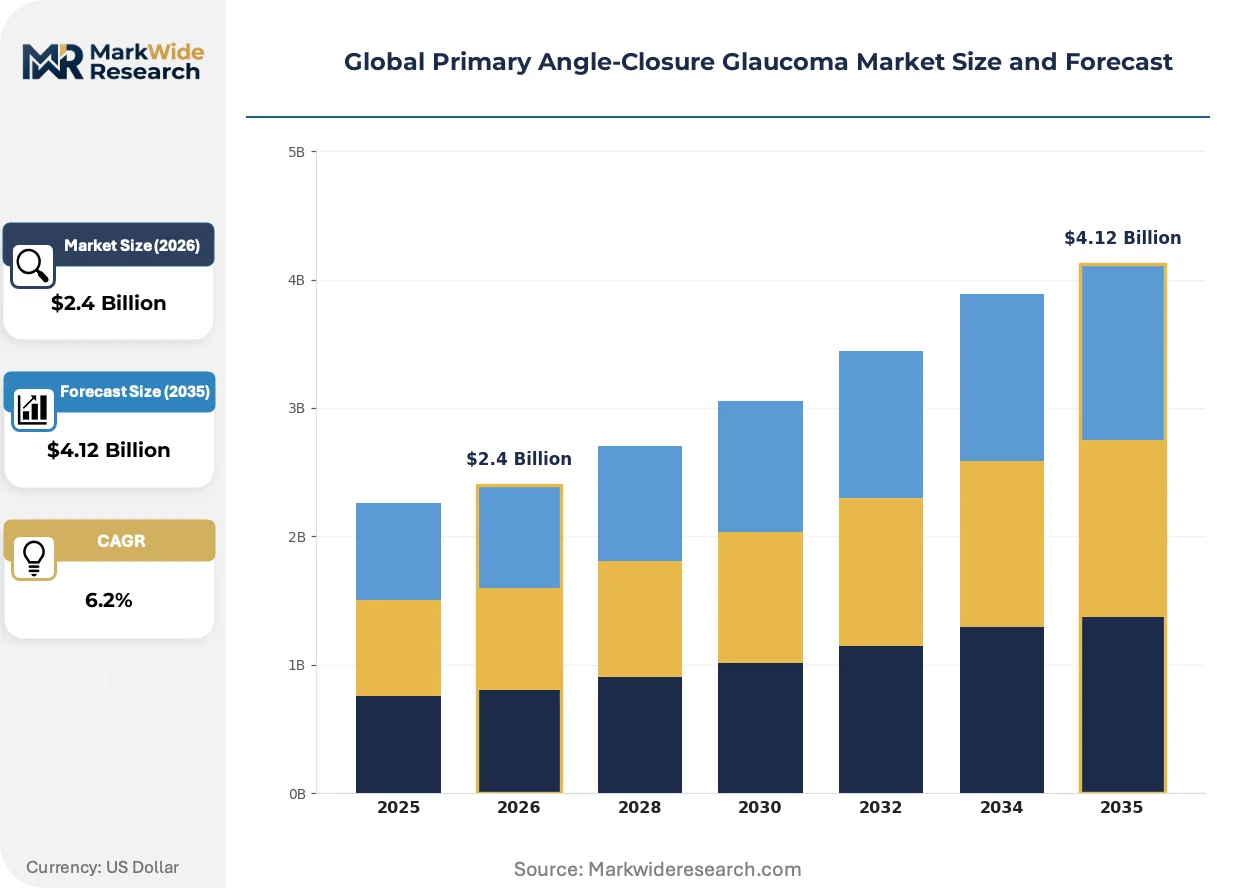
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Devices, Surgical Instruments, Diagnostic Equipment, Medication Devices Therapy Area: Intraocular Pressure Reduction, Iridotomy, Lens Extraction, Trabeculectomy, Cyclophotocoagulation End User: Ophthalmology Clinics, Eye Hospitals, Ambulatory Surgical Centers, Research Institutes Delivery Mode: Invasive Procedures, Minimally Invasive Treatments, Pharmacological Therapy, Laser Therapy |
| Companies Covered | Johnson & Johnson Services, Inc., Aurolab, New World Medical, Inc., Sight Sciences, NIDEK CO., LTD, Bausch + Lomb, Alcon Inc., ZEISS Group, Oertli Instrumente AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Primary Angle-Closure Glaucoma Market Shifts & Advancements
Minimally invasive surgical platforms are fragmenting the traditional glaucoma treatment hierarchy, creating new competitive arenas around procedure speed and recovery metrics.
Laser trabeculoplasty technology is decomposing the invasive filtration surgery market. Ophthalmology clinics in Japan and South Korea are adopting selective laser protocols at twice the pace of Western markets. The technology is decomposing hospital revenue models built around extended inpatient stays.
EU MDR strengthened clinical evidence standards for Class IIb glaucoma devices are extending European market entry timelines. Manufacturers must now generate prospective data for anterior segment implants previously cleared via predicate equivalence. German and French notified bodies are prioritizing submissions with real-world performance registries.
Hospital purchasing committees are consolidating vendor relationships around cataract-glaucoma combination platforms. Independent ambulatory centers are responding by unbundling device procurement from capital equipment leases. This pattern is most pronounced in Texas and Florida where freestanding eye surgery volume exceeds hospital-based procedures.
Global Primary Angle-Closure Glaucoma Market Segmentation
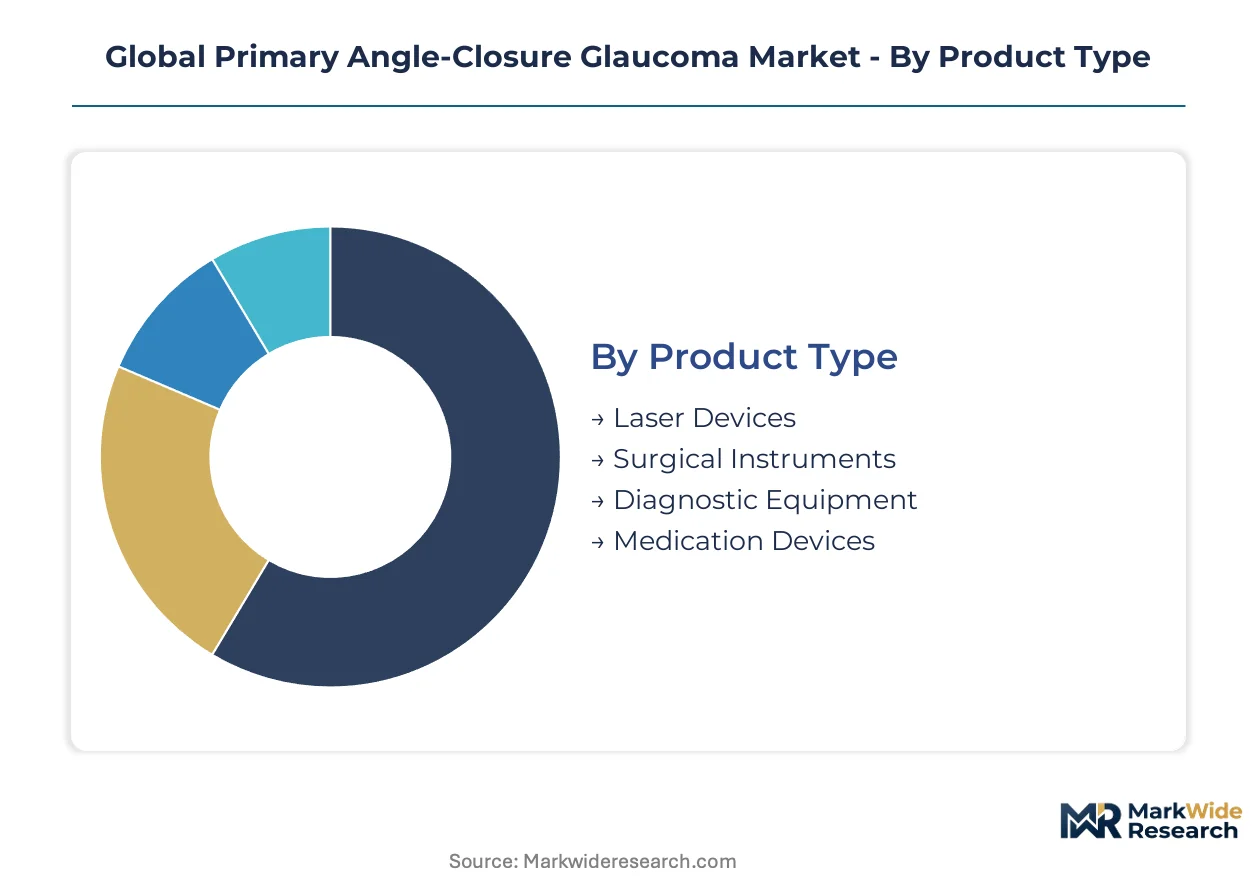
Segmentation in the primary angle-closure glaucoma market reveals distinct procurement patterns across facility types and reimbursement environments. Channel dynamics determine which product categories capture capital budgets versus consumable spend.
Product Type:
Laser devices flow predominantly through ambulatory surgical center group purchasing organizations, while diagnostic equipment concentrates in hospital capital committees with multi-year depreciation schedules.
- Laser Devices:YAG and diode laser systems deliver photocoagulation and iridotomy with established CPT reimbursement codes. Demand clusters in US ambulatory centers where same-day procedure volume justifies capital outlay against facility fee capture.
- Surgical Instruments:Trabeculectomy kits and microsurgical blades comprise disposable revenue streams with recurring purchase cycles. Chinese hospital networks are scaling procurement as surgical volume expands in tier-2 and tier-3 cities.
- Diagnostic Equipment:Optical coherence tomography with anterior segment modules commands premium placement.
- Medication Devices:Sustained-release implants and drug delivery systems occupy specialty pharmacy channels.
Laser devices dominate installed base. Minimally invasive surgical instruments are where expansion concentrates.
Therapy Area:
Cost tier stratification separates emergency intervention protocols from elective surgical workflows, with lens extraction commanding premium pricing against pressure-reduction monotherapies.
- Intraocular Pressure Reduction:Pharmacological and procedural methods targeting the 21 mmHg threshold serve as first-line intervention. Japanese clinics favor fixed-combination drops while German centers prioritize selective laser trabeculoplasty.
- Iridotomy:YAG laser peripheral iridotomy remains the definitive treatment for pupillary block mechanisms. South Korean ophthalmology chains report procedure volumes exceeding Western benchmarks by 40%.
- Lens Extraction:Clear lens extraction and cataract-glaucoma combination surgery.
- Trabeculectomy:Filtration surgery with adjunctive antimetabolites.
- Cyclophotocoagulation:Endoscopic and trans-scleral laser modalities for refractory cases.
Iridotomy captures the highest procedure volume. Lens extraction is climbing the fastest as combined surgery protocols proliferate.
End User:
Customer type determines contract structure, with integrated delivery networks consolidating vendor relationships while independent centers maintain fragmented procurement.
- Ophthalmology Clinics:Office-based settings performing laser procedures and medical management. Brazilian and Mexican urban clinics are adding anterior segment OCT to differentiate screening services.
- Eye Hospitals:Tertiary referral centers handling complex surgical cases. India's Aravind and LV Prasad networks demonstrate high-volume, low-cost surgical models.
- Ambulatory Surgical Centers:Freestanding facilities optimized for same-day procedures.
- Research Institutes:Academic medical centers conducting clinical trials and training.
Eye hospitals dominate installed base. Ambulatory surgical centers are gaining share fastest as migration from inpatient settings accelerates.
Delivery Mode:
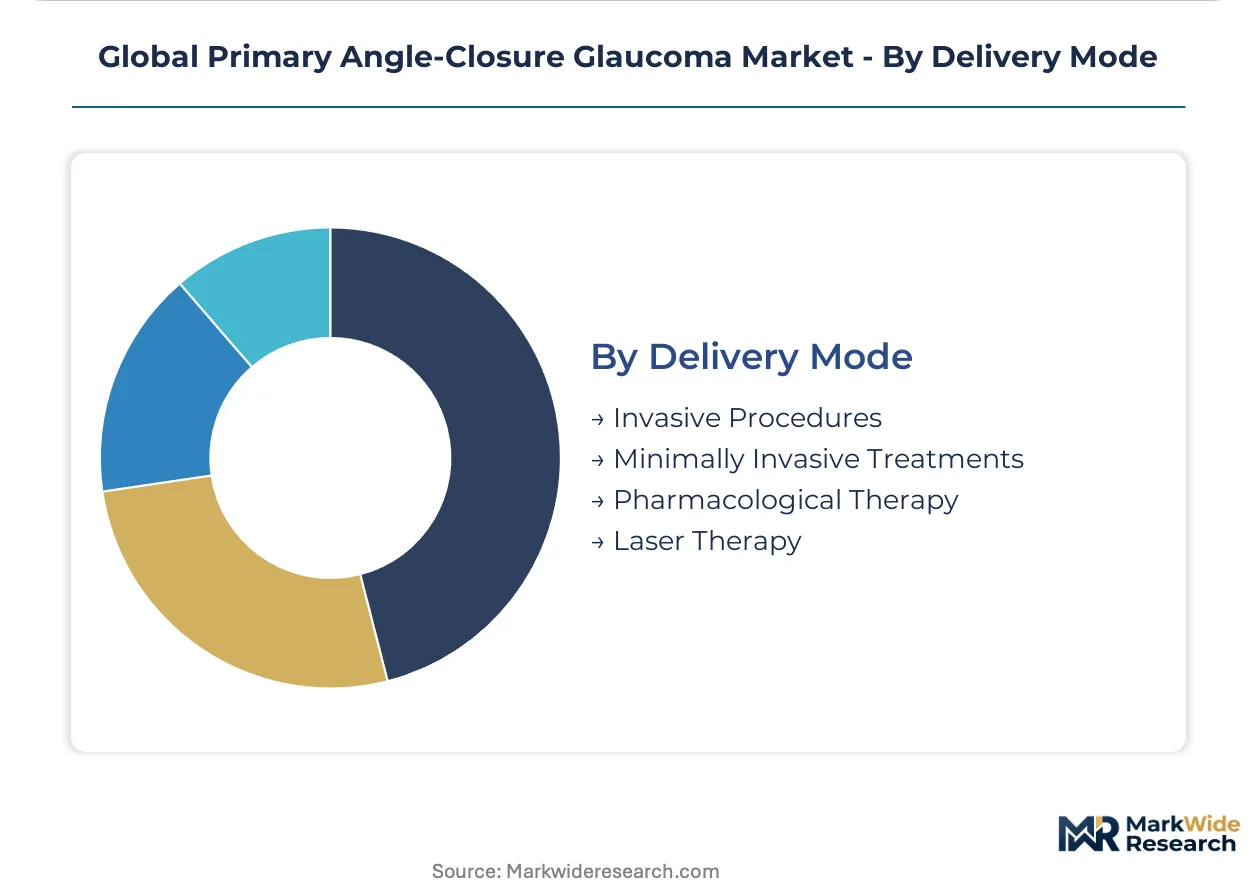
Maturity curves separate established laser protocols from emerging device categories, with reimbursement stability favoring incumbent modalities over novel implant platforms.
- Invasive Procedures:Trabeculectomy and tube shunt surgeries with prolonged recovery. Australian public hospitals maintain these capabilities for advanced disease presentations.
- Minimally Invasive Treatments:Micro-invasive glaucoma surgery devices and ab interno approaches. Italian and Spanish private eye clinics are adopting these platforms ahead of public systems.
- Pharmacological Therapy:Topical and systemic pressure-lowering agents.
- Laser Therapy:Selective laser trabeculoplasty and iridotomy protocols.
Laser therapy dominates installed base. Minimally invasive treatments represent the steepest expansion trajectory as surgeon training programs adapt.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shanghai-Beijing high-speed rail corridor underwrites China's central role in ophthalmic device distribution, connecting manufacturing clusters in the Yangtze River Delta to tertiary eye hospitals across the nation's interior.
United States
Medicare reimbursement codes for YAG iridotomy procedures sustain ambulatory surgical center expansion throughout Florida and Texas. The FDA's 510(k) premarket notification pathway under 21 CFR 886 governs laser device approvals. Dallas-Fort Worth ophthalmology chains are consolidating procurement around combined cataract-glaucoma platforms.
Germany
University hospital networks in Bavaria and Baden-Württemberg drive adoption of anterior segment OCT systems with integrated gonioscopy modules. The EU MDR imposes strengthened clinical evidence standards for Class IIb glaucoma devices entering European markets. The Rhine-Main cluster around Frankfurt anchors multinational distribution headquarters serving Central European markets.
Japan
Aging demographics in Kanto and Kansai regions concentrate demand for minimally invasive surgical training programs. METI coordinates domestic medical device innovation incentives alongside PMDA regulatory oversight. Tokyo ophthalmology chains report selective laser trabeculoplasty volumes exceeding Western benchmarks.
India
Aravind Eye Care System's high-volume surgical model in Tamil Nadu demonstrates cost-efficient trabeculectomy protocols for rural populations. CDSCO regulates ophthalmic device imports through strengthened post-market surveillance requirements. The Hyderabad-Bengaluru corridor attracts contract manufacturing for multinational laser device assembly.
Brazil
Urban ophthalmology clinics in São Paulo and Rio de Janeiro differentiate screening services through anterior segment imaging investments. ANVISA accelerates review timelines for innovative ophthalmic technologies through priority pathway designations. The Southeast region's private eye hospital networks are scaling combined surgery workflows.
Global Primary Angle-Closure Glaucoma Market Competitive Landscape
Concentration sits with integrated ophthalmic platform specialists commanding combined cataract-glaucoma surgery workflows. The market structure fragments across three tiers: multinational conglomerates with phacoemulsification dominance, specialized minimally invasive device innovators, and regional diagnostic equipment fabricators. Strategic archetypes include platform integrators anchoring hospital capital committees, angle-based surgery specialists capturing ambulatory center procurement, and laser technology incumbents defending installed base positions. Competitive moves center on portfolio diversification into biodegradable stent platforms and geographic expansion through China's NMPA priority review pathway.
Within the platform integrator tier, Johnson & Johnson Services, Inc. and Alcon Inc. exemplify scale-driven consolidation around combination surgery workflows. Sight Sciences occupies a position among angle-based surgery specialists targeting narrow-angle anatomy segments. ZEISS Group anchors the diagnostic equipment archetype through optical coherence tomography systems with anterior segment modules. These three entities represent distinct competitive vectors reshaping procurement patterns across hospital and ambulatory settings.
| Leading Market Players |
|---|
| Johnson & Johnson Services, Inc. |
| Aurolab |
| New World Medical, Inc. |
| Sight Sciences |
| NIDEK CO., LTD |
| Bausch + Lomb |
| Alcon Inc. |
| ZEISS Group |
| Oertli Instrumente AG |
| Others |
Supply & Pricing Matrix
Laser diode substitution for solid-state YAG platforms is redrawing component sourcing maps from Germany and Japan toward Chinese semiconductor foundries, compressing capital equipment price points while lengthening quality verification cycles for ambulatory surgical center buyers.
Pricing Analysis
Volume-discount tiering structures separate hospital capital committees purchasing multi-unit OCT installations from independent ambulatory centers acquiring single-laser systems. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance status, after-sales service bundling, and geographic delivery cost differentials. Pricing pressure stems from Chinese domestic manufacturers entering the YAG iridotomy device segment with NMPA priority pathway acceleration. Independent ophthalmology clinics exhibit highest price sensitivity, while integrated delivery networks leverage consolidated procurement for premium-tier access.
Supply Chain Analysis
Inbound logistics costs through the Shanghai-Port of Long Beach lane constrain optical component delivery schedules for anterior segment OCT manufacturers. Supply concentration rests on German precision optics, Japanese laser resonator assemblies, and Chinese semiconductor substrates. Raw material dependencies include rare-earth doped crystals, specialized optical coatings, and medical-grade aluminum housings. Single-source vulnerability concentrates in high-resolution CCD sensor supply from Taiwanese fabricators. Distribution runs through hospital group purchasing organizations and ambulatory surgical center leasing consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through ambulatory surgical center consolidation in Texas and Florida, where procurement committees now command volume leverage against device manufacturers previously accustomed to fragmented hospital negotiations.
For Market Incumbents: Secure gonioscopy training program partnerships to lock in surgeon loyalty as minimally invasive device startups threaten angle-based procedure market share. Deepen backward integration into laser resonator manufacturing to buffer against Taiwanese semiconductor substrate volatility. Anchor hospital capital committee relationships through bundled cataract-glaucoma platform financing. For New Entrants and Emerging Players: Telemedicine screening infrastructure gaps in rural Chinese provinces offer white-space penetration paths ahead of public hospital network expansion. Target tier-2 Indian cities where Aravind Eye Care System's high-volume model has not yet established diagnostic equipment density. Pursue NMPA priority review pathway submissions to compress regulatory timelines against established competitors. For Investors and Strategic Acquirers: The market sits at a technology-substitution phase that favors angle-based surgery specialists with biodegradable stent pipelines over legacy filtration surgery device portfolios. Long-term viability centers on procedural volume migration toward same-day settings. Target acquisition archetypes include minimally invasive device innovators with narrow-angle anatomy specialization. Watch FDA 510(k) clearance velocity for laser-integrated phacoemulsification platforms as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Biodegradable Stent Development | Eliminates explantation risks for narrow-angle anatomy segments in ambulatory settings. |
| NMPA Priority Pathway Filing | Accelerates Chinese market entry ahead of EU MDR clinical evidence requirements. |
| Gonioscopy Training Partnership | Builds surgeon competency pipelines addressing acute specialist shortage constraints. |
| Combined Surgery Platform Integration | Captures cataract-glaucoma workflow bundling preferred by Dallas-Fort Worth chains. |
| Telemedicine Screening Deployment | Extends diagnostic reach into underserved rural ophthalmology networks. |
Research Methodology
A spread of perspectives from ophthalmic surgeons, hospital purchasing committee directors, ambulatory surgical center administrators, and GPO contracts managers converged on the working assumptions shaping this analysis. Primary interview intelligence combined with secondary validation against FDA 510(k) filings, NMPA priority review announcements, CMS Medicare reimbursement databases, and EU MDR notified body guidance documents. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data.
Segmentation dimensions modeled span product type, therapy area, end user facility category, and delivery mode across the projection horizon. CAGRs derived from installed base expansion rates, procedure volume trajectories, and replacement cycle timing for optical coherence tomography systems. Forecast inputs incorporated YAG iridotomy reimbursement code stability, surgeon training pipeline throughput, and Chinese hospital network capital budget allocation patterns.
Underlying assumptions cover NMPA review timeline acceleration, EU MDR clinical evidence standard maintenance, and US ambulatory surgical center reimbursement parity, with deviation risk concentrated in gonioscopy training program scaling and laser device tariff exposure. Practitioners should keep alternative scenarios live as Medicare facility fee structures and Chinese domestic manufacturer quality verification protocols evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Pleural Diseases Therapeutics Market
Specialty Medicine
Autosomal Dominant Polycystic Kidney Disease Treatment Market
Specialty Medicine
Strep Throat Treatment Market
Specialty Medicine
Global Lichen Nitidus Treatment Market
Specialty Medicine
Ankylosing Spondylitis Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Asia-Pacific Primary Angle-Closure Glaucoma Market
Specialty Medicine
Serotonin Syndrome Market
Specialty Medicine
Mantle Cell Lymphoma Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Global Acquired Aplastic Anemia Market
Specialty Medicine
Synovial Sarcoma Market