
 Pharmaceuticals Preservative Market | 2026-2036
Pharmaceuticals Preservative Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceuticals Preservative Market Outlook
Specialty chemical producers in Germany is recalibrating output schedules to meet rising pharmaceutical-grade preservative orders. BASF SE leverages integrated feedstock access to control benzyl alcohol purity grades across European supply chains. Lonza Group Ltd. anchors its position through cGMP-certified manufacturing sites that service parenteral drug makers. Evonik Industries AG specializes in high-purity sorbic acid variants designed for ophthalmic and inhalant applications.
Pharmaceuticals preservatives are antimicrobial or antioxidant agents added to drug formulations at concentrations typically between 0.1% and 1.0% to prevent microbial proliferation and maintain chemical stability during shelf life. Parabens dominate liquid ophthalmic and topical preparations due to broad-spectrum efficacy against Gram-positive bacteria, though sorbic acid is displacing them in inhalant formulations where respiratory safety margins are narrower. Powder preservatives occupy the fastest-expanding formulation segment as lyophilized biologics and single-dose reconstitutable products gain share in hospital and research laboratory channels.
The FDA sets maximum allowable concentrations for thiomersal in vaccines and biologics, while EMA REACH restrictions limit certain paraben derivatives in dermal applications, forcing reformulation investments across oral medication and topical treatment portfolios. WHO pharmacopeial guidelines on antimicrobial effectiveness testing create harmonized benchmarks that determine market access for preservative suppliers serving multiple geographies. Stakeholders must monitor evolving EMA guidance on endocrine-disrupting chemical classifications, as reclassification of established preservatives would trigger immediate portfolio restructuring and qualification timelines for alternative chemistries.
Market Dynamics
Injectable drug manufacturers are consolidating preservative sourcing around multi-dose vial stability requirements, while FDA and EMA safety thresholds for paraben content force simultaneous reformulation toward benzyl alcohol and sorbic acid alternatives.
Growth Catalysts
- EMA REACH restrictions on paraben derivatives:These limitations accelerate reformulation investments across oral medication and topical treatment portfolios, creating replacement demand for alternative chemistries.
- Lyophilized biologics expansion:Powder preservatives capture fastest-expanding formulation segment as single-dose reconstitutable products gain share in hospital and research laboratory channels.
- Sterile drug production clusters:Concentrated manufacturing in the United States, Germany, and Japan sustains premium-grade preservative procurement volumes aligned with stringent pharmacopeial standards.
Market Restraints
- Feedstock purity volatility:Pharmaceutical-grade benzyl alcohol production depends on toluene oxidation pathways vulnerable to petrochemical input cost swings.
- cGMP certification concentration:Manufacturing sites capable of parenteral-grade output cluster in Western Europe and Japan, creating geographic supply risk for other regions.
- Respiratory safety margins:Sorbic acid displacement of parabens in inhalant formulations faces narrow therapeutic index constraints that limit concentration flexibility.
Strategic Opportunities
- Hospital pharmacy compounding:Underpenetrated institutional channels in India and Brazil present expansion vectors for preservative suppliers qualifying under WHO pharmacopeial guidelines.
- Ophthalmic preservative-free alternatives:Regulatory tailwinds from FDA guidance on contact lens solution safety create white space for oxidative stabilization technologies.
- Continuous manufacturing integration:Real-time release testing convergence with preservative dosing automation enables quality-by-design adoption among mid-scale generic injectable producers.
Industry Challenges
- Analytical method qualification timelines:Antimicrobial effectiveness testing under USP and EP standards requires 18-24 month validation cycles that compress product launch windows.
- Endocrine-disrupting chemical reclassification risk:EMA guidance evolution on preservative hazard categories threatens immediate portfolio restructuring and alternative chemistry qualification investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceuticals Preservative Market |
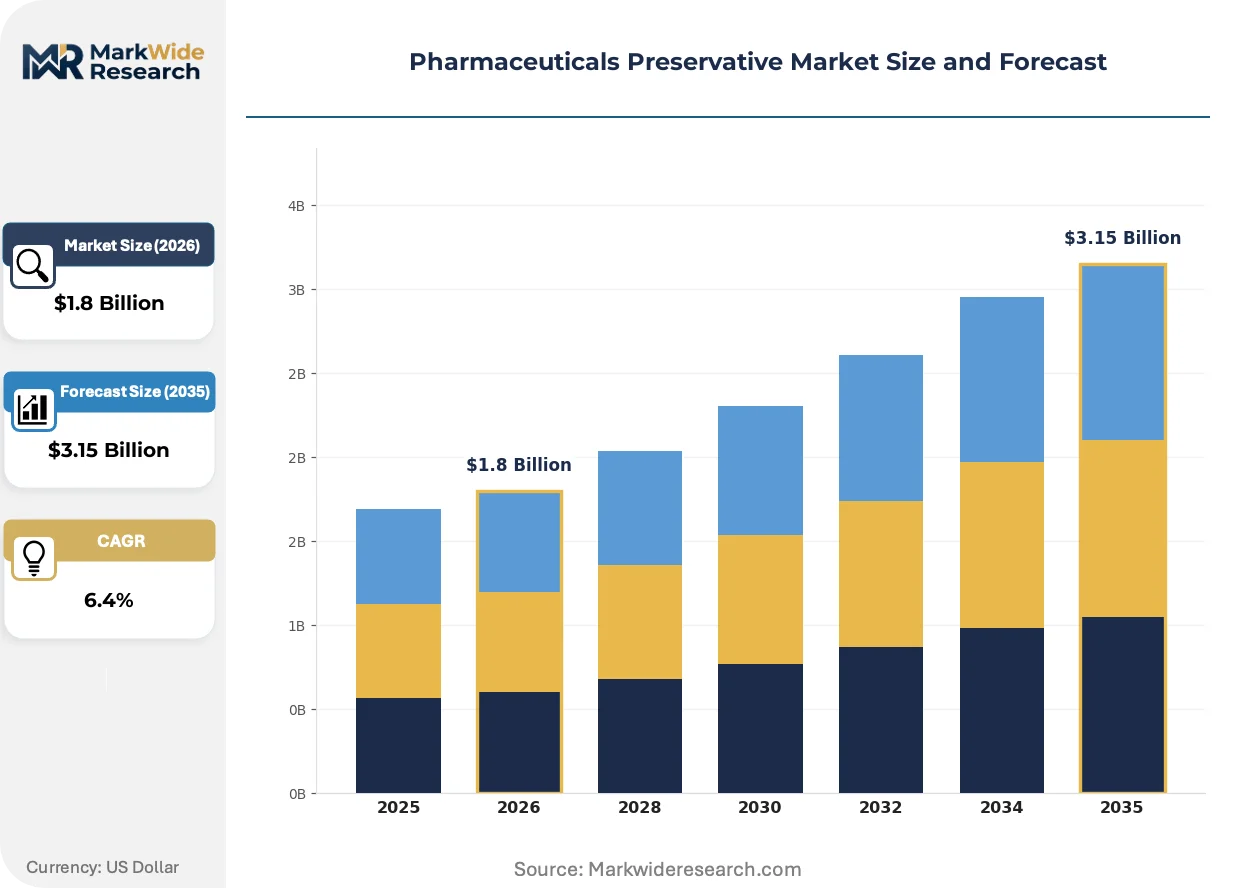
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Parabens, Benzyl Alcohol, Sorbic Acid, Thiomersal Formulation Type: Liquid, Powder, Cream, Gel End User: Pharmacies, Hospitals, Clinics, Research Laboratories Application: Injectable, Oral Medications, Topical Treatments, Inhalants |
| Companies Covered | Clariant AG, Evonik Industries AG, Lonza Group Ltd., Celanese Corporation, Akzo Nobel N.V., BASF SE, Eastman Chemical Company, DowDuPont, Lanxess AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceuticals Preservative Market Strategic Shifts
Preservative formulation is pivoting toward application-specific efficacy profiles as regulatory safety margins tighten and biologic drug complexity escalates compatibility requirements.
Self-emulsifying drug delivery systems are integrating phenoxyethanol-phenethyl alcohol combinations to achieve broad-spectrum antimicrobial coverage in lipid-based parenteral formulations. Specialty injectable manufacturers in Switzerland and Singapore are qualifying these systems for high-viscosity biologic suspensions. The technology is integrating preservative efficacy with solubilization function, compressing excipient count and simplifying regulatory filing complexity.
EMA guidance on endocrine-disrupting chemical classifications is forcing reformulation roadmaps across dermal and mucosal drug portfolios. Manufacturers are accelerating sorbic acid and benzyl alcohol qualification studies to preempt paraben derivative restrictions. Ophthalmic solution producers in Germany and France face the most compressed transition timelines as national competent authorities align with centralized EMA hazard assessments.
Multi-dose vial procurement is consolidating around single-source preservative qualification to reduce regulatory audit burden. Hospital purchasing cooperatives in the United States and Japan are unbundling preservative supply from finished drug contracts, creating direct supplier relationships with cGMP-certified chemical producers. This channel disintermediation is most visible in oncology supportive care injectables, where sterility assurance requirements override traditional pharmaceutical excipient distribution hierarchies.
Pharmaceuticals Preservative Market Segmentation
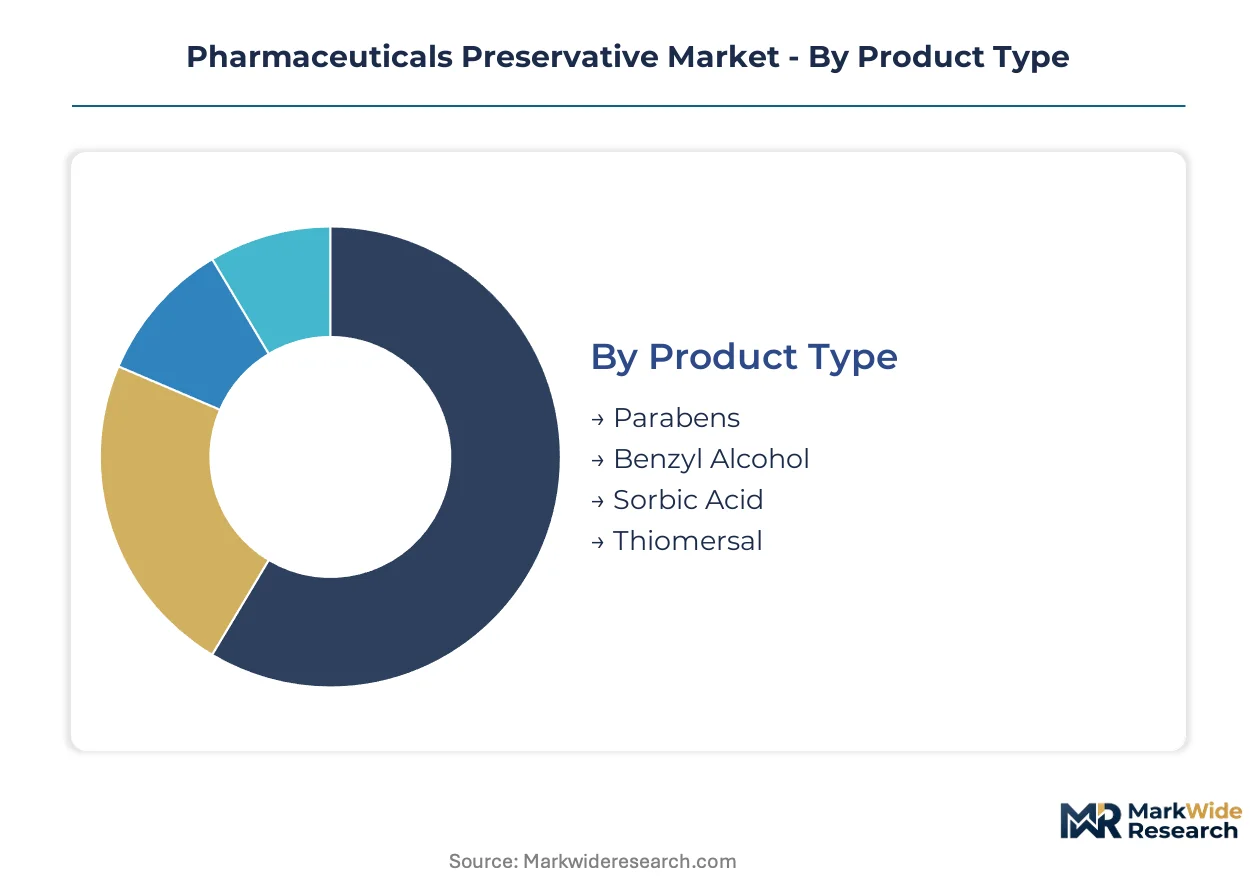
Preservative selection cascades through formulation economics, regulatory filing complexity, and sterilization validation requirements. Each segment tier imposes distinct capital commitments for manufacturers qualifying chemistries across pharmacopeial jurisdictions.
Product Type:
Capital intensity varies sharply across chemistries, with parenteral-grade production demanding dedicated GMP suites and analytical infrastructure that generic-grade operations cannot repurpose.
- Parabens:Methyl- and propylparaben formulations retain dominance in liquid ophthalmic and topical applications due to established USP/EP monographs and broad-spectrum Gram-positive coverage. Reformulation pressure from EMA REACH restrictions on endocrine-disrupting classifications is compressing procurement volumes in Germany and France.
- Benzyl Alcohol:Toluene oxidation pathways yield pharmaceutical-grade material with integrated antioxidant stabilization for multi-dose parenterals. BASF SE and Evonik Industries AG anchor European supply through backward integration into petrochemical feedstocks.
- Sorbic Acid:High-purity variants serve inhalant formulations where respiratory safety margins constrain concentration flexibility. Powder grades for lyophilized biologics command premium qualification timelines.
- Thiomersal:Mercury-containing preservative faces FDA concentration ceilings in vaccines and biologics, limiting new qualification investments to legacy product maintenance.
Most installed capacity flows through paraben chemistries. Expansion is steepest in benzyl alcohol as multi-dose vial adoption accelerates.
Formulation Type:
Manufacturing scale and sterility assurance requirements separate hospital-grade supply from commodity chemical distribution.
- Liquid:Aqueous solutions dominate ophthalmic and injectable applications, requiring terminal sterilization compatibility and container closure integrity validation. Demand concentrates in United States hospital purchasing cooperatives unbundling excipient supply from finished drug contracts.
- Powder:Lyophilized formats for single-dose reconstitutable biologics represent the steepest expansion trajectory as hospital and research laboratory channels gain share. cGMP-certified sites in Switzerland and Japan control qualification bottlenecks.
- Cream:Semisolid emulsions for dermal drug delivery face compressed transition timelines under evolving EMA hazard assessments.
- Gel:Hydrogel matrices for mucosal applications integrate preservative function with rheology modification, reducing excipient count in regulatory filings.
Volume leadership sits with liquid formats. Powder investments are climbing fastest on biologics pipeline expansion.
End User:
Procurement sophistication and pharmacopeial compliance requirements stratify customer tiers across institutional and research channels.
- Pharmacies:Retail and hospital pharmacy compounding operations in India and Brazil present underpenetrated expansion vectors for WHO-qualified suppliers. Regulatory harmonization gaps slow market access.
- Hospitals:Oncology supportive care injectables drive direct supplier relationships with cGMP-certified chemical producers, bypassing traditional excipient distributors. Sterility assurance requirements override conventional procurement hierarchies.
- Clinics:Outpatient settings prioritize single-dose presentations that minimize preservative exposure, constraining multi-dose vial adoption.
- Research Laboratories:Preclinical and clinical trial material supply demands flexible batch scales and rapid analytical turnaround, favoring regional specialty chemical producers over commodity suppliers.
Hospital procurement channels concentrate premium-grade volumes. Research laboratory segments are gaining share fastest on biologics pipeline expansion.
Application:
Route-of-administration safety margins determine preservative concentration ceilings and compatibility testing burdens.
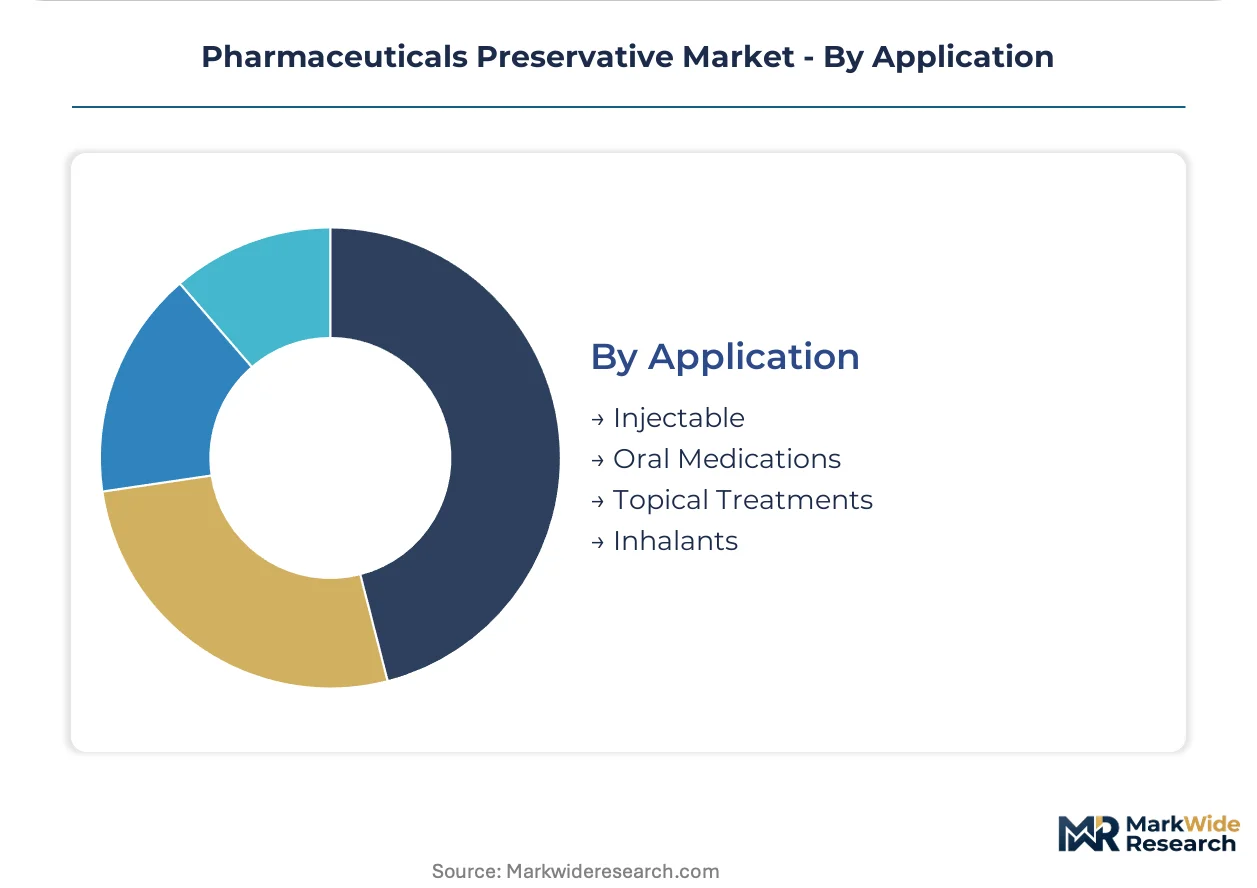
- Injectable:Parenteral formulations impose the narrowest therapeutic indices, requiring 18-24 month antimicrobial effectiveness validation cycles under USP and EP standards. Multi-dose vial stability requirements are consolidating sourcing around single-source qualification to reduce regulatory audit burden.
- Oral Medications:Liquid and solid dosage forms tolerate broader preservative portfolios, though EMA reformulation mandates are accelerating sorbic acid displacement of paraben derivatives.
- Topical Treatments:Dermal applications face the most compressed transition timelines as national competent authorities align with centralized EMA endocrine-disrupting chemical assessments.
- Inhalants:Respiratory safety margins constrain sorbic acid concentration flexibility, creating formulation challenges for nebulized and dry powder delivery systems.
Injectable applications anchor revenue concentration. Inhalant segments are expanding most quickly on respiratory drug pipeline growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate to jurisdictions with stable pharmacopeial standards but lower compliance friction. The United States, Germany, Japan, India, and Switzerland collectively host the infrastructure for pharmaceutical-grade preservative supply.
United States
FDA concentration ceilings on thiomersal and multi-dose vial stability mandates drive preservative qualification investments. The agency's antimicrobial effectiveness testing protocols under USP standards create 18-24 month validation timelines that favor incumbent suppliers. New Jersey and Massachusetts clusters concentrate sterile injectable manufacturing, with hospital purchasing cooperatives unbundling excipient supply from finished drug contracts.
Germany
EMA REACH restrictions on paraben derivatives accelerate reformulation roadmaps across dermal and mucosal portfolios. The country's national competent authority aligns with centralized EMA endocrine-disrupting chemical assessments, compressing transition timelines. BASF SE and Evonik Industries AG anchor European benzyl alcohol and sorbic acid supply through integrated petrochemical feedstock access.
Japan
PMDA pharmacopeial standards for parenteral-grade preservatives sustain premium procurement volumes from domestic sterile drug manufacturers. METI industrial policy supports cGMP-certified chemical production for biologics export markets. The Kanto region around Tokyo concentrates lyophilized biologics manufacturing, with powder preservatives gaining share in single-dose reconstitutable products.
India
WHO pharmacopeial guidelines create harmonized benchmarks for preservative suppliers targeting hospital pharmacy compounding channels. CDSCO regulatory harmonization gaps slow market access for international suppliers. Maharashtra and Gujarat pharmaceutical manufacturing corridors present underpenetrated expansion vectors for qualified preservative producers.
Switzerland
Swissmedic standards for high-purity excipients attract specialty injectable manufacturers qualifying self-emulsifying drug delivery systems. The country's precision chemical infrastructure supports phenoxyethanol-phenethyl alcohol combinations for lipid-based parenteral formulations. Basel and Zurich regions concentrate biologics R&D, driving demand for application-specific preservative efficacy profiles.
Pharmaceuticals Preservative Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue application-specific efficacy certifications as differentiation vectors. The market structures around three maturity tiers: integrated petrochemical majors with backward feedstock control, cGMP-certified specialists serving parenteral drug makers, and regional compounders supplying pharmacy compounding channels. Dominant competitive moves include capacity expansion at cGMP-certified sites and strategic partnerships with biologics manufacturers for co-development of preservative-excipient combinations.
Among European integrated chemical producers, BASF SE, Evonik Industries AG, and Lonza Group Ltd. occupy positions that exemplify distinct archetypes. BASF SE represents the petrochemical-backward-integration model with toluene oxidation pathways for benzyl alcohol. Evonik Industries AG sits within the high-purity specialization tier for inhalant and ophthalmic applications. Lonza Group Ltd. anchors the cGMP-certified manufacturing segment with sites servicing parenteral drug qualification requirements.
| Leading Market Players |
|---|
| Clariant AG |
| Evonik Industries AG |
| Lonza Group Ltd. |
| Celanese Corporation |
| Akzo Nobel N.V. |
| BASF SE |
| Eastman Chemical Company |
| DowDuPont |
| Lanxess AG |
| Others |
Value Chain & Pricing Dynamics
Pharmaceutical-grade certification tiers create a three-tier pricing structure across premium, standard, and economy levels that manifests in both procurement premiums and supply chain redundancy requirements. Parenteral-grade benzyl alcohol commands substantial markups over technical-grade equivalents, while buyers in Germany and Japan mandate parallel supplier qualification to satisfy cGMP audit protocols.
Pricing Analysis
Distributor margins compress as hospital purchasing cooperatives in the United States and Japan unbundle excipient supply from finished drug contracts. Pricing stratifies across premium, standard, and economy tiers based on USP/EP certification grade and batch-scale flexibility. Cost compression in technical-grade parabens is intensifying because feedstock toluene volatility transmits directly through oxidation pathways. Compounding pharmacies in India and Brazil exhibit highest price sensitivity, while oncology injectable manufacturers show lowest sensitivity due to sterility assurance mandates.
Supply Chain Analysis
Dual-sourcing requirements from FDA and EMA audit standards force buyers to maintain qualified secondary suppliers for all parenteral-grade chemistries. Manufacturing concentrates in Germany, Japan, and Switzerland where cGMP-certified sites cluster around sterile drug production hubs. Pharmaceutical-grade output draws from toluene, potassium sorbate, and phenol feedstocks vulnerable to petrochemical input swings. Single-source vulnerability concentrates in high-purity sorbic acid variants for inhalant applications. Distribution runs through direct supplier relationships with chemical producers, bypassing traditional excipient wholesalers in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceuticals preservative demand functions as a regulatory compounder where EMA REACH restrictions on paraben derivatives accelerate replacement chemistry procurement across European formulators.
For Market Incumbents: Anchor market position through backward integration into toluene oxidation feedstocks and capacity expansion at cGMP-certified sites in Germany and Switzerland. Emerging biotechnology entrants with self-emulsifying drug delivery systems threaten traditional excipient bundling. Certification investment in high-purity sorbic acid variants for ophthalmic applications secures pricing power against commodity-grade competitors. For New Entrants and Emerging Players: Capture underpenetrated hospital pharmacy compounding channels in Maharashtra and Gujarat corridors where WHO pharmacopeial guideline adoption outpaces international supplier qualification. Regulatory harmonization gaps at CDSCO create accessible entry points for regional compounders. Direct technical service relationships with institutional buyers bypass established distribution hierarchies. For Investors and Strategic Acquirers: Consolidation pressure builds where cGMP certification concentration limits scalable supply from Western Europe and Japan. Five-to-ten-year viability favors specialty chemical producers with integrated petrochemical access and parenteral-grade manufacturing infrastructure. Acquisition targets include mid-scale German and Swiss producers with existing EMA qualification dossiers. Signal to monitor: EMA endocrine-disrupting chemical reclassification announcements that would trigger immediate portfolio restructuring mandates.| Strategic Initiative | Industry Significance |
|---|---|
| cGMP Certification Investment | EMA and FDA audit standards require 18-24 month validation cycles that incumbent suppliers leverage to exclude unqualified competitors. |
| Backward Feedstock Integration | BASF SE and Evonik Industries AG control benzyl alcohol purity through captive toluene oxidation capacity. |
| Application-Specific Formulation Development | Phenoxyethanol-phenethyl alcohol combinations for lipid-based parenterals compress excipient count in Swiss biologics filings. |
| Direct Hospital Supply Relationships | Oncology injectable procurement in New Jersey and Massachusetts clusters bypasses traditional excipient distributors. |
| Regulatory Pre-Qualification Studies | Sorbic acid displacement of parabens in German ophthalmic solutions accelerates under ANSM-aligned EMA hazard assessments. |
Study Parameters
Bottom-up formulation modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with regulatory affairs leads at EMA-notified bodies, procurement managers at hospital purchasing cooperatives, technical directors at specialty chemical producers, and quality assurance officers at parenteral drug manufacturers combined with secondary validation from FDA 483 inspection observations, EMA assessment reports, USP monograph revisions, and pharmaceutical customs data. Triangulation across these sources isolates volume and value estimates.
Historical trendline analysis of preservative procurement volumes by formulation type, chemistry grade, and end-user channel established baseline growth patterns across the projection horizon. Segmentation dimensions modeled include product chemistry, formulation state, application route, and regional regulatory cluster. CAGRs were derived from slope analysis of validated data points. Forecast inputs incorporate lyophilized biologics pipeline expansion rates and EMA guidance evolution timelines.
Regulatory reclassification announcements, feedstock price volatility spikes, and cGMP certification delays are the dominant revision risks to modeled outputs. Deviation in EMA endocrine-disrupting chemical classification timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Australia Pharmaceuticals Market
Pharmaceuticals
Nikethamide Injection Market
Pharmaceuticals
Nimodipine Market
Pharmaceuticals
RNA-Targeted Small Molecules Market
Pharmaceuticals
Amylin Analogs Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Injectable Potassium Phosphate Market
Pharmaceuticals
Mexico Dimenhydrinate Market
Pharmaceuticals
Asia-Pacific Human Papillomavirus Vaccine Market
Pharmaceuticals
Medical Nitroglycerin Spray Market
Pharmaceuticals
Italy Diabetes Drugs Market
Pharmaceuticals
Allergic Rhinitis Drugs Market
Pharmaceuticals
Trenbolone Acetate Market
Pharmaceuticals
Polypill Products Market