
 Fatty Liver Treatment Market | 2026-2036
Fatty Liver Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Fatty Liver Treatment Market Foresight
Multi-source clinical trial outsourcing is restructuring how pharmaceutical developers advance NASH pipelines. Gilead Sciences leverages its antiviral manufacturing infrastructure to repurpose liver-targeting capabilities. Madrigal Pharmaceuticals anchors its position through thyroid hormone receptor-beta selectivity. Novo Nordisk competes by extending its metabolic disease franchise into fibrotic liver indications.
Fatty liver treatment encompasses pharmacological, nutritional, and procedural interventions targeting hepatic steatosis, inflammation, and fibrosis progression, with oral small molecules constituting the dominant delivery modality due to patient compliance advantages. Medications command the largest value pool as resmetirom and similar agents approach commercialization, while injectable GLP-1 analogs represent the fastest-expanding delivery segment driven by metabolic comorbidity overlap. Hospital end users absorb the majority of advanced therapy administration, though home care channels gain traction for oral maintenance regimens.
FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines for NASH candidates, while WHO liver disease mortality targets pressure national health systems to expand screening. The EU MDR tightens clinical evidence requirements for implantable hepatic devices. Stakeholders must monitor regulatory divergence between accelerated approval pathways and confirmatory trial obligations.
Market Dynamics
FDA breakthrough therapy designations and EMA PRIME eligibility compress development timelines, while WHO liver disease mortality targets pressure national health systems to expand screening infrastructure and specialist capacity.
Growth Catalysts
- Accelerated Approval Pathways:FDA breakthrough therapy designation and EMA PRIME eligibility compress Phase II-to-III transitions for NASH candidates, compressing time-to-market for novel mechanisms.
- Metabolic Comorbidity Overlap:Type 2 diabetes and obesity prevalence expansion creates addressable patient pools in the United States, Germany, and Japan where specialist liver centers cluster.
- Non-Invasive Diagnostics:FibroScan and MRI-PDFF adoption reduces reliance on liver biopsy, expanding treatable patient identification in hospital hepatology departments.
Market Restraints
- Biomarker Uncertainty:Lack of validated surrogate endpoints beyond histology forces extended confirmatory trial designs, inflating development costs and regulatory risk.
- Reimbursement Friction:Payer scrutiny of emerging NASH therapies delays commercial uptake in Medicare and national health systems awaiting mortality outcome data.
- Specialist Bottleneck:Hepatologist supply constraints in the United States and Germany limit patient throughput for advanced therapy initiation and monitoring.
Strategic Opportunities
- Home Care Channel Expansion:Oral small molecule maintenance regimens enable pharmacy-direct dispensing, reducing hospital outpatient burden for stable patients.
- Combination Regimen Development:Pairing thyroid hormone receptor-beta agonists with GLP-1 analogs addresses metabolic and fibrotic pathways simultaneously.
- Companion Diagnostic Integration:Genomic stratification tools identify responders pre-treatment, improving payer value demonstration and clinical trial efficiency.
Industry Challenges
- Histopathologist Scarcity:Centralized biopsy reading requirements strain pathology networks, creating enrollment bottlenecks for registrational trials.
- Legacy IT Integration:Electronic health record fragmentation across hospital systems complicates real-world evidence collection for post-market commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fatty Liver Treatment Market |
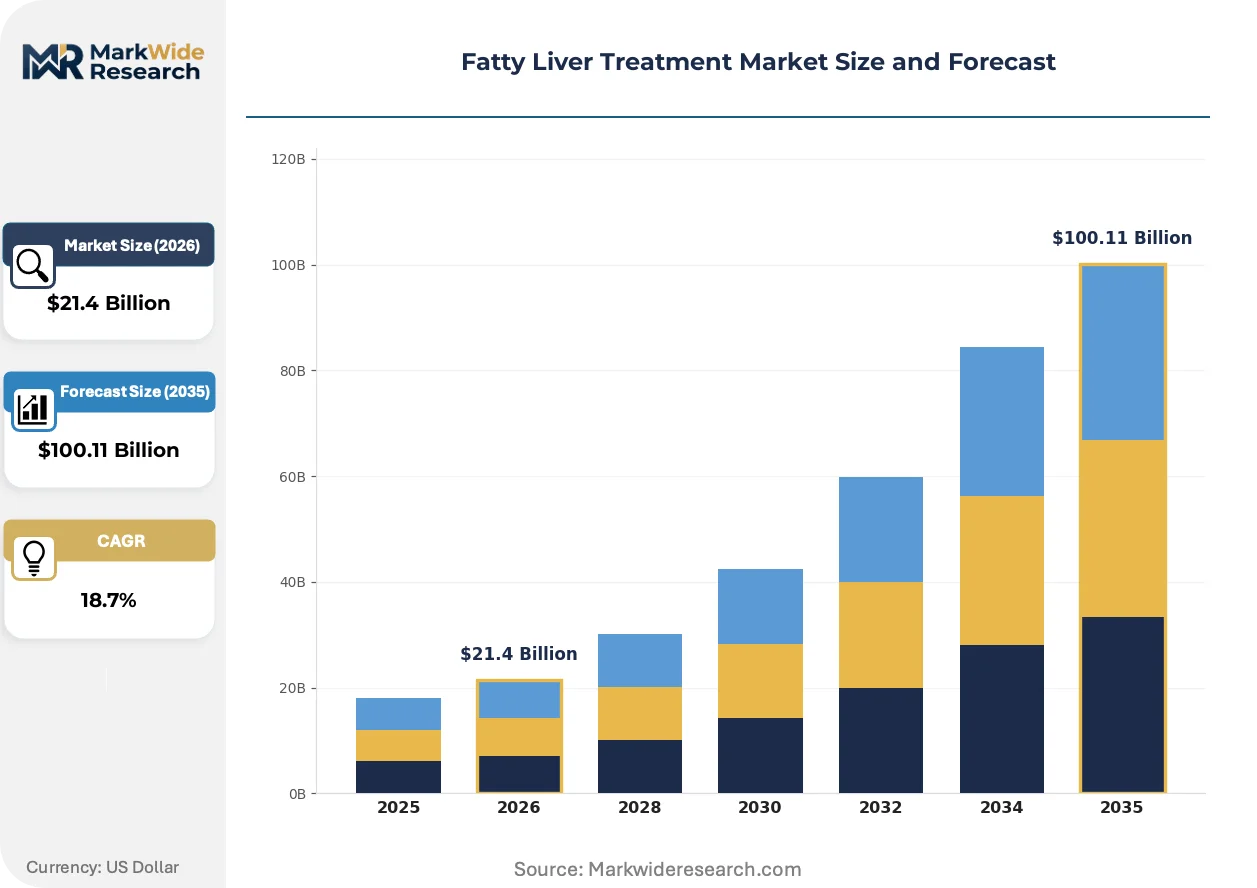
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $100.11 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medications, Nutraceuticals, Therapies, Surgery Delivery Mode: Oral, Injectable, Intravenous, Transdermal End User: Hospitals, Clinics, Home Care, Rehabilitation Centers Indication: Nonalcoholic Fatty Liver Disease, Alcoholic Hepatitis, Cirrhosis, Hepatic Encephalopathy |
| Companies Covered | Gilead Sciences, AbbVie, Intercept Pharmaceuticals, Madrigal Pharmaceuticals, Novo Nordisk, AstraZeneca, Pfizer, Novartis, Akero Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fatty Liver Treatment Market Shifts & Advancements
Therapeutic modality preferences are fragmenting across delivery mechanisms and treatment settings, with oral formulations gaining ground against injectable alternatives in maintenance phases.
Thyroid hormone receptor-beta selective agonists are overtaking pan-agonist approaches in late-stage development. These molecules target hepatic lipid metabolism without systemic thyroid activation. Hospital hepatology departments in the United States and Japan are prioritizing these agents for biopsy-confirmed NASH patients. The technology is overtaking earlier mechanisms that required intensive cardiovascular monitoring.
EMA's MDR tightening for implantable hepatic devices elevates clinical evidence requirements for interventional radiology tools used in advanced fibrosis. Manufacturers must now submit extended follow-up data for CE marking renewal. German and French hospital procurement committees are delaying device adoption pending harmonized EU guidance.
Integrated care contracts are consolidating pharmacy and diagnostic spend under single budgets in United States accountable care organizations. Risk-bearing entities now negotiate directly with specialty pharmacies for oral NASH therapies. This shift is most visible in Medicare Advantage networks across Florida and Texas, where hepatology groups assume total cost of care accountability.
Fatty Liver Treatment Market Segmentation
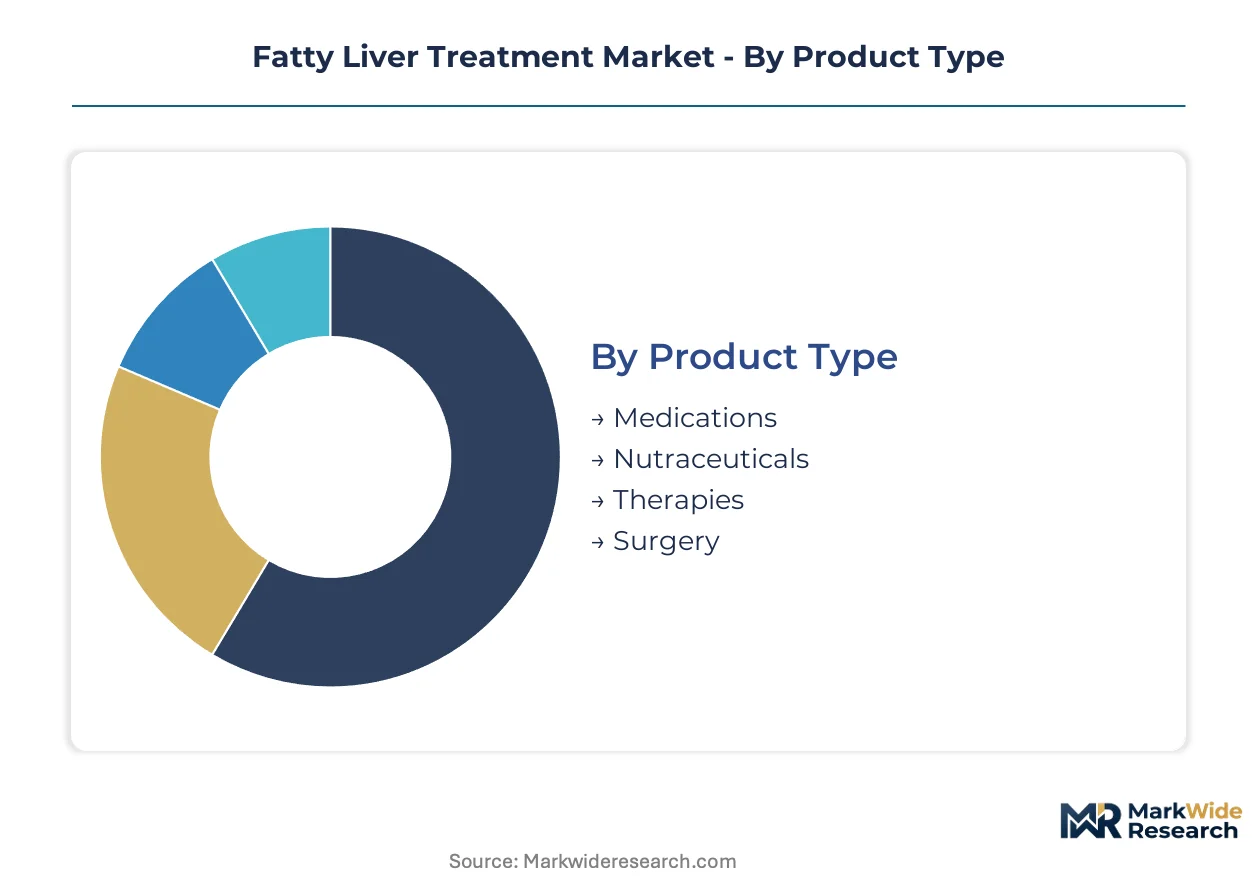
Segmentation in the fatty liver treatment market reveals how therapeutic modality, care setting, and disease severity reshape commercial strategy. Each axis exposes distinct margin structures, regulatory pathways, and patient access requirements that determine competitive positioning.
Product Type:
Product differentiation centers on clinical evidence depth and reimbursement tier, with pharmacological agents commanding premium pricing against procedural alternatives.
- Medications:Small-molecule agents targeting thyroid hormone receptor-beta selectivity dominate late-stage pipelines. Hospital formularies in the United States and Germany prioritize these for biopsy-confirmed NASH, though confirmatory trial costs inflate development risk.
- Nutraceuticals:Omega-3 formulations and vitamin E derivatives circulate through pharmacy-direct channels without prescription requirements. Demand concentrates in Japan's aging population seeking pre-symptomatic intervention, constrained by limited payer coverage for non-pharmacological approaches.
- Therapies:Lifestyle intervention programs and structured weight management protocols integrate with metabolic disease clinics. These face margin compression against pharmaceutical alternatives despite lower adverse event profiles.
- Surgery:Bariatric procedures and liver transplantation address end-stage fibrotic disease. Specialist capacity bottlenecks in the United States and Germany limit throughput, creating waitlist dynamics that delay revenue recognition.
Medications lead on scale; nutraceuticals lead on momentum.
Delivery Mode:
Route of administration determines patient adherence economics and care setting requirements, with oral formulations reducing clinical overhead against parenteral alternatives.
- Oral:Tablets and capsules enable home-based maintenance regimens, reducing hepatology department burden. Pharmacy-direct dispensing contracts in United States Medicare Advantage networks favor this modality for stable patients.
- Injectable:GLP-1 analogs and biologic agents require cold-chain logistics and clinical supervision. These are expanding most quickly through metabolic disease crossover indications in Japan and Germany.
- Intravenous:Hospital-administered infusions target acute decompensation episodes. Specialist nursing requirements concentrate demand in tertiary liver centers.
- Transdermal:Patch-based delivery remains experimental for hepatic indications, limited by skin permeability challenges for large-molecule therapeutics.
Oral formulations anchor volume; injectables capture the steepest expansion trajectory.
End User:
Care setting selection reflects disease severity staging and reimbursement architecture, with acute intervention concentrating in institutional settings against chronic management migration.
- Hospitals:Tertiary hepatology departments in the United States, Germany, and Japan absorb advanced therapy initiation, biopsy confirmation, and decompensation management. These facilities capture the majority of high-acuity spend.
- Clinics:Outpatient hepatology practices handle stable patient monitoring and oral therapy titration. FibroScan deployment in these settings expands treatable identification without biopsy requirements.
- Home Care:Pharmacy-direct dispensing and remote monitoring technologies enable maintenance regimen adherence. This channel gains traction where oral small molecules reduce hospital outpatient burden.
- Rehabilitation Centers:Structured programs address alcohol cessation and lifestyle modification for alcoholic hepatitis patients. These integrate with hospital discharge planning in integrated care networks.
Hospitals dominate value capture; home care channels are gaining share fastest.
Indication:
Disease indication segmentation exposes distinct pathophysiology targets, regulatory endpoint requirements, and addressable population dynamics across the fatty liver spectrum.
- Nonalcoholic Fatty Liver Disease:NASH with fibrosis represents the primary commercial target for emerging pharmacological agents. FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines for candidates in this segment.
- Alcoholic Hepatitis:Acute-on-chronic presentations require hospital-based corticosteroid or pentoxifylline protocols. Limited therapeutic innovation in this segment reflects trial enrollment challenges and mortality endpoint requirements.
- Cirrhosis:Decompensated disease management centers on complication prevention and transplant evaluation. Interventional radiology procedures for portal hypertension face elevated EU MDR evidence requirements.
- Hepatic Encephalopathy:Lactulose and rifaximin dominate maintenance therapy, with limited pipeline activity for novel mechanisms. This indication captures stable but lower-growth revenue pools.
Nonalcoholic fatty liver disease leads on investment intensity; cirrhosis presents the most constrained clinical trial pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialist liver centers in the United States, Germany, and Japan concentrate the highest-value fatty liver treatment demand, with hospital systems in these markets expanding hepatology capacity to manage rising patient volumes.
United States
Medicare Advantage networks in Florida and Texas are consolidating pharmacy and diagnostic spend under integrated care contracts for oral NASH therapies. FDA breakthrough therapy designation compresses Phase II-to-III development timelines for late-stage candidates. Hospital hepatology departments in Houston and Miami absorb advanced therapy initiation and biopsy confirmation.
Germany
Specialist hepatologist supply constraints limit patient throughput for advanced therapy initiation in university hospital systems. EMA PRIME eligibility accelerates market access for novel mechanisms while EU MDR tightens clinical evidence requirements for interventional devices. Procurement committees in Berlin and Munich delay device adoption pending harmonized guidance.
Japan
Aging demographics expand the addressable pool for pre-symptomatic intervention through nutraceutical channels. PMDA review pathways prioritize metabolic disease crossover indications for GLP-1 analogs. Tokyo and Osaka tertiary centers prioritize thyroid hormone receptor-beta selective agonists for biopsy-confirmed patients.
United Kingdom
NHS England screening infrastructure expansion targets liver disease mortality reduction aligned with WHO targets. NICE technology appraisals scrutinize emerging NASH therapies pending mortality outcome data. London hepatology clusters concentrate clinical trial enrollment for registrational studies.
Switzerland
Swissmedic accelerated pathways attract pharmaceutical developers seeking early market presence for novel mechanisms. Basel and Zurich hospital networks integrate FibroScan deployment to reduce biopsy reliance. Private payers negotiate risk-sharing arrangements for high-cost specialty therapies.
Fatty Liver Treatment Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue metabolic disease franchise extensions into fibrotic liver indications. The market structure fragments across therapeutic modality specialists, with oral small molecule developers competing against injectable biologic platforms for maintenance and acute segments respectively. Three archetypes dominate: antiviral infrastructure repurposers, metabolic disease extenders, and thyroid hormone receptor-beta selectivity anchors. Competitive moves concentrate on combination regimen development and companion diagnostic integration to improve payer value demonstration.
Within the infrastructure repurposer archetype, Gilead Sciences exemplifies leveraging existing antiviral manufacturing capabilities for liver-targeting applications. Madrigal Pharmaceuticals and Novo Nordisk occupy distinct positioning vectors—Madrigal through thyroid hormone receptor-beta selectivity and Novo Nordisk through metabolic disease franchise extension. These three entities represent the dominant strategic postures visible in late-stage pipeline activity.
| Leading Market Players |
|---|
| Gilead Sciences |
| AbbVie |
| Intercept Pharmaceuticals |
| Madrigal Pharmaceuticals |
| Novo Nordisk |
| AstraZeneca |
| Pfizer |
| Novartis |
| Akero Therapeutics |
| Others |
Supply & Pricing Matrix
Specialist liver centers in the United States, Germany, and Japan concentrate purchasing power for advanced NASH therapies, driving value-based contracting that ties reimbursement to histological response endpoints rather than transactional per-unit pricing. This buyer concentration enables risk-sharing arrangements where hospital systems negotiate outcomes-guaranteed pricing for thyroid hormone receptor-beta selective agonists.
Pricing Analysis
Input-cost pass-through from active pharmaceutical ingredient synthesis and specialized cold-chain logistics shapes pricing stratification across premium, standard, and economy tiers in the fatty liver treatment market. Price differentiation rests on FDA breakthrough therapy designation status and companion diagnostic bundling, with designated agents commanding premium positioning against standard-of-care alternatives. Cost compression in the oral small molecule segment intensifies as multiple thyroid hormone receptor-beta agonists approach commercialization, pressuring first-mover margins. Medicare Advantage networks exhibit highest price sensitivity due to total cost of care accountability, while Japanese private payers demonstrate lowest sensitivity for metabolic disease crossover indications.
Supply Chain Analysis
Workforce availability constraints in pharmaceutical manufacturing hubs across the United States, Ireland, and Switzerland limit capacity expansion for liver-targeting small molecule production. Active pharmaceutical ingredient supply draws from specialized chemical synthesis facilities in India and China, with finished dose formulation concentrated in FDA-inspected sites. Single-source vulnerability for thyroid hormone receptor-beta agonist precursors creates supply chain risk given limited qualified suppliers meeting current Good Manufacturing Practice standards. Distribution runs through specialty pharmacy networks for oral maintenance regimens, with hospital-based procurement for acute decompensation therapies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in the fatty liver treatment market stems from diagnostic-bundled pricing models that capture value across the patient journey from FibroScan screening through maintenance therapy, reducing cost-to-serve through home care channel migration.
For Market Incumbents: Anchor formulary position through companion diagnostic integration that stratifies responders pre-treatment, improving payer value demonstration against emerging GLP-1 analog competitors. Deepen backward integration into active pharmaceutical ingredient supply to secure thyroid hormone receptor-beta agonist precursor access amid qualified supplier scarcity. Defend against metabolic disease franchise extenders by locking hospital system partnerships through integrated care contracts in Medicare Advantage networks. For New Entrants and Emerging Players: FDA breakthrough therapy designation in the United States opens a window for accelerated Phase II-to-III transitions that compress development timelines against established players. Target home care channel expansion for oral small molecule maintenance regimens, the most penetrable segment given pharmacy-direct dispensing infrastructure gaps. Pursue genomic stratification tools as the go-to-market angle, enabling precision positioning that commands premium reimbursement. For Investors and Strategic Acquirers: Large-cap metabolic disease specialists are the most active acquirer in this space, seeking fibrotic liver indications to extend franchise longevity. Long-term viability hinges on confirmatory trial success demonstrating mortality benefit beyond histological surrogates. Acquisition target archetype: mid-cap developers with thyroid hormone receptor-beta selectivity assets and existing FDA breakthrough therapy designation. Watch for EMA PRIME eligibility announcements as the inflection indicator signaling accelerated European market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses Phase II-to-III transitions for NASH candidates. |
| Companion Diagnostic Integration | Genomic stratification tools improve payer value demonstration and clinical trial efficiency. |
| Manufacturing Scale-Up | Antiviral infrastructure repurposing leverages existing liver-targeting capabilities for new mechanisms. |
| Hospital System Partnership | Integrated care contracts consolidate pharmacy and diagnostic spend under single budgets. |
| Pipeline Diversification | Combination regimens pairing thyroid hormone receptor-beta agonists with GLP-1 analogs address multiple pathways. |
Research Methodology
Multiple input streams — primary interviews with drug development executives, regulatory affairs leads, and formulary directors; secondary validation through FDA filings, EMA submissions, and ClinicalTrials.gov records; and hospital procurement database analysis — were reconciled through bottom-up patient-flow modeling and top-down epidemiological triangulation. Conversations with payer access specialists and hepatology department administrators informed reimbursement architecture assumptions. Secondary sources included formulary databases, CMS Medicare data, and GPO contracts to anchor volume estimates.
Data-stream reconciliation across the projection horizon applied segmented growth rate derivation by treatment line, administration route, and regional regulatory cluster. The analytical framework modeled patient population dynamics, therapy penetration curves, and pricing evolution throughout the forecast period. CAGRs were derived from epidemiological trend extrapolation, regulatory approval probability weighting, and historical analog performance from comparable metabolic disease markets. Forecast inputs incorporated WHO liver disease mortality targets and national screening infrastructure expansion timelines.
Revisions become necessary when confirmatory trial outcomes diverge from surrogate endpoint predictions, regulatory pathways shift between accelerated and traditional approval, or reimbursement decisions from Medicare and national health systems materially change access assumptions. Material deviation in these triggers warrants pause and re-evaluation of market size and competitive positioning projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cerebral Palsy Market
Specialty Medicine
Marfan Syndrome Management Market
Specialty Medicine
Synovial Sarcoma Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
Fibroadenoma Market
Specialty Medicine
Global Focal Segmental Glomerulosclerosis Market
Specialty Medicine
Mental Retardation Treatment Market
Specialty Medicine
Global Myeloproliferative Disorders (MPD) Treatment Market
Specialty Medicine
Healthcare Specialty Enzymes Market
Specialty Medicine
Middle-East and Africa Colorectal Cancer Market
Specialty Medicine
Global Childhood Absence Epilepsy Treatment Market
Specialty Medicine
Malabsorption Syndrome Market
Specialty Medicine
Global Actinic Keratosis Treatment Market
Specialty Medicine
Nephrogenic Systemic Fibrosis (NSF) Treatment Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Alcoholic Liver Diseases Treatment Market