
 TNF Inhibitors Market | 2026-2036
TNF Inhibitors Market Size, Share, and Industry Trends Forecast 2026-2036
TNF Inhibitors Market Outlook
India's biologics manufacturing corridor is fragmenting as contract development organizations multiply near Hyderabad and Bangalore. AbbVie Inc. leverages its Humira franchise infrastructure to sustain manufacturing scale across multiple continents. Pfizer Inc. anchors its position through biosimilar development partnerships that compete on cost with reference biologics. Amgen Inc. differentiates via in-house production of active pharmaceutical ingredients and fill-finish capabilities.
TNF inhibitors are monoclonal antibodies or receptor fusion proteins that bind soluble or membrane-bound tumor necrosis factor-alpha, blocking its pro-inflammatory signaling cascade; these biologics typically require mammalian cell culture production in Chinese hamster ovary lines, followed by purification via protein A chromatography and viral inactivation steps, yielding formulations with specified endotoxin limits and aggregate content below percent thresholds. Adalimumab and infliximab still occupy the largest revenue pools among product types, though golimumab and certolizumab are gaining share in subcutaneous delivery niches where patient self-administration drives preference. The intravenous segment dominates hospital-based therapy for Crohn's Disease and ankylosing spondylitis, while subcutaneous formulations are displacing infusion center visits in rheumatoid arthritis maintenance protocols.
The FDA's biosimilar approval framework and the EMA's comparability guidelines shape market access timelines and interchangeability standards across major jurisdictions. India's CDSCO and the PLI scheme for biopharmaceuticals are accelerating local fill-finish capacity that serves export markets. Samsung Bioepis and Boehringer Ingelheim Pharmaceuticals navigate this regulatory mosaic with dual-track development strategies targeting both regulated and emerging markets. Stakeholders must monitor FDA interchangeability designations and CMS reimbursement rulings that will determine whether biosimilar uptake accelerates beyond current substitution rates.
Market Dynamics
FDA interchangeability designations are compressing substitution timelines for adalimumab biosimilars, forcing originators to defend formulary placement through outcome-based contracting rather than patent exclusivity alone.
Growth Catalysts
- Biologics Price Competition and Innovation Act:The FDA's abbreviated biosimilar pathway accelerates approval timelines, compressing development costs for follow-on entrants targeting reference biologics.
- Subcutaneous self-administration:Patient preference for home-based injection over infusion center visits drives formulary preference toward pen-device formulations in rheumatoid arthritis maintenance.
- Hyderabad-Bangalore manufacturing corridor:India's contract development organization cluster expands fill-finish capacity serving regulated export markets, lowering production cost structures.
Market Restraints
- Mammalian cell culture input costs:Chinese hamster ovary line maintenance and serum media pricing volatility squeeze margin structures for in-house producers.
- Prior authorization protocols:United States specialty pharmacy networks impose step-therapy requirements that delay TNF inhibitor initiation by 30-90 days versus conventional synthetic DMARDs.
- Immunogenicity surveillance burden:Mandatory anti-drug antibody monitoring protocols add clinical trial complexity and post-market pharmacovigilance costs.
Strategic Opportunities
- Brazil's ANVISA accelerated pathway:Emerging market regulators are streamlining biosimilar review timelines, creating first-mover advantage for manufacturers with FDA or EMA-approved dossiers.
- Combination therapy protocols:Methotrexate co-administration regimens in juvenile idiopathic arthritis expand addressable patient pools beyond monotherapy labels.
- Continuous processing technology:Perfusion bioreactor adoption enables smaller-footprint manufacturing with higher volumetric productivity than fed-batch methods.
Industry Challenges
- Protein A chromatography resin supply:Single-source dependency for purification media creates bottleneck risk during demand surges or geopolitical trade restrictions.
- Interchangeability study design:FDA switching trial requirements demand complex pharmacokinetic modeling and immunogenicity endpoints that extend development timelines.
- Cold chain integrity:Subcutaneous formulation stability requirements complicate distribution through non-specialty retail pharmacy channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | TNF Inhibitors Market |
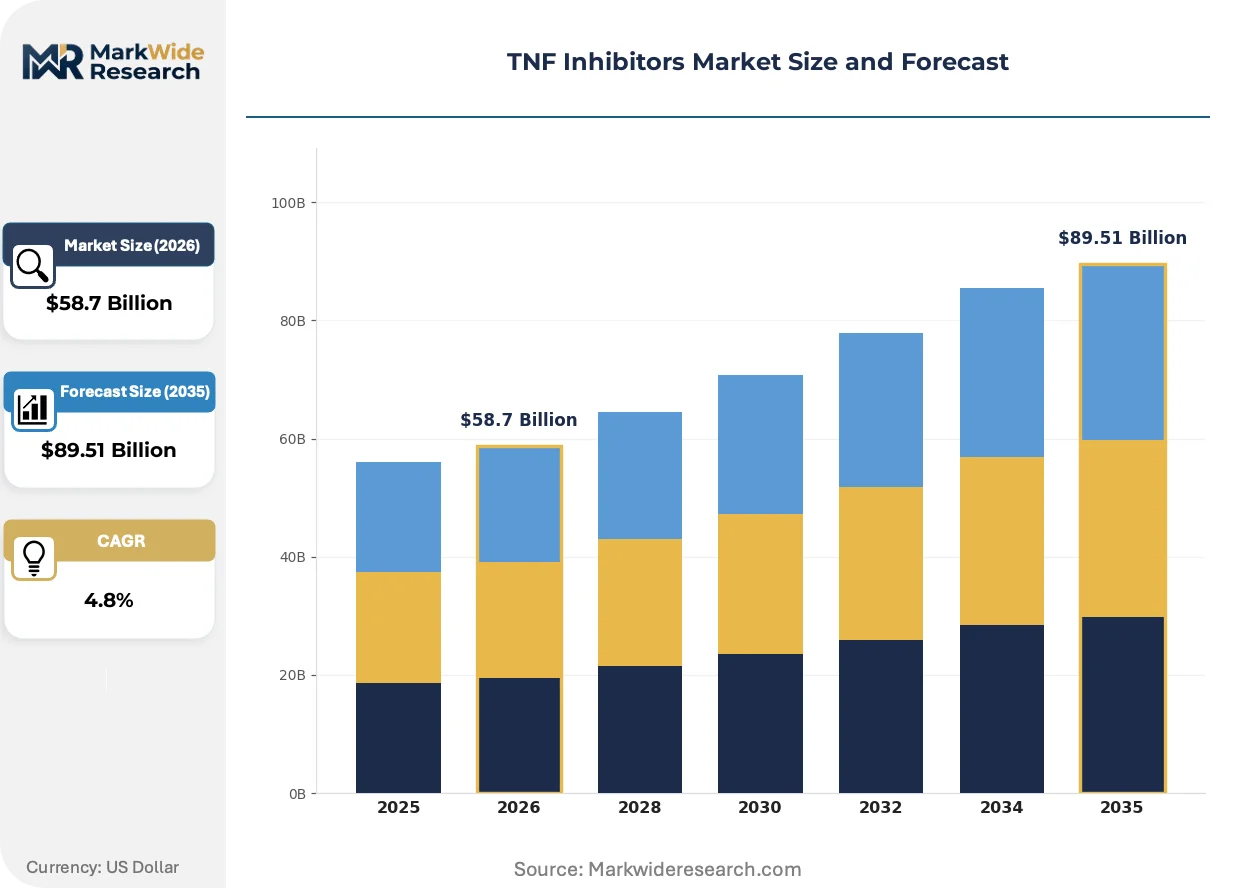
| Market Size in 2026 | $58.7 Billion |
| Market Size in 2035 | $89.51 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adalimumab, Infliximab, Golimumab, Certolizumab Delivery Mode: Subcutaneous, Intravenous, Oral, Transdermal Therapy Area: Rheumatoid Arthritis, Psoriasis, Ankylosing Spondylitis, Crohn's Disease End User: Hospitals, Clinics, Homecare, Specialty Pharmacies |
| Companies Covered | AbbVie Inc., Pfizer Inc., Amgen Inc., Johnson & Johnson, UCB S.A., Merck & Co., Samsung Bioepis, Boehringer Ingelheim Pharmaceuticals, Novartis International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
TNF Inhibitors Market Strategic Shifts
Biosimilar development strategies are pivoting from replication toward differentiation, with manufacturers investing in device design and real-world evidence generation to secure favorable formulary placement.
High-concentration subcutaneous formulations are migrating from infusion-dependent Crohn's Disease protocols toward maintenance therapy in ulcerative colitis, where gastroenterology practices seek to reduce chair time and nursing overhead. Hospital systems in the United States are adopting these formulations fastest, driven by site-of-care reimbursement compression that penalizes extended infusion visits. The technology is compressing revenue per patient for infusion center operators while expanding addressable volume for self-injectable presentations.
The European Medicines Agency's revised comparability guidelines now permit analytical similarity waivers for certain quality attributes when extensive functional data demonstrates equivalent clinical performance. This regulatory evolution reduces redundant clinical trial requirements for well-characterized biosimilar programs, accelerating market entry for developers with sophisticated physicochemical characterization capabilities. Manufacturers are responding by front-loading investment in mass spectrometry and surface plasmon resonance analytical platforms.
Specialty pharmacy networks are consolidating prior authorization processing through centralized hub services that disintermediate traditional wholesale distribution for TNF inhibitors. United States payers are mandating exclusive specialty pharmacy relationships that capture dispensing margin and data assets previously retained by physician buy-and-bill arrangements. Rheumatology practices in Medicare Advantage plans are experiencing this channel shift most acutely, as vertical integration between insurers and pharmacy benefit managers accelerates.
TNF Inhibitors Market Segmentation
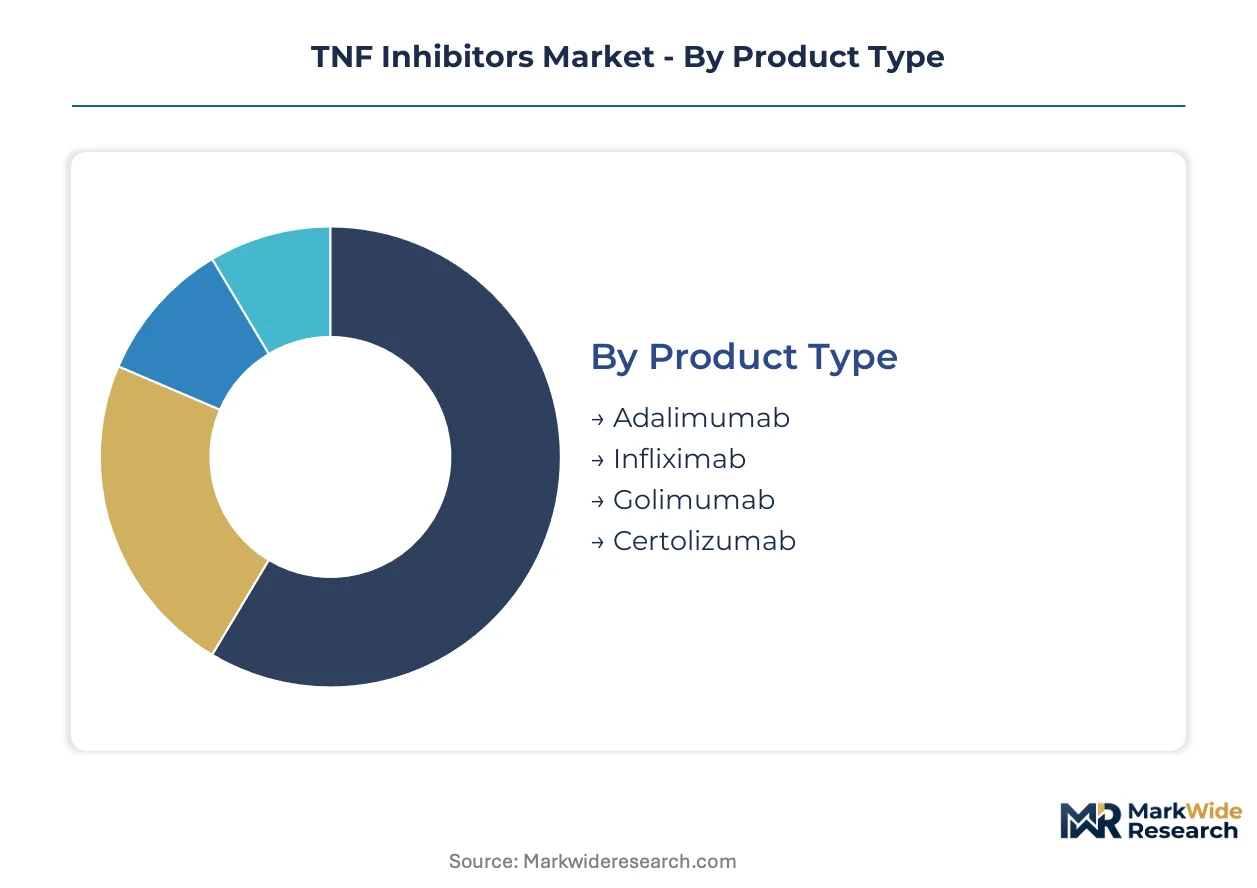
Segmentation in TNF inhibitors reveals how formulation science, site-of-care economics, and patient self-administration preferences partition revenue pools. Manufacturers calibrate development pipelines across these dimensions to capture formulary placement and optimize reimbursement pathways.
Product Type:
Cost tier stratification across the reference biologic portfolio determines which molecules face imminent biosimilar pressure versus sustained originator pricing power.
- Adalimumab:A fully human IgG1 monoclonal antibody targeting TNF-alpha with subcutaneous and intravenous presentations; demand concentrates in United States Medicare Part D plans where prior authorization volume exceeds all other TNF inhibitors combined, though biosimilar substitution is accelerating through FDA interchangeability designations.
- Infliximab:A chimeric monoclonal antibody requiring intravenous infusion in hospital or infusion center settings; rheumatology and gastroenterology practices in Germany and France still favor this molecule for Crohn's Disease induction therapy where infusion monitoring protocols dominate clinical workflows.
- Golimumab:A once-monthly subcutaneous human monoclonal antibody with a lower immunogenicity profile; expanding in United States rheumatoid arthritis maintenance where injection frequency drives adherence metrics.
- Certolizumab:A PEGylated Fab' fragment lacking Fc region, enabling reduced placental transfer; preferred in United Kingdom maternal-fetal medicine protocols for pregnant patients with active inflammatory bowel disease.
Adalimumab holds installed capacity across manufacturing networks. Certolizumab is rotating up the share rankings in specialty populations requiring pregnancy-compatible biologics.
Delivery Mode:
Application-driven route selection reflects site-of-care reimbursement compression and patient preference for autonomy in chronic disease management.
- Subcutaneous:Pen-device and prefilled syringe formulations enabling self-injection; United States specialty pharmacy networks are consolidating volume here as Medicare Advantage plans impose home administration incentives that displace infusion center visits.
- Intravenous:Hospital-administered infusion requiring nursing supervision and chair time; dominates Japan's Crohn's Disease protocols where gastroenterology societies maintain strict induction therapy guidelines favoring monitored administration.
- Oral:Small-molecule TNF pathway modulators in development; limited current commercial presence with most candidates stalled at Phase II due to hepatotoxicity signals.
- Transdermal:Patch-based delivery systems utilizing microneedle or iontophoresis technology; experimental formats in South Korean and Israeli development pipelines targeting pediatric populations with injection anxiety.
Intravenous retains the hospital formulary anchor position. Subcutaneous formulations are climbing the fastest as United States payers shift reimbursement toward lower-cost sites of care.
Therapy Area:
Volume distribution across immunology indications tracks prevalence epidemiology and biologic penetration rates in access-constrained versus reimbursed markets.
- Rheumatoid Arthritis:The largest addressable population with established TNF inhibitor first-line positioning; United States commercial payers mandate step-therapy through conventional synthetic DMARDs, compressing time-to-biologic initiation despite high disease activity.
- Psoriasis:Dermatology-driven demand with strong patient self-advocacy for clear-skin outcomes; biosimilar uptake in United Kingdom NHS England is outpacing other indications due to tender-based procurement that favors lowest-cost eligible products.
- Ankylosing Spondylitis:Axial spondyloarthritis spectrum with delayed diagnosis averaging 8-10 years; concentrates in German and Canadian rheumatology practices with established axial imaging protocols.
- Crohn's Disease:Gastroenterology-managed inflammatory bowel disease with acute flare protocols; intravenous infliximab maintains dominance in United States hospital systems due to infusion center infrastructure and J-code reimbursement mechanics.
Rheumatoid Arthritis holds installed capacity across manufacturing scale. Psoriasis is gaining share fastest as dermatology practices expand biologic penetration into moderate disease severity segments.
End User:
Customer type determines channel economics, with vertical integration between insurers and pharmacy benefit managers restructuring margin capture away from traditional wholesale.
- Hospitals:Integrated delivery networks with 340B pricing eligibility and infusion center operations; United States health systems are consolidating biologic purchasing through centralized pharmacy and therapeutics committees that standardize across multiple sites.
- Clinics:Physician-owned rheumatology and gastroenterology practices with buy-and-bill arrangements; facing reimbursement compression as Medicare's average sales price plus methodology narrows dispensing margin.
- Homecare:Self-administration settings supported by nursing visit or telehealth oversight; expanding in Netherlands and Denmark where national health systems reimburse home injection training as standard of care.
- Specialty Pharmacies:Centralized dispensing hubs with prior authorization processing capabilities; CVS Caremark and Express Scripts in the United States are mandating exclusive relationships that capture data assets and dispensing fees previously retained by physician practices.
Hospitals hold installed capacity through infusion infrastructure. Specialty Pharmacies are climbing the fastest as United States vertical integration accelerates channel control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA interchangeability designations in the United States are compressing substitution timelines for adalimumab biosimilars, forcing originators to defend formulary placement through outcome-based contracting rather than patent exclusivity alone. This regulatory pressure cascades through manufacturing investment decisions across major producing geographies.
United States
Medicare Part D prior authorization volume for adalimumab exceeds all other TNF inhibitors combined, driving specialty pharmacy network consolidation. The FDA's biosimilar approval pathway and CMS reimbursement rulings determine substitution rates. Massachusetts and California health systems are standardizing biologic purchasing through centralized pharmacy and therapeutics committees.
Germany
Rheumatology and gastroenterology practices favor infliximab for Crohn's Disease induction therapy where infusion monitoring protocols dominate clinical workflows. The EMA's comparability guidelines shape biosimilar market access timelines. Bavaria's hospital networks maintain strict induction therapy guidelines favoring monitored intravenous administration.
India
The CDSCO and PLI scheme for biopharmaceuticals are accelerating local fill-finish capacity serving export markets. Contract development organizations multiply near Hyderabad and Bangalore, fragmenting the biologics manufacturing corridor. These clusters now supply regulated export markets with lower production cost structures.
Japan
Gastroenterology societies maintain strict Crohn's Disease induction therapy guidelines favoring monitored intravenous administration. The PMDA regulates biosimilar review timelines with reference to EMA and FDA precedents. The Kanto region around Tokyo anchors hospital-based infusion center infrastructure.
Brazil
ANVISA's accelerated pathway for biosimilars is streamlining review timelines, creating first-mover advantage for manufacturers with FDA or EMA-approved dossiers. Emerging market demand concentrates in rheumatoid arthritis and psoriasis indications. São Paulo's hospital systems are expanding biologic formularies for autoimmune indications.
TNF Inhibitors Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another, producing a bifurcated structure where originator biologics manufacturers defend patent-expired franchises against biosimilar entrants. The market consolidates around three strategic archetypes: vertically integrated originators with global manufacturing footprints, biosimilar specialists leveraging abbreviated regulatory pathways, and contract manufacturers capturing fill-finish margin. Dominant competitive moves include outcome-based contracting to secure formulary placement and continuous processing technology adoption to compress unit costs.
Among vertically integrated originators, AbbVie Inc. and Amgen Inc. occupy positions exemplifying the scale-driven archetype, with captive production of active pharmaceutical ingredients and multi-continent manufacturing infrastructure. Pfizer Inc. represents the partnership-based biosimilar strategy, competing on cost with reference biologics through development alliances rather than in-house biologic discovery. Samsung Bioepis anchors the emerging-market specialist tier, navigating regulatory mosaics with dual-track development strategies targeting both regulated and emerging markets.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Pfizer Inc. |
| Amgen Inc. |
| Johnson & Johnson |
| UCB S.A. |
| Merck & Co. |
| Samsung Bioepis |
| Boehringer Ingelheim Pharmaceuticals |
| Novartis International AG |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in India's Hyderabad-Bangalore biologics corridor is compressing fill-finish margins while simultaneously expanding supplier leverage for contract manufacturers serving regulated export markets. This utilization dynamic shapes both originator defense strategies and biosimilar entrant pricing postures across the TNF inhibitor landscape.
Pricing Analysis
United States-Medicaid price spreads against German hospital procurement tenders reveal substantial geographic arbitrage in adalimumab equivalents. Three-tier pricing structure across reference biologics, interchangeable biosimilars, and non-interchangeable follow-ons segments buyer sophistication levels. Cost compression in the interchangeable tier is intensifying because FDA designations accelerate substitution velocity. Medicaid programs demonstrate highest price sensitivity; originator-loyal rheumatology practices in Medicare Advantage show lowest.
Supply Chain Analysis
Samsung Bioepis and Boehringer Ingelheim Pharmaceuticals anchor contract manufacturing capacity for biosimilar fill-finish operations. Active pharmaceutical ingredient production concentrates in the United States, Germany, and Singapore; final formulation and packaging clusters in India and Ireland. Mammalian cell culture draws from Chinese hamster ovary line dependencies and protein A chromatography resin single-source vulnerabilities. Tariff exposure on purification media creates bottleneck risk during demand surges. Distribution runs through consolidated specialty pharmacy networks that disintermediate traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in maternal-fetal medicine and pediatric self-administration niches where pregnancy-compatible biologics and injection-anxiety solutions create addressable white space. Biosimilar proliferation combined with interchangeability designations is splintering formerly concentrated demand pools.
For Market Incumbents: Pre-empt formulary displacement through outcome-based contracting with United States Medicare Advantage plans before FDA interchangeability designations fully mature. Lock in multi-year supply agreements with Indian CDOs to secure fill-finish capacity against emerging market entrants. Capture backward integration into protein A chromatography resin alternatives to neutralize single-source purification bottlenecks.
For New Entrants and Emerging Players: Brazil's ANVISA accelerated pathway offers lowest regulatory friction for manufacturers holding FDA or EMA-approved dossiers. Target maternal-fetal medicine protocols in the United Kingdom and Nordic markets where certolizumab's reduced placental transfer commands premium positioning. Deploy real-world evidence generation partnerships with national health systems to differentiate beyond analytical similarity.
For Investors and Strategic Acquirers: Capital is best deployed toward biosimilar specialists with dual-track regulatory capabilities spanning FDA/EMA and emerging market pathways. Long-term viability hinges on manufacturing scale advantages that survive originator price defense cycles. Monitor CMS reimbursement rulings on interchangeability substitution incentives as the critical inflection signal for biosimilar uptake velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Interchangeability Designation | Accelerates substitution timelines and compresses originator pricing power in Medicare Part D. |
| Continuous Processing Technology Adoption | Perfusion bioreactor deployment at Samsung Bioepis enables higher volumetric productivity than fed-batch methods. |
| Specialty Pharmacy Network Consolidation | CVS Caremark and Express Scripts capture dispensing margin and data assets from physician buy-and-bill arrangements. |
| EMA Comparability Guideline Alignment | Analytical similarity waivers reduce redundant clinical trial requirements for well-characterized biosimilar programs. |
| Indian PLI Scheme Capacity Expansion | CDSCO incentives accelerate local fill-finish infrastructure serving regulated export markets with lower cost structures. |
Study Parameters
A standing panel of drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers provided ongoing calibration throughout the research process. Primary interviews with payer access specialists and CDO operations heads combined with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient-volume modeling and top-down revenue reconciliation anchored market sizing across the analysis window.
Scenario-bracketing framed demand projections under varying biosimilar substitution assumptions and reimbursement policy trajectories. Segmentation dimensions modeled include product type, delivery mode, therapy area, end user, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to epidemiology-adjusted patient populations and pricing tier trajectories. Continuous processing technology adoption curves and interchangeability designation timelines served as key forecast inputs.
Practitioners should monitor FDA interchangeability rulings, CMS reimbursement policy shifts, and protein A resin supply disruptions for early signals of forecast deviation. Quarterly review of biosimilar substitution rates in Medicare Part D and EMA comparability guideline revisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
Nesiritide Market
Pharmaceuticals
Global Rheumatoid Arthritis Therapeutics Market
Pharmaceuticals
OX40 Receptor Agonist Market
Pharmaceuticals
Global Anticoccidial Drugs Market
Pharmaceuticals
Desloratadine Market
Pharmaceuticals
Global Ovulation Inducing Drugs Market
Pharmaceuticals
Oral Antibiotics Market
Pharmaceuticals
Saudi Arabia Pharmaceutical Market
Pharmaceuticals
Theophylline and Aminophylline Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Focal Segmental Glomerulosclerosis (FSGS) Therapeutics Market
Pharmaceuticals
B7-H3 Antibody Market
Pharmaceuticals
Targeted Therapeutics Market
Pharmaceuticals
Global Acetazolamide Market