
 Atopic Dermatitis Therapeutics Market | 2026-2036
Atopic Dermatitis Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Atopic Dermatitis Therapeutics Market Analysis
The capability gap between biologic-scale manufacturers and topical specialists is collapsing as JAK inhibitors and injectable therapies command higher reimbursement and R&D investment. AbbVie Inc. leverages its immunology infrastructure to sustain pipeline dominance across severe disease segments. Sanofi anchors its position through channel control in European dermatology networks. Eli Lilly & Company differentiates via manufacturing scale for systemic therapies targeting moderate-to-severe populations.
Atopic dermatitis therapeutics encompass pharmacological agents designed to modulate immune dysregulation, restore skin barrier function, and interrupt the IL-4, IL-13, and JAK-STAT signaling cascades central to disease pathophysiology. These therapies serve commercial and clinical purposes ranging from acute flare management to chronic disease modification in outpatient and institutional settings. Biologics occupy the highest-margin tier as physician-administered infusions and self-injectables capture severe disease spending, while JAK inhibitors represent the fastest-expanding oral systemic category reshaping patient adherence dynamics. Topical corticosteroids remain the mature volume base in pediatric and adult primary care, though immunomodulators increasingly occupy the maintenance niche between acute and chronic therapy.
FDA safety mandates on JAK inhibitors, EMA pharmacovigilance protocols for biologics, and WHO prequalification pathways for dermatology medicines collectively elevate clinical evidence standards and market access barriers. These frameworks compress timelines for post-market surveillance while expanding requirements for comparative effectiveness data across pediatric and adult indications. Stakeholders must monitor regulatory divergence between FDA and EMA on JAK class labeling, as this will determine portfolio prioritization and geographic launch sequencing for pipeline assets.
Market Dynamics
The FDA's evolving safety mandates on JAK inhibitors are compressing clinical trial timelines while elevating evidence requirements, forcing manufacturers to restructure development programs around comparative effectiveness data and pediatric labeling expansions.
Growth Catalysts
- EMA Pharmacovigilance Protocols:The European Medicines Agency's enhanced post-market surveillance frameworks for biologics accelerate physician confidence and institutional adoption across European dermatology networks.
- Pediatric Caregiver Demand:Parents of children with moderate-to-severe atopic dermatitis actively seek corticosteroid-sparing alternatives, driving formulary negotiations and long-term therapy transitions.
- Injectable Biologics:Self-administered subcutaneous therapies reduce clinic dependency and improve adherence profiles among working-age adults managing chronic disease.
Market Restraints
- API Manufacturing Concentration:Active pharmaceutical ingredient production for JAK inhibitors concentrates among a limited supplier base in India and China, exposing pipelines to geopolitical and quality audit disruptions.
- FDA Black Box Requirements:Cardiovascular and malignancy warnings mandated for the JAK inhibitor class create prescribing hesitation among primary care physicians and delay institutional protocol updates.
- Topical Corticosteroid Substitution:Inexpensive generic corticosteroids remain the default first-line therapy in resource-constrained settings, limiting upfront access to novel mechanisms.
Strategic Opportunities
- WHO Prequalification Pathways:The World Health Organization's expanding dermatology medicine standards open procurement channels for biosimilars in low- and middle-income health systems.
- Telemedicine Integration:Virtual dermatology platforms enable remote monitoring of treatment response, expanding reach into rural and underserved patient populations.
- Maintenance-Indication Labeling:Regulatory approvals for proactive therapy regimens extend treatment duration and capture patients previously cycling between flare and remission.
Industry Challenges
- Specialized Dermatology Trialists:Principal investigators with biologic and JAK inhibitor experience concentrate in academic medical centers, creating site activation bottlenecks for multi-regional studies.
- Legacy EHR Integration:Electronic health record systems in community dermatology practices lack structured fields for atopic dermatitis severity scoring, complicating real-world evidence collection.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Atopic Dermatitis Therapeutics Market |
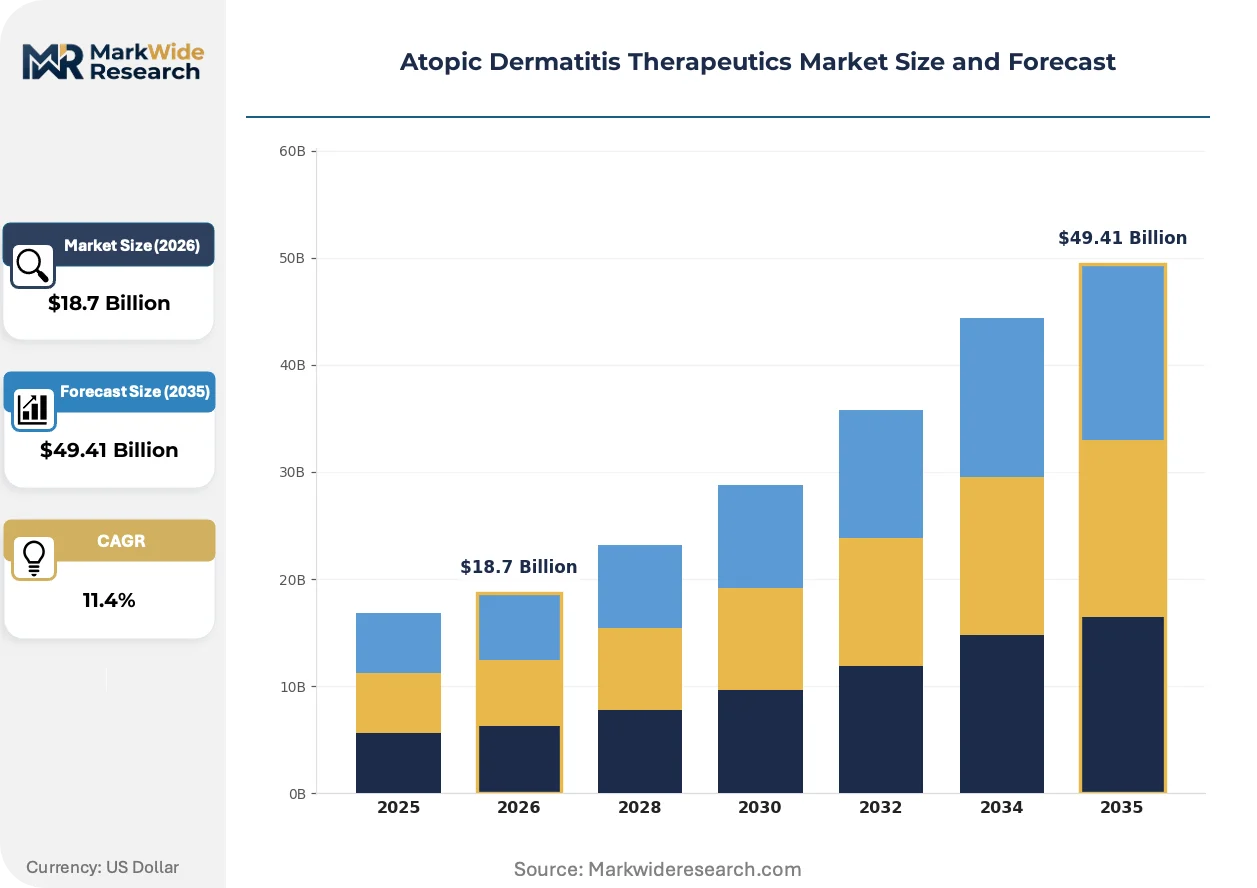
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Corticosteroids, Immunomodulators, Biologics, JAK Inhibitors Indication: Moderate Disease, Severe Disease, Recurring Flare-ups, Chronic Condition End User: Pediatric Patients, Adult Patients, Dermatology Clinics, Healthcare Institutions Delivery Mode: Topical, Injectable, Oral, Transdermal |
| Companies Covered | AbbVie Inc., Pfizer Inc., Sanofi, Regeneron Pharmaceuticals Inc., LEO Pharma, Novartis AG, Eli Lilly & Company, Incyte Corp., Galderma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Atopic Dermatitis Therapeutics Market Emerging Trajectories
Oral JAK inhibitors are reconfiguring competitive dynamics by collapsing the historical boundary between topical specialists and systemic therapy manufacturers, while regulatory divergence between FDA and EMA labeling requirements forces parallel development tracks.
Next-generation selective JAK1 inhibitors are displacing first-generation pan-JAK blockers in physician preference hierarchies. Dermatology clinics in the United States and Germany are prioritizing these agents for biologic-experienced patients seeking oral alternatives. The displacement is compressing reimbursement timelines for older JAK assets and forcing portfolio rationalization among mid-cap developers.
REACH compliance deadlines in the European Union are tightening excipient purity standards for topical formulations. Manufacturers reformulating emollient bases to eliminate classified substances face 18-24 month stability revalidation cycles. The burden falls disproportionately on European contract manufacturers supplying private-label dermatology brands.
Caregiver-driven treatment decisions are fragmenting the traditional prescriber-patient dyad in pediatric atopic dermatitis. Parents now initiate specialist referrals armed with social media-sourced comparisons of biologic safety profiles, particularly in suburban United States markets. Pharmaceutical account teams are retraining field forces to engage dual decision-makers during clinic consultations.
Atopic Dermatitis Therapeutics Market Segmentation
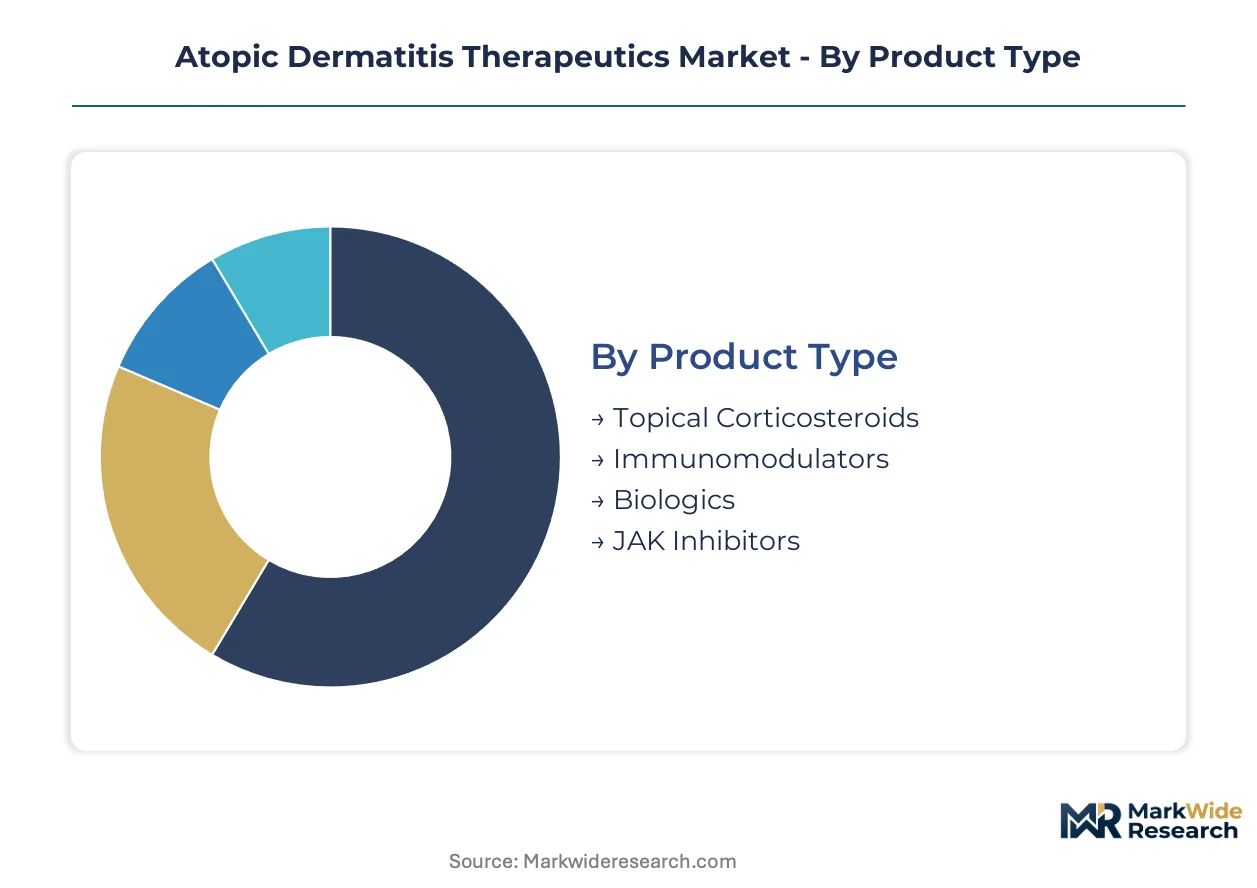
Atopic dermatitis therapeutics fragment across four intersecting dimensions that determine pricing power, regulatory burden, and prescriber loyalty. Product type and indication severity create the primary fault lines for portfolio strategy, while delivery mode and end-user concentration shape channel economics and reimbursement negotiations.
Product Type:
Generic substitution pressure concentrates most intensely on mature topical categories, while novel mechanisms command protected pricing windows.
- Topical Corticosteroids:Hydrocortisone, betamethasone, and clobetasol formulations constitute the high-volume, low-margin foundation of first-line therapy. Demand concentrates in pediatric primary care across the United States and India, where cost-containment protocols and caregiver familiarity sustain prescribing inertia despite safety concerns with prolonged use.
- Biologics:Monoclonal antibodies targeting IL-4 and IL-13 pathways deliver the highest per-patient revenue in severe disease management. Demand clusters in United States academic medical centers and German dermatology networks, where institutional prior authorization pathways and specialist density accelerate adoption over conventional immunosuppressants.
- JAK Inhibitors:Oral and topical Janus kinase blockers occupy the fastest-expanding mechanism class, reshaping adherence dynamics for patients rejecting injectable regimens.
- Immunomodulators:Calcineurin inhibitors such as tacrolimus and pimecrolimus serve the maintenance niche between acute flare management and chronic systemic therapy.
Topical corticosteroids retain volume leadership; JAK inhibitors hold the steepest expansion curve.
Indication:
Severity stratification determines prescriber specialty access and reimbursement tier placement, with the most severe cases generating disproportionate lifetime value.
- Severe Disease:Patients failing multiple prior therapies qualify for biologic and systemic JAK inhibitor coverage through specialty pharmacy channels. Concentration in United States Medicare and commercial managed care populations drives prior authorization complexity and patient assistance program investment.
- Moderate Disease:This segment bridges primary care dermatology and specialist referral, representing the primary battleground for JAK inhibitor penetration against phototherapy and traditional systemic agents. United Kingdom and French prescribing guidelines increasingly favor targeted therapies over cyclosporine in this severity band.
- Recurring Flare-ups:Intermittent high-potency corticosteroid use dominates this pattern, with limited biologic uptake due to discontinuous treatment need.
- Chronic Condition:Long-term maintenance indication labeling enables proactive therapy models and extended revenue capture.
Severe disease commands premium pricing; moderate disease offers the broadest addressable population expansion.
End User:
Decision-making authority fragments between institutional procurement and individual prescriber preference, with pediatric populations introducing caregiver influence into the selection process.
- Pediatric Patients:Corticosteroid-sparing alternatives gain traction as parents of children with moderate-to-severe disease actively research biologic safety profiles and demand specialist referrals. United States suburban markets exhibit the highest caregiver-driven treatment switching rates.
- Dermatology Clinics:Outpatient specialty practices in Germany and Japan concentrate biologic initiation and maintenance monitoring, with EMA pharmacovigilance protocols reinforcing physician confidence in long-term safety data.
- Adult Patients:Working-age populations prioritize self-administered therapies minimizing clinic absenteeism, particularly in United States commercial insurance pools.
- Healthcare Institutions:Academic medical centers and hospital-based dermatology departments anchor clinical trial recruitment and protocol development for novel mechanisms.
Pediatric patients represent the most rapidly expanding prescriber priority; dermatology clinics control the highest-value initiation decisions.
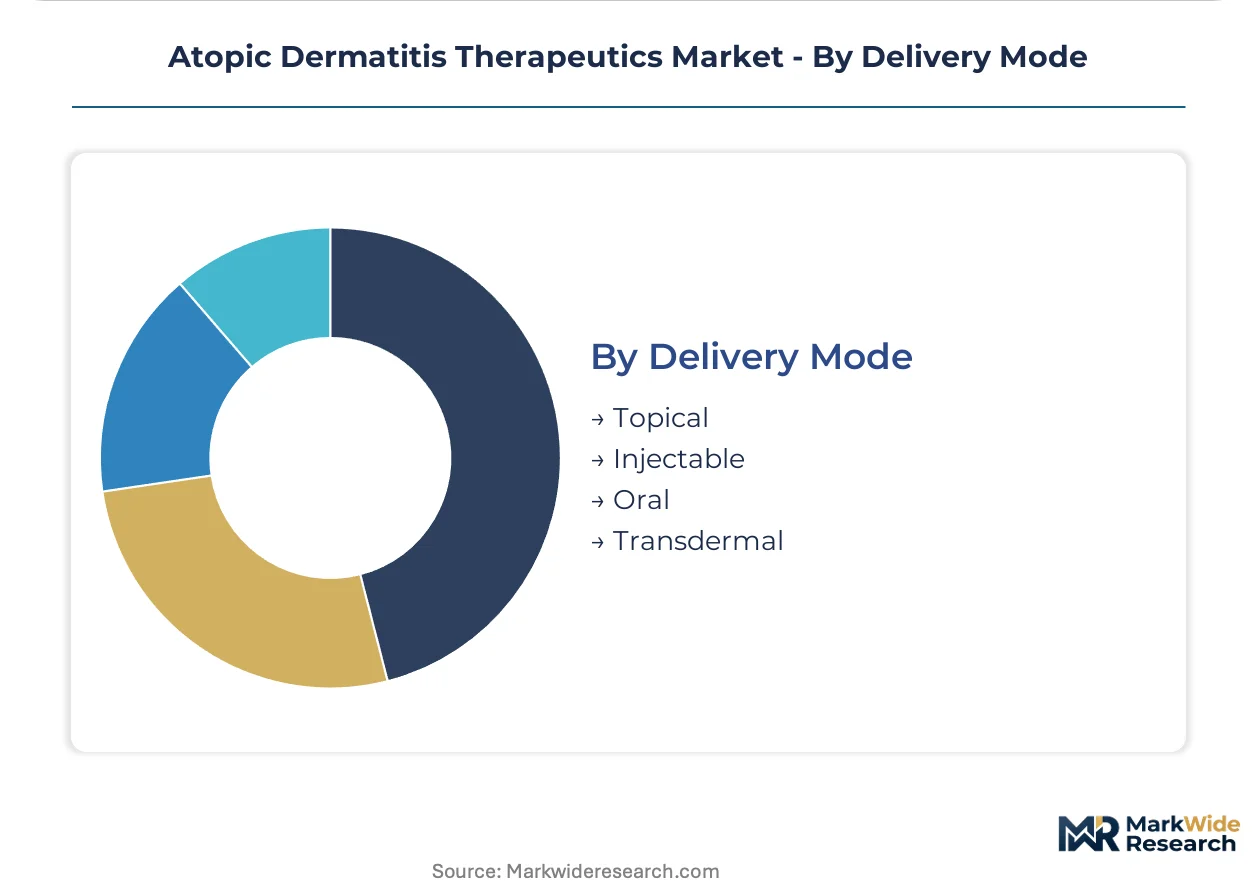
Delivery Mode:
Route of administration determines patient autonomy, cold-chain requirements, and the competitive set against which therapies benchmark for reimbursement.
- Injectable:Subcutaneous biologics require cold-chain distribution and specialty pharmacy coordination, with United States hub services managing prior authorization and patient onboarding. Self-injection training programs reduce clinic dependency and improve persistence rates among employed adults.
- Oral:JAK inhibitors in tablet form collapse the convenience gap with topical therapies while avoiding injection burden, attracting biologic-experienced patients seeking regimen flexibility.
- Topical:Creams, ointments, and lotions dominate pediatric and primary care prescribing, with REACH compliance deadlines in the European Union forcing excipient reformulation and stability revalidation cycles.
- Transdermal:Patch-based delivery remains experimental for atopic dermatitis, with limited commercial presence outside clinical development programs.
Injectable biologics retain the highest per-patient revenue; oral systemic therapies are climbing the fastest toward parity in prescriber preference hierarchies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while Germany and Japan compete on protocol standardization, creating a two-tier reimbursement landscape that shapes launch sequencing for pipeline assets.
United States
Biologic penetration in academic medical centers and dermatology clinics outpaces all other national markets, with prior authorization complexity driving investment in hub services and patient assistance programs. FDA safety mandates on JAK inhibitors compress clinical trial timelines while elevating cardiovascular and malignancy evidence requirements. The Northeast corridor and California clusters concentrate principal investigators with biologic and JAK inhibitor trial experience.
Germany
Dermatology networks anchor biologic initiation and maintenance monitoring, with EMA pharmacovigilance protocols reinforcing physician confidence in long-term safety data. The country's national pharmaceutical regulator maintains stringent post-market surveillance frameworks that accelerate institutional adoption. Bavaria and North Rhine-Westphalia host the densest concentrations of outpatient specialty practices managing severe disease populations.
Japan
PMDA review pathways for dermatology medicines emphasize local clinical evidence generation, extending development timelines but securing durable market access upon approval. METI industrial policy supports domestic manufacturing scale for systemic therapies. The Kanto region around Tokyo concentrates regulatory affairs expertise and specialist referral networks.
United Kingdom
NICE technology appraisals increasingly favor targeted therapies over cyclosporine for moderate-to-severe disease, shifting formulary placement toward JAK inhibitors and biologics. Prescribing guidelines from the national health service create standardized access pathways that reduce regional variation. London and the Southeast concentrate dermatology trial sites and specialist training programs.
India
Active pharmaceutical ingredient production for JAK inhibitors concentrates among suppliers serving global pipelines, exposing manufacturers to quality audit disruptions and geopolitical friction. CDSCO accelerated approval pathways for dermatology medicines expand access to biosimilars in tier-one cities. Maharashtra and Gujarat host contract manufacturing facilities supplying emollient bases and topical formulations.
Atopic Dermatitis Therapeutics Market Vendor Landscape
Concentration sits with immunology-scale conglomerates that leverage cross-indication infrastructure to sustain pipeline dominance across severe disease segments. The vendor base stratifies into three tiers: multinational biopharmaceuticals with dermatology divisions, mid-cap developers with single-mechanism focus, and regional specialists in topical formulations. Two competitive moves dominate: portfolio diversification into oral systemic categories and strategic partnerships to secure principal investigator networks for multi-regional trials.
Among immunology-scale conglomerates, AbbVie Inc., Sanofi, and Eli Lilly & Company exemplify the infrastructure-heavy archetype that anchors severe disease segments through channel control and manufacturing scale. These entities occupy positions where cross-portfolio synergies in immunology therapeutic areas reinforce dermatology-specific investment. Mid-cap developers with JAK inhibitor specialization represent the fastest-expanding competitive set, displacing first-generation mechanisms through selective target profiles.
| Leading Market Players |
|---|
| AbbVie Inc. |
| Pfizer Inc. |
| Sanofi |
| Regeneron Pharmaceuticals Inc. |
| LEO Pharma |
| Novartis AG |
| Eli Lilly & Company |
| Incyte Corp. |
| Galderma |
| Others |
Supply Flow & Price Mechanics
API sourcing substitution from Western European fine chemical houses toward Indian and Chinese contract manufacturers simultaneously collapses manufacturing cost baselines and concentrates pricing power among intermediaries controlling JAK inhibitor precursor supply. This geographic shift feeds back into formulary negotiations as manufacturers pass through cost savings to secure preferred tier placement against entrenched biologics.
Pricing Analysis
The customization-premium spread separates standard topical corticosteroid contracts from configured biologic access programs with embedded patient support services. Pricing stratifies across premium, standard, and economy tiers where biologics command value-based arrangements tied to treatment response, while generic corticosteroids compete on tender price alone. Cost compression in the oral systemic category is intensifying as selective JAK1 inhibitors displace first-generation pan-JAK blockers and compress reimbursement timelines. Pediatric caregivers exhibit highest price sensitivity for maintenance therapies, whereas severe disease populations in United States academic centers demonstrate lowest sensitivity due to prior authorization insulation.
Supply Chain Analysis
India and China anchor active pharmaceutical ingredient production for JAK inhibitors, with Maharashtra and Gujarat hosting contract manufacturing facilities serving global pipelines. Raw material dependencies center on specialized kinase inhibitor precursors, high-purity solvents, and REACH-compliant excipient bases for topical formulations. Single-source vulnerability concentrates in intermediate suppliers subject to CDSCO quality audit disruptions and geopolitical friction over pharmaceutical trade. Distribution runs through United States specialty pharmacy hubs managing cold-chain biologics alongside oral therapies, with patient onboarding services bundled into channel economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The atopic dermatitis therapeutics market functions as a service-attach opportunity where patient assistance programs and adherence monitoring platforms expand faster than molecule sales alone. Hub services, co-pay support infrastructure, and remote disease management tools constitute the recurring-revenue layer driving lifetime value capture beyond initial prescription.
For Market Incumbents: Secure principal investigator networks in United States academic medical centers before site activation bottlenecks harden for multi-regional JAK inhibitor trials. Consolidate manufacturing scale through backward integration into API supply to mitigate concentration risk in Indian and Chinese precursor markets. Channel control in German dermatology networks and United States specialty pharmacy hubs remains the priority defensive lever against mid-cap JAK specialists. For New Entrants and Emerging Players: FDA pediatric labeling fast-tracks offer the most penetrable regulatory pathway for novel mechanisms seeking orphan exclusivity windows. White-space targets concentrate in moderate disease populations cycling between phototherapy and systemic therapy in United Kingdom and French markets. A telemedicine-integrated go-to-market angle enables remote monitoring partnerships that bypass established clinic gatekeepers. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed JAK inhibitor developers possessing selective target profiles but lacking commercial infrastructure. Five-to-ten year viability hinges on portfolio diversification beyond single-mechanism dependence and manufacturing scale adequacy for systemic therapy supply. The signal to watch is FDA-EMA regulatory divergence on JAK class labeling, which will determine geographic launch sequencing and stranded asset risk.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | Pediatric indication expansions through FDA fast-track programs extend patent-protected revenue capture. |
| Manufacturing Scale-Up | Domestic JAK inhibitor API production under METI industrial policy secures Japanese market access durability. |
| Pipeline Diversification | Next-generation selective JAK1 inhibitors displace pan-JAK blockers in United States prescriber preference hierarchies. |
| Licensing Agreement | European dermatology network partnerships accelerate biologic adoption under EMA pharmacovigilance protocols. |
| Reimbursement Strategy | NICE technology appraisals in the United Kingdom shift formulary placement toward targeted therapies over cyclosporine. |
Methodological Framework
Operator-level perspectives from drug development executives, regulatory affairs leads, formulary directors, and payer access specialists anchored the qualitative base for this study. Primary interview findings triangulated against FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases. Bottom-up patient flow modeling and top-down pharmaceutical spending analysis converged to validate market sizing across the analysis window.
Sensitivity analysis tested forecast robustness against JAK inhibitor safety labeling revisions, biosimilar entry timelines, and pediatric indication expansion scenarios. The analytical framework segmented volume and value across treatment line, dosage form, administration route, and regional regulatory clusters throughout the projection horizon. CAGRs derived from patient population epidemiology, therapy transition rates, and pricing trajectory assumptions for biologics versus oral systemics.
Underlying assumptions cover stable FDA-EMA regulatory convergence, with deviation risk concentrated in JAK class cardiovascular warning escalations and API supply disruptions from Indian manufacturing inspections. Forecasts reflect these conditions with explicit acknowledgment that WHO prequalification pathway acceleration or REACH compliance deadline extensions would revise growth trajectories. Recalibration cycles align with material shifts in regulatory labeling, biosimilar approval decisions, and principal investigator network availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dermatology
Australia Skin Laser Market
Dermatology
Global Dermatology Lasers Market
Dermatology
Global Onychomycosis Market
Dermatology
Homecare Dermatology Energy-Based Devices Market
Dermatology
Dermabrasion Market
Dermatology
Dermabrasion and Micro Needling Market
Dermatology
Darier Disease Drugs Market
Dermatology
Global Dermatology Cro Market
Dermatology
China Scar Treatment Market
Dermatology
Dermatophytic Onychomycosis Treatment Market
Dermatology
Scleroderma Treatment Market
Dermatology
Skin Excision Market
Dermatology
Global Ozone Therapy in Dermatology Market
Dermatology
Dermatology Diagnostic Devices and Therapeutics Market
Dermatology
Dermatology Devices Market
Dermatology
Immunodermatology Market