
 Global Appendicitis Market | 2026-2036
Global Appendicitis Market Size, Share, and Industry Trends Forecast 2026-2036
Global Appendicitis Market Foresight
Postoperative monitoring and surgical support subscriptions are expanding as a distinct revenue layer in appendicitis care, shifting hospital procurement from capital expenditure toward bundled service contracts. Medtronic plc leverages its laparoscopic platform ecosystem to sustain recurring revenue through instrument sterilization and maintenance programs. Johnson & Johnson Services Inc anchors its position through Ethicon's suture and stapling portfolios that dominate operating room workflows. Pfizer Inc competes via antibiotic supply agreements that lock in formulary placement across integrated delivery networks.
Appendicitis is an acute inflammatory condition of the vermiform appendix typically diagnosed through elevated white blood cell counts, C-reactive protein levels, and cross-sectional imaging such as contrast-enhanced CT or graded compression ultrasound, with treatment spanning surgical resection or nonoperative antibiotic protocols depending on perforation risk and patient stability. Emergency Surgery applications command the largest procedure volume and device utilization, while Laparoscopic Devices represent the fastest-growing product category as minimally invasive approaches displace open procedures in uncomplicated cases. Antibiotic Therapy as a nonoperative Treatment Method is gaining structural traction in select patient populations, creating parallel margin pools distinct from surgical hardware.
FDA 510(k) clearance pathways and EU MDR conformity assessments govern device commercialization, while WHO Essential Medicines List inclusion shapes antibiotic procurement standards in lower-resource settings. These regulatory frameworks directly influence product development priorities, clinical trial design, and geographic launch sequencing for manufacturers. Stakeholders must monitor evolving nonoperative management guidelines and reimbursement policy shifts that could reallocate volume between surgical and pharmaceutical interventions.
Market Dynamics
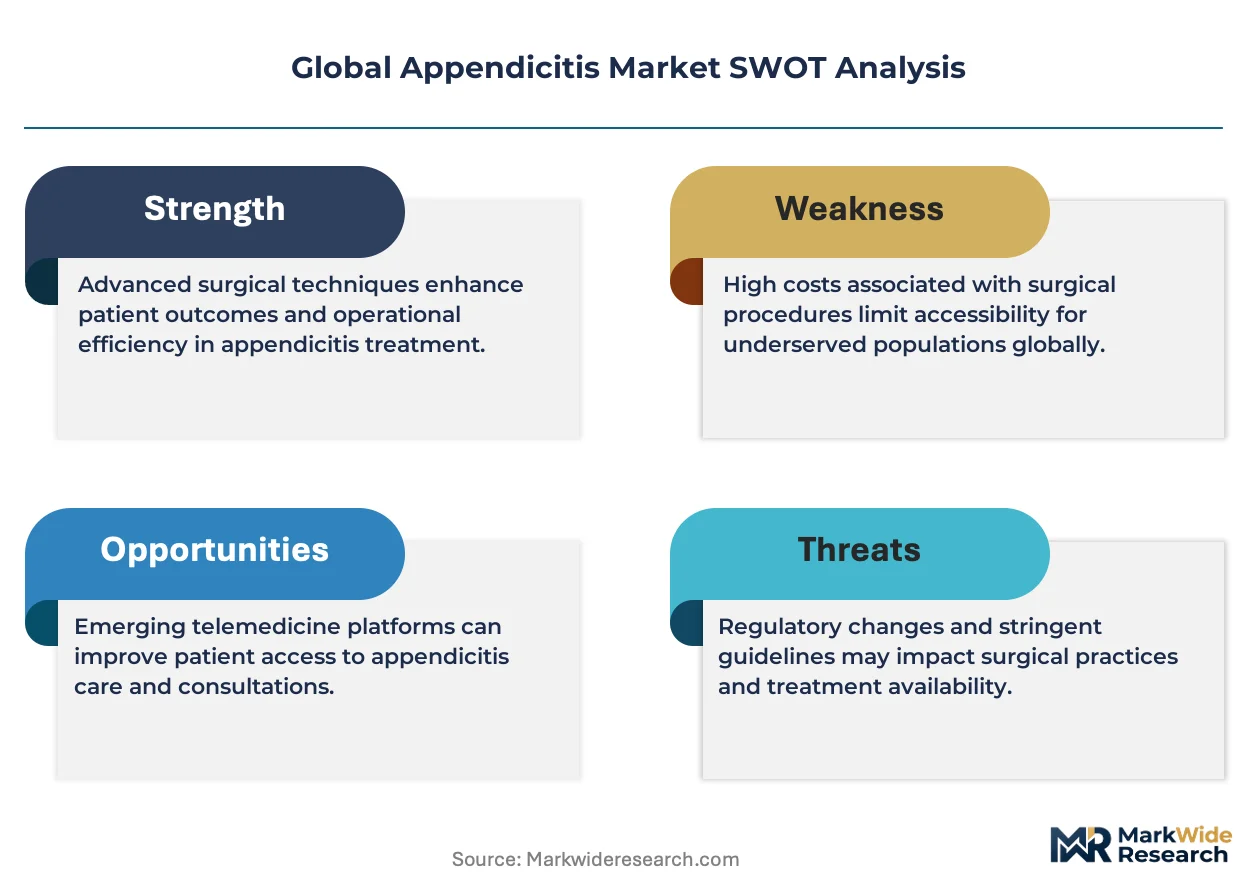
EU MDR conformity assessment timelines and FDA 510(k) pathway modifications are compressing device commercialization windows while antibiotic stewardship protocols are reallocating procedure volumes between surgical and pharmaceutical interventions.
Growth Catalysts
- Emergency Surgery Procedural Volume:Rising acute presentation rates in aging populations are amplifying demand for laparoscopic platforms and disposable instrumentation across hospital systems.
- EU MDR Harmonization:Streamlined conformity assessment procedures for Class IIa surgical devices are accelerating market access for manufacturers with established quality management systems.
- Antibiotic Protocol Refinement:Nonoperative management guidelines from the American College of Surgeons are expanding eligible patient pools for pharmaceutical-first treatment pathways.
Market Restraints
- Single-Use Instrument Cost Structure:Disposable trocar and stapler pricing creates per-procedure cost pressure that limits adoption in budget-constrained hospital systems.
- Supply Concentration Risk:German and Japanese precision component manufacturers dominate electrosurgical generator subassembly supply, creating vulnerability to regional logistics disruptions.
- Technical Limitation:Current laparoscopic platforms lack haptic feedback sufficient for perforated appendicitis cases, preserving open procedure requirements in complex presentations.
Strategic Opportunities
- Underpenetrated Geography:India's tier-2 and tier-3 cities present untapped demand as CDSCO streamlined approval pathways and government health insurance expansion improve surgical access.
- Technology Convergence:Integration of artificial intelligence-assisted imaging with conventional laparoscopic stacks is creating differentiated value propositions for academic medical centers.
- Distribution Innovation:Direct-to-hospital instrument sterilization and maintenance subscriptions are displacing traditional capital equipment sales models in integrated delivery networks.
Industry Challenges
- Specialized Surgical Workforce Scarcity:Fellowship-trained minimally invasive surgeons remain concentrated in tertiary centers, limiting laparoscopic procedure penetration in community hospitals.
- EU MDR Technical Documentation Burden:Expanded clinical evidence requirements for legacy device recertification are consuming regulatory affairs bandwidth and delaying portfolio updates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Appendicitis Market |
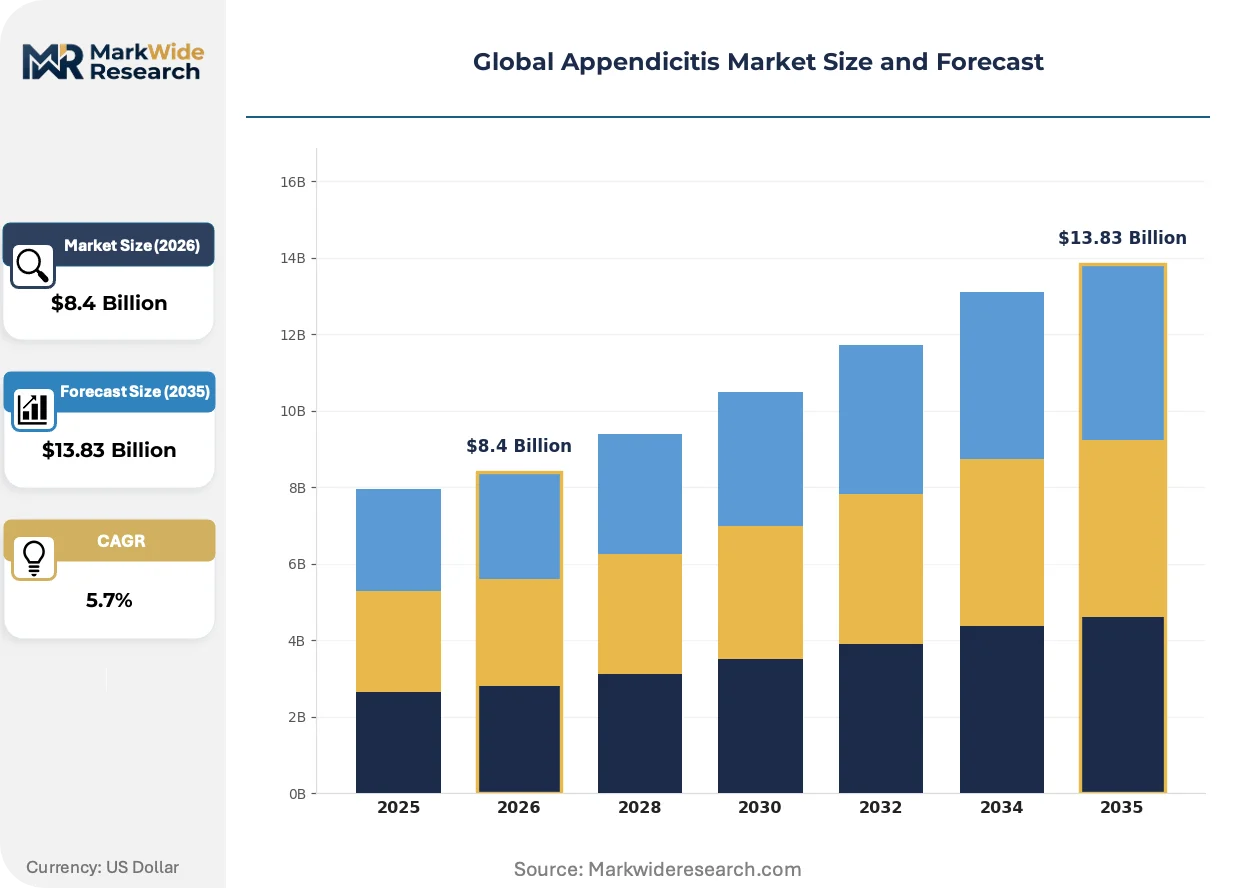
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $13.83 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surgical Instruments, Diagnostic Imaging, Laparoscopic Devices, Antibiotics, Pain Management Solutions Application: Emergency Surgery, Outpatient Treatment, Pediatric Cases, Geriatric Care, Postoperative Recovery Medical Practitioner Type: General Surgeons, Radiologists, Anesthesiologists, Emergency Physicians, Pediatricians Treatment Method: Conventional Surgery, Laparoscopic Surgery, Antibiotic Therapy, Minimally Invasive Procedures, Observation |
| Companies Covered | Johnson & Johnson Services Inc, Pfizer Inc, Medtronic plc, Baxter International Inc, B. Braun Melsungen, Stryker Corporation, Sanofi, GSK plc, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Appendicitis Market Shifts & Advancements
Device miniaturization and intelligent instrumentation are converging with evolving reimbursement frameworks to reshape how appendicitis care is delivered and monetized across acute care settings.
Single-incision laparoscopic surgery platforms are expanding into standard emergency department workflows as instrument articulation mechanisms improve triangulation capability. Community hospital systems in the United States and Germany are adopting these systems at moderate pace to differentiate service lines without full robotic infrastructure investment. This expansion is compressing the addressable market for conventional multi-port devices in uncomplicated cases while creating aftermarket revenue streams through specialized training programs.
EU MDR Article 10 post-market surveillance requirements are mandating systematic device performance tracking across implanted and long-term use surgical hardware. Manufacturers must now maintain active safety monitoring systems that feed into periodic safety update reports, increasing compliance infrastructure costs. Class IIa laparoscopic instruments face heightened scrutiny in Germany and France where notified bodies apply enhanced clinical evaluation standards.
Hospital procurement departments are consolidating vendor relationships through multi-year bundled contracts that span devices, disposables, and technical support. Traditional equipment distributors in Japan and the United States are losing ground to manufacturer-direct service organizations that capture lifetime value through subscription pricing. This concentration is most visible in integrated delivery networks where standardization across facility networks overrides individual surgeon preference.
Global Appendicitis Market Segmentation
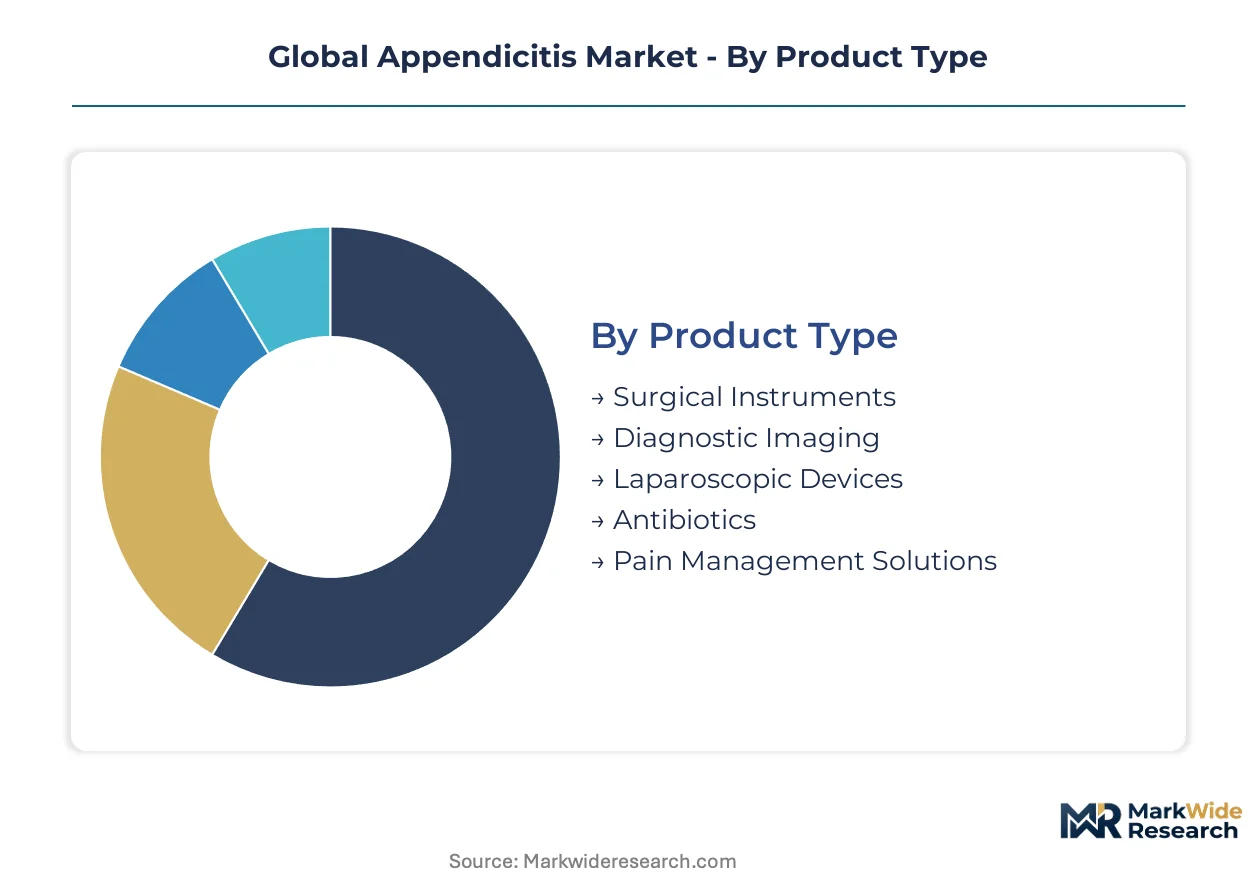
Appendicitis care delivery fragments across procedural intensity, patient acuity, and intervention philosophy. Procurement decisions diverge sharply between emergency surgical workflows and pharmaceutical-first management pathways.
Product Type:
Hospital capital budgets and per-procedure reimbursement rates determine device selection intensity across product categories.
- Surgical Instruments:Standardized retractors, forceps, and scalpels form the baseline infrastructure for open appendectomy procedures. Demand concentrates in United States community hospitals and German regional medical centers where conventional surgery retains substantial volume amid laparoscopic transition.
- Laparoscopic Devices:Articulating graspers, trocar systems, and insufflation platforms enable minimally invasive tissue manipulation through small abdominal incisions. United States academic medical centers and Japanese tertiary hospitals drive specification requirements as procedural volume shifts toward single-incision platforms.
- Diagnostic Imaging:Ultrasound transducers and CT scanner protocols support preoperative confirmation.
- Antibiotics:Broad-spectrum and targeted antimicrobial formulations serve nonoperative management protocols.
- Pain Management Solutions:Regional anesthesia delivery systems and multimodal analgesia protocols support recovery trajectories.
Volume sits with Surgical Instruments; growth tilts toward Laparoscopic Devices.
Application:
Patient presentation severity and facility capability boundaries reshape service line economics across application segments.
- Emergency Surgery:Acute perforation risk and hemodynamic instability mandate immediate operative intervention in hospital operating suites. Germany's trauma network hospitals and United States Level I trauma centers capture the highest procedure density through dedicated emergency surgical teams.
- Outpatient Treatment:Selected uncomplicated cases with reliable follow-up infrastructure qualify for ambulatory antibiotic protocols. Japan's clinic-based primary care networks and United States urgent care chains are expanding eligible patient identification through standardized risk stratification tools.
- Pediatric Cases:Age-adjusted surgical techniques and anesthesia protocols address developmental anatomical considerations.
- Geriatric Care:Comorbidity-adjusted intervention selection balances operative risk against perforation consequences.
- Postoperative Recovery:Wound care and complication surveillance protocols complete the care continuum.
Emergency Surgery commands absolute procedure counts; Outpatient Treatment expands most quickly.
Medical Practitioner Type:
Specialty certification boundaries and scope-of-practice regulations determine which clinicians control treatment decisions.
- General Surgeons:Board-certified abdominal surgeons retain definitive authority for operative intervention decisions and technical execution. United States surgical residency programs and German Facharzt certification pathways produce the specialist workforce that dominates hospital-based appendectomy volume.
- Emergency Physicians:Frontline diagnostic authority and initial therapeutic selection rest with emergency medicine specialists. Japan's emergency medicine board system and United States emergency department staffing models place these practitioners at the critical decision node between operative and nonoperative pathways.
- Radiologists:Cross-sectional imaging interpretation guides diagnostic confirmation.
- Anesthesiologists:Perioperative risk management and pain control protocols fall under their domain.
- Pediatricians:Age-specific presentation recognition and referral coordination shape pediatric pathways.
Clinical authority concentrates with General Surgeons; Emergency Physicians are gaining decision influence fastest.
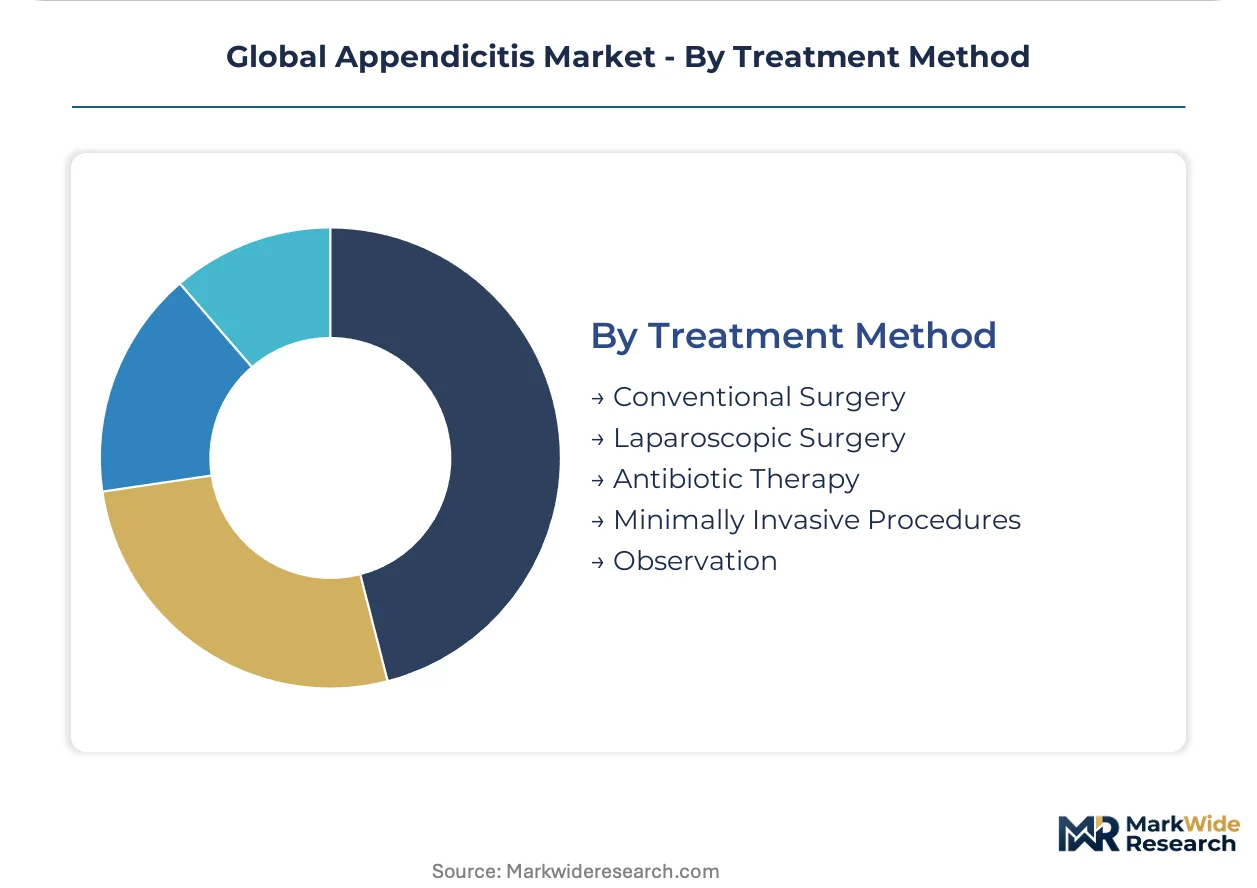
Treatment Method:
Evidence base evolution and reimbursement policy adjustments reallocate patients across intervention categories.
- Laparoscopic Surgery:Multi-port and single-incision techniques reduce wound complications and accelerate return to function compared with open procedures. Japanese Society of Endoscopic Surgery guidelines and American College of Surgeons quality programs are standardizing training requirements across hospital systems.
- Antibiotic Therapy:Nonoperative management with scheduled reassessment protocols avoids surgical intervention in selected uncomplicated presentations. Finland's national appendicitis antibiotic trial infrastructure and United Kingdom randomized study networks are generating the outcome data that expands insurance coverage eligibility.
- Conventional Surgery:Open laparotomy retains indication for perforated cases with diffuse peritonitis.
- Minimally Invasive Procedures:Natural orifice transluminal approaches represent experimental alternatives.
- Observation:Diagnostic uncertainty protocols mandate serial examination in atypical presentations.
Procedure volume still favors Laparoscopic Surgery; Antibiotic Therapy shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device manufacturers concentrate production in Germany and Japan, while procedural consumption tilts toward the United States where emergency surgical volume and reimbursement density create the highest revenue capture per capita.
United States
Level I trauma centers and academic medical centers in Boston, Houston, and Los Angeles drive laparoscopic platform procurement through dedicated emergency surgical teams. FDA 510(k) clearance pathways compress commercialization timelines for Class IIa surgical instruments. The Southeast corridor from Atlanta to Miami exhibits the fastest adoption velocity for single-incision systems as community hospital systems differentiate service lines.
Germany
Trauma network hospitals and Facharzt-certified surgical departments sustain the highest per-capita appendectomy volume in Europe. EU MDR Article 10 post-market surveillance requirements mandate systematic device performance tracking across implanted surgical hardware. The Baden-Württemberg precision engineering cluster around Stuttgart dominates electrosurgical generator subassembly supply for global manufacturers.
Japan
Tertiary hospitals under the Japanese Society of Endoscopic Surgery guidelines standardize training requirements and drive specification intensity for articulating graspers. PMDA marketing approval pathways align with international standards while maintaining distinct clinical trial design expectations. The Kansai region surrounding Osaka concentrates domestic instrument sterilization and maintenance service providers serving manufacturer-direct subscription contracts.
India
Tier-2 and tier-3 cities present untapped procedural demand as government health insurance expansion improves surgical access beyond metropolitan centers. CDSCO streamlined approval pathways for Class IIa devices accelerate market entry for established quality management systems. The Maharashtra-Gujarat industrial corridor hosts emerging domestic manufacturers of disposable trocar systems targeting price-sensitive hospital procurement.
United Kingdom
Randomized study networks through the National Institute for Health and Care Research generate outcome data expanding insurance coverage eligibility for nonoperative antibiotic protocols. NHS England bundled payment pilots reallocate volume between surgical and pharmaceutical interventions based on cost-effectiveness thresholds. The Oxford-Cambridge-London triangle concentrates health technology assessment capability influencing European guideline development.
Global Appendicitis Market Competitive Landscape
Top-tier vendors anchor integrated platform ecosystems, while mid-tier specialists compete on instrument sterilization subscriptions and regional service density. The vendor base stratifies across three tiers: multinational conglomerates with laparoscopic platform breadth, pharmaceutical manufacturers with antibiotic formulary lock-in, and regional distributors losing ground to manufacturer-direct organizations. Consolidation pressure favors players with captive supply of precision electrosurgical components and established notified body relationships under EU MDR.
Among diversified healthcare conglomerates, Johnson & Johnson Services Inc, Medtronic plc, and Pfizer Inc exemplify the three dominant competitive archetypes. Johnson & Johnson Services Inc occupies a position representing surgical hardware incumbency through suture and stapling portfolio dominance. Medtronic plc anchors the platform-ecosystem tier where recurring revenue flows from instrument sterilization and maintenance programs. Pfizer Inc sits within the pharmaceutical-first intervention vector where antibiotic supply agreements lock in formulary placement across integrated delivery networks.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc |
| Pfizer Inc |
| Medtronic plc |
| Baxter International Inc |
| B. Braun Melsungen |
| Stryker Corporation |
| Sanofi |
| GSK plc |
| Novartis AG |
| Others |
Supply & Pricing Matrix
Stainless steel alloy costs for trocar cannulas and laparoscopic graspers flow from German precision forges through three-tier pricing structures separating premium articulating instruments from standard fixed-angle devices and economy disposable sets procured by India's tier-2 hospitals.
Pricing Analysis
Margin tightening in mid-tier laparoscopic platforms reflects concentrated purchasing power within United States integrated delivery networks and Japanese hospital chains. Three-tier pricing structure across premium, standard, and economy levels differentiates by instrument articulation capability, FDA 510(k) clearance status, and bundled sterilization service inclusion. Cost compression accelerates in standard-tier disposable trocars as Maharashtra-Gujarat domestic manufacturers enter with CDSCO-approved alternatives. Community hospital procurement committees exhibit highest price sensitivity; academic medical centers prioritize specification compliance over per-unit cost.
Supply Chain Analysis
Instrument refurbishment and sterilization service returns flow through Osaka-based technical centers serving manufacturer-direct subscription contracts across East Asian markets. Electrosurgical generator subassembly production concentrates in Germany's Baden-Württemberg cluster, Japan's Kansai precision manufacturing zone, and select United States Midwest industrial corridors. Supply chains rest on titanium alloy sheet, medical-grade polymer resins, and precision-machined actuator components. Single-source vulnerability persists for articulating mechanism bearings sourced from Japanese specialty suppliers. Distribution runs through manufacturer-direct service organizations displacing traditional regional distributors in consolidated procurement environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR notified body capacity constraints and extended conformity assessment timelines prop pricing power for incumbent manufacturers with established quality management certifications, creating supply-constrained conditions favoring prepared players.
For Market Incumbents: Deepen backward integration into precision electrosurgical component manufacturing to reduce exposure to Baden-Württemberg supply concentration. Expand sterilization and maintenance subscription penetration across United States integrated delivery networks before domestic competitors achieve CDSCO scale. Prioritize EU MDR technical documentation investment to defend against recertification delays threatening legacy device portfolios. For New Entrants and Emerging Players: Begin with India's tier-2 and tier-3 cities where government health insurance expansion outpaces established service infrastructure. Target antibiotic therapy protocol support services as the most penetrable segment given pharmaceutical-first guideline expansion in Finland and United Kingdom study networks. Deploy direct-to-hospital instrument sterilization subscriptions as the primary go-to-market mechanism bypassing traditional distributor relationships. For Investors and Strategic Acquirers: FDA 510(k) clearance pathway modifications accelerating Class IIa surgical device timelines is the leading indicator that regulatory arbitrage opportunities are compressing for mid-tier specialists. Long-term viability centers on platform-ecosystem players capturing recurring instrument service revenue rather than transactional device vendors. Monitor American College of Surgeons nonoperative management guideline revisions as the critical signal for surgical volume reallocation between hardware and pharmaceutical interventions.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Acceleration | Streamlined notified body relationships compress market access timelines for Class IIa laparoscopic instruments in Germany and France. |
| Hospital System Partnership Expansion | Bundled device-service contracts with United States Level I trauma centers lock in multi-year procurement commitments against competitor entry. |
| Antibiotic Therapy Protocol Development | Nonoperative management guideline alignment with American College of Surgeons criteria expands addressable patient pools beyond surgical hardware. |
| Software Companion Development | AI-assisted imaging integration with conventional laparoscopic stacks differentiates platform offerings for academic medical center procurement. |
| Reimbursement Strategy Investment | NHS England bundled payment pilot alignment positions manufacturers for cost-effectiveness threshold compliance in European markets. |
Research Methodology
Independent corroboration across hospital procurement databases, GPO contract filings, and CMS Medicare reimbursement data underwrites the qualitative findings presented in this study. Primary interviews with general surgeons, emergency physicians, hospital purchasing committee members, and biomedical engineers combined with secondary validation from FDA 510(k) clearance records, EU MDR notified body documentation, and WHO Essential Medicines List procurement standards. Bottom-up procedure volume estimates and top-down market sizing triangulate across the analysis window.
Comparable-period anchoring to historical emergency surgery procedural volumes and laparoscopic device shipment data establishes the forecast baseline across the projection horizon. Segmentation modeling spans product type, application intensity, treatment method philosophy, and regional regulatory cluster variations. CAGRs derive from trend extrapolation of procedural volume shifts, reimbursement rate adjustments, and technology substitution patterns. Antibiotic stewardship protocol adoption curves and single-incision platform penetration rates serve as industry-specific forecast inputs.
Underlying measurement precision varies by segment; laparoscopic device revenue estimates carry tighter precision than antibiotic therapy protocol volume given hospital procurement data availability versus ambulatory prescription tracking limitations. Forecasts reflect documented assumptions regarding EU MDR implementation pace, nonoperative management guideline evolution, and integrated delivery network consolidation trajectories. Practitioners should monitor FDA 510(k) pathway modification announcements, American College of Surgeons guideline revision schedules, and CDSCO Class IIa approval velocity for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Glaucoma Market
Specialty Medicine
Hemophilia Market
Specialty Medicine
Respiratory Syncytial Virus (RSV) Therapeutics Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Global Scleroderma Therapeutics Market
Specialty Medicine
Large Granular Lymphocytic Leukemia (LGLL) Therapeutics Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Global Autism Spectrum Disorders Treatment Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Global Lung Transplant Therapeutics Market
Specialty Medicine
Neurometabolic Disorder Market
Specialty Medicine
Chronic Smell and Flavor Loss Treatment Market
Specialty Medicine
Balantidiasis Treatment Market
Specialty Medicine
Cervical Dystonia Market
Specialty Medicine
CARD9 Deficiency Treatment Market
Specialty Medicine
Pulmonary Arterial Hypertension (PAH) Market