
 Asset Tracking Market | 2026-2036
Asset Tracking Market Size, Share, and Industry Trends Forecast 2026-2036
Asset Tracking Market Intelligence
Healthcare procurement teams is redrawing demand patterns across the asset tracking landscape. Zebra Technologies Corporation dominates hospital-grade RFID and barcode hardware for patient and equipment visibility. Samsara Inc. competes in cloud-connected fleet and industrial asset monitoring with integrated cellular and GPS architectures. Trimble Inc. specializes in precision GPS tracking for construction, agriculture, and transportation fleets operating in remote environments.
Asset tracking encompasses hardware, software, and connectivity systems that capture real-time or periodic location, condition, and utilization data for physical resources, typically operating across radio frequencies from 125 kHz to 5.9 GHz depending on protocol. These systems enable inventory accuracy, loss prevention, regulatory compliance, and operational workflow optimization across distributed facilities. RFID technology leads in closed-loop enterprise environments where tag cost and read-range predictability anchor procurement decisions. Cloud-based deployment is expanding fastest among mid-market logistics operators seeking subscription flexibility and reduced IT overhead. On-premises systems retain margin concentration in defense and critical infrastructure buyers with data sovereignty requirements.
The FCC governs unlicensed spectrum use for RFID, Bluetooth, and Wi-Fi tracking devices through Part 15 rules, while FDA oversight applies to medical device tracking systems integrated with patient care workflows. ETSI harmonizes European radio equipment standards through EN 300 220 and EN 302 208, shaping cross-border product certification costs. Stakeholders must monitor evolving spectrum allocation decisions and cybersecurity mandates as tracking systems merge with operational technology networks.
Market Dynamics
Healthcare procurement teams are redrawing demand patterns across the asset tracking landscape, with hospital networks prioritizing real-time location systems that integrate directly with electronic health record workflows and patient safety protocols.
Growth Catalysts
- Hospital digitization mandates:Healthcare facilities in the United States face operational pressure to reduce equipment search time and improve utilization rates of mobile medical devices.
- FCC Part 15 spectrum access:Unlicensed radio frequency allocations for RFID and Bluetooth Low Energy lower deployment barriers for mid-size logistics operators seeking indoor-outdoor visibility.
- Cloud-native architectures:Subscription software models reduce upfront capital requirements and accelerate deployment cycles for fleet and warehouse operators.
Market Restraints
- Silicon supply concentration:Semiconductor fabrication for RFID chips and GPS modules concentrates in East Asian foundries, exposing hardware vendors to input volatility.
- Sub-GHz spectrum congestion:Unlicensed bands in industrial zones experience interference that degrades read reliability for passive RFID deployments.
- Battery chemistry limitations:Lithium primary cells in active tags face thermal constraints and shipping restrictions that limit deployment in extreme environments.
Strategic Opportunities
- Cold chain pharmaceuticals:Temperature-sensitive biologics distribution creates demand for combined location and condition monitoring in last-mile logistics.
- India's PLI scheme for electronics:Domestic manufacturing incentives attract hardware assembly for regional RFID and IoT device markets.
- 5G RedCap convergence:Reduced capability NR modules enable cellular tracking at lower cost and power than full 5G, opening industrial asset monitoring applications.
Industry Challenges
- RF engineering talent scarcity:Antenna design and propagation modeling expertise concentrates in defense and telecommunications sectors, constraining vendor hiring.
- Multi-protocol integration complexity:Enterprise buyers operate mixed environments of Wi-Fi, Bluetooth, UWB, and cellular that require unified software layers.
- FDA 510(k) timelines:Medical device tracking systems integrated with patient care workflows face extended certification cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asset Tracking Market |
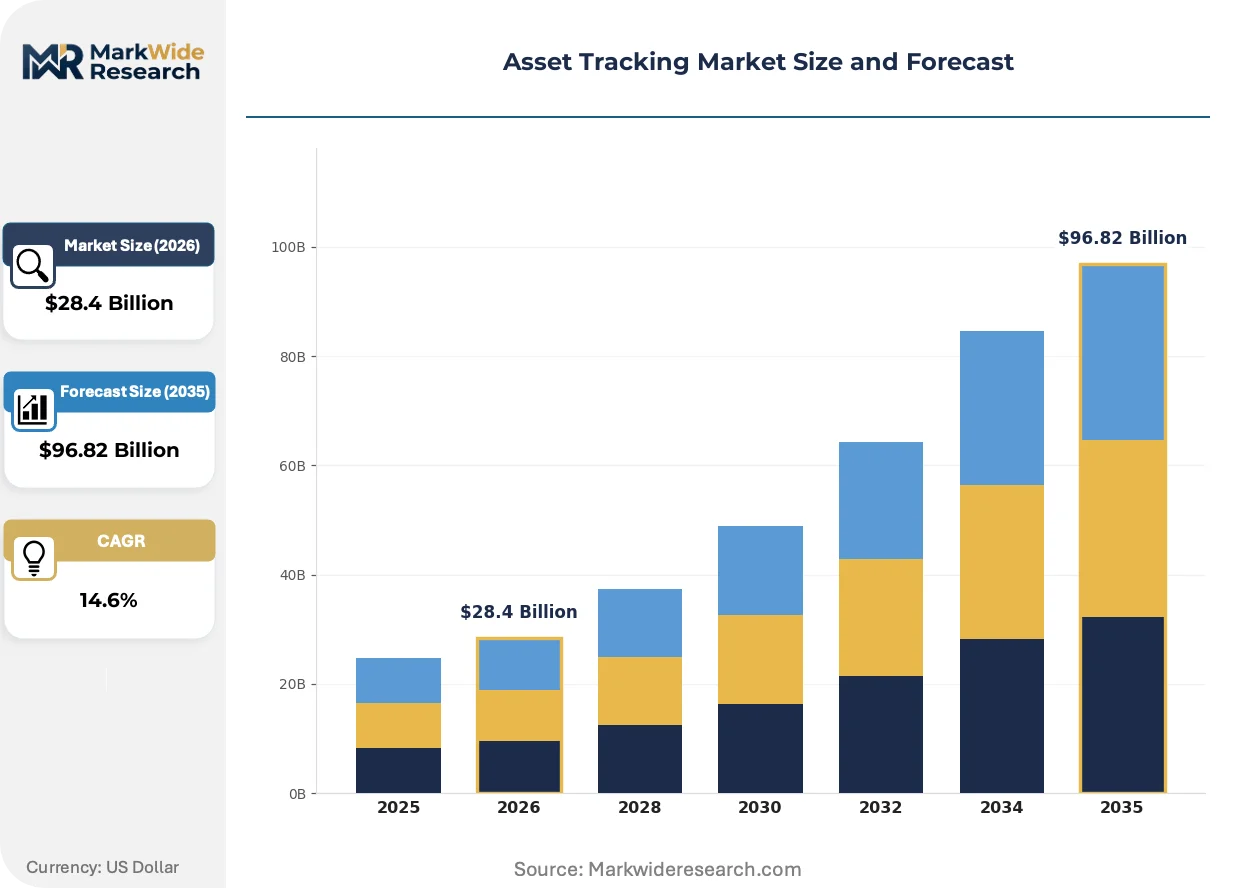
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $96.82 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, GPS, Bluetooth, Wi-Fi Application: Logistics, Healthcare, Manufacturing, Retail Deployment: Cloud-Based, On-Premises, Hybrid, Mobile End User: Enterprises, SMBs, Government, Non-Profit |
| Companies Covered | AT&T Inc., Asset Panda, Zebra Technologies Corporation, ServiceNow, UpKeep, Samsara Inc., Trimble Inc., Asset Infinity, Verizon Communications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asset Tracking Market Strategic Shifts & Innovations
Ultra-wideband positioning is compressing location accuracy thresholds in indoor environments, while regulatory pressure on medical device traceability and shifting procurement models toward operational expenditure reshape competitive requirements.
Ultra-wideband radio technology delivers centimeter-level precision for indoor asset positioning through time-of-flight measurements rather than signal strength estimation. Hospital networks in Germany and the United States are deploying UWB infrastructure for operating room equipment tracking and sterile supply chain verification. The technology is miniaturizing into battery-powered tags that operate for multiple years, displacing Wi-Fi and Bluetooth alternatives in high-value medical equipment use cases.
The EU Medical Device Regulation imposes unique device identification and traceability requirements that extend through distribution and clinical use phases. Asset tracking systems must capture and retain location histories that satisfy notified body audit protocols for Class IIa and higher devices. European hospital procurement now specifies UDI-compliant tracking infrastructure as a contractual precondition for capital equipment purchases.
Hospital capital committees are migrating from perpetual license purchases to subscription-based RTLS deployments that bundle hardware, software, and maintenance. This shift compresses vendor cash conversion cycles and elevates recurring revenue valuation multiples. The United States acute care segment leads this transition, with health system consolidation creating concentrated buyer power that demands performance-based contract structures.
Asset Tracking Market Segmentation
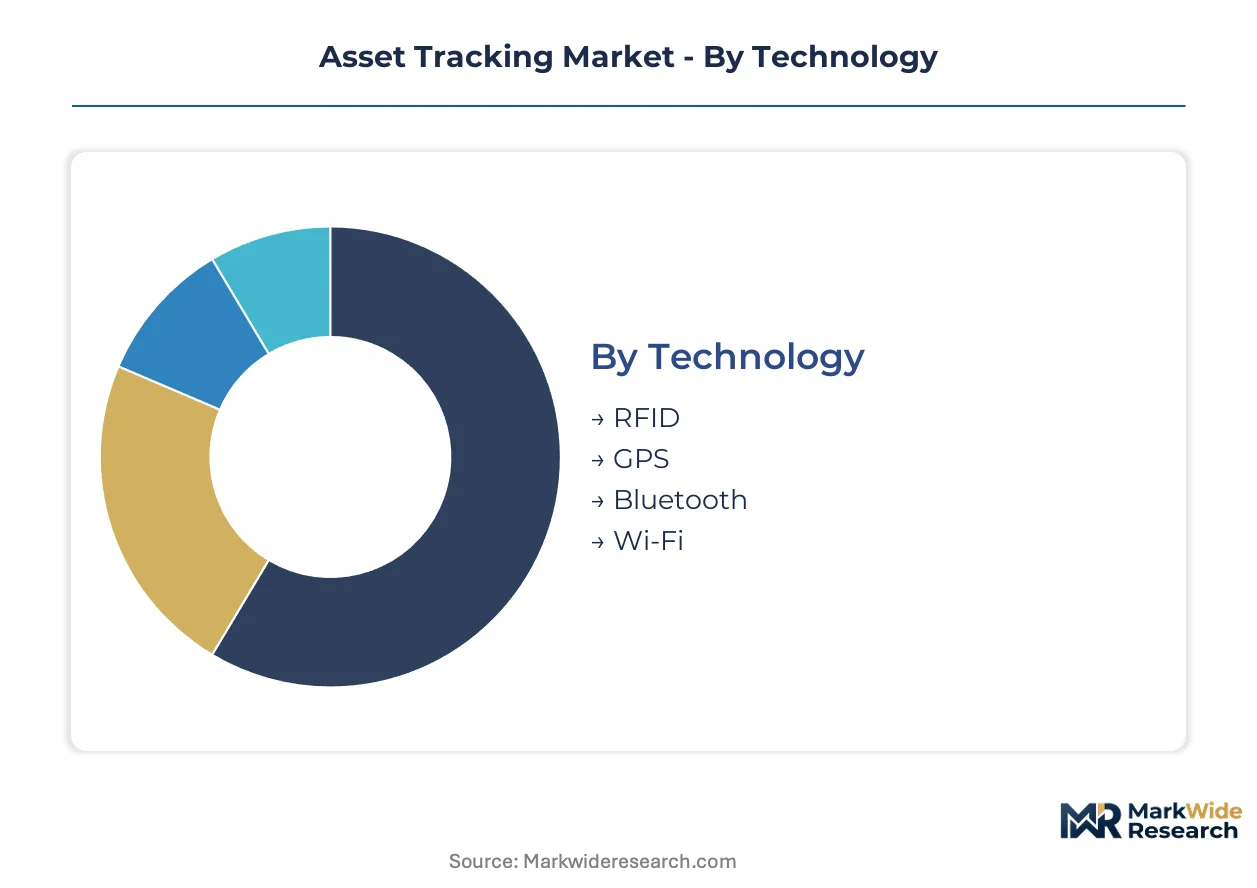
Technology choices in asset tracking cascade through deployment architecture, application requirements, and procurement channels. Each segmentation dimension reveals distinct margin structures and vendor specialization patterns that shape competitive positioning.
Technology:
RFID and GPS dominate hardware procurement through industrial distributors, while Bluetooth and Wi-Fi flow through systems integrators serving facility management channels.
- RFID:Passive and active radio frequency identification operates across 125 kHz to 960 MHz with tag costs ranging from sub-dollar to fifty-dollar price points. Hospital networks in the United States deploy UHF RFID for medical equipment visibility, driven by Joint Commission requirements for emergency device readiness.
- GPS:Satellite-based positioning leverages L1/L2/L5 bands with precision ranging from meter to centimeter depending on augmentation systems. Fleet operators across Germany and the United States mandate GPS tracking for regulatory compliance and insurance underwriting.
- Bluetooth:Low Energy 5.x protocols enable battery-powered beacons with sub-ten-meter accuracy for indoor positioning.
- Wi-Fi:Infrastructure reuse through 802.11-based positioning reduces deployment costs in existing wireless environments.
RFID dominates installed base. Bluetooth is where expansion concentrates.
Application:
Cost tier stratification separates enterprise-grade healthcare and logistics deployments from mid-market retail and manufacturing implementations.
- Logistics:Cross-dock, yard management, and last-mile visibility systems integrate barcode, RFID, and cellular tracking across multimodal freight networks. Third-party logistics providers in the United States and Netherlands deploy these systems to meet customer SLA requirements and customs documentation mandates.
- Healthcare:Real-time location systems for medical devices, patient flow, and staff safety operate under FDA and EMA regulatory frameworks. German hospital networks lead European adoption, driven by MDR traceability requirements for Class IIa and higher devices.
- Manufacturing:Work-in-process tracking and tool management systems reduce search time and improve OEE metrics.
- Retail:Inventory accuracy and loss prevention applications concentrate in apparel and electronics verticals.
Logistics commands the largest revenue pool. Healthcare is climbing the fastest.
Deployment:
Customer type determines deployment modality, with enterprises favoring hybrid architectures and SMBs defaulting to cloud-native subscriptions.
- Cloud-Based:Multi-tenant SaaS platforms with API-first architectures enable rapid onboarding for mid-market logistics operators. Subscription pricing reduces upfront capital requirements and accelerates procurement cycles for fleet and warehouse buyers.
- On-Premises:Dedicated infrastructure with air-gapped networks serves defense contractors and critical infrastructure operators with data sovereignty requirements. These deployments concentrate margin in professional services and custom integration.
- Hybrid:Edge processing with cloud analytics balances latency-sensitive operations with centralized reporting.
- Mobile:Smartphone-dependent tracking leverages existing device fleets for light-asset visibility.
Cloud-Based captures the majority of new deployments. Hybrid is gaining share fastest.
End User:
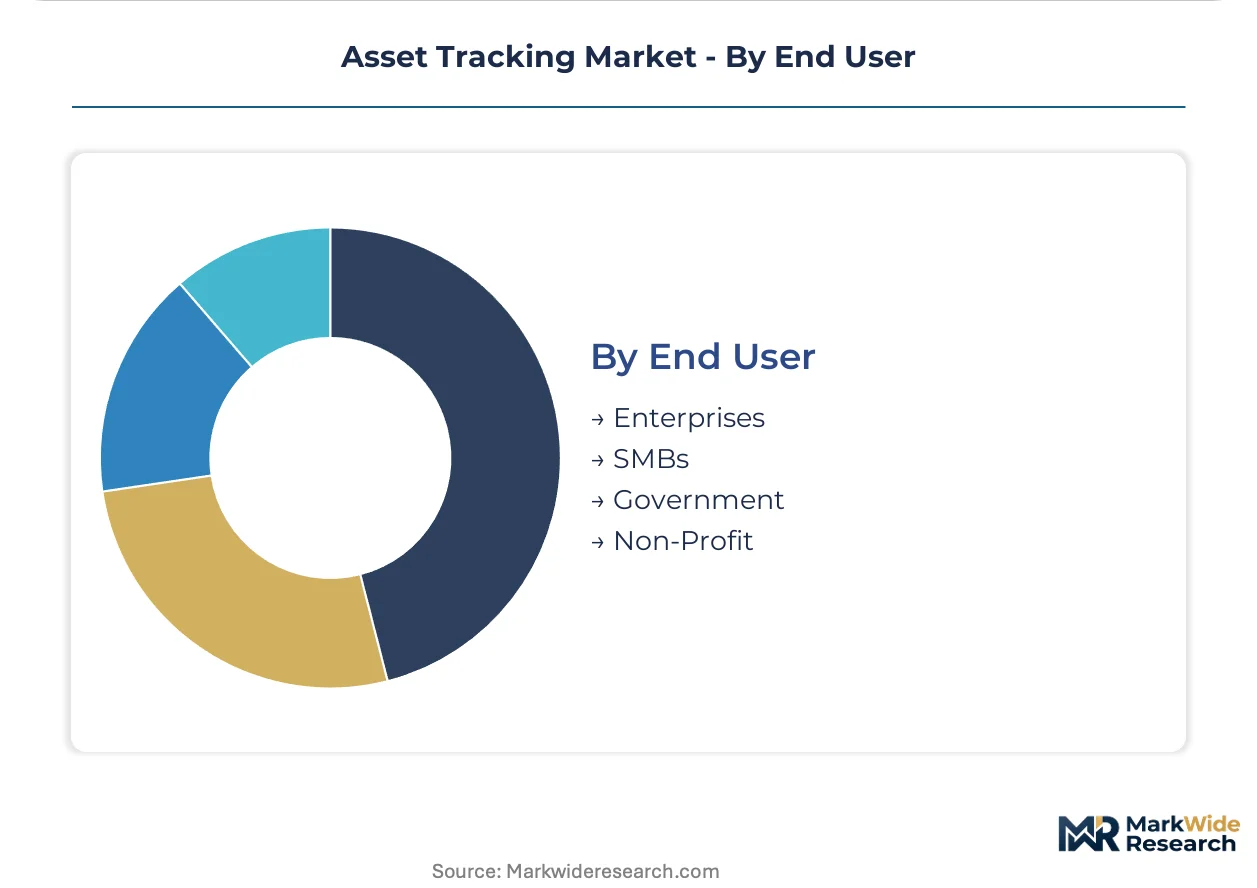
Volume concentration sits with Enterprises, while Government procurement exhibits the longest sales cycles and most stringent certification requirements.
- Enterprises:Fortune 500 manufacturers, healthcare systems, and logistics operators deploy integrated RTLS platforms with dedicated IT support. These buyers negotiate multi-year contracts with performance-based pricing and SLA penalties.
- SMBs:Small and mid-sized businesses adopt point solutions through channel partners, prioritizing ease of deployment over customization.
- Government:Defense and civilian agencies mandate FIPS 140-2 encryption and FedRAMP authorization for cloud deployments.
- Non-Profit:Humanitarian and development organizations deploy asset tracking for supply chain transparency in low-infrastructure environments.
Enterprises dominate installed base. Government is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement teams and third-party logistics operators concentrate purchasing power across five major economies. Each geography presents distinct regulatory frameworks and industrial cluster dynamics that shape deployment patterns.
United States
Healthcare systems and freight operators drive enterprise-grade RTLS adoption. FCC Part 15 rules govern unlicensed spectrum for RFID and Bluetooth deployments. The Dallas-Fort Worth logistics corridor anchors multimodal tracking infrastructure serving cross-border freight.
Germany
Automotive suppliers and hospital networks demand precision tracking for work-in-process and medical devices. EU MDR traceability mandates reshape procurement specifications for Class IIa devices. The Stuttgart manufacturing belt integrates UWB positioning for tool management and assembly line visibility.
China
Electronics manufacturing and e-commerce logistics scale passive RFID and cellular tracking. MIIT spectrum allocations for 5G RedCap enable lower-cost industrial monitoring. The Yangtze River Delta cluster concentrates tag fabrication and reader module assembly.
India
Pharmaceutical cold chain and retail inventory management expand tracking infrastructure. PLI scheme incentives for electronics manufacturing attract hardware assembly investment. The Mumbai-Pune corridor hosts emerging IoT device production for regional markets.
United Kingdom
NHS procurement standardization drives hospital asset visibility programs. GDPR compliance requirements shape cloud deployment architectures for patient-adjacent tracking. The Cambridge life sciences cluster pilots UWB systems for laboratory equipment management.
Asset Tracking Market Key Industry Players
Player mix skews toward diversified technology conglomerates with adjacent enterprise software or telecommunications portfolios. Market structure exhibits moderate concentration at the top tier, with specialized vendors capturing niche healthcare and industrial segments. Two strategic archetypes dominate: infrastructure-integrated platforms bundling hardware, connectivity, and cloud analytics; and point-solution specialists delivering vertical-specific functionality. Competitive moves center on strategic partnerships with systems integrators and portfolio diversification into adjacent IoT monitoring categories.
Within the infrastructure-integrated tier, Zebra Technologies Corporation and Samsara Inc. exemplify contrasting architectural approaches to enterprise visibility. Zebra anchors the hardware-centric archetype with origins in automatic identification and data capture equipment. Samsara occupies a position representing cloud-native fleet and industrial monitoring built on integrated cellular and GPS foundations. Trimble Inc. sits within the precision-positioning specialist category, with company structure indicating diversified technology holdings across construction, agriculture, and transportation applications.
| Leading Market Players |
|---|
| AT&T Inc. |
| Asset Panda |
| Zebra Technologies Corporation |
| ServiceNow |
| UpKeep |
| Samsara Inc. |
| Trimble Inc. |
| Asset Infinity |
| Verizon Communications |
| Others |
Cost & Logistics Intelligence
Silicon-to-cellular module substitution in active tag architectures is redrawing procurement geography and compressing hardware economics. Hospital networks migrating from proprietary RFID infrastructure toward Bluetooth Low Energy and 5G RedCap modules source from contract manufacturers in Vietnam and Mexico, bypassing traditional East Asian silicon consolidation.
Pricing Analysis
Cost-plus contracts with quarterly silicon indexation dominate enterprise healthcare procurement, insulating vendors from wafer price volatility while capping upside. Three-tier pricing structure across enterprise-grade, mid-market subscription, and entry-level point solutions separates FDA-validated systems from uncertified alternatives. Cost compression in passive UHF tags is intensifying because Chinese tag converters are expanding capacity for inlay lamination. Mid-market logistics operators exhibit highest price sensitivity, while defense contractors accepting FIPS 140-2 mandates show lowest elasticity.
Supply Chain Analysis
Taiwan Strait transit risk concentrates exposure for UHF RFID chip fabrication, with NXP and Impinj wafers moving through Kaohsiung port consolidation points. Hardware assembly draws from China, Vietnam, and Mexico, with Mexico gaining share for USMCA-compliant medical device tracking. Lithium manganese dioxide cells from Japan and South Korea face UN38.3 shipping restrictions that constrain active tag deployment. Distribution runs through industrial distributors like Ingram Micro and Arrow Electronics for enterprise accounts, while direct-to-manufacturer models serve high-volume logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The asset tracking market is recovering from a capital expenditure trough driven by hospital network consolidation pauses. Equipment utilization mandates and MDR traceability deadlines are restarting procurement cycles across US and European healthcare systems.
For Market Incumbents: Secure long-term silicon supply agreements with foundries in Taiwan and South Korea before capacity allocation tightens. Deepen backward integration into antenna design and firmware development to defend margin position against modular hardware commoditization. Lock in exclusive GPO contracts with Vizient and Premier to block emerging cloud-native entrants from hospital system access.
For New Entrants and Emerging Players: Lead with 5G RedCap-native architectures targeting Indian pharmaceutical cold chain operators underserved by legacy GPS-cellular hybrids. India's PLI scheme for electronics manufacturing offers localized assembly cost advantages against imported Chinese hardware. Partner with domestic systems integrators in Mumbai-Pune corridor for regulatory navigation and hospital procurement access.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed RTLS specialists carrying 2021-era leverage from hospital digitization surges. Five-to-ten year viability hinges on recurring revenue conversion and cloud migration completion rates. Watch FDA 510(k) clearance velocity for medical device tracking modules as the signal indicating whether healthcare procurement acceleration sustains or stalls.
| Strategic Initiative | Industry Significance |
|---|---|
| UWB Infrastructure Deployment | German automotive suppliers and US hospital networks demand centimeter-level precision for tool tracking and surgical equipment location. |
| 5G RedCap Module Integration | MIIT spectrum allocations enable lower-cost cellular tracking for China's Yangtze River Delta manufacturing clusters. |
| Cloud-Native Platform Migration | Subscription models reduce upfront capital barriers for mid-market logistics operators in Netherlands cross-dock networks. |
| FDA 510(k) Certification Investment | Medical device tracking systems require extended validation cycles that delay revenue but lock out uncertified competitors. |
| India PLI Manufacturing Localization | Domestic assembly incentives attract hardware production for regional RFID and IoT device markets serving pharmaceutical cold chain. |
Research Approach
The analysis maps RFID hardware, GPS modules, Bluetooth beacons, and cloud analytics platforms, each validated through hospital procurement managers, logistics technology officers, and biomedical engineering directors. Primary interviews with GPO contract specialists and RTLS implementation consultants combined with secondary validation from FCC equipment authorization databases, FDA 510(k) filings, and EU MDR notified body audit records. Bottom-up tag volume estimates and top-down enterprise IT spending surveys underwent cross-referencing for triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation modeling incorporated technology type, deployment architecture, application vertical, and end-user scale dimensions. CAGRs derived from fitted growth curves applied to installed base expansion and replacement cycle assumptions, with semiconductor supply elasticity and hospital capital committee approval timelines as specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained FCC Part 15 spectrum stability and EU MDR enforcement continuity would require recalibration. Practitioners should keep alternative scenarios live as 5G RedCap module pricing and India PLI scheme disbursement timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Smart Barcode Readers Market
Sensors
Terrestrial Laser Scanning System Market
Sensors
Europe Lidar Market
Sensors
Machine Health Monitoring Market
Sensors
Underground Service Locator Market
Sensors
Transportation Sensors Market
Sensors
IO Link Market
Sensors
Bluetooth Beacons Market
Sensors
Remote Sensing Technology Market
Sensors
Real Time Location System Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
Asset Tags Market
Sensors
Industrial Automation Sensors Market
Sensors
Lidar in Construction Market
Sensors
Heat Stress Meter Market
Sensors
Alcohol Sensor Market