
 Beacons Management Software Market | 2026-2036
Beacons Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Beacons Management Software Market Analysis
Event management companies is reorganizing demand patterns as experiential marketing budgets recover post-pandemic. Zebra Technologies Corporation leverages its enterprise mobility heritage to anchor large-scale venue deployments. Beaconinside GmbH specializes in European retail analytics, while Estimote Inc competes through hardware-software bundling for developer ecosystems.
Beacons Management Software constitutes a centralized platform for configuring, monitoring, and analyzing Bluetooth Low Energy (BLE) beacon networks, typically supporting signal range calibration between one and seventy meters and real-time location engine integration. Cloud-Based Solutions dominate current procurement as retailers prioritize centralized fleet management over capital-intensive on-premise infrastructure, while Ultra-Wideband deployment is expanding fastest where centimeter-level positioning accuracy commands premium pricing in logistics and healthcare wayfinding.
The Federal Communications Commission governs unlicensed spectrum allocation affecting BLE transmission power, while the European Telecommunications Standards Institute enforces cross-border protocol harmonization that simplifies multi-country rollouts. California's Consumer Privacy Act and analogous state-level frameworks are compelling vendors to embed granular consent management into proximity-triggered data collection. Stakeholders must weigh interoperability investments against the fragmentation risk of competing proprietary beacon protocols.
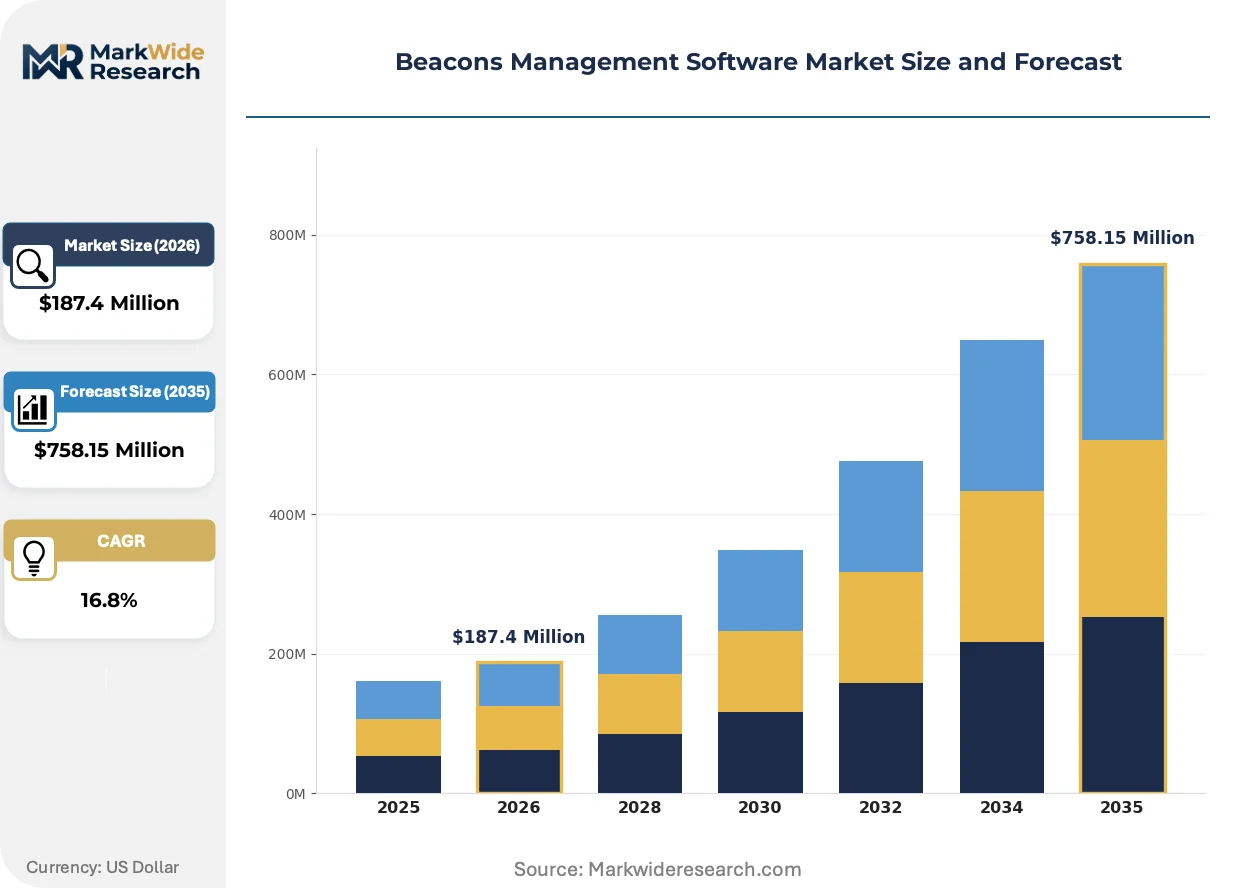
Market Dynamics
Bluetooth Low Energy protocol standardization through IEEE is collapsing interoperability barriers while cloud-native fleet management platforms consolidate procurement preferences across retail and logistics verticals.
Growth Catalysts
- Proximity Marketing Recovery:Event management companies are reorganizing experiential marketing budgets post-pandemic, expanding beacon deployments for attendee engagement and foot-traffic analytics at convention centers and stadiums.
- FCC Spectrum Allocation:The Federal Communications Commission's unlicensed spectrum rules for BLE transmission power enable denser beacon networks without licensing friction, accelerating venue-scale rollouts.
- Ultra-Wideband Convergence:Centimeter-level positioning accuracy from UWB integration is commanding premium pricing in healthcare wayfinding and automated guided vehicle coordination.
Market Restraints
- Silicon Supply Concentration:BLE chipset fabrication depends on concentrated Asian foundry capacity, exposing beacon hardware vendors to input volatility and extended lead times.
- State-Level Privacy Fragmentation:California's Consumer Privacy Act and analogous frameworks in Illinois and Virginia compel vendors to embed granular consent management, increasing compliance engineering overhead.
- Battery Chemistry Constraints:Lithium coin cell availability and disposal regulations limit beacon lifecycle economics in high-density deployments.
Strategic Opportunities
- European Retail Analytics:GDPR-compliant beacon networks remain underpenetrated in German and French department store chains, creating first-mover advantages for consent-native platform architectures.
- Industrial Asset Tracking:Manufacturing facilities in the United States are adopting BLE-AoA (Angle of Arrival) for real-time equipment localization, opening greenfield demand beyond traditional retail.
- CSRD Reporting Integration:The EU Corporate Sustainability Reporting Directive mandates granular facility utilization data, positioning beacon-derived occupancy analytics as compliance infrastructure.
Industry Challenges
- RF Engineering Talent Scarcity:Deployment of hybrid BLE-UWB networks requires specialized antenna design expertise that remains concentrated among semiconductor vendors and their direct partners.
- Legacy POS Integration:Retailers with entrenched on-premise transaction systems face middleware complexity when connecting beacon-triggered promotions to existing inventory databases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beacons Management Software Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $758.15 Million |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based Solutions, On-Premise Solutions, Hybrid Solutions, SaaS Solutions End User: Retail Stores, Event Management Companies, Museums, Hospitality Industry Deployment: Indoor Deployment, Outdoor Deployment, Multi-Site Deployment, Venue-Specific Deployment Technology: Bluetooth Low Energy, NFC, Wi-Fi, Ultra-Wideband |
| Companies Covered | Relution Inc, Beaconinside GmbH, Zebra Technologies Corporation, Estimote Inc, Quuppa Oy, MobStac Inc, Gimbal, Kontakt io, Sensoro Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beacons Management Software Market Emerging Trajectories
Cloud-based beacon fleet orchestration is compressing total cost of ownership while edge-native location engines reduce latency for time-sensitive proximity triggers in logistics and healthcare.
Ultra-Wideband positioning is supplanting pure BLE trilateration in applications demanding sub-meter accuracy. Automotive manufacturers deploying UWB-enabled digital key systems are driving chipset volume economics. This technology convergence is compressing pricing premiums for centimeter-level indoor positioning.
REACH substance restrictions and RoHS directives in Europe are forcing hardware vendors to reformulate PCB solder compositions and battery contact materials. Beacon manufacturers with Chinese assembly operations are relocating final integration to Eastern European facilities to maintain CE marking compliance without tariff exposure.
Buyers are consolidating vendor relationships around platforms offering unified beacon-RTLS-WiFi management rather than point solutions. Healthcare systems in Texas and Florida are demanding consolidated dashboards spanning multiple location technologies. This preference compression disadvantages standalone beacon software specialists lacking WiFi or RFID integration depth.
Beacons Management Software Market Segmentation
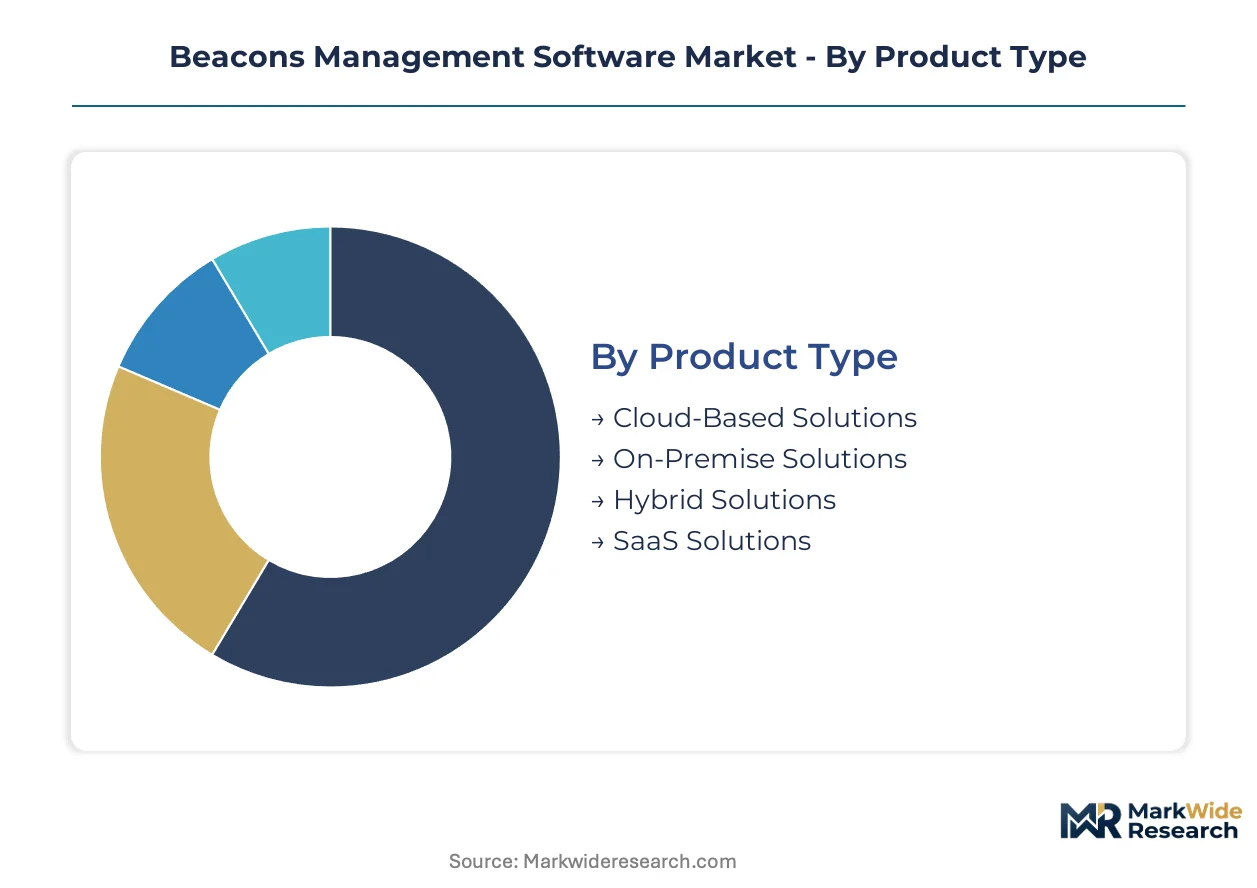
Beacon management platforms fragment across deployment models, wireless protocols, and venue types, each carrying distinct integration costs and substitution vulnerabilities. Buyers face trade-offs between cloud agility and on-premise data sovereignty, while protocol choices lock in hardware ecosystems for years.
Product Type:
Substitution pressure from adjacent RTLS platforms is squeezing standalone beacon software margins, forcing deployment-model differentiation.
- Cloud-Based Solutions:Centralized fleet orchestration through browser-based dashboards enables remote firmware updates and real-time analytics without capital infrastructure. Retail chains in Texas and Florida prioritize this model for rapid multi-store rollouts where IT staffing remains thin.
- SaaS Solutions:Subscription pricing with API-first architectures attracts mid-market event management companies recovering post-pandemic experiential budgets. Tiered feature gating aligns costs with beacon count, reducing upfront commitment for seasonal venue operators.
- Hybrid Solutions:Combines edge processing for latency-sensitive triggers with cloud analytics for longitudinal trend analysis. Manufacturing facilities in Michigan deploy this architecture to balance real-time equipment alerts against predictive maintenance modeling.
- On-Premise Solutions:Air-gapped installations serving defense contractors and healthcare systems with strict HIPAA data residency requirements. Higher total cost of ownership limits adoption outside regulated verticals.
Cloud-Based Solutions retain volume leadership; SaaS Solutions holds the steepest expansion curve.
End User:
Customer concentration patterns reveal which verticals tolerate hardware refresh cycles versus demanding decade-long platform stability.
- Retail Stores:Proximity marketing deployments spanning department stores and grocery chains leverage beacon-triggered promotions tied to POS systems. California's Consumer Privacy Act compliance overhead is slowing deployment velocity in the state's major metropolitan corridors.
- Event Management Companies:Temporary installations for conventions and stadiums prioritize rapid deployment tools and post-event analytics export. Budget recovery post-pandemic is expanding beacon counts per event for attendee heat-mapping.
- Museums:Indoor wayfinding and exhibit-triggered content delivery drives demand for sub-meter accuracy. Institutions in Paris and Berlin face GDPR consent complexity for visitor tracking that US counterparts avoid.
- Hospitality Industry:Hotels deploy beacons for guest room access and concierge service automation. Integration with legacy property management systems creates middleware friction for boutique chains lacking enterprise IT resources.
Retail Stores anchor procurement volume; Event Management Companies is climbing the fastest as experiential budgets normalize.
Deployment:
Physical installation scope determines antenna engineering requirements and ongoing maintenance labor intensity.
- Indoor Deployment:Ceiling-mounted beacon grids for retail and healthcare wayfinding require RF propagation modeling through building materials. Signal attenuation from concrete and metal demands denser node placement in industrial facilities.
- Multi-Site Deployment:Standardized configurations across franchise networks or retail chains enable centralized template management. Logistics operators in the United States use this approach for consistent warehouse localization across distribution centers.
- Venue-Specific Deployment:Custom beacon density and power calibration for stadiums, airports, and convention centers with unique traffic patterns. Temporary overlay networks for music festivals and trade shows fall within this category.
- Outdoor Deployment:Weatherproof enclosures and extended transmission range for smart city applications and campus navigation. Battery life degradation in temperature extremes limits economic viability for always-on installations.
Indoor Deployment retains volume leadership; Multi-Site Deployment is gaining share fastest through franchise standardization mandates.
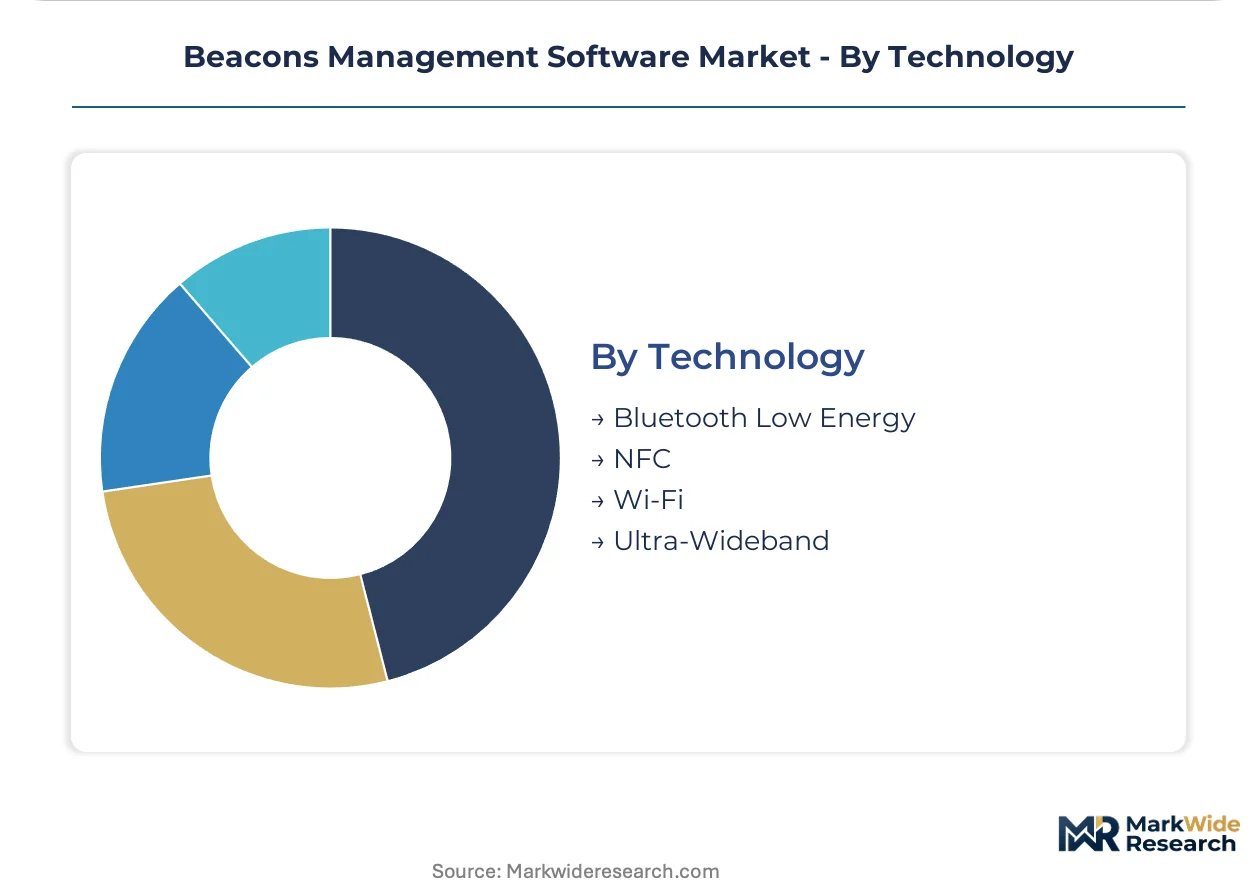
Technology:
Protocol selection locks buyers into chipset ecosystems with diverging accuracy specifications and power profiles.
- Bluetooth Low Energy:IEEE-standardized protocol dominating retail and logistics through low-power beacon hardware and mature smartphone ecosystem support. FCC unlicensed spectrum rules enable dense deployments without licensing friction.
- Ultra-Wideband:Centimeter-level positioning accuracy commands premium pricing in healthcare surgical suite wayfinding and automated guided vehicle coordination. Automotive digital key applications are driving chipset volume economics.
- Wi-Fi:Existing infrastructure reuse for coarse-grained presence detection where sub-meter precision remains unnecessary. Enterprise IT departments favor this approach to minimize parallel network management overhead.
- NFC:Tap-to-interact proximity triggers for payment authentication and museum exhibit engagement. Extremely short range limits applicability to deliberate user-initiated interactions rather than ambient detection.
Bluetooth Low Energy retains volume leadership; Ultra-Wideband is expanding most quickly as accuracy premiums compress through automotive scale effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German beacon management platforms export into French and Dutch retail chains through the Rhine-Ruhr logistics corridor, while US vendors supply proximity marketing infrastructure to Canadian stadium operators and Mexican franchise networks.
United States
Retail chains in Texas and Florida deploy cloud-based fleet management for rapid multi-store rollouts where IT staffing remains thin. FCC unlicensed spectrum rules enable dense BLE networks without licensing friction. California's Consumer Privacy Act compliance overhead slows deployment velocity in Los Angeles and San Francisco metropolitan corridors.
Germany
Department store chains in Berlin and Hamburg underpenetrate GDPR-compliant beacon networks, creating first-mover advantages for consent-native architectures. ETSI cross-border protocol harmonization simplifies multi-country rollouts into neighboring markets. Bavarian automotive manufacturers drive UWB chipset volume economics through digital key system integration.
France
Museums in Paris demand sub-meter accuracy for exhibit-triggered content delivery while facing GDPR consent complexity for visitor tracking. ANSM and CNIL enforcement shapes granular data collection frameworks. Île-de-France hospitality clusters integrate beacons with legacy property management systems for guest room access automation.
China
Manufacturing facilities in the Yangtze River Delta adopt BLE-AoA for real-time equipment localization beyond traditional retail applications. MIIT Bluetooth standardization reduces proprietary protocol fragmentation. Shenzhen hardware vendors relocate final integration to Eastern European facilities to maintain CE marking compliance without tariff exposure.
United Kingdom
Event management companies in London reorganize experiential marketing budgets post-pandemic, expanding beacon deployments for attendee heat-mapping at convention centers. UK GDPR alignment with EU frameworks maintains cross-border data flow continuity. Midlands logistics operators use standardized multi-site configurations for consistent warehouse localization.
Beacons Management Software Market Vendor Landscape
Player mix skews toward enterprise mobility heritage vendors and hardware-software bundlers, with cloud-native specialists occupying the fastest-expanding tier. Market structure concentrates around three strategic archetypes: legacy industrial automation firms leveraging RTLS integration depth, developer ecosystem platforms competing through API-first architectures, and regional analytics specialists embedding consent-native compliance. Dominant competitive moves include portfolio diversification into adjacent WiFi and RFID management, plus geographic expansion through Eastern European assembly relocation to maintain CE marking access.
Within the enterprise mobility tier, Zebra Technologies Corporation anchors large-scale venue deployments through its industrial automation heritage. Beaconinside GmbH represents the European regional specialist archetype, embedding GDPR-native consent management for German and French retail analytics. Estimote Inc exemplifies hardware-software bundling strategies targeting developer ecosystems with integrated beacon and cloud platform offerings.
| Leading Market Players |
|---|
| Relution Inc |
| Beaconinside GmbH |
| Zebra Technologies Corporation |
| Estimote Inc |
| Quuppa Oy |
| MobStac Inc |
| Gimbal |
| Kontakt io |
| Sensoro Co Ltd |
| Others |
Supply Flow & Price Mechanics
Automotive digital key volume economics are compressing BLE-UWB chipset premiums while concentrating fabrication capacity in Taiwanese and South Korean foundries, creating asymmetric pricing power for cloud-native platform vendors against hardware-dependent competitors.
Pricing Analysis
Prior-generation BLE-only beacon management platforms face price erosion from next-generation UWB-integrated suites commanding accuracy premiums in healthcare wayfinding. Three-tier pricing structure across premium, standard, and economy levels stratifies by integration depth—enterprise mobility heritage vendors capture top tier through WiFi-RFID convergence, while API-first SaaS providers compete on per-beacon subscription scalability. Cost compression in standard-tier cloud solutions is intensifying because hyperscaler infrastructure commoditizes backend orchestration. Mid-market event management companies exhibit highest price sensitivity due to seasonal deployment volatility, whereas hospital systems in Texas and Florida tolerate premium pricing for HIPAA-compliant on-premise installations.
Supply Chain Analysis
Taiwan Strait transit vulnerability exposes beacon hardware vendors to semiconductor fabrication chokepoints, as BLE-UWB chipset supply concentrates in Taiwanese, South Korean, and Chinese foundries. Lithium coin cell chemistry draws from concentrated Japanese and Korean battery suppliers, while PCB solder compositions hinge on RoHS-compliant European material sourcing. Single-source vulnerability in 7nm BLE SoC fabrication creates extended lead time exposure for hardware-software bundlers. Distribution runs through Shenzhen assembly corridors with final integration relocating to Eastern European facilities to maintain CE marking compliance without tariff exposure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
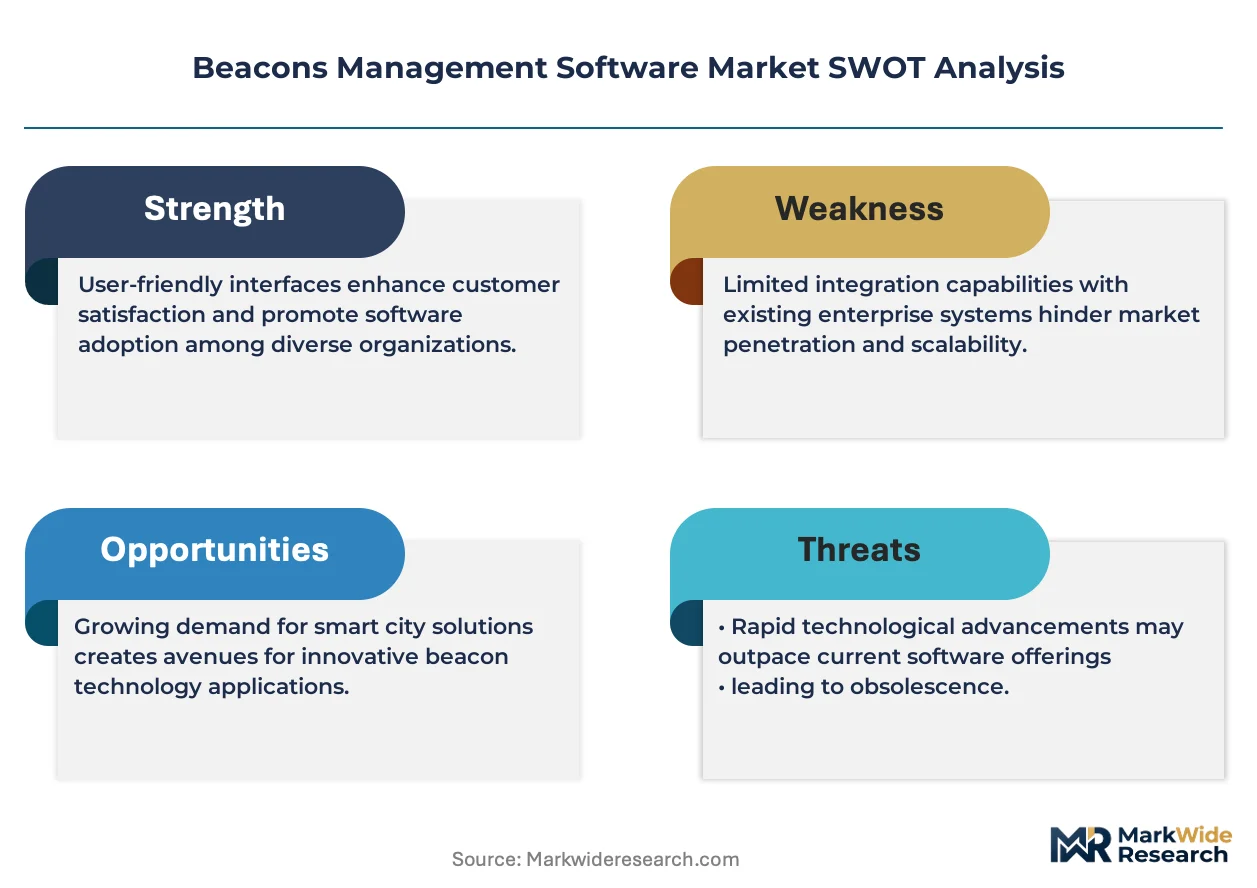
Beacon management software exhibits defensive moat characteristics through high switching costs—retailers with deployed ceiling-mounted beacon grids face substantial RF re-engineering expenses when migrating platforms, entrenching incumbent vendors with installed base telemetry advantages.
For Market Incumbents: Fortify platform stickiness through backward integration into UWB chipset co-design partnerships, reducing dependency on concentrated Asian foundry capacity. Deepen WiFi and RFID convergence investments to match healthcare system demands for consolidated location technology dashboards in Texas and Florida hospital networks. Emerging cloud-native specialists with pure-play beacon software architectures pose substitution threats absent multi-protocol integration depth. For New Entrants and Emerging Players: Anchor in GDPR-native consent management architectures for underpenetrated German and French department store chains, where first-mover advantages await platforms embedding granular data collection frameworks from inception. Target industrial asset tracking verticals in Michigan manufacturing facilities adopting BLE-AoA for equipment localization, bypassing saturated retail proximity marketing competition. API-first SaaS pricing with tiered beacon-count gating reduces upfront commitment barriers for seasonal event operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors hybrid BLE-UWB platform vendors with industrial automation heritage over standalone beacon software specialists lacking adjacent RTLS integration depth. Long-term viability across the 5-10 year horizon rests on automotive digital key volume economics compressing UWB chipset costs and expanding addressable market into logistics wayfinding. Acquisition target archetype: European regional analytics specialists with GDPR-compliant architectures and established Rhine-Ruhr retail channel relationships. Signal to watch: FCC spectrum allocation rulings affecting BLE transmission power ceilings for dense venue deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified beacon-RTLS-WiFi management compresses vendor consolidation preferences among healthcare systems. |
| Acquisition of Specialist Firm | GDPR-native European analytics capabilities fill compliance gaps for US vendors targeting German retail chains. |
| Geographic Expansion | Eastern European final integration relocation maintains CE marking access without tariff exposure from Shenzhen. |
| Product Launch | UWB-enabled centimeter-precision suites capture premium pricing in healthcare surgical suite wayfinding. |
| Strategic Partnership | Automotive digital key chipset partnerships secure volume economics for logistics and healthcare positioning. |
Methodological Framework
A standing panel of beacon platform engineering directors, retail IT procurement officers, healthcare biomedical systems managers, and event technology integration specialists provided ongoing calibration against secondary validation from SEC filings of enterprise mobility vendors, ETSI protocol harmonization documents, FCC unlicensed spectrum rulings, and hyperscaler IoT platform capex disclosures. Bottom-up beacon deployment counts across Texas, Florida, California, Berlin, and Paris retail corridors triangulated with top-down platform revenue aggregation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with segmentation modeling spanning deployment model, wireless protocol generation, venue type density, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and technology convergence elasticity coefficients incorporated automotive UWB chipset volume trajectories and GDPR compliance implementation lag effects.
Material uncertainties—silicon supply concentration disruption, state-level privacy framework fragmentation, and lithium battery chemistry availability constraints—sit outside the modeled envelope. Forecasts reflect documented assumptions regarding IEEE protocol standardization velocity and ETSI cross-border harmonization continuity. Practitioners should keep alternative scenarios live as FCC spectrum allocation proceedings and REACH substance restriction enforcement evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Product Prototyping Market
Digital Solutions
Desktop Virtualization Market
Digital Solutions
Incidence Management Software Market
Digital Solutions
United Kingdom Digital Twin Market
Digital Solutions
Digital Onboarding Market
Digital Solutions
Global Data Catalog Market
Digital Solutions
Enterprise Content Management (ECM) Market
Digital Solutions
Revenue Management Solutions Market
Digital Solutions
Online Dating Application Market
Digital Solutions
Global Insight As a Service Market
Digital Solutions
Webrtc Market
Digital Solutions
Container Management Software Market
Digital Solutions
Virtual Hiring Tools Market
Digital Solutions
Disaster Recovery As a Service (Draas) Market
Digital Solutions
Game Engines Market
Digital Solutions
Canada Digital Twin Market