
 Underground Service Locator Market | 2026-2036
Underground Service Locator Market Size, Share, and Industry Trends Forecast 2026-2036
Underground Service Locator Market Analysis
OSHA excavation safety standards is hardening liability exposure for contractors who strike unmarked utilities, forcing fleet upgrades across the detection equipment value chain. USIC sustains the largest field technician footprint in North America, deploying electromagnetic and ground penetrating radar crews at municipal scale. Radiodetection Ltd. dominates electromagnetic locator design heritage, leveraging decades of signal-processing intellectual property. Hexagon AB extends its geospatial software-hardware integration into utility mapping workflows, competing on data interoperability rather than standalone hardware sales.
Underground service locators are electronic detection instruments that transmit electromagnetic, acoustic, or radio-frequency signals to identify buried pipes, cables, and conduits without surface excavation, typically resolving targets at depths from several centimeters to ten meters depending on soil conductivity and frequency selection. Their primary commercial purpose is preventing utility strikes that interrupt critical infrastructure service and endanger excavation personnel. Electromagnetic locators anchor the majority of unit sales due to lower capital cost and established technician familiarity, though ground penetrating radar commands premium positioning where non-metallic polyethylene pipes or undocumented backfill obscure conventional detection. Combination locators represent the fastest-expanding product configuration as contractors consolidate multiple detection modalities into single platform investments to reduce crew training overhead and equipment transport logistics.
The Federal Communications Commission governs radio-frequency emissions from active locator transmitters, while state public utility commissions enforce one-call compliance windows that dictate pre-excavation notice periods and certified locator response requirements. The Pipeline and Hazardous Materials Safety Administration mandates damage reporting thresholds that elevate documentation standards for utility strike incidents, indirectly stimulating demand for GPS-integrated locator systems that generate auditable spatial records. Stakeholders must weigh capital deployment toward multi-technology platforms against the operational simplicity of single-modality fleets as regulatory documentation burdens intensify and insurance underwriters adjust premium structures based on detection technology verification protocols.
Market Dynamics
State-level one-call mandates in the United States are compressing pre-excavation notice windows and compelling contractors to deploy certified detection equipment with auditable GPS records, restructuring procurement priorities across the detection equipment value chain.
Growth Catalysts
- Pipeline Safety Directives:Federal mandates from PHMSA elevate documentation standards for utility strike incidents, stimulating demand for integrated locator systems that generate spatial audit trails.
- Fiber-Optic Grid Expansion:Telecommunications infrastructure upgrades across Texas, California, and Florida accelerate procurement of combination locator systems capable of detecting non-metallic conduits.
- Electromagnetic Signal Processing:Advances in frequency selection algorithms extend detection depth in high-conductivity soils, expanding addressable excavation environments.
Market Restraints
- Ground Penetrating Radar Cost Structure:Premium positioning of GPR units relative to electromagnetic alternatives limits fleet penetration among small and mid-sized contractors.
- Soil Conductivity Variability:Technical limitations in clay-heavy or saline environments degrade signal resolution and force redundant verification methods.
- Technician Certification Bottlenecks:State-mandated response requirements for certified locators create supply constraints in high-growth metropolitan corridors.
Strategic Opportunities
- Data Interoperability Platforms:Convergence of geospatial software with detection hardware enables subscription-based utility mapping workflows.
- Municipal Fleet Modernization:City-scale infrastructure replacement cycles create concentrated demand for combination locator platforms with reduced training overhead.
- Insurance Premium Adjustments:Underwriter verification protocols rewarding GPS-integrated systems create financial incentives for technology upgrades.
Industry Challenges
- Multi-Modality Crew Training:Consolidation of electromagnetic, acoustic, and GPR capabilities into single platforms extends certification timelines and operational readiness.
- Legacy Infrastructure Documentation:Undocumented backfill and aging pipe materials in pre-digital municipal records force manual verification protocols that slow excavation workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Underground Service Locator Market |
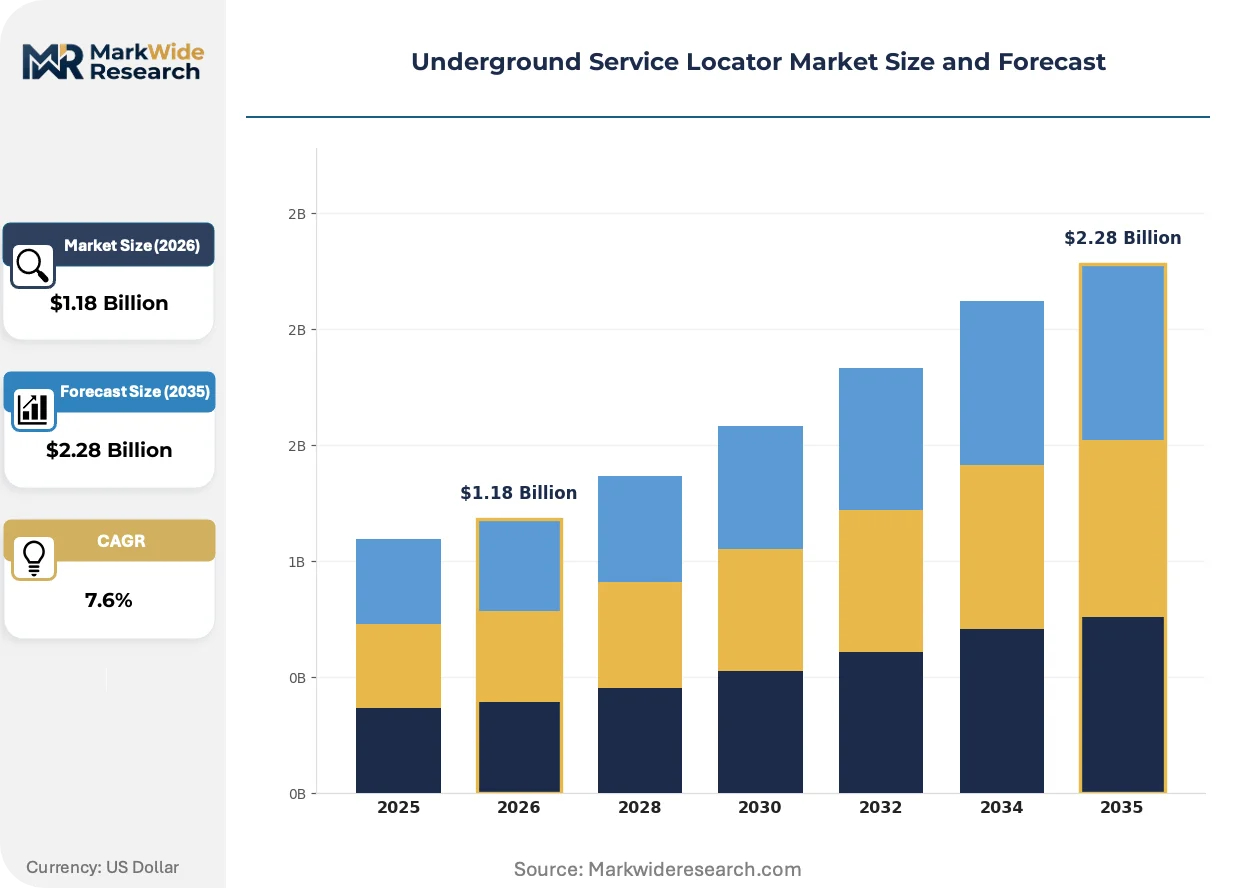
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromagnetic Locators, Ground Penetrating Radar, Acoustic Locators, Combination Locators Technology: Active Technology, Passive Technology, RFID Technology, Laser Technology Application: Utilities Detection, Construction Management, Pipeline Inspection, Environmental Monitoring End User: Construction Companies, Utility Providers, Engineering Firms, Government Agencies |
| Companies Covered | Trimble Inc., Guideline Geo, USIC, Schonstedt Instrument Company, Ridge Tool Company, Vivax-Metrotech, Hexagon AB, Leica Geosystems AG, Radiodetection Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Underground Service Locator Market Emerging Trajectories
Detection technology is converging with geospatial data infrastructure, shifting competitive differentiation from standalone hardware performance to integrated utility mapping ecosystems that compress project documentation cycles.
Ground penetrating radar is converging with electromagnetic detection in single-platform combination locators, enabling contractors to address polyethylene pipes and undocumented backfill without equipment swaps. Municipal-scale excavation crews in high-growth metropolitan corridors are adopting these consolidated systems fastest. The structural consequence is collapsing the historical segmentation between premium GPR positioning and economy electromagnetic fleets.
OSHA excavation safety standards are hardening liability exposure for contractors who strike unmarked utilities, forcing documentation protocol upgrades across the detection equipment value chain. State public utility commissions are aligning one-call compliance windows with federal pipeline safety directives. Contractors in Texas and California are responding by prioritizing GPS-integrated locator systems that generate auditable spatial records.
Equipment procurement is consolidating around multi-technology platforms that reduce crew training overhead and transport logistics. Fleet managers at utility providers and municipal contractors are displacing single-modality equipment purchases with combination locator investments. This behavioral shift is most visible in states with intensifying fiber-optic and electric grid replacement cycles.
Underground Service Locator Market Segmentation
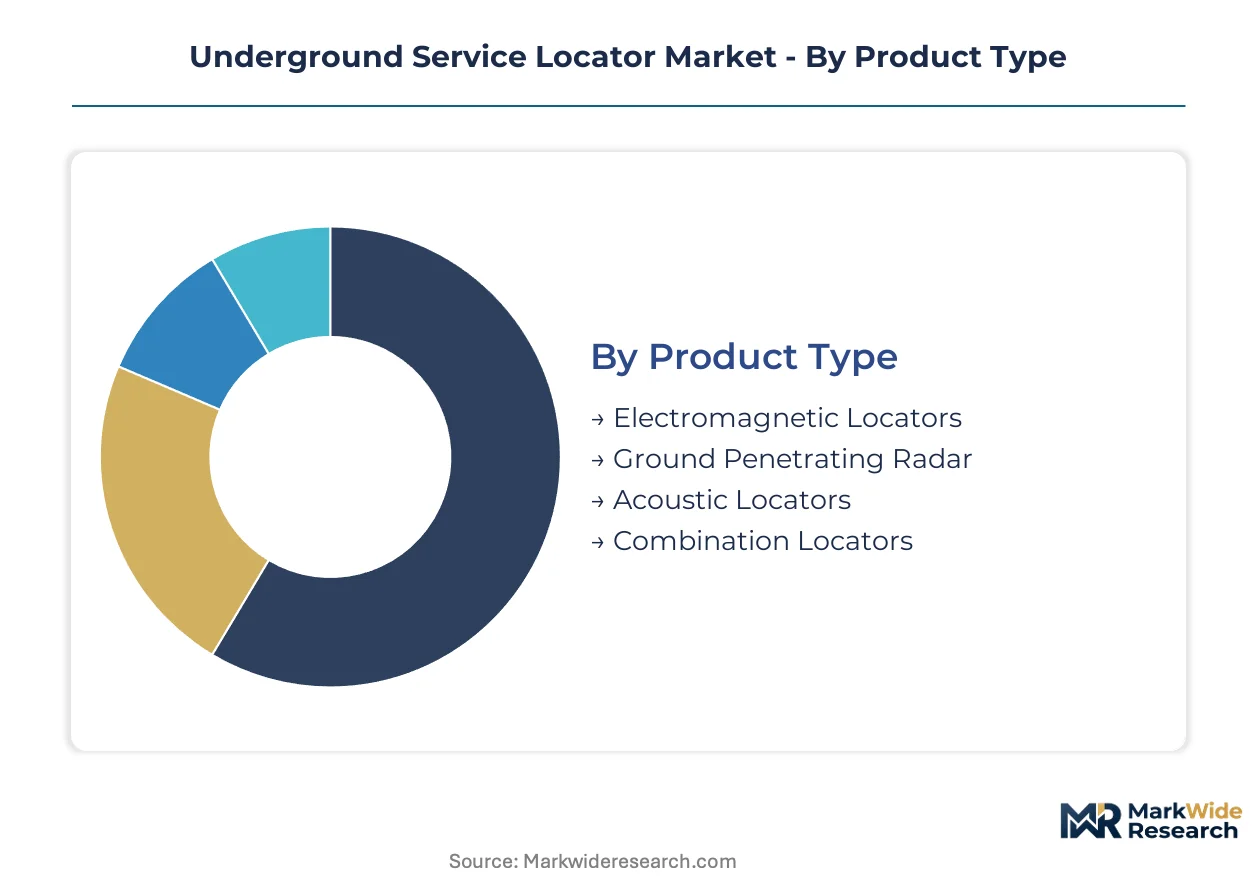
Underground service locator procurement splits sharply between standardized single-modality equipment and integrated multi-technology platforms. Contractors weigh capital efficiency against operational flexibility as regulatory documentation requirements intensify across excavation workflows.
Product Type:
Standardization dominates at the economy tier while customization accelerates at the premium end, with fleet managers consolidating capabilities to reduce certification overhead and transport logistics.
- Electromagnetic Locators:These instruments transmit low-frequency electromagnetic signals to trace conductive metallic utilities through soil, resolving targets at depths up to ten meters depending on frequency selection and ground conductivity. Demand concentrates among municipal contractors in Texas and California where aging metallic water mains and electric distribution lines require routine location verification before replacement cycles. Signal-processing advances in clay-heavy soils extend addressable environments, though saline conditions degrade resolution and force redundant verification protocols.
- Combination Locators:Integrated platforms consolidate electromagnetic detection with ground penetrating radar and acoustic sensing in single chassis designs, enabling crews to address polyethylene pipes and undocumented backfill without equipment swaps. Procurement accelerates among fiber-optic grid contractors across Florida and high-growth metropolitan corridors where non-metallic conduits dominate new infrastructure deployment. GPS-integrated variants generate auditable spatial records that satisfy PHMSA documentation mandates and insurance underwriter verification protocols.
- Ground Penetrating Radar:High-frequency radar pulses penetrate subsurface materials to image non-metallic utilities and soil disturbances, commanding premium positioning where electromagnetic methods fail.
- Acoustic Locators:Pressure-wave detection systems identify pressurized pipe leaks and valve locations through sound propagation analysis, serving water utility maintenance crews.
Leading the category by volume: Electromagnetic Locators. Growing fastest: Combination Locators.
Technology:
Active transmission methods anchor commercial deployment while passive and RFID modalities address specialized verification scenarios with reduced operator intervention.
- Active Technology:Transmitter-receiver architectures dominate commercial sales, with technicians injecting electromagnetic signals directly onto target utilities through conductive clamps or inductive coupling. Municipal-scale excavation crews across the United States deploy active systems for pre-excavation clearance where one-call mandates compress response windows and demand definitive target identification.
- Passive Technology:Receiver-only configurations detect ambient electromagnetic fields from energized power lines and cathodically protected pipelines without transmitter attachment, accelerating reconnaissance surveys. Utility providers in high-density urban corridors employ passive detection for rapid corridor mapping where direct utility access proves impractical.
- RFID Technology:Buried marker tags encode utility attribute data for precision retrieval during maintenance operations, gaining traction in smart city infrastructure deployments.
- Laser Technology:Optical scanning systems support above-ground utility pole and conduit mapping with centimeter-grade accuracy, serving telecommunications documentation workflows.
Active Technology commands the largest installed base. RFID Technology is gaining share fastest in smart infrastructure corridors.
Application:
Volume concentrates in damage prevention while emerging use cases expand into environmental compliance and asset lifecycle management.
- Utilities Detection:Pre-excavation clearance of buried electric, gas, water, and telecommunications infrastructure represents the core commercial purpose, with contractors deploying certified equipment to satisfy state-level one-call mandates. Demand intensifies in Texas, California, and Florida where fiber-optic and electric grid replacement cycles intersect with extreme weather-related infrastructure damage.
- Construction Management:Integrated locator systems feed geospatial data directly into project management platforms, compressing documentation cycles and reducing change-order exposure. Large-scale civil contractors leverage GPS-integrated outputs to generate auditable spatial records that defend against liability claims from utility strikes.
- Pipeline Inspection:Inline inspection tool tracking and coating defect location services employ specialized locator configurations for integrity management programs.
- Environmental Monitoring:Subsurface contamination plume mapping and landfill monitoring applications drive specialized GPR deployments with depth-calibrated antenna arrays.
Utilities Detection generates the highest unit volume. Construction Management applications are expanding most quickly as documentation protocols harden.
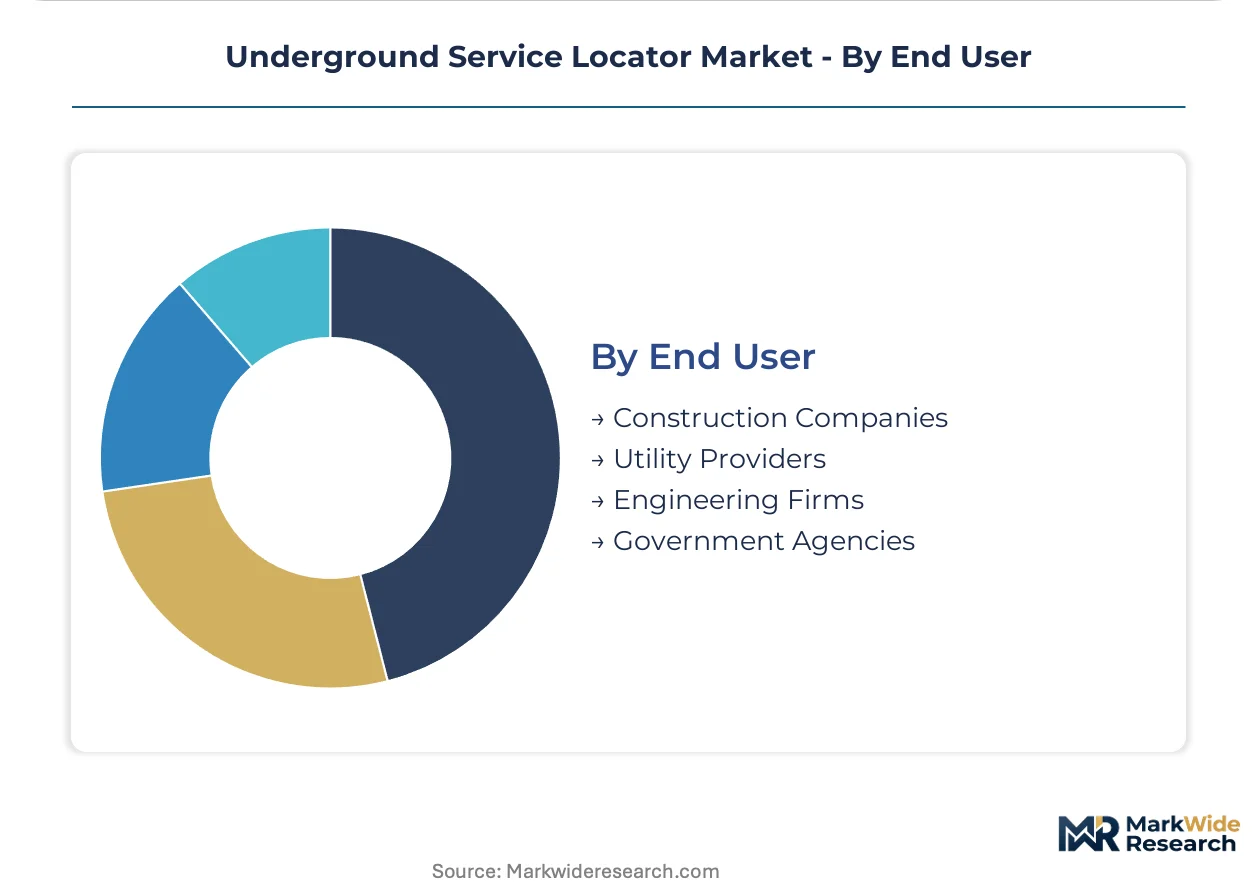
End User:
Fleet ownership patterns diverge between capital-intensive municipal utilities and equipment-rental-dependent construction contractors.
- Construction Companies:Excavation contractors face hardening liability exposure under OSHA standards, compelling fleet upgrades to certified detection equipment with auditable GPS records. Small and mid-sized operators increasingly rent combination locator platforms to avoid capital commitment while satisfying insurance underwriter verification protocols.
- Utility Providers:Electric, gas, water, and telecommunications operators maintain captive locator fleets at municipal scale, with USIC sustaining the largest field technician footprint in North America. Internal procurement prioritizes electromagnetic and GPR crews for routine maintenance and emergency response.
- Engineering Firms:Geotechnical and surveying consultancies deploy specialized GPR configurations for subsurface investigation and utility mapping deliverables.
- Government Agencies:Department of Transportation and municipal public works departments modernize fleets during infrastructure replacement cycles, favoring combination platforms with reduced training overhead.
Utility Providers own the largest installed equipment base. Construction Companies are driving replacement demand fastest as liability frameworks tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility infrastructure replacement cycles concentrate procurement in the United States, where state-level one-call mandates and federal pipeline safety directives compress pre-excavation response windows. Fiber-optic grid expansion and extreme weather-related damage drive concentrated demand across Texas, California, and Florida metropolitan corridors.
United States
State public utility commissions enforce one-call compliance windows that dictate certified locator response requirements, while PHMSA mandates elevate documentation standards for utility strike incidents. OSHA excavation safety standards harden liability exposure, compelling contractors to deploy GPS-integrated detection equipment. Demand clusters in Texas, California, and Florida where aging infrastructure maps intersect with fiber-optic and electric grid replacement cycles.
Canada
Municipal public works departments modernize locator fleets during infrastructure replacement cycles across Ontario and Quebec provinces. Health Canada and provincial regulators align damage prevention protocols with federal transportation safety directives. Toronto and Vancouver metropolitan areas drive combination locator procurement as contractors address undocumented backfill in pre-digital municipal records.
Germany
The country's national infrastructure regulator enforces excavation safety standards that elevate documentation requirements for utility strike prevention. REACH and CE marking frameworks govern electromagnetic emissions from active locator transmitters. Industrial clusters in North Rhine-Westphalia and Bavaria concentrate demand among municipal contractors upgrading electromagnetic and GPR capabilities for aging water main replacement.
China
MIIT and national standards bodies govern radio-frequency emissions from detection equipment while dual carbon goals accelerate smart city infrastructure deployment. Yangtze River Delta and Pearl River Delta metropolitan corridors drive combination locator adoption as contractors address polyethylene pipe networks in high-density urban construction. State-owned utility providers consolidate procurement around multi-technology platforms with reduced crew training overhead.
Australia
The country's national telecommunications regulator governs radio-frequency spectrum allocation for active locator transmitters used in utility detection workflows. State-level excavation safety frameworks in New South Wales and Victoria mandate certified equipment deployment ahead of ground disturbance. Sydney and Melbourne infrastructure replacement cycles concentrate demand for GPS-integrated systems that generate auditable spatial records for liability defense.
Underground Service Locator Market Vendor Landscape
North American service providers anchor one tier; European geospatial specialists hold another. The vendor base distributes across electromagnetic hardware heritage, integrated software-hardware platforms, and municipal-scale field service operations. Three archetypes dominate: field-service operators with captive technician fleets, geospatial integrators competing on data interoperability, and electromagnetic equipment specialists with decades of signal-processing intellectual property. Competitive moves center on multi-technology platform consolidation and subscription-based utility mapping workflows.
Among the named players, USIC exemplifies the field-service operator archetype with municipal-scale technician deployment. Radiodetection Ltd. and Hexagon AB occupy positions on the technology heritage and geospatial integration vectors respectively. Trimble Inc. and Leica Geosystems AG represent precision measurement specialists extending capabilities into utility mapping workflows. These companies illustrate the competitive tension between standalone hardware performance and integrated data ecosystem differentiation.
| Leading Market Players |
|---|
| Trimble Inc. |
| Guideline Geo |
| USIC |
| Schonstedt Instrument Company |
| Ridge Tool Company |
| Vivax-Metrotech |
| Hexagon AB |
| Leica Geosystems AG |
| Radiodetection Ltd. |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up field service operators anchor North American supply, concentrating procurement leverage among USIC-scale fleets while compressing margins for standalone electromagnetic equipment vendors serving price-sensitive municipal contractors.
Pricing Analysis
Short lead-time premiums command pricing power where PHMSA-mandated documentation deadlines compress contractor response windows. Three-tier pricing structure across GPS-integrated premium platforms, standard electromagnetic units, and rental economy tiers stratifies the market. Price differentiation hinges on certification grade alignment with state one-call mandates and after-sales calibration service bundling. Cost compression in the economy tier intensifies as rental penetration rises among small contractors seeking to avoid capital commitment.
Supply Chain Analysis
Antenna array and signal-processing chip supply rests on Taiwanese semiconductor foundries and German precision electronics manufacturers. Electromagnetic coil assemblies and radar transceiver modules draw from Chinese component ecosystems and Japanese specialty sensor producers. Single-source vulnerability concentrates in high-frequency radar subassemblies where qualified secondary suppliers remain limited. Distribution runs through manufacturer-direct municipal fleet contracts and regional equipment rental networks serving construction contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
State-level one-call mandates in the United States erect a cost-of-compliance barrier that favors incumbent field service operators with certified technician scale over capital-light equipment entrants lacking GPS-integrated platform portfolios.
For Market Incumbents: Anticipate margin compression from combination locator commoditization by locking municipal fleet replacement cycles through subscription-based utility mapping workflows. Consolidate electromagnetic and GPR capabilities into unified data platforms before emerging geospatial software entrants capture interoperability rents. Prioritize certification investment in Texas and California where infrastructure replacement intensity peaks.
For New Entrants and Emerging Players: OSHA excavation safety standards in the United States open a window for niche acoustic detection specialists targeting water utility maintenance crews underserved by electromagnetic-centric incumbents. Penetrate Florida fiber-optic contractor segments through rental partnership models that eliminate capital barriers. Deploy go-to-market strategies anchored on insurance underwriter verification protocol compliance to bypass direct price competition with established fleets.
For Investors and Strategic Acquirers: Distressed-cycle entries favor combination locator technology specialists with proprietary signal-processing IP in North American metropolitan corridors. Long-term viability over the mid-decade horizon hinges on data interoperability positioning rather than standalone hardware margins. Monitor state public utility commission mandate expansion as the primary inflection signal for fleet modernization acceleration.
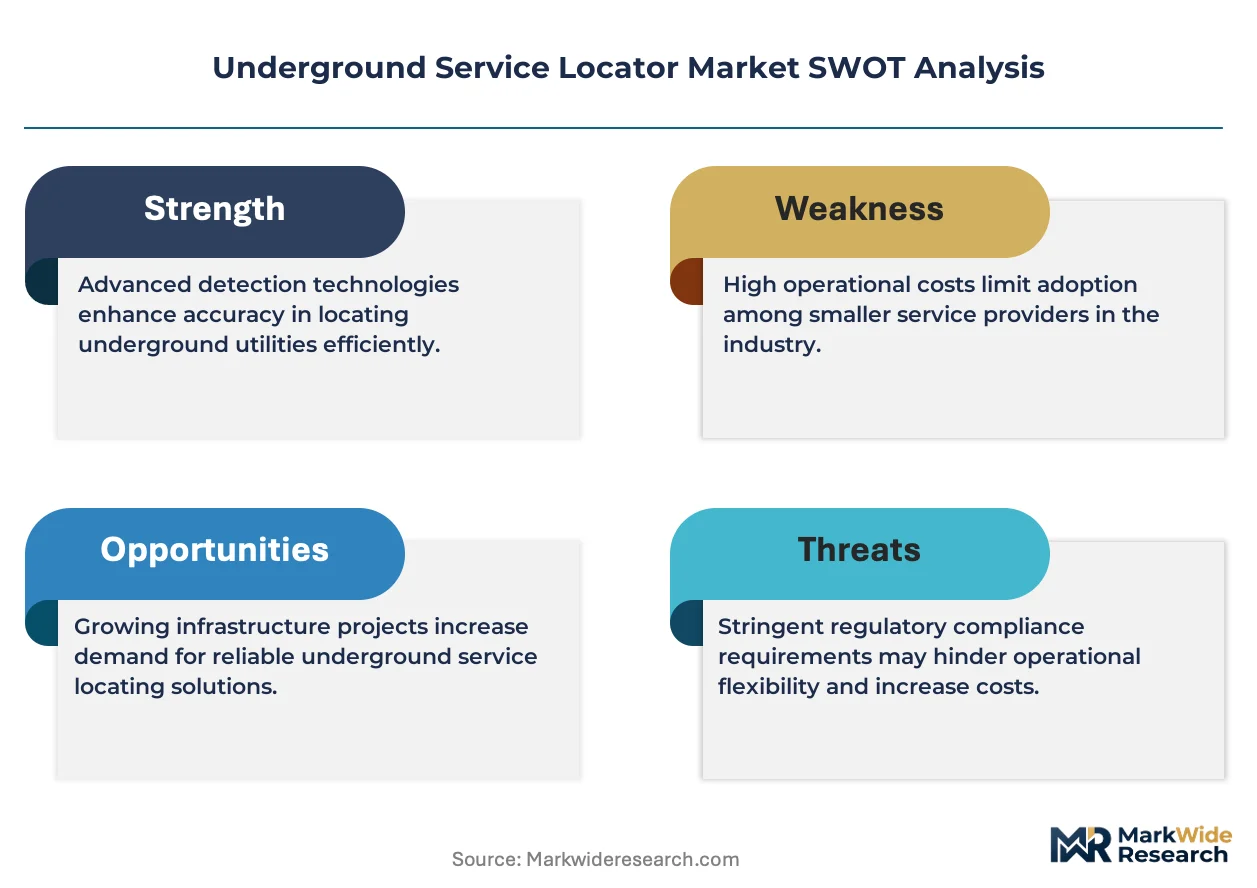
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Technology Platform Integration | Consolidation of electromagnetic, GPR, and acoustic capabilities reduces crew training overhead for municipal contractors. |
| Subscription-Based Utility Mapping | Recurring revenue models align with PHMSA documentation mandates requiring continuous spatial audit trail generation. |
| Certification Investment Expansion | State-mandated locator response requirements create captive demand for certified technician deployment at scale. |
| Insurance Verification Protocol Alignment | GPS-integrated system adoption accelerates as underwriters adjust premium structures based on detection technology verification. |
| Regional Rental Network Partnership | Equipment-rental-dependent construction contractors access combination platforms without capital commitment. |
Methodological Framework
Independent corroboration across municipal procurement officers, field service operations managers, and equipment rental network directors underwrites the qualitative findings. Primary interviews with utility provider fleet managers, certified locator technicians, and geospatial software integration specialists combined with secondary validation from FCC equipment authorization databases, state public utility commission one-call compliance filings, and OSHA excavation incident reports. Bottom-up equipment shipment triangulation against top-down infrastructure spending allocations anchors market sizing.
Rate-of-change decomposition across product type, technology modality, application segment, and end-user ownership pattern structures the analytical framework. CAGRs derive from modeled replacement cycle intensity, regulatory mandate expansion trajectories, and fiber-optic grid deployment schedules. Forecast inputs incorporate soil conductivity mapping variability and technician certification pipeline constraints.
The model assumes a particular technology adoption path; alternative pathways for ground penetrating radar cost reduction would alter the outlook. Forecasts reflect assumptions regarding state mandate harmonization and municipal budget continuity. Equipment rental penetration acceleration or electromagnetic signal-processing breakthroughs could revise projections. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Industrial Barcode Scanners Market
Sensors
Global RFID Market
Sensors
Terrestrial Laser Scanning System Market
Sensors
Global Energy Harvesting System for Wireless Sensor Network Market
Sensors
Refrigeration Monitoring Market
Sensors
Indoor Location Market
Sensors
Eye Tracking Solutions Market
Sensors
Portable Iris Recognition Scanner Market
Sensors
Heat Stress Meter Market
Sensors
Voice Sounders Market
Sensors
Residential Water Leak Detection System Market
Sensors
Active Noise and Vibration Control (ANVC) Systems Market
Sensors
Temperature Data Loggers Market
Sensors
Remote Sensing Technology Market
Sensors
Global Equipment Monitoring Market
Sensors
Indoor Positioning and Navigation Market