
 Device Tracking Software Market | 2026-2036
Device Tracking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Device Tracking Software Market Insights
The premium tier of device tracking software is consolidating around real-time IoT-enabled platforms with sub-meter location accuracy, while commodity offerings stagnate in basic barcode logging. Zebra Technologies leverages its hardware-software integration to dominate rugged enterprise deployments. Oracle anchors cloud-based asset management through enterprise ERP connectivity. Trimble specializes in GPS-differentiated tracking for construction and field service fleets.
Device tracking software comprises location-aware platforms that capture, process, and visualize asset position data through GPS triangulation, RFID interrogation, Bluetooth beacon proximity detection, or barcode optical scanning, typically achieving refresh intervals from continuous streaming to periodic batch updates. These systems serve industrial and commercial operators by eliminating manual inventory audits, reducing asset shrinkage, and orchestrating just-in-time equipment deployment across distributed facilities. Cloud-based deployment is capturing the fastest expansion as manufacturers and logistics providers shed capital-intensive server infrastructure. IoT Solutions technology leads in R&D allocation, though Data Analytics now generates the highest margin pools by converting raw location feeds into predictive maintenance and utilization optimization insights.
FDA's Unique Device Identification rule and the EPA's hazardous materials transport protocols are tightening audit trail requirements, forcing healthcare and chemical logistics buyers toward validated tracking platforms with immutable record architectures. FCC Part 15 regulations govern Bluetooth and RFID transmission power, directly constraining indoor positioning accuracy and hardware certification pathways in US deployments. Stakeholders must weigh interoperability investments against proprietary ecosystem lock-in as regulatory bodies on both coasts advance data portability mandates.
Market Dynamics
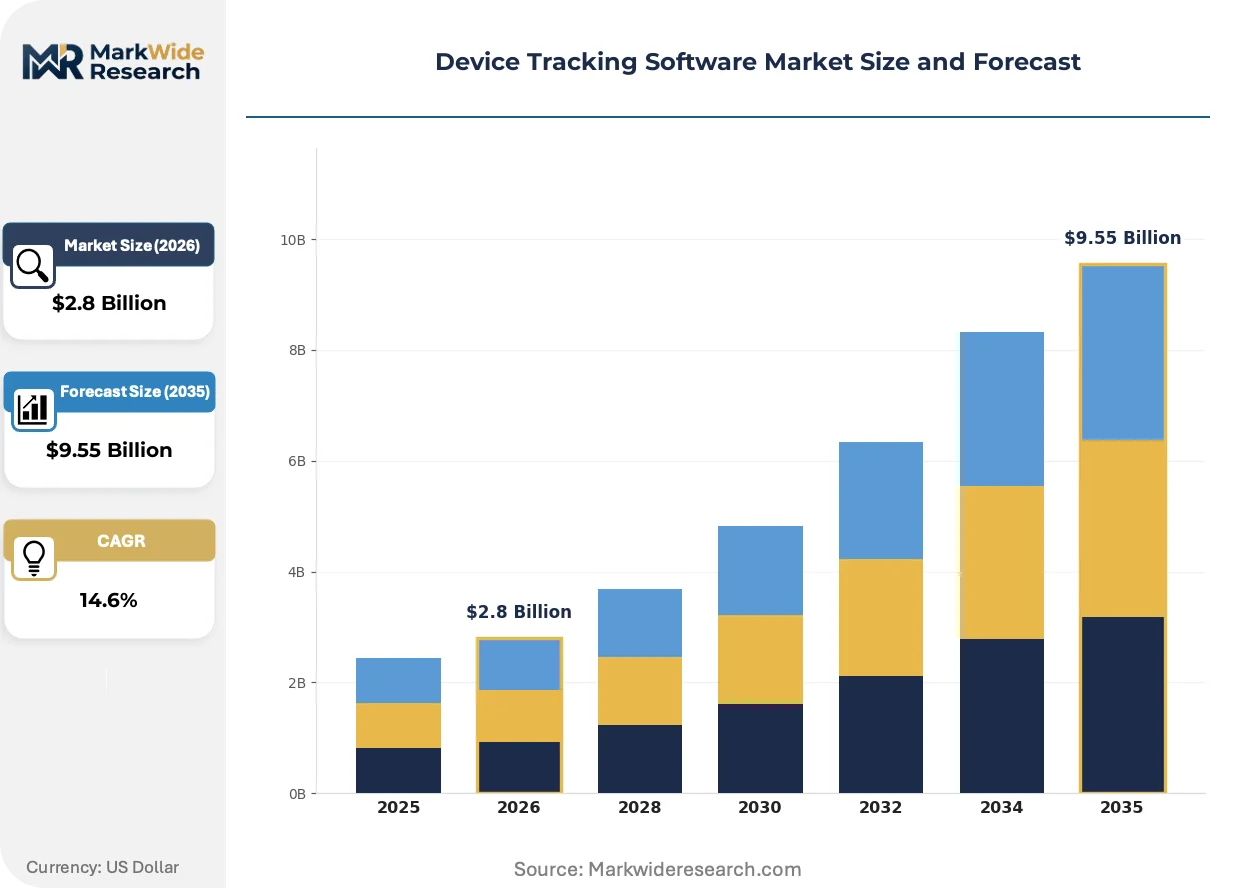
The Device Tracking Software Market is undergoing structural compression as real-time IoT platforms displace legacy barcode systems, with regulatory mandates forcing validated architectures and cloud deployment economics eliminating on-premise infrastructure advantages.
Growth Catalysts
- Healthcare Asset Monitoring:Hospital networks are deploying sub-meter accuracy platforms to eliminate equipment loss and optimize patient flow through operating theaters.
- FDA UDI Mandate:The Unique Device Identification rule compels medical device manufacturers toward interoperable tracking systems with immutable audit trails.
- Defense Logistics Modernization:Military supply chains are accelerating GPS-differentiated fleet tracking for hazardous materials transport and field equipment orchestration.
Market Restraints
- Hardware Certification Barriers:FCC Part 15 power limits constrain Bluetooth and RFID transmission ranges, degrading indoor positioning accuracy in US deployments.
- Data Portability Friction:Proprietary ecosystem lock-in from dominant platform vendors resists interoperability investments despite emerging mandates.
- Immutable Architecture Costs:Validated tracking platforms with tamper-proof record systems require specialized engineering that commodity vendors cannot replicate.
Strategic Opportunities
- Construction Fleet Digitization:GPS-anchored tracking for heavy equipment remains underpenetrated among mid-sized contractors managing distributed job sites.
- EPA Transport Protocol Alignment:Chemical logistics providers face tightening hazardous materials documentation requirements that favor automated tracking adoption.
- Edge-Cloud Convergence:Hybrid architectures combining local sensor processing with centralized analytics are opening mid-market access previously blocked by bandwidth costs.
Industry Challenges
- RF Engineering Talent Scarcity:Indoor positioning system design requires specialized expertise in signal propagation modeling that outpaces university pipeline output.
- Legacy ERP Integration Complexity:Enterprise resource planning connectivity demands custom middleware development that extends deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Device Tracking Software Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Tracking, RFID Tracking, Barcode Tracking, Bluetooth Tracking End User: Manufacturing, Logistics, Retail, Healthcare Deployment: On-Premises, Cloud-Based, Hybrid, Mobile Technology: IoT Solutions, Software as a Service, Real-Time Monitoring, Data Analytics |
| Companies Covered | Zebra Technologies, Oracle, Asset Panda, Trimble, Royal 4 Systems, Trackforce, Terso Solutions, Dynatablet, CalAmp Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Device Tracking Software Market Trends and Innovations
Sensor fusion architectures and predictive analytics layers are transforming device tracking from reactive location logging into proactive asset optimization engines.
Ultra-wideband (UWB) positioning is consolidating around centimeter-accurate indoor location systems that triangulate between fixed anchors and mobile tags. Pharmaceutical cleanrooms and semiconductor fabs are adopting UWB at accelerated pace to track high-value tools through contamination-controlled zones. This precision tier is compressing the addressable market for WiFi-based alternatives that cannot achieve comparable spatial resolution.
EMA's Medical Device Regulation and the EU AI Act are tightening algorithmic transparency requirements for predictive maintenance modules embedded in tracking platforms. Manufacturers must now document training data provenance and decision logic for location-derived failure predictions. German hospital networks and French logistics operators are responding by demanding ISO 13485-certified software stacks with auditable machine learning pipelines.
Subscription-based platform economics are displacing perpetual license models as buyers prioritize operational expenditure flexibility over capital ownership. Third-party logistics providers and regional hospital systems are driving this transition, particularly in United States markets where equipment-as-a-service contracts bundle tracking software with hardware refresh cycles. Vendors are unbundling professional services to preserve margin while competing on pure software recurring revenue.
Device Tracking Software Market Segmentation
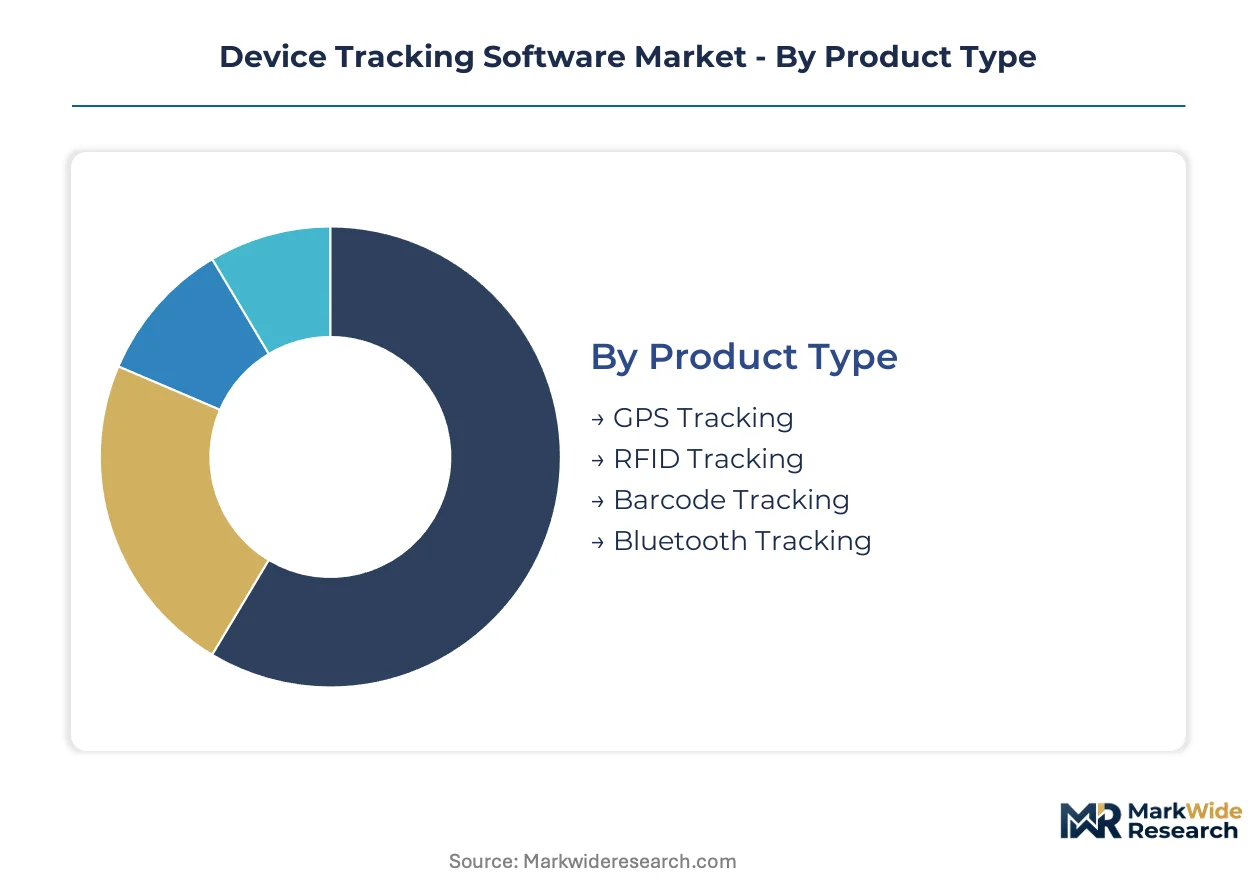
Device tracking software segments diverge sharply by technical capability and infrastructure requirement. Buyers select positioning technologies and deployment models based on asset mobility patterns, regulatory audit demands, and existing enterprise system architectures.
Product Type:
Positioning accuracy and environmental penetration define the technology hierarchy across indoor and outdoor use cases.
- GPS Tracking:Satellite triangulation enables meter-level accuracy for mobile assets operating outdoors without infrastructure investment. Defense logistics programs and construction fleet operators in the United States deploy GPS-differentiated platforms for hazardous materials convoys and distributed heavy equipment.
- RFID Tracking:Passive and active radio frequency identification interrogates tags through fixed readers, achieving room-level precision without line-of-sight constraints. Hospital networks deploy RFID for surgical instrument sterilization workflows and pharmaceutical cold chain verification, though FCC Part 15 power limits constrain transmission range in US facilities.
- Barcode Tracking:Optical scanning of printed codes remains the lowest-cost entry point for static inventory management. Warehouse operators with predictable asset flows use barcode systems where real-time visibility is unnecessary.
- Bluetooth Tracking:Low-energy beacon proximity detection enables sub-meter indoor positioning at moderate infrastructure cost. Retail environments and corporate campuses deploy Bluetooth for personnel safety and space utilization analytics.
Mature deployment sits with Barcode Tracking. Newer deployment is concentrated in Bluetooth Tracking.
End User:
Industry verticals impose distinct regulatory, accuracy, and integration requirements that reshape platform specifications.
- Healthcare:FDA UDI mandates and patient safety protocols demand validated platforms with immutable audit trails. Operating theater equipment tracking and implantable device traceability drive sub-meter accuracy requirements.
- Logistics:Third-party providers prioritize cloud elasticity and API connectivity for multi-tenant fleet orchestration. EPA hazardous materials transport protocols favor automated documentation systems.
- Manufacturing:Production line integration and predictive maintenance modules convert location data into utilization optimization. Automotive and electronics assemblers lead in IoT sensor fusion adoption.
- Retail:Inventory visibility and customer experience applications favor lower-cost beacon networks. Loss prevention and click-and-collect fulfillment represent primary deployment drivers.
Regulatory pressure is reshaping competitive positioning in Healthcare. Logistics represents the steepest expansion trajectory for cloud-native platforms.
Deployment:
Infrastructure ownership models determine capital allocation patterns and operational flexibility across buyer segments.
- Cloud-Based:Subscription economics eliminate server capital expenditure and enable elastic scaling for seasonal volume fluctuations. Third-party logistics providers and regional hospital systems drive this transition in United States markets.
- Hybrid:Edge processing combined with centralized analytics addresses bandwidth constraints and latency-sensitive applications. Mid-sized manufacturers adopt hybrid architectures for distributed facility networks.
- On-Premises:Dedicated server installations persist where data sovereignty or air-gapped security requirements override cost considerations. Defense and classified research facilities maintain on-premise deployments.
- Mobile:Smartphone-native applications extend tracking capabilities without dedicated hardware investment. Field service technicians and temporary event operations favor mobile-first deployment.
Procurement is shifting most dramatically toward Cloud-Based deployment. On-Premises retention concentrates in defense and intelligence sectors.
Technology:
Functional layer differentiation separates commodity location logging from premium predictive optimization platforms.
- Data Analytics:Machine learning pipelines convert raw position feeds into failure prediction and utilization insights. German hospital networks and French logistics operators demand ISO 13485-certified software stacks with auditable algorithmic transparency under EU AI Act requirements.
- IoT Solutions:Sensor fusion architectures integrate GPS, RFID, and beacon inputs through unified data models. Semiconductor fabs and pharmaceutical cleanrooms adopt ultra-wideband-enabled IoT for centimeter-accurate tool tracking through contamination-controlled zones.
- Real-Time Monitoring:Continuous streaming architectures enable immediate alerting for geofence violations and asset misuse. Construction fleet operators use real-time monitoring for theft prevention and operator safety compliance.
- Software as a Service:Platform unbundling separates core tracking functionality from professional services and hardware provisioning. Equipment-as-a-service contracts bundle SaaS tracking with refresh cycles.
R&D allocation concentrates in IoT Solutions. Margin expansion is accelerating in Data Analytics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego anchors North American device tracking software deployment through its dense concentration of defense contractors and naval logistics operations feeding into the broader United States market.
United States
Hospital networks in Texas and Florida are deploying sub-meter accuracy platforms to eliminate surgical equipment loss and optimize patient throughput. FDA's Unique Device Identification mandate compels medical device manufacturers toward interoperable tracking systems with immutable audit trails. Boston's medical technology corridor drives validation engineering for healthcare-grade tracking architectures.
Germany
Automotive assemblers in Stuttgart and Munich are converting location data into predictive maintenance modules for production line optimization. EMA's Medical Device Regulation tightens algorithmic transparency requirements for AI-embedded tracking platforms. The Ruhr industrial basin concentrates IoT sensor fusion adoption for distributed manufacturing facility networks.
China
Logistics providers in Shanghai and Shenzhen prioritize cloud elasticity and API connectivity for multi-tenant fleet orchestration across manufacturing export corridors. NMPA device traceability requirements push pharmaceutical cold chain operators toward validated tracking platforms. The Yangtze River Delta anchors GPS-differentiated fleet tracking for hazardous materials transport.
United Kingdom
Third-party logistics operators in the Midlands demand ISO 13485-certified software stacks with auditable machine learning pipelines under EU AI Act alignment pressure. MHRA post-Brexit regulatory frameworks maintain UDI-equivalent traceability mandates for medical device tracking. London's fintech corridor drives subscription-based platform economics displacing perpetual license models.
Japan
Semiconductor fabs in Kyushu adopt ultra-wideband-enabled tracking for centimeter-accurate tool positioning through contamination-controlled cleanrooms. METI industrial digitization programs subsidize edge-cloud convergence architectures for mid-sized manufacturers. The Kansai manufacturing belt concentrates real-time monitoring deployments for theft prevention and operator safety compliance.
Device Tracking Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the accuracy-certification dimension, with validated healthcare-grade platforms commanding pricing multiples over basic barcode logging systems. The vendor base stratifies into hardware-integrated specialists, cloud-native ERP connectors, and GPS-differentiated field service providers. Dominant competitive moves include strategic partnerships with medical device manufacturers and geographic expansion through equipment-as-a-service contract bundling.
Within the hardware-integrated tier, Zebra Technologies leverages its rugged enterprise heritage to dominate industrial deployments. Oracle anchors cloud-based asset management through enterprise ERP connectivity. Trimble occupies a position among GPS-differentiated specialists serving construction and field service fleet operators. These three exemplify the archetype fragmentation between physical infrastructure control, software platform scale, and vertical specialization that defines competitive positioning in this market.
| Leading Market Players |
|---|
| Zebra Technologies |
| Oracle |
| Asset Panda |
| Trimble |
| Royal 4 Systems |
| Trackforce |
| Terso Solutions |
| Dynatablet |
| CalAmp Corp |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement committees consolidating vendor lists under FDA UDI compliance timelines are squeezing commodity tracking providers and elevating validated platform pricing power. Supply chains must absorb certification engineering costs or exit healthcare verticals entirely.
Pricing Analysis
Outcome-based contracts tied to equipment uptime guarantees anchor pricing for premium healthcare-grade platforms. Three-tier pricing structure across validated healthcare, industrial-grade, and basic barcode tiers separates FDA-certified stacks from uncertified alternatives. Pricing pressure stems from mid-market buyers demanding SaaS flexibility without enterprise implementation overhead. Regional hospital systems exhibit highest price sensitivity; defense logistics programs demonstrate lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from United States hospital networks and defense contractors, while value-added resellers serve mid-sized contractors. Hardware component sourcing concentrates in China, Taiwan, and South Korea for RFID readers and GPS modules. Semiconductor supply for UWB positioning chips rests on single-source vulnerability at advanced node foundries. Distribution runs through authorized integrators with vertical-specific certification credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as regulatory validation requirements and cloud infrastructure investments force sub-scale vendors toward acquisition or exit.
For Market Incumbents: Anchor market position through ISO 13485 certification investments that commodity competitors cannot replicate. Deepen backward integration into UWB sensor manufacturing to control hardware-software margin capture. Defend against cloud-native ERP connectors by embedding predictive analytics modules that generate recurring revenue stickiness. For New Entrants and Emerging Players: Capture construction fleet digitization white space among mid-sized contractors managing distributed job sites in Texas and Florida. Target hybrid edge-cloud architectures for bandwidth-constrained manufacturing facilities. Lead with equipment-as-a-service bundling to bypass capital procurement friction. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated hardware-software specialists given FDA UDI mandate acceleration. Long-term viability favors platforms with validated healthcare architectures and defense contract credentials. Watch NMPA traceability rule expansion in China as inflection indicator for Asia-Pacific licensing demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | ERP connectivity with Oracle and SAP systems captures enterprise procurement workflows. |
| Regulatory Certification Investment | ISO 13485 and FDA validation opens healthcare pricing tiers closed to uncertified rivals. |
| Strategic Partnership | Medical device manufacturer alliances embed tracking software at point of manufacture. |
| Geographic Expansion | Equipment-as-a-service contracts in Germany and Japan penetrate regulated healthcare markets. |
| Acquisition of Specialist Firm | UWB positioning startups add centimeter-accuracy capability for semiconductor cleanroom applications. |
Research Methodology
Multi-period observation of hospital procurement database trends and defense contract award patterns anchored the trend analysis, supplemented by interviews with biomedical engineers, GPO contracts managers, platform integration specialists, and EPC contractors. Secondary validation drew from FDA UDI registration data, CMS Medicare equipment utilization reports, SEC 10-K filings, and hyperscaler capex disclosures. Bottom-up segment sizing triangulated against top-down macro indicators.
Segment-weighting across deployment models, organization size tiers, vertical applications, and regional adoption patterns structured the analytical framework. CAGRs derived from logistic diffusion curves fitted to technology substitution patterns across the projection horizon. Forecast inputs incorporated FCC Part 15 regulatory constraint trajectories and EPA hazardous materials transport protocol enforcement intensity.
The model holds under stable regulatory enforcement and continued cloud infrastructure cost decline; deviation in semiconductor supply availability or tariff regime shifts would shift hardware-dependent segment growth rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Service Dispatch Software Market
Software & Services
Global User Interface Service Market
Software & Services
Global Business Software and Service Market
Software & Services
Test Management Software Market
Software & Services
Exploration and Production (E&P) Software Market
Software & Services
Software-Defined Anything Market
Software & Services
Test Automation Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Global Localization Software Market
Software & Services
Lending Software Market
Software & Services
Admission Management Software Market
Software & Services
Remote Sensing Software Market
Software & Services
Japan IT Services Market
Software & Services
Construction Jobsite Management Software Market
Software & Services
United States Donation Management Software Market
Software & Services
Batch Management Software Market