
 Agriculture Robotics Market | 2026-2036
Agriculture Robotics Market Size, Share, and Industry Trends Forecast 2026-2036
Agriculture Robotics Market Insights
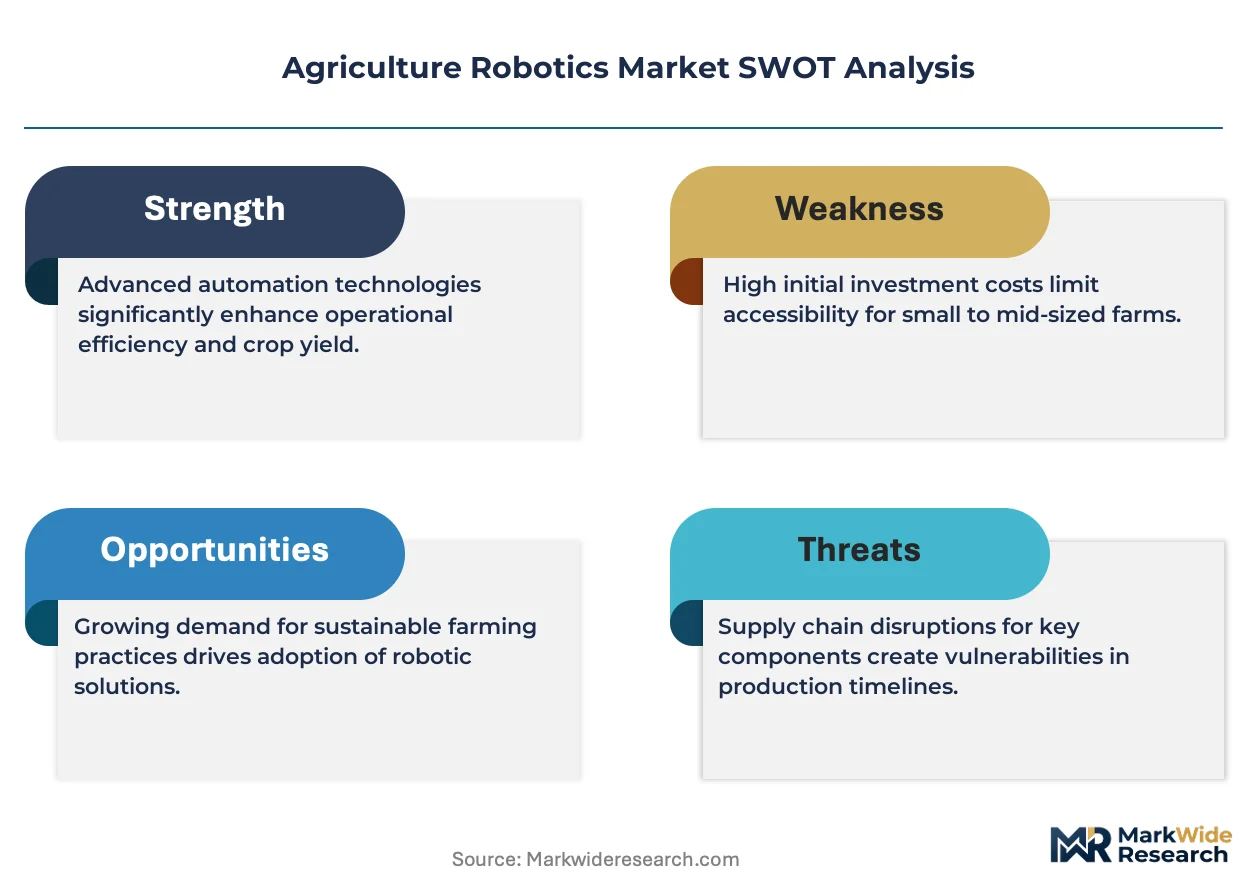
EU Farm to Fork Strategy is expanding compliance burdens on chemical inputs and labor practices across European arable operations. Deere & Company leverages its precision-ag software stack to anchor autonomous tractor deployments across North American row-crop belts. AGCO Corporation competes through open-architecture platforms that let farmers mix third-party robotic implements. CNH Industrial specializes in integrated harvesting autonomy, controlling development pathways from sensor fusion to grain-tank logistics.
Agriculture robotics encompasses autonomous ground vehicles, aerial drones, and stationary robotic systems engineered for mechanical precision in field and barn environments, typically operating with sub-centimeter GPS accuracy and real-time multispectral feedback. These systems execute seeding, cultivation, spraying, harvesting, and livestock management tasks with continuous environmental responsiveness that reduces input waste and labor dependency. Automated harvesters currently dominate product-type revenue as strawberry and apple producers face acute seasonal labor shortages. Machine learning and computer vision technologies are capturing the fastest technology-category expansion, enabling robotic arms to identify ripeness and disease pressure without human intervention. Farmers represent the most fragmented end-user segment, though agribusiness companies consolidate purchasing power through fleet-scale autonomous deployments.
FDA oversees residue thresholds that shape spraying-robot validation protocols, while EPA chemical-application rules constrain autonomous nozzle configurations in US specialty-crop zones. EU Green Deal emissions targets and REACH substance restrictions are redirecting R&D investment toward mechanical weeding robots that eliminate herbicide dependency. ISO 18497 safety standards for autonomous agricultural machinery govern collision-avoidance architectures that manufacturers must certify before commercial rollout. Stakeholders must weigh regulatory divergence between jurisdictions when designing platform architectures that can migrate across North American, European, and Asian compliance regimes without complete hardware redesign.
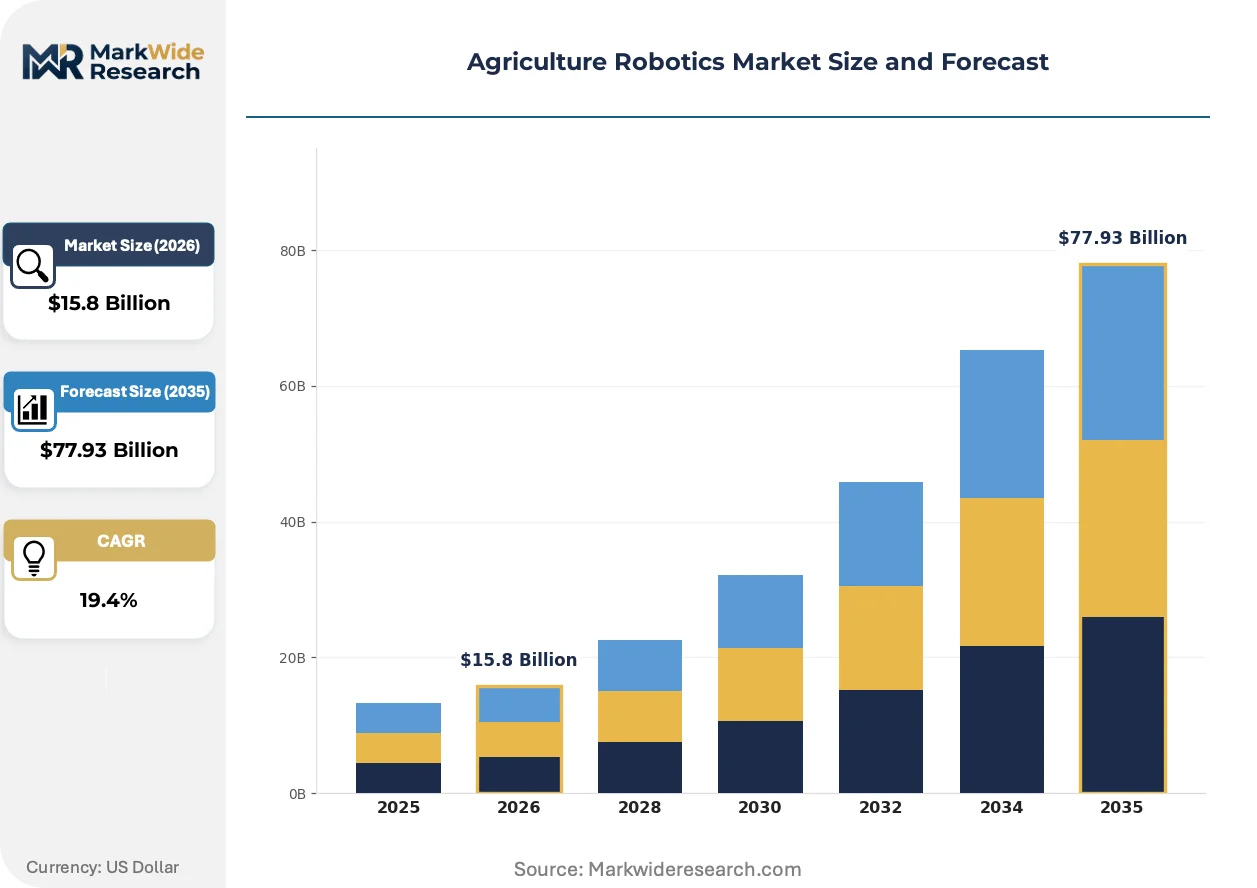
Market Dynamics
Machine learning convergence with precision sensing is compressing deployment economics for autonomous field systems, forcing equipment manufacturers to restructure hardware-software integration roadmaps around real-time environmental responsiveness rather than incremental automation.
Growth Catalysts
- Labor scarcity demographics:Japan's aging farmer population is accelerating robotic milking and transplanting adoption in dairy and rice operations, creating pull-through demand for integrated barn-to-field platforms.
- EU Green Deal emissions mandates:REACH substance restrictions and mechanical weeding incentives are redirecting capital from chemical-dependent spraying systems toward vision-guided cultivators that eliminate herbicide dependency.
- Computer vision maturation:Sub-centimeter GPS accuracy combined with multispectral feedback is enabling robotic arms to execute selective harvesting of strawberries and apples without human ripeness assessment.
Market Restraints
- Sensor supply concentration:Lidar and hyperspectral camera modules rely on concentrated East Asian component foundries, exposing fleet-scale deployments to single-source vulnerability.
- ISO 18497 certification timelines:Collision-avoidance architecture validation for autonomous agricultural machinery requires 18-24 month approval cycles that delay commercial rollout.
- High-voltage battery cost volatility:Lithium-ion cell price fluctuations directly compress margins on electric autonomous platforms targeting all-day field endurance.
Strategic Opportunities
- Underpenetrated specialty crop zones:California lettuce and vine operations remain below 5% robotic harvesting penetration despite acute seasonal labor shortages, offering first-mover expansion potential.
- EU Farm to Fork compliance services:Chemical-input tracking and labor-practice documentation requirements create adjacent revenue streams for robotics platforms with embedded compliance logging.
- 5G-edge convergence:Low-latency connectivity combined with on-vehicle inference chips enables swarm coordination of multiple autonomous units without centralized cloud dependency.
Industry Challenges
- Mechatronics talent scarcity:Agricultural robotics development requires rare cross-functional expertise spanning mechanical engineering, agronomy, and embedded systems software.
- Legacy equipment integration friction:Mixed-fleet environments force autonomous platforms to interoperate with 15-20 year-old tractors lacking CAN bus or precision-ag data interfaces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agriculture Robotics Market |
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $77.93 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Harvesters, Planting Robots, Weeding Robots, Spraying Robots Technology: Machine Learning, Computer Vision, GPS Navigation, Sensor Technology End User: Farmers, Agribusiness Companies, Research Institutes, Cooperative Societies Application: Crop Management, Pest Control, Soil Monitoring, Yield Estimation |
| Companies Covered | Deere & Company, AGCO Corporation, CNH Industrial, GEA Group, Lely, DJI, Trimble Inc., Autonomous Solutions Inc., YANMAR HOLDINGS CO., LTD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agriculture Robotics Market Trends and Innovations
Active reshaping of the agriculture robotics landscape centers on three converging vectors: edge intelligence deployment, regulatory reconfiguration of input protocols, and compressed buyer decision cycles for capital-intensive automation.
Computer vision systems with embedded neural inference engines are absorbing the ripeness-assessment and disease-detection functions previously requiring human agronomists. Strawberry and apple producers in California and the Netherlands are deploying these platforms at pilot-to-production scale within single growing seasons. This capability compression is eliminating the labor-quality bottleneck that constrained autonomous harvesting economics in delicate specialty crops.
EPA chemical-application rules are constraining autonomous nozzle configurations in US specialty-crop zones, forcing equipment redesigns that prioritize mechanical weeding and precision spraying over broadcast herbicide deployment. California leafy-green operations face the most acute compliance pressure, accelerating validation partnerships between robotics developers and regional grower cooperatives for residue-threshold documentation.
Buyer decision cycles for autonomous platforms are compressing from multi-year evaluation to single-season procurement as agribusiness companies consolidate purchasing power through fleet-scale deployments. Equipment financing channels are displacing traditional dealer relationships in North American row-crop belts, with credit decisions increasingly tied to demonstrated per-acre labor savings rather than brand loyalty or trade-in value. This shift is most visible in Midwest corn-soy operations where 500+ unit fleet commitments now dominate manufacturer order books.
Agriculture Robotics Market Segmentation
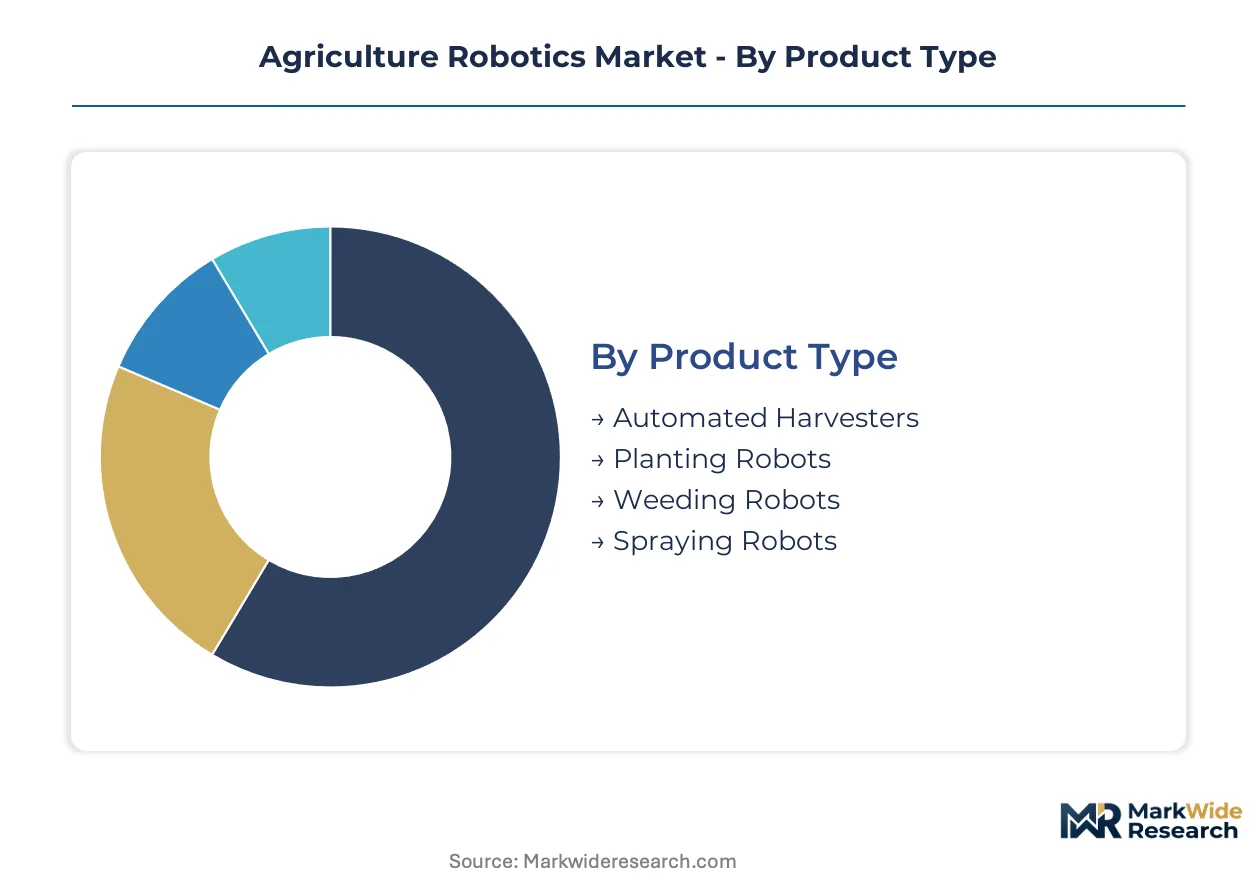
Agriculture robotics segmentation reveals distinct commercial zones where hardware-software integration depth varies sharply. Equipment manufacturers calibrate platform architectures differently across product categories, technology stacks, and buyer sophistication levels.
Product Type:
Volume deployments concentrate in broad-acre automation, while premium pricing attaches to specialty-crop precision systems.
- Automated Harvesters:Robotic platforms integrate articulated arms with gripper mechanisms for delicate fruit and vegetable retrieval without bruising. Strawberry producers in California and apple orchards in Washington deploy these systems where seasonal labor availability collapses during peak ripening windows.
- Weeding Robots:Vision-guided mechanical cultivators eliminate herbicide dependency through millimeter-accurate intrarow cultivation. Dutch greenhouse operations and French vineyard cooperatives drive demand as EU Green Deal emissions mandates tighten chemical-input allowances.
- Planting Robots:Autonomous seeders and transplanters achieve sub-centimeter GPS accuracy for uniform crop establishment.
- Spraying Robots:Precision nozzle arrays adjust droplet size and application rate based on real-time canopy sensing.
Mature deployment sits with automated harvesters. Newer deployment is concentrated in weeding robots.
Technology:
Cost tiers separate foundational positioning systems from premium perception layers that command higher per-unit pricing.
- Machine Learning:Embedded neural inference engines process environmental data onboard without cloud dependency. Rice transplanting operations in Japan and dairy barn automation across the Netherlands leverage these capabilities for real-time decision-making in connectivity-constrained rural environments.
- Computer Vision:Multispectral and RGB camera arrays enable ripeness assessment, disease detection, and obstacle identification. California specialty-crop growers deploy these systems for selective harvesting where human labor quality has deteriorated.
- GPS Navigation:RTK-corrected positioning delivers sub-centimeter accuracy for repeated field passes without drift accumulation.
- Sensor Technology:Lidar, radar, and hyperspectral modules fuse into environmental perception stacks.
Established integration sits with GPS navigation. Accelerating integration is concentrated in machine learning.
End User:
Buyer sophistication and fleet scale create divergent procurement patterns across customer categories.
- Agribusiness Companies:Large-scale operators consolidate purchasing power through 500-plus unit fleet commitments. Midwest corn-soy operations in the United States negotiate direct manufacturer relationships with financing tied to demonstrated per-acre labor savings.
- Farmers:Fragmented individual producers rely on dealer networks and cooperative purchasing arrangements. Japanese rice farming cooperatives aggregate demand for robotic transplanting equipment to achieve volume pricing.
- Research Institutes:University and government experimental stations validate platform performance under controlled conditions.
- Cooperative Societies:Pooled ownership models spread capital costs across member growers.
Consolidated procurement sits with agribusiness companies. Distributed procurement is concentrated in farmers.
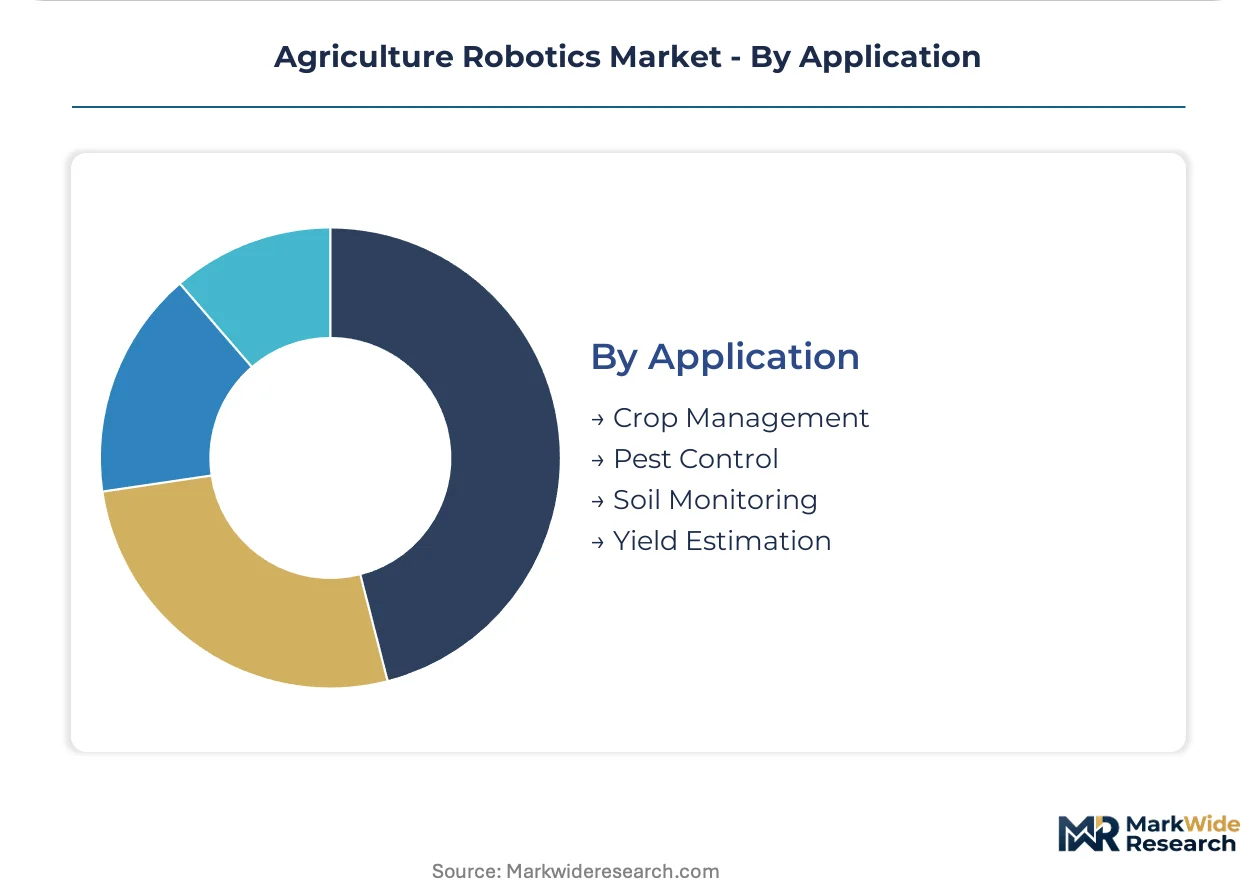
Application:
Margin structures favor predictive analytics over reactive intervention across use-case categories.
- Crop Management:Integrated platforms execute seeding, cultivation, and monitoring through unified control architectures. North American row-crop belts deploy these systems for continuous field operations that compress growing-season timelines.
- Yield Estimation:Multispectral imaging and machine learning models forecast harvest volume weeks before physical collection. French grain cooperatives and Australian wheat operations use these predictions for forward-contracting and logistics planning.
- Pest Control:Autonomous scouting and targeted intervention reduce pesticide application frequency.
- Soil Monitoring:Subsurface sensors and electromagnetic mapping characterize fertility and moisture profiles.
Operational deployment sits with crop management. Emerging deployment is concentrated in yield estimation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan concentrates the most visible demand pull for agriculture robotics, where aging farm demographics accelerate robotic milking and transplanting adoption across dairy and rice operations.
United States
Midwest corn-soy belts deploy 500-plus unit autonomous tractor fleets as agribusiness companies consolidate procurement power through direct manufacturer financing. EPA chemical-application rules constrain autonomous nozzle configurations in California specialty-crop zones. Central Valley strawberry producers validate vision-guided harvesting platforms with regional grower cooperatives for residue-threshold documentation.
Netherlands
Dutch greenhouse operations and vineyard cooperatives drive demand for vision-guided mechanical weeding robots as EU Green Deal emissions mandates tighten chemical-input allowances. REACH substance restrictions redirect capital toward cultivators that eliminate herbicide dependency. Wageningen University clusters anchor validation partnerships between robotics developers and regional agricultural experimental stations.
Japan
Aging farmer demographics accelerate robotic milking and transplanting adoption in dairy and rice operations, creating pull-through demand for integrated barn-to-field platforms. METI standards govern safety certifications for autonomous agricultural machinery before commercial rollout. Hokkaido and Tohoku rice farming cooperatives aggregate demand for robotic transplanting equipment to achieve volume pricing.
Germany
Precision-ag software integration anchors autonomous tractor deployments across arable operations in Lower Saxony and Bavaria. EU Farm to Fork Strategy expands compliance burdens on chemical inputs and labor practices. KBA and federal agricultural research centers in Braunschweig validate collision-avoidance architectures for autonomous machinery certification.
China
Yangtze River Delta and Shandong Peninsula clusters scale autonomous ground vehicle production for domestic specialty-crop zones and export markets. GB standards and MIIT regulations shape sensor fusion requirements for agricultural autonomy platforms. Shenzhen and Hangzhou technology corridors concentrate lidar and hyperspectral camera module supply chains.
Agriculture Robotics Market Competitive Landscape
United States producers anchor the integrated-platform tier; European specialists hold the precision-implement segment; East Asian manufacturers concentrate component supply and aerial systems. The vendor base structures around three archetypes: full-stack autonomy providers, open-architecture platform builders, and component-specialist suppliers. Consolidation pressures intensify as equipment financing channels displace traditional dealer relationships. Strategic moves center on fleet-scale deployment partnerships and embedded compliance-logging capabilities.
Within the full-stack tier, Deere & Company and CNH Industrial exemplify integrated autonomy providers that control development pathways from sensor fusion to grain-tank logistics. AGCO Corporation occupies a position representing open-architecture competition that enables farmers to mix third-party robotic implements. These three anchors illustrate how hardware-software integration depth separates premium platform vendors from modular component suppliers.
| Leading Market Players |
|---|
| Deere & Company |
| AGCO Corporation |
| CNH Industrial |
| GEA Group |
| Lely |
| DJI |
| Trimble Inc. |
| Autonomous Solutions Inc. |
| YANMAR HOLDINGS CO., LTD |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of sensor fusion modules and precision-actuation hardware anchors supply positioning for full-stack autonomy providers while compressing procurement costs for fleet-scale buyers. This backward integration pattern concentrates pricing power among vertically integrated equipment manufacturers that control development pathways from component sourcing to field deployment, leaving modular platform builders exposed to lithium-ion cell volatility and East Asian lidar supply constraints.
Pricing Analysis
Volume deployments of GPS-guided tractors and broad-acre seeders command thin margins at scale, while specialty-crop harvesting platforms with embedded machine learning inference engines capture premium pricing tiers. Three-tier pricing structure across premium vision-guided systems, standard GPS-automated equipment, and economy retrofit kits differentiates offerings, with ISO 18497 certification grade and fleet-scale volume serving as primary price discrimination levers. Cost compression in electric autonomous platforms is intensifying because lithium-ion battery price fluctuations directly erode manufacturer margins. Individual farmers in fragmented procurement arrangements demonstrate highest price sensitivity, whereas agribusiness companies with 500-plus unit commitments negotiate financing tied to demonstrated per-acre labor savings rather than sticker price.
Supply Chain Analysis
Workforce availability constraints in Shenzhen and Hangzhou technology corridors are compressing production timelines for lidar and hyperspectral camera modules that feed into autonomous perception stacks. Component manufacturing concentrates in China, South Korea, and Japan, with raw material dependencies spanning lithium carbonate for battery cells, rare earth elements for precision motors, and high-purity silicon for inference chips. Single-source vulnerability around East Asian foundry capacity exposes fleet-scale deployments to disruption. Distribution runs through direct manufacturer financing channels that displace traditional dealer networks in North American row-crop belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over sensor fusion hardware and precision-ag software stacks determines pricing power and fleet-scale contract capture. Players are pursuing downstream service revenue through embedded compliance logging and per-acre performance guarantees.
For Market Incumbents: Acquire computer vision and machine learning specialist teams to close perception-stack gaps before open-architecture platforms commoditize hardware layers. Defensive consolidation requires locking exclusive sensor supply agreements with Shenzhen and Hangzhou component foundries to neutralize single-source vulnerability. Capacity addition in Midwest corn-sooy manufacturing corridors anchors fleet-scale fulfillment timelines against emerging East Asian competitors.
For New Entrants and Emerging Players: Dealer networks in fragmented farmer segments represent the most accessible channel partner type for bypassing incumbent direct-financing relationships. White-space targets concentrate in California lettuce and vine operations below five percent robotic harvesting penetration, plus EU Farm to Fork compliance documentation services adjacent to core hardware sales. Equipment-as-a-service subscription models with residue-threshold logging capabilities offer the most penetrable go-to-market angle against capital-intensive ownership structures.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by full-stack autonomy providers seeking to compress hardware-software integration timelines. Long-term viability favors vertically integrated platform vendors with captive sensor supply and embedded compliance capabilities over modular component suppliers exposed to pricing erosion. Acquisition target archetype: mid-scale vision-guided implement specialists with validated ISO 18497 certification and established grower cooperative partnerships. Watch for inflection in 5G-edge deployment timelines signaling swarm coordination capability maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Fusion Hardware Acquisition | Captive lidar and hyperspectral supply insulates against East Asian foundry concentration risk. |
| Embedded Compliance Logging Development | FDA residue documentation and EU Farm to Fork tracking create adjacent recurring revenue streams. |
| Fleet-Scale Financing Partnership | Direct manufacturer credit decisions tied to per-acre labor savings displace traditional dealer relationships. |
| 5G-Edge Swarm Coordination Platform | Low-latency multi-unit control without cloud dependency unlocks large-field operational economics. |
| Mechanical Weeding Robot Scale-Up | REACH substance restrictions and EPA nozzle constraints redirect capital from chemical spraying systems. |
Research Methodology
Independent corroboration across equipment manufacturer product roadmaps, grower cooperative procurement records, and regulatory filing databases underwrites the qualitative findings in this study. Primary interviews with precision-ag software engineers, fleet operations managers at agribusiness companies, component procurement leads at autonomy platform builders, and compliance officers at specialty-crop cooperatives combined with secondary validation against SEC 10-K disclosures, EPA chemical-application rulemakings, EU Green Deal implementation documents, and METI safety certification records. Bottom-up unit deployment estimates and top-down addressable market sizing triangulate to anchor segment-level projections.
Rate-of-change decomposition across technology adoption curves, regulatory compliance timelines, and fleet replacement cycles structures the analytical framework over the projection horizon. Segmentation dimensions modeled include product type, technology stack depth, end-user procurement scale, and application use case, with regional regulatory cluster serving as an additional agriculture-specific dimension. CAGRs derive from fitted adoption curves calibrated against historical precision-ag equipment penetration patterns and forward-looking grower cooperative investment intentions. Industry-specific forecast inputs incorporate lithium-ion battery cost trajectory assumptions and ISO 18497 certification pipeline visibility.
Several conditions sit outside the modeled scope, including abrupt trade policy shifts affecting East Asian component flows, breakthrough battery chemistry displacing lithium-ion cost structures, and force majeure disruptions to seasonal labor availability that could accelerate or retard autonomous adoption independently of modeled drivers. Forecasts reflect assumptions around regulatory stability and technology maturation timelines without guaranteeing their realization. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Robotics and Automation
Cognitive Robotic Process Automation Market
Robotics and Automation
SCARA Robots Market
Robotics and Automation
Security and Law Enforcement Robot Market
Robotics and Automation
Vision Guided Robotics Market
Robotics and Automation
Europe Cloud Robotics Market
Robotics and Automation
Social Robots Market
Robotics and Automation
Thailand Cloud Robotics Market
Robotics and Automation
Non-Medical Biomimetic Robots Market
Robotics and Automation
Autonomous Drilling Robots Market
Robotics and Automation
Hospital Logistics Robots Market
Robotics and Automation
Europe Underwater Robotics Market
Robotics and Automation
Autonomous Robot Market
Robotics and Automation
Rehabilitation Robot Gloves Market
Robotics and Automation
Virtual 3D Nanorobots Market
Robotics and Automation
South America AUV and ROV Market
Robotics and Automation
Robot Coffee Kiosk Market