
 Heat Stress Meter Market | 2026-2036
Heat Stress Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Heat Stress Meter Market Foresight
Asset-light leasing models for environmental monitoring equipment is narrowing the competitive field to firms with strong balance sheets and service networks. TSI Incorporated leverages its captive calibration infrastructure to sustain recurring revenue streams across industrial accounts. Nielsen-Kellerman anchors its position in sports and military segments through specialized wet-bulb globe temperature sensors. PCE Instruments competes on price-accessible digital display units for small-to-mid-sized facility operators.
A heat stress meter measures environmental parameters including wet-bulb temperature, dry-bulb temperature, and globe temperature to calculate heat stress indices such as WBGT. These instruments incorporate thermistor or thermocouple sensor arrays with response times under 30 seconds, serving occupational health officers and athletic trainers who must enforce work-rest cycles or competition suspensions. Portable meters dominate current procurement volumes due to flexibility across construction sites and training grounds, while IoT-enabled wireless sensors represent the fastest-expanding technology tier as facilities pursue real-time dashboard integration. Cloud-based deployment architectures capture disproportionate margin pools through subscription telemetry services layered over hardware sales.
OSHA heat illness prevention initiatives in the United States, the EU's Physical Agents Directive framework, and Australia's Safe Work Australia heat guidelines collectively elevate product certification requirements and compliance documentation burdens. Manufacturers must navigate divergent accuracy tolerances and calibration protocols to maintain market access across jurisdictions. Stakeholders should monitor evolving enforcement thresholds in high-temperature economies where regulatory lag creates both compliance risk and first-mover positioning for certified suppliers.
Market Dynamics
Wearable IoT sensor networks are compressing replacement cycles for standalone meters as industrial buyers prioritize real-time dashboard integration over point-in-time measurements.
Growth Catalysts
- OSHA Heat Illness Prevention Rulemaking:Proposed federal workplace heat standards in the United States mandate continuous environmental monitoring for indoor and outdoor employers above threshold temperatures.
- Mining Automation:Australian underground and surface operations deploy connected WBGT arrays to automate work-rest rotations and reduce heat-related stoppages.
- Edge Computing Architectures:On-device processing capabilities eliminate latency for critical safety decisions at construction sites and athletic venues.
Market Restraints
- Thermistor Supply Concentration:Precision temperature sensor fabrication concentrates among East Asian foundries, exposing meter manufacturers to input volatility and extended lead times.
- Calibration Infrastructure Gaps:Accredited wet-bulb globe temperature calibration facilities remain sparse outside industrialized economies, limiting certified product deployment in emerging markets.
- Smartphone Sensor Substitution:Consumer-grade environmental applications on iOS and Android devices capture price-sensitive recreational users, compressing the entry-level instrument segment.
Strategic Opportunities
- EU Physical Agents Directive Enforcement:Member state adoption of mandatory heat exposure assessments creates compliance-driven replacement demand across manufacturing and logistics facilities.
- Subscription Telemetry Services:Cloud-based data logging and predictive analytics packages layered over hardware sales capture recurring revenue from enterprise safety departments.
- Sports Federation Certification:FIFA, World Athletics, and national Olympic committees specify WBGT thresholds for competition suspension, institutionalizing instrument procurement for event organizers.
Industry Challenges
- Cross-Jurisdictional Calibration Protocols:Divergent accuracy tolerances between OSHA, Safe Work Australia, and EU-OSHA frameworks force manufacturers to maintain multiple product variants or modular certification modules.
- Legacy System Integration:Industrial facilities with entrenched SCADA architectures require custom API development and protocol translation to incorporate wireless heat stress sensors into existing safety management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heat Stress Meter Market |
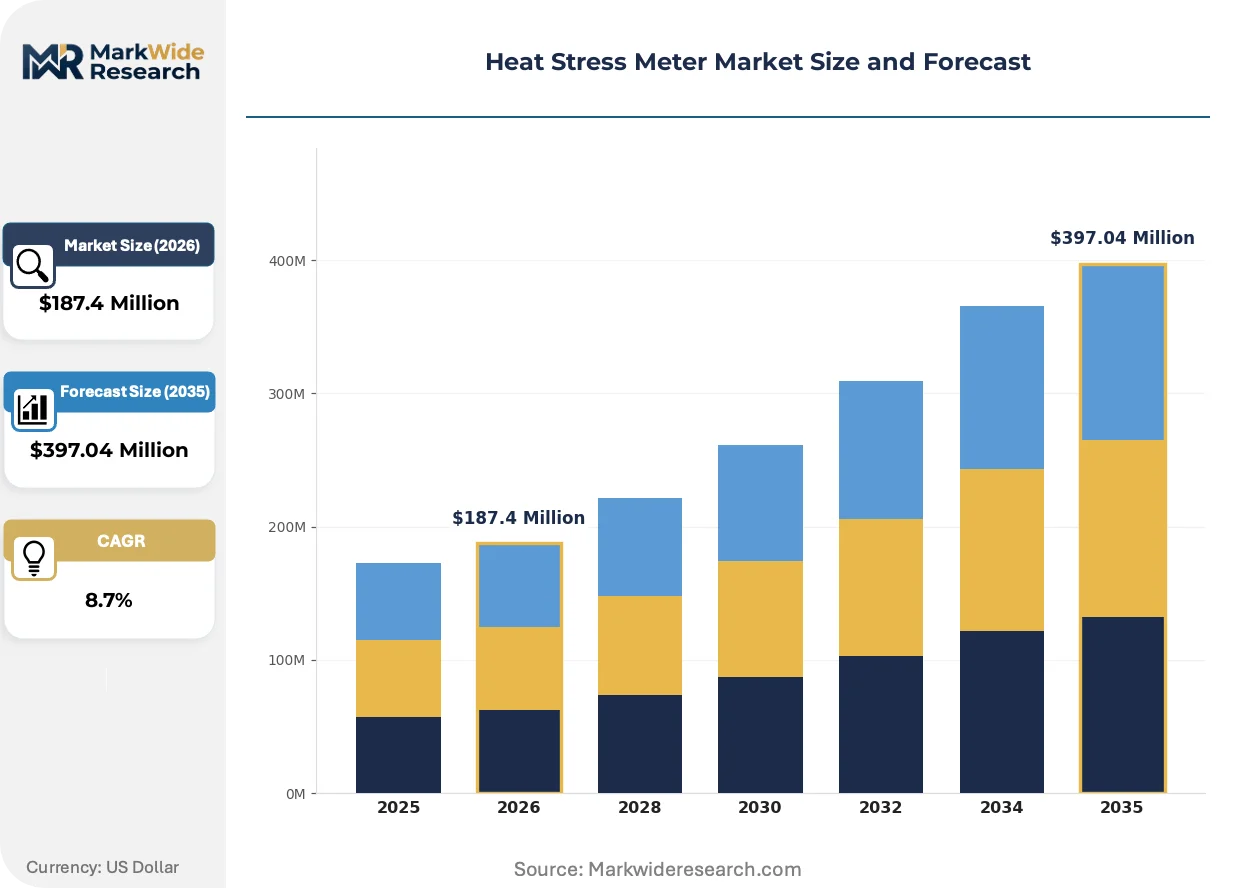
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Wireless Sensors, Fixed Installations, Data Loggers Deployment: Cloud-Based, On-Premises, Hybrid Solutions, Mobile Platforms End User: Agriculture, Sports Organizations, Industrial Facilities, Research Institutions Technology: IoT-Enabled, Analog Systems, Digital Display, Remote Monitoring |
| Companies Covered | TSI Incorporated, Nielsen-Kellerman, Teledyne FLIR, Extech Instruments, Sper Scientific, REED Instruments, PCE Instruments, Romteck, BESANTEK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heat Stress Meter Market Shifts & Advancements
Sensor miniaturization and edge AI processing are collapsing the distinction between portable meters and fixed monitoring networks, enabling fluid deployment models across construction, sports, and industrial verticals.
Multi-parameter environmental sensors is virtualizing the standalone heat stress meter category. These compact modules integrate WBGT calculation with particulate, gas, and noise monitoring. Mining operators in Western Australia and construction consortia in the United Arab Emirates deploy them at scale. The technology is virtualizing hardware boundaries by collapsing multiple instrument categories into single wearable or fixed nodes, compressing vendor count and service contract complexity.
Safe Work Australia's heat stress guidelines revision tightens measurement frequency requirements for outdoor workers. The updated framework mandates 15-minute interval logging during amber and red heat alert periods. Heavy industry employers in Queensland and Western Australia face stepped compliance documentation burdens. Mining contractors respond by procuring IoT-enabled continuous monitoring systems with automated alert escalation to site safety officers.
Leasing arrangements for environmental monitoring equipment are displacing capital purchase patterns among mid-sized facility operators. Construction project managers and event organizers favor operational expenditure structures that bundle hardware, calibration, and data analytics. This preference is most pronounced in Australia's resources sector and North American infrastructure projects where contract duration uncertainty discourages asset ownership.
Heat Stress Meter Market Segmentation
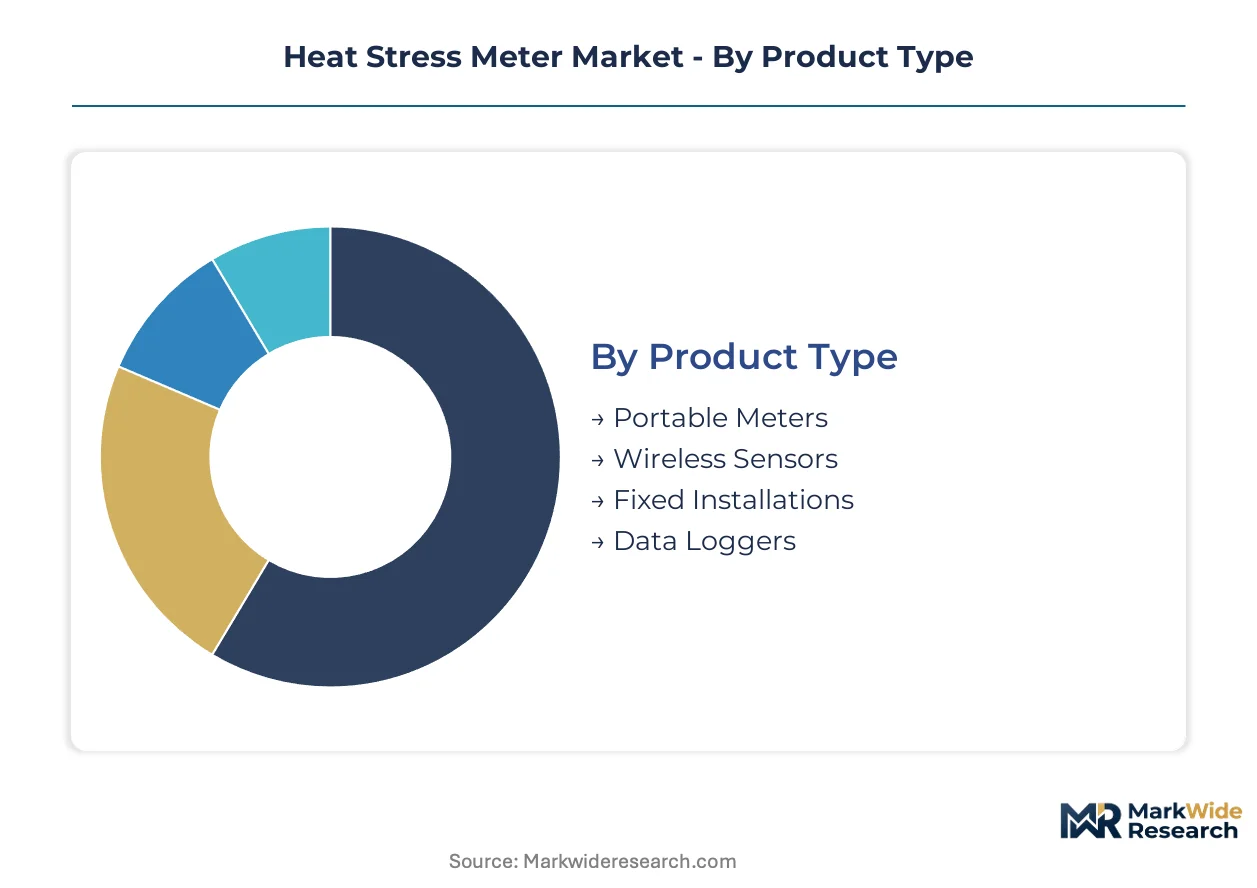
Heat stress meter procurement patterns diverge sharply across product architectures and operational contexts. Deployment choices reflect facility infrastructure maturity, while end-user segments impose distinct accuracy and connectivity requirements.
Product Type:
Mature portable instruments coexist with emerging wireless architectures, creating a bifurcated procurement landscape.
- Portable Meters:Handheld units integrate wet-bulb, dry-bulb, and globe temperature sensors with sub-30-second response times. Construction contractors and athletic trainers in Australia prioritize these for site flexibility and immediate WBGT readings without infrastructure dependency.
- Wireless Sensors:Battery-powered nodes transmit environmental data via LoRaWAN or cellular protocols to centralized dashboards. Mining operators in Western Australia deploy these in connected arrays to automate work-rest rotations and eliminate manual logging burdens.
- Fixed Installations:Permanent sensor networks serve industrial facilities with continuous monitoring mandates under OSHA heat illness prevention frameworks.
- Data Loggers:Standalone recording devices capture interval-based measurements for compliance documentation in research and regulatory audit contexts.
Portable meters retain volume leadership; wireless sensors hold the steepest expansion curve.
Deployment:
Cost tier stratification separates enterprise-grade cloud architectures from budget-constrained on-premises alternatives.
- Cloud-Based:Subscription telemetry services aggregate sensor feeds into predictive analytics platforms with automated alert escalation. Enterprise safety departments in the United States favor these for multi-site visibility and reduced IT overhead.
- On-Premises:Local server installations maintain data sovereignty for defense contractors and critical infrastructure operators with air-gapped security requirements.
- Hybrid Solutions:Edge processing with selective cloud synchronization balances latency-sensitive decisions against centralized reporting needs.
- Mobile Platforms:Smartphone-tethered applications serve recreational users and small contractors with intermittent monitoring requirements.
Cloud-based deployment captures margin concentration; hybrid solutions are expanding most quickly among mid-sized facility operators.
End User:
Application context drives specification divergence from agricultural fieldwork to elite athletic competition.
- Industrial Facilities:Manufacturing and logistics employers face tightening OSHA compliance thresholds for indoor and outdoor heat exposure. Continuous monitoring systems with automated work-rest alerts dominate procurement in foundries, warehouses, and construction sites.
- Sports Organizations:FIFA, World Athletics, and national Olympic committees mandate WBGT thresholds for competition suspension. Event organizers procure certified instruments with federation-recognized calibration protocols.
- Agriculture:Orchard operators and livestock producers deploy basic digital units for seasonal worker protection in high-temperature harvesting periods.
- Research Institutions:Academic and government laboratories require traceable calibration chains for peer-reviewed environmental physiology studies.
Industrial facilities command procurement volume; sports organizations drive premium-tier specification adoption.
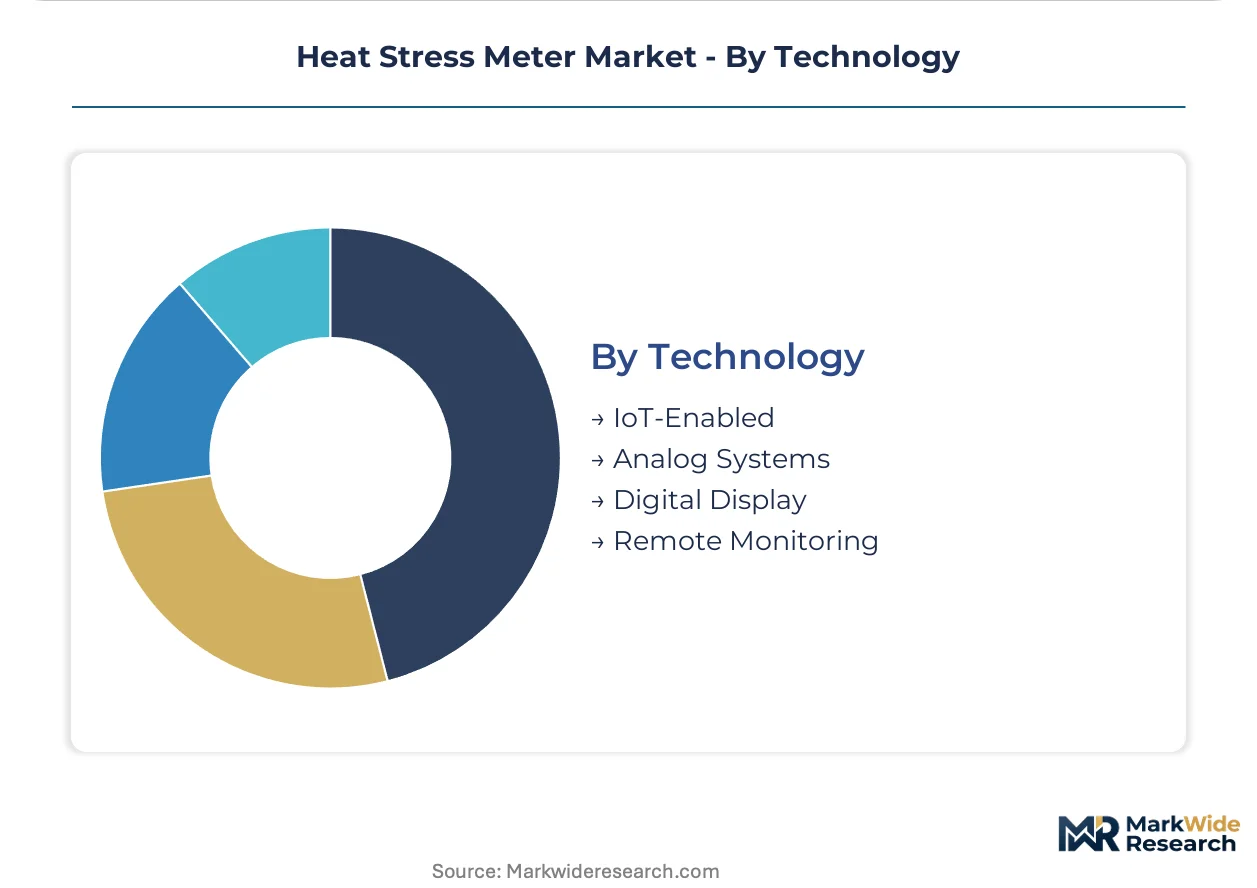
Technology:
Customer type separates connected system buyers from legacy equipment maintainers.
- IoT-Enabled:Networked sensors with edge AI processing enable real-time decision automation. Mining automation initiatives in Australia and construction safety programs in the United Arab Emirates deploy these at scale for predictive heat stress intervention.
- Digital Display:Microprocessor-based units with LCD readouts serve small-to-mid-sized facility operators seeking OSHA compliance without connectivity complexity.
- Remote Monitoring:Satellite or cellular-linked systems extend coverage to offshore platforms, remote pipeline corridors, and isolated agricultural operations.
- Analog Systems:Mechanical wet-bulb and sling psychrometer configurations persist in budget-constrained educational and developing economy contexts.
IoT-enabled technology leads replacement demand; remote monitoring gains share fastest in resource extraction verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of precision temperature sensors concentrate in East Asian manufacturing clusters, while import demand for certified heat stress instrumentation clusters in mining-intensive and regulatory-advanced economies. Trade balances reflect divergent calibration infrastructure maturity and occupational safety enforcement intensity.
United States
OSHA's advancing heat illness prevention rulemaking drives procurement of continuous monitoring systems across construction and logistics sectors. The proposed federal workplace heat standards mandate environmental monitoring above threshold temperatures for indoor and outdoor employers. Industrial safety departments in Houston and Phoenix deploy cloud-integrated sensor networks to automate compliance documentation.
Australia
Mining automation initiatives in Western Australia and Queensland sustain replacement cycles for connected WBGT arrays. Safe Work Australia's revised heat stress guidelines impose 15-minute interval logging mandates during amber and red alert periods. Resource extraction contractors in the Pilbara region procure IoT-enabled systems with automated alert escalation to site safety officers.
Germany
EU Physical Agents Directive enforcement creates compliance-driven replacement demand across manufacturing facilities. Member state adoption of mandatory heat exposure assessments elevates product certification requirements for industrial employers. Precision engineering clusters in Bavaria and Baden-Württemberg integrate heat monitoring into existing SCADA safety architectures.
United Arab Emirates
Construction consortia and event organizers deploy multi-parameter environmental sensors for worker protection and competition safety. Extreme ambient temperatures accelerate instrument degradation and shorten replacement cycles. Dubai-based infrastructure developers favor operational expenditure leasing models that bundle hardware, calibration, and analytics services.
Japan
METI industrial safety guidelines and aging workforce demographics elevate precision monitoring requirements in manufacturing. Summer heat countermeasures in automotive and electronics factories drive adoption of edge-computing sensor networks. Industrial clusters in Aichi Prefecture and the Kanto region integrate predictive heat stress intervention into lean production systems.
Heat Stress Meter Market Competitive Landscape
On the supply side, the industry is bifurcated between precision instrumentation specialists and diversified environmental sensor conglomerates. Consolidation pressures favor firms with captive calibration infrastructure and recurring service revenue streams. Two strategic archetypes dominate: integrated solution providers bundling hardware with telemetry subscriptions, and component-focused specialists competing on measurement accuracy and response speed. Competitive moves concentrate on geographic certification expansion and cloud platform integration partnerships.
Among North American instrumentation specialists, TSI Incorporated and Nielsen-Kellerman occupy distinct positioning tiers. TSI represents the integrated solutions archetype through its calibration infrastructure and service network depth. Nielsen-Kellerman exemplifies specialization in federation-certified sports and military segments. German-based PCE Instruments competes on price-accessible digital display units for mid-sized facility operators. These three firms anchor the competitive structure without exhausting its diversity.
| Leading Market Players |
|---|
| TSI Incorporated |
| Nielsen-Kellerman |
| Teledyne FLIR |
| Extech Instruments |
| Sper Scientific |
| REED Instruments |
| PCE Instruments |
| Romteck |
| BESANTEK |
| Others |
Supply & Pricing Matrix
Guangdong Province's thermistor foundry capacity determines downstream pricing power for precision temperature sensor procurement. Meter manufacturers face margin compression when East Asian fabrication runs at capacity, while Australian mining contractors absorb premium pricing for expedited delivery during replacement cycles.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification grade under OSHA heat illness prevention frameworks and subscription telemetry bundling separate premium IoT-enabled systems from basic digital display units. Cost compression in the economy tier is intensifying because smartphone sensor substitution captures recreational users. Small-to-mid-sized facility operators exhibit highest price sensitivity; enterprise safety departments with multi-site mandates show lowest.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for thermistor-dependent manufacturers. Precision temperature sensor fabrication concentrates in China, South Korea, and Japan; wet-bulb globe temperature calibration equipment sources primarily from Germany and the United States. Component dependencies include thermistor arrays, lithium-ion power cells, and LoRaWAN communication modules. Distribution runs through industrial instrumentation distributors with captive service networks in mining and construction verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat stress meter procurement is shifting toward service-attach models where calibration subscriptions and predictive analytics layers expand faster than hardware unit sales. Telemetry revenue streams now exceed instrument margins for leading integrated solution providers.
For Market Incumbents: Pre-empt smartphone sensor substitution by embedding edge AI processing that consumer devices cannot replicate. Deepen captive calibration infrastructure in Australia and the United States to lock in multi-year service contracts. Vertical integration into thermistor sourcing hedges East Asian foundry concentration risk.
For New Entrants and Emerging Players: Build out white-space positions in EU Physical Agents Directive compliance services for mid-sized German manufacturing facilities. Agricultural orchard operations in high-temperature harvesting regions represent the most penetrable segment. Lead with price-accessible digital display units bundled with seasonal calibration packages.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because regulatory mandates institutionalize replacement cycles and telemetry subscriptions. Target firms with accredited WBGT calibration facilities and established service networks. Monitor OSHA heat illness prevention rulemaking finalization as the primary demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | Captive service networks in Australia and the United States lock in multi-year enterprise contracts. |
| Edge AI Processing Integration | On-device computation differentiates premium instruments from smartphone sensor substitution. |
| Subscription Telemetry Services | Cloud-based analytics packages transform transactional hardware sales into recurring revenue streams. |
| EU Certification Pathway Investment | CE marking and Physical Agents Directive compliance open compliance-driven replacement demand in Germany. |
| Sports Federation Partnership | FIFA and World Athletics WBGT thresholds institutionalize procurement for event organizers. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with occupational health officers, mining safety directors, athletic trainers, industrial procurement managers, and calibration service technicians; and secondary validation against OSHA regulatory filings, Safe Work Australia guideline documents, EU-OSHA Physical Agents Directive frameworks, and industrial instrumentation trade records. Bottom-up unit economics triangulated against top-down market sizing.
Forecast inputs span product architecture, deployment model, end-user vertical, and technology tier across the projection horizon. CAGRs derive from segment-level growth rate reconciliation with macroeconomic indicators and regulatory enforcement intensity. Mining automation adoption curves and sports federation certification mandates serve as industry-specific demand drivers.
Stress conditions across thermistor supply availability, OSHA rulemaking timing, and Australian mining capital expenditure cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Conveyor Monitoring Market
Sensors
Traffic Sensor Market
Sensors
Ultrasonic Technologies Market
Sensors
Europe Remote Sensing Technology Market
Sensors
Vibration Monitoring Market
Sensors
RFID Smart Cabinet Market
Sensors
Wireless RFID Readers Market
Sensors
Industrial Automation Sensors Market
Sensors
Smart Mat Market
Sensors
Fixed RFID Readers Market
Sensors
Global Location-Based Services (LBS) and Real-Time Location Systems (RTLS) Market
Sensors
Underground Service Locator Market
Sensors
Drain Camera Market
Sensors
Temperature Data Loggers Market
Sensors
Global Equipment Monitoring Market
Sensors
Global RFID Market