
 Asset Tags Market | 2026-2036
Asset Tags Market Size, Share, and Industry Trends Forecast 2026-2036
Asset Tags Market Outlook
Aftermarket tag data services is rewriting profit allocation across the value chain. Brady Corporation leverages its specialty identification portfolio to anchor premium industrial accounts. Zebra Technologies dominates enterprise mobility and automated data capture with integrated hardware-software stacks. Avery Dennison Corporation sustains material science leadership through advanced adhesive and substrate R&D programs.
Asset tags are durable identification labels affixed to physical property, typically constructed from anodized aluminum, polyester substrates, or tamper-evident polymers with serialized encoding and pressure-sensitive or mechanical fastening systems. Their primary function is to enable automated tracking, authentication, and lifecycle documentation across equipment fleets and inventory systems. RFID technology commands the highest value pool where real-time location systems justify premium hardware and software subscriptions. Metal substrates lead in heavy industrial settings where abrasion, chemical exposure, and thermal cycling degrade plastic alternatives. Plastic and paper formats occupy high-volume, lower-unit-cost segments in retail inventory and short-cycle logistics applications.
FDA Unique Device Identification requirements mandate machine-readable labels on medical devices, directly expanding healthcare demand for durable, scannable asset tags. EPA hazardous material handling standards and OSHA workplace safety regulations enforce equipment identification protocols in manufacturing and chemical processing facilities. Stakeholders must monitor evolving serialization mandates across pharmaceutical and food supply chains as regulators tighten traceability expectations without specifying implementation timelines.
Market Dynamics
Real-time location systems are compressing replacement cycles as hospitals and manufacturers abandon passive barcode inventories for active RFID tracking infrastructure. This hardware refresh dynamic concentrates procurement power among integrators capable of bundling sensors, software, and cloud analytics into multi-year service agreements.
Growth Catalysts
- FDA Unique Device Identification:Machine-readable label mandates on medical devices force hospital systems to retag equipment fleets, creating durable demand for tamper-evident polymer substrates with serialized encoding.
- EU MDR traceability requirements:Medical device regulation mandates end-to-end lifecycle documentation, pushing European manufacturers toward RFID-enabled tags with encrypted authentication layers.
- Automotive EV battery tracking:Cell-to-pack serialization for warranty and recycling compliance drives high-temperature resistant metal tag adoption across battery assembly plants in Germany and China.
Market Restraints
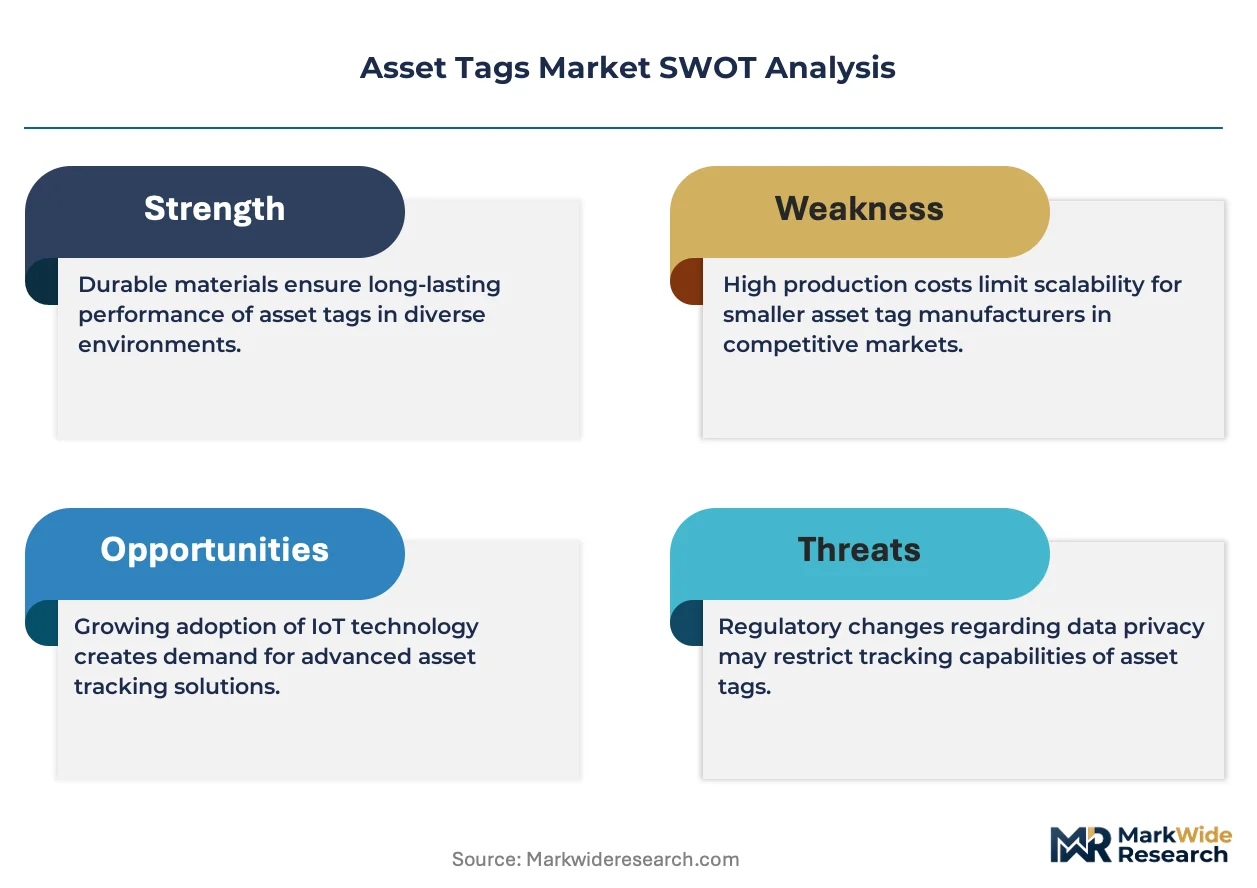
- Aluminum substrate cost volatility:Anodized aluminum prices fluctuate with energy-intensive smelting economics, squeezing margin on industrial-grade asset tags specified for chemical and thermal resistance.
- RFID chip supply concentration:Semiconductor fabrication for UHF inlays clusters in Taiwan and South Korea, exposing tag assemblers to geographic concentration risk during logistics disruptions.
- Passive tag read-range limitations:Metal and liquid environments degrade inductive coupling performance, restricting barcode-to-RFID migration in heavy manufacturing and cold-chain logistics.
Strategic Opportunities
- India pharmaceutical serialization:DGFT track-and-trace mandates for active pharmaceutical ingredients create first-mover advantage for tag suppliers establishing local converting partnerships.
- 5G-enabled industrial IoT convergence:Integration of cellular low-power wide-area networks with passive RFID bridges real-time visibility gaps in sprawling warehouse and yard management applications.
- California battery passport regulations:Circular economy disclosure requirements for lithium-ion batteries mandate durable physical identifiers linked to digital twin records, opening premium tag service contracts.
Industry Challenges
- RFID systems integration expertise:Hospital IT departments lack in-house capability to harmonize tag data with existing enterprise asset management platforms, slowing deployment velocity.
- Multi-standard certification timelines:ISO 18000-6C, GS1 EPC Gen2, and regional frequency allocations require sequential testing cycles that extend product launch schedules by quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asset Tags Market |
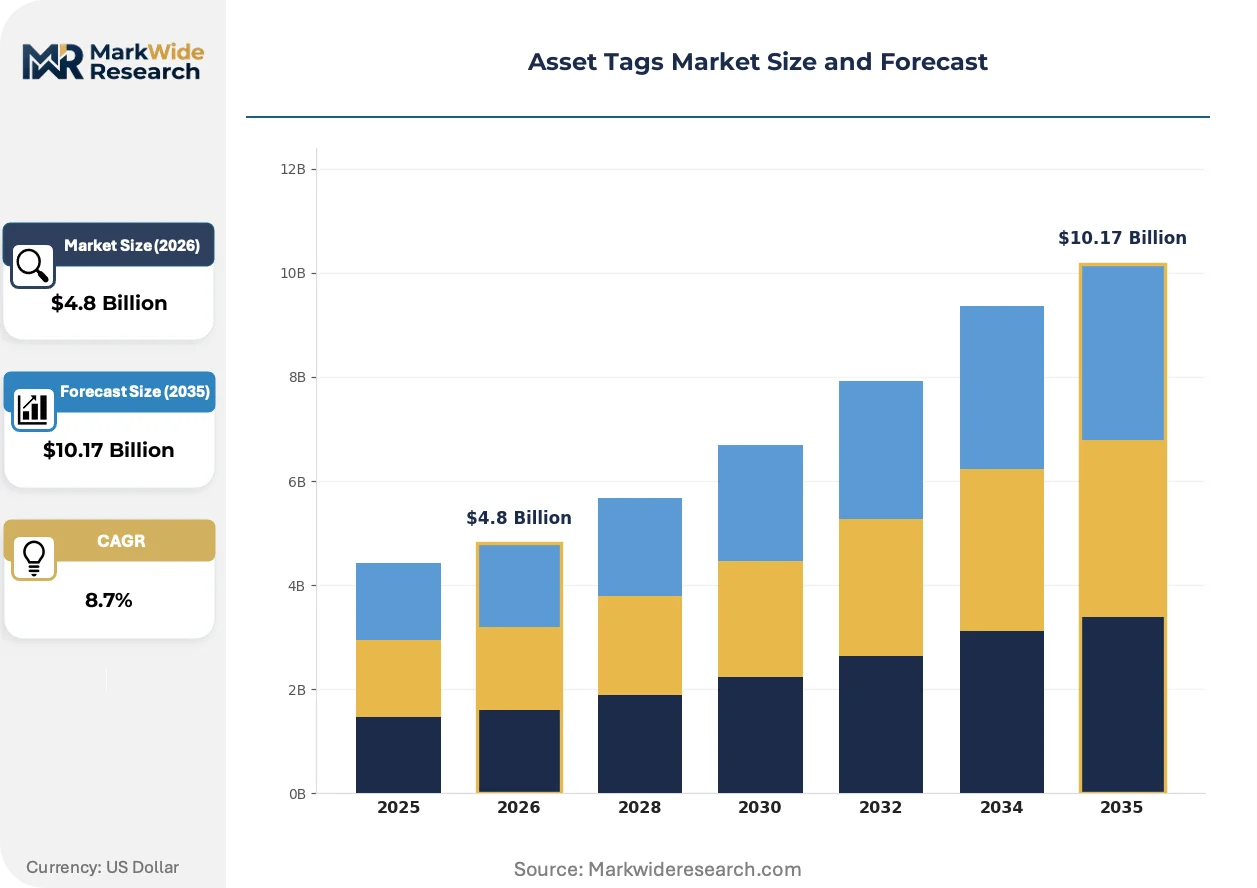
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: RFID, QR Code, Barcode, NFC Material: Plastic, Metal, Paper, Fabric End User: Healthcare, Manufacturing, Retail, Transportation Application: Inventory Management, Asset Tracking, Logistics, Equipment Maintenance |
| Companies Covered | Avery Dennison Corporation, Brady Corporation, Zebra Technologies, Metalcraft, Camcode, Seton, William Frick & Co, Honeywell International, Alien Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asset Tags Market Strategic Shifts
Tag intelligence is migrating toward edge-computing architectures where onboard sensors capture environmental conditions beyond simple identity. This capability expansion redefines hardware specifications and software subscription economics across industrial verticals.
Passive UHF RFID is migrating from inventory gatekeeping to item-level pharmaceutical authentication. European contract manufacturers are embedding tamper-responsive tags at unit dose, enabling anticounterfeiting verification through smartphone-readable NFC interfaces. This migration from pallet-scale to dose-scale tracking compresses tag unit costs while expanding total addressable volume.
REACH substance restrictions are tightening adhesive chemistry specifications for tags deployed in consumer goods and medical packaging. ECHA authorization requirements for certain phthalate plasticizers force reformulation of pressure-sensitive laminates used in wash-down and sterilization environments. German chemical processors and Italian packaging converters are accelerating validation of bio-based acrylic alternatives to maintain CE-marked product continuity.
Hospital procurement departments are consolidating vendor relationships around full-stack asset visibility contracts rather than commodity tag purchasing. Integrated hardware-software agreements displace piecemeal RFID inlay orders as health systems seek outcome guarantees on equipment utilization rates. This behavioral shift concentrates supplier selection authority among enterprise mobility platforms with proven hospital EHR integration in the United States and United Kingdom acute care networks.
Asset Tags Market Segmentation
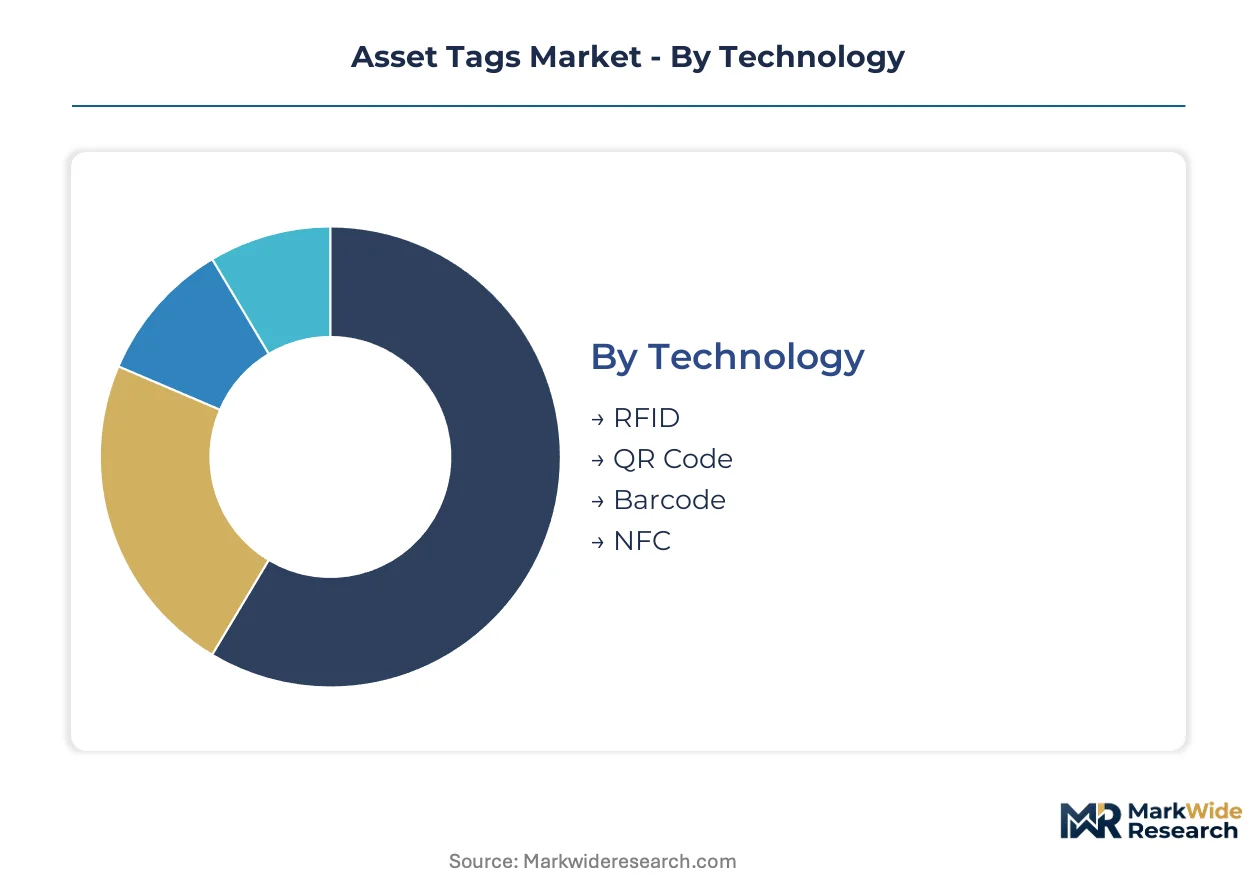
Asset tags serve divergent operational requirements across industrial, healthcare, and commercial environments. Technology selection determines hardware investment levels and data capture capabilities. Material substrates must match abrasion, thermal, and chemical exposure profiles specific to deployment settings.
Technology:
RFID dominates high-value tracking scenarios where line-of-sight scanning proves impractical.
- RFID:Passive UHF inlays and active battery-assisted tags enable real-time location systems in hospital equipment yards and automotive assembly plants. FDA medical device identification mandates in the United States and EU MDR traceability requirements in Germany are forcing hospital systems toward encrypted RAIN RFID implementations despite higher per-unit costs.
- QR Code:Two-dimensional matrix codes store substantially more data than linear alternatives while remaining readable through standard smartphone cameras. Manufacturing facilities in China deploy QR-based work-in-process tracking where cloud-connected mobile devices replace dedicated scanner hardware.
- Barcode:Linear symbologies persist in high-volume retail inventory and short-cycle logistics applications where infrastructure simplicity outweighs data density requirements. Legacy warehouse management systems across the United States continue specifying Code 128 and GS1-128 formats for backward compatibility.
- NFC:Near-field communication tags operating at 13.56 MHz enable tap-to-authenticate workflows for pharmaceutical anticounterfeiting and luxury goods provenance. European contract manufacturers embed NFC inlays at unit-dose level for smartphone-readable verification.
The dominant share belongs to Barcode, while RFID is closing the gap fastest.
Material:
Substrate selection directly determines field lifespan and replacement cycle economics.
- Metal:Anodized aluminum and stainless steel substrates withstand thermal cycling, chemical exposure, and mechanical abrasion in heavy industrial settings. Automotive battery assembly plants in Germany specify high-temperature resistant metal tags for cell-to-pack serialization under EV warranty tracking mandates.
- Plastic:Polyester and polycarbonate films with pressure-sensitive adhesives dominate healthcare equipment labeling where sterilization compatibility and tamper-evidence are required. FDA UDI rules mandate durable polymer substrates that survive hospital autoclave and disinfectant protocols.
- Paper:Uncoated and thermal transfer papers serve short-lifecycle logistics and retail inventory where unit cost minimization outweighs durability requirements. E-commerce fulfillment centers in China consume paper labels by the billion for outbound parcel identification.
- Fabric:Woven and printed textile tags attach to uniforms, linens, and reusable garments in hospitality and healthcare laundry operations. RFID-enabled fabric labels withstand industrial wash cycles while maintaining read performance.
Metal commands premium pricing in industrial verticals, though Plastic is expanding most quickly through healthcare compliance spending.
End User:
Vertical-specific regulations and operational models reshape procurement specifications.
- Healthcare:Hospital systems deploy integrated asset visibility platforms combining RFID hardware with enterprise asset management software. United Kingdom acute care networks are consolidating vendor relationships around full-stack outcome contracts rather than commodity tag purchasing.
- Manufacturing:Discrete and process manufacturers track work-in-process, tooling, and finished goods through automated data capture. OSHA workplace safety regulations in the United States enforce equipment identification protocols in chemical processing facilities.
- Retail:Omnichannel fulfillment operations require item-level inventory accuracy for buy-online-pickup-in-store and ship-from-store workflows. Cold-chain grocery logistics in Germany face barcode-to-RFID migration barriers where liquid and metal environments degrade inductive coupling.
- Transportation:Fleet operators and third-party logistics providers track trailers, containers, and returnable transport items across distributed networks. California battery passport regulations are mandating durable physical identifiers linked to digital twin records for lithium-ion freight equipment.
Healthcare generates the steepest expansion trajectory as regulatory mandates force infrastructure replacement cycles.
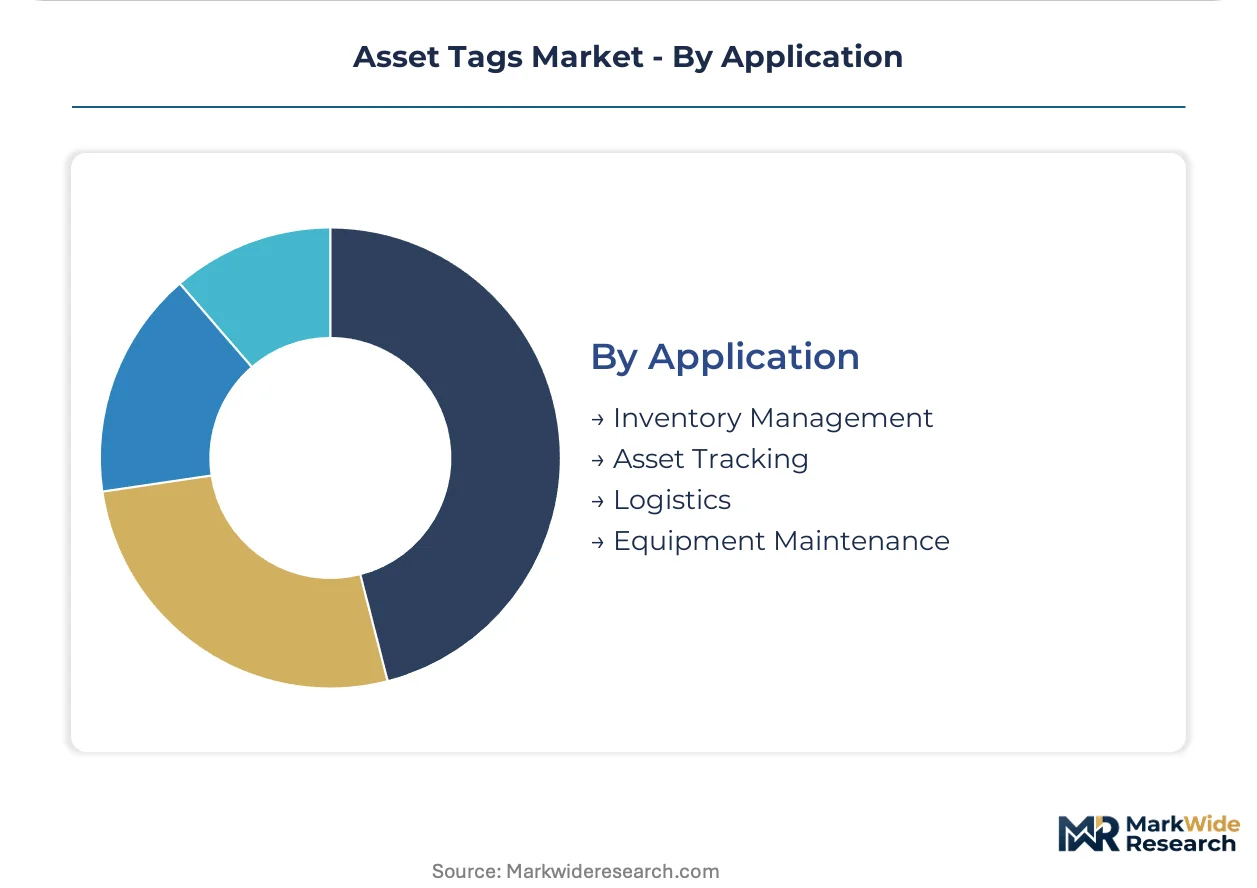
Application:
Functional use cases determine data structure, read frequency, and integration architecture requirements.
- Inventory Management:Cyclic counting and perpetual inventory systems rely on rapid bulk scanning capabilities. Retail distribution centers in China are bridging passive RFID with 5G-enabled industrial IoT for real-time yard visibility.
- Asset Tracking:Equipment location and utilization monitoring drives active RFID and real-time location system adoption. Hospital procurement departments seek outcome guarantees on equipment utilization rates from integrated platform vendors.
- Logistics:In-transit visibility and proof-of-delivery documentation require tags surviving environmental extremes. REACH substance restrictions are forcing adhesive reformulation for tags deployed in European consumer goods supply chains.
- Equipment Maintenance:Service history documentation and predictive maintenance scheduling link physical assets to computerized maintenance management systems. Indian pharmaceutical serialization mandates under DGFT track-and-trace rules are creating demand for maintenance-linked tag systems in active ingredient production.
Asset Tracking holds the dominant revenue position, while Equipment Maintenance is gaining share fastest through predictive service contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare systems in the United States deploy RFID infrastructure differently than German manufacturers, who favor metal substrates for industrial durability, while Chinese logistics operations prioritize high-volume paper and plastic formats for e-commerce scale.
United States
FDA Unique Device Identification mandates force hospital systems toward encrypted RAIN RFID implementations for medical device tracking. OSHA workplace safety regulations enforce equipment identification protocols across chemical processing facilities. Acute care networks in Texas and California consolidate vendor relationships around full-stack asset visibility contracts rather than commodity tag purchasing.
Germany
Automotive EV battery assembly plants drive demand for high-temperature resistant metal tags under cell-to-pack serialization requirements. EU MDR traceability mandates push medical device manufacturers toward RFID-enabled tags with encrypted authentication layers. Industrial clusters in Bavaria and Baden-Württemberg anchor precision manufacturing adoption of real-time location systems.
China
E-commerce fulfillment centers consume paper labels by the billion for outbound parcel identification in high-volume logistics. NMPA medical device traceability standards align with international serialization protocols for export compliance. Yangtze River Delta manufacturing hubs deploy QR-based work-in-process tracking where cloud-connected mobile devices replace dedicated scanner hardware.
India
DGFT track-and-trace mandates for active pharmaceutical ingredients create first-mover advantage for tag suppliers establishing local converting partnerships. CDSCO medical device regulations tighten identification requirements for imported equipment. Pharmaceutical manufacturing clusters in Maharashtra and Gujarat accelerate validation of maintenance-linked tag systems in active ingredient production facilities.
United Kingdom
NHS procurement departments consolidate around outcome-based asset visibility contracts with proven EHR integration capabilities. REACH substance restrictions force adhesive reformulation for tags deployed in consumer goods supply chains. London and Southeast acute care networks lead European adoption of integrated hardware-software agreements for equipment utilization guarantees.
Asset Tags Market Competitive Environment
Capability concentration sits with specialty identification portfolio holders; scale advantage sits with enterprise mobility platform operators. The market structures around three tiers: industrial-grade substrate specialists, integrated hardware-software stack providers, and high-volume converting operations. Two strategic archetypes dominate—material science leaders commanding premium industrial accounts, and automated data capture vendors bundling sensors with cloud analytics. Competitive moves concentrate on multi-year service agreement structures and hospital EHR integration partnerships.
Among North American identification specialists, Avery Dennison Corporation and Brady Corporation exemplify the material science leadership archetype, while Zebra Technologies anchors the integrated platform tier. These three occupy positions spanning substrate innovation through enterprise software deployment, representing the capability-to-scale spectrum that defines vendor selection authority in hospital and manufacturing procurement.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Brady Corporation |
| Zebra Technologies |
| Metalcraft |
| Camcode |
| Seton |
| William Frick & Co |
| Honeywell International |
| Alien Technology |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta converting clusters anchor global RFID inlay capacity, with their expansion dynamics directly translating into downstream pricing leverage for hospital systems and automotive OEMs negotiating multi-year tag supply agreements.
Pricing Analysis
Long-term offtake contracts dominate hospital and automotive procurement, with three-tier pricing structure across premium, standard, and economy levels separating encrypted RAIN RFID implementations from basic barcode alternatives. Price differentiation hinges on ISO 18000-6C certification tier and volume scale, with healthcare GPOs commanding steeper discounts than discrete manufacturers. Cost compression in standard-grade polymer substrates is intensifying because REACH adhesive reformulation expenses are squeezing converter margins. Retail logistics buyers exhibit highest price sensitivity, while FDA-mandated medical device tag purchasers accept premium positioning for compliance assurance.
Supply Chain Analysis
Extended payment terms from Taiwanese semiconductor foundries to UHF chip assemblers are restructuring working capital requirements across the value chain. Taiwan, South Korea, and China concentrate UHF inlay fabrication, with anodized aluminum feedstock drawing from Chinese smelters and German specialty metal processors. Single-source vulnerability clusters around Taiwan's RFID chip foundry capacity, exposing tag manufacturers to geographic concentration risk. Distribution runs through regional converting partnerships in Maharashtra, Bavaria, and Texas that laminate inlays to hospital-specified substrates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asset tag demand is recovering from pandemic-delayed hospital infrastructure cycles, with FDA UDI enforcement deadlines and EU MDR implementation timelines creating predictable replacement waves across healthcare systems.
For Market Incumbents: Insulate margin position by deepening backward integration into anodized aluminum substrate production in Germany and the United States, offsetting energy-cost volatility that squeezes industrial-grade tag profitability. Accelerate ISO 18000-6C and GS1 EPC Gen2 certification pipelines to compress multi-quarter testing cycles that delay product launches against emerging RFID platform competitors.
For New Entrants and Emerging Players: Pursue white-space opportunity in India's DGFT-mandated pharmaceutical serialization market, where local converting partnerships remain underdeveloped and CDSCO medical device regulations are tightening identification requirements for imported equipment. Target maintenance-linked tag systems in Maharashtra and Gujarat active ingredient facilities, leveraging smartphone-readable NFC authentication as a lower-capital entry path against entrenched RAIN RFID vendors.
For Investors and Strategic Acquirers: Long-term, this sits as a compliance-driven recurring revenue play because regulatory mandates for medical device traceability and battery passport documentation are embedding physical identification into circular economy infrastructure. Acquisition targets should emphasize hospital EHR integration capabilities and proven enterprise asset management software stacks rather than commodity inlay manufacturing. The signal to watch is California battery passport regulation adoption velocity, which would accelerate premium service contract demand for lithium-ion freight equipment tagging.
| Strategic Initiative | Industry Significance |
|---|---|
| Hospital EHR Integration Partnership | Bridges RFID hardware with Epic and Cerner systems for utilization outcome guarantees. |
| Backward Integration into Substrate Production | Captures anodized aluminum margin and insulates against energy-intensive smelting cost spikes. |
| 5G-Enabled Industrial IoT Platform Launch | Combines passive RFID with cellular LPWAN for real-time yard visibility in Chinese logistics hubs. |
| REACH-Compliant Adhesive Reformulation | Validates bio-based acrylic alternatives to maintain CE-marked product continuity in European supply chains. |
| Local Converting Partnership in India | Establishes DGFT track-and-trace compliance capability ahead of pharmaceutical serialization mandates. |
Study Parameters
A spread of perspectives from hospital biomedical engineers, automotive Tier 1 procurement leads, RFID platform engineers, and pharmaceutical GPO contracts managers converged on the working assumptions driving this analysis. Primary interview insights were cross-validated against FDA UDI guidance documents, EU MDR technical documentation requirements, DGFT track-and-trace notifications, and SEC 10-K filings from identification technology vendors. Bottom-up unit economics from tag substrate and inlay production were triangulated with top-down healthcare and manufacturing capital expenditure patterns.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with technology segmentation (RFID, QR code, barcode, NFC), material substrate tier, and end-user vertical modeled as core dimensions. CAGRs were derived from equipment replacement cycle analysis and regulatory mandate implementation schedules. Forecast inputs incorporated hospital RFID infrastructure deployment velocity and automotive EV battery assembly plant expansion timelines without specifying calendar years.
Sensitivities concentrate around Taiwan semiconductor foundry capacity utilization and aluminum smelting energy cost trajectories. Forecasts reflect assumptions about regulatory enforcement consistency and healthcare capital allocation priorities. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors
Industrial Barcode Scanners Market
Sensors
Transport Monitoring System Market
Sensors
Global Radio Frequency Identification (RFID) Smart Cabinet Market
Sensors
Telemetric Devices Market
Sensors
Near Field Communication (NFC) Tags Market
Sensors
North America Eye Tracking Solutions Market
Sensors
Digital Direction Finder Market
Sensors
Remote Sensing Technology Market
Sensors
Global RFID Market
Sensors
Eye Tracking Solutions Market
Sensors
Eye Tracking Market
Sensors
Low Power Geolocation Market
Sensors
Beacon Technology Market
Sensors
Machine Health Monitoring Market
Sensors
Location-Based Ambient Intelligence Market
Sensors
Smart Beacon Market