
 Prepaid Wireless Service Market | 2026-2036
Prepaid Wireless Service Market Size, Share, and Industry Trends Forecast 2026-2036
Prepaid Wireless Service Market Outlook
Modular plan bundling is expanding across prepaid wireless, letting subscribers mix voice, data, and text blocks without annual contracts. Verizon leverages its nationwide infrastructure to anchor premium prepaid tiers with priority network access. T-Mobile competes on unlimited data positioning through its Metro by T-Mobile flanker brand. Cricket Wireless specializes in budget-conscious family plans with multi-line discounts across Hispanic-majority markets.
Prepaid wireless service denotes mobile telecommunications access purchased in advance via pay-as-you-go credits, monthly renewals, or promotional buckets, typically operating on MVNO or host-operator infrastructure with IMEI-based authentication and no credit verification. The primary commercial purpose is delivering flexible, low-barrier connectivity to credit-averse consumers, temporary residents, and cost-sensitive households. Bundled Services now lead gross additions as carriers merge streaming perks and hotspot allotments into single SKUs. Individual Users remain the volume base, though Small Businesses represent the fastest-growing customer type as sole proprietors abandon postpaid complexity. Monthly Plans capture the dominant pricing model share, while Pay-as-you-go persists among migrant worker populations and tourism-dependent corridors.
FCC rules on number portability and truth-in-billing shape how carriers structure promotional pricing and disclosure requirements in the United States. Mexico's IFT enforces wholesale access terms that determine which MVNOs can lease capacity from América Móvil and AT&T Mexico networks. Brazil's Anatel mandates biometric SIM registration, raising compliance costs but reducing fraud-driven churn. Stakeholders must weigh eSIM-only device proliferation against persistent cash-payment cultures when designing distribution and activation workflows.
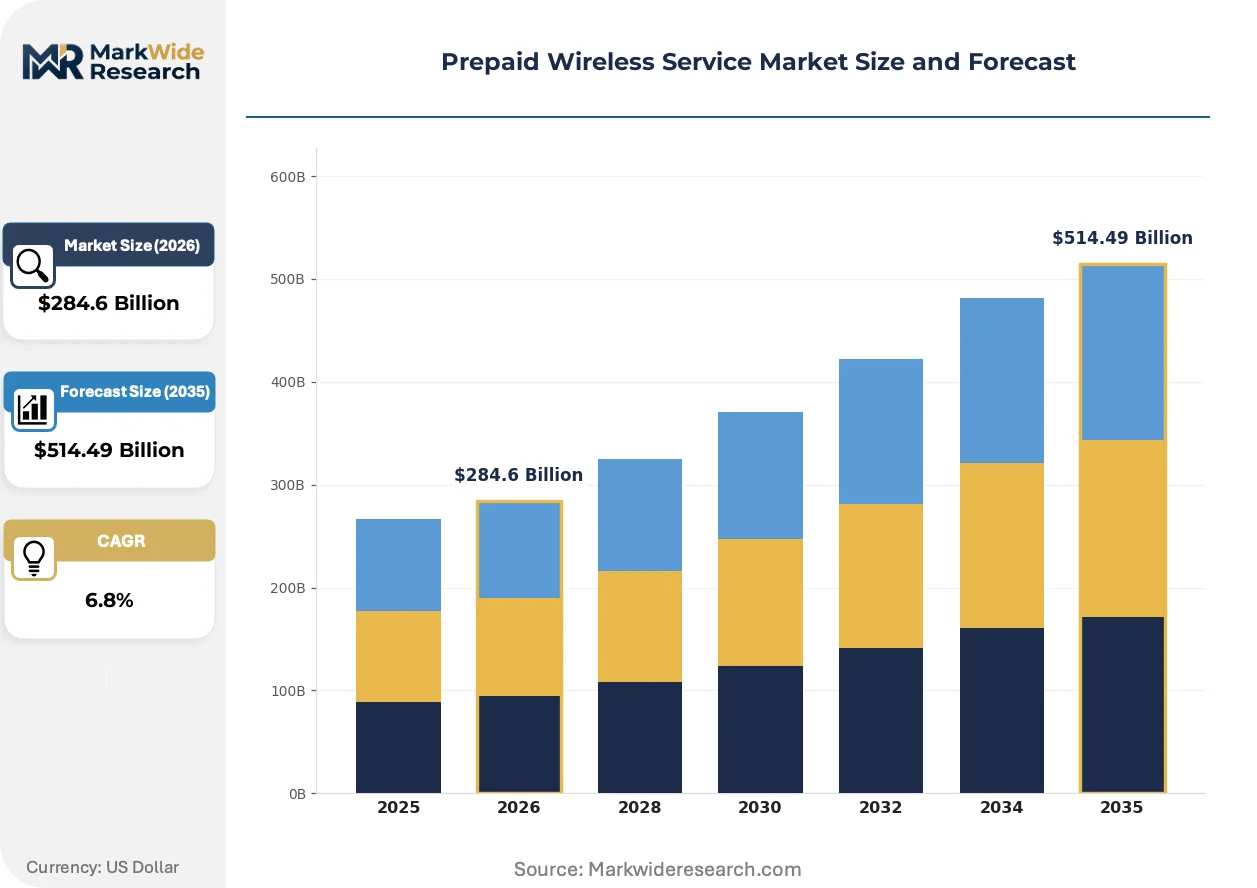
Market Dynamics
eSIM technology is collapsing subscriber acquisition costs and eroding carrier lock-in across the prepaid wireless sector. Digital-first onboarding now enables same-day activation without retail presence, fundamentally restructuring distribution economics and churn patterns.
Growth Catalysts
- FCC number portability rules:The United States mandates seamless carrier transfers, lowering psychological barriers for prepaid subscribers testing competing networks. Switching friction has compressed from weeks to minutes.
- Gig-economy workforce expansion:Delivery drivers, rideshare operators, and freelance contractors require flexible, no-contract connectivity that aligns with irregular income cycles. This demographic now drives gross additions for monthly prepaid tiers.
- Smartphone penetration in underbanked corridors:Mexico and Brazil see device ownership climb among populations excluded from traditional credit systems. Prepaid becomes the default access mode where postpaid credit checks block entry.
Market Restraints
- Biometric SIM registration mandates:Brazil's Anatel requires fingerprint-linked activation, raising per-subscriber compliance costs and complicating cash-based retail distribution. Smaller MVNOs face disproportionate burden.
- Host network concentration:América Móvil controls wholesale tower and spectrum access across Latin American markets, constraining independent carrier pricing autonomy and service differentiation.
- Interoperability gaps between eSIM and legacy IMEI systems:Older device fleets and rural retail points lack technical compatibility, fragmenting activation workflows and support complexity.
Strategic Opportunities
- Small business sole proprietorship expansion:Individual contractors operating as micro-enterprises seek unified voice, data, and hotspot bundles without enterprise contract minimums. This segment shows highest willingness-to-pay for premium prepaid tiers.
- Streaming service bundling convergence:Carriers can merge entertainment subscriptions into single-SKU offerings, capturing share of wallet from cord-cutting households. The model replicates postpaid value propositions without credit exposure.
- IFT wholesale access framework liberalization:Mexico's regulator is expanding mandatory network leasing terms, creating entry pathways for digital-native MVNOs without legacy infrastructure investments.
Industry Challenges
- eSIM provisioning talent scarcity:Carriers lack sufficient technical staff capable of remote profile management and over-the-air activation troubleshooting. Training cycles lag behind deployment timelines.
- Legacy billing system integration:Established operators struggle to merge real-time prepaid balance engines with promotional credit mechanics and third-party content partnerships. Technical debt slows product iteration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prepaid Wireless Service Market |
| Market Size in 2026 | $284.6 Billion |
| Market Size in 2035 | $514.49 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Voice, Data, Text, Bundled Services Customer Type: Individual Users, Small Businesses, Enterprises, Students Distribution Channel: Retail Stores, Online, Direct Sales, Authorized Resellers Pricing Model: Pay-as-you-go, Monthly Plans, Yearly Subscriptions, Promotional Offers |
| Companies Covered | Verizon, AT&T, T-Mobile, Boost Mobile, Metro by T-Mobile, Cricket Wireless, TracFone Wireless, Straight Talk, Total Wireless, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prepaid Wireless Service Market Strategic Shifts
Prepaid wireless is undergoing platformization, with carriers repositioning as digital service aggregators rather than pure connectivity vendors. Technology, regulation, and consumer behavior are simultaneously rewriting competitive rules.
Embedded SIM technology is converging with cloud-native subscriber management platforms to eliminate physical retail dependencies. Younger demographics and urban migrants adopt eSIM-first activation through carrier apps within hours of device purchase. This compression is converging with legacy distribution, forcing brick-and-mortar partners to pivot toward support and payment collection rather than acquisition.
Mexico's IFT is enforcing stricter wholesale access parity between host operators and virtual carriers, mandating equivalent network priority disclosure. The regulation erodes historical information asymmetries that favored incumbents. Budget-focused MVNOs now compete more transparently on price, while premium positioning requires explicit quality differentiation rather than implied network superiority.
Subscription fatigue among streaming households is compressing willingness to manage multiple monthly bills. Prepaid carriers respond by consolidating entertainment, cloud storage, and mobile data into single-renewal bundles. Hispanic-majority markets in the United States show strongest uptake, where multi-generational households prioritize simplified household expense management over à-la-carte flexibility.
Prepaid Wireless Service Market Segmentation
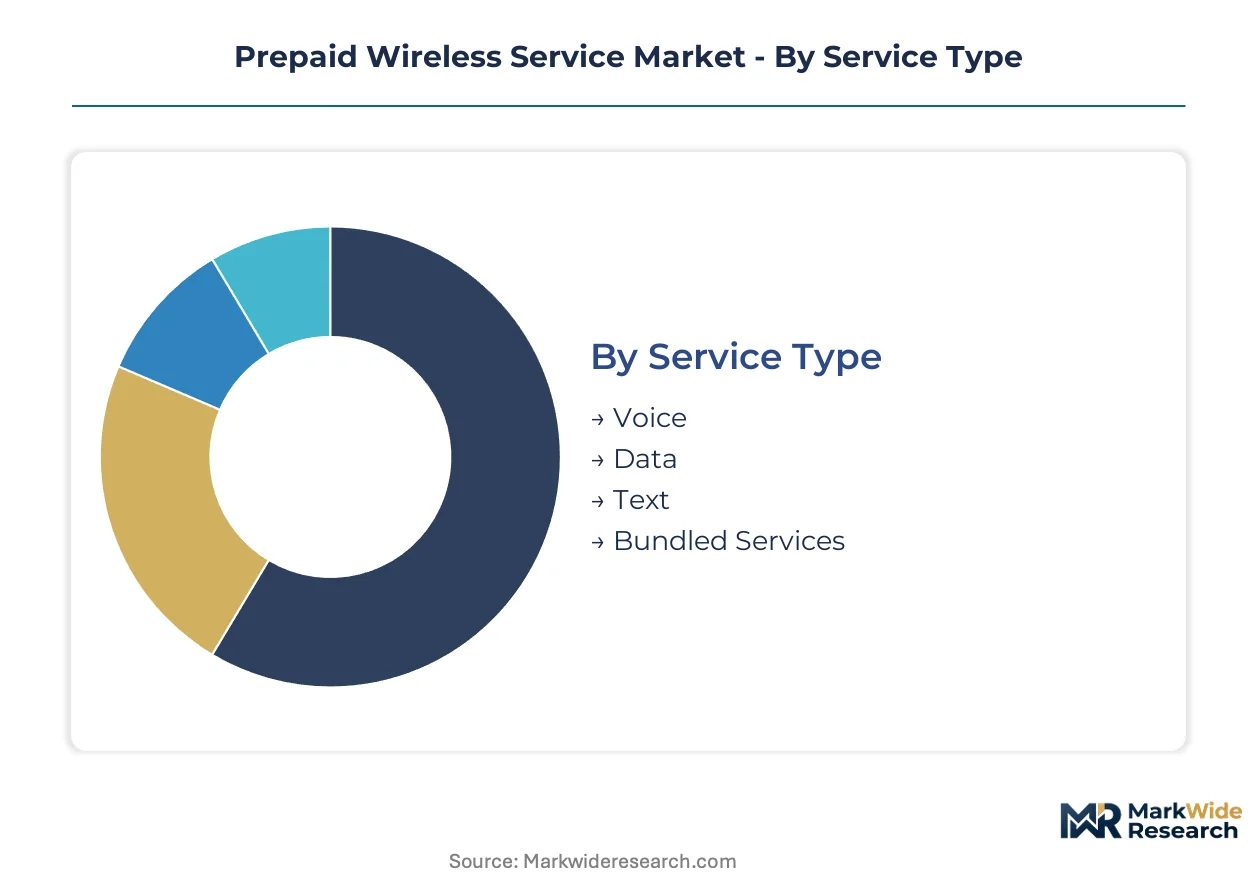
Prepaid wireless segmentation reveals how carriers align product architecture with payment behavior, device ownership patterns, and distribution access. Each dimension carries distinct margin profiles and churn risk, shaping how operators prioritize network investment and digital onboarding spend.
Service Type:
FCC disclosure rules on network priority and throttling thresholds apply differentially across service categories, with bundled offerings facing heightened truth-in-billing scrutiny.
- Bundled Services:Streaming perks, hotspot allotments, and cloud storage merge into single-SKU renewals. Hispanic-majority households in the United States concentrate demand here, driven by subscription fatigue and multi-generational expense simplification.
- Data:Unlimited and tiered data buckets dominate monthly plan attachments. Gig-economy drivers in Mexico and Brazil anchor volume, requiring flexible replenishment aligned with irregular income cycles.
- Voice:Traditional minute-based blocks persist among older demographics and rural corridors with limited smartphone penetration. Demand concentrates where VoIP alternatives face connectivity constraints.
- Text:SMS bundles retain relevance in migrant worker corridors and tourism-dependent zones where over-the-top messaging apps encounter network quality gaps.
Bundled Services sits at the top of the volume ranking, with Data climbing the fastest.
Customer Type:
Cost tier stratification separates credit-averse entry segments from premium positioning targets willing to absorb higher per-GB rates for flexibility.
- Small Businesses:Sole proprietors and micro-enterprises seek unified voice, data, and hotspot allocations without enterprise contract minimums. Contractors across Brazil's informal economy anchor this segment's expansion.
- Individual Users:Personal accounts comprise the foundational volume base, spanning students, temporary residents, and cost-sensitive households excluded from postpaid credit systems.
- Students:Educational pricing tiers and semester-aligned renewal cycles concentrate demand in urban centers with university density.
- Enterprises:Corporate prepaid accounts for seasonal or contingent workforces remain underpenetrated, constrained by procurement complexity and reconciliation friction.
Individual Users commands the largest subscriber base, though Small Businesses gains share fastest among commercial categories.
Distribution Channel:
Geography and digital maturity determine channel viability, with eSIM proliferation compressing physical retail dependence in metropolitan corridors.
- Online:Carrier apps and digital-first onboarding enable same-day activation without retail presence. Younger demographics and urban migrants in Mexico adopt this channel most aggressively.
- Retail Stores:Brick-and-mortar locations pivot toward payment collection and support as acquisition migrates digital. Cash-payment cultures in Brazil sustain this channel's relevance.
- Authorized Resellers:Independent dealers extend reach into underbanked neighborhoods and rural zones lacking flagship carrier presence.
- Direct Sales:Telesales and field agents retain niche utility for enterprise accounts and complex multi-line configurations.
Retail Stores maintains the widest footprint, while Online expands most quickly as eSIM adoption accelerates.
Pricing Model:
Application use case—temporary versus sustained connectivity—determines which pricing architecture subscribers select, with implications for carrier cash flow predictability.
- Monthly Plans:Fixed-renewal subscriptions dominate gross additions, offering predictable costs aligned with budget-conscious household management. This model captures the majority of smartphone-owning prepaid subscribers.
- Pay-as-you-go:Credit-based replenishment persists among migrant worker populations, tourism corridors, and temporary residents requiring minimal commitment.
- Promotional Offers:Time-bound discounts and bonus data incentives drive subscriber acquisition during competitive windows, particularly around device launch cycles.
- Yearly Subscriptions:Annual prepay discounts attract cost-certain households willing to lock in rates, though penetration remains limited by liquidity constraints in underbanked segments.
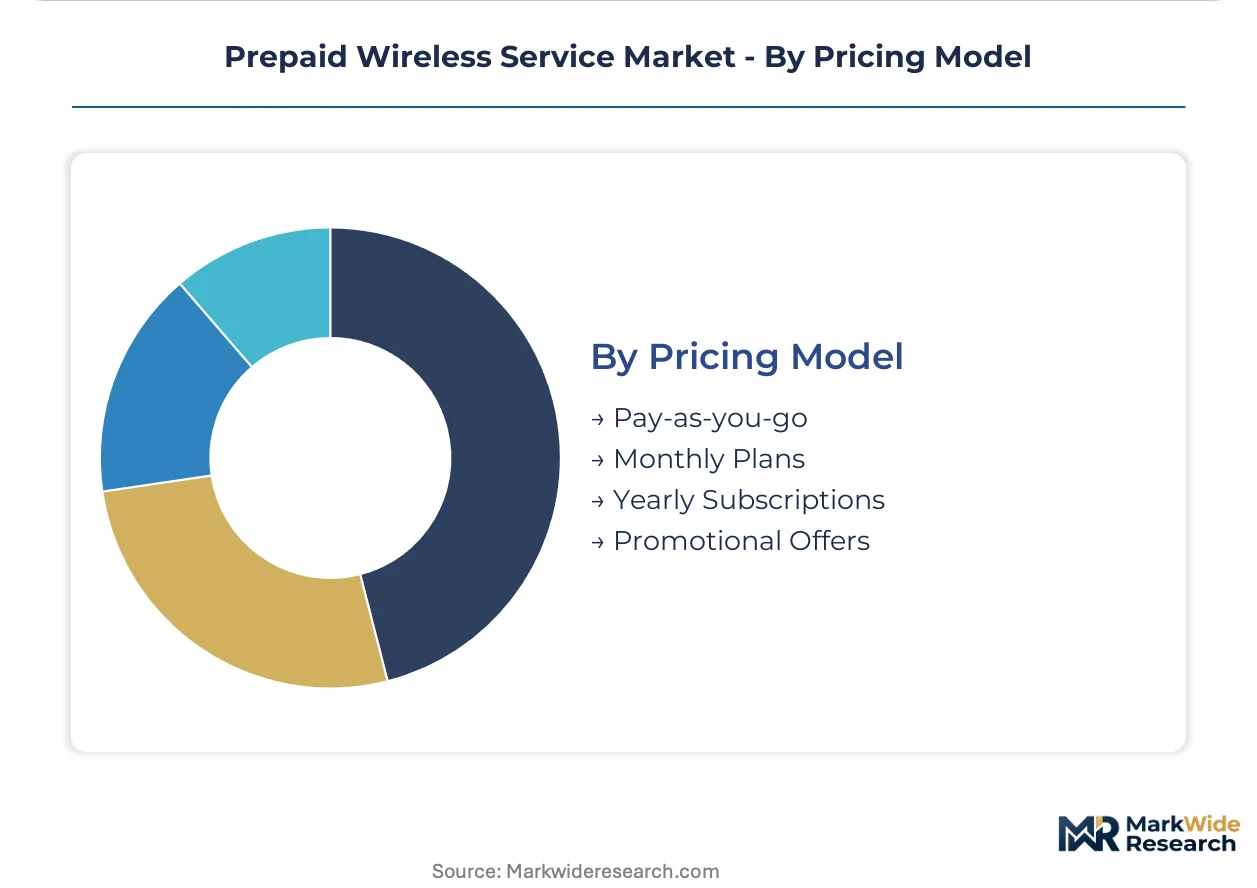
Monthly Plans leads by subscriber count, with Promotional Offers showing the steepest expansion trajectory during competitive intensity periods.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prepaid wireless service originated in the United States during the 1990s as a response to credit-excluded consumer segments, then diffused through Latin American markets where underbanked populations drove adoption. The industry's geographic footprint now centers on North and Latin America, where regulatory frameworks and payment cultures sustain distinct operational models.
United States
Gig-economy workers and younger demographics propel demand for no-contract flexibility across urban corridors. FCC number portability rules compress switching friction from weeks to minutes, intensifying carrier competition. Hispanic-majority markets in Florida and Texas concentrate family plan uptake, with multi-line discounts anchoring household retention strategies.
Mexico
Smartphone penetration climbs among populations excluded from traditional credit systems, positioning prepaid as default access mode. IFT wholesale access mandates force América Móvil and AT&T Mexico to lease capacity to virtual carriers on parity terms. Mexico City Metro and Nuevo León host the densest MVNO activation clusters as digital-native entrants exploit regulatory liberalization.
Brazil
Informal economy workers and sole proprietors drive monthly plan adoption aligned with irregular income cycles. Anatel biometric SIM registration requirements raise per-subscriber compliance costs and complicate cash-based retail distribution. São Paulo and Rio de Janeiro concentrate carrier infrastructure investment, though smaller MVNOs face disproportionate regulatory burden outside metropolitan cores.
Canada
Temporary residents and cost-sensitive households sustain pay-as-you-go persistence alongside monthly plan migration. National telecommunications regulators enforce wholesale access terms that constrain incumbent pricing autonomy. Ontario and Quebec anchor subscriber volume, with Greater Toronto and Montreal serving as testbeds for eSIM-first onboarding among younger demographics.
Prepaid Wireless Service Market Competitive Environment
The competitive structure tilts toward host-operator dominance with flanker brand proliferation. National infrastructure owners anchor premium positioning through priority network access, while virtual carriers exploit wholesale leasing to compete on price. Three archetypes prevail: facility-based majors with prepaid divisions, pure-play MVNOs without spectrum assets, and retail-branded resellers dependent on host capacity. M&A activity concentrates among flanker brand consolidation, and strategic partnerships with streaming platforms now substitute for network differentiation.
Within the facility-based tier, Verizon and AT&T occupy positions as infrastructure owners with prepaid flanker brands, while T-Mobile exemplifies the unlimited-data positioning archetype through its Metro by T-Mobile division. These three entities represent the competitive center of gravity, with their wholesale leasing terms determining viable positioning space for dependent virtual carriers.
| Leading Market Players |
|---|
| Verizon |
| AT&T |
| T-Mobile |
| Boost Mobile |
| Metro by T-Mobile |
| Cricket Wireless |
| TracFone Wireless |
| Straight Talk |
| Total Wireless |
| Others |
Value Chain & Pricing Dynamics
Gig-economy procurement preferences for no-contract flexibility are compressing carrier pricing power and forcing supply chain reconfiguration toward digital-first activation infrastructure with lower per-subscriber fulfillment costs.
Pricing Analysis
Monthly fixed-renewal subscriptions anchor the dominant pricing architecture across prepaid wireless, with three-tier pricing structure across premium, standard, and economy levels separating Verizon's priority network access from Metro by T-Mobile's unlimited positioning and Cricket's budget family tiers. Price differentiation rests on network priority disclosure and bundled streaming perks rather than raw connectivity. Cost compression in economy tiers is intensifying because host-operator wholesale rates constrain MVNO margin autonomy. Individual users in underbanked corridors show highest price sensitivity, while small business sole proprietors absorb premium rates for unified voice-data-hotspot flexibility.
Supply Chain Analysis
FCC network priority disclosure mandates and Brazil's Anatel biometric registration requirements are gating supply chain participation, favoring carriers with compliant provisioning infrastructure. Network infrastructure concentrates in the United States, Mexico, and Brazil, with host-operator tower and spectrum assets forming non-substitutable inputs. Raw material dependencies span eSIM chipsets, cloud-native subscriber management platforms, and biometric authentication hardware. Single-source vulnerability runs through América Móvil's wholesale tower access across Latin America. Distribution runs through carrier-owned retail footprints, authorized reseller networks, and app-based digital onboarding channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Prepaid wireless has matured into a late-cycle quality market where subscriber lifetime value now depends on premium bundle execution rather than raw acquisition scale, with Hispanic-majority household demand shifting decisively toward streaming-integrated offerings.
For Market Incumbents: Anticipate eSIM-native digital entrants eroding brick-and-mortar acquisition economics by accelerating priority network tier investments and securing exclusive streaming partnership rights. Vertical integration into cloud-native subscriber management platforms reduces third-party provisioning dependency. Defensive consolidation of flanker brand portfolios eliminates channel conflict between premium and economy positioning. For New Entrants and Emerging Players: Mexico's IFT wholesale access liberalization opens a window for digital-native MVNOs to lease América Móvil and AT&T Mexico capacity without legacy infrastructure investments. Small business sole proprietorships in Brazil's informal economy represent the most penetrable segment, with unified voice-data-hotspot bundles commanding willingness-to-pay premiums. A direct-to-consumer app-based go-to-market angle bypasses cash-payment retail dependencies. For Investors and Strategic Acquirers: Asymmetric upside sits with digital-first MVNOs possessing compliant eSIM provisioning infrastructure and streaming partnership pipelines. Long-term viability over the next decade hinges on subscriber management platform ownership rather than wholesale rate arbitrage. The signal to watch is IFT enforcement intensity on wholesale access parity disclosure requirements.| Strategic Initiative | Industry Significance |
|---|---|
| eSIM-First Platform Migration | Cloud-native subscriber management eliminates physical SIM logistics and compresses activation timelines to hours. |
| Streaming Bundle Integration | Consolidated entertainment-mobile billing captures cord-cutting household wallet share in Hispanic-majority markets. |
| Biometric Compliance Infrastructure | Fingerprint-linked activation systems satisfy Anatel mandates while reducing fraud-driven churn in Brazil. |
| Wholesale Access Diversification | Multi-host network leasing reduces dependency on América Móvil tower concentration across Latin America. |
| Small Business Product Tier Launch | Unified voice-data-hotspot bundles without enterprise minimums target sole proprietorship expansion. |
Study Parameters
Bottom-up gig-economy workforce modeling reconciled against top-down host-operator capacity tracking forms the analytical core of this study. Primary interviews with carrier pricing strategy leads, MVNO wholesale agreement managers, regulatory affairs directors at Latin American operators, and digital product executives at flanker brands combined with secondary validation from FCC rulemaking dockets, IFT wholesale access determinations, Anatel biometric registration enforcement records, carrier SEC 10-K disclosures, and smartphone penetration surveys from national statistical institutes. Triangulation across these sources anchors subscriber and revenue estimates.
Input-output matrices map pricing model adoption by customer archetype against network infrastructure deployment patterns across the projection horizon. Segmentation dimensions modeled include service type, customer category, distribution channel, and pricing model, with additional disaggregation by network priority tier and bundled content attachment. CAGRs derive from subscriber growth run-rates reconciled against ARPU compression trajectories and host-operator wholesale rate evolution. Forecast inputs incorporate eSIM device penetration curves and biometric registration compliance cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under wholesale access regulation reversals or host-operator consolidation events. Model outputs reflect documented assumptions on switching cost trajectories and streaming bundle attachment rates. A model refresh is warranted upon material change in IFT wholesale parity enforcement or FCC network priority disclosure rulemaking.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Enterprise WLAN Market
Wireless Technologies
Global Wi-Fi Market
Wireless Technologies
Italy Fixed Wireless Access (FWA) Market
Wireless Technologies
Wireless Charger Market
Wireless Technologies
Global Massive MIMO Market
Wireless Technologies
Wireless Antenna Market
Wireless Technologies
Global Wireless Mesh Network Market
Wireless Technologies
Light Fidelity Market
Wireless Technologies
North America Wireless Microphone Market
Wireless Technologies
P2P Antennas Market
Wireless Technologies
Li-Fi Market
Wireless Technologies
Femtocell Market
Wireless Technologies
5G Fixed Wireless Access Market
Wireless Technologies
Wireless Communication Equipment Market
Wireless Technologies
France Fixed Wireless Access (FWA) Market
Wireless Technologies
Fixed Wireless Access (5G/Wttx/LTE) Market