
 Equipment Tracking Software Market | 2026-2036
Equipment Tracking Software Market Size, Share, and Industry Trends Forecast 2026-2036
Equipment Tracking Software Market Insights
Healthcare providers is realigning procurement priorities toward real-time asset visibility, displacing traditional spreadsheet-based inventory methods. Zebra Technologies dominates hospital-grade RFID deployments with specialized hardware-software bundles. Samsara Inc. competes on cloud-native architecture, while Asset Panda sustains mid-market share through configurable mobile workflows.
Equipment tracking software comprises digital systems that capture, process, and transmit location, utilization, and condition data for physical assets through GPS receivers, barcode imagers, or IoT sensor gateways with sub-meter accuracy. These platforms synchronize field-generated telemetry with enterprise resource planning modules to eliminate phantom inventory and optimize maintenance scheduling. Cloud-based solutions now lead deployment preferences, while RFID systems command premium pricing in environments requiring non-line-of-sight bulk reads. GPS tracking anchors outdoor fleet applications, whereas IoT connectivity is expanding fastest in predictive maintenance scenarios where vibration and temperature streams trigger automated work orders.
The Federal Communications Commission governs radio spectrum allocation for GPS and IoT transmissions in the United States, directly constraining device certification pathways and signal reliability thresholds. The European Medicines Agency and GDPR supervisory authorities impose traceability mandates on medical equipment location records, forcing vendors to architect region-specific data residency controls. Stakeholders must weigh sovereign cloud requirements against latency performance when selecting deployment architectures for cross-border asset fleets.
Market Dynamics
Cloud migration pressure and sovereign data requirements are forcing vendors to split architectures between latency-optimized edge nodes and compliance-bound regional clouds, reshaping deployment economics across industrial and healthcare verticals.
Growth Catalysts
- EU AI Act traceability mandates:Automated audit trails for asset location history are now compulsory for high-risk AI applications in manufacturing, compelling ERP vendors to embed native tracking modules.
- Construction sector fleet digitization:German and Dutch infrastructure contractors are replacing paper-based equipment logs with GPS-integrated project management platforms to reduce idle-time penalties.
- Predictive maintenance sensor fusion:Vibration and thermal IoT streams are triggering automated work orders, compressing mean-time-to-repair intervals in heavy machinery deployments.
Market Restraints
- Semiconductor supply concentration:GPS and RFID chip fabrication remains concentrated in Taiwan and South Korea, exposing hardware vendors to geopolitical disruption risks.
- GDPR data residency friction:Cross-border asset fleets face mandatory regional cloud storage, adding 15-25% latency overhead for real-time tracking applications.
- Battery chemistry cost volatility:Lithium-ion cell prices for portable tracking devices fluctuate with cobalt and nickel spot markets, squeezing hardware margins unpredictably.
Strategic Opportunities
- India's industrial corridor expansion:PLI scheme incentives for smart manufacturing are creating first-mover advantages for vendors offering rupee-denominated SaaS pricing.
- 5G private network convergence:Ultra-reliable low-latency communication is enabling sub-10-millisecond indoor positioning in warehouses, opening new premium service tiers.
- CSRD circularity reporting:EU corporate sustainability disclosure rules are mandating asset lifecycle tracking, creating bundled compliance-software demand.
Industry Challenges
- Legacy ERP integration complexity:SAP and Oracle systems in industrial facilities require custom middleware development, extending implementation timelines by 6-12 months.
- Cybersecurity certification bottlenecks:IEC 62443 industrial security standards demand third-party penetration testing, delaying product launches for mid-tier software vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equipment Tracking Software Market |
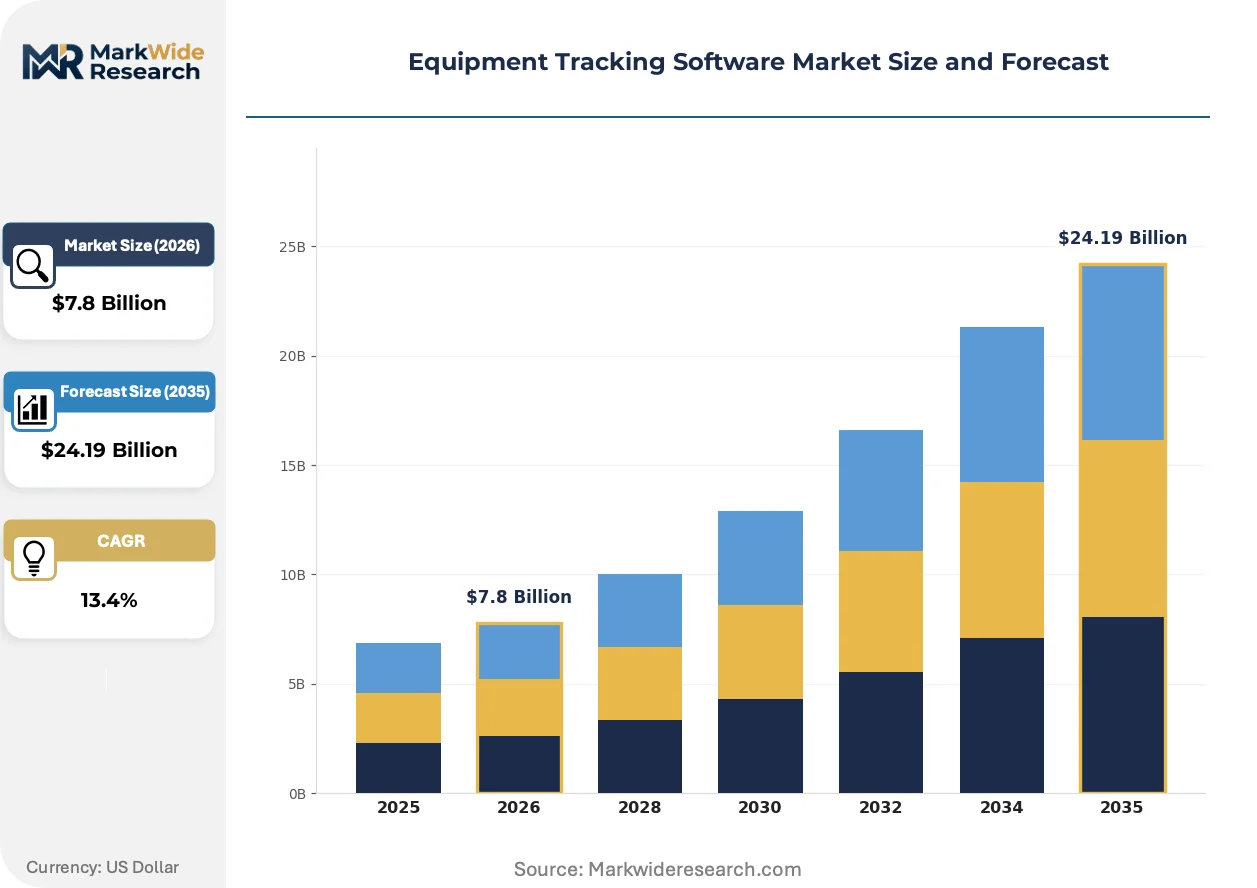
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $24.19 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Software, Cloud-Based Solutions, Mobile Applications, RFID Systems Technology: GPS Tracking, Barcode Scanning, IoT Connectivity, Cloud Computing End User: Construction Firms, Healthcare Providers, Manufacturing Units, Events Management Deployment: On-Premises, Hybrid, SaaS, Mobile |
| Companies Covered | Zebra Technologies, Honeywell, Oracle Corporation, SAP SE, Samsara Inc., Trimble Inc., IBM Corporation, Microsoft Corporation, Asset Panda, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equipment Tracking Software Market Trends and Innovations
Edge computing architectures are redistributing processing loads from centralized clouds to asset-proximate gateways, enabling real-time decision-making without connectivity dependencies.
Machine learning inference at the edge is automating anomaly detection in equipment utilization patterns. Mining operators in Western Australia are deploying these models on ruggedized gateways to flag maintenance triggers before telemetry reaches central dashboards. This distributed intelligence is compressing response windows from hours to seconds in remote extraction sites.
REACH substance restrictions are forcing hardware redesigns for battery-powered tracking devices. European manufacturers must eliminate cadmium and certain flame retardants from circuit assemblies, triggering supply chain audits extending to Southeast Asian component suppliers. Medical device vendors face the tightest compliance windows under concurrent MDR and EMA traceability rules.
Subscription-based pricing is displacing perpetual licenses in mid-market procurement. Facility managers in US manufacturing hubs now prioritize operational expenditure models that bundle hardware, software, and cellular connectivity into single monthly rates. This preference shift favors vendors with captive financing arms or telecom partnerships over pure-play software providers.
Equipment Tracking Software Market Segmentation
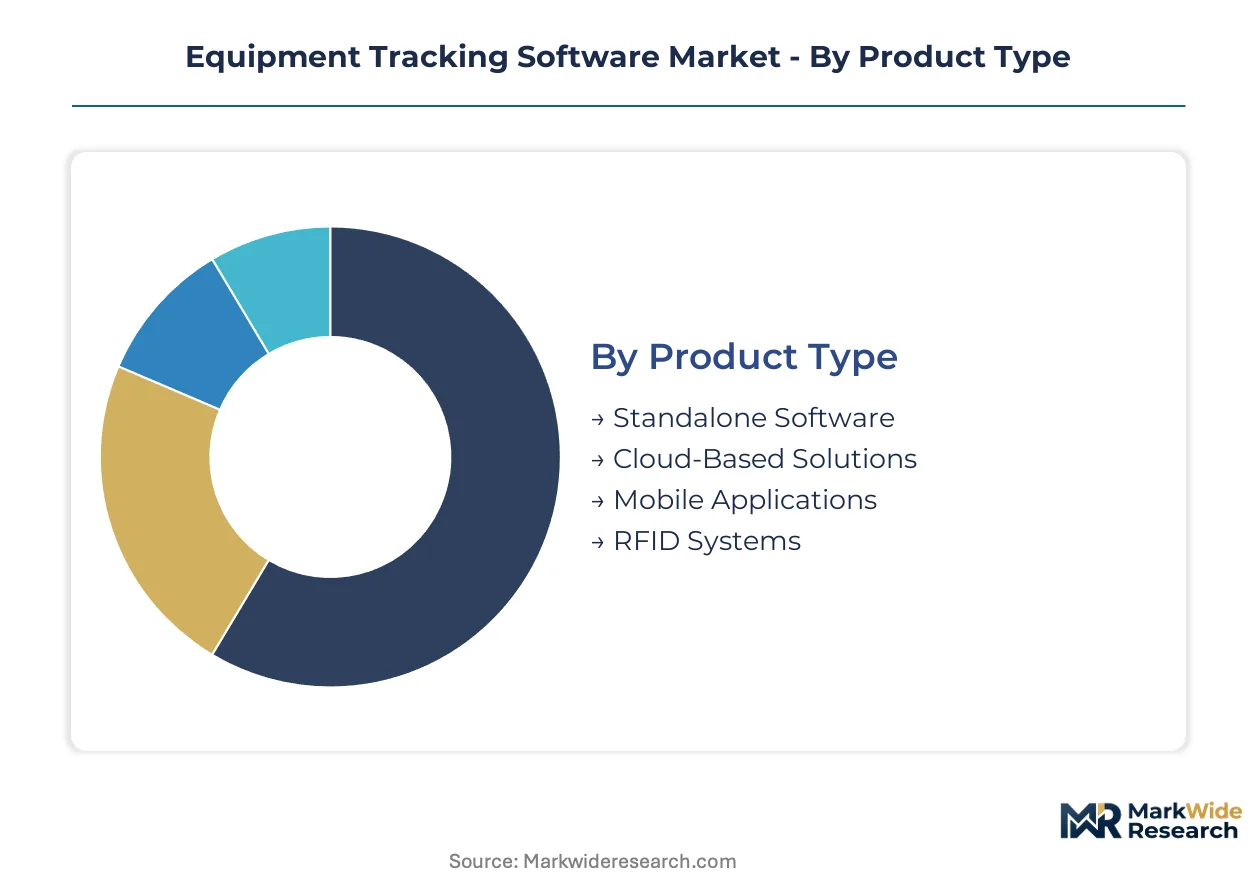
Equipment tracking software vendors architect product roadmaps around distinct technical and operational boundaries. Each segment carries unique integration requirements, compliance obligations, and margin structures that shape competitive positioning.
Product Type:
Replacement cycles vary sharply across deployment modes, with cloud-native platforms refreshing every 18-24 months while RFID hardware extends to 7-10 year lifespans.
- Cloud-Based Solutions:Multi-tenant architectures with API-first design enable ERP synchronization without on-site infrastructure. German manufacturing corridors favor these platforms for their sovereign data residency controls under GDPR. Demand concentrates among mid-market industrials seeking operational expenditure models.
- RFID Systems:Passive and active tag configurations with UHF and NFC protocols enable non-line-of-sight bulk reads in healthcare and logistics environments. EMA traceability mandates for medical devices drive hospital procurement in France and Germany. Premium pricing reflects hardware-software bundling requirements.
- Standalone Software:Perpetual-license deployments with localized database management persist in air-gapped defense and nuclear facilities.
- Mobile Applications:Smartphone-native asset verification tools with offline sync capabilities serve field technicians in remote construction sites.
Volume placements concentrate in Cloud-Based Solutions; the faster expansion belongs to RFID Systems.
Technology:
Technology selection hinges on environmental constraints—outdoor fleet operations demand satellite positioning while indoor warehousing prioritizes mesh networking protocols.
- IoT Connectivity:Sensor gateways stream vibration, temperature, and humidity telemetry through LPWAN or cellular networks. Mining operators in Western Australia deploy these for predictive maintenance triggers. Battery chemistry costs and semiconductor supply concentration constrain hardware margins.
- GPS Tracking:Multi-constellation receivers leveraging GPS, GLONASS, and Galileo signals deliver sub-meter accuracy for outdoor fleet management. FCC spectrum allocation governs device certification pathways in the United States. Construction firms in the Netherlands and Germany integrate these with project management platforms to reduce idle-time penalties.
- Barcode Scanning:Linear and 2D imager modules with Bluetooth tethering remain cost-effective for low-velocity inventory environments.
- Cloud Computing:Distributed processing architectures split workloads between edge nodes and regional data centers to balance latency against compliance.
Revenue concentration sits with GPS Tracking; IoT Connectivity is climbing the fastest as sensor fusion applications multiply.
End User:
End-user procurement patterns diverge by regulatory exposure—healthcare and construction face mandatory audit trails while events management operates with lighter compliance burdens.
- Healthcare Providers:Real-time location systems track infusion pumps, wheelchairs, and surgical instruments through hospital campuses. EMA and national regulators impose traceability mandates on medical equipment location records. Zebra Technologies dominates specialized hardware-software bundles in this vertical.
- Construction Firms:GPS-integrated platforms monitor excavators, cranes, and portable power across distributed job sites. German and Dutch infrastructure contractors lead fleet digitization to eliminate paper-based equipment logs. Idle-time penalties and project overruns drive software procurement.
- Manufacturing Units:ERP-integrated asset monitoring synchronizes production line equipment with maintenance scheduling modules.
- Events Management:Temporary asset tracking for staging, lighting, and audio equipment supports short-duration deployment cycles.
Contract values peak with Healthcare Providers; Construction Firms are gaining share fastest as infrastructure investment accelerates.
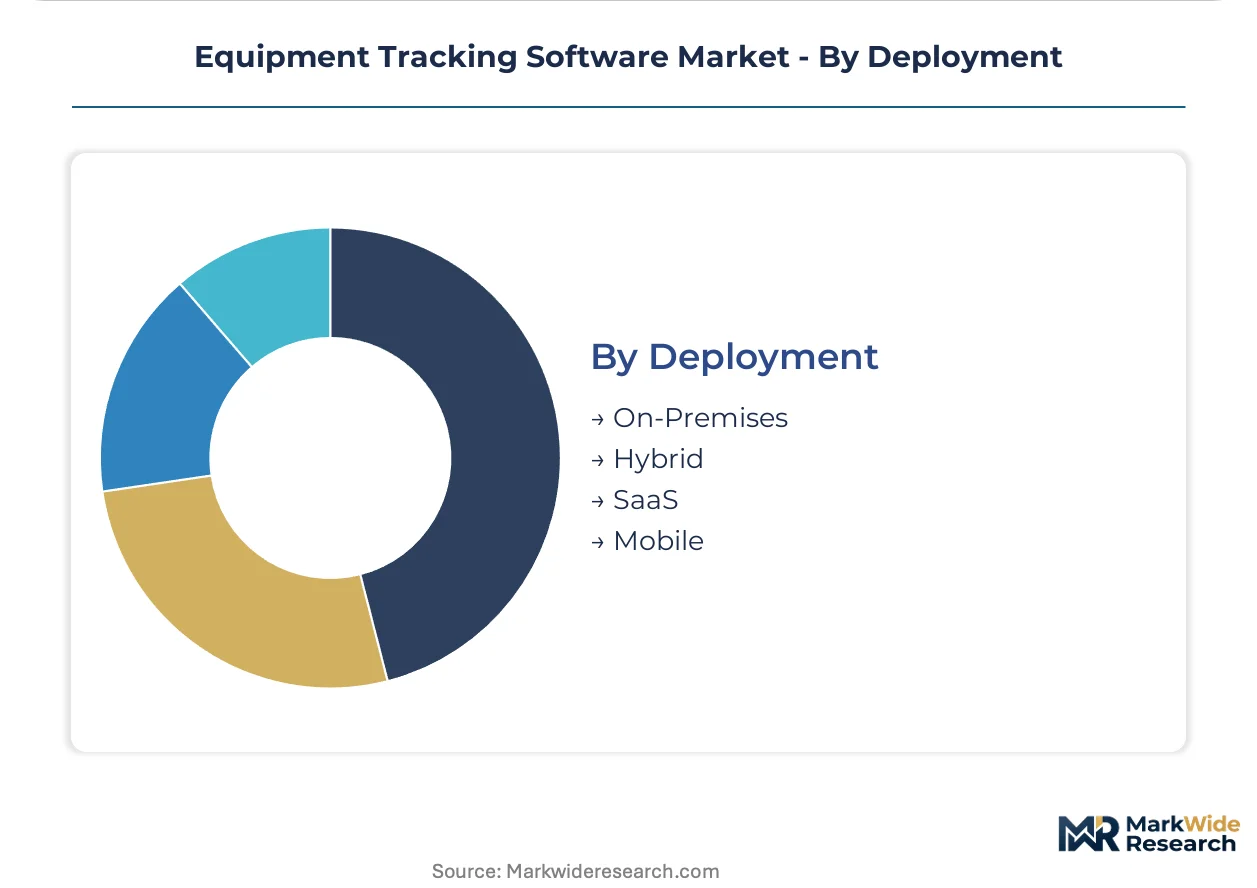
Deployment:
Deployment architecture selection increasingly reflects data sovereignty requirements rather than purely technical considerations.
- SaaS:Fully managed subscriptions bundle software, hosting, and cellular connectivity into single monthly rates. US manufacturing hubs prioritize these operational expenditure models. Vendors with captive financing arms or telecom partnerships capture preference over pure-play providers.
- Hybrid:Split configurations process sensitive data on-premises while pushing analytics to regional cloud instances. GDPR data residency friction adds 15-25% latency overhead for cross-border asset fleets. EU AI Act traceability mandates compel this architecture for high-risk manufacturing applications.
- On-Premises:Air-gapped installations in defense, nuclear, and critical infrastructure sectors satisfy security certification requirements.
- Mobile:Smartphone-centric deployments leverage native iOS and Android applications for field asset verification.
Customer acquisition concentrates in SaaS; Hybrid deployments are expanding most quickly as regulatory fragmentation deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States and Germany, while deployment demand spreads across industrial corridors in India and construction hubs in the Netherlands. Consumption patterns diverge sharply between GDPR-bound European facilities and FCC-regulated North American operations.
United States
Healthcare systems and defense contractors drive procurement of air-gapped and hybrid deployment architectures. FCC spectrum allocation governs GPS and IoT device certification pathways, constraining signal reliability thresholds for cross-border fleet operations. Hospital networks in the Greater Boston and Pacific Northwest corridors prioritize real-time location systems for medical device traceability.
Germany
Industrial manufacturers in the automotive and machinery sectors anchor European demand for ERP-integrated asset monitoring. EU AI Act traceability mandates and GDPR data residency rules compel sovereign cloud configurations with 15-25% latency overhead. The Baden-Württemberg and North Rhine-Westphalia industrial corridors lead integration of IoT-enabled fleet management with existing SAP infrastructure.
India
PLI scheme incentives for smart manufacturing are accelerating adoption of rupee-denominated SaaS pricing among domestic industrials. The central government's production-linked incentive framework supports domestic hardware assembly for tracking devices. Manufacturing clusters in Maharashtra and Gujarat are deploying cloud-native platforms to synchronize production line equipment with maintenance modules.
Netherlands
Infrastructure contractors are replacing paper-based equipment logs with GPS-integrated project management platforms to eliminate idle-time penalties. REACH substance restrictions and concurrent ECHA compliance windows force supply chain audits extending to Southeast Asian component suppliers. Rotterdam and Amsterdam port logistics hubs are expanding RFID deployments for non-line-of-sight bulk cargo tracking.
Japan
Precision manufacturers and mining operators deploy edge-computing gateways for predictive maintenance in remote extraction sites. METI industrial standards and JIS certification requirements shape procurement specifications for hardware-software bundles. The Chubu region around Nagoya and northern Kyushu industrial zones are compressing mean-time-to-repair intervals through vibration and thermal IoT sensor fusion.
Equipment Tracking Software Market Competitive Landscape
Top-tier vendors anchor enterprise-grade ERP integration, while mid-market specialists compete on configurable mobile workflows and operational expenditure models. The vendor base splits between hardware-software bundlers with specialized RFID deployments and cloud-native architects with API-first designs. Two strategic archetypes dominate: legacy technology conglomerates with captive financing arms, and vertical-focused SaaS providers with telecom partnerships. Competitive moves center on sovereign cloud infrastructure investments and custom middleware development for legacy system integration.
Within the hardware-software bundling tier, Zebra Technologies and Honeywell occupy positions exemplifying specialized industrial and healthcare deployments. Samsara Inc. represents the cloud-native architecture vector, competing through fully managed subscriptions that bundle cellular connectivity. These three anchors illustrate the market's bifurcation between premium bundled offerings and lightweight SaaS configurations.
| Leading Market Players |
|---|
| Zebra Technologies |
| Honeywell |
| Oracle Corporation |
| SAP SE |
| Samsara Inc. |
| Trimble Inc. |
| IBM Corporation |
| Microsoft Corporation |
| Asset Panda |
| Others |
Pricing and Supply Chain Analysis
REACH substance restrictions gate qualified supply for battery-powered tracking hardware and enforce premium-tier pricing access for EMA-compliant medical device vendors. German industrial buyers absorb 15-25% latency premiums for GDPR-sovereign cloud configurations, while mid-market US manufacturers prioritize operational expenditure models that bundle hardware, software, and cellular connectivity into single monthly rates.
Pricing Analysis
Margin tightening in mid-market SaaS tiers reflects lithium-ion cell price volatility and cobalt spot market swings squeezing hardware margins. Three-tier pricing structure across premium, standard, and economy levels separates EMA-certified hospital bundles from configurable mobile workflows and basic GPS fleet modules. Cost-down pressure on economy-tier deployments accelerates because construction firms in the Netherlands and Germany demand rupee-denominated SaaS pricing for cross-border fleet standardization. Healthcare providers show least price sensitivity due to EMA traceability mandates; mid-market industrials exhibit highest sensitivity, prioritizing bundled connectivity rates over feature depth.
Supply Chain Analysis
Reverse-logistics flows for RFID tag refurbishment and gateway remanufacturing concentrate in Taiwan and South Korea, where semiconductor fabrication anchors GPS and IoT chip supply. Hardware vendors draw from lithium-ion cell producers in China and Japan, with cobalt and nickel feedstocks tethered to spot market volatility. Single-source vulnerability in Taiwan semiconductor foundries exposes vendors to geopolitical disruption risks. Distribution runs through OEM-direct channels for enterprise ERP integrations and telecom-partnered SaaS marketplaces for mid-market subscription sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
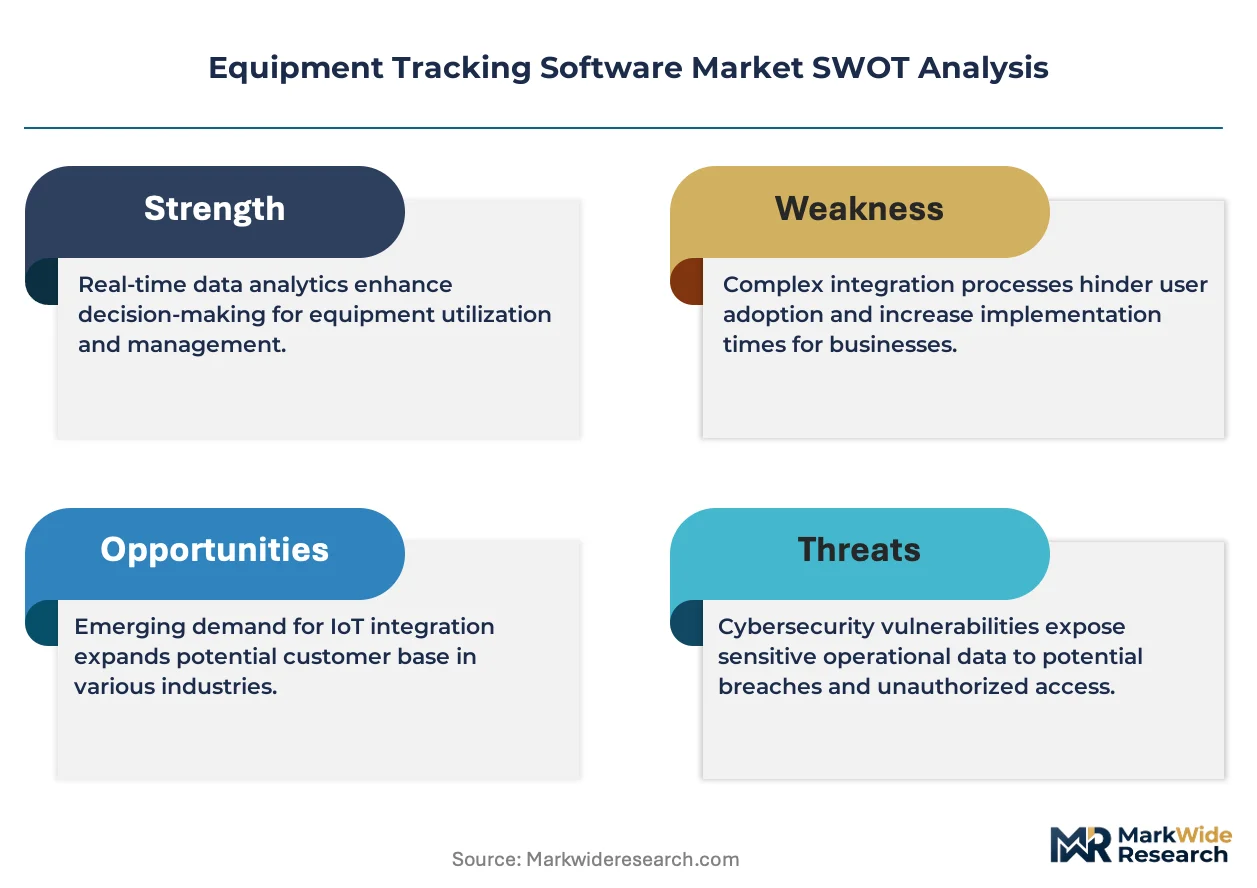
EU AI Act traceability mandates and GDPR data residency friction are forcing sub-scale vendors toward exit or acquisition, consolidating competitive positions around sovereign cloud infrastructure holders.
For Market Incumbents: Deploy captive financing arms to lock in multi-year SaaS contracts with US manufacturing hubs, insulating against pure-play software competitors. Deepen backward integration into edge-computing gateway assembly to bypass Taiwan semiconductor bottlenecks. Acquire mid-tier middleware specialists to compress SAP and Oracle integration timelines from 12 months to 6 months, neutralizing a key buyer objection. For New Entrants and Emerging Players: India's PLI scheme beneficiaries represent the most penetrable buyer archetype, with domestic industrials in Maharashtra and Gujarat seeking rupee-denominated pricing without legacy ERP baggage. Target 5G private network convergence opportunities in warehouse logistics, where sub-10-millisecond indoor positioning commands premium service tiers. Lead with API-first designs that bypass custom middleware development, accelerating time-to-value against incumbent integration timelines. For Investors and Strategic Acquirers: IEC 62443 industrial security certification delays exceeding six months are the leading indicator that mid-tier software vendors face product launch bottlenecks and distressed valuations. Position acquisitions around vertical-focused SaaS providers with telecom partnerships, capturing operational expenditure preference shifts. Monitor CSRD circularity reporting mandate adoption rates among EU manufacturing clients as the inflection signal for bundled compliance-software demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Infrastructure Investment | GDPR data residency controls in German industrial corridors command 15-25% latency premiums from compliant vendors. |
| Edge Computing Gateway Development | Ruggedized deployments in Western Australian mining sites compress mean-time-to-repair intervals through local inference. |
| Telecom Partnership Formation | Cellular connectivity bundling captures US manufacturing hub preference for single monthly operational expenditure rates. |
| RFID Hardware-Software Bundling | EMA traceability mandates for medical devices in France and Germany sustain premium pricing against commoditized GPS tiers. |
| Custom Middleware Acquisition | SAP and Oracle integration specialists reduce implementation timelines, neutralizing a primary competitive disadvantage. |
Research Methodology
Multi-period observation of EMA traceability mandate adoption rates, GDPR enforcement patterns, and PLI scheme disbursement velocities anchored the trend analysis, supplemented by interviews with hospital biomedical engineers, construction fleet managers, manufacturing plant engineers, and telecom partnership directors. Secondary validation drew from SEC 10-K filings of listed vendors, EU AI Act implementation guidance documents, FCC spectrum allocation dockets, and customs records of GPS and RFID hardware imports. Bottom-up deployment counts across German industrial corridors and top-down SaaS revenue estimates were triangulated to cross-check segment sizing.
Input-output matrices modeled relationships between semiconductor supply availability, battery chemistry cost indices, and hardware pricing elasticity across the projection horizon. Segmentation dimensions included deployment architecture, organization size, vertical industry, integration complexity with legacy ERP systems, and regional regulatory cluster. CAGRs were derived from logistic diffusion curves fitted to cloud-native adoption patterns and sensor fusion penetration rates in predictive maintenance applications. Forecast inputs incorporated sovereign cloud latency overhead coefficients and REACH substance restriction compliance cost estimates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Taiwan semiconductor supply disruption, EU AI Act enforcement variance, and lithium-ion commodity price swings. Practitioners should monitor IEC 62443 certification backlog lengths, 5G private network auction results in industrial zones, and CSRD circularity reporting adoption curves for early signals of competitive position shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Global Handwriting Digital Pen Market
Digital Solutions
Revenue Management Solutions Market
Digital Solutions
API Monetization Platform Market
Digital Solutions
Data Extraction Market
Digital Solutions
Digital Check Scanning Solutions Market
Digital Solutions
Online Recruitment Market
Digital Solutions
Global Sharing Economy Market
Digital Solutions
IT Operations and Service Management (ITOSM) Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Enterprise Information Management (EIM) Solution Market
Digital Solutions
Kenya ICT Market
Digital Solutions
North America Enterprise Information Archiving (EIA) Market
Digital Solutions
Precision Agriculture Software Market
Digital Solutions
Digital Signage Systems Market
Digital Solutions
Session Replay Software Market
Digital Solutions
Function As a Service (Faas) Market